Fiduciary Liability Insurance Market Global Industry Analysis and Forecast (2026-2035)

Fiduciary Liability Insurance Market size was USD 3.02 billion in 2026, projected to reach USD 5.32 billion by 2035, growing at a CAGR of 6.5% from 2026 to 2035. Key drivers include sustained ERISA excessive fee litigation, expanding fiduciary exposure across health and welfare plans, and growing small and medium enterprise adoption, with North America leading the market.
Download Free Sample PDF
Base Year (2025)
$2.85 Billion
Forecast (2035)
$5.32 Billion
CAGR (2026-2035)
6.5%
Top Region
North America

What Is the Fiduciary Liability Insurance Market Size?
The global fiduciary liability insurance market size was valued at USD 2.85 billion in 2025 and is estimated at USD 3.02 billion in 2026, forecast to reach USD 5.32 billion by 2035, at a 6.5% CAGR from 2026 to 2035. North America leads with approximately 68% share, while package fiduciary liability coverage dominates all other coverage types with approximately 64% share.

We observed that growth is accelerating fastest in health and welfare plan coverage and small and medium enterprise adoption, reflecting expanding plaintiff litigation activity beyond traditional retirement plan fee disputes.

By Coverage Type: Package Fiduciary Liability held the largest share of approximately 64% (USD 1.82 Billion) in 2025; Standalone Fiduciary Liability is the fastest-growing sub-segment at 7.7% CAGR from 2026-2035. By Plan Type Insured: Defined Contribution Plans held the largest share of approximately 42% (USD 1.20 Billion) in 2025; Health and Welfare Plans is the fastest-growing sub-segment at 8.9% CAGR from 2026-2035. By Organization Size: Large Enterprises held the largest share of approximately 61% (USD 1.74 Billion) in 2025; Small and Medium Enterprises is the fastest-growing sub-segment at 7.9% CAGR from 2026-2035. Dominant Region: North America dominated with approximately 68% revenue share (USD 1.93 Billion) in 2025. Fastest-Growing Region: Middle East & Africa is expected to register the highest CAGR of 11.6% during 2026-2035. Dominant Country: U.S. led with approximately USD 1.78 Billion in 2025. Fastest-Growing Country: India is the fastest-growing country at approximately 15.1% CAGR from 2026-2035.

Market Opportunity: The fiduciary liability insurance market is expected to create an absolute dollar opportunity of USD 2.30 billion between 2026 and 2035, presenting significant investment potential across standalone fiduciary programs, health and welfare plan coverage, and small and medium enterprise distribution.

According to Next Move Strategy Consulting analysis, insurers offering proactive plan governance and fee-benchmarking risk services alongside coverage are increasingly winning renewal business over pure risk-transfer providers, a shift that favors carriers with dedicated fiduciary liability underwriting expertise as plaintiff litigation theories continue expanding into health and welfare plan administration through 2035.

Fiduciary Liability Insurance Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast
Values in USD Billion

2025 $2.85 Billion
2025
2026 $3.02 Billion
2026
2027 $3.22 Billion
2027
2028 $3.43 Billion
2028
2029 $3.65 Billion
2029
2030 $3.89 Billion
2030
2031 $4.14 Billion
2031
2032 $4.41 Billion
2032
2033 $4.69 Billion
2033
2034 $5.00 Billion
2034
2035 $5.32 Billion
2035

What Does the Fiduciary Liability Insurance Market Encompass?
The fiduciary liability insurance market encompasses coverage protecting plan sponsors, trustees, and named fiduciaries against claims of mismanagement, breach of duty, or imprudent decision-making in the administration of employee benefit plans, most commonly arising under the Employee Retirement Income Security Act in the United States and analogous pension trustee liability frameworks elsewhere. Our assessment indicates that the scope spans coverage bundled within broader management liability packages alongside standalone policies purchased separately by large plan sponsors. The category has evolved from a narrow retirement-plan-fee-dispute product into broader protection spanning health and welfare plan administration as plaintiff litigation theories expand.
Regulatory frameworks such as the U.S. Department of Labor's fiduciary oversight requirements and evolving case law from courts addressing excessive fee and imprudent investment claims directly shape underwriting standards and coverage terms. We observed that technology adoption is shifting toward fee-benchmarking and plan governance analytics tools that insurers increasingly bundle with coverage, complementing broader employee benefits administration technology adoption. Next Move Strategy Consulting's analysis indicates that this structural shift is redefining underwriting criteria across the fiduciary liability insurance market as insurers price risk based on plan governance quality.

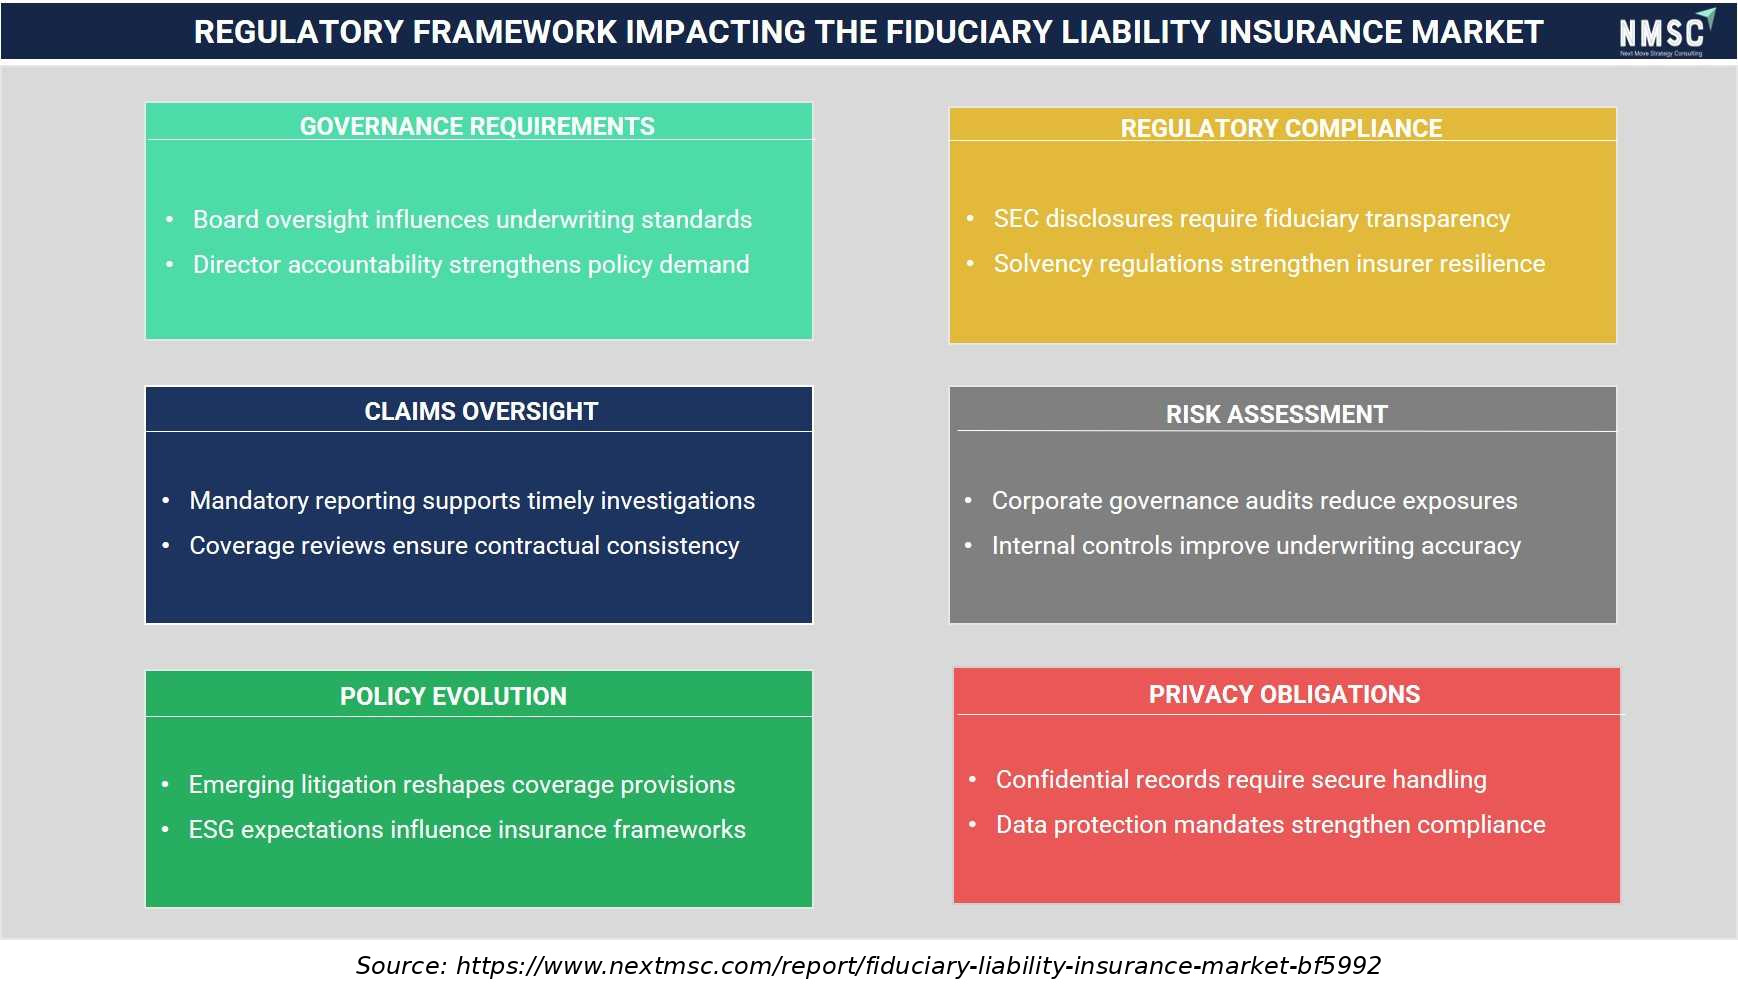
REGULATORY FRAMEWORK IMPACTING THE FIDUCIARY LIABILITY INSURANCE MARKET

This graphic illustrates the regulatory framework impacting the fiduciary liability insurance market, highlighting how governance requirements, regulatory compliance, claims oversight, risk assessment, policy evolution, and privacy obligations influence insurer underwriting, coverage provisions, and compliance practices. It emphasizes board oversight, reporting, internal controls, emerging litigation, ESG considerations, and data-protection requirements as factors shaping fiduciary liability insurance.

Market Drivers & Dynamics

Interactive Dataset
Sustained ERISA excessive fee litigation volume driver +1.9% North America 2026-2035
Expansion of fiduciary litigation into health and welfare plans driver +1.6% North America 2026-2035
Growing small and medium enterprise plan sponsor awareness driver +1.2% North America, Europe 2026-2035
Broker commission and voluntary benefit litigation exposure driver +0.9% North America 2026-2033
Expanding pension and trustee liability frameworks internationally driver +0.8% Asia-Pacific, Middle East & Africa 2026-2035
Employee stock ownership plan valuation dispute activity driver +0.6% North America 2026-2032
Rate softening amid stable underwriting results restraint -1.1% North America 2026-2030
Limited standalone product awareness outside the U.S. restraint -0.7% Global 2026-2033
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Fiduciary Liability Insurance Market?

Sustained ERISA excessive fee litigation volume is the primary driver of the market. We observed that defined contribution plans were involved in 63% of 2025 ERISA litigation, with 94 excessive fee class actions filed during the year, the highest level since 2020, according to Encore Fiduciary's analysis conducted with Dorsey & Whitney. This sustained litigation frequency continues to anchor baseline fiduciary liability underwriting demand across large and mid-sized plan sponsors.

How Is Litigation Theory Expansion Driving Market Growth?

Expansion of fiduciary litigation theories beyond traditional retirement plan disputes into health and welfare and voluntary benefit programs is accelerating market growth. Our assessment indicates that four novel class actions relating to voluntary benefit programs emerged in the final days of 2025 alone, per WTW's official fiduciary liability market outlook for 2026. This litigation theory expansion is compressing the timeline for coverage broadening among insurers seeking to address previously uncovered exposure categories.

Growth Inhibitors

What Is Restraining Fiduciary Liability Insurance Market Expansion?
Rate softening amid stable underwriting results restrains premium growth across the industry, as insurers offer improved terms to plan sponsors with favorable risk profiles despite sustained litigation frequency. Limited standalone product awareness outside the United States further limits international market expansion, since fiduciary liability remains most directly tied to ERISA's U.S.-specific regulatory framework. We found that insurers face particular exposure to these constraints in markets lacking comparable pension trustee liability litigation activity.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Package Fiduciary Liability 2025: $1.82 Billion | 2035: $3.19 Billion
Package Fidu
Standalone Fiduciary Liability 2025: $1.03 Billion | 2035: $2.13 Billion
Standalone F
Package Fiduciary Liability $1.82 Billion $3.19 Billion 5.7%
Standalone Fiduciary Liability $1.03 Billion $2.13 Billion 7.7%

Which Coverage Type Dominates the Fiduciary Liability Insurance Market?

Package Fiduciary Liability led the market with USD 1.82 billion in 2025, supported by established demand for fiduciary coverage bundled within broader management liability and directors and officers insurance programs. We observed that Standalone Fiduciary Liability is the fastest-growing coverage type, expanding at a 7.7% CAGR from 2026 to 2035, as large plan sponsors increasingly purchase dedicated fiduciary limits separate from package programs to address sustained litigation severity.

2025 (USD Billion)
2035 (USD Billion)
Defined Cont
Health and W
Defined Bene
Employee Sto
Other Employ
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Defined Contribution Plans $10.0 USD Billion $40.0 USD Billion 25.0%
Health and Welfare Plans $17.1 USD Billion $51.1 USD Billion 11.0%
Defined Benefit Plans $24.2 USD Billion $62.2 USD Billion 25.0%
Employee Stock Ownership Plans $31.3 USD Billion $73.3 USD Billion 11.0%
Other Employee Benefit Plans $38.4 USD Billion $84.4 USD Billion 16.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Plan Type Insured.

Unlock Full Data

Which Plan Type Leads Fiduciary Liability Insurance Demand?

Defined Contribution Plans remained the leading plan type insured, valued at USD 1.20 billion in 2025 on sustained excessive fee and imprudent investment litigation targeting retirement plan sponsors. Our findings suggest that Health and Welfare Plans is the fastest-growing plan type, registering an 8.9% CAGR from 2026 to 2035, as plaintiff litigation theories expand into prescription drug pricing and voluntary benefit program administration previously outside typical fiduciary coverage scope.

2025 (USD Billion)
2035 (USD Billion)
Large Enterp
Small and Me
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Large Enterprises $10.0 USD Billion $40.0 USD Billion 27.0%
Small and Medium Enterprises $17.1 USD Billion $51.1 USD Billion 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Organization Size.

Unlock Full Data

Which Organization Size Leads Fiduciary Liability Insurance Purchasing?

Large Enterprises led the market, valued at USD 1.74 billion in 2025, reflecting established fiduciary insurance purchasing practices among sponsors of large, litigation-exposed retirement plans. Our analysis shows that Small and Medium Enterprises is the fastest-growing organization size segment, registering a 7.9% CAGR from 2026 to 2035, as smaller plan sponsors increasingly recognize fiduciary exposure amid broader plaintiff firm targeting of mid-sized retirement and health plans.

2025 (USD Billion)
2035 (USD Billion)
Broker Inter
Direct To Em
Program And
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Broker Intermediated $10.0 USD Billion $40.0 USD Billion 14.0%
Direct To Employer $17.1 USD Billion $51.1 USD Billion 24.0%
Program And MGA Administered $24.2 USD Billion $62.2 USD Billion 22.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Distribution Channel.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
North Americ
Canada
Mexico
Europe: UK
Germany
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
North America: U.S. $10.0 USD Billion $40.0 USD Billion 24.0%
Canada $17.1 USD Billion $51.1 USD Billion 22.0%
Mexico $24.2 USD Billion $62.2 USD Billion 20.0%
Europe: UK $31.3 USD Billion $73.3 USD Billion 22.0%
Germany $38.4 USD Billion $84.4 USD Billion 13.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Region.

Unlock Full Data

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the fiduciary liability insurance market over the 2026-2035 forecast period.

How Can Health and Welfare Plan Coverage Extensions Unlock Value for Insurers?

Health and welfare plan coverage extensions present a whitespace opportunity for insurers offering fiduciary policies addressing prescription drug pricing and voluntary benefit administration exposure. Insurers that commercialize validated coverage forms for these emerging litigation categories stand to capture premium growth as plan sponsors seek protection against novel class action theories extending beyond traditional retirement plan disputes.

Where Does Small and Medium Enterprise Distribution Create New Demand?

Small and medium enterprise plan sponsor education represents an underpenetrated opportunity for insurers and brokers expanding distribution beyond large corporate accounts. Insurers that develop simplified, cost-effective fiduciary liability products for smaller retirement plans can access a substantial underserved customer base, benefiting from recurring premium revenue as plaintiff firm targeting extends further into mid-sized plan sponsors.

How Can Plan Governance Analytics Benefit Underwriting Differentiation?

Plan governance and fee-benchmarking analytics tools create an opportunity for insurers seeking underwriting differentiation beyond pure risk transfer. Early movers that bundle governance analytics with coverage can differentiate with plan sponsors pursuing proactive litigation risk mitigation, capturing recurring premium revenue tied to employee benefits administration technology adoption through 2035.

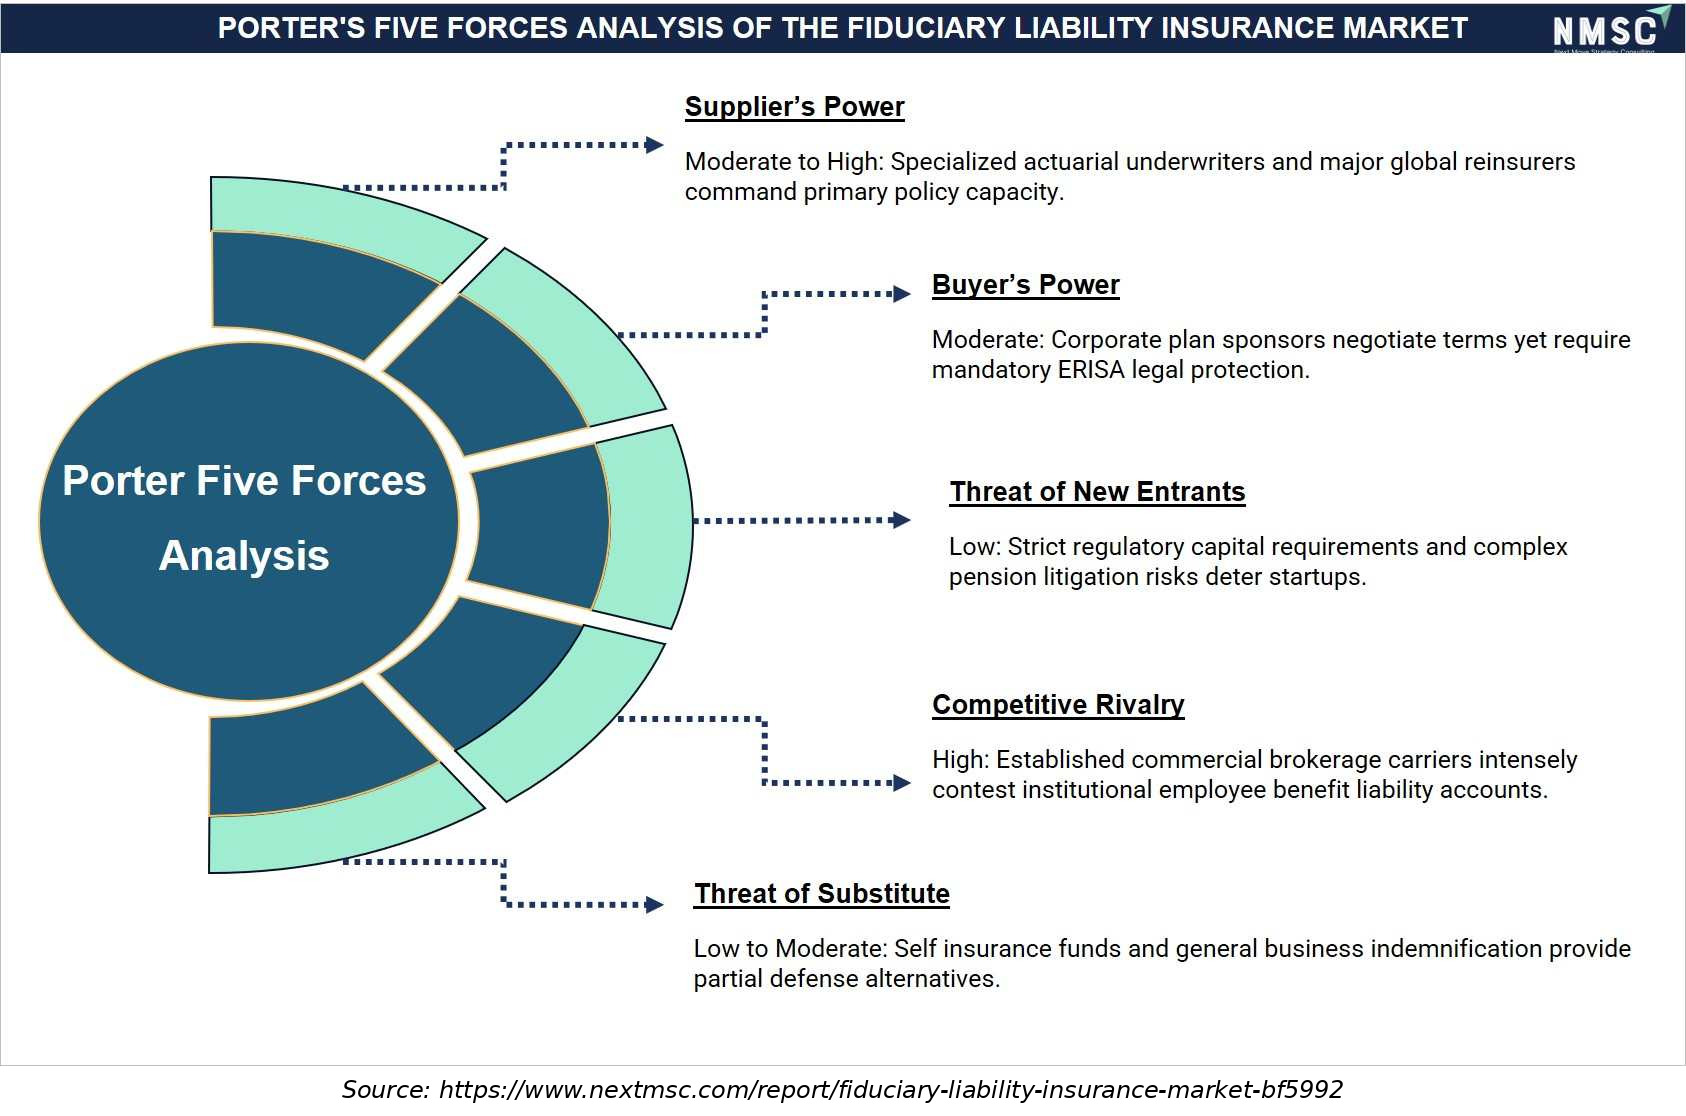
PORTER'S FIVE FORCES ANALYSIS OF THE FIDUCIARY LIABILITY INSURANCE MARKET

Porter’s Five Forces analysis evaluates the competitive structure of the fiduciary liability insurance market through the bargaining power of buyers and suppliers, the threat of new entrants and substitutes, and competitive rivalry. Established insurers benefit from underwriting expertise, regulatory knowledge, established distribution networks, and claims-management capabilities, creating entry barriers. Buyer power varies with corporate size and coverage requirements, while competition remains influenced by pricing, policy customization, risk assessment capabilities, and insurer capacity. Alternative risk-transfer solutions and evolving liability exposures further shape competitive dynamics.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Latin Americ
Middle East
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Latin America $31.3 USD Billion $73.3 USD Billion 23.0%
Middle East & Africa $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the fiduciary liability insurance market features a moderately consolidated competitive landscape, with diversified global insurers competing alongside specialty management liability underwriters on underwriting expertise, claims handling experience, and plan governance advisory services.

Dimension Description
Market Structure Moderately consolidated; the leading companies profiled in this report collectively account for a significant share of global fiduciary liability premium, with underwriting concentrated among established specialty and multinational insurers.
Innovation Focus Coverage extensions addressing health and welfare plan litigation, broker commission oversight, and plan governance analytics bundled with underwriting dominate current innovation pipelines across leading insurers.
M&A Activity Limited to date; competitive activity is concentrated in underwriting capacity expansion and coverage form innovation rather than large-scale consolidation, as specialty insurers respond to sustained litigation frequency.

How Do Companies Compete in the Fiduciary Liability Insurance Market?

Companies compete primarily on underwriting expertise, claims handling track record, and plan governance advisory capability across the industry. Diversified global insurers such as Chubb Limited and American International Group, Inc. leverage broad management liability portfolios and established claims infrastructure to serve large corporate plan sponsors, while specialty underwriters such as Beazley plc compete on dedicated fiduciary underwriting depth for complex, litigation-exposed accounts.

Which Competitive Archetypes Dominate the Fiduciary Liability Insurance Market?

Two archetypes dominate the market: diversified multinational insurers offering fiduciary liability within broader management liability and directors and officers portfolios, and specialty underwriters focused on complex management liability risk. Chubb Limited and Travelers Companies, Inc. exemplify the diversified archetype through integrated management liability offerings, while Beazley plc and Hiscox Ltd exemplify the specialty archetype, concentrating on complex, litigation-intensive fiduciary and management liability accounts.

How Are Companies Differentiating Through Innovation in Fiduciary Liability Insurance?

Innovation and differentiation strategy increasingly center on proactive risk management services bundled with coverage rather than pure risk transfer. Insurers are expanding coverage forms addressing broker commission oversight and health and welfare plan litigation exposure identified through 2025 and 2026 case law developments. Our analysis shows that insurers unable to demonstrate credible underwriting expertise in emerging litigation categories risk losing renewal business to competitors with dedicated fiduciary claims teams.

What M&A and Investment Activity Is Shaping the Fiduciary Liability Insurance Market?

Investment activity in the market remains concentrated in underwriting capacity and coverage innovation rather than large-scale mergers and acquisitions, reflecting the specialty line's relatively stable, litigation-driven demand structure. Insurers continue expanding claims teams and actuarial capability to address sustained ERISA litigation frequency, while brokers such as WTW publish annual market outlooks tracking litigation trends that inform underwriting and coverage form development across the industry.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping underwriting capacity, coverage innovation, and geographic expansion within the global fiduciary liability insurance market.

Chubb Limited American International Group, Inc. Travelers Companies, Inc. The Hartford Financial Services Group, Inc. CNA Financial Corporation Zurich Insurance Group AG AXA SA Allianz SE Berkshire Hathaway Inc. Liberty Mutual Holding Company Inc. Beazley plc Hiscox Ltd Markel Group Inc. W. R. Berkley Corporation American Financial Group, Inc. Nationwide Mutual Insurance Company Selective Insurance Group, Inc. Arch Capital Group Ltd. Everest Group, Ltd. Sompo Holdings, Inc.

Latest Developments

We found that recent developments within the fiduciary liability insurance market are concentrated on litigation theory expansion and market outlook publications, reflecting the industry's response to sustained and evolving ERISA fiduciary litigation activity.

Date Event
May 2026 Zurich published guidance explaining the distinction between ERISA fidelity bonds and fiduciary liability insurance. ERISA fidelity bonds protect employee benefit plans against losses resulting from fraud or dishonesty by covered persons, while fiduciary liability insurance generally addresses losses arising from breaches of fiduciary responsibilities. The two forms of coverage serve different purposes, and fiduciary liability insurance does not satisfy ERISA's fidelity-bonding requirement.

Investment Opportunities

What Capital Inflows Are Targeting the Fiduciary Liability Insurance Market?

Capital inflows into the market are increasingly directed toward specialty underwriting capacity capable of pricing evolving litigation theories. We observed that established specialty insurers continue expanding fiduciary claims teams and actuarial capability in response to sustained litigation frequency documented through 2025 and into 2026. Investors favor insurers demonstrating validated fiduciary claims expertise as a proxy for long-term underwriting profitability amid evolving litigation risk.

How Is Infrastructure Investment Supporting Fiduciary Liability Insurance Distribution?

Infrastructure investment is expanding broker and insurer capability to serve growing small and medium enterprise plan sponsor awareness. Our findings suggest that insurers are investing in plan governance analytics and fee-benchmarking tools bundled with coverage, reflecting broader industry investment in proactive risk management capability that extends beyond traditional risk transfer across the distribution chain.

What ESG Considerations Are Shaping Fiduciary Liability Insurance Investment Decisions?

Environmental, social, and governance considerations are increasingly relevant to investment decisions across the industry, particularly regarding retirement security and employee benefit plan governance quality. Insurers continue to emphasize plan governance standards as part of underwriting criteria, aligning risk pricing with sponsor accountability for participant outcomes. We found that investors increasingly favor insurers with transparent claims and underwriting disclosures, treating them as governance indicators alongside financial strength ratings.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support underwriting and distribution decisions across the fiduciary liability insurance industry. Our analysis shows that detailed coverage type, plan type, and organization size breakdowns help insurance leaders align product development with evolving litigation exposure while identifying underserved segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the fiduciary liability insurance sector. We observed that the report's regional and segment-level growth differentials help identify which insurers are best positioned to capture above-market growth in standalone coverage and health and welfare plan protection through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including plan governance analytics and fee-benchmarking tools, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around governance technology and litigation risk analytics increasingly bundled with fiduciary liability coverage by leading insurers.

Key Market Segments Evaluated

By Coverage Type

  • Package Fiduciary Liability
  • Standalone Fiduciary Liability

By Plan Type Insured

  • Defined Contribution Plans
  • Health and Welfare Plans
  • Defined Benefit Plans
  • Employee Stock Ownership Plans
  • Other Employee Benefit Plans

By Organization Size

  • Large Enterprises
  • Small and Medium Enterprises

By Distribution Channel

  • Broker Intermediated
  • Direct To Employer
  • Program And MGA Administered

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

What Is the Long-Term Outlook for the Fiduciary Liability Insurance Market?

The long-term outlook for the market remains positive, with global revenue projected to expand from USD 2.85 billion in 2025 to USD 5.32 billion by 2035 at a 6.5% CAGR. We observed that sustained ERISA litigation volume, expanding health and welfare plan exposure, and growing international pension governance awareness will continue underpinning demand across large and small plan sponsor segments through the forecast period.

What Strategic Positioning Should Fiduciary Liability Insurance Providers Pursue?

Providers should prioritize dedicated fiduciary claims expertise while pursuing coverage extensions addressing health and welfare plan and broker commission litigation exposure to secure long-term renewal business. Our assessment indicates that insurers investing early in plan governance analytics and expanded coverage forms, alongside small and medium enterprise distribution capability, will be best positioned to capture premium growth within the fiduciary liability insurance market.

How Attractive Is the Fiduciary Liability Insurance Market for New Investment?
The fiduciary liability insurance industry presents a steady, litigation-driven investment case, supported by a USD 2.30 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in health and welfare plan coverage and emerging international markets. We found that investment attractiveness is highest for insurers combining validated claims expertise with expanded coverage innovation, positioning them to serve both large enterprise and small and medium enterprise segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor rate softening pressure, potential legislative reform responding to high-profile litigation outcomes, and limited international standalone product awareness as key risks to the fiduciary liability insurance market. Our analysis shows that insurers unable to adapt underwriting to expanding litigation theories risk mispricing emerging exposure categories, particularly as broker commission and health plan litigation theories continue evolving through court rulings.

What Are the Key Growth Pathways for the Fiduciary Liability Insurance Market?

Key growth pathways include expanding standalone coverage adoption among large plan sponsors, scaling small and medium enterprise distribution capability, and deepening penetration into health and welfare plan protection. Next Move Strategy Consulting's analysis indicates that insurers pursuing these pathways while maintaining underwriting discipline amid sustained litigation frequency will be best positioned to capture the fiduciary liability insurance market's projected growth through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Premium & Claims Trend Analysis
  • Historical gross written premium and policy-count analysis across coverage types, plan types insured, and regions.
  • Identifies high-growth coverage and plan segments and sets the baseline for growth priorities.
Company-Level Premium Volume Analysis
  • Insurer-level fiduciary liability gross written premium and policies-in-force benchmarking from annual reports and regulatory filings.
  • Highlights insurer scale and share differences to guide competitive positioning and partnership targets.
Addressable Market Sizing by Organization Size
  • TAM / SAM / VAM sizing of fiduciary liability premium potential by organization size, plan type insured, and region.
  • Prioritizes the most accessible client segments and supports market entry and growth targeting.
Plan Sponsor Exposure & Penetration Mapping
  • Mapping of retirement and benefit plan counts, assets, and sponsors by plan type and organization size using government plan filings, with insurance penetration estimates.
  • Reveals underinsured plan segments and quantifies the cross-sell opportunity.
Fiduciary Litigation & Regulatory Enforcement Assessment
  • Country-wise analysis of fiduciary breach litigation, ERISA-type class actions, and regulator enforcement trends linked to coverage demand.
  • Anticipates demand and loss-cost drivers to support underwriting and pricing decisions.
Distribution Channel & Coverage Pricing Benchmarking
  • Benchmarking of distribution channel mix and coverage-type structures, including limits, retentions, and extensions, from regulatory rate filings and insurer disclosures.
  • Supports channel strategy and product and pricing optimization across segments.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖