How Smart Cutting Tech Can Give Small Manufacturers a Big Advantage

Precision manufacturing runs on friction. Every ground weld, polished turbine blade, and deburred EV battery housing depends on abrasives and demand for them is climbing fast enough that it's reshaping how the world's biggest industrial suppliers allocate capital. According to the Abrasives Market report from Next Move Strategy Consulting, the global market was valued at USD 45.09 billion in 2023 and is projected to reach USD 62.21 billion by 2030, growing at a CAGR of 4.71% from 2024 to 2030.
That growth isn't evenly spread. It's concentrated in automotive and aerospace manufacturing, in construction activity across emerging economies, and increasingly in the raw-material supply chains dominated by a handful of countries that feed grinding wheels, coated belts, and cutting discs to factory floors worldwide.
What's Driving the Abrasives Market?
Three forces are doing most of the work. First, automotive and aerospace production keeps expanding, and both industries lean on abrasives for grinding, polishing, and finishing metal and composite components to tight tolerances. Second, construction activity in emerging economies particularly across Asia-Pacific is driving demand for surface preparation, sanding, and cutting abrasives on concrete, metal, and wood. Third, Industry 4.0 adoption is pushing manufacturers toward higher-performance, more automated abrasive systems as production lines integrate more sensors, data analytics, and robotics.
Asia-Pacific remains the market's center of gravity, driven in large part by China's vehicle manufacturing base domestic production is projected to reach 35 million vehicles by 2025 and by rising smartphone and electronics manufacturing across the region. North America's growth is steadier, driven more by regulatory requirements around surface quality and safety in automotive, aerospace, and general manufacturing.
In short: the Abrasives Market's growth is following industrial production, not consumer demand which makes it a reasonably durable, if cyclical, growth story tied to manufacturing capex cycles.
-
Automotive and aerospace expansion is the single largest demand driver
-
Construction growth in emerging Asia-Pacific and Middle East economies is a secondary but meaningful driver
-
Industry 4.0 automation is shifting demand toward higher-performance, precision-engineered abrasive products
-
Asia-Pacific dominates on volume; North America and Europe grow more on regulatory-driven quality requirements
Precision Abrasive Machining in Modern Manufacturing
Nowhere is that shift toward precision more visible than in abrasive waterjet cutting a cold-cutting process that mixes a high-pressure water stream with abrasive particles, typically garnet, to slice through metal, stone, and composite materials without the heat distortion that plasma or laser cutting can introduce. It's become a genuine equalizer for smaller fabrication shops: systems from suppliers like TECHNI Waterjet let operations that could never afford large-scale production tooling achieve comparable accuracy on short-run and custom jobs.
That shift toward automated, sensor-guided abrasive processes is also reshaping the equipment side of the industry. As CNC-guided grinding, cutting, and finishing systems become standard rather than premium, demand is rising for the machine tools that abrasives are consumed on a dynamic covered in more depth in NMSC's Machine Tools Market report, which tracks the CNC and automation trends running in parallel with abrasive-product demand.
Raw Material Supply and Trade Dynamics
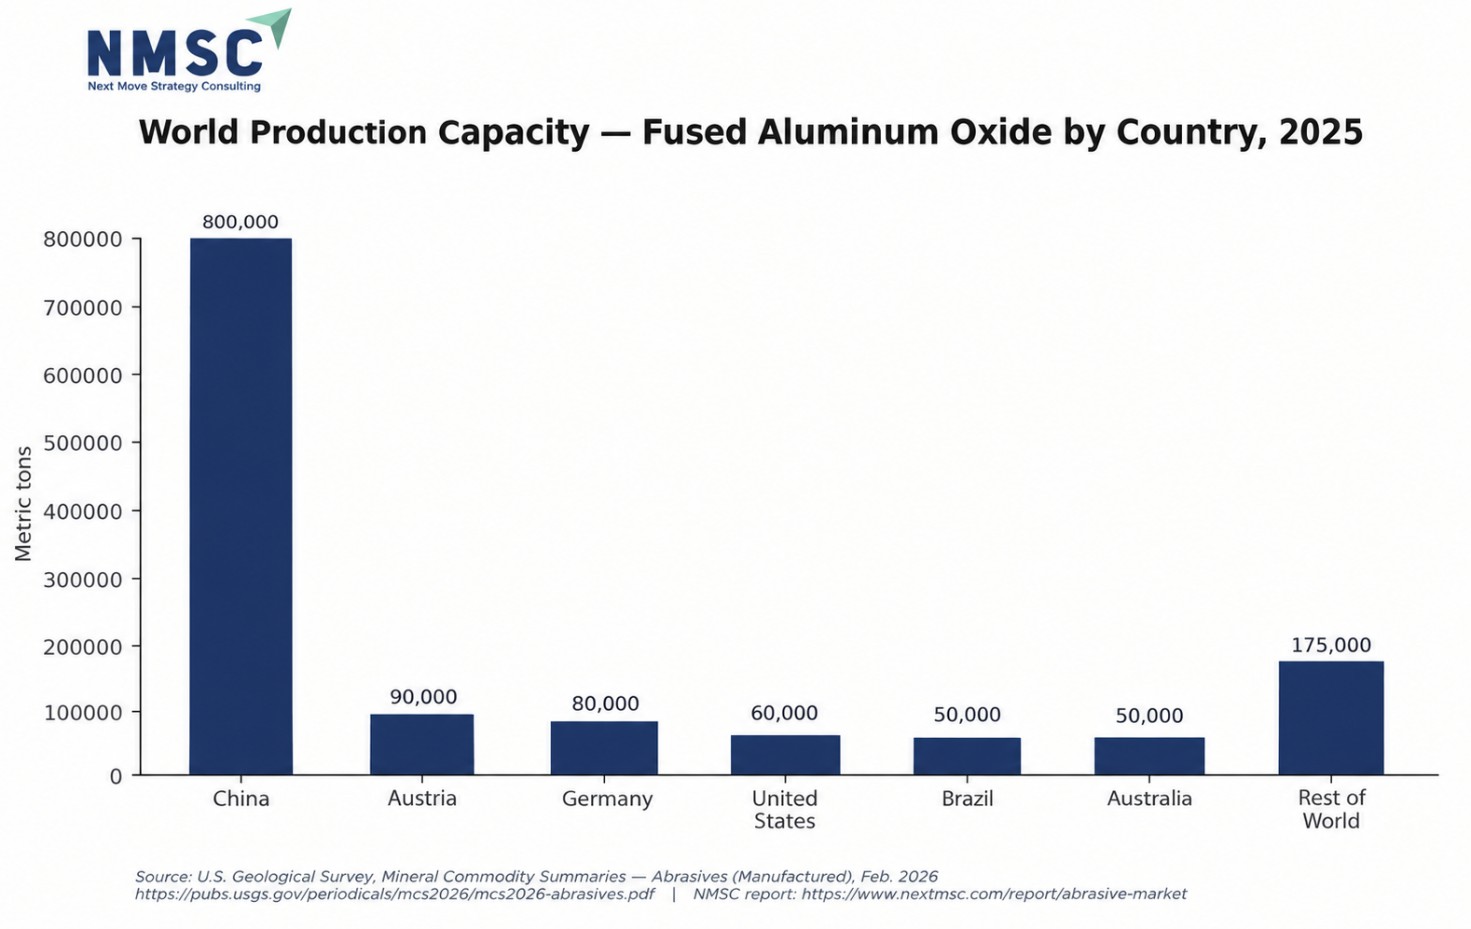
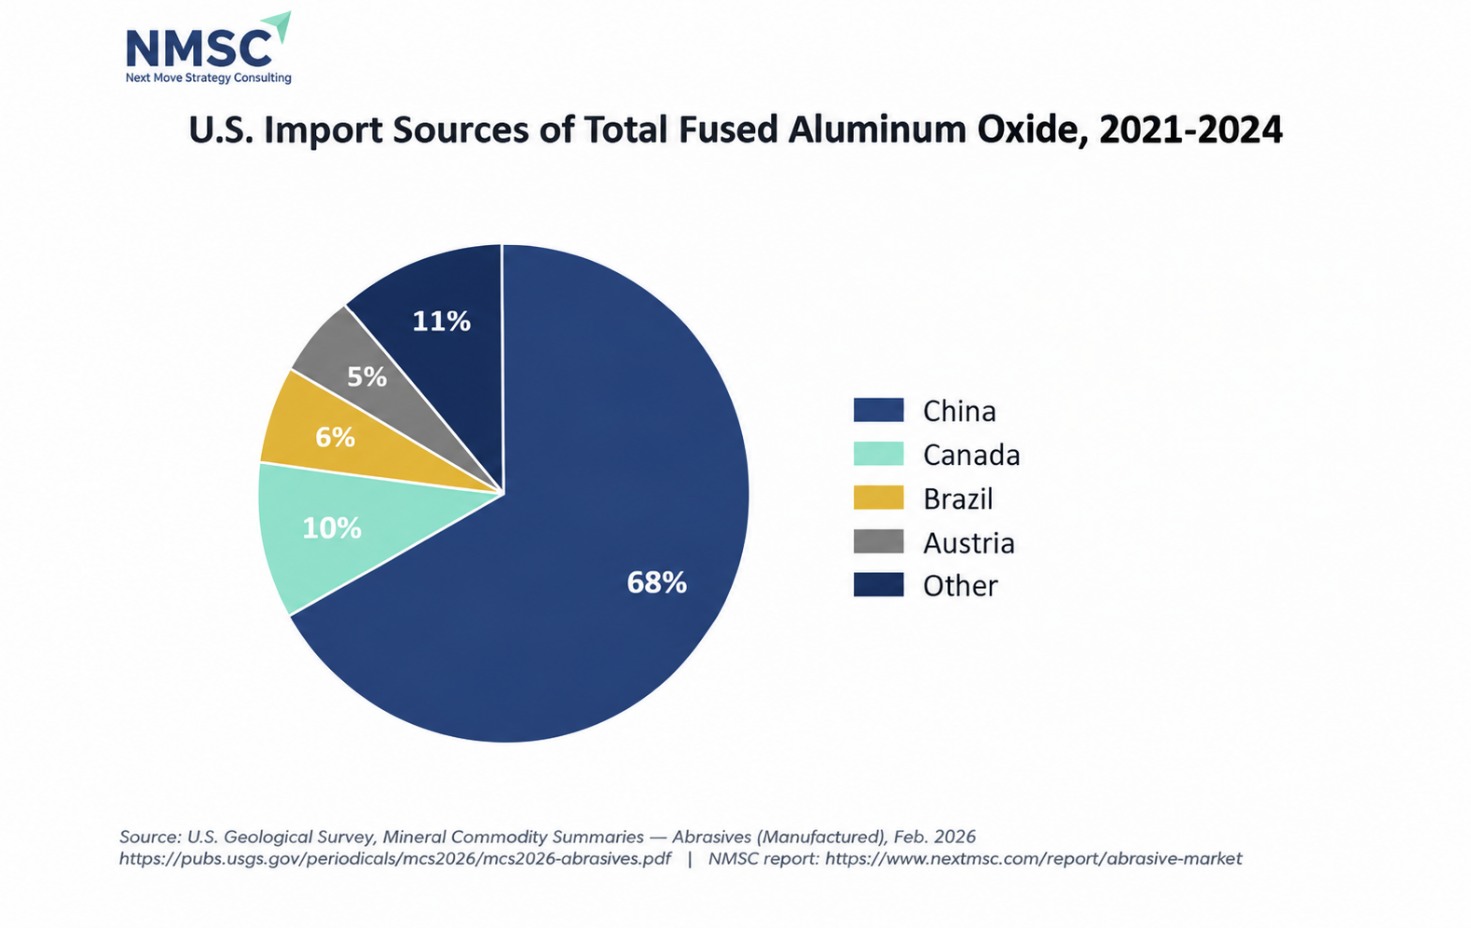
Abrasives manufacturing runs on a narrow set of raw materials fused aluminum oxide and silicon carbide chief among them and supply is heavily concentrated. According to the U.S. Geological Survey's February 2026 Mineral Commodity Summaries, China was the world's leading manufacturer of both abrasive fused aluminum oxide and abrasive silicon carbide in 2025, and Chinese imports continued to challenge U.S. and Canadian abrasives manufacturers on cost.
The U.S. remained more than 95% net import-reliant on fused aluminum oxide and roughly 74% reliant on silicon carbide in 2025. Abrasive products from China also remained subject to Section 301 duties layered on top of standard tariff rates including an additional 7.5% ad valorem on certain fused aluminum oxide grain and a 25% additional duty on Chinese-origin steel granules used in metallic abrasives. Import volumes of crude fused aluminum oxide fell 33% in 2025 versus 2024, while crude silicon carbide imports fell 20%, reflecting both tariff pressure and softer industrial demand.
U.S. Manufactured Abrasives Production, Trade & Consumption (Metric Tons)
|
Metric |
2021 |
2022 |
2023 |
2024 |
2025e |
|
Fused aluminum oxide, crude production |
10,000 |
20,000 |
25,000 |
25,000 |
20,000 |
|
Silicon carbide production |
35,000 |
40,000 |
45,000 |
40,000 |
30,000 |
|
Metallic abrasives production |
176,000 |
180,000 |
198,000 |
193,000 |
160,000 |
|
Fused aluminum oxide imports |
159,000 |
225,000 |
120,000 |
161,000 |
150,000 |
|
Silicon carbide imports |
125,000 |
165,000 |
114,000 |
113,000 |
95,000 |
|
Fused aluminum oxide apparent consumption |
146,000 |
210,000 |
110,000 |
152,000 |
140,000 |
Net Import Reliance & Average Import Unit Value
|
Metric |
2021 |
2022 |
2023 |
2024 |
2025e |
|
Fused aluminum oxide net import reliance |
>95% |
>95% |
>95% |
>95% |
>95% |
|
Silicon carbide net import reliance |
76% |
79% |
70% |
72% |
74% |
|
Fused aluminum oxide, ground/refined avg. import price ($/metric ton) |
$1,290 |
$1,560 |
$1,380 |
$1,440 |
$1,500 |
|
Metallic abrasives avg. import price ($/metric ton) |
$1,510 |
$2,130 |
$1,850 |
$1,910 |
$2,000 |
In short: Abrasive raw-material supply is a China-concentrated, tariff-exposed chain, and that concentration is a structural risk factor for every downstream abrasives manufacturer not a one-time headline.
-
The U.S. is >95% import-reliant on fused aluminum oxide and roughly three-quarters reliant on silicon carbide
-
China supplies the large majority of both crude abrasive grain imports and holds the largest share of world production capacity
-
Section 301 tariffs add real cost on top of standard duties for Chinese-origin abrasive grain and metallic abrasive inputs
-
Import volumes fell across most abrasive raw-material categories in 2025, reflecting both tariff friction and softer demand
Industry Leader Moves
The abrasives sector's largest players are all executing distinct strategies in response to the same underlying demand: precision manufacturing growth in automotive, aerospace, and EV production, layered onto rising input costs.
Carborundum Universal Limited (CUMI) posted the most concrete abrasives-specific activity of the group. Its FY2026 results, reported May 14, 2026, showed standalone Abrasives segment sales growth of 6.2% for the year and 21.5% in the fourth quarter alone, backed by the company's highest-ever capital expenditure program ₹3,094 million consolidated, directed in part toward new Thin Wheels production capacity. CUMI also commissioned a new cutting-and-grinding-wheel manufacturing facility at Hosur, India, materially expanding annual output, while winding down its loss-making German subsidiary, CUMI AWUKO Abrasives GmbH, as part of a broader portfolio rationalization. By Q1 FY2027 (reported August 2026), standalone Abrasives sales were up 14.7% year-over-year.
3M Company reported mid-single-digit growth in its Safety and Industrial Business Group which houses its Abrasive Systems line in Q1 2026, citing continued market-share gains. The company also began rolling out price increases across key markets from May 2026 to offset roughly $125 million in new raw-material costs, a direct read-through of the same trade and tariff pressure documented in the USGS data above.
Saint-Gobain, through its Norton Abrasives brand, expanded its RazorStar precision-shaped ceramic grain product line with new fiber discs in March 2026, and is showcasing new gear-grinding wheels using VS3PN bond technology and Paradigm diamond wheels for aerospace-grade grinding at IMTS 2026 both aimed squarely at high-precision, difficult-to-machine applications in gear manufacturing and turbine components.
Robert Bosch Power Tools GmbH expanded its North American portfolio with 39 new corded and cordless tools and accessories in June 2026, following a January 2026 launch of 60 new products including surface-grinding equipment debuted at World of Concrete.
Among the smaller listed players, Hindustan Abrasives used GrindingHub 2026 in Stuttgart (May 2026) to push into European export markets, highlighting lower-heat bond systems engineered for nickel-based and titanium alloys used by aerospace customers. Sterling Abrasives exhibited at IMTS 2026 in Chicago, though its FY2026 revenue growth was modest at roughly 2% amid margin pressure consistent with sector-wide raw-material cost increases. No material 2026 strategic activity was publicly disclosed for Deerfos, Osborn Lippert India Private Limited, or SAK Abrasives Limited during the period reviewed; all three continue operating within their established regional manufacturing and distribution footprints.
In short: the abrasives sector's leaders are investing where precision and aerospace/EV-grade specifications command better margins, while absorbing and passing through raw-material cost pressure everywhere else.
-
CUMI's record capex and new Hosur facility signal the clearest abrasives-specific capacity expansion in the group
-
3M and Saint-Gobain/Norton are both pushing further into high-precision, aerospace-grade grinding technology
-
Price increases tied to raw-material costs (3M) echo the tariff and import-cost pressure documented in U.S. trade data
-
Smaller regional players are competing on export reach and specialized alloy-grinding capability rather than scale
Abrasives Market Outlook: What's Next Through 2030
Through 2030, the Abrasives Market's trajectory looks tied to three things holding steady: continued automotive and aerospace production growth, sustained infrastructure investment in Asia-Pacific and the Middle East, and the pace at which manufacturers can absorb rising raw-material and tariff costs without losing share to lower-cost regional competitors. The precision end of the market super abrasives, aerospace-grade grinding wheels, and automated CNC-guided systems looks best positioned, given how directly it maps to where 3M, Saint-Gobain, and CUMI are each currently directing investment.
In short: expect the Abrasives Market's growth to keep concentrating at the high-precision end, even as the commodity end of the business faces continued margin pressure from raw-material costs and tariffs.
-
Aerospace- and EV-grade precision grinding is the clearest growth pocket through 2030
-
Raw-material trade exposure remains a persistent risk for manufacturers outside China
-
Capacity investment (CUMI's Hosur plant, 3M's continued Abrasive Systems share gains) is concentrating among a handful of leaders
Ready to dig into the full segment-by-segment forecast? Download Free Sample of NMSC's Abrasives Market report for the complete market sizing, CAGR breakdown, and competitive analysis.
Conclusion
The Abrasives Market isn't a flashy corner of industrial manufacturing, but it's a genuinely load-bearing one every precision-machined part in an EV, an aircraft, or a smartphone passes through some form of grinding, polishing, or cutting abrasive on its way to finished product. With the market on track to grow from USD 45.09 billion in 2023 to USD 62.21 billion by 2030, and with raw-material supply chains under real trade pressure, the manufacturers investing in precision-grade capacity now CUMI, 3M, and Saint-Gobain among them look best positioned to hold share as the market matures.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment