Leading Companies Supplying Concrete Barriers for Large-Scale Projects
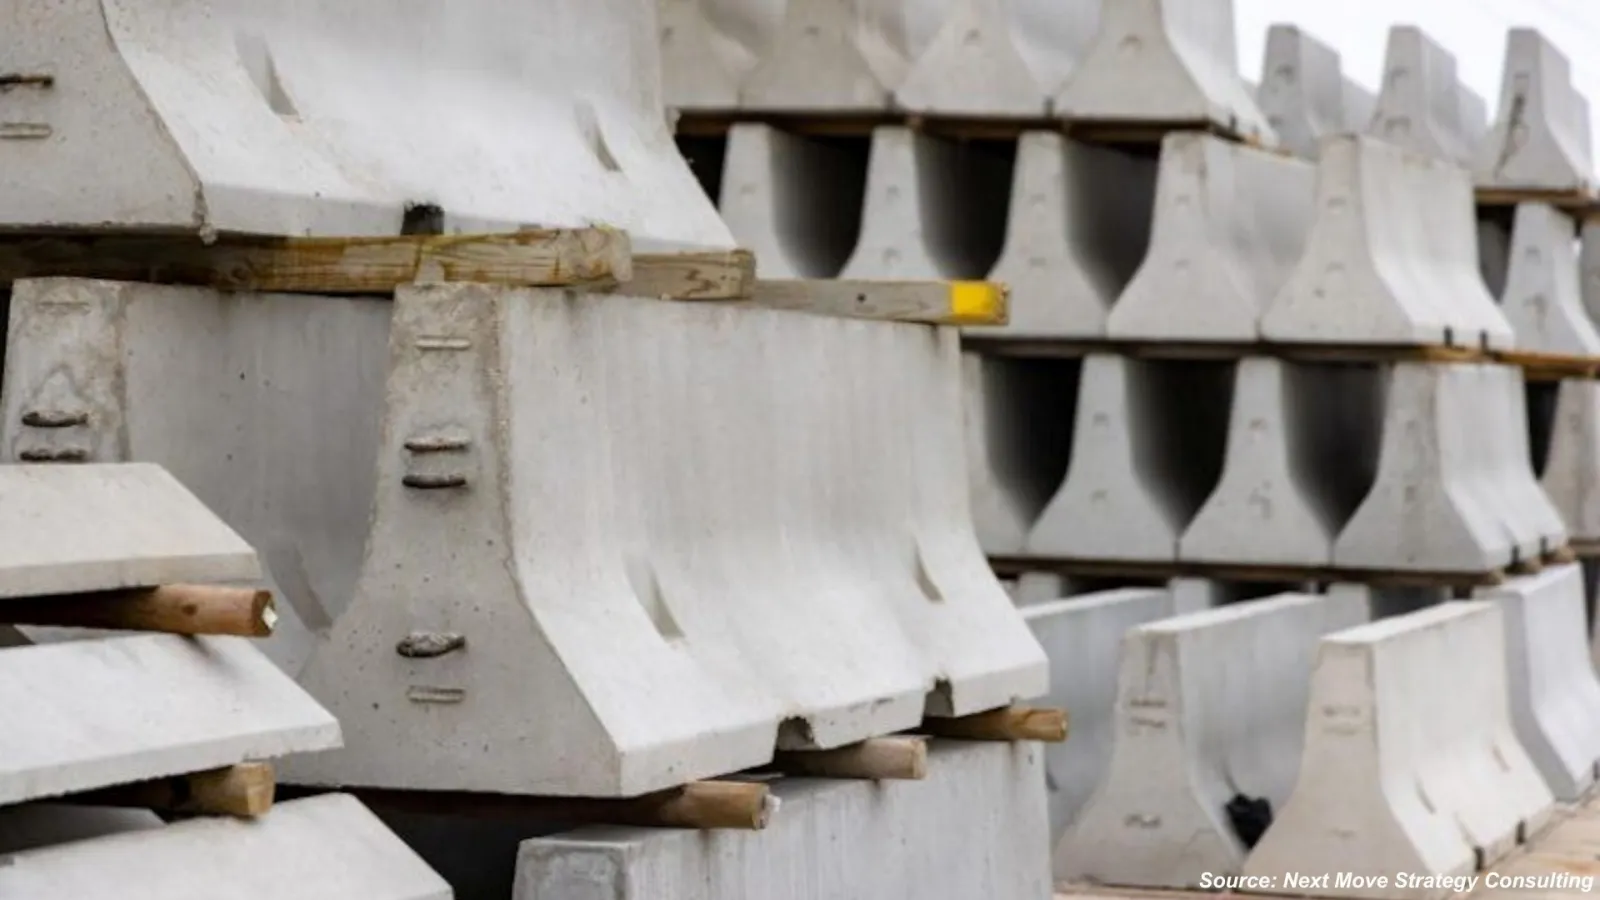
Concrete barriers rarely make headlines on their own. But the companies that supply them sit downstream of one of the largest and most consolidating industrial categories on earth. According to Next Move Strategy Consulting's Construction Material Market research, global revenue across cement, aggregates, metals, and specialty building products reached USD 1.41 trillion in 2025 and is projected to climb to USD 1.89 trillion by 2035, expanding at a 2.9% CAGR. That growth is not evenly distributed and 2026 has brought a wave of acquisitions among the aggregates and cement producers that ultimately feed barrier manufacturing, changing who controls quarries, logistics networks, and pricing power along the way.
This review evaluates the companies that actually supply concrete barriers to large-scale transportation and infrastructure projects, then goes further than a typical supplier roundup: it tracks the specific deals, capacity investments, and portfolio moves the sector's largest material producers have made over 2026, and what they signal for procurement teams sourcing barriers today.
Research Methodology and Selection Criteria
The supplier profiles below draw on publicly available information company websites, documented project experience, and industry listings evaluated against consistent criteria: demonstrated involvement in concrete barrier or precast concrete supply, operational scale and geographic coverage, evidence of project execution in construction or infrastructure environments, breadth of services (supply, logistics, installation), and publicly stated compliance documentation. This review does not rank suppliers as "best" or "leading"; it maps different operating models within a market that is itself being reshaped from above.
Market Overview: Where Concrete Barriers Sit in the Construction Material Market
Concrete barriers are a small but structurally important corner of the cementitious products category the largest material segment NMSC tracks in the Construction Material Market, generating an estimated USD 291.4 billion in 2025 on the strength of Portland cement, blended cements, and ready-mix concrete demand. Precast barrier production draws directly from that base, and from the similarly sized Aggregates & Fillers category that supplies the crushed stone underlying most barrier mix designs.
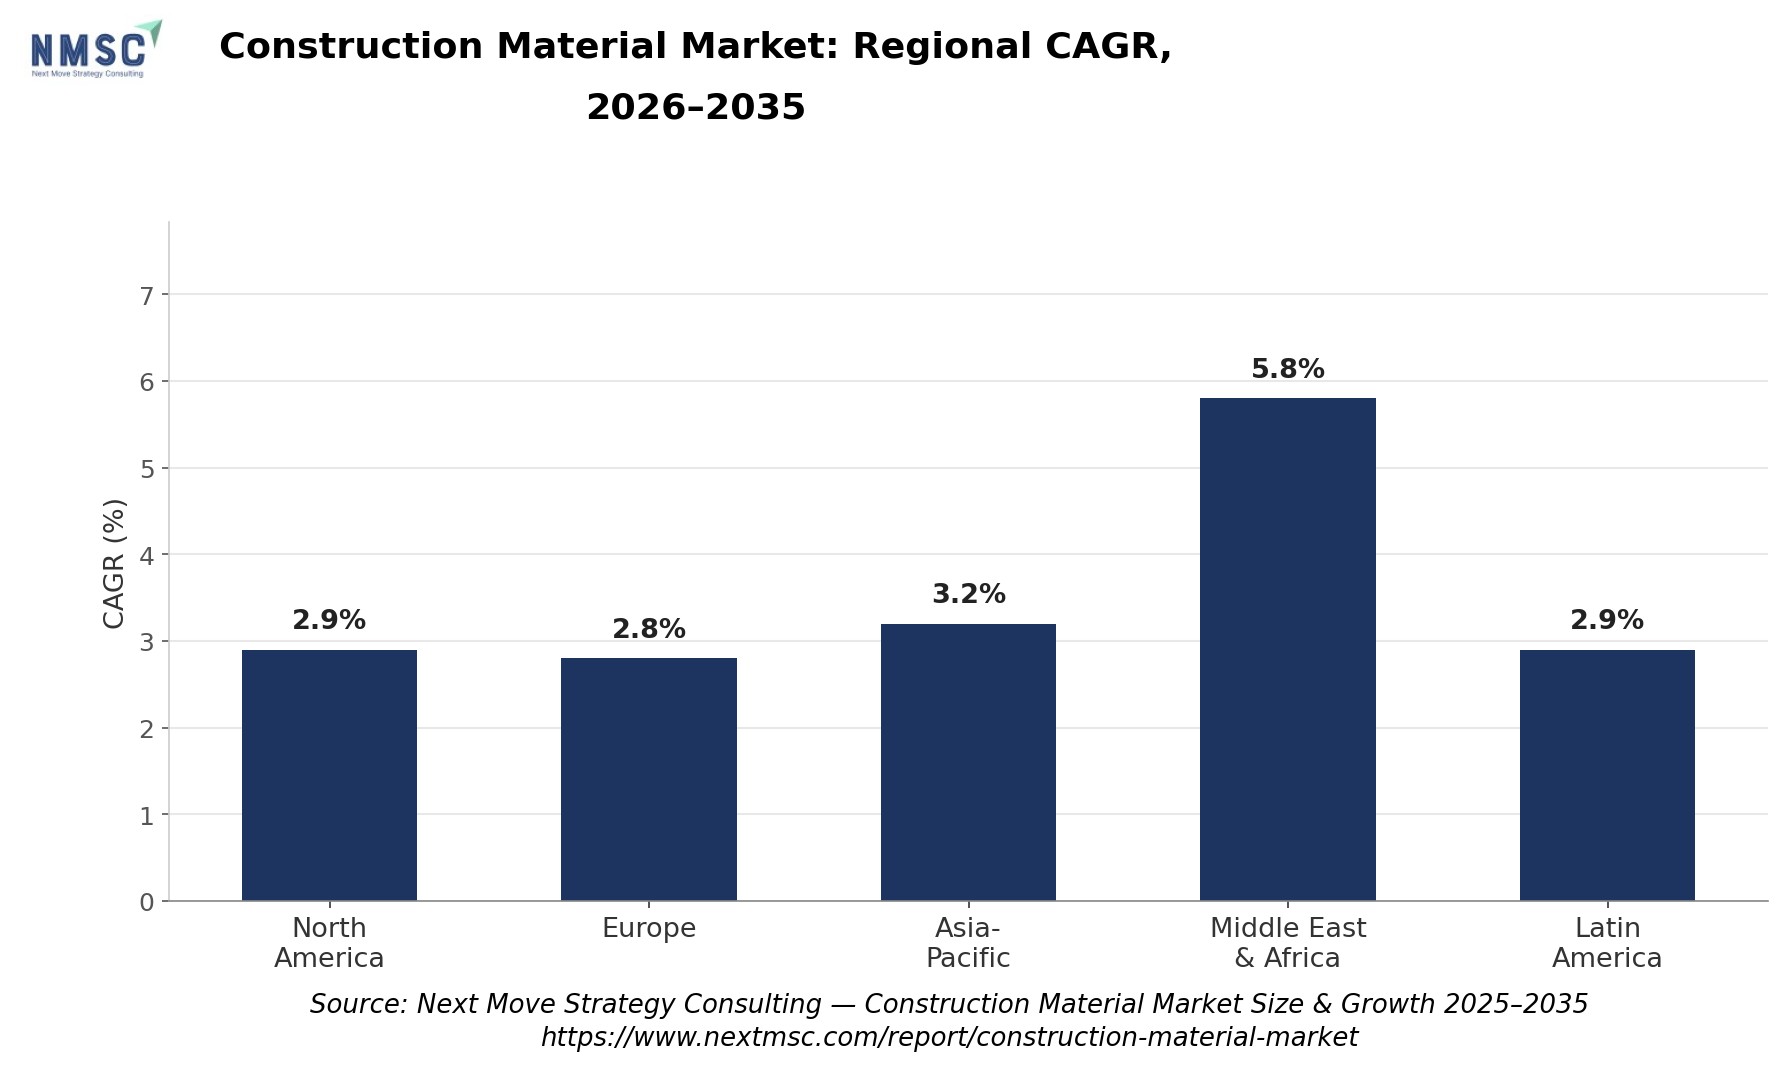
Regionally, Asia-Pacific accounts for the largest share of global construction material demand at USD 672.4 billion of the USD 1.41 trillion 2025 total, followed by Europe (USD 268.6 billion) and North America (USD 218.4 billion). For barrier suppliers specifically, growth rate matters more than absolute scale: North America's construction material demand is forecast to expand at a 2.9% CAGR through 2035, underpinned by the USD 1.2 trillion Infrastructure Investment and Jobs Act, which continues to channel spending into roads, bridges, and water infrastructure a direct demand driver for structural steel, ready-mix concrete, asphalt, and precast concrete components.
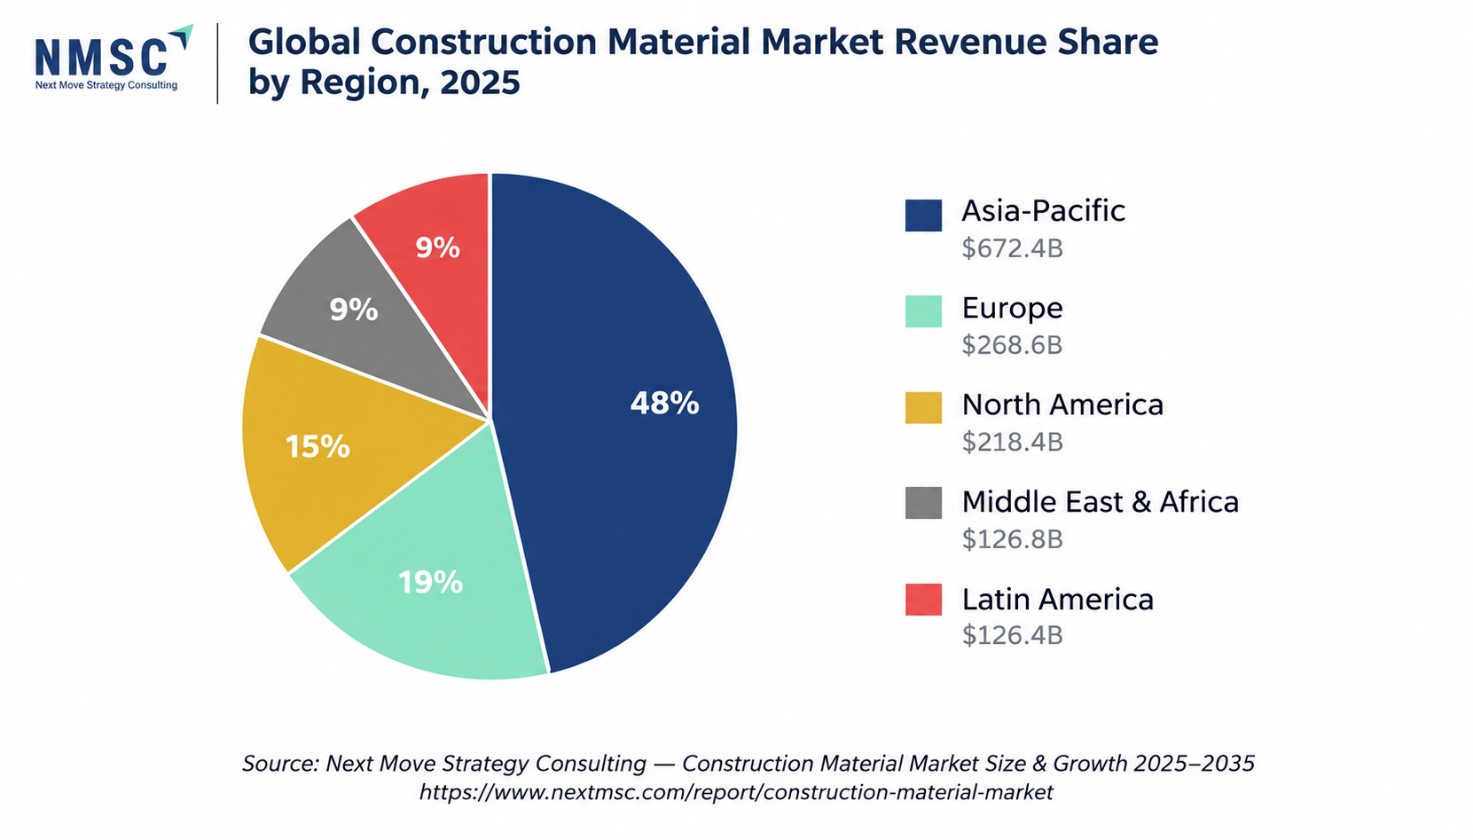
Regional shares are calculated from NMSC's 2025 regional revenue figures (Asia-Pacific $672.4B, Europe $268.6B, North America $218.4B, Middle East & Africa $126.8B, Latin America $126.4B).
Section summary: The Construction Material Market's overall scale is concentrated in Asia-Pacific, but the segment that matters most to barrier suppliers infrastructure-linked cementitious and aggregate demand in North America is growing on the back of public capital programs rather than private construction cycles.
-
Cementitious Products, the category barrier production belongs to, generated USD 291.4 billion in 2025 the largest material-type segment tracked.
-
Asia-Pacific leads global demand, but North America's IIJA-driven infrastructure spending is the more direct growth lever for barrier suppliers.
-
Infrastructure is the single largest end-user category industry-wide, at USD 410.8 billion in 2025.
Top Companies Supplying Concrete Barriers for Large-Scale Projects
The companies below reflect different operating models within the concrete barrier supply space brokerage, regional precast manufacturing, integrated construction services, and rental logistics rather than a ranked list.
1. 48 Barriers
48 Barriers operates as a U.S.-based supplier and broker of concrete barrier products, offering both new and used units. The company supports contractors and project managers by connecting them with available inventory across multiple states, focusing on reducing procurement lead times by leveraging distributed inventory rather than relying solely on manufacturing cycles an approach that has gained relevance as aggregates producers consolidate their own distribution footprints (see Industry Leader Moves, below).
2. Concrete Specialists
Concrete Specialists is a regional construction services company based in Indiana, providing excavation, site preparation, and concrete-related services. Its work includes infrastructure support activities where concrete components, including barriers, may be used as part of broader project requirements operating within a wider construction services framework rather than focusing exclusively on barrier manufacturing.
3. Michie Concrete Products
Michie Concrete Products is a precast concrete manufacturer serving the New England region. Its product range includes structural precast elements such as utility structures, culverts, and traffic-related concrete products. The company operates multiple production facilities and serves both public and private infrastructure projects, reflecting an established position in regional precast supply chains.
4. Superior Concrete
Superior Concrete is a Washington-based company engaged in structural concrete manufacturing and installation services. Its operations include large-scale infrastructure components such as retaining systems, detention structures, and custom precast elements. Its integrated service model combining design, production, and installation can reduce coordination requirements across multiple subcontractors on complex projects.
5. Accent-Barriers LLC
Accent-Barriers LLC provides concrete barrier supply, rental, and installation services primarily in the eastern United States, working with both short-term traffic control projects and longer-duration infrastructure deployments. Its offerings include standard barrier units used in roadway safety applications, with an emphasis on flexible rental and delivery options depending on project duration.
Industry Leader Moves: Consolidation Reshapes the Construction Material Market
While barrier suppliers compete on quarry proximity and MASH-compliant inventory, the material producers that ultimately feed their supply chains are moving through their most active consolidation stretch in years. Six developments between February and August 2026 illustrate the direction of travel and none carry equal weight, so the largest, most capital-intensive deals get the most space here.
CRH plc $8.5 billion Arcosa acquisition
On June 22, 2026, CRH agreed to acquire Arcosa, Inc. for $150 per share in an all-cash transaction valuing the Dallas-based aggregates and infrastructure-products supplier at approximately $8.5 billion, or 11.5x 2026 estimated EBITDA. Arcosa's Construction Products business brings 109 quarries and yards, nine asphalt plants, 19 terminals, and roughly 35 million tons of 2025 aggregates shipments; combined with CRH's existing footprint, the deal builds an aggregates platform exceeding 265 million tons of annualized production. CRH also disclosed $1.4 billion spent on 17 smaller bolt-on acquisitions through the first half of 2026, including Utah-based Pisgah Stone Products in August, reinforcing what CEO Jim Mintern has called an "aggregates-led, connected portfolio" strategy. The transaction is expected to close in the first quarter of 2027, subject to Arcosa shareholder and regulatory approval.
Martin Marietta Materials, Inc. $13.5 billion Lhoist North America combination
Martin Marietta completed its combination with Lhoist North America (LNA) on August 21, 2026, roughly two months after the deal was announced on June 29. The transaction, valued at $13.5 billion including debt and funded through $7 billion in cash plus $6.5 billion in Martin Marietta stock, adds LNA's high-calcium and dolomitic lime and industrial-minerals business, which serves steel manufacturing, infrastructure, and heavy nonresidential construction end markets. Company leadership said the deal establishes Martin Marietta as the nation's leading producer of limestone products. It follows a February 2026 asset exchange with Quikrete Holdings roughly 20 million tons of annual aggregates capacity in Virginia, Missouri, Kansas, and British Columbia, plus $450 million in cash, swapped for a Texas cement plant and ready-mix assets and an April 2026 agreement to acquire Midwestern aggregates producer New Frontier Materials, all under the company's "SOAR 2030" strategic plan.
Vulcan Materials Company aggregates-led portfolio realignment
On June 8, 2026, Vulcan Materials the largest U.S. producer of construction aggregates completed a portfolio swap rather than a straightforward acquisition: it divested its California ready-mixed concrete operations to CalPortland while acquiring the southern Colorado and Dallas-Fort Worth operations of Brannan Sand & Gravel, including a rail-connected quarry with long-term reserves near Lamar, Colorado. CEO Ronnie Pruitt described the moves as sharpening Vulcan's "aggregates-led growth strategy," a framing echoed almost verbatim by CRH and Martin Marietta in the same window a sign that the largest North American producers are converging on the same playbook: shed lower-margin concrete and distribution assets, concentrate on quarry reserves.
Compagnie de Saint-Gobain S.A. construction chemicals expansion
Saint-Gobain acquired Xypex, a Richmond, B.C.-based manufacturer of crystalline concrete waterproofing admixtures, coatings, and additive products, in a deal disclosed July 6, 2026. The acquisition extends a run of construction-chemicals bolt-ons under Saint-Gobain's "Lead & Grow" strategy a category NMSC separately quantifies in its Construction Chemicals Market report, which projects the segment to reach $93.49 billion by 2030. Saint-Gobain followed the Xypex deal with two Asia-Pacific acquisitions in late July a plasterboard facility in Vietnam and a building-materials business in Japan after reporting 9% local-currency sales growth in the region in the first quarter of 2026.
ArcelorMittal S.A. steel capacity and reinforcement supply
Structural and reinforcing steel underpins barrier design as much as concrete does, and ArcelorMittal took a final investment decision on a new electric arc furnace at Dunkirk, France (roughly €1.3 billion gross) on February 10, 2026. The company guided full-year 2026 capital expenditure to $4.5–5.0 billion and reported second-quarter EBITDA of $143 per tonne, up from a historical 2012–2019 average of $89 per tonne, while continuing to evaluate an 8.2-million-tonne first-phase greenfield steel plant in Andhra Pradesh, India, as part of a stated pathway toward 40 million tonnes of steelmaking capacity.
Holcim Ltd the backdrop to 2026's consolidation wave
Much of 2026's activity follows a template Holcim set in June 2025, when it completed the 100% spin-off of its North American operations into Amrize, an independent, separately listed company (NYSE: AMRZ) that Reuters valued at roughly $30 billion at the time. Splitting Holcim's international cement and ready-mix business from Amrize's North American building-solutions portfolio gave both companies sharper strategic focus a rationale CRH, Martin Marietta, and Vulcan have each echoed in their own 2026 portfolio moves.
Construction Material Industry Leader Moves, 2025–2026
|
Company |
Move |
Date |
Disclosed value |
|
CRH plc |
Agreement to acquire Arcosa, Inc. (U.S. aggregates & infrastructure products) |
Jun 22, 2026 |
~$8.5B (11.5x 2026E EBITDA) |
|
Martin Marietta Materials |
Completed combination with Lhoist North America (lime & industrial minerals) |
Aug 21, 2026 |
$13.5B (incl. debt) |
|
Vulcan Materials Company |
Divested CA ready-mix concrete; acquired Brannan Sand & Gravel's CO/TX aggregates ops |
Jun 8, 2026 |
Not disclosed |
|
Compagnie de Saint-Gobain |
Acquired Xypex (concrete waterproofing admixtures) |
Jul 6, 2026 |
Not disclosed |
|
ArcelorMittal S.A. |
Final investment decision on new EAF at Dunkirk |
Feb 10, 2026 |
~€1.3B gross |
|
Holcim Ltd |
Completed spin-off of North American business as Amrize (NYSE: AMRZ) |
Jun 23, 2025 |
~$30B valuation |
Industry impact summary: North America's largest aggregates and cement producers are converging on the same strategy at the same time: concentrate on quarry reserves and industrial minerals, shed lower-margin concrete and distribution assets, and let specialty players like Saint-Gobain consolidate the higher-margin chemicals layer. For barrier suppliers, that means fewer, larger upstream counterparties controlling raw-material pricing and logistics.
-
CRH's Arcosa deal and Martin Marietta's Lhoist combination are 2026's two largest construction-material transactions, together exceeding $22 billion.
-
CRH, Martin Marietta, and Vulcan Materials each executed an "aggregates-led" portfolio move in 2026 acquiring quarry reserves while divesting ready-mix concrete assets.
-
Saint-Gobain's Xypex acquisition signals continued consolidation in construction chemicals, the fastest-growing material segment at a 5.6% CAGR (2026–2035).
-
Steel capacity investment from ArcelorMittal supports the reinforcement inputs barrier and infrastructure producers depend on.
Key Considerations When Evaluating Concrete Barrier Suppliers
Selecting a supplier for concrete barriers involves more than product availability. Several operational, technical, and increasingly macroeconomic factors influence project performance:
-
Geographic coverage. Delivery capability is often a determining factor, especially for projects in remote or multi-state locations.
-
Supply model (manufacturing vs. brokerage). Some suppliers produce barriers directly, while others operate through inventory networks or brokerage systems, each affecting lead time and pricing structure differently.
-
Compliance and specifications. Barriers used in public infrastructure projects often need to meet DOT specifications and crash-safety standards such as MASH TL-3 or TL-4, depending on application.
-
Logistics capability. Given the weight and size of precast barriers, transport planning and delivery coordination remain critical to supplier performance.
-
Project timeline alignment. Lead times, rental availability, and stock readiness can significantly affect construction scheduling.
-
Raw-material cost exposure. A U.S. Trade Representative Section 301 investigation opened in March 2026 into steel, cement clinker, rebar, and related construction inputs layered on top of existing duties affecting Canadian and Mexican cement imports has added a new source of price volatility that project owners are now factoring into fixed-price barrier contracts.
Construction Material Market Segmentation by Material Type
Cementitious products and aggregates together anchor the categories that feed barrier production; construction chemicals, though comparatively small, is the segment growing fastest.
Construction Material Market Size by Material Type, 2025–2035
|
Material type |
2025 (USD trillion) |
2035 (USD trillion) |
Note |
|
Cementitious Products |
0.30 |
0.40 |
Largest segment; Portland/blended cement and ready-mix concrete |
|
Aggregates & Fillers |
0.30 |
0.40 |
Core input for concrete barrier and precast production |
|
Metals |
0.30 |
0.30 |
Structural and reinforcing steel |
|
Ceramics & Clay-Based Products |
0.10 |
0.20 |
Tile and clay-based building products |
|
Construction Chemicals & Coatings |
0.10 |
0.10* |
Fastest-growing segment (5.6% CAGR, 2026–2035, per NMSC) |
|
Insulation Materials |
<0.10 |
0.10 |
Growing with building-energy mandates |
*Rounded to the nearest USD 0.1 trillion; NMSC separately states Construction Chemicals & Coatings as the fastest-growing material type by CAGR despite the rounded totals appearing flat. Source: Next Move Strategy Consulting, Construction Material Market Size & Growth 2025–2035.
Comparative Overview of Supply Models
The companies profiled above reflect four primary operating models in the concrete barrier supply market:
-
Brokerage and distribution-focused suppliers that prioritize inventory access and fast procurement.
-
Regional precast manufacturers that integrate barrier production into broader concrete product lines.
-
Full-service concrete contractors that include barrier supply as part of larger infrastructure service offerings.
-
Rental and logistics providers that support temporary traffic-management needs.
Each model serves different project requirements depending on scale, urgency, and specification complexity but 2026's wave of upstream consolidation among aggregates and cement majors is narrowing the number of independent counterparties supplying the raw inputs behind all four models, a dynamic worth watching for any project team building a multi-year procurement plan.
Future Outlook for the Construction Material Market
NMSC's forecast points to steady rather than explosive growth for the Construction Material Market overall a 2.9% CAGR through 2035 but with clear pockets of acceleration: construction chemicals and coatings (5.6% CAGR), online/digital procurement channels (8.0% CAGR), and the Middle East & Africa region (5.8% CAGR), driven by Gulf giga-projects and Sub-Saharan African urbanization. For barrier suppliers, the more immediate signal is upstream: as CRH, Martin Marietta, and Vulcan Materials consolidate aggregates reserves and Saint-Gobain expands its chemicals portfolio, project owners sourcing barriers over the next several years will likely be negotiating with fewer, larger, and more vertically integrated raw-material suppliers than they were in 2025.
Future outlook summary: Growth in the broader Construction Material Market will be steady rather than dramatic, but the supplier landscape feeding barrier production is consolidating faster than the market itself is growing.
-
Construction Chemicals & Coatings, Online Retail distribution, and Middle East & Africa are the three fastest-growing categories tracked through 2035.
-
2026's aggregates M&A wave (CRH, Martin Marietta, Vulcan) is likely to continue reducing the number of independent upstream suppliers.
-
Trade-policy developments, including the March 2026 Section 301 investigation into steel and cement inputs, remain an open variable for barrier procurement costs.
Segment-level forecasts, regional breakdowns, and full competitive benchmarking sit behind the figures cited in this review. Download Free Sample
Conclusion
The market for concrete barrier supply remains diverse, spanning specialized precast manufacturers, logistics-driven distributors, and integrated construction service providers no single supplier type fits every project scenario. What has changed since this review last ran is the ground beneath those suppliers: the Construction Material Market's largest upstream producers spent 2026 consolidating aggregates reserves, industrial minerals, and construction chemicals at a pace not seen in years. For large-scale infrastructure work, compliance documentation, delivery reliability, and production capacity remain as important as product availability but understanding who now controls the raw-material supply chain behind each barrier supplier has become part of that evaluation too.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.











Add Comment