Smart Glasses in 2025: The Future of Wearable Tech
Introduction
The global smart glass market stands at a pivotal inflection point, driven by the convergence of stringent building energy mandates, accelerating electric vehicle adoption, and the commercial maturation of electrochromic and suspended particle device (SPD) technologies. According to Next Move Strategy Consulting's Smart Glass Market report, the global smart glass market was valued at USD 6.02 billion in 2023 and is projected to reach USD 11.74 billion by 2030, growing at a CAGR of 10.0% from 2024 to 2030. This trajectory is not incidental — it is the direct result of regulatory pressure on building envelopes, OEM-level integration of dynamic glazing into premium and electric vehicle platforms, and the expanding role of smart glass in commercial aviation.
For C-level executives and institutional investors evaluating materials science and advanced construction technology, the smart glass market presents a rare combination of regulatory tailwinds, cross-sector demand, and defensible intellectual property. The market's growth is being shaped by concrete, traceable events: the European Union's revised Energy Performance of Buildings Directive (EPBD) mandating national renovation plans with a transposition deadline of 29 May 2026, and the debut of dual-technology smart glass stacks in flagship automotive concept vehicles at global motor shows. These are not peripheral signals — they are structural demand catalysts that are reshaping procurement decisions across architecture, automotive, and aerospace.
For More Information: Download FREE Sample on Smart Glass Market Report
When Glass Becomes Infrastructure: The Dual-Technology Breakthrough Redefining Automotive and Architectural Glazing
The Mercedes-Benz Vision V: A Commercial Signal Disguised as a Concept Car
In April 2025, Gauzy Ltd. (NASDAQ: GAUZ) announced that Mercedes-Benz had selected its dual smart glass technology stack — combining both Suspended Particle Device (SPD) and Polymer Dispersed Liquid Crystal (PDLC) technologies — for approximately 75% of the glazing in the Vision V show car, unveiled at Auto Shanghai 2025.
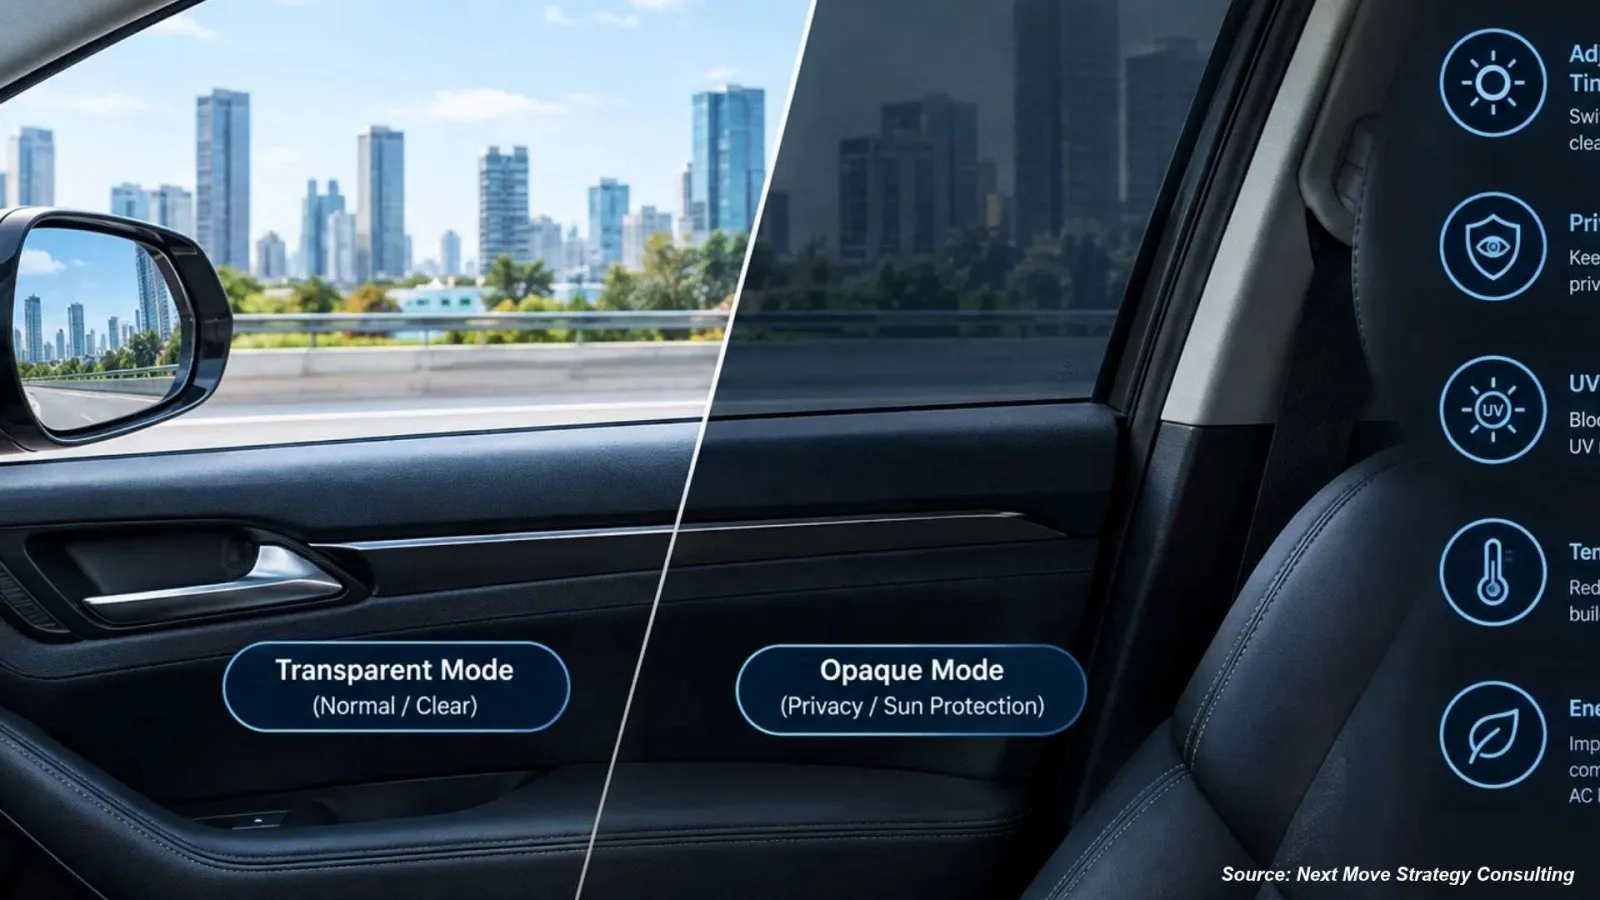
This was the first time Mercedes-Benz selected Gauzy's dual-technology configuration — combining both SPD and PDLC into a singular glass unit — enabling seamless transitions between transparent, shaded, and fully private states across the vehicle's side and quarter windows, while simultaneously creating a projection surface for immersive passenger experiences. A segmented PDLC smart partition further separates the driver and passenger cabins, offering adaptive privacy zones that reconfigure the interior environment on demand.
The significance of this deployment extends well beyond a single concept vehicle. Mercedes-Benz has already integrated SPD technology across five serial production models, including the Maybach S-Class and the SL Roadster, through its Magic Sky Control panoramic roof system. The Vision V's dual-stack configuration signals the next phase: the consolidation of multiple dynamic glazing functions into a single, vertically integrated glass unit that addresses glare mitigation, thermal management, privacy, and digital display within one component. For automotive OEMs managing the thermal load challenges of battery electric vehicles — where cabin cooling directly affects range — this is a material engineering solution with measurable commercial value.
The Architectural Pivot: From Specification to Mandate
The architectural segment is undergoing a parallel transformation, but driven by regulatory compulsion rather than OEM innovation cycles. The revised EU Energy Performance of Buildings Directive (EPBD, EU/2024/1275), which entered into force on 28 May 2024 with a national transposition deadline of 29 May 2026, mandates that EU member states reduce the average primary energy use of residential buildings by 16% by 2030 and between 20–22% by 2035. For non-residential buildings, the directive requires the renovation of the 16% worst-performing buildings by 2030 and 26% by 2033.
Buildings currently account for approximately 40% of total energy consumed in the EU, with around 85% of the existing building stock constructed before 2000 and 75% classified as having poor energy performance. Dynamic glazing — which modulates solar heat gain and visible light transmission without mechanical shading — is one of the few envelope-level interventions that can deliver measurable energy reductions without structural alteration, making it directly relevant to the renovation pathways the EPBD mandates.
The U.S. Department of Energy has quantified this impact: dynamic glazing can reduce building energy use by up to 20–30%, a figure cited by Gauzy in its August 2025 announcement of its selection as the exclusive smart glass supplier for a Fortune 100 U.S. financial institution, with installations already completed across offices in Texas, Florida, and Pennsylvania as part of a multi-phase nationwide rollout.
The Aeronautics Dimension: Cockpit Shading as a Recurring Revenue Platform
The aerospace segment adds a third demand vector that is structurally distinct from both automotive and architectural channels. Gauzy's aeronautics division holds approximately 95% market share in cockpit shading — a position the company projects will generate USD 240 million in revenue over the next ten years — and has expanded into commercial cabin shading through a cooperation agreement with Air France for its La Première first-class suites on Boeing 777 models. The aeronautics channel is particularly attractive from an investor standpoint because aircraft cabin specifications are locked in for the duration of a fleet's operational life, creating long-duration, low-churn revenue streams that are structurally different from the project-by-project dynamics of architectural glazing.
NMSC Strategic Perspective: What the Convergence of Regulatory and OEM Demand Means for Market Structure
NextMSC primary research and analysis identifies the current period as a structural inflection point for the smart glass market, characterized by three simultaneous demand accelerators that are compressing the technology's adoption curve in ways that were not present in prior growth cycles.
First, the EPBD's mandatory renovation targets create a non-discretionary demand floor for high-performance glazing across the EU's 27 member states. Unlike incentive-based programs, which are subject to budget cycles and political variability, minimum energy performance standards create procurement obligations that building owners cannot defer indefinitely. This converts a portion of smart glass demand from discretionary capital expenditure into compliance-driven spending — a fundamentally different demand quality.
Second, the automotive sector's transition to battery electric vehicles is creating a new engineering rationale for dynamic glazing that did not exist in internal combustion engine platforms. In BEV architectures, every watt of cabin cooling load that can be offset by solar heat gain reduction through smart glass directly extends driving range — a metric that OEMs and consumers treat as a primary purchase criterion. This creates a performance-based specification argument for smart glass that is independent of luxury positioning, expanding the addressable vehicle segments beyond premium and ultra-premium tiers.
Third, the vertical integration of smart glass supply chains — exemplified by Gauzy's model of controlling SPD film manufacturing, lamination, and controls — is enabling OEM-grade quality consistency and faster time-to-market that was previously unavailable from fragmented component suppliers. This supply chain maturation is a prerequisite for high-volume automotive adoption and is now sufficiently advanced to support serial production commitments.
NextMSC primary research and analysis projects that the construction segment — spanning both residential and commercial applications — will remain the largest application category through 2030, while the automotive and transportation segment will deliver the highest incremental growth rate, driven by EV platform proliferation and the expanding specification of dynamic glazing beyond panoramic roofs into side windows, quarter windows, and interior partitions.
Section Summary: The smart glass market's current growth phase is being driven by three structurally distinct but mutually reinforcing demand channels: EU regulatory mandates on building energy performance, OEM-level integration of dual-technology dynamic glazing in electric vehicle platforms, and long-duration aeronautics supply agreements. Each channel has a different demand quality — compliance-driven, performance-driven, and contract-driven — which collectively reduce the market's sensitivity to any single economic cycle.
Key Takeaways:
-
Mercedes-Benz's Vision V deployed Gauzy's dual SPD+PDLC stack across 75% of vehicle glazing at Auto Shanghai 2025, marking the first dual-technology automotive integration and signaling the next phase of OEM smart glass specification.
-
The EU EPBD's 29 May 2026 transposition deadline converts building envelope performance from a discretionary upgrade into a compliance obligation across 27 member states, creating a non-discretionary demand floor for high-performance glazing.
-
Gauzy's 95% cockpit shading market share in aeronautics, combined with its Air France La Première cabin shading contract, demonstrates that smart glass has achieved mission-critical status in commercial aviation — a segment with structurally long contract durations.
-
The U.S. Department of Energy's quantification of 20–30% building energy savings from dynamic glazing provides the performance benchmark that institutional real estate owners are using to justify smart glass specifications in office modernization programs.
Industry Impact Analysis
The Saint-Gobain–AGC Electrified Furnace Partnership: Decarbonizing the Supply Chain
On 8 June 2026, Saint-Gobain and AGC Group announced a collaboration to deploy the world's first large-scale hybrid highly electrified furnace for flat glass production at Saint-Gobain's plant in Avilés, Spain. The furnace, funded in part by the European Union Emissions Trading System (ETS) Innovation Fund, is expected to reach 75% electrification of the melting process, avoid approximately 80 kt CO₂eq emissions per year — representing a 50% reduction compared to a conventional gas furnace — and save approximately 265 GWh of natural gas per year. Construction is scheduled to begin in January 2027, with production resuming in the second half of 2027.
This development has direct implications for the smart glass market's supply chain economics. Smart glass substrates — particularly electrochromic and PDLC glass — are manufactured on float glass production lines that share the same energy-intensive melting processes as conventional flat glass. A 50% reduction in direct CO₂ emissions from flat glass production lowers the embodied carbon of smart glass products, which is increasingly a specification criterion in green building certification schemes such as LEED and BREEAM. As life-cycle global warming potential disclosure becomes mandatory for new EU buildings from January 2028 under the EPBD's Delegated Regulation (EU/2026/52), lower-carbon glass substrates will carry a measurable competitive advantage in architectural specifications.
"Our technological partnership with AGC now reaches a new milestone with the deployment of the world's first large-scale hybrid electric furnace for flat glass production. This breakthrough demonstrates our ability to transform pioneering technologies into industrial reality positioning Saint-Gobain as the go-to partner for customers committed to lower-carbon solutions," said Nicolas Miègeville, Chief Technology Officer of Saint-Gobain, in the company's official announcement dated 8 June 2026.
Gauzy's FY2024 Performance: Validating the Multi-Sector Smart Glass Model
Gauzy's FY2024 financial results, published in June 2025, provide the most granular publicly available evidence of smart glass market demand across multiple end-use sectors. The company reported full-year revenue of USD 103.5 million, a 33% year-over-year increase, with Q4 2024 delivering record gross margins of 36.5% and positive Adjusted EBITDA. The company's certified partner distribution channel exceeded 100 partners serving more than 60 countries, with architectural projects spanning airports in India and Singapore and the Washington Monument in Washington, D.C.
The company's Smart-Vision® Camera Monitor Systems (CMS) — an ADAS product line that leverages the same light and vision control technology platform as its smart glass products — were installed in over 15,000 commercial vehicles globally as of mid-2025, with supply partnerships including Yutong, the world's largest commercial bus manufacturer, and distribution agreements with Journeo and Luminator Technology Group. This cross-sector revenue diversification — spanning architecture, automotive, aeronautics, and safety technology — demonstrates that the smart glass market's growth is not concentrated in a single application vertical.
IEA Energy Efficiency 2025: The Macro Context for Smart Glass Demand
The International Energy Agency's Energy Efficiency 2025 report, published in November 2025, found that global energy efficiency improvement reached approximately 1.8% in 2025, up from around 1% in 2024 — but still well below the COP28 target of 4% annual improvement by 2030. The IEA's analysis identified building envelopes — including insulation and windows — as a primary lever for closing this gap, noting that combined spending on building retrofits and envelopes in China, the U.S., and the EU increased more than 20% to approximately USD 120 billion in 2024 since 2019.
The IEA's finding that energy for space cooling has grown more than 4% per year since 2000 — the fastest growth of any end-use in buildings — is particularly relevant to the smart glass market. Dynamic glazing that reduces solar heat gain directly addresses cooling load, which is the fastest-growing component of building energy demand. In climates where cooling dominates the energy profile, smart glass delivers its highest return on investment precisely where the IEA identifies the greatest efficiency gap.
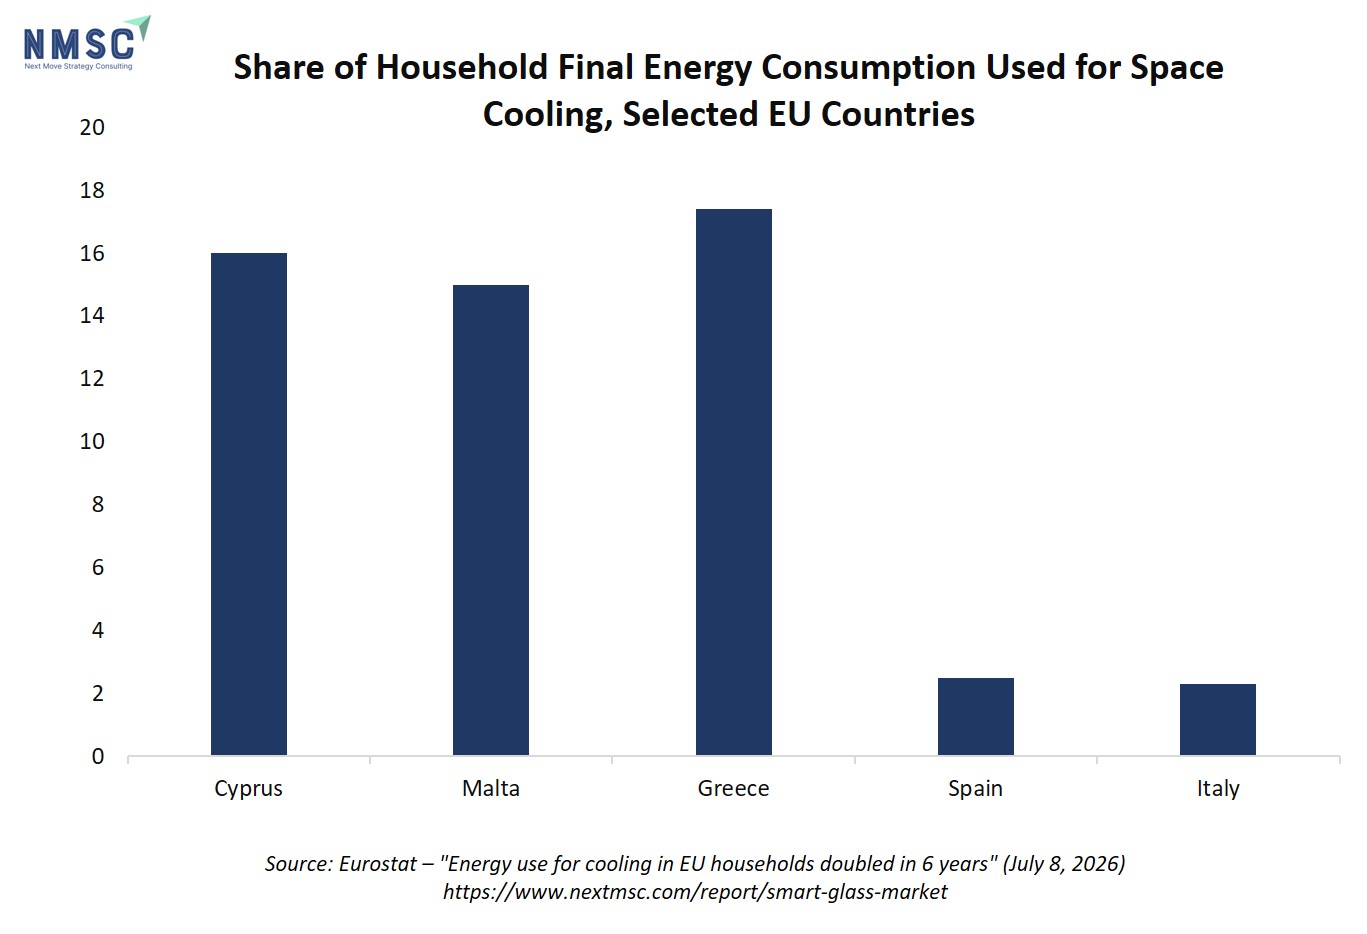
Section Summary: The industry impact of current market developments is operating on three levels simultaneously: supply chain decarbonization (Saint-Gobain–AGC electrified furnace), demand-side validation through commercial deployments (Gauzy's Fortune 100 institutional contract and FY2024 revenue growth), and macro-level policy pressure (IEA's identification of building envelopes as a primary energy efficiency lever). Together, these forces are compressing the smart glass market's adoption timeline.
Key Takeaways:
-
Saint-Gobain and AGC's world-first large-scale hybrid electrified furnace, announced June 2026, will reduce flat glass production CO₂ emissions by approximately 50% — lowering the embodied carbon of smart glass substrates at a time when life-cycle carbon disclosure is becoming mandatory under EU law.
-
Gauzy's 33% revenue growth to USD 103.5 million in FY2024 and its selection as exclusive smart glass supplier to a Fortune 100 U.S. financial institution confirm that institutional-grade commercial deployments are now operational, not merely in pilot phase.
-
The IEA's identification of space cooling as the fastest-growing building energy end-use since 2000 — growing more than 4% per year — creates a direct, quantifiable performance case for dynamic glazing in markets where cooling loads dominate.
-
Combined building retrofit and envelope spending in China, the U.S., and the EU reached approximately USD 120 billion in 2024, establishing the capital pool from which smart glass specifications are being funded.
Pros and Cons of Recent Market Developments
|
Development |
Pros |
Cons |
|
EU EPBD Transposition (May 2026) |
Creates non-discretionary demand for high-performance glazing across 27 EU member states; renovation of 16% worst-performing non-residential buildings by 2030 mandated |
Implementation pace varies by member state; annual renovation rate remains at 1%, indicating execution risk in translating policy into procurement |
|
Gauzy–Mercedes-Benz Vision V Dual-Stack Deployment (April 2025) |
First dual SPD+PDLC integration in a flagship OEM vehicle validates multi-function glazing as a serial production pathway; strengthens Gauzy's position with Tier-1 automotive suppliers |
Concept vehicle deployments do not guarantee serial production timelines; OEM capital allocation decisions can shift between design cycles |
|
Saint-Gobain–AGC Electrified Furnace Partnership (June 2026) |
Reduces embodied carbon of flat glass substrates by ~50%, improving smart glass's life-cycle carbon profile ahead of mandatory EU disclosure requirements from 2028 |
Construction begins January 2027 with production resuming H2 2027; near-term supply chain carbon benefits are not yet realized |
|
Gauzy Fortune 100 Institutional Contract (August 2025) |
Establishes a no-substitution specification template for financial services office environments; creates recurring demand through multi-phase nationwide rollout |
Client identity undisclosed, limiting third-party verification; institutional real estate capex cycles are sensitive to interest rate environments |
|
IEA Energy Efficiency 2025 Report |
Confirms building envelopes as a primary efficiency lever; USD 120B in combined retrofit spending validates the capital pool available for smart glass specifications |
Global efficiency improvement of 1.8% remains well below the COP28 target of 4% annually, indicating that policy ambition has not yet translated into proportionate deployment velocity |
Key Data & Statistics
Key Industry Developments and Quantified Impact
|
Event |
Entity |
Date |
Quantified Impact |
|
Dual SPD+PDLC smart glass in Mercedes-Benz Vision V |
Gauzy Ltd. / Mercedes-Benz |
April 2025 |
~75% of vehicle glazing area covered; first dual-technology OEM integration |
|
FY2024 Revenue & Margin Results |
Gauzy Ltd. (NASDAQ: GAUZ) |
June 2025 |
USD 103.5M revenue (+33% YoY); Q4 2024 gross margin 36.5% (record) |
|
Exclusive Fortune 100 institutional smart glass contract |
Gauzy Ltd. |
August 2025 |
Multi-phase nationwide rollout; DOE-cited 20–30% building energy savings from dynamic glazing |
|
Air France La Première cabin shading on Boeing 777 |
Gauzy Ltd. / Air France |
2025 |
95% cockpit shading market share; USD 240M projected 10-year aeronautics revenue |
|
World's first large-scale hybrid electrified flat glass furnace |
Saint-Gobain / AGC |
June 2026 |
~80 kt CO₂eq avoided/year; ~50% emissions reduction vs. conventional furnace; ~265 GWh gas saved/year |
|
EU EPBD transposition deadline |
European Commission |
May 2026 |
16% residential primary energy reduction by 2030; 16% worst non-residential buildings renovated by 2030 |
|
Global building retrofit & envelope spending |
IEA |
2024 data |
USD ~120B combined spend in China, U.S., EU (2024); up >20% since 2019 |
Future Outlook & Forecast
NMSC Market Trajectory: From USD 6.02 Billion to USD 11.74 Billion
NextMSC primary research and analysis projects the global smart glass market to nearly double from its 2023 base of USD 6.02 billion to USD 11.74 billion by 2030, at a CAGR of 10.0%. This growth trajectory is underpinned by demand across all four primary end-use segments — architectural, automotive, avionics, and marine — with the construction segment maintaining volume leadership and the automotive and transportation segment delivering the highest incremental growth rate as EV platform proliferation expands the addressable specification window for dynamic glazing beyond panoramic roofs.
North America is projected to maintain the largest regional market share through 2030, supported by the concentration of key technology developers and manufacturers, the prevalence of adverse weather conditions that create year-round demand for thermally efficient glazing, and the institutional real estate sector's growing adoption of smart glass as a sustainability and occupant experience differentiator. The Asia-Pacific region is projected to deliver the strongest growth rate, driven by commercial construction activity in China and India, the expansion of the electronics and transportation industries, and increasing government investment in smart city infrastructure.
The Electrochromic Technology Trajectory
Within the active smart glass technology segment, electrochromic glass — which changes tint in response to an applied electrical voltage and retains its tinted state without continuous power draw — is positioned for accelerating adoption in commercial building applications. The technology's ability to reduce solar heat gain without blocking outward visibility, combined with its compatibility with building automation and control systems (a requirement introduced for non-residential buildings under the revised EPBD), makes it a natural fit for the renovation programs that EU member states are now obligated to implement.
The passive smart glass segment — comprising photochromic and thermochromic glass — serves a different market function, offering lower-cost, electricity-free light control for applications where dynamic switching is not required. This segment is particularly relevant to residential construction in markets where the cost premium of active smart glass remains a barrier to specification.
The Solar Integration Opportunity
One of the most consequential long-term growth vectors identified by NextMSC primary research and analysis is the integration of smart glass with building-integrated photovoltaics (BIPV). Gauzy's debut of a smart glass BIPV solution — designed to harvest solar energy to power smart glass and other building electronics — represents an early commercial manifestation of this convergence. The EPBD's requirement that new buildings be "solar-ready" — meaning fit to host photovoltaic or solar thermal installations — creates a regulatory framework that is structurally compatible with BIPV-integrated smart glass, potentially expanding the addressable market for smart glass beyond its current glazing-replacement function into a broader energy generation and management role.
Section Summary: The smart glass market's path to USD 11.74 billion by 2030 is supported by a combination of regulatory mandates, technology maturation, and cross-sector OEM adoption that collectively reduce the market's dependence on any single demand driver. The emergence of BIPV-integrated smart glass represents a potential step-change in the market's addressable opportunity beyond the current forecast horizon.
Key Takeaways:
-
NextMSC primary research and analysis projects a 10.0% CAGR from 2024 to 2030, with the market reaching USD 11.74 billion — nearly doubling from the 2023 base of USD 6.02 billion.
-
North America retains regional market leadership through 2030, while Asia-Pacific delivers the highest growth rate, driven by commercial construction and transportation sector demand in China and India.
-
Electrochromic glass is positioned for accelerating commercial building adoption as EU member states implement EPBD-mandated renovation programs requiring building automation and control system integration.
-
The convergence of smart glass with BIPV technology — exemplified by Gauzy's solar-harvesting smart glass solution — represents a structural expansion of the market's addressable opportunity that extends beyond the current glazing-replacement value proposition.
Next Steps for Stakeholders
For C-Level Executives in Real Estate and Construction:
The EU EPBD's 29 May 2026 transposition deadline means that national minimum energy performance standards for non-residential buildings are now legally operative across EU member states. Executives managing commercial real estate portfolios in the EU should initiate glazing performance audits to identify assets in the 16% worst-performing non-residential building cohort targeted for renovation by 2030. Dynamic glazing specifications should be evaluated not only on upfront capital cost but on the life-cycle carbon disclosure obligations that become mandatory from January 2028 under Delegated Regulation EU/2026/52 — a metric on which lower-carbon smart glass substrates, such as those produced using Saint-Gobain and AGC's electrified furnace technology, will carry a measurable advantage.
For Automotive OEM Procurement and Engineering Leaders:
The Mercedes-Benz Vision V's dual SPD+PDLC deployment establishes a new benchmark for smart glass integration density in premium and electric vehicle platforms. Engineering teams evaluating glazing specifications for next-generation EV platforms should assess the thermal management contribution of dynamic glazing — specifically its capacity to reduce cabin cooling load and extend driving range — as a performance metric alongside privacy and aesthetic functions. Gauzy's prefabricated smart glass stack for automotive, announced as a strategic priority for 2025–2026, is designed to reduce integration complexity and enable high-volume adoption beyond concept vehicle applications.
For Institutional Investors:
The smart glass market's 10.0% CAGR through 2030, as projected by NextMSC primary research and analysis, is supported by demand drivers that are structurally distinct from discretionary consumer spending: regulatory compliance obligations, OEM serial production commitments, and long-duration aeronautics supply contracts. Investors evaluating exposure to this market should assess companies' vertical integration depth — specifically their control of core technology IP, manufacturing, and distribution — as the primary differentiator between commodity glazing suppliers and defensible technology platforms. Gauzy's 146 active global patents across SPD, PDLC, aeronautic light control, and ADAS technologies illustrate the IP density that characterizes the market's leading participants.
For Aerospace and Aviation Procurement Teams:
Gauzy's 95% cockpit shading market share and its Air France La Première cabin shading contract on Boeing 777 models demonstrate that smart glass has achieved mission-critical status in commercial aviation. Procurement teams evaluating cabin modernization programs should assess dynamic glazing not only as a passenger comfort feature but as a weight-reduction and maintenance-cost alternative to mechanical shading systems, which require moving parts and periodic replacement.
Conclusion
The global smart glass market is not growing because of a single technology breakthrough or a single policy initiative — it is growing because regulatory mandates, OEM engineering requirements, and institutional sustainability commitments have converged simultaneously across three of the world's largest capital-intensive industries: construction, automotive, and aerospace. The EU EPBD's binding renovation targets, Mercedes-Benz's dual-technology smart glass integration in the Vision V, Saint-Gobain and AGC's world-first electrified flat glass furnace, and Gauzy's institutional-grade commercial deployments are not isolated events. They are mutually reinforcing signals that the smart glass market has crossed the threshold from emerging technology to infrastructure-grade specification.
According to NextMSC primary research and analysis, the global smart glass market is projected to reach USD 11.74 billion by 2030 at a CAGR of 10.0% — a trajectory that reflects the compounding effect of compliance-driven architectural demand, performance-driven automotive adoption, and contract-driven aeronautics growth. For executives and investors who evaluate materials science markets through the lens of structural demand quality rather than cyclical volume, the smart glass market's current configuration presents a compelling case for strategic engagement.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.










Add Comment