The Future of Money Management: How Individuals and Businesses Can Stay Ahead
Two things happened in wealth management technology within days of each other in September 2026: Envestnet a platform already touching more than a third of U.S. financial advisors agreed to acquire Vestmark, a $2 trillion-asset trading and tax-technology provider. And the UK's Financial Conduct Authority published survey data showing nearly half the wealth-management industry is now using or actively planning to use AI. Neither event is isolated. Together, they capture where the WealthTech market actually is right now: consolidating fast, automating faster, and doing both under closer regulatory watch than a year ago.
Content: WealthTech Market Growth and the AI Adoption Curve
The scale of the opportunity is what's drawing this activity. Next Move Strategy Consulting (NMSC) estimates the global WealthTech market at USD 22.99 billion in 2025, growing to USD 71.59 billion by 2030 a 25.5% CAGR.
WealthTech Market size and growth
|
Metric |
Value |
Period |
|
Market size (base year) |
USD 18.32 billion |
2024 |
|
Market size |
USD 22.99 billion |
2025 |
|
Market size (forecast) |
USD 71.59 billion |
2030 |
|
Growth rate |
CAGR of 25.5% |
2025–2030 |
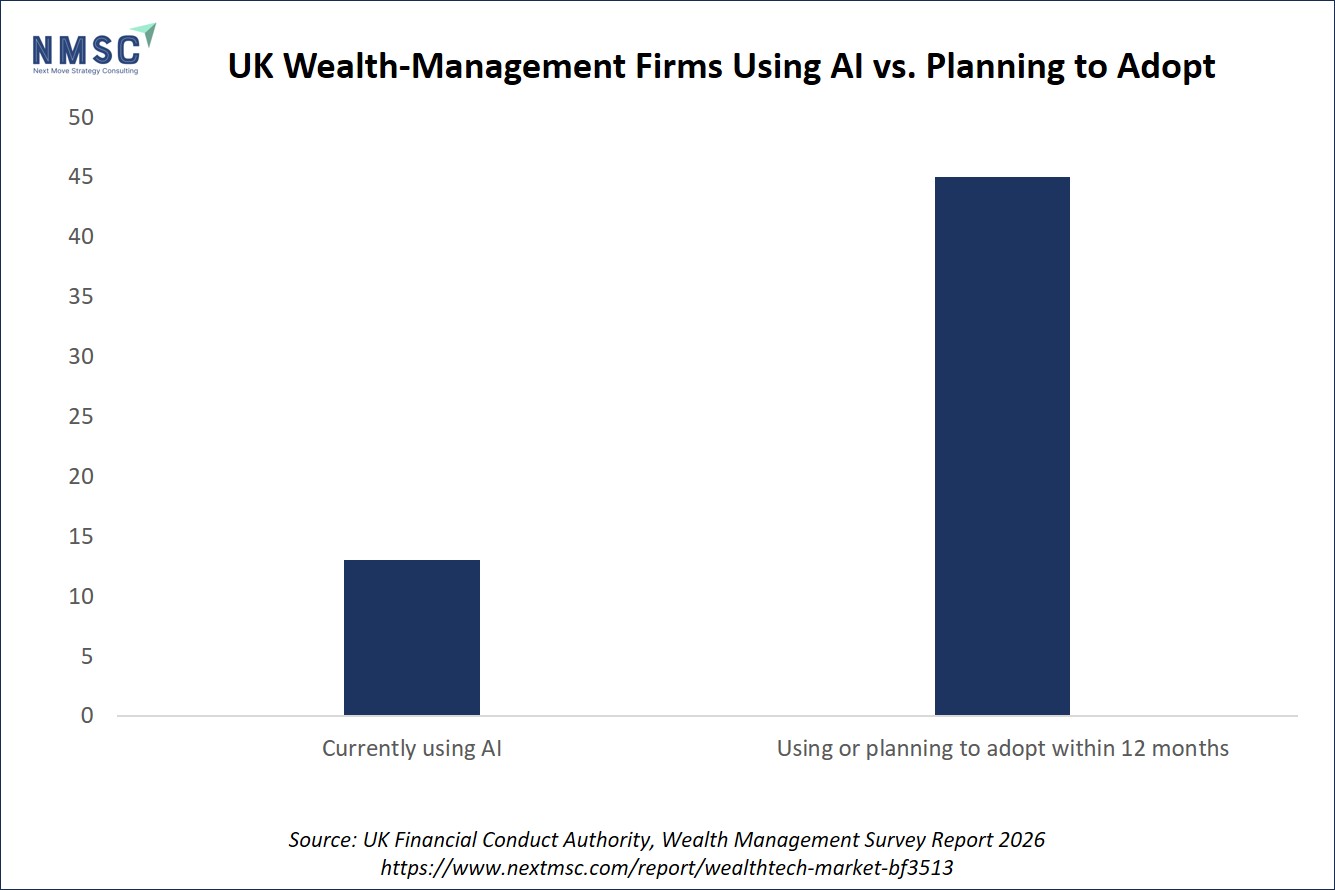
The clearest read on actual AI adoption as opposed to vendor marketing comes from the FCA's Wealth Management Survey Report 2026, published August 18, 2026. Across more than 400 supervised firms serving 5.5 million retail clients and managing almost £1 trillion in assets, 13% were already using in-house or third-party AI tools at the time of the survey, rising to 45% once firms planning adoption within 12 months are included. The regulator's own caveat is worth keeping: because the data reflects a single collection point, actual adoption today is likely already higher.
That adoption curve is showing up in concrete institutional commitments, not just pilots. That adoption curve is showing up in concrete institutional commitments, not just pilots. Research from Accenture has also found strong enthusiasm among financial advisors for AI in wealth management, with advisors seeing applications in areas such as client relationships, insight generation, and productivity. Accenture's research on AI in wealth management provides additional context on how advisors view AI adoption and its potential impact on the profession.
HSBC announced on July 27, 2026 that it will open a Global AI Centre of Excellence in Singapore, hiring more than 100 AI specialists alongside 100 new wealth relationship managers pairing the automation build-out with human headcount rather than substituting one for the other. Those pairing matters: the FCA's survey found the sector remains strongly relationship-led even as digital engagement expands, with firms still relying on direct interaction for the parts of the client relationship that carry the most judgment.
Section Summary: AI use across wealth-management firms has moved from experimentation to mainstream planning within a single year, but the data and the firms adopting fastest consistently point toward automation paired with human oversight rather than replacing it.
Key Takeaways:
-
WealthTech market size is projected to more than triple, from $23B (2025) to $71.6B (2030)
-
45% of FCA-supervised firms are now using or actively planning AI adoption, up from 13% currently in active use
-
HSBC's Singapore investment pairs 100+ AI hires with 100 new human wealth managers evidence of augmentation, not substitution
-
The sector remains relationship-led even as AI adoption accelerates
Industry Impact: Platform Consolidation Is Reshaping WealthTech
Two acquisitions this year illustrate how fast the ownership structure of wealth-management technology is shifting.
Recent WealthTech M&A milestones
|
Date |
Development |
Why It Matters |
|
Aug 26, 2026 |
Vanguard agrees to acquire Altruist, an AI-forward custody and advisor platform, for ~$4B Vanguard’s largest acquisition ever |
A $12T asset manager choosing to buy WealthTech infrastructure outright rather than partner with it |
|
Sep 9, 2026 |
Envestnet agrees to acquire Vestmark, adding $2T in assets and 5M+ accounts to its $8T platform |
Two of the NMSC report's own named key players merging trading, tax, and portfolio tools consolidating under one roof |
Both deals point the same direction: firms that already own distribution want to own the underlying trading, custody, and AI infrastructure too, rather than integrate with a third party. For smaller technology providers, that raises the bar interoperability alone is no longer a durable advantage if the larger platforms are simply acquiring the capability instead of connecting to it.
Regulators are watching the same shift from a different angle. The FCA's 2026 survey found that more than 92% of wealth-management firms outsource at least part of their operations, technology among the most common functions outsourced. As wealth firms modernize their broader operating infrastructure, automation is also extending into finance and administrative workflows, including procurement, invoice processing, and payment operations. Procure-to-pay software is one example of how these back-office processes can be digitized and managed through integrated workflows. The regulator's message was pointed: outsourcing brings expertise and scale, but it does not transfer regulatory responsibility firms remain accountable for outcomes even when the infrastructure underneath them belongs to someone else. That's a directly relevant caution as WealthTech platforms consolidate into fewer, larger providers.
Section Summary: WealthTech's technology layer is consolidating into fewer, larger platforms through direct acquisition rather than partnership, which raises real questions about vendor concentration even as it simplifies the buyer's stack.
Key Takeaways:
-
Vanguard's ~$4B Altruist deal and Envestnet's Vestmark acquisition both closed within two weeks of each other in late 2026
-
Consolidation is concentrating trading, custody, and AI capability inside a smaller number of platforms
-
92%+ of wealth firms outsource some technology function and regulators are explicit that outsourcing doesn't outsource accountability
Future Outlook: Where WealthTech Growth Meets Its Constraints
The growth case for WealthTech is strong, but it isn't unconditional. The Bank for International Settlements' Annual Economic Report 2026, published June 28, 2026, named the sustainability of AI-related investment as one of four global pressure points on financial stability flagging that AI capital expenditure is increasingly debt-financed, with productivity benefits that remain uneven across sectors. For WealthTech specifically, the relevant version of that risk is operational: as platforms consolidate and firms lean harder on shared AI infrastructure and cloud providers, a technology failure or breach at one concentrated provider has a larger downstream footprint than it would have a few years ago, when the market was more fragmented.
Tokenization adds a second frontier worth watching rather than betting on yet. State Street's institutional research, published July 2026, found tokenized real-world assets still represent roughly 2% of the average financial institution's portfolio small in absolute terms, but growing, and increasingly used for genuine collateral and liquidity management rather than speculation. That's a leading indicator, not a current allocation case: institutional infrastructure typically matures a year or two before retail-accessible products follow.
For individual investors, the practical takeaway across all of this is that "is an advisor worth it" is the wrong frame. The more useful question is what a given platform's technology stack lets an advisor do that a pure robo-tool can't, and where AI-driven automation is actually freeing up time for the judgment calls estate planning, tax strategy, and life transitions that remain hardest to automate. Investors considering professional advice can also evaluate whether a wealth manager is worth it based on the complexity of their financial situation, the level of guidance they need, and the value of ongoing support. For a closer look at the specific shifts driving this, see NMSC's related coverage of WealthTech market trends reshaping digital finance.
Section Summary: WealthTech's growth trajectory is real, but it now carries genuine operational-concentration risk as the market consolidates, and its newer frontiers like tokenization remain early-stage rather than mainstream.
Key Takeaways:
-
BIS flags AI investment sustainability as a financial-stability pressure point, with implications for concentrated WealthTech infrastructure
-
Tokenized real-world assets remain ~2% of institutional portfolios real momentum, not yet scale
-
Retail access to tokenized products typically lags institutional adoption by a year or more
-
The advisor-value question is shifting from "human vs. AI" to "what does this platform's AI free the advisor to do"
A 5-Step Plan to Get Ahead of the WealthTech Curve
-
Audit your current advisory or investment stack against what's now considered standard 45% of FCA-supervised firms are already there or planning to be within a year.
-
Evaluate hybrid platforms over pure robo-tools. The data consistently favors AI-plus-human models, not either extreme.
-
Track the M&A activity in your platform's category. Two major acquisitions closed within weeks of each other in 2026 know whether your provider is a likely acquirer or acquisition target.
-
Ask who's actually accountable when technology is outsourced. Regulators are explicit that vendor dependency doesn't reduce a firm's own responsibility for outcomes.
-
Treat tokenized assets as a small, monitored allocation, not a core strategy, while institutional infrastructure continues to mature.
The Future of Wealth Management Is Already Being Built
NMSC's forecast from roughly $23 billion in 2025 to $71.6 billion by 2030 isn’t a distant projection; it's already visible in the deals being signed and the adoption curves regulators are measuring in real time. For investors, that means more personalized, AI-assisted guidance than existed even a year ago. For advisors and platforms, the choice is increasingly whether to build the underlying infrastructure, buy it outright, or be acquired by a firm that already has. Full WealthTech Market Insights, Global Analysis & Forecast are available from NMSC for segment-level and regional detail.
For More Information: Download FREE Sample on WealthTech Market Report
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.




Add Comment