What’s Driving the Quantum Chip Market in 2025?
Introduction
The global quantum chip market is no longer a laboratory curiosity — it is a strategic industrial frontier attracting sovereign-level capital commitments, executive-order mandates, and a wave of public listings that signal a decisive shift from research to revenue. According to Next Move Strategy Consulting's Quantum Chip Market report, the global quantum chip market was valued at USD 0.60 billion in 2024 and is projected to reach USD 5.58 billion by 2030, growing at a CAGR of 44.8% from 2025 to 2030. This trajectory is underpinned by three converging forces: escalating defense and aerospace expenditure that demands quantum-grade secure computation, the rapid maturation of semiconductor fabrication techniques that is lowering the cost of qubit production, and a coordinated wave of government-backed manufacturing incentives that is reshaping the domestic supply chain architecture of quantum hardware.
The pace of change in this market has accelerated sharply in the first three quarters of 2026. Within a span of weeks, the United States government committed over USD 2 billion in CHIPS Act incentives to nine quantum companies, President Trump signed Executive Order 14413 establishing a whole-of-government quantum strategy, and Microsoft unveiled its Majorana 2 processor — a chip whose topological qubits are 1,000 times more reliable than its predecessor and whose commercial timeline has been cut in half. For C-level executives and institutional investors, the question is no longer whether quantum chips will matter, but which modalities, supply chain positions, and application verticals will capture disproportionate value as the market scales toward USD 5.58 billion by 2030.
For More Information: Download FREE Sample on Quantum Chip Market Report
From Lab to Ledger: The Policy and Hardware Inflection Reshaping the Quantum Chip Market
The $2 Billion CHIPS Act Catalyst: Domestic Quantum Foundry Infrastructure Takes Shape
The single most consequential structural event for the quantum chip market in 2026 was the U.S. Department of Commerce's announcement on May 21, 2026, of USD 2.013 billion in federal incentives under the CHIPS and Science Act, directed at nine quantum companies spanning five distinct hardware modalities. This was not a broad research grant — it was a targeted manufacturing infrastructure play. IBM received USD 1 billion in planned funding to establish a new quantum foundry subsidiary for quantum-grade superconducting wafers, while GlobalFoundries received USD 375 million to build a secure domestic quantum foundry capable of supporting superconducting, trapped ion, photonic, topological, and silicon spin architectures.
The remaining USD 638 million was distributed across seven quantum computing companies — Atom Computing, D-Wave, Infleqtion, PsiQuantum, Quantinuum, Rigetti, and Diraq — each tasked with resolving discrete, modality-specific engineering bottlenecks including device reproducibility, photonic loss, cryogenic systems integration, and ultra-fast readout electronics. The Department of Commerce will receive a minority, non-controlling equity stake in each company as a condition of funding — a structure that aligns taxpayer returns with commercial success and signals that Washington is treating quantum chip manufacturing with the same strategic seriousness it applied to classical semiconductor fabs under the broader CHIPS Act.
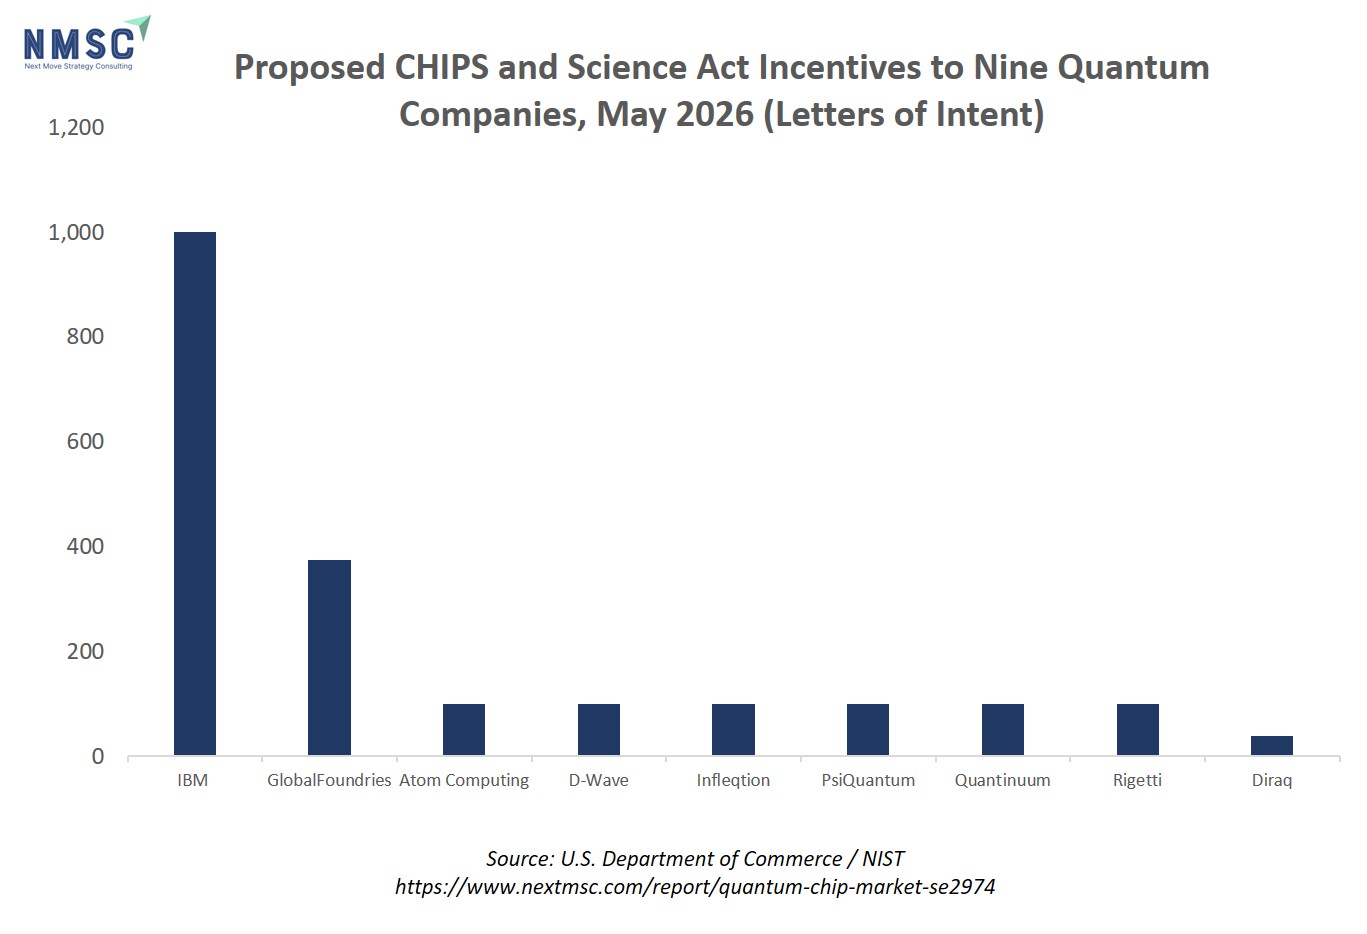
This investment directly addresses the most persistent structural constraint on quantum chip market growth: the absence of a scalable, domestic, multi-modality fabrication base. By simultaneously funding foundry infrastructure (IBM and GlobalFoundries) and the companies that will consume that foundry capacity (Atom Computing, Rigetti, Quantinuum, and others), the Commerce Department has created a vertically integrated demand signal that will accelerate the transition from bespoke, laboratory-scale chip production to repeatable, utility-scale manufacturing.
Executive Order 14413: A Whole-of-Government Quantum Mandate
One month after the CHIPS Act announcement, on June 22, 2026, President Trump signed Executive Order 14413, "Ushering in the Next Frontier of Quantum Innovation," establishing the Quantum Computer for Application Development and Discovery Science (QC-ADDS) Effort — a national program to deliver at least one utility-scale quantum computer to a Department of Energy facility and make it accessible to the scientific community. The order mandates the Secretary of War to identify at least three next-generation quantum sensor projects for field deployment by September 30, 2028, and directs the Secretary of Commerce to develop a plan for strengthening QIST supply chains and eliminating manufacturing barriers.
Critically, the order also directs the expansion of the Quantum Information Science and Technology Counterintelligence Protection Team (QCPT) and mandates coordination with allies to harmonize export controls and investment restrictions on quantum-enabling technologies — a direct response to China's USD 10 billion National Laboratory for Quantum Information Sciences and the recognition that Europe and the United Kingdom have collectively committed nearly three times as much public funding to quantum development as the United States.
Microsoft Majorana 2: A Materials Breakthrough That Halved the Commercial Timeline
At Microsoft Build 2026, the company unveiled Majorana 2, its next-generation topological quantum processor. The chip replaces the aluminum superconductor used in Majorana 1 with lead, combined with an updated semiconductor active region of indium arsenide and indium arsenide antimonide. The result is a topological gap more than double that of the previous processor, translating into qubit lifetimes that exceed 20 seconds — and in some cases surpass one minute — compared with the 1 to 12 milliseconds achieved by Majorana 1. This represents a greater than 1,000-fold improvement in qubit stability, achieved through AI-assisted materials design and fabrication.
The commercial implication is direct: Microsoft has cut its timeline to a scalable, practical quantum computer in half, now targeting 2029. DARPA has advanced Microsoft to the final phase of its Underexplored Systems for Utility-Scale Quantum Computing (US2QC) program — one of only two companies to reach this stage — where Microsoft intends to build a fault-tolerant prototype based on topological qubits. For the quantum chip market, this milestone matters because topological qubits are inherently smaller and require fewer error-correction overhead qubits than superconducting alternatives — a property that, if it scales as Microsoft's roadmap projects, would substantially reduce the chip area and cryogenic infrastructure required per logical qubit, lowering the total cost of ownership for enterprise quantum deployments.
IBM's Nighthawk and Kookaburra: Scaling Toward Quantum Advantage
IBM's 2026 quantum roadmap, updated in March 2026, positions the Nighthawk processor as the platform for exploring quantum advantage ahead of large-scale fault-tolerant systems. Nighthawk is expected to run circuits with 7,500 gates across up to three 120-qubit modules (360 qubits total) in 2026, scaling to 10,000 gates in 2027 and 15,000 gates in 2028. Simultaneously, IBM's Kookaburra processor — a 1,386-qubit multi-chip processor with a quantum communication link — is scheduled to demonstrate a single logical processing unit and quantum memory module before year-end, serving as the foundational building block for IBM's Starling large-scale fault-tolerant architecture.
In a proof point for near-term quantum utility, an IBM team in partnership with Cleveland Clinic and RIKEN used two quantum systems paired with two classical supercomputers to model a 12,635-atom protein complex in May 2026 — a computation that would be intractable on classical hardware alone. This demonstration directly expands the addressable market for quantum chips in pharmaceutical and materials science applications, where molecular simulation at this scale has immediate commercial value in drug discovery pipelines.
NMSC Strategic Perspective: What the Convergence of Policy, Hardware, and Capital Means for Market Structure
NextMSC primary research and analysis identifies three structural shifts that will define quantum chip market dynamics through 2030. First, the CHIPS Act foundry investments are bifurcating the competitive landscape into companies with domestic manufacturing access and those dependent on foreign or bespoke fabrication — a distinction that will increasingly determine which players can win government contracts and scale production. Second, the simultaneous maturation of multiple qubit modalities (superconducting, topological, neutral atom, trapped ion, photonic) means that no single architecture will dominate the 2025–2030 forecast period; instead, application-specific modality selection will become a key differentiator, with superconducting chips maintaining near-term volume leadership while topological and neutral atom architectures capture premium defense and cryptography segments. Third, the "harvest now, decrypt later" threat — in which adversaries collect encrypted data today for future quantum decryption — is converting quantum cryptography from a speculative application into an immediate procurement priority for financial institutions, defense agencies, and critical infrastructure operators, creating a demand pull for quantum chip production that is independent of the timeline to full fault tolerance.
Section Summary:
-
The quantum chip market's growth trajectory is being shaped by a convergence of sovereign capital deployment, hardware breakthroughs, and enterprise demand that is specific to this technology's unique security and computational properties.
-
The U.S. Department of Commerce committed USD 2.013 billion in CHIPS Act incentives to nine quantum companies in May 2026, establishing the first multi-modality domestic quantum foundry infrastructure.
-
Microsoft's Majorana 2 chip achieved qubit lifetimes exceeding 20 seconds — a 1,000-fold improvement over its predecessor — and cut the company's timeline to a scalable quantum computer to 2029.
-
IBM's Nighthawk processor targets 7,500-gate circuits across 360 qubits in 2026, with the Kookaburra multi-chip processor demonstrating the first logical processing unit and quantum memory module before year-end.
-
Executive Order 14413 mandates a whole-of-government quantum strategy, including quantum sensor deployment by 2028 and supply chain resilience measures targeting adversarial technology acquisition.
Industry Impact Analysis
Defense and Aerospace: The Primary Demand Engine for Quantum Chip Procurement
The quantum chip market's most immediate and measurable demand driver is defense and aerospace expenditure. According to the Stockholm International Peace Research Institute's 2024 report, global military expenditure increased from USD 2.28 trillion in 2022 to USD 2.44 trillion in 2023, a 6.8% increase in a single year. This trajectory has continued into 2026: U.S. discretionary spending on national defense rose by more than 17% in the current fiscal year, according to the Arms Control Association.
Within this defense budget expansion, quantum technology is receiving disproportionate attention. U.S. lawmakers are seeking a 68% increase in annual military quantum spending to USD 567 million, building on the more than USD 2 billion in planned Trump administration investments already announced. The defense applications driving this spending are specific: quantum sensors for GPS-denied navigation and underground detection, quantum-secured communication networks resistant to interception, and quantum processors capable of running complex battlefield simulations that exceed classical supercomputer capabilities. Each of these applications requires dedicated quantum chip hardware — not cloud access to shared quantum systems — creating a procurement pipeline that is structurally separate from commercial enterprise demand.
The aerospace dimension reinforces this demand. The World Economic Forum projects the global space economy will grow from USD 630 billion in 2023 to USD 1.8 trillion by 2035, at a compound annual rate of approximately 9%. Satellite navigation, secure inter-satellite communication, and Earth observation systems all require the high-precision timing and computation that quantum chips uniquely provide at the performance levels demanded by next-generation space infrastructure.
Enterprise Adoption: From Awareness to Budget Allocation
Beyond defense, enterprise adoption of quantum computing — and by extension, quantum chip demand — is transitioning from exploratory to budgeted. According to 451 Research's Voice of the Enterprise: Digital Pulse, Emerging Technologies — Quantum Computing 2026 survey, 53% of enterprise IT leaders express high intent to invest in quantum technology, up from 46% a year ago. Of those, 35.8% expect quantum to produce material business value within one to three years, and 27.5% within three to five years — a timeline that aligns with most hardware vendor roadmaps.
D-Wave's commercial performance provides a concrete data point: the company reported record bookings of more than USD 33 million in Q1 2026, up 2,000% year over year, driven by enterprise demand for quantum annealing in optimization applications. This growth is not attributable to a single large contract but to a broadening base of enterprise customers in logistics, financial services, and energy — sectors where combinatorial optimization problems are computationally expensive on classical hardware and where quantum annealing chips deliver measurable performance improvements today.
The IPO Wave: Capital Markets Validate the Commercial Trajectory
The quantum chip market's commercial credibility received further validation in early 2026 through a wave of public listings. Xanadu Quantum Technologies — a photonic quantum computing company and Nvidia partner — began trading on the Nasdaq and Toronto Stock Exchange in March 2026 following a SPAC merger, rallying 15% on its U.S. debut. Horizon Quantum, a Singapore-based quantum software company, and Infleqtion, a neutral atom quantum computing company, also completed public listings in the first quarter of 2026.
"The narrative has shifted from science project to commercial trajectory, and companies are capitalizing on that window," said Velu Sinha, Partner at Bain & Company, in an interview with CNBC on March 30, 2026. Sinha further noted that the addressable market at full maturity is estimated at USD 100 to USD 250 billion, providing patient capital with a structural reason to look past near-term volatility.
The EU Quantum Act and European Manufacturing Ambitions
Europe is pursuing a parallel but distinct strategy. The European Commission's EU Quantum Act — scheduled for adoption in 2026 — targets three objectives: boosting research and innovation, scaling industrial capacity through pilot lines and a design facility, and reinforcing supply chain resilience. This legislation builds on the EU's €1 billion Quantum Technologies Flagship, the Quantum Europe Strategy adopted in July 2025, and the inauguration of the Euro-Q-Exa quantum computer in Munich in February 2026. The EuroHPC Regulation was also amended in January 2026 to strengthen Europe's AI and quantum capabilities, expanding the mandate of the European High Performance Computing Joint Undertaking to integrate quantum accelerators with classical supercomputers at six sites across the EU.
Section Summary:
The quantum chip market's industry impact is being driven by defense procurement mandates, enterprise budget allocation, capital markets validation, and coordinated sovereign manufacturing strategies across three major economic blocs.
-
U.S. military quantum spending is targeted to increase 68% to USD 567 million annually, on top of USD 2.013 billion in CHIPS Act manufacturing incentives.
-
53% of enterprise IT leaders express high intent to invest in quantum, with D-Wave recording USD 33 million in Q1 2026 bookings — a 2,000% year-over-year increase.
-
The EU Quantum Act, scheduled for 2026 adoption, targets domestic quantum manufacturing scale-up and supply chain resilience across 27 member states.
-
The global semiconductor industry — the foundational supply chain for quantum chip fabrication — recorded USD 526.88 billion in sales in 2023, projected to reach USD 697.18 billion by 2025, providing the manufacturing infrastructure base on which quantum chip production is scaling.
Key Quantum Chip Hardware Milestones and Government Investment Events (2026)
|
Event |
Organization |
Date |
Key Metric / Commitment |
|
CHIPS Act Quantum Incentives |
U.S. Department of Commerce / NIST |
May 21, 2026 |
USD 2.013 billion across 9 companies; IBM ($1B), GlobalFoundries ($375M), 7 quantum computing companies ($100M each) |
|
Executive Order 14413 |
White House |
June 22, 2026 |
Whole-of-government quantum strategy; QC-ADDS effort; quantum sensor deployment by Sept. 2028 |
|
Majorana 2 Unveiling |
Microsoft |
June 2026 |
Qubit lifetimes >20 seconds (1,000x improvement); scalable quantum computer target: 2029 |
|
Nighthawk Processor Roadmap |
IBM |
March 2026 (updated) |
7,500 gates / 360 qubits in 2026; Kookaburra (1,386 qubits) logical processing unit demo before year-end |
|
EU Quantum Act (Call for Evidence) |
European Commission |
2026 |
Scheduled adoption 2026; targets industrial scale-up, supply chain resilience, R&D boost |
|
Military Quantum Spending Push |
U.S. Congress (House) |
August 2026 |
Proposed 68% increase to USD 567 million in annual military quantum spending |
|
D-Wave Q1 2026 Bookings |
D-Wave Quantum Inc. |
Q1 2026 |
Record USD 33M+ bookings; 2,000% year-over-year growth |
|
Euro-Q-Exa Inauguration |
EuroHPC / European Commission |
February 2026 |
Europe's latest quantum computer inaugurated in Munich |
Future Outlook & Forecast
The Path to USD 5.58 Billion: Modality Maturation and Application Expansion
NextMSC primary research and analysis projects the global quantum chip market will reach USD 5.58 billion by 2030 at a CAGR of 44.8%, driven by the simultaneous maturation of multiple qubit architectures and the expansion of quantum chip applications from computing into cryptography, sensing, and communication. The 2026–2029 window is the most consequential period in this trajectory: it is when the first fault-tolerant quantum systems are expected to emerge, when the CHIPS Act foundry investments will begin producing commercial-grade quantum wafers at scale, and when the EU Quantum Act's industrial capacity provisions will start generating European manufacturing output.
Superconducting quantum chips will maintain volume leadership through 2028, supported by IBM's Nighthawk and Kookaburra roadmap and the GlobalFoundries and IBM foundry investments. However, topological qubits — if Microsoft's Majorana 2 roadmap holds — will begin capturing premium defense and cryptography segments from 2029 onward, given their inherently lower error rates and smaller physical footprint per logical qubit. Neutral atom architectures, backed by CHIPS Act investments in Atom Computing and Infleqtion, are positioned to address the large-scale optimization and simulation markets where qubit counts above 10,000 are required for commercially impactful applications.
The "harvest now, decrypt later" threat is creating an immediate, non-discretionary demand pull for quantum cryptography chips that is independent of the timeline to full fault tolerance. IBM's 2026 roadmap explicitly notes that enterprises needing strong data protection should already be evaluating and implementing post-quantum cryptographic migration plans, given that completing an inventory, performing a risk assessment, and migrating vulnerable cryptography will take several years. This urgency is converting quantum cryptography from a future application into a present procurement priority, expanding the addressable market for quantum chip production beyond computing into security hardware.
The 451 Research Quantum Quarterly Q2 2026 survey found that 67% of IT decision-makers expect quantum to produce material business value within three years, and that the quantum computing market is set to grow by nearly 36% over the next five years. Velu Sinha of Bain & Company told CNBC that the first demonstrations of practical quantum advantage are expected at around 100 logical qubits — a threshold the industry is approaching by 2028–2029 — while commercially impactful applications in drug discovery and large-scale logistics optimization will require 1,000 to 10,000 logical qubits, more likely achievable in the mid-2030s.
The Asia-Pacific region represents the fastest-growing demand geography within the NMSC forecast. India's National Quantum Mission targets the development of intermediate-scale quantum computers of 50 to 1,000 qubits, and the Indian space economy — valued at USD 8.4 billion in 2024 — is projected to reach USD 44 billion by 2033, a 423% increase that will generate sustained demand for quantum chips in satellite navigation and secure communication systems.
Section Summary:
The quantum chip market's path to USD 5.58 billion by 2030 is supported by converging hardware roadmaps, sovereign manufacturing investments, and application-specific demand that is already generating commercial revenue.
-
Fault-tolerant quantum systems are targeted by IBM, Microsoft, Quantinuum, and IonQ for the 2027–2030 window, with Microsoft's Majorana 2 accelerating its own timeline to 2029.
-
The "harvest now, decrypt later" threat is converting quantum cryptography chips into an immediate procurement priority for financial institutions, defense agencies, and critical infrastructure operators.
-
Asia-Pacific demand is accelerating, anchored by India's National Quantum Mission and a space economy projected to grow 423% to USD 44 billion by 2033.
-
54% of enterprises plan to access quantum via cloud providers (AWS, Azure, Google Cloud), positioning hyperscalers as the dominant commercial gateway and creating a sustained demand signal for quantum chip production at cloud-scale.
Next Steps for Stakeholders
For C-Level Executives and Technology Leaders:
1. Initiate post-quantum cryptography migration planning now. IBM's 2026 roadmap explicitly states that completing a cryptographic inventory, risk assessment, and migration to post-quantum standards will take several years. Organizations that delay this process until fault-tolerant quantum computers arrive will face a compressed, high-risk migration window. Engage your CISO and infrastructure teams to begin this process in the current fiscal year.
2. Evaluate cloud-based quantum access as the near-term on-ramp. With 54% of enterprises planning to access quantum via cloud providers, the hyperscaler platforms (AWS Braket, Azure Quantum, Google Quantum AI) offer the lowest-friction entry point for algorithm development and use-case validation. Pilot programs on these platforms can identify which of your organization's computational workloads are candidates for near-term quantum value — particularly in optimization, financial modeling, and chemical simulation.
3. Monitor the CHIPS Act foundry portfolio for supply chain positioning. The nine companies receiving CHIPS Act incentives — particularly IBM, GlobalFoundries, Rigetti, Quantinuum, and Atom Computing — will define the domestic quantum chip supply chain through 2030. Organizations with defense contracts or critical infrastructure designations should assess their quantum hardware procurement strategies in light of the domestic sourcing requirements that are likely to accompany future government quantum mandates.
4. Track modality-specific roadmaps, not aggregate market forecasts. The quantum chip market's 44.8% CAGR (NextMSC primary research and analysis) masks significant divergence between modalities. Superconducting chips are the near-term volume play; topological chips (Microsoft's 2029 target) are the long-term scalability bet; neutral atom and trapped ion chips are the precision application specialists. Investment and procurement decisions should be modality-specific, aligned to the application verticals where each architecture delivers measurable performance advantages.
For Institutional Investors:
5. Assess the middleware layer as a near-term value capture opportunity. The 451 Research Quantum Quarterly Q2 2026 identifies the software and orchestration stack as the key differentiator for near-term quantum value, with companies like Haiqu claiming 50x error mitigation efficiency improvements. Middleware companies generate revenue from today's NISQ-era hardware without requiring fault tolerance, offering a lower-risk entry point than pure-play hardware investments.
6. Evaluate the CHIPS Act equity stakes as a valuation signal. The Department of Commerce's minority equity positions in nine quantum companies provide a government-validated floor for the commercial viability of these organizations. Companies in this portfolio — particularly those with both foundry access (IBM, GlobalFoundries) and application-specific revenue (D-Wave, Quantinuum) — represent the most de-risked positions in the quantum chip investment landscape.
Conclusion
The global quantum chip market is at a structural inflection point that is distinct from the speculative cycles that characterized earlier quantum investment waves. The USD 2.013 billion in CHIPS Act foundry investments, Executive Order 14413's whole-of-government mandate, Microsoft's Majorana 2 breakthrough, and IBM's Nighthawk and Kookaburra roadmap are not isolated events — they are coordinated signals that the United States, European Union, and major technology companies have concluded that quantum chip manufacturing is a strategic industrial priority that must be secured domestically and scaled commercially within this decade.
According to NextMSC primary research and analysis, the global quantum chip market will grow from USD 0.60 billion in 2024 to USD 5.58 billion by 2030 at a CAGR of 44.8% — a trajectory that reflects the compounding effect of defense procurement mandates, enterprise adoption, semiconductor industry expansion, and the emergence of modular quantum processor architectures that address the scalability constraints that have historically limited quantum chip production. For executives and investors who engage with this market now — through supply chain positioning, post-quantum cryptography migration, and modality-specific technology partnerships — the window for establishing a structural advantage ahead of the fault-tolerant era is open. It will not remain so indefinitely.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.










Add Comment