U.S. Homebuilder Sentiment Falls in July 2026
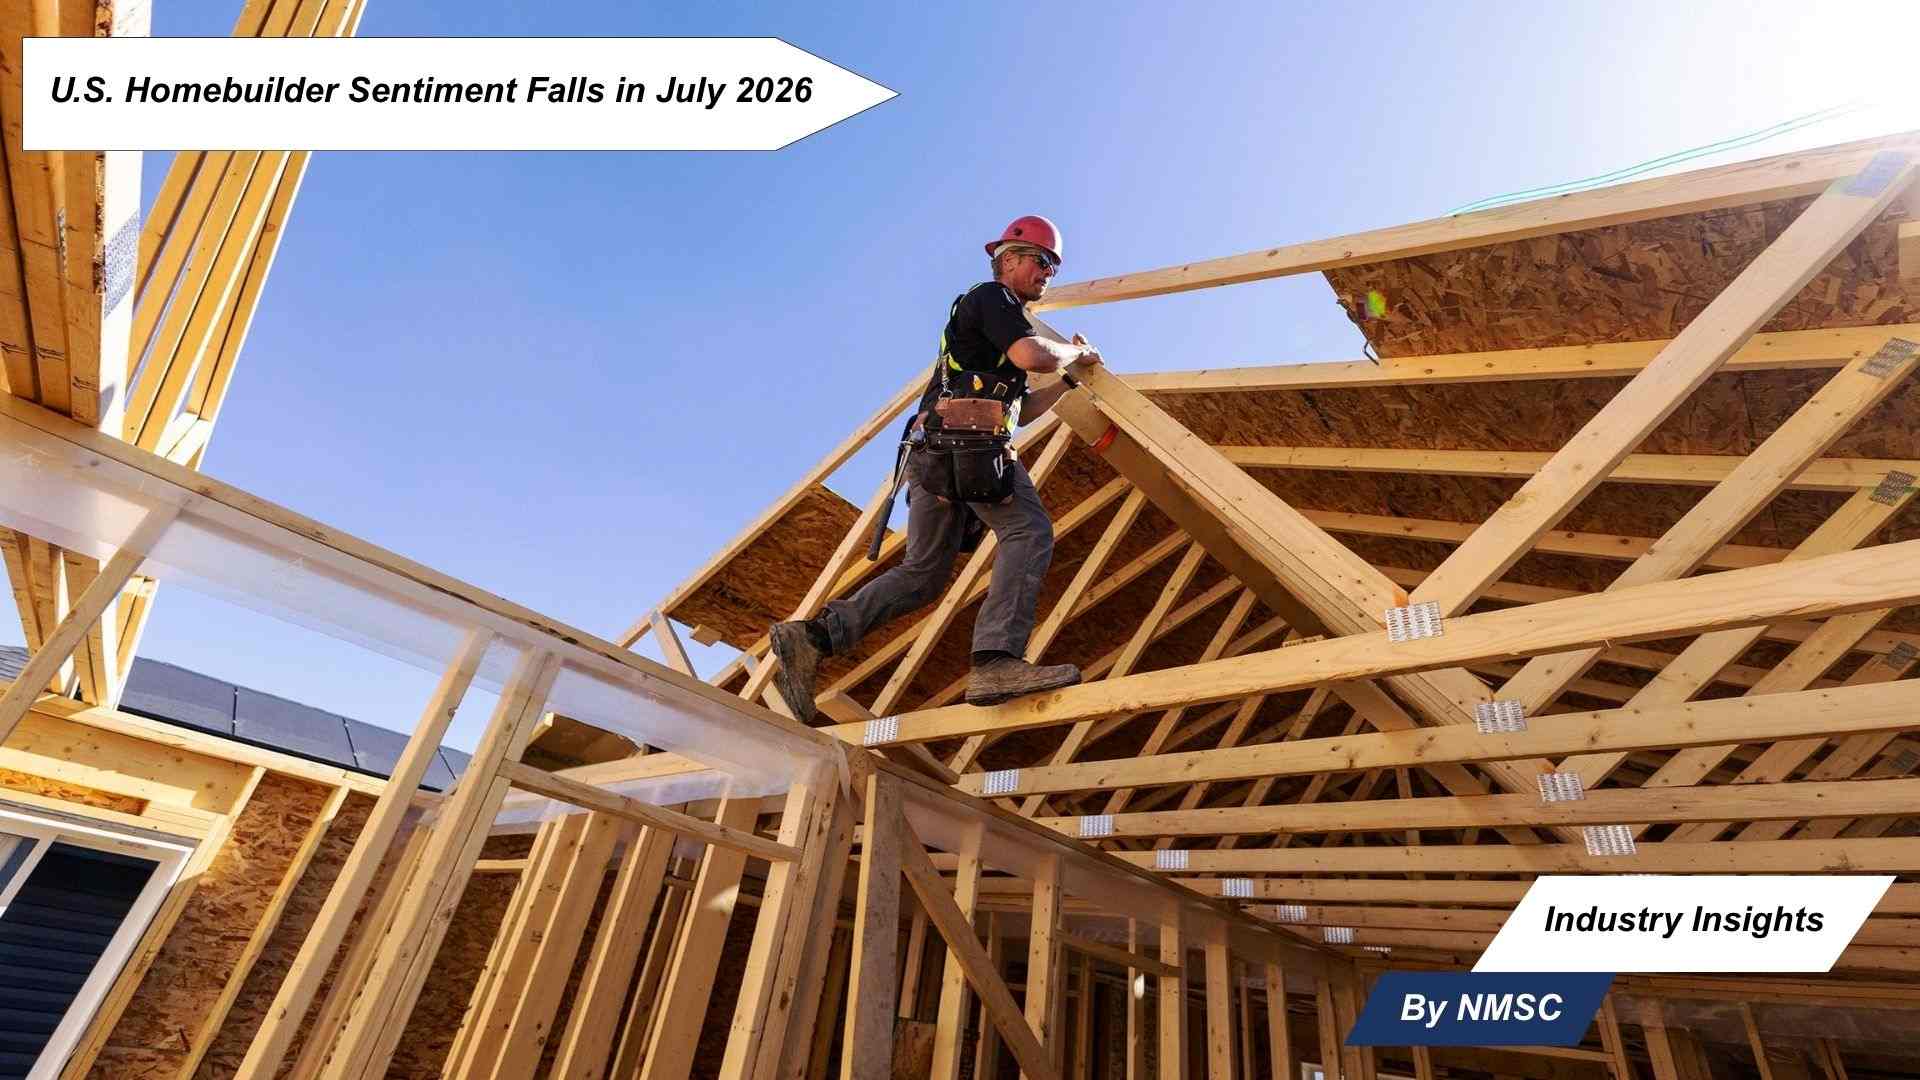
U.S. Homebuilder Confidence Drops to 34 in July as Mortgage Rates, Geopolitical Risks Weigh on Housing Market
WASHINGTON, United States — July 21, 2026 — U.S. homebuilder sentiment unexpectedly declined in July 2026, as persistently elevated mortgage rates, economic uncertainty, and renewed geopolitical tensions in the Middle East continued to suppress buyer demand and weigh on the broader real estate market, according to a survey released by the National Association of Home Builders (NAHB).
Main Development
The NAHB/Wells Fargo Housing Market Index fell two points to 34 in July, down from an upwardly revised reading of 36 in June. The result fell short of economist forecasts polled by Reuters, which had anticipated the index holding steady at 35. July marks the 15th consecutive month the index has remained below the 40-threshold — the longest such stretch since 2012.
NAHB Chairman Bill Owens attributed the weakness to buyer hesitancy. "Many potential buyers remain on the sidelines as they wait for lower mortgage rates, more certainty on inflation and a clearer economic outlook," Owens stated.
Mortgage rates are expected to remain elevated following the collapse of a fragile U.S.-Iran ceasefire last week, which has reignited hostilities and added a new layer of macroeconomic uncertainty to an already strained housing environment.
On the legislative front, a bipartisan housing affordability bill recently passed by the U.S. Congress became law over the weekend, despite President Donald Trump declining to sign it. The legislation includes provisions to restrict single-family homeownership by investment firms and to waive or expedite environmental reviews for new construction projects. NAHB Chief Economist Robert Dietz described the measure as "a positive step that will help expand housing supply and lower overall housing costs," while cautioning that further policy action at the state and local level remains necessary.
The share of builders reporting price reductions rose to 37% in July from 35% in June, with the average price cut holding steady at 6%. The use of sales incentives climbed to 63% from 62%, marking the 16th consecutive month this metric has reached 60% or higher. The survey's gauge of current sales conditions fell one point to 37, while the measure of future sales expectations dropped two points to 43. A sub-index tracking prospective buyer traffic slipped two points to 23.
Key Highlights:
-
The NAHB/Wells Fargo Housing Market Index fell to 34 in July 2026, the 15th consecutive month below 40 — the longest such streak since 2012.
-
Elevated mortgage rates and renewed U.S.-Iran geopolitical tensions are cited as primary headwinds suppressing buyer activity.
-
37% of builders reported cutting prices in July, up from 35% in June; sales incentive use reached 63%, the 16th straight month at or above 60%.
-
A bipartisan U.S. housing affordability law — restricting institutional single-family homeownership and streamlining construction approvals — became effective over the weekend, offering a potential medium-term supply-side catalyst.
Analyst Insight:
According to analysts at Next Move Strategy Consulting, the sustained weakness in homebuilder sentiment reflects a structural affordability challenge that extends beyond near-term rate movements. The global real estate market is projected to reach USD 33.61 trillion by 2030, registering a CAGR of 5.87% over the forecast period.
NMSC analysts note that while the newly enacted U.S. housing legislation represents a constructive policy development, the near-term trajectory of the residential segment will remain contingent on the Federal Reserve's rate path, geopolitical risk resolution, and the pace at which new housing supply enters the market. Markets that align development pipelines with infrastructure investment corridors and adopt flexible, mixed-use models are better positioned to capture long-term value amid the current affordability squeeze
Industry Outlook:
The U.S. residential real estate sector faces a complex near-term environment defined by the intersection of elevated financing costs, constrained inventory, and geopolitical uncertainty. However, the passage of bipartisan housing affordability legislation signals a policy pivot toward supply-side expansion that could gradually ease structural imbalances. Globally, the real estate industry's long-term growth trajectory remains intact, underpinned by urbanization, digital infrastructure investment, and rising demand for sustainable, technology-integrated developments. Stakeholders who align capital allocation with these structural trends — while managing near-term rate and credit risks — are positioned to capture durable returns as market conditions normalize.
Source: Reuters
For More Information – Download FREE Sample on Real Estate Market Report
Prepared By: Sanyukta Deb
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.










Add Comment