8K Technology Market Global Industry Analysis and Forecast (2026-2035)

8K Technology Market size was USD 62.21 Billion in 2025, projected to reach USD 111.70 Billion by 2035, growing at a CAGR of 5.82% from 2026 to 2035. Key drivers include falling display panel prices accelerating consumer 8K television adoption, rising professional and broadcast demand for ultra-high-resolution capture and production equipment, and expanding healthcare and surveillance applications requiring extreme-detail imaging, with Asia-Pacific leading the market.
Download Free Sample PDF
Base Year (2025)
$62.21 Billion
Forecast (2035)
$111.70 Billion
CAGR (2026-2035)
5.8%
Top Country
Asia-Pacific

What Is the 8K Technology Market Size?
The global 8K Technology Market size reached USD 62.21 Billion in 2025 and is estimated at USD 67.16 Billion in 2026, forecast to reach USD 111.70 Billion by 2035 at a CAGR of 5.82% between 2026 and 2035. Asia-Pacific leads with approximately 46% regional revenue share in 2025, while Display Equipment dominates the product axis at approximately 58% share.

8K Technology Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $62.21 Billion
2025
2026 $67.16 Billion
2026
2027 $71.07 Billion
2027
2028 $75.20 Billion
2028
2029 $79.58 Billion
2029
2030 $84.21 Billion
2030
2031 $89.11 Billion
2031
2032 $94.30 Billion
2032
2033 $99.79 Billion
2033
2034 $105.60 Billion
2034
2035 $111.70 Billion
2035

Key Takeaways

By Product: Display Equipment held the largest share, expanding from USD 36.08 Billion in 2025 to USD 62.15 Billion by 2035; Production and Signal Equipment is the fastest-growing sub-segment at 7.14% CAGR from 2026–2035.

By Resolution: UHD 8K held the largest share, expanding from USD 44.39 Billion in 2025 to USD 79.31 Billion by 2035; DCI 8K is the fastest-growing sub-segment at 7.48% CAGR from 2026–2035.

By Technology: Display Architecture held the largest share, expanding from USD 34.22 Billion in 2025 to USD 57.08 Billion by 2035; MicroLED is the fastest-growing display architecture at 12.34% CAGR from 2026–2035.

By Application: Home Entertainment held the largest share, expanding from USD 18.66 Billion in 2025 to USD 33.51 Billion by 2035; Healthcare and Life Sciences is the fastest-growing application at 8.62% CAGR from 2026–2035.

By Sales Channel: Distributor Sales held the largest share, expanding from USD 21.77 Billion in 2025 to USD 37.18 Billion by 2035; System Integrator Sales is the fastest-growing channel at 7.91% CAGR from 2026–2035.

Dominant Region: Asia-Pacific dominated with approximately 46% revenue share in 2025.

Fastest-Growing Region: Asia-Pacific is also expected to register the highest CAGR of 6.94% during 2026–2035.

Dominant Country: China led the market, anchored by its scale display panel manufacturing base and large premium consumer electronics market.

Fastest-Growing Country: India is the fastest-growing country, driven by rising premium television penetration and expanding healthcare and surveillance infrastructure investment.

The 8K Technology Market presents an absolute investment opportunity of approximately USD 44.54 Billion between 2026 and 2035, calculated as the difference between the 2035 forecast of USD 111.70 Billion and the 2026 estimate of USD 67.16 Billion, positioning panel manufacturers, camera OEMs, and signal processing specialists for sustained long-horizon revenue compounding across consumer and professional end markets.

According to NMSC analysis, the simultaneous maturation of 8K panel production cost curves, AI-based upscaling chipset integration, and professional broadcast infrastructure refresh cycles is creating a rare demand convergence across consumer, enterprise, and institutional procurement streams that structurally differentiates the 2026–2035 growth trajectory from the 4K adoption curve that preceded it.

Ecosystem Analysis of the 8K Technology Industry

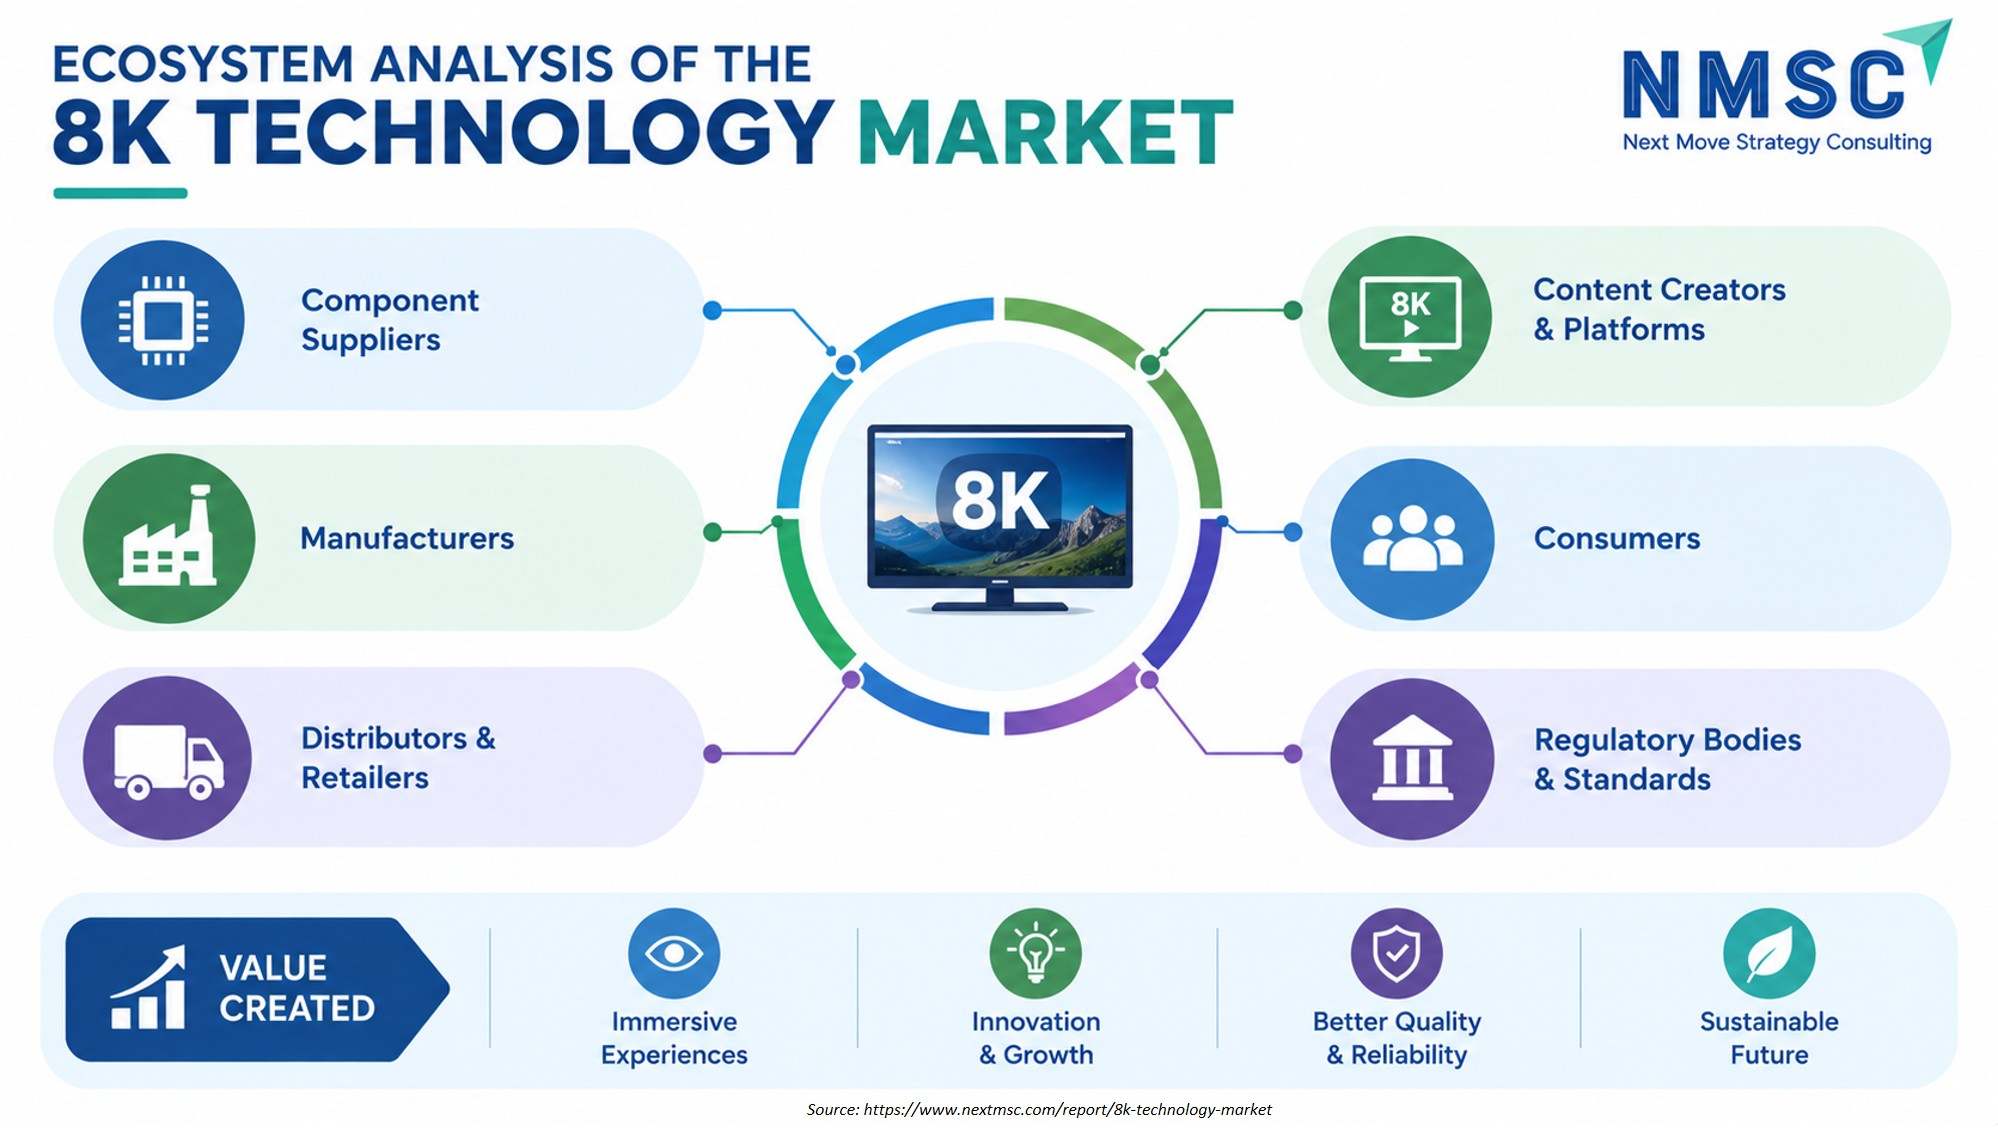
The above infographic presents the 8K technology market ecosystem through key stakeholders, including component suppliers, manufacturers, distributors and retailers, content creators and platforms, consumers, and regulatory bodies. It shows how these participants connect across the market while contributing to immersive experiences, technological innovation, product quality, reliability, and sustainable long-term growth .

What Does the 8K Technology Market Encompass?

The 8K Technology Market covers hardware, systems, and finished equipment operating at or natively processing 7,680 × 4,320 pixel resolution or equivalent DCI 8K formats, spanning display equipment including televisions, professional monitors, and large-format displays ; capture equipment including cinema, broadcast, consumer, surveillance, and scientific cameras; projection systems; and production and signal infrastructure encompassing switchers, encoders, recorders, routers, and test equipment. The market scope captures only primary product revenue at the first point of commercial sale, excluding content licensing, streaming service fees, installation labour, and maintenance contracts that constitute separate service-market categories.

Regulatory and standards frameworks shaping the 8K Technology Market include HDMI 2.1 specifications, VESA DisplayPort 2.1, ITU-R BT.2020 parameters for UHDTV systems, ITU-R BT.2077 interfaces for UHDTV signals, and SMPTE standards governing HDR metadata and professional media workflows . Technology adoption is being accelerated by AI upscaling chipsets , embedded in Samsung, Sony, and LG 8K television platforms , that allow sub-8K native content to render at full 8K output quality, effectively decoupling panel adoption from native 8K content availability and removing the adoption barrier that historically constrained 4K penetration in early years.

Market Drivers & Dynamics

Interactive Dataset
Falling 8K display panel manufacturing cost enabling retail price reduction driver +1.8% Asia-Pacific, North America, Europe 2026–2035
AI upscaling chipset integration removing content scarcity adoption barrier driver +1.2% Global 2026–2032
Professional broadcast 8K infrastructure refresh ahead of major global sporting events driver +0.9% Japan, Europe, North America 2026–2030
Healthcare and surgical visualization 8K adoption across hospital system procurement driver +0.7% North America, Europe, Asia-Pacific 2026–2035
8K surveillance and security system adoption in smart city and critical infrastructure programs driver +0.5% Asia-Pacific, MEA 2027–2035
Scarcity of native 8K content limiting consumer perceived value proposition restraint −0.8% Global 2026–2030
High manufacturing cost of OLED and MicroLED 8K panels compressing addressable price tier restraint −0.6% Global 2026–2031
Bandwidth infrastructure constraints limiting 8K streaming delivery at scale restraint −0.4% MEA, Latin America 2026–2032
Consumer HDMI 2.1 and DisplayPort 2.1 adoption lag limiting 8K ecosystem completeness restraint −0.2% Global 2026–2029
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the 8K Technology Market?

Falling 8K display panel manufacturing cost is the primary growth driver for the 8K Technology Industry , contributing an estimated +1.8% incremental CAGR impact through 2035. Japan's Ministry of Economy, Trade and Industry production data tracks the progressive cost curve reduction in large-format LCD and OLED panel manufacturing, which is the direct precedent for the 8K panel cost trajectory. Samsung Display and LG Display official production disclosures both reference continued Gen 10.5 glass substrate utilisation for 8K panel production, with larger substrate sizes improving panel yield per sheet and reducing effective per-unit manufacturing cost.

How Is AI Upscaling Technology Driving the 8K Technology Market Growth?

Our analysis shows that AI upscaling chipset integration is the most significant demand catalyst operating on the consumer side of the 8K Technology Market, directly addressing the content scarcity problem that structurally delayed 4K television mainstream adoption by enabling real-time neural network-based super-resolution rendering of widely available 4K and HD content at native 8K output quality. AI-based upscaling enables 8K displays to process lower-resolution source material and generate higher-resolution output, reducing the dependence of display value propositions on the availability of native 8K content .

Growth Inhibitors

What Is Restraining the 8K Technology Market?

The scarcity of natively produced 8K content represents the most persistent structural restraint on 8K Technology Market consumer revenue growth, with native 8K broadcast programming available only through Japan's NHK 8K Super Hi-Vision channel and limited streaming titles on select platforms as of 2025. Japan's NHK official broadcast schedules document the world's only regular 8K broadcast service, illustrating that even after years of technical availability, native 8K content production infrastructure remains nascent relative to the scale required to sustain mainstream consumer demand for 8K-capable displays independent of AI upscaling as a value justification.

What Are the Growth Opportunities?

Can MicroLED Large-Format 8K Displays Capture the Premium Commercial and Institutional Visualization Segment?

MicroLED tile-based 8K display systems targeting broadcast studios, simulation centres, command and control environments, and premium retail and venue installations represent a growing segment in which resolution, brightness, and modular scalability advantages over LCD and OLED large-format alternatives create sustainable premium pricing. Manufacturers delivering MicroLED 8K solutions through System Integrator Sales channels can capture this opportunity at materially higher per-square-metre revenue than consumer television volume channels, benefiting the Display Equipment product segment and Commercial and Public Display application segment simultaneously.

Does 8K Healthcare Imaging Present a Differentiated, Margin-Superior Revenue Channel for Camera and Monitor OEMs?

Camera and display OEMs that develop and qualify 8K imaging systems for surgical, endoscopic, and pathology visualization through hospital procurement and medical device regulatory approval channels access a margin-superior institutional customer base that evaluates products on clinical performance rather than retail price competition. This opportunity benefits the Capture Equipment and Display Equipment product segments and the Healthcare and Life Sciences application segment, with Sony, Canon, and EIZO already investing in medical-grade 8K system qualification that enables hospital system procurement independent of consumer market adoption cycles.

How Can Production and Signal Equipment Manufacturers Capitalize on the 8K Virtual Production Studio Build-Out?

The global expansion of virtual production facilities using 8K LED volume walls as real-time background rendering environments for film and television production creates sustained demand for 8K-native production switchers, signal processors, recorders, and video wall controllers that can manage the signal bandwidth of multi-camera 8K composite scenes. This opportunity primarily benefits the Production and Signal Equipment product segment and the Content Production and Broadcasting application segment, as virtual production studio build-outs require complete 8K signal infrastructure procurement through System Integrator Sales channels.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Display Equi
8K Televisio
LCD Televisi
OLED Televis
MicroLED Tel
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Display Equipment $10.0 USD Billion $40.0 USD Billion 14.0%
8K Televisions $17.1 USD Billion $51.1 USD Billion 8.0%
LCD Televisions $24.2 USD Billion $62.2 USD Billion 14.0%
OLED Televisions $31.3 USD Billion $73.3 USD Billion 20.0%
MicroLED Televisions $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Product.

Unlock Full Data

Which Product Segment Dominates the 8K Technology Market?

Display Equipment leads at USD 36.08 Billion in 2025, expanding to USD 62.15 Billion by 2035, driven by 8K television consumer volume growth and rising large-format commercial and professional monitor procurement across broadcast, visualisation, and institutional segments. Production and Signal Equipment is the fastest-growing product segment at 7.14% CAGR, as broadcast facilities, virtual production studios, and live events operators invest in 8K-native signal processing infrastructure that is a precondition for any live 8K capture-to-transmission production workflow deployment.

2025 (USD Billion)
2035 (USD Billion)
UHD 8K
DCI 8K
Other 8K-Cla
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
UHD 8K $10.0 USD Billion $40.0 USD Billion 25.0%
DCI 8K $17.1 USD Billion $51.1 USD Billion 11.0%
Other 8K-Class $24.2 USD Billion $62.2 USD Billion 25.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Resolution.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Display Arch
LCD
Standard LED
Mini LED Bac
Quantum Dot
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Display Architecture $10.0 USD Billion $40.0 USD Billion 27.0%
LCD $17.1 USD Billion $51.1 USD Billion 9.0%
Standard LED Backlight $24.2 USD Billion $62.2 USD Billion 19.0%
Mini LED Backlight $31.3 USD Billion $73.3 USD Billion 17.0%
Quantum Dot LCD $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Technology.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Home Enterta
Home Cinema
Premium Tele
Gaming and P
Content Prod
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Home Entertainment $10.0 USD Billion $40.0 USD Billion 14.0%
Home Cinema $17.1 USD Billion $51.1 USD Billion 24.0%
Premium Television $24.2 USD Billion $62.2 USD Billion 22.0%
Gaming and Personal Media $31.3 USD Billion $73.3 USD Billion 12.0%
Content Production and Broadcasting $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data

Which Application Segment Leads and Which Grows Fastest?

Home Entertainment leads application demand at USD 18.66 Billion in 2025, reflecting the dominance of 8K television as the primary consumer product category by revenue within the broader 8K Technology Market. Healthcare and Life Sciences is the fastest-growing application segment at 8.62% CAGR, driven by hospital system procurement of 8K surgical visualization systems , endoscopic imaging monitors, and pathology display workstations that require full 8K resolution to support minimally invasive and robotic surgical procedures at cellular-scale imaging fidelity.

2025 (USD Billion)
2035 (USD Billion)
Direct Sales
Distributor
Dealer and R
System Integ
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Sales $10.0 USD Billion $40.0 USD Billion 24.0%
Distributor Sales $17.1 USD Billion $51.1 USD Billion 22.0%
Dealer and Reseller Sales $24.2 USD Billion $62.2 USD Billion 20.0%
System Integrator Sales $31.3 USD Billion $73.3 USD Billion 22.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data

Which Sales Channel Leads and Which Grows Fastest?

Distributor Sales leads at USD 21.77 Billion in 2025, reflecting the established role of consumer electronics and professional AV distributor networks as the primary route-to-market for 8K televisions, cameras, and monitors across both retail and institutional procurement. System Integrator Sales is the fastest-growing channel at 7.91% CAGR, as broadcast facilities, command centres, surgical suites, and virtual production stages require complete 8K system integration spanning capture, processing, signal distribution, and display that exceeds the capability of product-only distributor or dealer supply relationships.

Growth Opportunities

Our findings suggest that three distinct whitespace opportunities will generate disproportionate revenue growth for 8K Technology Market participants with the right product, channel, and application positioning through 2035.

Can MicroLED Large-Format 8K Displays Capture the Premium Commercial and Institutional Visualization Segment?

MicroLED tile-based 8K display systems targeting broadcast studios, simulation centres, command and control environments, and premium retail and venue installations represent a growing segment in which resolution, brightness, and modular scalability advantages over LCD and OLED large-format alternatives create sustainable premium pricing. Manufacturers delivering MicroLED 8K solutions through System Integrator Sales channels can capture this opportunity at materially higher per-square-metre revenue than consumer television volume channels, benefiting the Display Equipment product segment and Commercial and Public Display application segment simultaneously.

Does 8K Healthcare Imaging Present a Differentiated, Margin-Superior Revenue Channel for Camera and Monitor OEMs?

Camera and display OEMs that develop and qualify 8K imaging systems for surgical, endoscopic, and pathology visualization through hospital procurement and medical device regulatory approval channels access a margin-superior institutional customer base that evaluates products on clinical performance rather than retail price competition. This opportunity benefits the Capture Equipment and Display Equipment product segments and the Healthcare and Life Sciences application segment, with Sony, Canon, and EIZO already investing in medical-grade 8K system qualification that enables hospital system procurement independent of consumer market adoption cycles.

How Can Production and Signal Equipment Manufacturers Capitalize on the 8K Virtual Production Studio Build-Out?

The global expansion of virtual production facilities using 8K LED volume walls as real-time background rendering environments for film and television production creates sustained demand for 8K-native production switchers, signal processors, recorders, and video wall controllers that can manage the signal bandwidth of multi-camera 8K composite scenes. This opportunity primarily benefits the Production and Signal Equipment product segment and the Content Production and Broadcasting application segment, as virtual production studio build-outs require complete 8K signal infrastructure procurement through System Integrator Sales channels.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Asia-Pacific
Europe
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Asia-Pacific $17.1 USD Billion $51.1 USD Billion 27.0%
Europe $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Supply Chain Analysis of the 8K Technology Industry

Supply Chain Analysis of the 8K Technology Industry
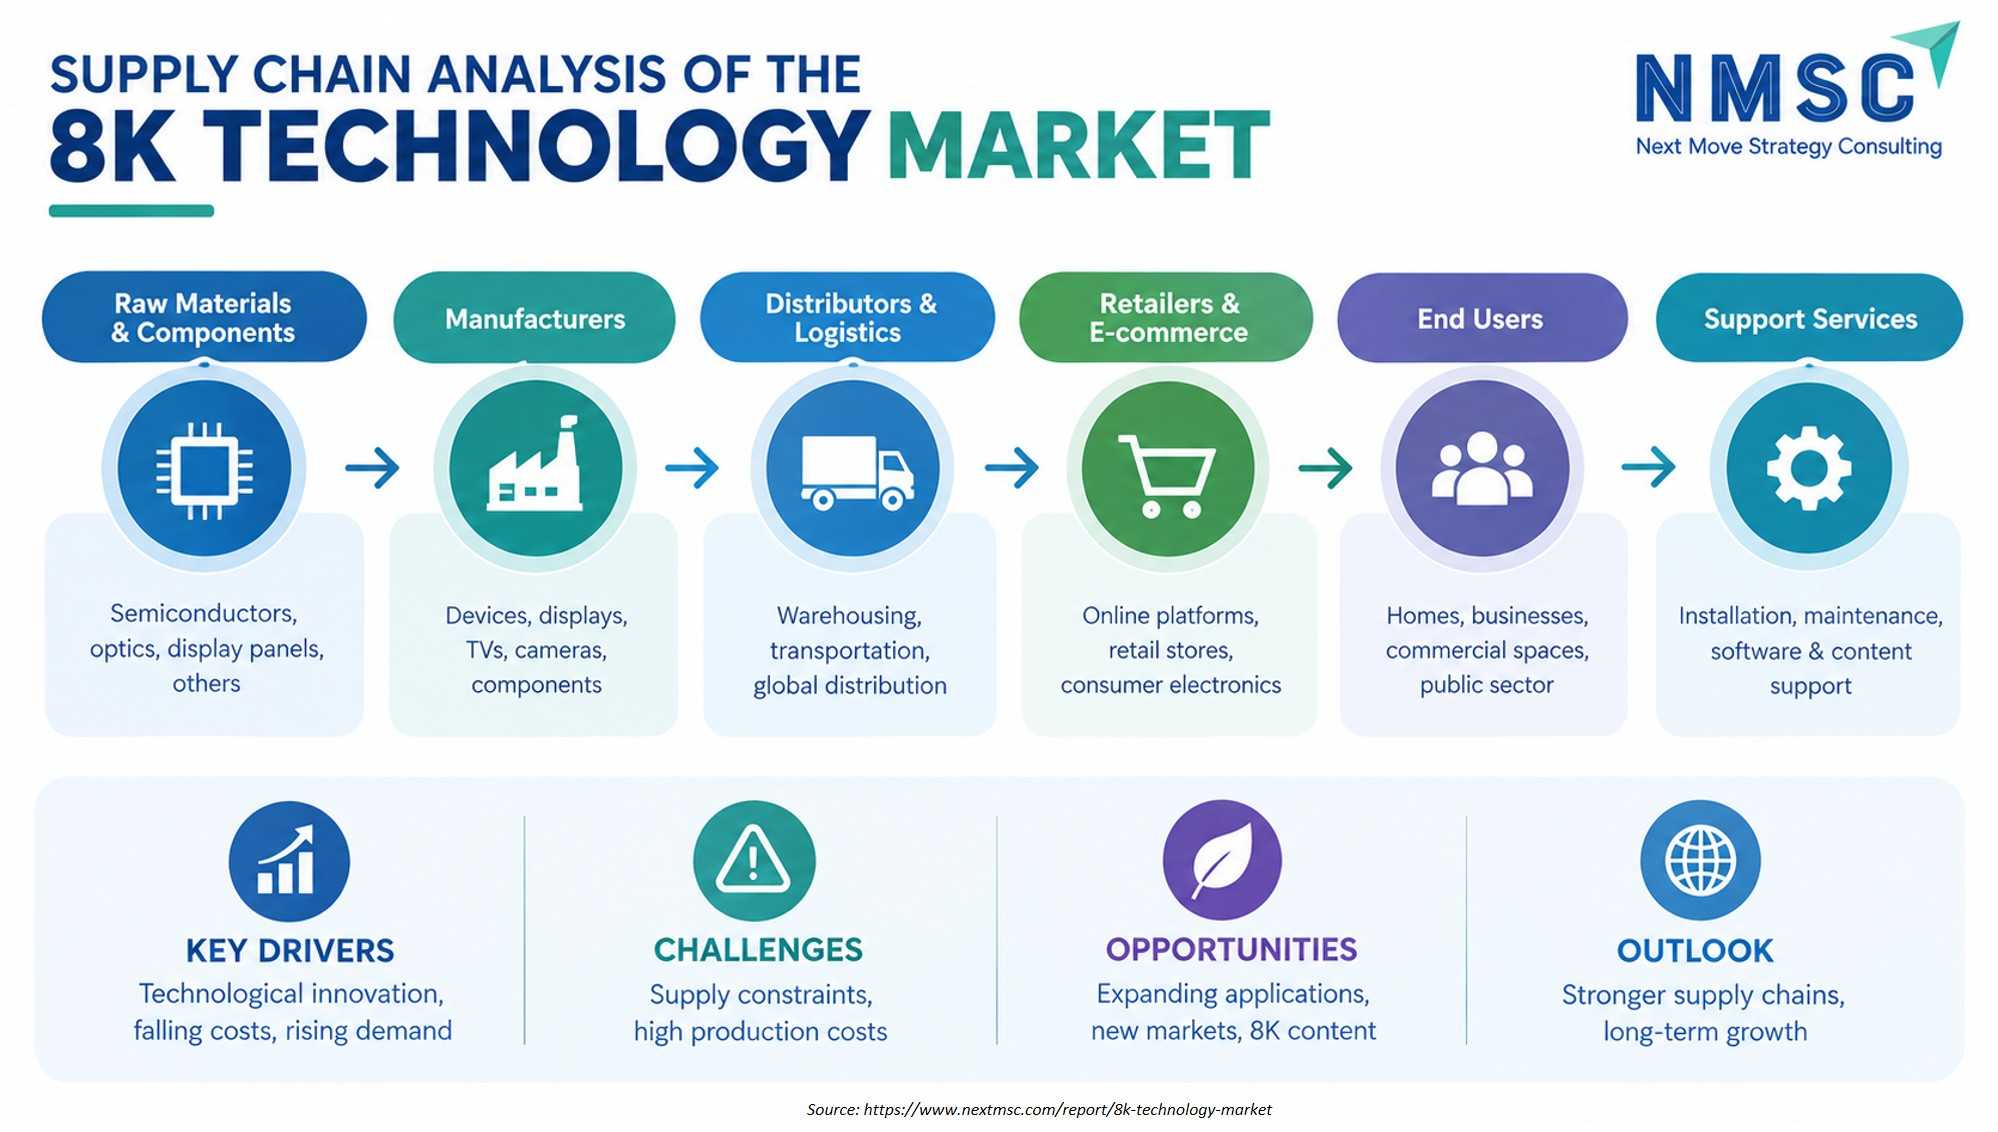
The above infographic maps the 8K technology market supply chain from raw materials and components through manufacturing, logistics, retail, end users, and support services. It highlights how semiconductors, displays, devices, distribution networks, and service providers connect across the value chain, while also summarizing major supply-chain drivers, challenges, opportunities, and the market outlook .

Competitive Landscape

Based on research conducted by NMSC, the 8K Technology Market competitive landscape spans consumer electronics giants, professional imaging OEMs, display panel manufacturers, and specialist signal processing companies, each holding differentiated competitive positions across the market's broad product, application, and channel segmentation.

Dimension Description
Dimension Assessment
Market Structure Moderately concentrated at the consumer display level with Samsung and LG Electronics holding dominant 8K television share, but highly fragmented across professional capture, signal processing, and projection segments where JVCKENWOOD, ASTRODESIGN, Analog Way, and Digital Projection hold specialist positions
Innovation Focus AI upscaling silicon differentiation in consumer 8K televisions; MicroLED large-format display system development; 8K CMOS sensor development for cinema, broadcast, and medical camera platforms; low-latency FPGA and ASIC signal processing for live 8K production infrastructure
M&A Activity Strategic acquisitions of specialist 8K signal processing and production equipment companies by broadcast infrastructure conglomerates; display panel manufacturing joint ventures in Asia-Pacific for Gen 10.5 substrate 8K panel capacity expansion

How Do Companies Compete in the 8K Technology Market?

Companies compete across distinctly separated consumer, professional, and industrial competitive arenas that rarely overlap in customer base, procurement channel, or performance specification priority. We observed that consumer electronics leaders Samsung, LG, Sony, TCL, and Hisense compete primarily on AI processing silicon capability, display panel technology differentiation, and retail price positioning, while professional imaging and signal processing companies including JVCKENWOOD, ASTRODESIGN, Analog Way, and Digital Projection compete on broadcast standards compliance, signal chain integration capability, and long-term product lifecycle support for institutional broadcast and cinema customers.

Which Competitive Archetypes Dominate the 8K Technology Industry?

Vertically integrated consumer electronics conglomerates , Samsung Electronics (panel + AI processor + television), Sony Group (image sensor + processor + display), and LG Electronics (OLED panel + TV) , dominate through end-to-end silicon, panel, and systems integration capability that allows AI chipset and display panel advances to be co-developed and deployed across consumer 8K television product lines faster than any competitor lacking similar vertical integration depth. Specialist professional equipment manufacturers including RED Digital Cinema, Blackmagic Design, and ASTRODESIGN dominate through deep engineering expertise in cinema-grade 8K sensor systems and broadcast infrastructure compliance that consumer electronics scale alone cannot replicate.

What Innovation and Differentiation Strategies Are Companies Pursuing?

Our analysis shows that companies are pursuing three parallel innovation tracks in the 8K Technology Market: AI upscaling neural network silicon development for consumer display differentiation, where Samsung and Sony lead; MicroLED large-format display system engineering for commercial and professional visualization premium segment capture, where Leyard , Unilumin , and Samsung are most active; and 8K CMOS global-shutter sensor development for cinema, scientific, and medical imaging applications, where Sony, Canon, and FUJIFILM have publicly disclosed active development programs targeting sub-pixel pitch improvements beyond current BSI CMOS sensor generation performance benchmarks.

Key Market Players

During our market evaluation, we noticed that the following companies represent the validated set of 8K Technology Market leaders across consumer display, professional imaging, signal processing, projection, and visualization equipment categories as of 2026.

Samsung Electronics Co., Ltd. Sony Group Corporation LG Electronics Inc. TCL Technology Group Corporation Hisense Visual Technology Co., Ltd. Canon Inc. Panasonic Holdings Corporation Sharp Corporation FUJIFILM Corporation Nikon Corporation Blackmagic Design Pty. Ltd. RED Digital Cinema, LLC Leyard Optoelectronic (Group) Co., Ltd. Unilumin Group Co., Ltd. JVCKENWOOD Corporation Digital Projection Limited ASTRODESIGN, Inc. Analog Way SAS EIZO Corporation Dell Technologies Inc.

Latest Developments

We found that the most significant recent activity across the 8K Technology Market reflects accelerating AI upscaling integration, MicroLED commercial product launches, and professional 8K equipment qualification for broadcast and medical applications through 2025 and 2026.

Date Event
January 2026 At ISE 2026, Digital Projection announced a new 8K-resolution flagship built on its Satellite MLS architecture, alongside a compact TITAN Luma range.
Sep tember 2025 Fujifilm launched the GFX ETERNA 55 filmmaking camera in September 2025 with a 102MP large-format sensor, professional cinema workflow features, and HDMI output supporting up to 8K/30P 12-bit RAW.
Mar ch 2025 Samsung Electronics America announced availability of the 2025 Neo QLED 8K QN990F and QN900F models, introducing Samsung Vision AI, 8K AI Upscaling Pro, Mini LED Quantum Matrix technology, glare-free viewing, and wireless connectivity.
Feb ruary 2025 Panasonic introduced the LUMIX S1RII in February 2025, its first LUMIX camera with 8K video recording, using a 44.3MP BSI CMOS sensor and supporting 8K video with up to 14 stops of dynamic range.
Feb ruary 2025 Nikon and RED launched the first Z CINEMA products, the V-RAPTOR [X] Z Mount and KOMODO-X Z Mount, integrating Nikon’s Z mount into RED cinema cameras. The V-RAPTOR [X] retains an 8K VV global-shutter sensor, while the collaboration expands lens choice and strengthens integrated 8K cinema-capture workflows.

Expert Insights

Bill Mandel

Bill Mandel

President | 8K Association

" Over the past year, the 8KA has continued to work tirelessly to develop and promote all of the key aspects of the 8K ecosystem . Given the growing interest in AI for use in next-generation ‘giant screen’ residential and commercial applications, we’re confident that 8K technology offers an important new business opportunity to AV dealers and custom integrators alike "

Analyst Interpretation

We observed that this perspective directly supports the increasing role of AI-enabled image processing and upscaling in expanding the commercial value proposition of 8K technology. NMSC’s analysis indicates that the integration of AI with next-generation giant-screen displays is shifting 8K adoption beyond native-resolution content availability toward enhanced image quality, intelligent processing, and premium viewing experiences. This transition is creating additional opportunities across AV dealerships, custom integration, commercial display installations, and high-end residential entertainment, strengthening the addressable application base for 8K technology beyond conventional consumer television deployments .

Investment Opportunities

Where Are Capital Inflows Concentrating in the 8K Technology Market?

Capital inflows are concentrating in AI upscaling silicon development for consumer display applications, MicroLED manufacturing infrastructure investment for large-format commercial and professional 8K displays, and professional 8K signal processing ASIC and FPGA development for broadcast and virtual production infrastructure. Private equity and strategic capital is increasingly targeting specialist 8K signal processing and production equipment companies in Europe and Japan, recognising that broadcast infrastructure refresh programs and virtual production studio build-outs create predictable multi-year equipment procurement pipelines that sustain revenue visibility above consumer electronics cycle volatility.

How Is Infrastructure Investment Shaping the 8K Technology Market Long-Term Capacity?

Display panel manufacturing infrastructure investment in Gen 10.5 glass substrate production lines in China and South Korea is the primary capacity investment determining long-term 8K panel supply economics, with BOE Technology and CSOT official investment disclosures indicating continued capacity expansion that will progressively reduce 8K panel manufacturing cost per square metre toward mass-market price tier thresholds between 2027 and 2031. Japan's NHK 8K broadcast infrastructure, documented in official budget filings, provides production quality reference standards that influence professional equipment specification requirements globally.

What ESG Considerations Are Influencing 8K Technology Market Investment?

Environmental, social, and governance considerations in themarket centre on display panel power consumption reduction , where 8K panels historically consume 20–40% more power than 4K equivalents at equivalent size , and sustainable manufacturing practices in display panel production , including rare earth material usage in OLED emitter compounds. Samsung, Sony, and LG official sustainability reports disclose active investment in energy-efficient backlight architectures, low-power OLED emitter chemistry development, and panel lifecycle extension programs that address the growing regulatory scrutiny of consumer electronics energy consumption under EU Ecodesign regulation frameworks.

Key Benefits for Stakeholders

How Does This Report Benefit 8K Technology Industry Leaders?

8K Technology Market industry leaders gain granular segment-level revenue forecasts and CAGR benchmarks across product, resolution, technology, application, and sales channel axes that enable product portfolio prioritisation, R&D investment allocation, and geographic expansion sequencing decisions grounded in the consistent 2025–2035 market sizing framework. Our findings on the fastest-growing segments , Healthcare and Life Sciences at 8.62% CAGR, MicroLED at 12.34%, and System Integrator Sales at 7.91% , provide actionable targeting insight for product development and go-to-market strategy planning.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts gain a reconciled market sizing model showing USD 62.21 billion in 2025 and USD 111.70 billion by 2035, reflecting a CAGR of 5.82%, supported by competitive landscape assessment, M&A activity tracking, and application segment growth decomposition that facilitates valuation and capital allocation decisions across consumer electronics, display technology, and professional AV portfolio companies. The Growth Catalyst and Risk Assessment Matrix quantifies the drivers contributing to the 5.82% CAGR and the impact of market restraints, enabling scenario analysis that distinguishes professional infrastructure-driven growth exposure from consumer-driven growth at the company level .

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain visibility into which technology sub-segments , including MicroLED at 12.34% CAGR, Global-Shutter CMOS at premium professional growth rates, and FPGA-based signal processing for live 8K production , are growing fastest and in which application and channel contexts demand is most concentrated. Our competitive landscape analysis and latest development tracking identify which OEMs are investing most actively in specific 8K technology categories, providing component and IP suppliers with early-stage procurement intelligence for design-win positioning and long-term supply agreement negotiation.

Key Market Segments Evaluated

By Product

  • Display Equipment 
    • 8K Televisions
      • LCD Televisions
      • OLED Televisions
      • MicroLED Televisions
    • 8K Professional Monitors
      • Imaging Monitors
      • Design and CAD Monitors
      • Creator and Gaming Monitors
    • 8K Large-Format Displays
      • Direct-View LED Displays
      • MicroLED Displays
      • Commercial Flat-Panel Displays
  • Capture Equipment 
    • 8K Cinema Cameras
      • Full-Frame Cinema Cameras
      • Large-Format Cinema Cameras
      • Modular Cinema Cameras
    • 8K Broadcast Cameras
      • Studio Cameras
      • Field Cameras
      • Outside-Broadcast Cameras
    • 8K Consumer Cameras
      • Mirrorless Cameras
      • Hybrid Cameras
    • 8K Surveillance Cameras
      • Fixed Cameras
      • PTZ Cameras
    • 8K Scientific and Industrial Cameras
      • Medical Cameras
      • Scientific Cameras
      • Industrial Cameras
  • Projection Equipment 
    • 8K Home Cinema Projectors
    • 8K Professional Projectors
      • Large-Venue Projectors
      • Simulation Projectors
      • Visualisation Projectors
  • Production and Signal Equipment 
    • 8K Production Equipment
      • Production Switchers
      • Recorders
      • Ingest Systems
    • 8K Video Processing Equipment
      • Signal Processors
      • Encoders
      • Decoders
      • Converters
    • 8K Presentation and Routing Equipment
      • Matrix Routers
      • Presentation Systems
      • Video Wall Processors
    • 8K Test and Measurement Equipment
      • Signal Generators
      • Signal Analysers
      • Video Test Systems
    • 8K Playback Equipment
      • Media Servers
      • Playback Systems
  • Other Finished 8K Equipment

By Resolution

  • UHD 8K
  • DCI 8K
  • Other 8K-Class

By Technology

  • Display Architecture 
    • LCD
      • Standard LED Backlight
      • Mini LED Backlight
      • Quantum Dot LCD
    • OLED
      • OLED
      • QD-OLED
    • MicroLED
  • Capture Architecture 
    • CMOS
      • Standard CMOS
      • BSI CMOS
      • Global-Shutter CMOS
    • Other Capture Architecture
  • Projection Architecture 
    • DLP
    • D-ILA
    • LCoS
    • Other Projection Architecture
  • Processing Architecture 
    • FPGA
    • GPU
    • ASIC
    • Other Processing Architecture

By Application

  • Home Entertainment 
    • Home Cinema
    • Premium Television
    • Gaming and Personal Media
  • Content Production and Broadcasting 
    • Film Production
    • Television Production
    • Sports Production
    • Live Broadcasting
    • Live Events
  • Professional Visualization 
    • CAD and Engineering
    • Simulation
    • Virtual Production
    • Scientific Visualization
  • Healthcare and Life Sciences 
    • Medical Imaging
    • Surgical Visualization
    • Clinical Visualization
  • Surveillance and Security 
    • Video Surveillance
    • Critical Infrastructure
    • Security Monitoring
  • Commercial and Public Display 
    • Digital Signage
    • Retail Display
    • Corporate Display
    • Venue Display
  • Education and Research 
    • Education
    • Research and Development
  • Other Institutional Applications

By Sales Channel

  • Direct Sales
  • Distributor Sales
  • Dealer and Reseller Sales
  • System Integrator Sales

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook for the 8K Technology Market is structurally positive, with revenue expanding from USD 67.16 Billion in 2026 to USD 111.70 Billion by 2035 at a 5.82% CAGR. We observed that the simultaneous maturation of consumer panel cost curves, AI upscaling silicon performance, and professional broadcast and healthcare visualization adoption is creating a broader and more durable demand base than any single segment could sustain independently, reducing the market's dependence on consumer television adoption pace as the sole growth driver.

What Strategic Positioning Do We Recommend?

Our assessment indicates that 8K Technology Market participants should prioritise Healthcare and Life Sciences application segment qualification , the fastest-growing application at 8.62% CAGR , alongside MicroLED large-format display system investment for commercial and professional visualization, and System Integrator Sales channel development for professional and institutional market access. Companies without healthcare market product qualification should evaluate OEM partnerships or co-development agreements with medical device-experienced partners to accelerate regulatory approval timelines and access institutional procurement channels.

How Attractive Is the 8K Technology Market for Investment?

Investment attractiveness in themarket is concentrated in three high-CAGR sub-segments: MicroLED display architecture at 12.34% CAGR, Healthcare and Life Sciences application at 8.62% CAGR, and System Integrator Sales channel at 7.91% CAGR , all materially above the 5.82% headline market rate. We found that the absolute USD 44.54 billion investment opportunity between 2026 and 2035 positions the market as a mid-to-large-scale technology investment with multiple high-growth pockets accessible through focused product and channel strategy.

What Are the Market Shifts and Key Risks?

The most significant structural market shift is the transition of the 8K value proposition from native content dependency toward AI-enabled upscaling performance , a shift that benefits consumer display OEMs with advanced AI silicon capability while reducing value capture opportunity for content production equipment manufacturers dependent on native 8K production mandate demand. Key risks include sustained native content scarcity constraining consumer-side growth beyond AI upscaling appeal, OLED and MicroLED manufacturing yield limitations constraining premium display supply at competitive retail price points, and bandwidth infrastructure constraints in MEA and Latin America limiting streaming-dependent 8K value proposition delivery.

What Are the Primary Growth Pathways Through 2035?

Primary growth pathways include MicroLED commercial display system revenue through System Integrator Sales to broadcast, corporate, and venue customers; Healthcare and Life Sciences 8K imaging system procurement through direct hospital capital equipment programs; professional broadcast infrastructure refresh ahead of major global sporting and cultural events; and smart city surveillance program 8K camera procurement in Asia-Pacific and MEA government infrastructure investment pipelines. Our analysis shows that companies with simultaneous exposure to three or more of these pathways are best positioned to sustain above-market CAGR performance through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market Growth Analysis
  • Historical sales, shipment and revenue analysis of 8K products across product types, resolution tiers and sales channels.
  • Reveals adoption trajectory and the segments and channels driving growth.
Company-Level Shipment Volume Analysis
  • Company-wise 8K unit shipments and sales volumes for TVs, displays, cameras and related devices.
  • Shows manufacturer scale and share shifts to guide competitive positioning.
Country-Level Trade Assessment
  • Country-wise import and export analysis of 8K displays, panels, cameras and key components.
  • Identifies sourcing hubs, supply dependencies and export opportunities.
8K Panel and Display Technology Benchmarking
  • Comparison of leading manufacturers' 8K offerings across LCD, QLED, OLED and MicroLED technologies, including specifications, announced roadmaps and price positioning.
  • Guides technology investment and product roadmap priorities against competitor offerings.
8K Content and Ecosystem Readiness Assessment
  • Mapping of 8K broadcast trials, streaming and content availability, and codec and interface standards by region and application.
  • Pinpoints markets and applications where content availability can sustain 8K demand.
Application-Level 8K Opportunity Assessment
  • Demand mapping of 8K adoption across consumer entertainment, broadcasting, medical imaging, surveillance, gaming and professional visualization, by sales channel.
  • Prioritizes high-potential applications and go-to-market channels.

FAQs

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Henri Knyphausen

HENRI KNYPHAUSEN

Partner at Singulier [Ex-BCG]

Singulier

I recently engaged NEXTMSC.com for a commercial due diligence project within the intralogistics sector, and I am pleased to provide a reference based on my experience. In utilizing NEXTMSC.com's services, I found their report to offer valuable insights into market dynamics and key industry players. The initial report provided a solid foundation for our analysis. However, as we were investigating a smaller target in the market, and I had specific customization requests requiring additional research. These requests included detailed information on product portfolios of various players and sub-market sizes, both inclusive and exclusive of certain product categories. NEXTMSC.com demonstrated commendable responsiveness and agility in accommodating these customization requests. Within a timeframe of 1-2 weeks, they delivered a revised report that met our specific needs. Furthermore, they were receptive to my follow-up inquiries, ensuring clarity and understanding of the data provided. The final deliverable significantly contributed to our due diligence efforts. One of NEXTMSC.com's notable strengths lies in their qualitative research capabilities. However, for future engagements, I would recommend the inclusion of a quantified market model in Excel format. Such a model would offer the ability to conduct in-depth analyses and explore various market segments, including country-specific data and subcomponent breakdowns. Based on my positive experience, I would not hesitate to work with NEXTMSC.com again. Their responsiveness, willingness to accommodate customization requests, and commitment to delivering actionable insights make them a reliable partner for commercial research projects.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖