Canada Agriculture Robots Market By Type (Unmanned Aerial Vehicles (UAVs), Milking Robots, Driverless Tractors, Automated Harvest Robots and Others), By Farming Type (Indoor Farming, Outdoor Farming and Indoor & Outdoor), and By Application (Aerial Monitoring & Scouting, Dairy & Livestock Automation, Field Operations, Harvest Management and Others): Opportunity Analysis & Industry Forecast, 2025–2035
Industry: Agriculture | Latest Edition: August 20, 2026 | No of Pages: 175 | No. of Tables: 66 | No. of Figures: 60 | Format: PDF | Report Code: AG617
Market Size & Forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 513.59 Million |
|
Market Size in 2026 |
USD 689.05 Million |
|
Revenue Forecast in 2035 |
USD 3,988.82 Million |
|
Growth Rate |
CAGR of 21.5% from 2026 to 2035 |
|
Market Volume in 2025 |
4 thousand Units |
|
Market Volume in 2026 |
5 thousand Units |
|
Volume Forecast in 2035 |
51 thousand Units |
|
Growth Rate |
CAGR of 28.4% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Million (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 Companies |
Industry Outlook
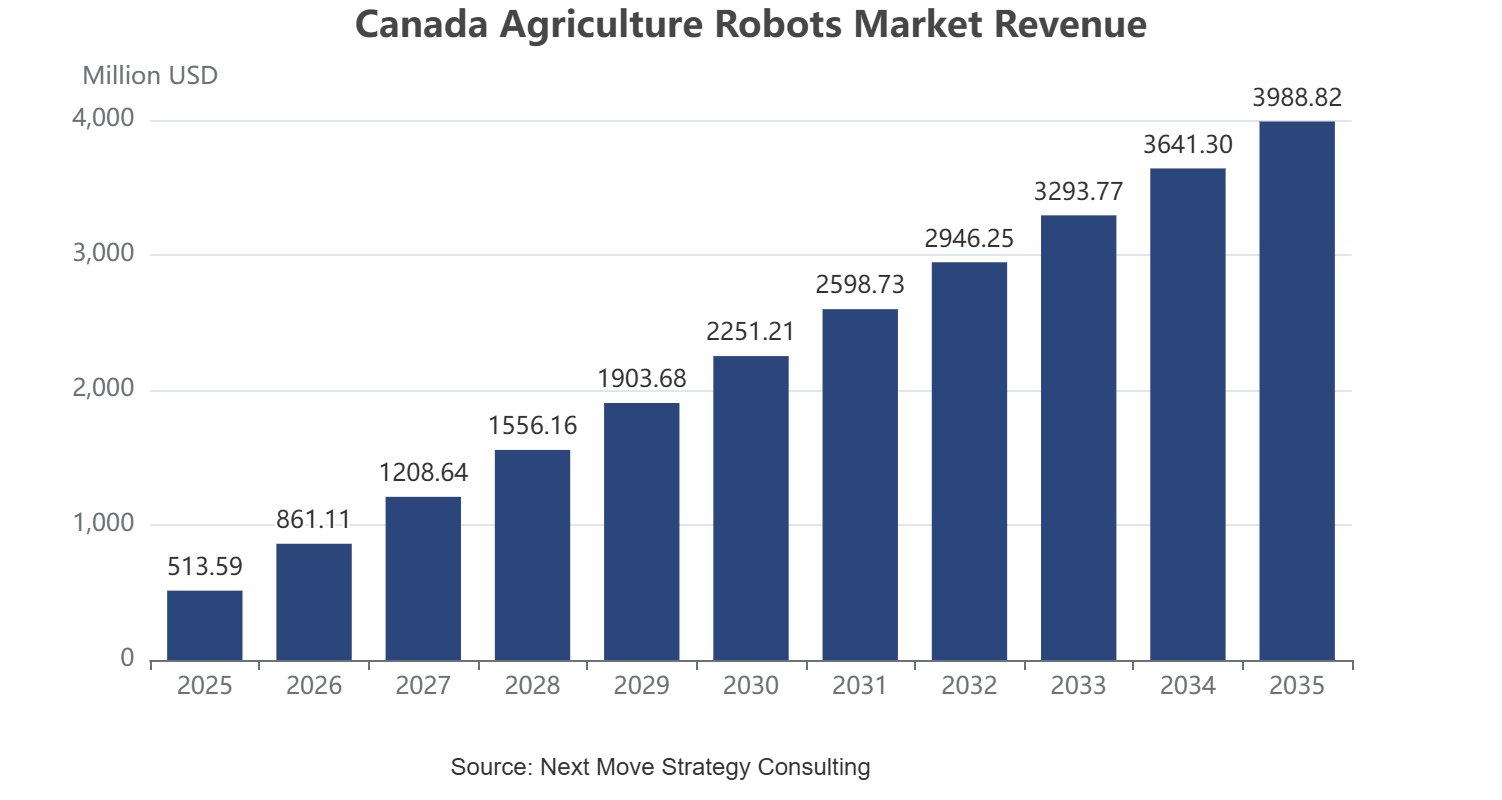
The Canada Agriculture Robots Industry was valued at USD 513.59 million in 2025 and is estimated to reach USD 689.05 million in 2026. The market is projected to reach USD 3,988.82 million by 2035, registering a CAGR of 21.5% during 2026–2035. In volume terms, the market accounted for 4 thousand units in 2025 and is expected to reach 5 thousand units in 2026, with shipments forecast to rise to 51 thousand units by 2035, reflecting a volume CAGR of 28.4%. Growth is driven by increasing adoption of autonomous farming technologies, precision agriculture advancements, and persistent agricultural labor shortages.
Ecosystem Analysis of the Canada Agriculture Robots Market
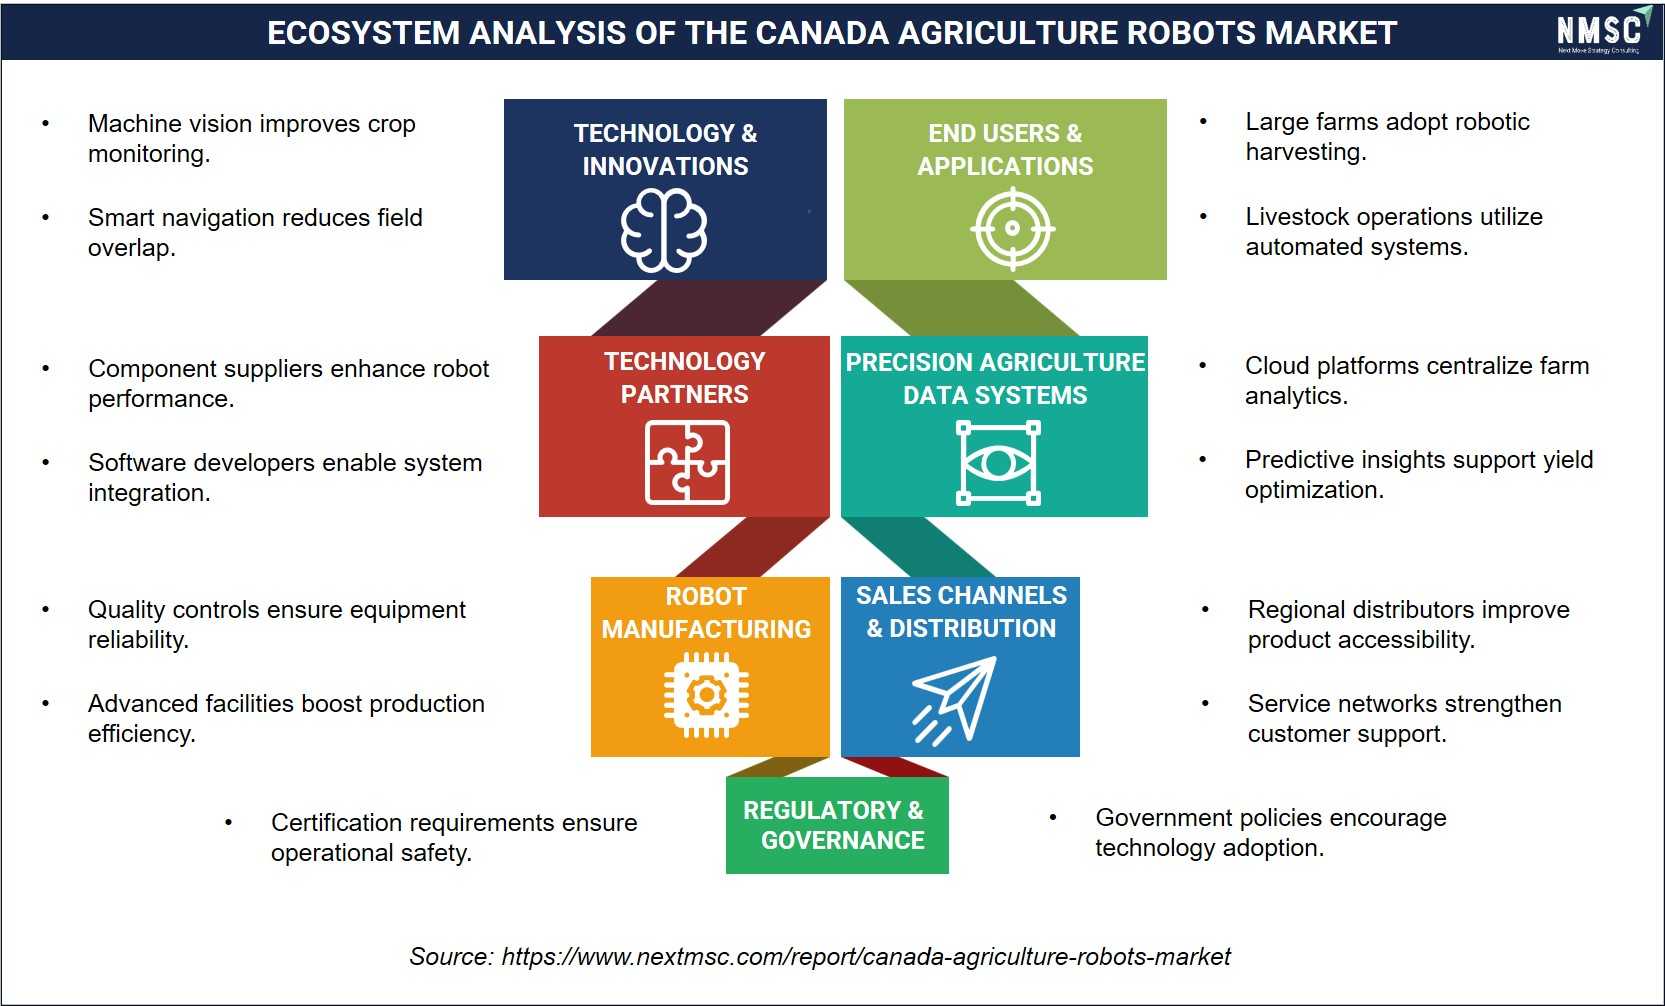
The Canada Agricultural Robots Market ecosystem is supported by collaboration among technology innovators, robot manufacturers, precision agriculture data providers, distribution partners, and end users. Advances in AI, robotics, sensing technologies, and data analytics, combined with strategic partnerships and a robust regulatory framework, are driving innovation and adoption. This integrated ecosystem enhances farm productivity, supports precision agriculture, and strengthens the market's long-term growth and competitiveness.
What Are the Key Growth Catalysts, Inhibitors, and Opportunities Shaping the Canada Agriculture Robots Industry?
Growth Catalyst & Risk Assessment Matrix
|
Drivers / Trends / Restraints |
(+/–) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Large-scale farming operations are increasingly investing in robotic solutions to enhance efficiency across Canadian agriculture. |
+2.10% |
Canada |
Short to medium term (1–4 years) |
|
Growing labor shortages in rural agricultural regions are accelerating farm automation adoption across Canada. |
+1.90% |
Canada |
Medium term (2–5 years) |
|
Government support for agricultural innovation is encouraging deployment of advanced robotic technologies in Canadian farms. |
+2.00% |
Canada |
Medium to long term (3–7 years) |
|
Seasonal farming patterns can limit utilization rates of expensive robotic equipment, constraining return on investment. |
-1.40% |
Canada |
Short to medium term (1–4 years) |
|
Autonomous field robots designed for broad-acre farming present attractive growth opportunities across Canada's prairie regions. |
+1.70% |
Canada |
Medium term (2–5 years) |
The Canada Agriculture Robots Industry is shaped by a dynamic interplay of growth drivers, restraints, and opportunities that collectively define the competitive trajectory of the industry. Large-scale farming investments, acute labor shortages, and government support for agricultural innovation are primary forces driving market expansion. However, seasonal farming patterns continue to constrain full utilization of robotic equipment investments. Simultaneously, the emergence of autonomous field robots for broad-acre farming presents transformative market opportunities across Canada's diverse agricultural landscape.
Growth Driver
How Are Large-Scale Farming Operations Increasingly Investing in Robotic Solutions to Enhance Efficiency in Canada?
Canada's agricultural sector is experiencing a significant shift as large-scale farming operations prioritize automation to improve operational efficiency and productivity. Rising input costs, evolving consumer demand for precision-produced commodities, and the need for scalable solutions are compelling commercial farms to deploy advanced robotic systems across field, dairy, and aerial applications. The integration of robotics into large farming enterprises delivers measurable gains in resource utilization, yield consistency, and labor cost reduction, serving as a primary near-term growth catalyst for the Canada Agriculture Robots Market.
How Are Growing Labor Shortages in Rural Agricultural Regions Accelerating Farm Automation Adoption in Canada?
Rural agricultural regions across Canada face persistent workforce availability challenges, driven by demographic shifts, urbanization trends, and declining interest in seasonal farm employment. These structural labor shortages compel farm operators to accelerate deployment of automated robotic systems that substitute and supplement human labor across critical farming operations. Agricultural robots provide reliable performance in planting, harvesting, monitoring, and livestock management functions, reducing dependency on seasonal labor and representing a fundamental structural driver sustaining strong demand throughout the Canada Agriculture Robots Market forecast period.
How Is Government Support for Agricultural Innovation Encouraging Deployment of Advanced Robotic Technologies in Canada?
Federal and provincial government programs in Canada are actively supporting agricultural technology adoption through grant schemes, subsidized financing, and research and development incentives. Policies aimed at modernizing Canada's agricultural sector facilitate procurement and deployment of advanced robotic systems among both large-scale and mid-tier farm operators. Regulatory frameworks encouraging precision agriculture adoption, combined with public funding for agri-tech innovation hubs, accelerate commercialization of next-generation farming robots, representing a significant enabling factor for sustained market growth throughout the forecast period.
Growth Inhibitor:
How Do Seasonal Farming Patterns Limit Utilization Rates of Expensive Robotic Equipment in Canada?
Canada's distinct agricultural calendar, characterized by defined planting, growing, and harvesting seasons, creates inherent challenges in maximizing utilization of capital-intensive robotic systems. During off-peak periods, robotic equipment may remain idle, reducing return on investment and extending payback periods for farm operators. This seasonal utilization constraint is particularly pronounced in regions with harsh winters and limited year-round farming activity. The resulting financial efficiency challenge tempers adoption rates among cost-conscious operators, representing a meaningful restraint on broader market penetration within the Canada Agriculture Robots Market.
Growth Opportunity:
How Do Autonomous Field Robots Designed for Broad-Acre Farming Present Attractive Growth Opportunities in Canada?
Canada's expansive agricultural landmass, encompassing vast stretches of prairie cropland and diverse farming terrains, creates ideal conditions for deploying autonomous field robots engineered for broad-acre operations. These robotic platforms, capable of performing seeding, soil management, fertilization, and crop scouting across large contiguous fields, address both labor efficiency and precision agriculture objectives. The scalability of broad-acre robotic solutions aligns with the operational demands of Canada's dominant grain and oilseed farming sectors, presenting substantial market expansion potential throughout the 2026–2035 forecast period.
How Is the Canada Agriculture Robots Industry Segmented in This Report, and What Are the Key Insights from the Segmentation Analysis?
By Type
Which Robot Type Is Driving the Greatest Revenue Growth across the Canada Agriculture Robots Industry?
The Canada Agriculture Robots Market by type is segmented into Unmanned Aerial Vehicles (UAVs), Milking Robots, Driverless Tractors, Automated Harvest Robots, and Others.
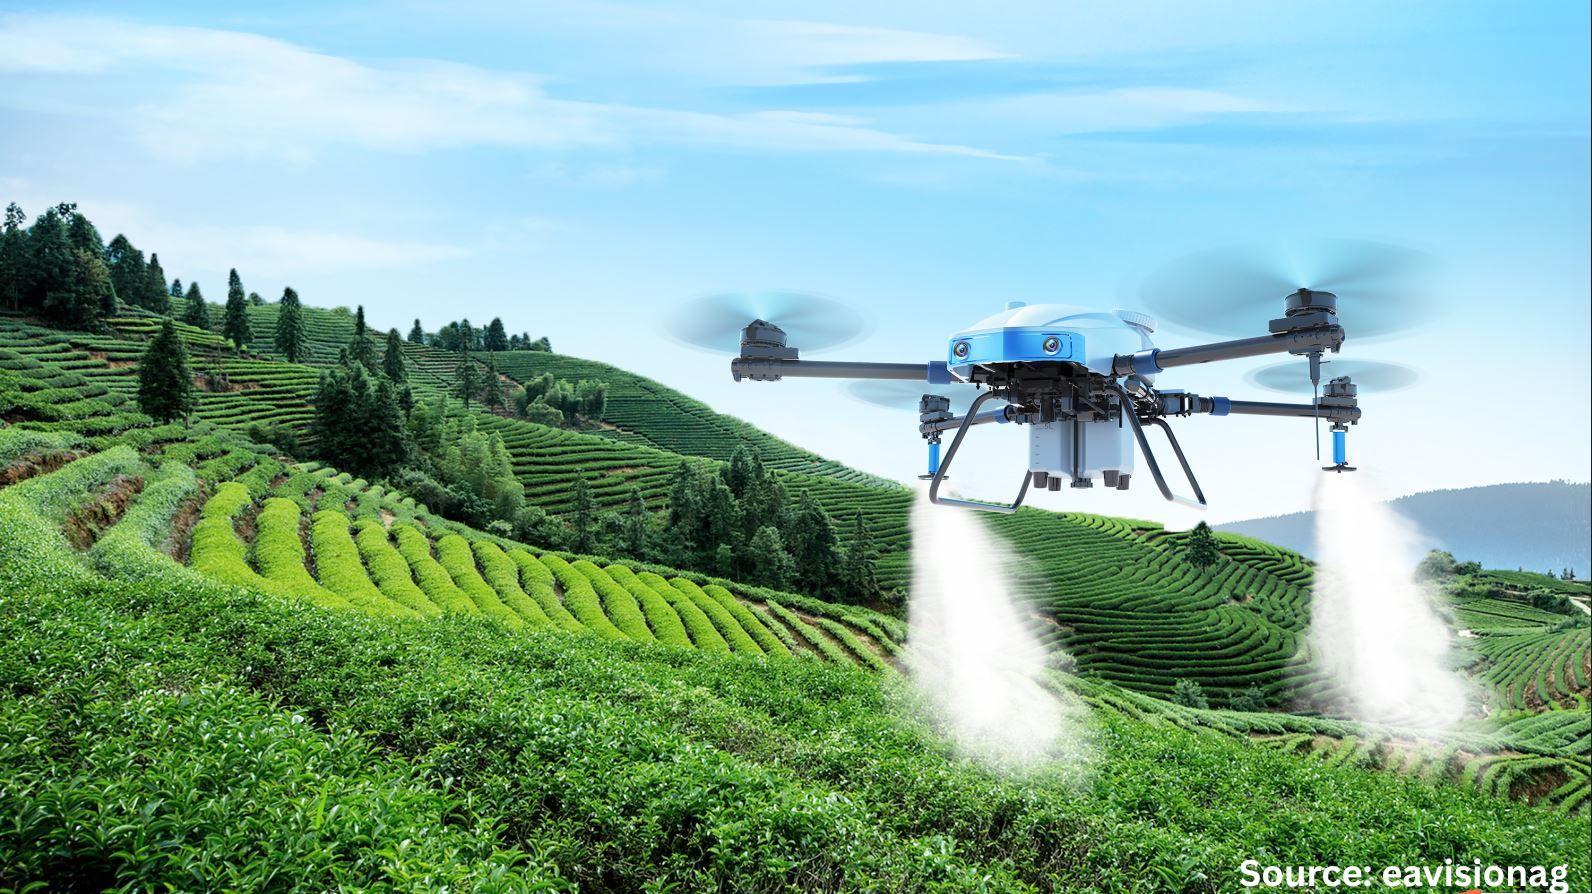
Among all robot types, Driverless Tractors and Automated Harvest Robots are emerging as significant contributors to market revenue, driven by extensive use of large field machinery across Canada's broad-acre farming landscape. Unmanned Aerial Vehicles (UAVs) are gaining rapid adoption for crop scouting and aerial monitoring applications, while Milking Robots continue to expand within Canada's substantial dairy farming sector. The diversification of robotic platforms across functional categories is expanding addressable market segments and supporting sustained revenue growth throughout the forecast period.
By Application
Which Application Segment Holds the Largest Share of the Canada Agriculture Robots Industry Revenue?
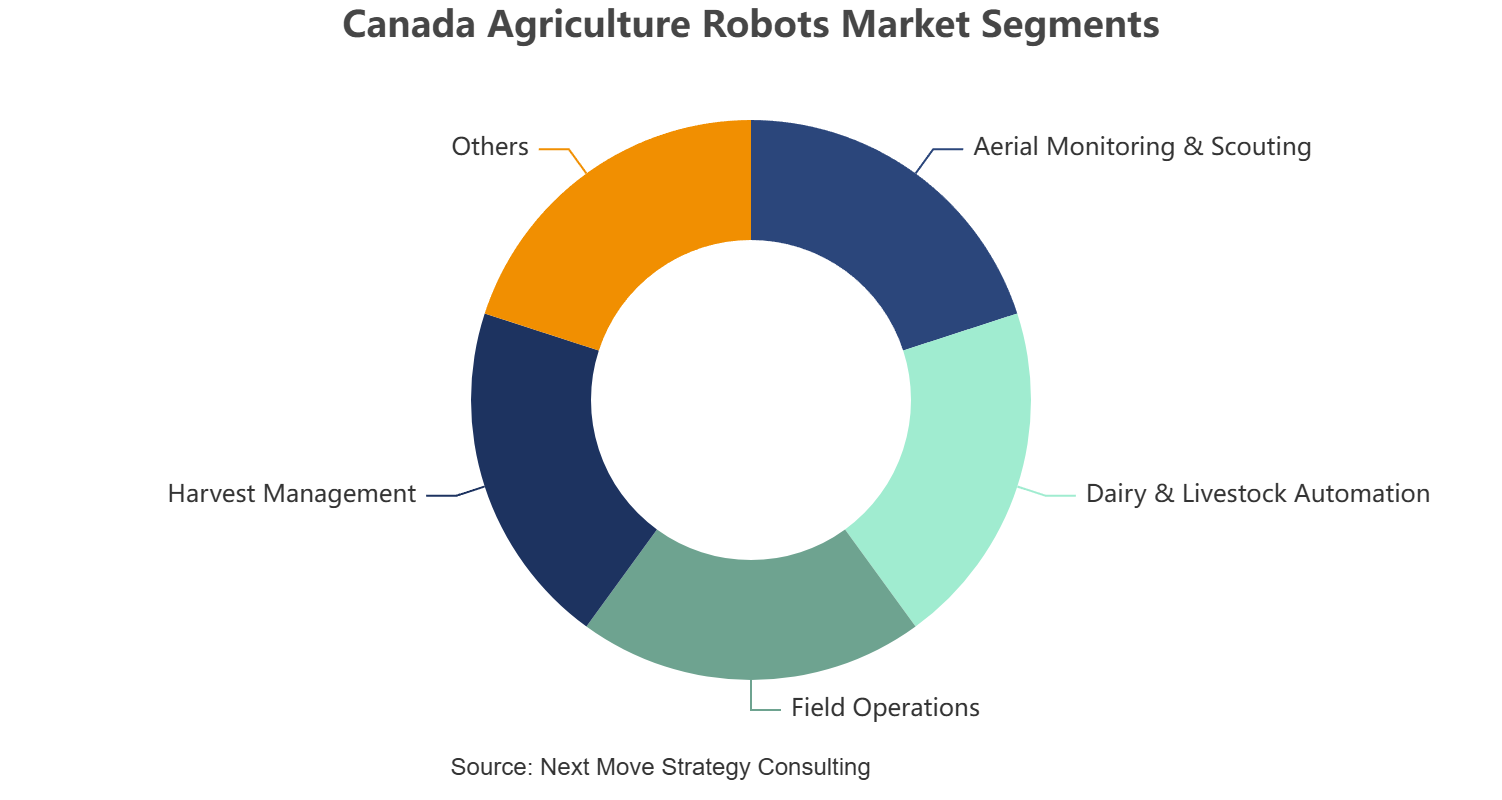
By application, the Canada Agriculture Robots Market is segmented into Aerial Monitoring & Scouting, Dairy & Livestock Automation, Field Operations, Harvest Management, and Others.
Field Operations represents a dominant application segment, encompassing plowing, seeding, field farming, and soil and irrigation management activities that benefit significantly from robotic automation across Canada's expansive agricultural regions. Dairy & Livestock Automation is also experiencing steady growth, driven by strong adoption of milking robots and dairy management systems within Canada's prominent dairy industry. Aerial Monitoring & Scouting is gaining traction through UAV-enabled crop protection, weed control, and weather tracking capabilities, while Harvest Management is emerging as a high-priority segment amid intensifying labor shortages.
Key Segments
By Type
-
Unmanned Aerial Vehicles (UAVs)
-
Milking Robots
-
Driverless Tractors
-
Automated Harvest Robots
-
Others
By Farming Type
-
Indoor Farming
-
Outdoor Farming
-
Indoor & Outdoor
By Application
-
Aerial Monitoring & Scouting
-
Crop Protection & Weed Control
-
Crop Scouting & Monitoring
-
Weather Tracking
-
Inventory Management
-
-
Dairy & Livestock Automation
-
Milking
-
Dairy Management
-
Shepherding and Herding
-
-
Field Operations
-
Plowing
-
Seeding
-
Field Farming
-
Soil & Irrigation Management
-
-
Harvest Management
-
Others
Competitive Landscape
The Canada Agriculture Robots Market features a highly competitive landscape characterized by the presence of established multinational corporations, specialized agri-tech innovators, and emerging technology providers. Market participants are actively investing in research and development, strategic partnerships, and product diversification to strengthen their competitive positioning within the Canadian market. The convergence of robotics, artificial intelligence, and precision agriculture is driving rapid product evolution, with companies competing on the basis of automation capabilities, cost efficiency, scalability, and integration with existing farm management systems.
Key Players
-
John Deere Canada ULC
-
Lely Holding B.V.
-
CNH Industrial Canada Ltd.
-
Carbon Robotics, Inc.
-
Kubota Canada Ltd.
-
Solinftec Canada Inc.
-
XAG Co., Ltd.
-
BouMatic LLC
-
Augean Robotics, Inc.
-
AgXeed B.V.
-
Korechi Innovations Inc.
-
FarmDroid ApS
-
Naïo Technologies
The competitive landscape includes leading global players such as John Deere Canada ULC and CNH Industrial Canada Ltd., which dominate field automation and driverless tractor segments. Lely Holding B.V., DeLaval Inc., and GEA Mechanical Equipment Inc. lead dairy and livestock automation offerings, while BouMatic LLC and FarmDroid ApS advance specialized farming automation solutions. Carbon Robotics, Inc., XAG Co., Ltd., and Naïo Technologies S are expanding precision weeding and aerial monitoring capabilities, with Solinftec Canada Inc., Kubota Canada Ltd., Augean Robotics, Inc., AgXeed B.V., and Korechi Innovations Inc. further intensifying the competitive landscape.
Regulatory Framework Impacting the Canada Agriculture Robots Market
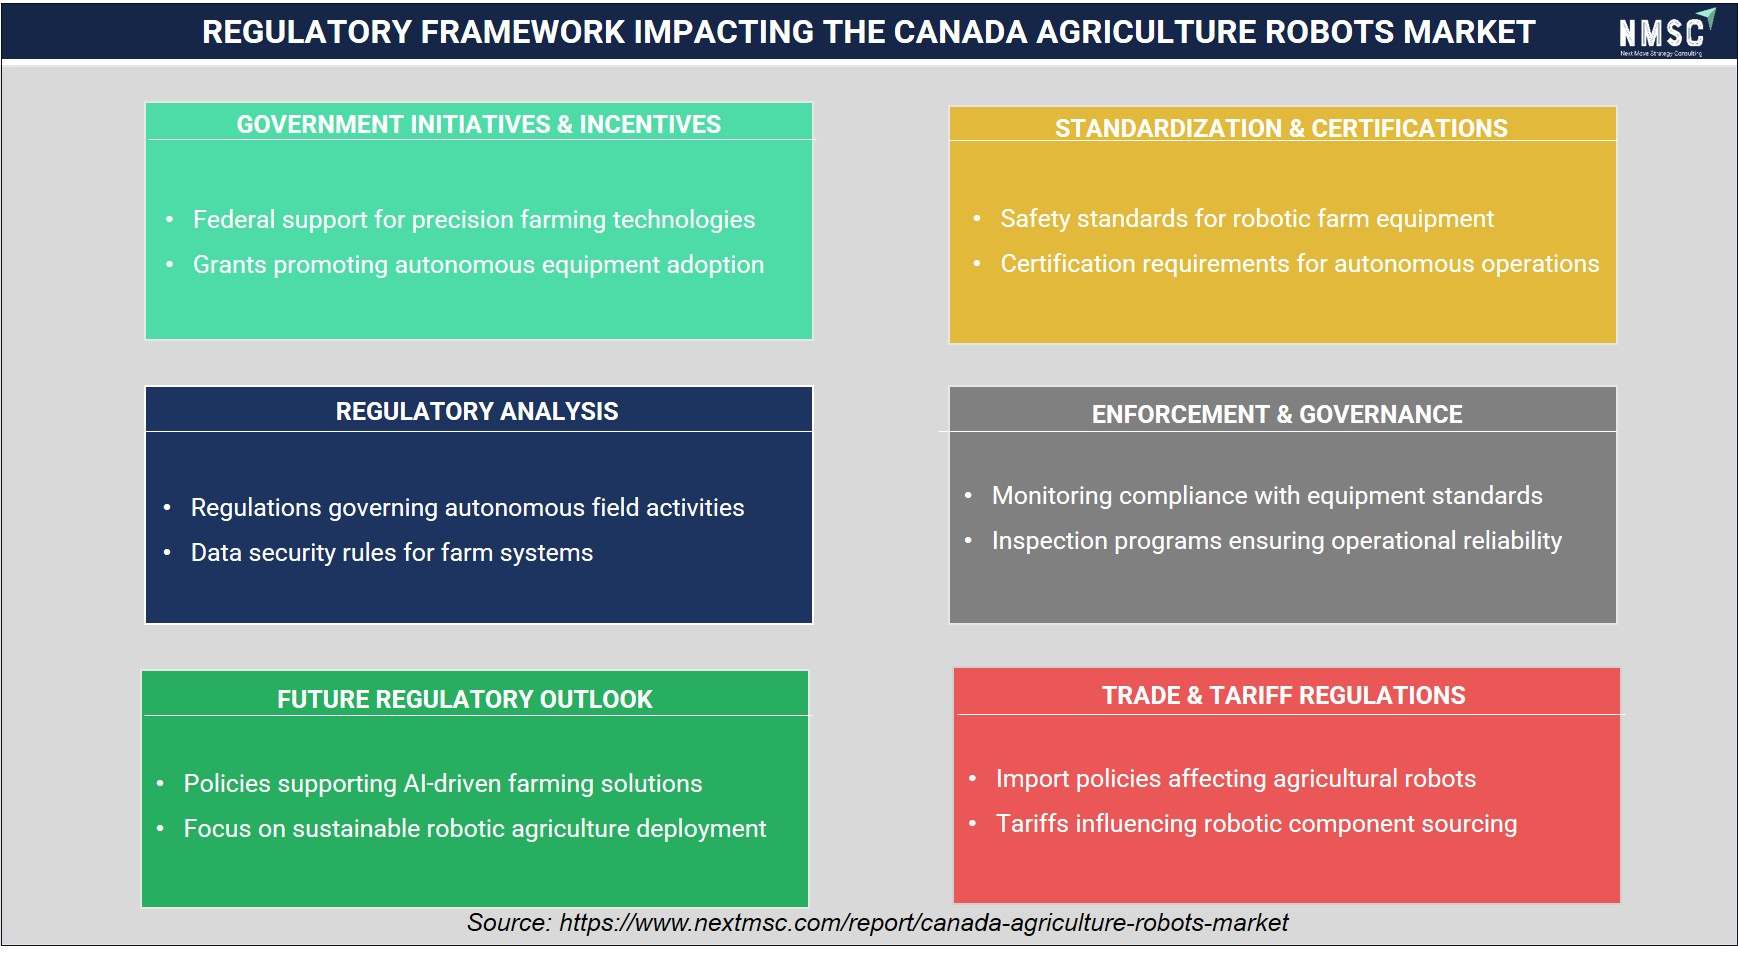
The Canada Agricultural Robots Market is supported by a well-defined regulatory framework that encourages innovation while ensuring safety, operational reliability, and compliance. Government incentives, equipment safety standards, certification requirements, and data security regulations facilitate the responsible adoption of autonomous farming technologies. Continued policy support for AI-driven agriculture, sustainability, and precision farming is expected to strengthen market growth and accelerate the deployment of advanced robotic solutions.
Key Benefits for Stakeholders
This report delivers comprehensive market intelligence for stakeholders across the Canada Agriculture Robots Market, enabling informed strategic decision-making. Industry participants, including manufacturers, technology developers, and agricultural enterprises, benefit from detailed segmentation analysis, competitive benchmarking, and growth opportunity identification. Investors and venture capital firms gain access to rigorous market sizing and revenue forecasting data spanning the 2026–2035 forecast period, facilitating accurate investment evaluation and portfolio management aligned with Canada's evolving agricultural technology landscape.
Policymakers and regulatory bodies can leverage the report's insights to develop evidence-based frameworks that support sustainable agricultural automation adoption across Canadian provinces. Research institutions and academic organizations benefit from comprehensive analysis of market trends, innovation trajectories, and technology adoption patterns within the Canadian agriculture sector. The customizable segmentation structure enables stakeholders to tailor analytical outputs to specific regional, product, or application requirements, enhancing the relevance and applicability of market intelligence across diverse organizational contexts.
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter's Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The Canada Agriculture Robots Industry is poised for exceptional growth, underpinned by large-scale farming investments, persistent labor shortages, and proactive government support for agricultural innovation. With revenue projected to grow from USD 689.05 million in 2026 to USD 3,988.82 million by 2035 at a CAGR of 21.5%, the market presents compelling opportunities across robotic platforms and applications. Competitive dynamics continue to intensify as established players and emerging innovators collaborate to deliver specialized autonomous solutions, positioning Canada as a significant growth market for agricultural robotics throughout the forecast period.
About the Author
 Mihul Sharma
— Sikha Haritwal is a researcher with more than 5 years of experience. She has been keeping a close eye on several industry verticals, including construction & manufacturing, personal care products, and consumer electronics. She has avid interest in writing news articles and hopes to use blog as a platform to share her knowledge with others.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

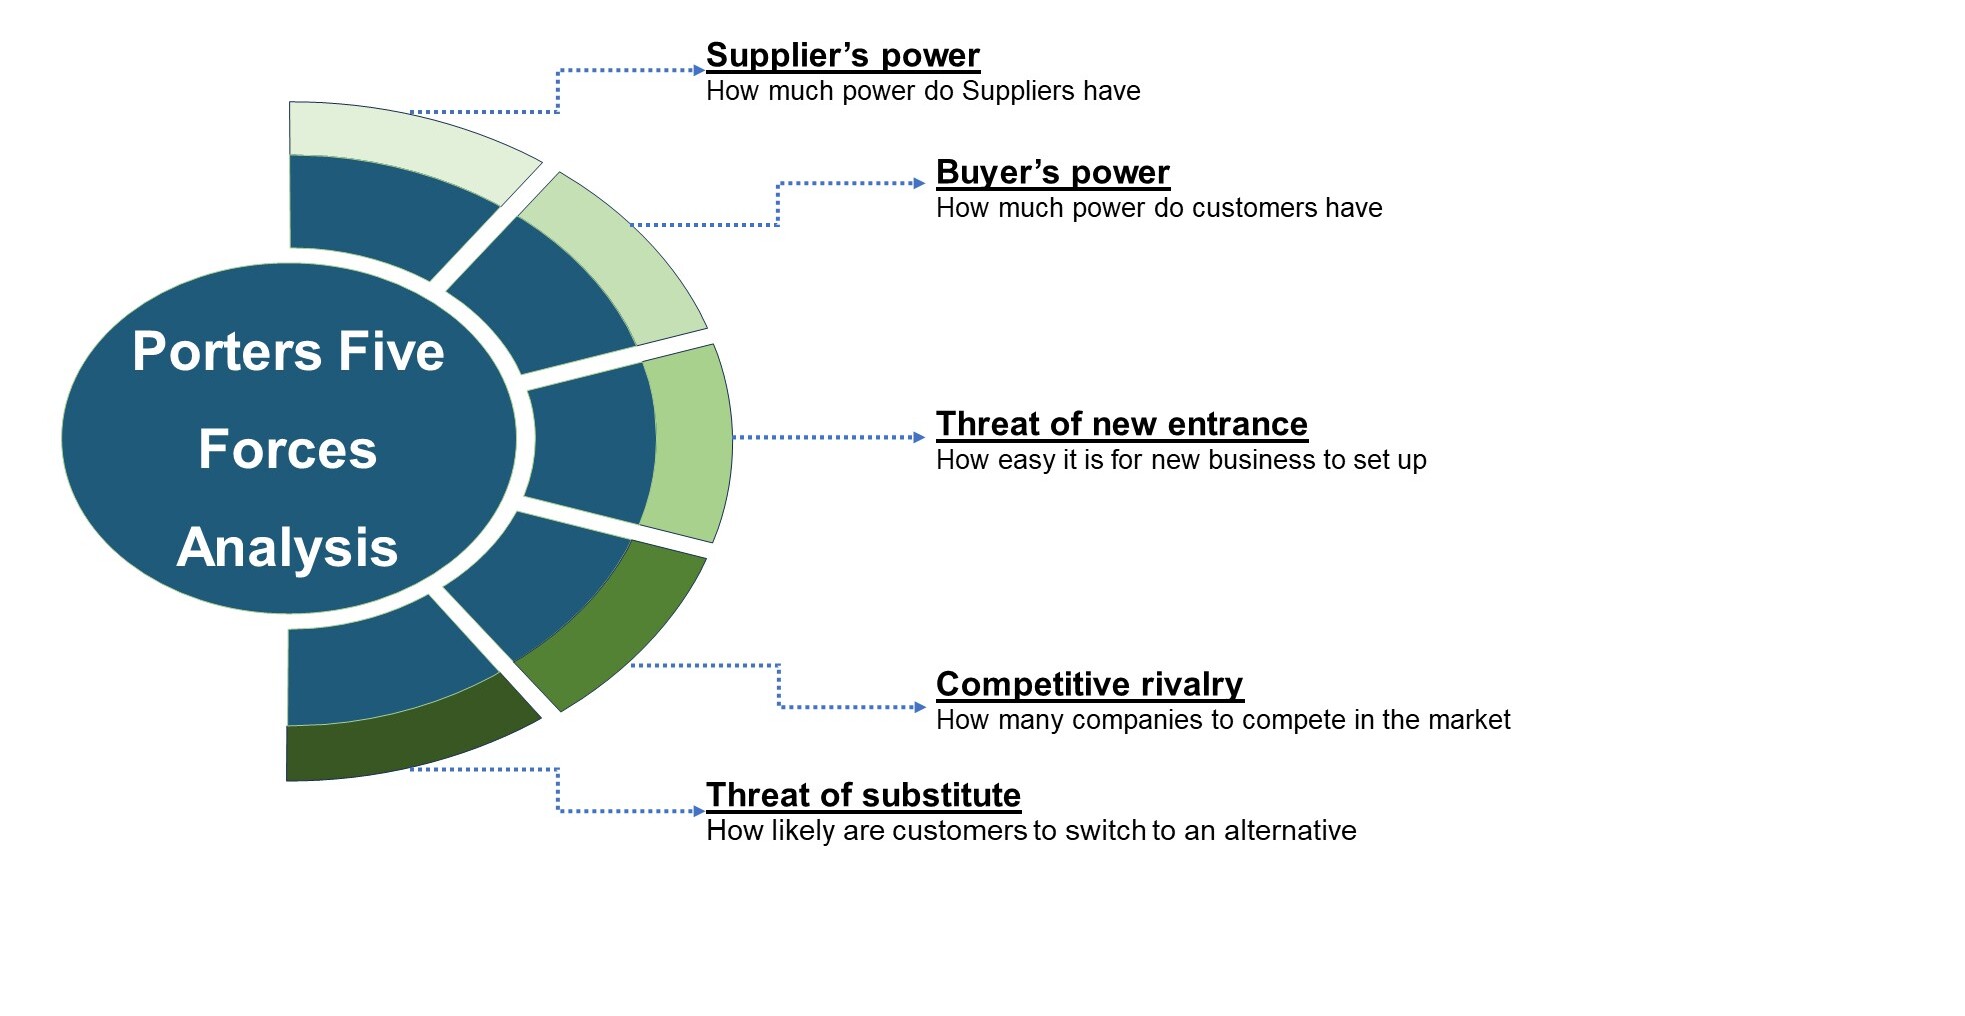
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.



 Speak to Our Analyst