Defibrillators Market Global Industry Analysis and Forecast (2026-2035)

The global Defibrillators Market is valued at USD 16.96 Billion in 2026 and is projected to reach USD 30.21 Billion by 2035, growing at a CAGR of 6.63% from 2026 to 2035. Key growth factors include rising sudden cardiac arrest incidence and expanding public-access AED programs, with North America leading the market and Implantable Defibrillators accounting for approximately 52% share.
Download Free Sample PDF
Base Year (2025)
$16.96 Billion
Forecast (2035)
$30.21 Billion
CAGR (2026-2035)
6.6%
Top Country
North America

What Is the Defibrillators Market Size?

The global defibrillators market size was valued at USD 15.48 billion in 2025 and is estimated at USD 16.96 billion in 2026, forecast to reach USD 30.21 billion by 2035, expanding at a 6.63% CAGR between 2026 and 2035. North America leads with approximately 42% share, while Implantable Defibrillators dominate all other product categories with approximately 52% share.

We observed that growth is broadening across every segmentation axis, with rising sudden cardiac arrest incidence, expanding public-access defibrillation programs, and growing reimbursement support for implantable cardioverter-defibrillators driving the dominant structural shifts through 2035.

Defibrillators Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $15.48 Billion
2025
2026 $16.96 Billion
2026
2027 $18.08 Billion
2027
2028 $19.28 Billion
2028
2029 $20.56 Billion
2029
2030 $21.93 Billion
2030
2031 $23.38 Billion
2031
2032 $24.93 Billion
2032
2033 $26.58 Billion
2033
2034 $28.34 Billion
2034
2035 $30.21 Billion
2035

Key Takeaways

By Product Type: Implantable Defibrillators held the largest share of approximately 52% (USD 8.05 billion) in 2025; Wearable Defibrillators are the fastest-growing sub-segment at 10.7% CAGR from 2026–2035.

By Defibrillation Technology: Biphasic held the largest share of approximately 93% (USD 14.40 billion) in 2025 and is also the fastest-growing sub-segment at 8.2% CAGR from 2026–2035.

By Sales Channel: Direct Sales held the largest share of approximately 54% (USD 8.36 billion) in 2025; Retail Sales is the fastest-growing sub-segment at 11.8% CAGR from 2026–2035.

By Buyer Type: Healthcare Providers held the largest share of approximately 44% (USD 6.81 billion) in 2025; Individual Consumers are the fastest-growing sub-segment at 10.8% CAGR from 2026–2035.

By End User: Healthcare Facilities held the largest share of approximately 46% (USD 7.12 billion) in 2025; Home Care is the fastest-growing sub-segment at 9.4% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 42% revenue share (USD 6.50 billion) in 2025.

Fastest-Growing Region: Middle East & Africa is expected to register the highest CAGR of 10.4% during 2026–2035.

Dominant Country: U.S. led with approximately USD 5.52 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 12.3% CAGR from 2026–2035.

Market Opportunity: The defibrillators market is expected to create an absolute dollar opportunity of USD 13.25 billion between 2026 and 2035, presenting significant investment potential across wearable cardioverter-defibrillator platforms and public-access AED infrastructure.

According to NMSC analysis, manufacturers are increasingly pairing implantable and wearable devices with remote monitoring platforms that transmit arrhythmia and device-status data directly to cardiac care teams, a shift that is changing procurement criteria from device performance alone toward connected- care capability as health systems seek to reduce unplanned follow-up visits and detect device or lead malfunctions between scheduled interrogations.

What Does the Defibrillators Market Encompass?

The defibrillators market encompasses implantable, wearable, and external devices that detect life-threatening ventricular arrhythmias, including ventricular fibrillation and ventricular tachycardia, and deliver corrective electrical shocks to restore normal cardiac rhythm. Cardiac arrest can result from several electrical rhythms, including shockable rhythms such as ventricular fibrillation and pulseless ventricular tachycardia, as well as non-shockable rhythms such as pulseless electrical activity and asystole. The market therefore serves three distinct care settings: continuous implantable protection for diagnosed high-risk patients, temporary wearable protection during periods of transient risk, and emergency external defibrillation in hospitals, ambulances, and public spaces. Our assessment indicates that scope spans transvenous and subcutaneous implantable cardioverter-defibrillators, cardiac resynchronization therapy defibrillators, wearable cardioverter-defibrillators, and professional and automated external defibrillators procured by healthcare providers, EMS organizations, government agencies, and individual consumers.

Regulatory frameworks including the U.S. Food and Drug Administration's premarket approval pathway for Class III implantable devices and the European Union's Medical Device Regulation continue to shape approval timelines and post-market surveillance obligations for cardiac rhythm management devices, while national public-access defibrillation statutes increasingly mandate AED placement in schools, airports, and commercial facilities. We observed that technology adoption is shifting toward remote monitoring-enabled implantable and wearable devices that transmit arrhythmia episodes and device diagnostics between scheduled clinical visits. NMSC's analysis indicates that this connected-care shift, combined with expanding public-access defibrillation infrastructure, is redefining procurement criteria across the defibrillators market.

Market Drivers & Dynamics

Interactive Dataset
Rising sudden cardiac arrest incidence tied to aging and cardiovascular disease burden driver +2.1% North America, Europe 2026-2035
Expanding public-access defibrillation mandates in schools and commercial facilities driver +1.5% North America, Europe, Asia-Pacific 2026-2035
Growing reimbursement support for implantable cardioverter-defibrillator procedures driver +1.2% North America, Europe 2026-2035
Rising adoption of remote monitoring-enabled cardiac rhythm management devices driver +0.9% Global 2026-2032
Expanding EMS and hospital infrastructure investment in emerging markets driver +0.8% Asia-Pacific, Middle East & Africa 2026-2035
Growing wearable defibrillator adoption for post-myocardial-infarction bridging therapy driver +0.6% North America, Europe 2026-2032
High procedural and device cost limiting implantable defibrillator access restraint -1.0% Asia-Pacific, Latin America, Middle East & Africa 2026-2035
Lead-related complications and device recalls affecting clinician confidence restraint -0.6% Global 2026-2032
Reimbursement variability and prior-authorization delays in emerging markets restraint -0.5% Latin America, Middle East & Africa 2028-2035
Limited cardiac electrophysiology specialist availability in rural regions restraint -0.4% Asia-Pacific, Latin America 2028-2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Defibrillators Market?

Rising sudden cardiac arrest incidence tied to aging populations and cardiovascular disease burden is the primary driver of the market. The U.S. Centers for Disease Control and Prevention continues to identify heart disease as the leading cause of death nationally, sustaining demand for both implantable protection among diagnosed high-risk patients and external defibrillation capability for undiagnosed cardiac arrest events. We observed that this disease burden, reinforced by expanding indications for cardiac resynchronization therapy in heart failure patients, continues to anchor baseline implantable and external defibrillator procurement across developed healthcare systems.

How Is Public-Access Defibrillation Policy Driving Defibrillators Market Growth?

Expanding public-access defibrillation mandates are accelerating market growth toward AED placement in schools, airports, and commercial facilities where bystander response time determines survival odds before EMS arrival. State and national legislation increasingly requires AED availability in high-occupancy public venues. Our assessment indicates that this regulatory push, combined with rising EMS infrastructure investment across Asia-Pacific, is compressing the gap between developed and emerging market AED density relative to prior forecast periods.

Growth Inhibitors

What Is Restraining Defibrillators Market Expansion?

High procedural and device cost restrains market expansion, particularly for implantable cardioverter-defibrillators requiring specialized electrophysiology implantation and long-term follow-up infrastructure. The World Health Organization continues to document limited access to advanced cardiac care in lower-resource health systems. We found that this cost barrier disproportionately affects patients in Asia-Pacific, Latin America, and Middle East & Africa, where out-of-pocket payment responsibility and limited specialist availability constrain implantable device utilization relative to disease prevalence.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Implantable
Transvenous
CRT-D
Subcutaneous
Extravascula
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Implantable Defibrillators $10.0 USD Billion $40.0 USD Billion 23.0%
Transvenous ICD $17.1 USD Billion $51.1 USD Billion 25.0%
CRT-D $24.2 USD Billion $62.2 USD Billion 19.0%
Subcutaneous ICD $31.3 USD Billion $73.3 USD Billion 17.0%
Extravascular ICD $38.4 USD Billion $84.4 USD Billion 22.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Product Type.

Unlock Full Data

Which Product Type Segment Dominates the Defibrillators Market?

Implantable Defibrillators led the market with USD 8.05 billion in 2025, reflecting the segment's high per-unit device cost and its clinical role as continuous, guideline-directed therapy for patients with confirmed high-risk arrhythmia indications such as prior sudden cardiac arrest or severely reduced ejection fraction. We observed that Wearable Defibrillators are the fastest-growing product segment, expanding at a 10.7% CAGR from 2026 to 2035, as clinicians increasingly prescribe wearable cardioverter-defibrillators to bridge patients through transient arrhythmia risk following myocardial infarction, revascularization, or newly diagnosed cardiomyopathy before a permanent implant decision is confirmed.

2025 (USD Billion)
2035 (USD Billion)
Biphasic
Monophasic
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Biphasic $10.0 USD Billion $40.0 USD Billion 24.0%
Monophasic $17.1 USD Billion $51.1 USD Billion 26.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Defibrillation Technology.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct Sales
Distributor
Retail Sales
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Sales $10.0 USD Billion $40.0 USD Billion 24.0%
Distributor Sales $17.1 USD Billion $51.1 USD Billion 10.0%
Retail Sales $24.2 USD Billion $62.2 USD Billion 8.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Healthcare P
EMS Organiza
Government O
Institutiona
Individual C
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Healthcare Providers $10.0 USD Billion $40.0 USD Billion 22.0%
EMS Organizations $17.1 USD Billion $51.1 USD Billion 12.0%
Government Organizations $24.2 USD Billion $62.2 USD Billion 14.0%
Institutional Buyers $31.3 USD Billion $73.3 USD Billion 12.0%
Individual Consumers $38.4 USD Billion $84.4 USD Billion 15.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Buyer Type.

Unlock Full Data

Which Buyer Type Leads the Defibrillators Market?

Healthcare Providers remained the dominant buyer type, reaching USD 6.81 billion in 2025 due to their direct procurement role for implantable and professional external defibrillators used in cardiac catheterization labs, operating rooms, and inpatient units. Based on research conducted by NMSC, we found that Individual Consumers are the fastest-growing buyer type at a 10.8% CAGR from 2026 to 2035, reflecting rising home AED purchases among households with a family member carrying an elevated cardiac risk profile.

2025 (USD Billion)
2035 (USD Billion)
Healthcare F
EMS
Public Acces
Home Care
Military
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Healthcare Facilities $10.0 USD Billion $40.0 USD Billion 26.0%
EMS $17.1 USD Billion $51.1 USD Billion 16.0%
Public Access $24.2 USD Billion $62.2 USD Billion 18.0%
Home Care $31.3 USD Billion $73.3 USD Billion 8.0%
Military $38.4 USD Billion $84.4 USD Billion 23.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data

Which End User Leads Defibrillators Market Demand?

Healthcare Facilities remained the leading end user within the market, valued at USD 7.12 billion in 2025 on sustained implantable device procedures and hospital-based emergency defibrillation requirements. Our findings suggest that Home Care is the fastest-growing end user, registering a 9.4% CAGR from 2026 to 2035, as wearable defibrillator prescriptions and consumer AED ownership extend defibrillation capability into residential settings for patients awaiting definitive risk stratification.

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the defibrillators market over the 2026-2035 forecast period.

How Can Remote Monitoring Platforms Unlock Growth in Implantable Defibrillator Follow-Up?

Remote monitoring platforms present a whitespace opportunity for manufacturers seeking to reduce clinic burden while improving early detection of arrhythmia recurrence and lead malfunction. Companies that expand connected-device data platforms integrated with electronic health records stand to capture recurring service revenue as cardiac electrophysiology practices consolidate follow-up workflows across growing implanted-patient panels.

Where Does Public-Access AED Registry Integration Create New Demand?

Community AED registry integration represents an underpenetrated opportunity as connected devices increasingly link to emergency dispatch systems that direct bystanders to the nearest unit. Manufacturers that build registry-compatible AEDs with location-reporting connectivity can capture recurring replacement and compliance-monitoring revenue as municipalities and commercial property owners formalize public-access defibrillation program requirements.

How Can Wearable Defibrillator Compliance Features Accelerate Bridging-Therapy Adoption?

Post-myocardial-infarction and post-revascularization patients awaiting risk restratification create a growing opportunity for wearable cardioverter-defibrillator manufacturers offering improved comfort and reduced false-alarm rates. Companies that demonstrate measurable wear-compliance improvement can secure broader prescribing support from cardiologists, benefiting from recurring rental and monitoring-service revenue during each patient's bridging period.

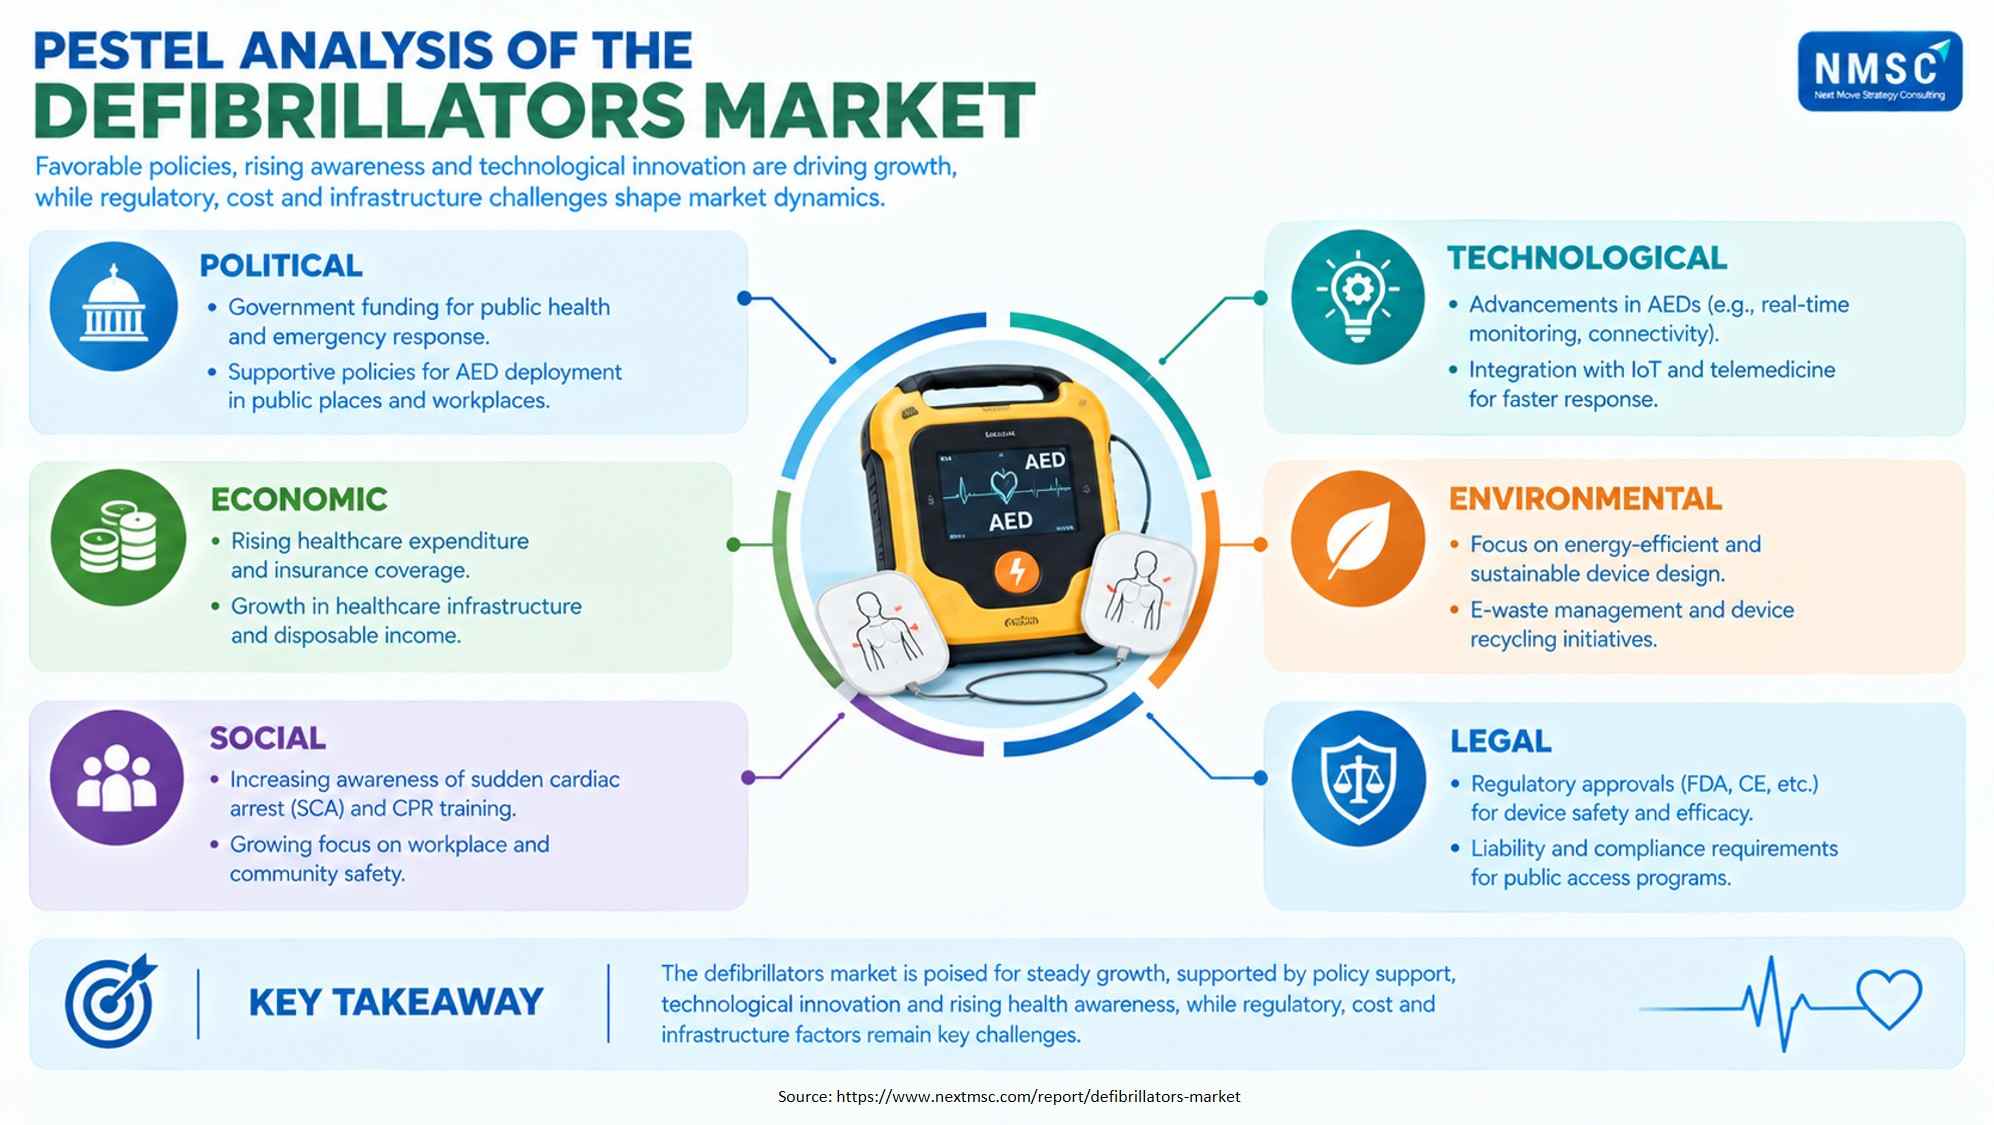
PESTEL Analysis of the Defibrillators Market

PESTEL Analysis of the Defibrillators Market

The PESTEL analysis of the defibrillators market highlights the external factors influencing adoption and market development. Government funding and supportive emergency-response policies are strengthening device deployment, while healthcare spending and awareness of sudden cardiac arrest support demand. Technological advances in connected AEDs, sustainability requirements, regulatory approvals, and compliance obligations continue to shape product development and commercialization.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the defibrillators market features a moderately consolidated competitive landscape, with global cardiac rhythm management leaders competing alongside specialized wearable and external defibrillator manufacturers on lead reliability, remote monitoring depth, and clinical outcomes evidence.

Dimension Description
Market Structure Moderately consolidated; a small group of diversified cardiac rhythm management leaders, including Medtronic plc, Abbott Laboratories, and Boston Scientific Corporation, compete alongside specialized wearable and external defibrillator manufacturers and numerous regional AED producers.
Innovation Focus Lumenless and extravascular lead design, AI-enhanced wearable alarm algorithms, remote monitoring connectivity, and registry-integrated AED platforms dominate current innovation pipelines across leading manufacturers.
Strategic Partnerships / Collaboration Activity Selective strategic collaboration activity, exemplified by manufacturers partnering with emergency-response technology providers to extend public-access defibrillation registry coverage.

How Do Companies Compete in the Defibrillators Market?

Companies compete primarily on clinical outcomes evidence, lead and battery longevity, and remote monitoring platform depth across the industry. Medtronic plc and Boston Scientific Corporation leverage extensive implantable device portfolios and long-term registry data to support electrophysiologist adoption, while ZOLL Medical Corporation competes on wearable and external defibrillator compliance features and emergency-response ecosystem integration for hospital and public-access customers.

Which Competitive Archetypes Dominate the Defibrillators Market?

Two archetypes dominate the market: diversified cardiac rhythm management leaders offering full implantable device portfolios supported by decades of clinical trial evidence, and focused specialists concentrated in wearable or external defibrillator categories. Medtronic plc and Abbott Laboratories exemplify the diversified archetype through comprehensive ICD and CRT-D portfolios, while ZOLL Medical Corporation and Kestra Medical Technologies, Inc. exemplify the focused archetype competing on wearable defibrillator compliance and comfort innovation.

How Are Companies Differentiating Through Innovation in Defibrillators?

Innovation and differentiation strategy increasingly center on reducing lead-related complications and improving patient compliance rather than competing on implant procedure count alone. Medtronic plc's OmniaSecure lumenless defibrillation lead and ZOLL Medical Corporation's AI-enhanced LifeVest algorithm both illustrate how manufacturers are addressing device-specific failure modes that have historically limited adoption or compliance. Our analysis shows that manufacturers unable to demonstrate credible complication-reduction evidence risk losing share to competitors with differentiated lead or wear-compliance data.

What Strategic Partnership and Expansion Activity Is Shaping the Defibrillators Market?

Strategic ecosystem partnerships continue to shape competitive positioning within the industry more than traditional acquisitions. ZOLL Medical Corporation's announced a new initiative with PulsePoint to grow the National Emergency AED Registry illustrates how manufacturers pursue distribution and data partnerships with emergency-response technology providers, while implantable device makers continue expanding clinical trial programs to support extravascular and subcutaneous ICD indication broadening.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping product innovation, clinical evidence generation, and manufacturing capacity within the global defibrillators market.

Abbott Laboratories Boston Scientific Corporation ZOLL Medical Corporation Stryker Corporation BIOTRONIK SE & Co. KG Koninklijke Philips N.V. MicroPort Scientific Corporation Nihon Kohden Corporation Shenzhen Mindray Bio-Medical Electronics Co., Ltd. SCHILLER AG Fukuda Denshi Co., Ltd. Shenzhen Comen Medical Instruments Co., Ltd. GS Elektromedizinische Geräte G. Stemple GmbH CU Medical Systems, Inc. Osatu S. Coop. Mediana Co., Ltd. Instramed Indústria Médico Hospitalar Ltda. Progetti S.r.l. Kestra Medical Technologies, Inc.

Latest Developments

We found that recent product developments within the defibrillators market are concentrated on lead reliability engineering and wearable defibrillator compliance features, reflecting the industry's focus on reducing device-specific complication and non-adherence risk.

Date Event
April 2026 SCHILLER announced that Spain’s Spanish Medical Emergency System equipped its ambulance fleet with more than 780 DEFIGARD Touch 7 monitor-defibrillators. The deployment expands SCHILLER’s prehospital presence across urban and rural emergency transport, adding integrated monitoring and defibrillation capabilities to a substantial ambulance fleet.
March 2026 Medtronic received U.S. FDA approval for an expanded indication of its OmniaSecure defibrillation lead, allowing placement in the left bundle branch area for conduction system pacing. The lumenless lead connects to ICD or CRT-D systems and supports defibrillation alongside advanced pacing applications.
February 2026 ZOLL’s Zenix professional monitor/defibrillator received European Union MDR approval. The device combines a large touchscreen, real-time CPR and ventilation feedback, configurable workflows, and information-management capabilities for EMS and hospital environments, advancing ZOLL’s professional defibrillator portfolio for high-acuity emergency response.
January 2026 Abbott and AtaCor Medical announced collaboration to advance an investigational parasternal extravascular ICD system. AtaCor’s investigational Atala lead will pair with Abbott’s investigational ICD system, with a pivotal IDE study planned for 2026, creating a next-generation approach that delivers defibrillation without placing the lead within blood vessels.

Investment Opportunities

What Capital Inflows Are Targeting the Defibrillators Market?

Capital inflows into the defibrillators market are increasingly directed toward lead-reliability engineering and wearable defibrillator compliance technology. Medtronic plc's OmniaSecure lead development and ZOLL Medical Corporation's AI-enhanced LifeVest platform illustrate sustained product investment behind complication reduction and patient adherence. We observed that investors favor manufacturers demonstrating credible clinical registry evidence, viewing long-term outcomes data as a proxy for continued electrophysiologist and cardiologist prescribing support.

How Is Infrastructure Investment Supporting Defibrillators Delivery?

Infrastructure investment is expanding electrophysiology laboratory capacity and EMS response networks to support growing implantable device procedure volumes and faster emergency defibrillation access. Our findings suggest that hospital systems are investing in cardiac catheterization and device-implant suites to meet rising heart failure and arrhythmia diagnosis rates, supporting the procedural capacity required as implantable device indications continue to broaden.

What ESG Considerations Are Shaping Defibrillators Investment Decisions?

Environmental, social, and governance considerations increasingly shape investment decisions, with equitable access to life-saving cardiac devices and post-market safety transparency as key criteria. Manufacturers increasingly disclose device recall history and complication-rate registry data as governance indicators. We found that investors increasingly favor manufacturers demonstrating measurable public-access defibrillation program support, treating community health investment as a governance indicator alongside product safety compliance.

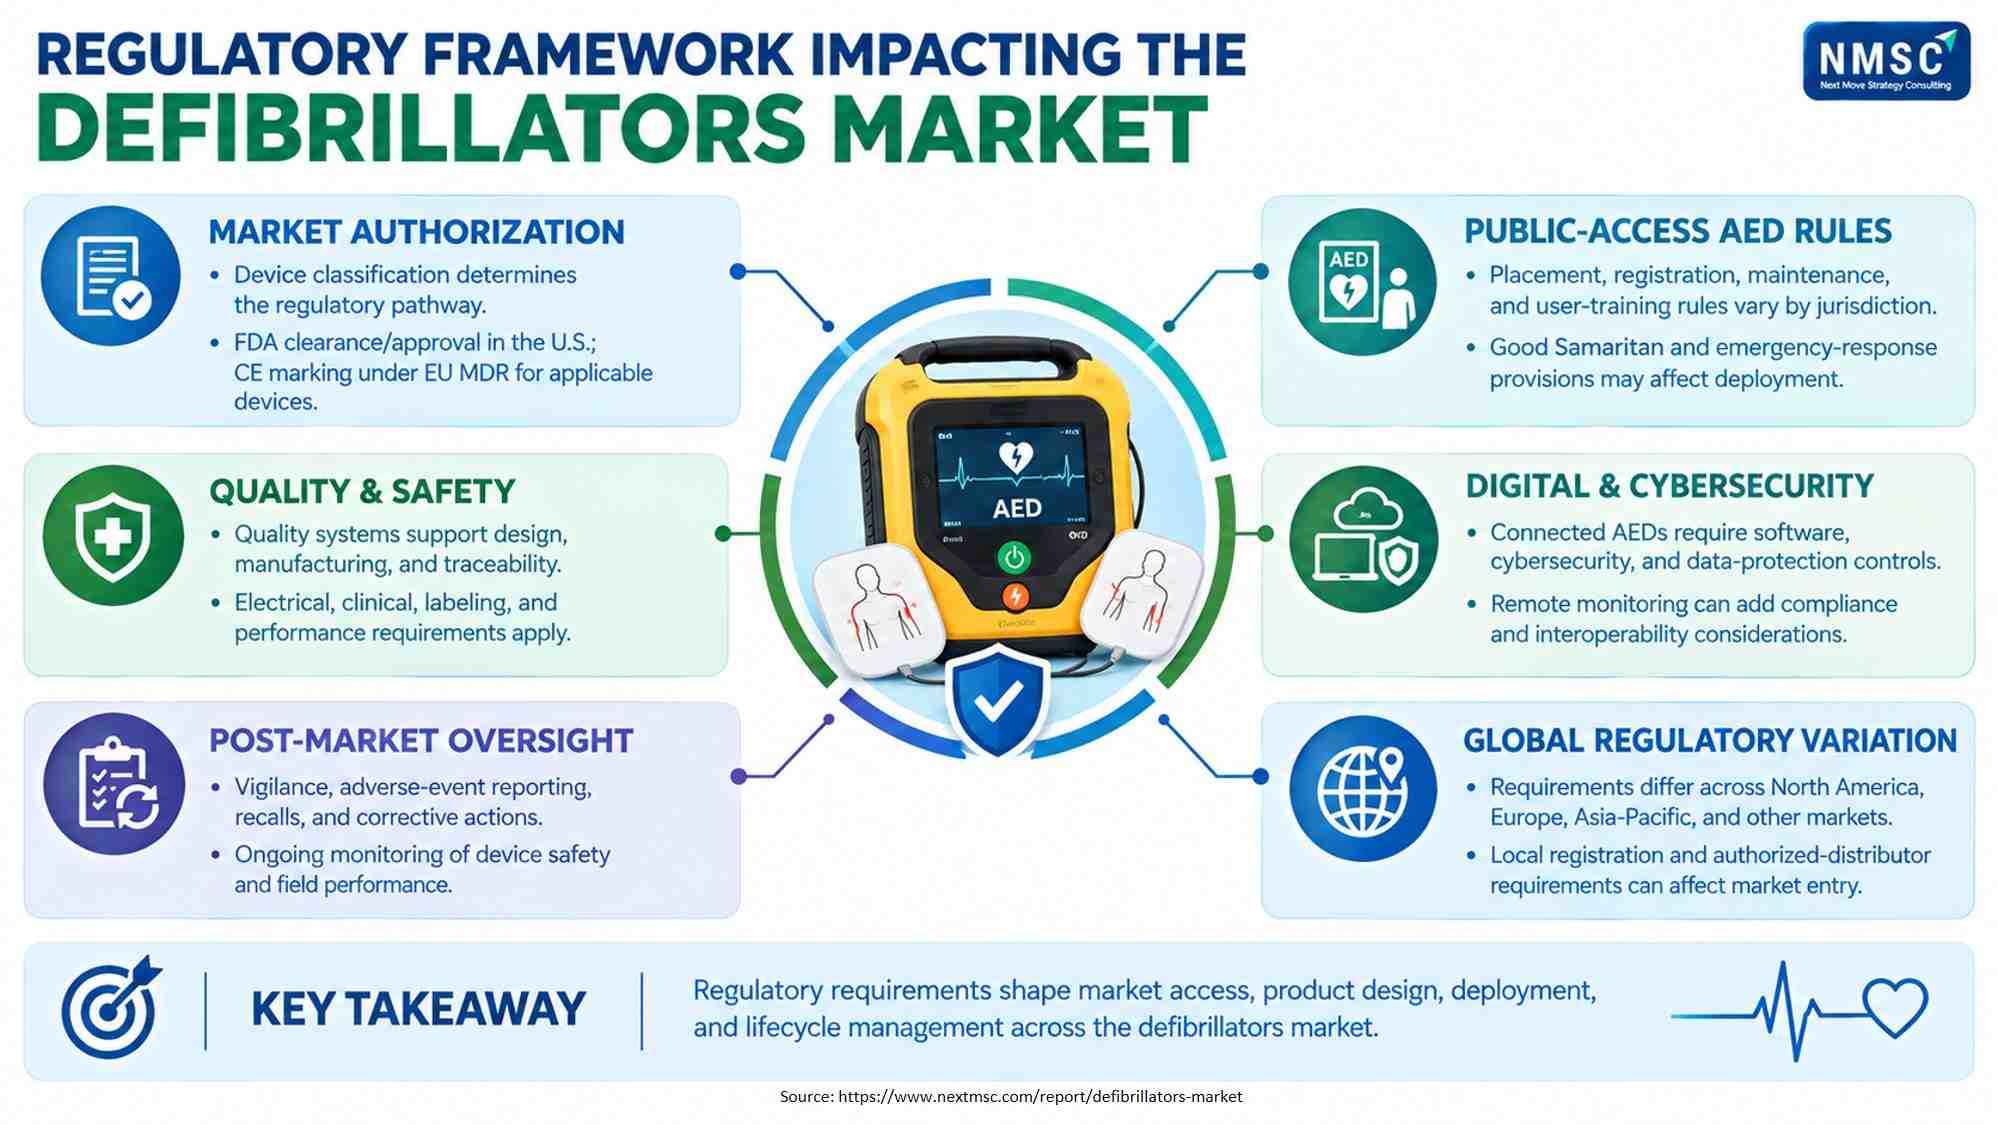
Regulatory Framework Impacting the Defibrillators Market

The regulatory framework for the defibrillators market encompasses device authorization, quality and safety requirements, public-access AED rules, cybersecurity, and post-market surveillance. Regulatory pathways such as FDA clearance and EU MDR requirements influence market entry, while jurisdiction-specific training, maintenance, labeling, and reporting provisions affect deployment. Increasing connectivity is also expanding compliance considerations around software, data protection, and interoperability.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support product portfolio and go-to-market decisions across the defibrillators industry. Our analysis shows that detailed product type, buyer type, and end-user breakdowns help commercial teams align device specifications with reimbursement and procurement requirements while identifying underserved patient categories for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the defibrillators device supply chain. We observed that the report's regional and segment-level growth differentials help identify which manufacturers are best positioned to capture above-market growth in wearable defibrillator and home care categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including remote monitoring connectivity, AI-enhanced alarm algorithms, and registry-integrated AED platforms, that are reshaping the industry. Our findings suggest that this analysis helps product roadmap teams prioritize investment around lead-reliability engineering and compliance-focused wearable design increasingly required by prescribing clinicians.

Key Market Segments Evaluated

By Product Type

  • Implantable Defibrillators 
    • Transvenous ICD
    • CRT-D
    • Subcutaneous ICD
    • Extravascular ICD
  • Wearable Defibrillators 
    • Wearable Cardioverter Defibrillator
  • External Defibrillators 
    • Professional Defibrillators
    • AEDs

By Defibrillation Technology

  • Biphasic
  • Monophasic

By Sales Channel

  • Direct Sales
  • Distributor Sales
  • Retail Sales

By Buyer Type

  • Healthcare Providers
  • EMS Organizations
  • Government Organizations
  • Institutional Buyers
  • Individual Consumers

By End User

  • Healthcare Facilities
  • EMS
  • Public Access
  • Home Care
  • Military

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook for the market remains positive, with global revenue projected to rise from USD 15.48 billion in 2025 to USD 30.21 billion by 2035. From the 2026 base, the market is projected to grow at a 6.63% CAGR through 2035. We observed that sustained sudden cardiac arrest incidence, expanding public-access defibrillation mandates, and growing remote monitoring adoption will continue underpinning demand across implantable, wearable, and external device categories through the forecast period.

What Strategic Positioning Should Defibrillator Manufacturers Pursue?

Manufacturers should prioritize lead-reliability engineering and remote monitoring integration while pursuing registry and emergency-response partnerships to secure durable clinician and public-access customer relationships. Our assessment indicates that manufacturers investing early in AI-enhanced wearable compliance features and extravascular implantable platforms will be best positioned to capture premium pricing within the defibrillators market.

How Attractive Is the Defibrillators Market for New Investment?

The defibrillators industry presents an attractive investment case, supported by a USD 13.25 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Middle East & Africa and wearable defibrillator categories. We found that investment attractiveness is highest for manufacturers combining established clinical registry evidence with connected-device capability, positioning them to serve both hospital-based implantable and public-access external defibrillator segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor high procedural cost barriers, lead-related complication risk, and reimbursement variability in emerging markets as key risks to the defibrillators market. Our analysis shows that manufacturers unable to demonstrate credible complication-reduction and clinical outcomes evidence risk losing share to competitors with differentiated lead design and registry data, particularly within North America's increasingly evidence-driven procurement environment.

What Are the Key Growth Pathways for the Defibrillators Market?

Key growth pathways include expanding remote monitoring platform capability, scaling wearable defibrillator compliance features, and deepening penetration into home care and public-access AED registry categories. NMSC's analysis indicates that manufacturers pursuing these pathways while maintaining reliability in core transvenous ICD and professional external defibrillator categories will be best positioned to capture the defibrillators market's projected growth through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Company-Level Defibrillator Unit Shipment Analysis
  • Manufacturer-level defibrillator unit shipments and installed units benchmarked by product type and end user.
  • Reveals manufacturer scale and share shifts to guide competitive positioning and channel investment.
Historical Market Growth Analysis
  • Historical revenue and unit volume analysis by product type, defibrillation technology, and end user.
  • Identifies high-growth device categories and sets a data-backed baseline for forecast and portfolio priorities.
Country-Level Trade Assessment
  • Country-wise import and export analysis for defibrillators, electrodes, and related components.
  • Highlights sourcing dependencies and import-led demand pockets to support market entry and supply chain decisions.
Regulatory Pathway and Reimbursement Assessment
  • Country-wise mapping of device approval pathways (FDA, CE/MDR, and others), classification requirements, and public AED and implantable device funding or reimbursement policies.
  • Shortens time-to-market planning and prioritizes launch geographies by approval ease and reimbursement support.
Public Access Defibrillation Opportunity Mapping
  • Country and region analysis of AED deployment mandates, public-access programs, and placement density across public venues, workplaces, and schools by buyer type and end user.
  • Pinpoints under-penetrated AED markets and institutional buyers for targeted sales and partnership strategies.
Technology Adoption and Pricing Benchmarking
  • Comparison of biphasic and monophasic technologies and ICD, external and wearable defibrillator offerings, with list pricing and tender price ranges by sales channel.
  • Supports pricing strategy and technology roadmap decisions across direct tender, distributor, and online channels.

FAQs

Consolidated Source Table

Source Name / Organization URL
Medtronic plc
ZOLL Medical Corporation
U.S. Food and Drug Administration (FDA)
U.S. Centers for Disease Control and Prevention (CDC)
Centers for Medicare & Medicaid Services (CMS)
World Health Organization (WHO)
European Commission – Medical Device Regulation (MDR)
Australia Therapeutic Goods Administration (TGA)
Saudi Food and Drug Authority (SFDA)
Brazil Agência Nacional de Vigilância Sanitária (ANVISA)
International Organization for Standardization (ISO)
Methodology Note
Market size, segment, and country-level figures presented in this report reflect the base-year, current-year, and forecast-year estimates supplied for this engagement, reconciled by NMSC through a proprietary bottom-up segmentation model incorporating company disclosures and regulatory data, as no single publicly verifiable dataset matches this report's exact market definition, scope, and forecast window. The CAGR impact estimates shown in the Growth Catalyst and Risk Assessment Matrix represent NMSC's internal scenario-model assessment of the contribution of individual drivers and restraints to forecast growth and are not independently reported industry statistics.

About the Author

Jayanta Das

Jayanta Das

Jayanta Das is Senior Analyst at Next Move Strategy Consulting, where he has spent 4.5 years covering the firm's full industry taxonomy — spanning aerospace and defense, healthcare, BFSI, energy and power, semiconductors, and beyond — rather than one specialization. His work follows NextMSC's research model, combining data mining, analytics, and secondary research to build market sizing and forecasts behind NextMSC's 2,000-plus research reports, trusted by more than 3,000 organizations globally.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖