High-Performance Fibers Market Global Industry Analysis and Forecast (2026-2035)

High-Performance Fibers Market size was USD 13.85 billion in 2025, projected to reach USD 31.48 billion by 2035, growing at a CAGR of 8.6% from 2026 to 2035. Key drivers include rising wind energy capacity additions and blade length growth, expanding automotive lightweighting and electric vehicle production, and growing aerospace production rates and composite structure adoption, with Asia-Pacific leading the market.

Download Free Sample PDF
Base Year (2025)
$13.85 Billion
Forecast (2035)
$31.48 Billion
CAGR (2026-2035)
8.6%
Top Region
Asia-Pacific

What Is the High-Performance Fibers Market Size?

The global high-performance fibers market size was valued at USD 13.85 billion in 2025 and is estimated at USD 14.98 billion in 2026, forecast to reach USD 31.48 billion by 2035, expanding at an 8.6% CAGR between 2026 and 2035. Asia-Pacific leads with approximately a 34% share, while Carbon Fiber dominates all other fiber types with approximately a 39% share.

We observed that growth is broad-based across every segmentation axis, with wind energy blade manufacturing and automotive lightweighting driving the dominant structural shifts through 2035.

High-Performance Fibers Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $13.85 Billion
2025
2026 $14.98 Billion
2026
2027 $16.27 Billion
2027
2028 $17.67 Billion
2028
2029 $19.19 Billion
2029
2030 $20.84 Billion
2030
2031 $22.63 Billion
2031
2032 $24.57 Billion
2032
2033 $26.69 Billion
2033
2034 $28.98 Billion
2034
2035 $31.48 Billion
2035

Key Takeaways

By Fiber Type: Carbon Fiber held the largest share of approximately 39% (USD 5.40 billion) in 2025; PBO Fiber is the fastest-growing sub-segment at 11.3% CAGR from 2026–2035.

By Form: Continuous Filament held the largest share of approximately 54% (USD 7.48 billion) in 2025; Continuous Filament is also the fastest-growing sub-segment at 9.3% CAGR from 2026–2035.

By Application: Aerospace and Defense held the largest share of approximately 29% (USD 4.02 billion) in 2025; Wind Energy is the fastest-growing sub-segment at 10.1% CAGR from 2026–2035.

By End-use Industry: Aerospace held the largest share of approximately 26% (USD 3.60 billion) in 2025; Electronics is the fastest-growing sub-segment at 13.6% CAGR from 2026–2035.

Dominant Region: Asia-Pacific dominated with approximately 34% revenue share (USD 4.71 billion) in 2025.

Fastest-Growing Region: Asia-Pacific is also expected to register the highest CAGR of 10.6% during 2026–2035.

Dominant Country: U.S. led with approximately USD 3.28 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 13.6% CAGR from 2026–2035.

Market Opportunity: The high-performance fibers market is expected to create an absolute dollar opportunity of USD 16.50 billion between 2026 and 2035, presenting significant investment potential across the wind energy and automotive lightweighting value chain.

According to NMSC analysis, wind turbine blade manufacturers are increasingly specifying carbon fiber spar caps over traditional glass fiber reinforcement to reduce blade weight and extend rotor length, a shift that favors carbon fiber producers with dedicated wind energy production lines over glass fiber-only suppliers as offshore wind capacity additions accelerate through 2035.

What Does the High-Performance Fibers Market Encompass?

The high-performance fibers market encompasses carbon, aramid, ultra-high molecular weight polyethylene, glass, and specialty heterocyclic fibers engineered for exceptional strength-to-weight ratios, thermal stability, and chemical resistance across aerospace, automotive, defense, and industrial applications. Our assessment indicates that the scope spans continuous filament, staple fiber, and woven fabric forms supplied to composite fabricators, protective equipment manufacturers, and original equipment manufacturers producing structural components, ballistic protection, and wind turbine blades.

Regulatory frameworks such as aviation structural certification standards shape aerospace-grade fiber qualification requirements, while ballistic protection standards increasingly influence aramid and UHMWPE fiber specifications for defense applications. We observed that technology adoption is shifting toward recycled and bio-based precursor materials for carbon fiber production, a structural change that NMSC's analysis indicates is redefining sourcing priorities across the carbonfiberin sports equipment and broader composite fabrication value chain.

Market Drivers & Dynamics

Interactive Dataset
Rising wind energy capacity additions and blade length growth driver +2.3% Global 2026–2035
Expanding automotive lightweighting and electric vehicle production driver +1.8% North America, Europe, Asia-Pacific 2026–2033
Growing aerospace production rates and composite structure adoption driver +1.5% North America, Europe 2026–2035
Rising global defense budgets and ballistic protection procurement driver +1.2% Global 2026–2034
Expanding carbon fiber production capacity across Asia-Pacific driver +1.0% Asia-Pacific 2026–2035
Growing recycled and bio-based fiber precursor development driver +0.7% Europe, North America 2026–2032
High production costs for carbon and specialty fibers restraint −1.2% Global 2026–2035
Competition from conventional glass fiber and metal alternatives restraint −0.8% Global 2026–2032
Volatile precursor and raw material pricing restraint −0.6% Global 2026–2033
Limited recycling infrastructure for end-of-life composite fibers restraint −0.4% Global 2028–2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the High-Performance Fibers Market?

Rising wind energy capacity additions and increasing blade length are the primary driver of the market. The U.S. Department of Energy continues to track sustained wind capacity growth as utilities expand renewable generation portfolios, supporting baseline demand for structural spar cap fibers across both onshore and offshore turbine installations. We observed that this renewable capacity expansion, reinforced by growing offshore wind project pipelines, continues to anchor consistent procurement of high-modulus carbon fiber grades across wind turbine blade manufacturers globally.

How Is Automotive Lightweighting Driving High-Performance Fibers Market Growth?

Expanding electric vehicle production is accelerating demand for lightweight fiber composites that offset battery pack weight while maintaining structural safety performance. Toyobo's continued development of high-modulus PBO and specialty fiber grades reflects the pace at which producers are scaling advanced fiber capacity to serve automotive structural applications. Our assessment indicates that this demand-side pressure, combined with tightening aerospace lightweight requirements, is compressing qualification timelines across global automotive fiber sourcing programs.

Growth Inhibitors

What Is Restraining High-Performance Fibers Market Expansion?

High production costs for carbon and specialty fibers restrain broader adoption, particularly in cost-sensitive applications where conventional glass fiber or metal alternatives remain economically competitive. Volatile precursor and raw material pricing further complicate fixed-price contract planning for fiber producers operating capital-intensive production lines. We found that limited recycling infrastructure for end-of-life composite fibers further slows circular economy adoption across the industry, particularly for thermoset composite applications lacking established reprocessing pathways.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Carbon Fiber 2025: $5.40 Billion | 2035: $13.54 Billion
Carbon Fiber
Aramid Fiber 2025: $3.74 Billion | 2035: $7.56 Billion
Aramid Fiber
UHMWPE Fiber 2025: $1.94 Billion | 2035: $4.72 Billion
UHMWPE Fiber
Glass Fiber 2025: $1.52 Billion | 2035: $2.52 Billion
Glass Fiber
PBO Fiber 2025: $0.55 Billion | 2035: $1.57 Billion
PBO Fiber
PBI Fiber 2025: $0.28 Billion | 2035: $0.63 Billion
PBI Fiber
Other High-Performance Fibers 2025: $0.42 Billion | 2035: $0.94 Billion
Other High-P
Carbon Fiber $5.40 Billion $13.54 Billion 9.8%
Aramid Fiber $3.74 Billion $7.56 Billion 7.2%
UHMWPE Fiber $1.94 Billion $4.72 Billion 9.4%
Glass Fiber $1.52 Billion $2.52 Billion 4.8%
PBO Fiber $0.55 Billion $1.57 Billion 11.3%
PBI Fiber $0.28 Billion $0.63 Billion 8.6%
Other High-Performance Fibers $0.42 Billion $0.94 Billion 8.6%

Which Fiber Type Segment Dominates the High-Performance Fibers Market?

Carbon Fiber dominated the high-performance fibers market, valued at USD 5.40 billion in 2025, driven by its exceptional strength-to-weight ratio and increasing adoption in aerospace, automotive, and wind-energy structural applications. The segment is projected to grow at a 9.8% CAGR from 2026 to 2035, supported by expanding production capacity and rising demand for carbon fiber in wind turbine blades and lightweight electric vehicle components.

2025 (USD Billion)
2035 (USD Billion)
Continuous f
Staple fiber
Woven fabric
Chopped fibe
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Continuous filament $10.0 USD Billion $40.0 USD Billion 17.0%
Staple fiber $17.1 USD Billion $51.1 USD Billion 11.0%
Woven fabric $24.2 USD Billion $62.2 USD Billion 9.0%
Chopped fiber $31.3 USD Billion $73.3 USD Billion 15.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Form.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Aerospace an
Automotive
Wind energy
Sporting goo
Industrial a
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Aerospace and defense $10.0 USD Billion $40.0 USD Billion 18.0%
Automotive $17.1 USD Billion $51.1 USD Billion 16.0%
Wind energy $24.2 USD Billion $62.2 USD Billion 22.0%
Sporting goods $31.3 USD Billion $73.3 USD Billion 12.0%
Industrial and protective equipment $38.4 USD Billion $84.4 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data

Which Application Segment Leads High-Performance Fibers Market Demand?

Aerospace and Defense remained the leading application within the market, valued at USD 4.02 billion in 2025 on sustained demand for structural carbon fiber composites and aramid-based ballistic protection across commercial and military platforms. Based on research conducted by NMSC, we found that Wind Energy is the fastest-growing application, registering a 10.1% CAGR from 2026 to 2035, as turbine manufacturers scale carbon fiber spar cap adoption to support longer blade designs.

2025 (USD Billion)
2035 (USD Billion)
Aerospace
Automotive
Defense
Energy
Industrial
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Aerospace $10.0 USD Billion $40.0 USD Billion 20.0%
Automotive $17.1 USD Billion $51.1 USD Billion 18.0%
Defense $24.2 USD Billion $62.2 USD Billion 12.0%
Energy $31.3 USD Billion $73.3 USD Billion 22.0%
Industrial $38.4 USD Billion $84.4 USD Billion 25.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End-use Industry.

Unlock Full Data

Which End-use Industry Segment Is Most Significant in the Market?

Aerospace remained the dominant end-use industry across the market, reaching USD 3.60 billion in 2025 as commercial and military aircraft manufacturers represent the largest concentration of structural carbon fiber and aramid composite consumption globally. Our analysis shows that Electronics is the fastest-growing end-use industry at a 13.6% CAGR from 2026 to 2035, reflecting expanding adoption of high-performance fibers in electromagnetic shielding and thermally conductive component applications.

PESTEL Analysis of the High-Performance Fibers Industry

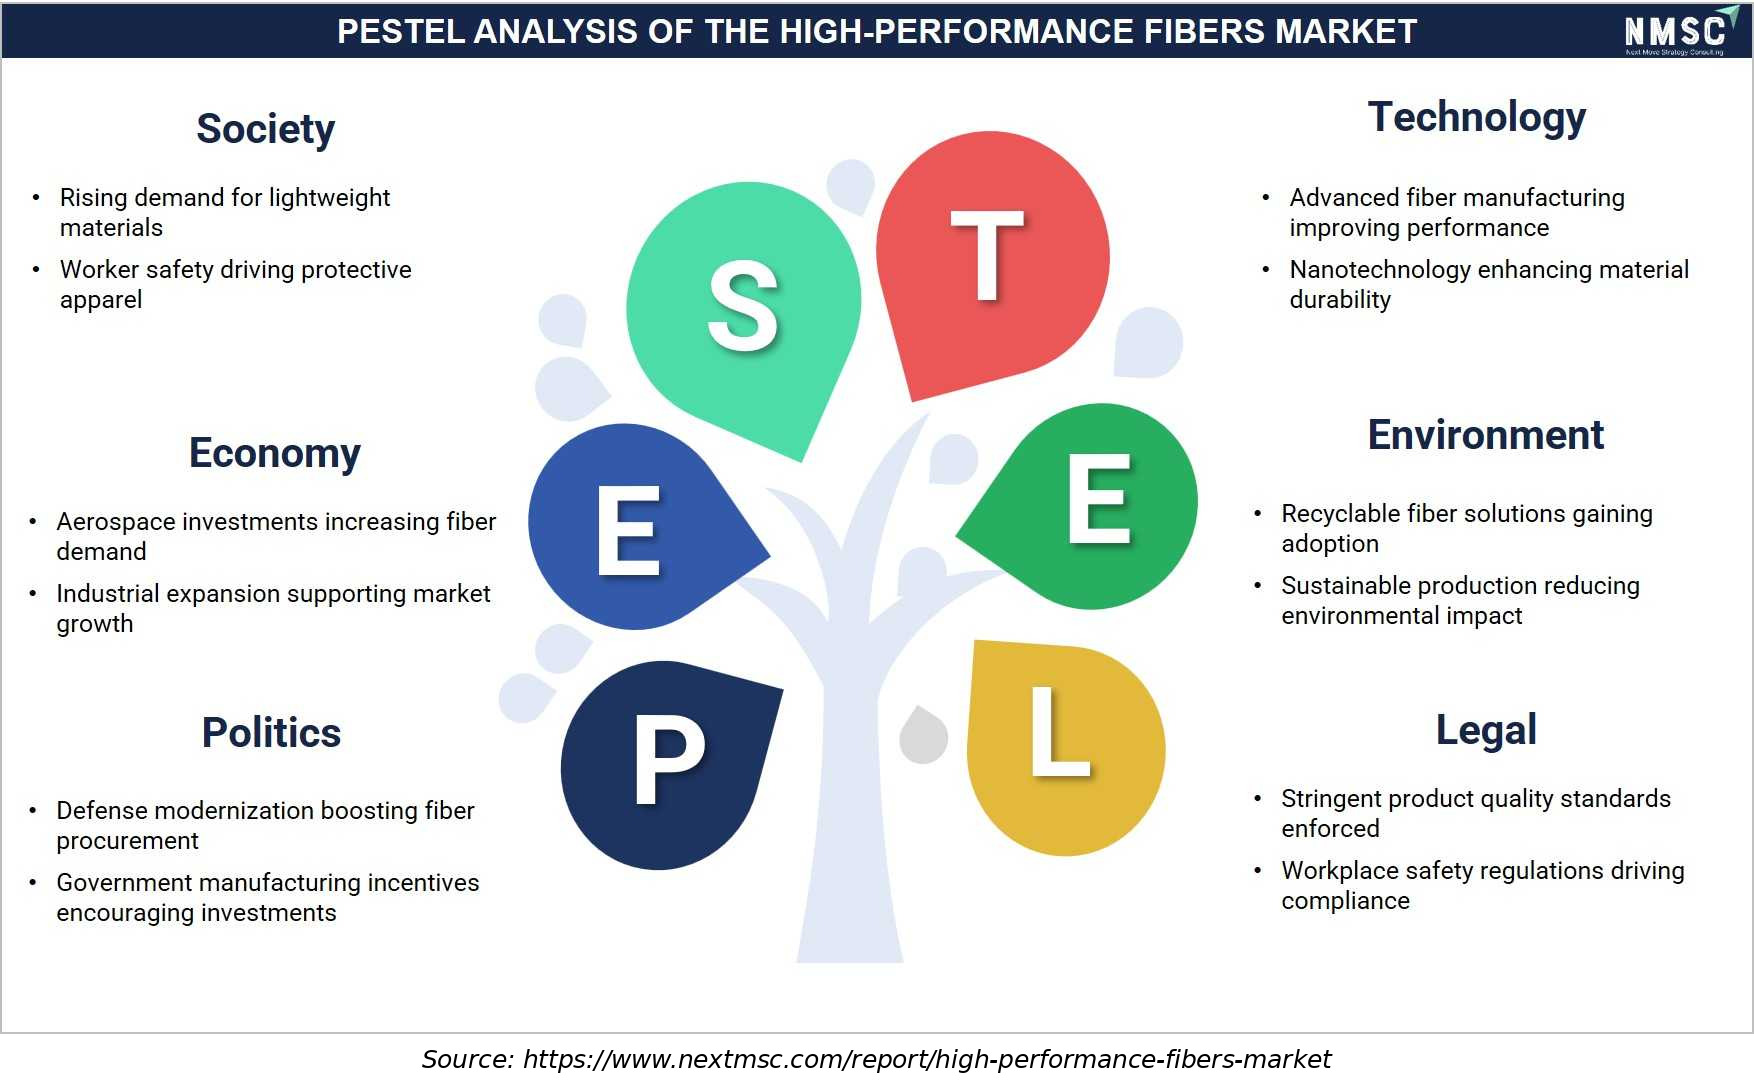
PESTEL Analysis of the High-Performance Fibers Industry
The above infographic presents a PESTEL analysis of the high-performance fibers market, wherein defense modernization and manufacturing incentives are driving procurement and investment. Rising demand for lightweight materials and worker safety is shaping social adoption, while advanced manufacturing technologies and nanotechnology are improving fiber performance and durability. Aerospace investments and industrial expansion are fueling economic growth, and sustainable fiber solutions are reducing environmental impact. Looking ahead, we observed that regulatory alignment and continued innovation will remain key to meeting evolving performance and sustainability standards across the industry.

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the high-performance fibers market over the 2026–2035 forecast period.

How Can Producers Capture Offshore Wind Blade Manufacturing Demand?

Offshore wind blade manufacturing represents a whitespace opportunity for fiber producers developing high-modulus carbon fiber grades optimized for extreme-length spar cap applications. Producers that commercialize dedicated wind energy fiber production lines stand to capture recurring procurement as offshore wind project pipelines expand across North America, Europe, and Asia-Pacific through 2035.

Where Does Recycled Carbon Fiber Create New Market Demand?

Recycled carbon fiber represents an underpenetrated opportunity for producers developing cost-competitive, lower-carbon-footprint fiber grades for non-aerospace structural applications. Companies that qualify recycled fiber formulations for glassfiberreinforced concrete-adjacent construction and automotive applications can secure long-term supply agreements with manufacturers seeking sustainability-differentiated material sourcing.

How Can Electronics-Grade Fiber Formulations Expand Recurring Revenue?

Electronics-grade fiber formulations create a sustained opportunity for producers seeking premium pricing in electromagnetic shielding and thermal management applications. Early movers that develop specialty carbon and aramid fiber grades for consumer electronics and telecommunications infrastructure can differentiate with manufacturers pursuing lightweight, high-performance material solutions beyond traditional aerospace and industrial applications.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the high-performance fibers market features a moderately consolidated competitive landscape, with integrated Japanese and North American fiber majors competing alongside expanding Korean and Chinese producers on production scale, precursor technology, and application development support.

Dimension Description
Market Structure Moderately consolidated; the top companies profiled in this report collectively account for a majority of global market revenue, given the capital-intensive nature of fiber production infrastructure.
Innovation Focus Recycled and bio-based fiber precursors, wind energy-grade carbon fiber, and electronics-grade specialty fiber formulations dominate current innovation pipelines across leading producers.
M&A Activity Selective capability acquisitions, exemplified by Avient Corporation's acquisition of DSM Protective Materials, which brought Dyneema UHMWPE fiber technology into its advanced materials portfolio.

How Do Companies Compete in the High-Performance Fibers Market?

Companies compete primarily on production scale, precursor technology, and application development support across the industry. Integrated majors such as Toray Industries, Inc. and Teijin Limited leverage proprietary precursor chemistry and decades of aerospace and automotive qualification experience to serve global composite fabricators, while Korean producers such as Kolon Industries, Inc. and Hyosung Advanced Materials Corporation compete through cost-competitive aramid production scale and expanding export capacity.

Which Competitive Archetypes Dominate the High-Performance Fibers Market?

Two archetypes dominate the market: integrated fiber technology majors offering proprietary precursor chemistry and application engineering support, and regional producers competing on production scale and cost efficiency. Toray Industries, Inc. and DuPont de Nemours, Inc. exemplify the technology-integrated archetype through branded carbon fiber and aramid product lines, while Yantai Tayho Advanced Materials Co., Ltd. and Guangwei Composites Co., Ltd. exemplify the scale-integrated archetype through large domestic production capacity serving China's expanding fiber demand.

How Are Companies Differentiating Through Innovation in High-Performance Fibers?

Innovation and differentiation strategy increasingly center on recycled precursor development and application-specific grade engineering for wind energy and electronics applications. Teijin Frontier's recycled polyester fabric development and Toray's continued expansion of wind energy-grade carbon fiber capacity both illustrate how producers extend platform relevance through sustainability credentials and application-specific performance. Our analysis shows that producers unable to demonstrate credible recycled content and application qualification risk losing specification wins with major aerospace and automotive customers.

What M&A and Expansion Activity Is Shaping the Market?

Capacity expansion and technology acquisition activity continue to reshape competitive positioning within the industry. Avient Corporation's acquisition of DSM Protective Materials strengthened its UHMWPE fiber technology position, while Toray's continued expansion of dedicated wind energy carbon fiber production capacity illustrates how producers pursue application-specific capacity investment to capture accelerating renewable energy and automotive demand without relying solely on traditional aerospace end markets.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping precursor innovation, production capacity expansion, and application development strategy within the global high-performance fibers market.

Toray Industries, Inc. Teijin Limited DuPont de Nemours, Inc. Honeywell International Inc. Avient Corporation Kolon Industries, Inc. Hyosung Advanced Materials Corporation Hexcel Corporation SGL Carbon SE Mitsubishi Chemical Group Corporation Solvay S.A. Toyobo Co., Ltd. Yantai Tayho Advanced Materials Co., Ltd. China Jushi Co., Ltd. Kureha Corporation PBI Performance Products, Inc. Kuraray Co., Ltd. Formosa Plastics Corporation China National Bluestar (Group) Co., Ltd. Guangwei Composites Co., Ltd.

Latest Developments

We found that recent activity within the high-performance fibers market is concentrated on recycled fiber development, wind energy capacity expansion, and portfolio innovation, reflecting the industry's response to accelerating sustainability and renewable energy demand.

Date Event
April 2026 Toray Composite Materials America entered a five-year carbon-fiber supply agreement with Syensqo, effective from January 2026. The companies strengthened supply stability and resilience for aircraft, space, and defense applications as next-generation aircraft development and aerospace demand continue driving requirements for high-performance carbon fiber.
March 2026 . Hexcel announced a new portfolio of lightweight composite technologies, including HexTow IM11 R carbon fiber, HexPly M51 rapid-cure prepreg, Towpreg thermoset and HexShape woven net-shape textiles. The portfolio targets aerospace, defense, and industrial applications requiring lightweight, high-performance materials and scalable processing.
December 2025 Mitsubishi Chemical decided to enhance high-performance carbon-fiber production at its Tokai Plant in Japan and Sacramento Plant in the U.S. The phased expansion, planned from 2025 through 2027, is expected to approximately double current production capacity, targeting aerospace, sports and leisure, hypercar and other high-end applications.
March 2025 Teijin Carbon launched Tenax IMS65 E23 36K 1630tex, its first 36K carbon fiber. The product delivers 5,800 MPa tensile strength and 280 GPa tensile modulus, while supporting high-speed filament winding and prepreg production.

Expert Insights

Philip Schell

executive VP | Zoltek

"One of the appealing facets about carbon fiber spar caps is that it opens the door to design not only lighter, but thinner blades with improved aerodynamic performance."

Analyst Interpretation

The insight highlights lightweighting and aerodynamic efficiency as important drivers for high-performance carbon-fiber adoption in renewable-energy applications. NMSC's analysis indicates that the growing demand for larger and more efficient wind turbines is creating opportunities for high-strength, lightweight fibers that can support longer and thinner blade designs. This is expanding the role of high-performance fibers beyond aerospace and automotive applications into renewable-energy infrastructure.

Investment Opportunities

What Capital Inflows Are Fueling High-Performance Fibers Market Development?

Capital investment is flowing into carbon fiber production capacity expansion and recycled precursor development, exemplified by continued producer investment in dedicated wind energy fiber production lines. Our findings suggest that this capital inflow is validating high-performance fiber production as a durable, margin-accretive materials segment rather than a mature commodity extension, attracting continued investor interest in application-specific capacity expansion.

How Is Infrastructure Investment Shaping High-Performance Fibers Market Expansion?

Production capacity investment, including expanded carbon fiber lines serving wind energy and automotive customers, is shaping how producers scale sustainable fiber supply globally. We observed that this infrastructure investment reflects sustained commitment to reducing feedstock carbon intensity while maintaining the performance characteristics required for premium aerospace, automotive, and energy applications.

What ESG Considerations Influence Market Investment?

Environmental, social, and governance considerations increasingly influence fiber investment as producers and customers prioritize recycled content and reduced carbon footprint materials over virgin petroleum-based alternatives. Our analysis shows that recycled fiber development and lightweight structural applications that reduce vehicle and aircraft fuel consumption align with emissions-reduction goals, strengthening the investment case for producers with demonstrated sustainability development track records.

Supply Chain Structure of the High-Performance Fibers Industry

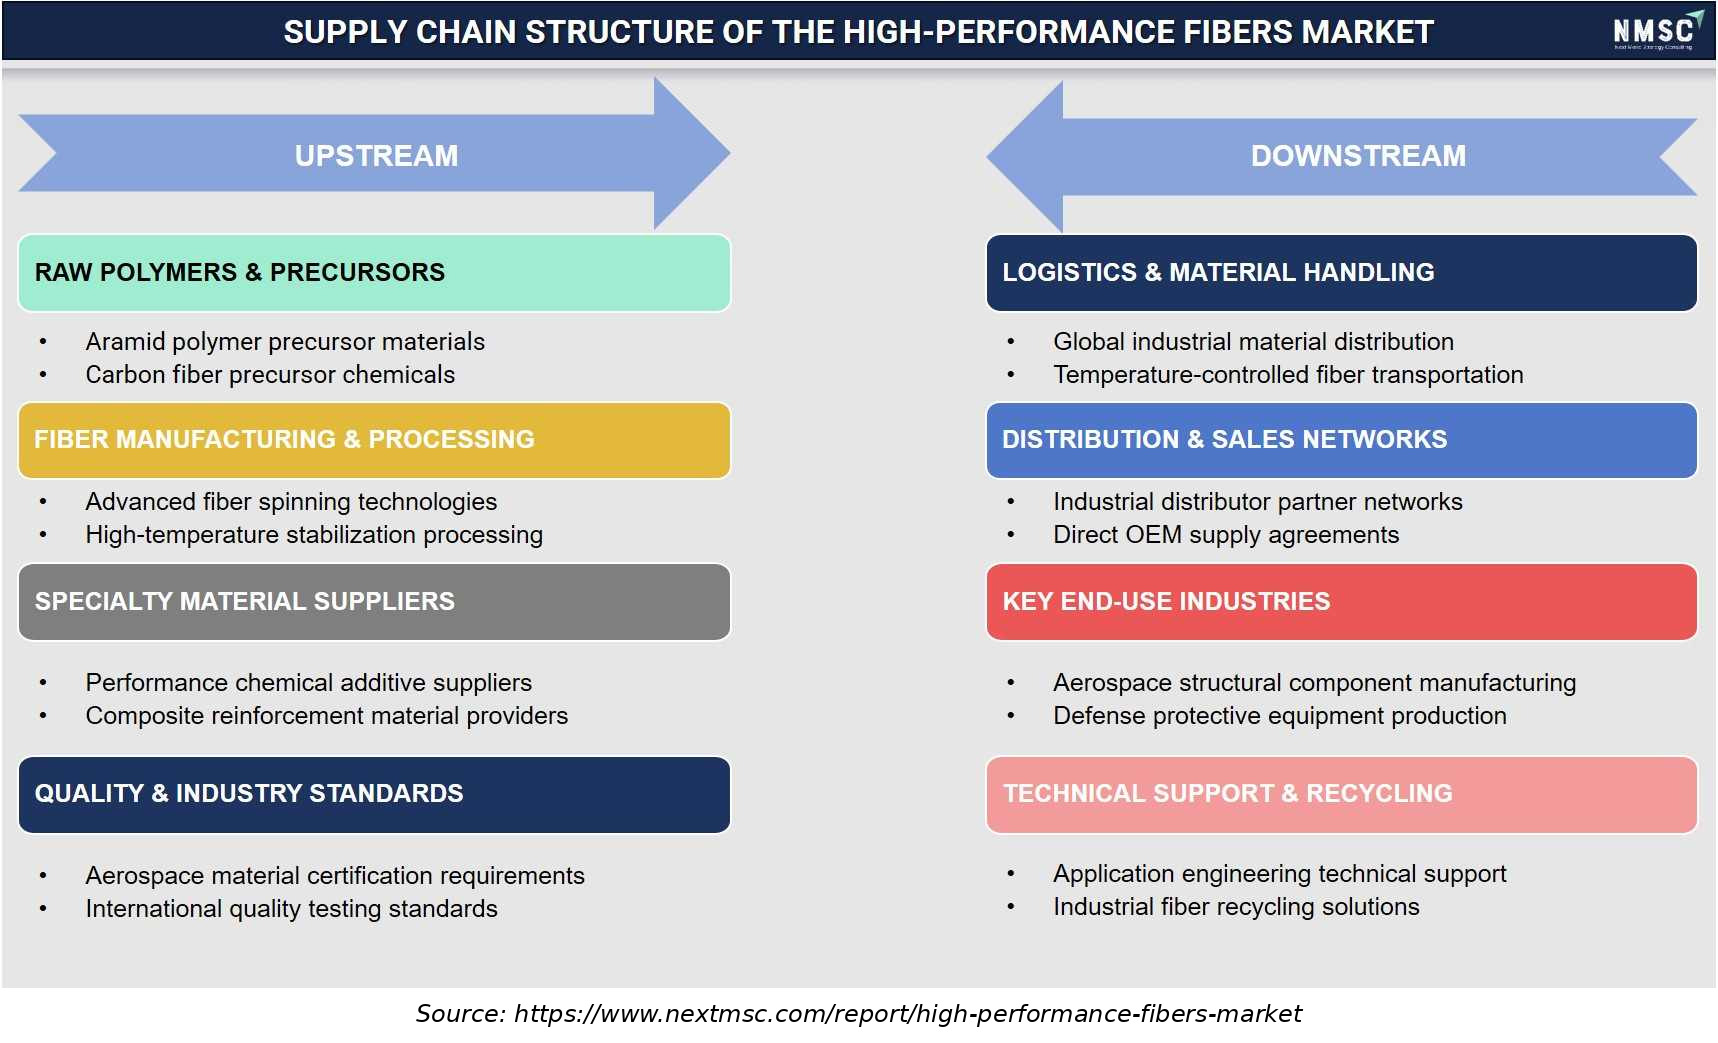
Supply Chain Structure of the High-Performance Fibers Industry
The above infographic presents the supply chain structure of the high-performance fibers market, segmented into upstream and downstream activities. Aramid and carbon fiber precursors are processed through advanced spinning and high-temperature stabilization, with chemical additives and composite materials supporting production. Compliance with aerospace and international quality standards ensures material reliability. Downstream, global logistics and distribution networks serve aerospace and defense sectors through OEM and industrial channels. Looking ahead, we observed that application engineering support and recycling solutions remain essential for optimizing performance and sustainability across the industry.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders?

This report equips materials and manufacturing industry leaders with segmented revenue forecasts, application adoption trends, and competitive benchmarking needed to prioritize fiber sourcing and product development across end-use segments. Our findings suggest that leaders can use the segmentation analysis and regional outlook to align procurement and product roadmaps with the fastest-growing fiber type, application, and end-use segments identified in this report.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts gain a data-driven view of market sizing, CAGR trajectories, and company-level competitive positioning to evaluate capital allocation across the high-performance fibers value chain. We found that the investment opportunities and competitive landscape sections provide the forecast granularity needed to assess producer capacity expansion and technology acquisition opportunities.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams benefit from detailed segmentation across fiber type, application, and end-use axes that clarify where precursor and formulation development investment will generate the strongest returns. Our assessment indicates that the growth opportunities and emerging trends sections help product teams prioritize wind energy and electronics-grade fiber roadmaps ahead of competitors.

Key Market Segments Evaluated

By Fiber Type

  • Carbon fiber
  • Aramid fiber
  • UHMWPE fiber
  • Glass fiber
  • PBO fiber
  • PBI fiber
  • Other high-performance fibers

By Form

  • Continuous filament
  • Staple fiber
  • Woven fabric
  • Chopped fiber

By Application

  • Aerospace and defense
  • Automotive
  • Wind energy
  • Sporting goods
  • Industrial and protective equipment
  • Marine
  • Electronics

By End-use Industry

  • Aerospace
  • Automotive
  • Defense
  • Energy
  • Industrial
  • Sports and leisure
  • Electronics

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook remains strongly positive, with the market projected to expand from USD 14.98 billion in 2026 to USD 31.48 billion by 2035 at an 8.6% CAGR. We observed that sustained wind energy capacity expansion and automotive lightweighting demand provide durable, structural tailwinds that extend well beyond the current forecast window, supporting continued producer investment across carbon fiber, aramid, and specialty fiber segments.

What Strategic Positioning Should Suppliers Pursue?

Suppliers should prioritize integrated precursor technology and application engineering capability that reduce customer qualification complexity across aerospace, automotive, and energy applications. Our assessment indicates that producers combining proven fiber performance with credible recycled content development will be best positioned to win recurring supply contracts, particularly as customers consolidate sourcing relationships to simplify long-term sustainability reporting.

How Attractive Is the High-Performance Fibers Market for New Investment?

The high-performance fibers industry presents an attractive investment case, supported by a USD 16.50 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and wind energy application categories. We found that investment attractiveness is highest for producers combining carbon fiber capacity depth with application-specific engineering support, positioning them to serve both established aerospace customers and emerging wind energy and electronics programs simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor precursor price volatility, competition from conventional materials, and limited recycling infrastructure as key risks to the high-performance fibers market. Our analysis shows that producers unable to demonstrate consistent quality and credible sustainability development risk losing specification wins, particularly as aerospace and automotive customers increasingly require recycled content disclosure across their supply chains.

What Are the Key Growth Pathways for the High-Performance Fibers Market?

Key growth pathways include expanding wind energy-grade carbon fiber production, scaling recycled and bio-based precursor development, and deepening penetration into electronics and automotive structural applications. NMSC's analysis indicates that producers pursuing these pathways while maintaining cost competitiveness in core aerospace and defense categories will be best positioned to capture the high-performance fibers market's projected growth through 2035.

FAQs

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Henri Knyphausen

HENRI KNYPHAUSEN

Partner at Singulier [Ex-BCG]

Singulier

I recently engaged NEXTMSC.com for a commercial due diligence project within the intralogistics sector, and I am pleased to provide a reference based on my experience. In utilizing NEXTMSC.com's services, I found their report to offer valuable insights into market dynamics and key industry players. The initial report provided a solid foundation for our analysis. However, as we were investigating a smaller target in the market, and I had specific customization requests requiring additional research. These requests included detailed information on product portfolios of various players and sub-market sizes, both inclusive and exclusive of certain product categories. NEXTMSC.com demonstrated commendable responsiveness and agility in accommodating these customization requests. Within a timeframe of 1-2 weeks, they delivered a revised report that met our specific needs. Furthermore, they were receptive to my follow-up inquiries, ensuring clarity and understanding of the data provided. The final deliverable significantly contributed to our due diligence efforts. One of NEXTMSC.com's notable strengths lies in their qualitative research capabilities. However, for future engagements, I would recommend the inclusion of a quantified market model in Excel format. Such a model would offer the ability to conduct in-depth analyses and explore various market segments, including country-specific data and subcomponent breakdowns. Based on my positive experience, I would not hesitate to work with NEXTMSC.com again. Their responsiveness, willingness to accommodate customization requests, and commitment to delivering actionable insights make them a reliable partner for commercial research projects.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖