Ibrutinib Market

Ibrutinib market size was USD 3.60 billion in 2025, projected to reach USD 8.70 billion by 2035, growing at a 9.2% CAGR through 2026–2035, per this report.

Download Free Sample PDF
Base Year (2025)
$3.60 Billion
Forecast (2035)
$8.70 Billion
CAGR (2026-2035)
9.2%
Top Region
North America

What Is the Ibrutinib Market Size?

The global ibrutinib market size was valued at USD 3.60 billion in 2025 and is estimated at USD 3.95 billion in 2026, forecast to reach USD 8.70 billion by 2035, expanding at a 9.2% CAGR between 2026 and 2035. North America leads with approximately 46% share, while Capsules dominate all other dosage forms with approximately 65% share.

We observed that growth is broad-based across every segmentation axis, with tablet formulations and generic market entry driving the most pronounced structural shifts through 2035.

Ibrutinib Market Revenue Forecast

Values in USD Billion

2025 $3.60 Billion
2025
2026 $3.95 Billion
2026
2027 $4.31 Billion
2027
2028 $4.71 Billion
2028
2029 $5.14 Billion
2029
2030 $5.62 Billion
2030
2031 $6.13 Billion
2031
2032 $6.70 Billion
2032
2033 $7.31 Billion
2033
2034 $7.99 Billion
2034
2035 $8.70 Billion
2035

Key Takeaways

By Dosage Form: Capsules held the largest share of approximately 65% (USD 2,340 million) in 2025; Tablets is the fastest-growing sub-segment at 13.6% CAGR from 2026–2035.

By Distribution Channel: Hospital held the largest share in 2025, while online is the fastest-growing sub-segment during the forecast period (2026–2035).

By Applications: Chronic Lymphocytic Leukemia (CLL) held the largest share of approximately 58% (USD 2,088 million) in 2025; Waldenström’s Macroglobulinemia (WM) is the fastest-growing sub-segment at 13.1% CAGR from 2026–2035.

By End-User: Hospitals held the largest share of approximately 42% (USD 1,512 million) in 2025; Ambulatory Surgical Centers is the fastest-growing sub-segment at 12.8% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 46% revenue share (USD 1,656 million) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 11.9% during 2026–2035.

Dominant Country: The U.S. led with approximately USD 1,457 million in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 13.6% CAGR from 2026–2035.

Market Opportunity: The ibrutinib market is expected to create an absolute dollar opportunity of USD 4.75 billion between 2026 and 2035, presenting significant investment potential across generic tablet manufacturing, online pharmacy distribution, and Waldenström’s macroglobulinemia treatment expansion.

According to Next Move Strategy Consulting analysis, generic manufacturers securing early tentative FDA approvals ahead of the branded product's primary patent expiration are positioning themselves to capture first-mover share as the ibrutinib market transitions toward multi-source competition through 2035.

What Does the Ibrutinib Market Encompass?

The ibrutinib market encompasses hard and soft gelatin capsules, immediate release tablets, and extended release tablets containing the Bruton's tyrosine kinase inhibitor ibrutinib, distributed through hospital, retail, and online pharmacy channels for chronic lymphocytic leukemia, mantle cell lymphoma, Waldenström's macroglobulinemia, and other B-cell malignancy indications. We observed that the scope spans hospitals, clinics, specialty centers, and ambulatory surgical centers administering both the originator branded product and an expanding base of generic formulations. The category has evolved from a single-source branded oncology therapy into a market approaching multi-source generic competition as the compound's primary patents near expiration.
Regulatory frameworks such as the U.S. Food and Drug Administration's Abbreviated New Drug Application pathway and tentative approval process shape the timing and structure of generic market entry. Our assessment indicates that technology adoption is shifting toward tablet formulations that offer manufacturing and dosing advantages over the originator's capsule presentation. Next Move Strategy Consulting's analysis indicates that this structural shift, combined with the primary U.S. patent's scheduled December 2026 expiration, is redefining competitive dynamics across the ibrutinib market.

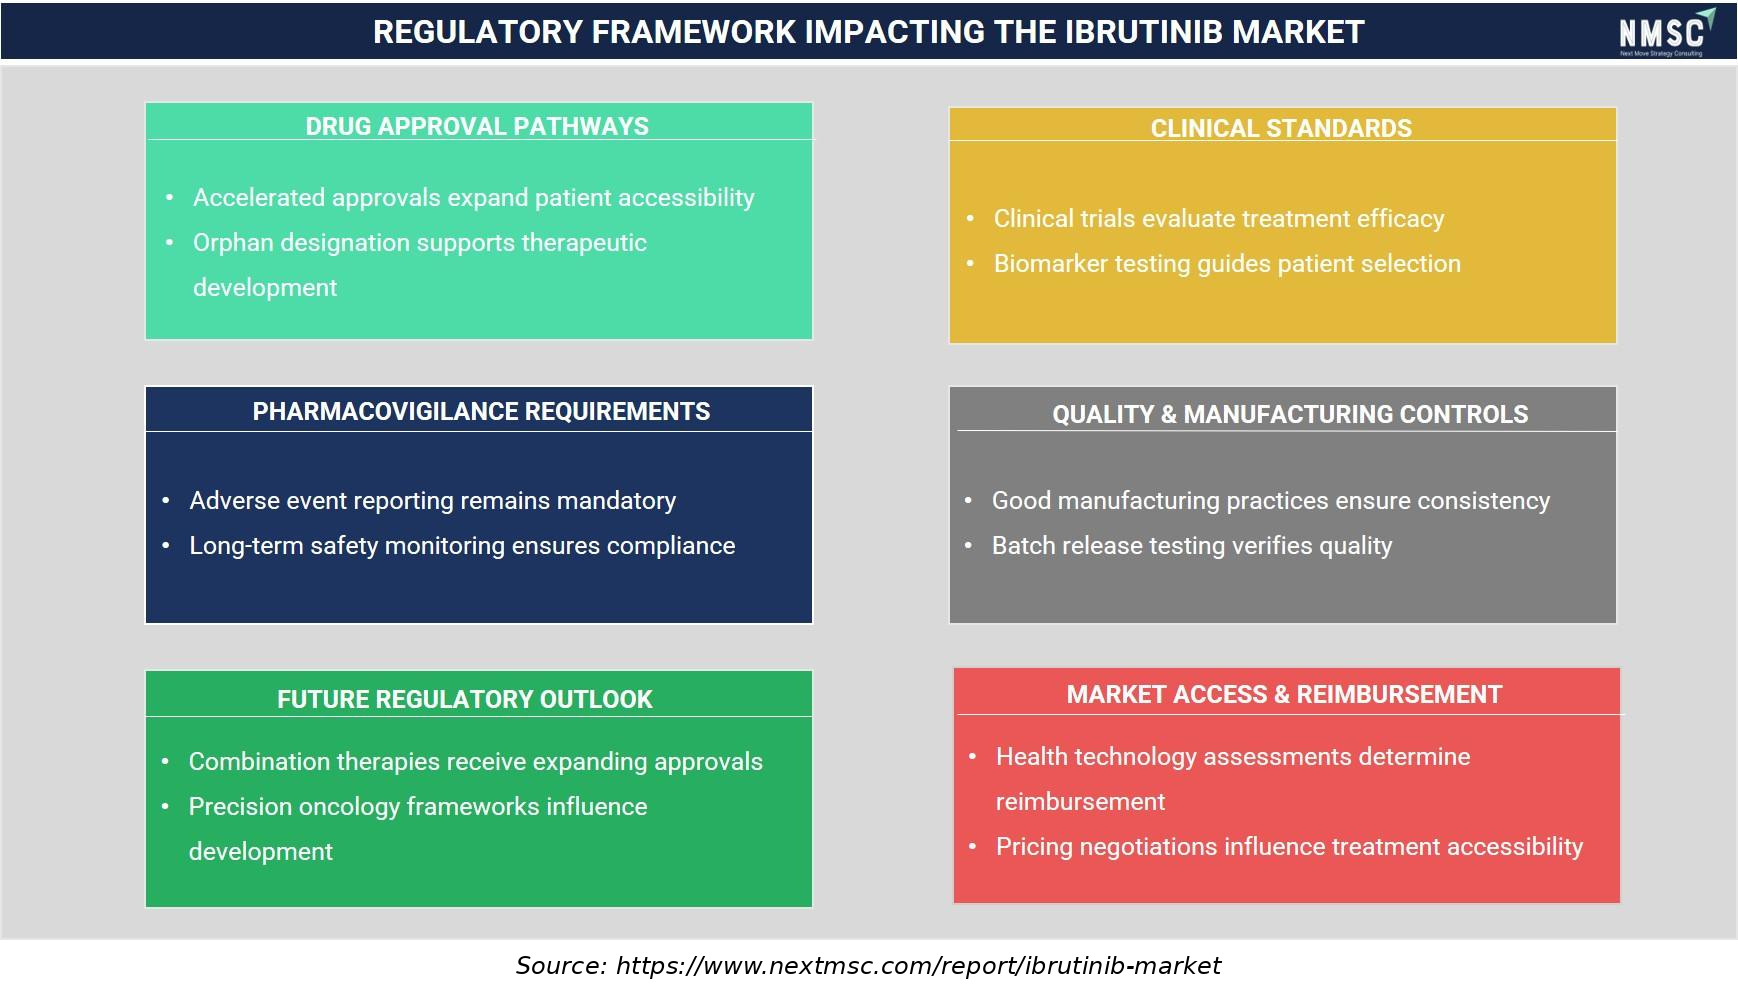
REGULATORY FRAMEWORK IMPACTING THE IBRUTINIB MARKET

The regulatory framework governing the Ibrutinib Market encompasses drug approval pathways, clinical trial standards, pharmacovigilance requirements, manufacturing quality controls, and reimbursement policies. Regulatory agencies such as the FDA and EMA require robust evidence of safety, efficacy, and manufacturing compliance before approval. Ongoing post-marketing surveillance, Good Manufacturing Practice (GMP) standards, and health technology assessments influence market access, pricing, reimbursement decisions, and the adoption of branded and generic ibrutinib therapies worldwide.

Market Drivers & Dynamics

Interactive Dataset
Rising global incidence of chronic lymphocytic leukemia and related B-cell malignancies driver +3.1% Global 2026–2035
Generic market entry expanding patient access following patent expiration driver +2.6% North America, Europe 2026–2032
Tablet formulation adoption improving manufacturing scalability driver +1.4% Global 2026–2032
Expanding Asia-Pacific generic manufacturing and treatment access driver +1.8% Asia-Pacific 2026–2035
Growing online pharmacy distribution for oral oncology therapies driver +1.1% Global 2026–2032
Competition from newer, more selective BTK inhibitors restraint −2.0% Global 2026–2032
Settlement-delayed generic entry in certain jurisdictions restraint −1.2% North America 2026–2030
High cost of originator branded product limiting access in price-sensitive markets restraint −0.8% Asia-Pacific, Latin America, MEA 2026–2030
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Ibrutinib Market?

Rising global incidence of chronic lymphocytic leukemia and related B-cell malignancies remains the primary driver of the market. AbbVie Inc.'s official regulatory disclosures confirm that Imbruvica remains indicated for chronic lymphocytic leukemia, small lymphocytic lymphoma, and Waldenström’s macroglobulinemia, among the most common adult leukemia and lymphoma subtypes in Western populations. We observed that this sustained disease burden continues to support demand across both branded and emerging generic ibrutinib products.

How Is Generic Market Entry Driving Market Growth?

Generic market entry is driving growth by expanding patient access to lower-cost ibrutinib therapy as the compound's primary U.S. patents approach their December 2026 expiration. The FDA has already granted tentative approval to Zydus Lifesciences Limited for generic ibrutinib tablets across three dosage strengths, according to regulatory disclosures reviewed by industry publications. Our assessment indicates that this tentative approval pathway is positioning multiple manufacturers to launch promptly once remaining regulatory and legal barriers clear.

Growth Inhibitors

What Is Restraining Ibrutinib Market Expansion?

Competition from newer, more selective Bruton's tyrosine kinase inhibitors restrains ibrutinib's continued market expansion. Industry-derived estimates indicate that oncology prescribing patterns have gradually shifted toward alternative BTK inhibitors offering improved cardiovascular tolerability profiles in certain patient populations. We found that settlement-delayed generic entry in some jurisdictions further compounds this restraint, as confidential licensing arrangements between originators and generic challengers can postpone multi-source competition beyond the nominal patent expiration date.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Capsules 2025: $2,340.00 Billion | 2035: $4,176.00 Billion
Capsules
Tablets 2025: $1,260.00 Billion | 2035: $4,524.00 Billion
Tablets
Capsules $2,340.00 Billion $4,176.00 Billion 6.0%
Tablets $1,260.00 Billion $4,524.00 Billion 13.6%

Which Dosage Form Segment Dominates the Ibrutinib Market?

Capsules led the market with USD 2,340 million in 2025, reflecting the originator product's established hard gelatin capsule formulation and its long-standing prescribing base. We observed that Tablets is the fastest-growing dosage form, expanding at a 13.6% CAGR from 2026 to 2035, as generic manufacturers including Zydus Lifesciences pursue tablet formulations that offer manufacturing scalability and dosing flexibility advantages over capsule presentations.

2025 (USD Billion)
2035 (USD Billion)
Hospital
Retail
Online
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Hospital $10.0 USD Billion $40.0 USD Billion 25.0%
Retail $17.1 USD Billion $51.1 USD Billion 11.0%
Online $24.2 USD Billion $62.2 USD Billion 25.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Distribution Channel.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Chronic Lymp
Mantle Cell
Waldenström'
Others
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Chronic Lymphocytic Leukemia (CLL) $10.0 USD Billion $40.0 USD Billion 27.0%
Mantle Cell Lymphoma (MCL) $17.1 USD Billion $51.1 USD Billion 9.0%
Waldenström's Macroglobulinemia (WM) $24.2 USD Billion $62.2 USD Billion 19.0%
Others $31.3 USD Billion $73.3 USD Billion 17.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Applications.

Unlock Full Data

Which Application Segment Leads Market Demand?

Chronic Lymphocytic Leukemia (CLL) remained the leading application, valued at USD 2,088 million in 2025, reflecting its status as the most common adult leukemia subtype and ibrutinib's longest-standing approved indication. Our findings suggest that Waldenström's Macroglobulinemia (WM) is the fastest-growing application, registering a 13.1% CAGR from 2026 to 2035, as growing physician familiarity with ibrutinib therapy for this rarer B-cell malignancy expands diagnosed patient treatment rates.

2025 (USD Billion)
2035 (USD Billion)
Hospitals
Clinics
Specialty Ce
Ambulatory S
Others
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Hospitals $10.0 USD Billion $40.0 USD Billion 14.0%
Clinics $17.1 USD Billion $51.1 USD Billion 24.0%
Specialty Centers $24.2 USD Billion $62.2 USD Billion 22.0%
Ambulatory Surgical Centers $31.3 USD Billion $73.3 USD Billion 12.0%
Others $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End-User.

Unlock Full Data

Which End-User Segment Dominates the Ibrutinib Market?

Hospitals remained the leading end-user, reaching USD 1,512 million in 2025, as complex oncology patients continue to receive initial ibrutinib prescriptions and monitoring within hospital-based hematology-oncology departments. Based on research conducted by Next Move Strategy Consulting, we found that Ambulatory Surgical Centers is the fastest-growing end-user, expanding at a 12.8% CAGR from 2026 to 2035, as outpatient care models increasingly manage stable, long-term oral oncology therapy outside traditional hospital settings.

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the ibrutinib market over the 2026–2035 forecast period.

How Can Generic Tablet Manufacturing Unlock Value Ahead of Patent Expiration?

Generic tablet manufacturing presents a whitespace opportunity for companies securing tentative FDA approval ahead of the compound's December 2026 primary patent expiration. Manufacturers that complete bioequivalence studies and regulatory filings early stand to capture first-mover share as multi-source competition begins, positioning tablet-format generics to displace capsule-based alternatives given their manufacturing cost advantages.

Where Does Online Pharmacy Distribution Create New Demand?

Online pharmacy distribution creates a significant opportunity for companies serving patients on long-term oral oncology therapy who prefer home delivery over recurring retail pharmacy visits. Distributors that establish specialty oncology online pharmacy capability can capture recurring prescription refill volume as patients managing chronic lymphocytic leukemia and related conditions increasingly favor convenient, predictable medication access.

How Can Asia-Pacific Manufacturing Scale Benefit Generic Entrants?

Asia-Pacific manufacturing scale creates an opportunity for generic entrants seeking cost-competitive production capacity ahead of global patent expiration. Companies that establish API and finished dose manufacturing in India and other regional hubs can capture export demand from price-sensitive markets while simultaneously supplying domestic treatment access as regional diagnosis rates for B-cell malignancies continue to rise.

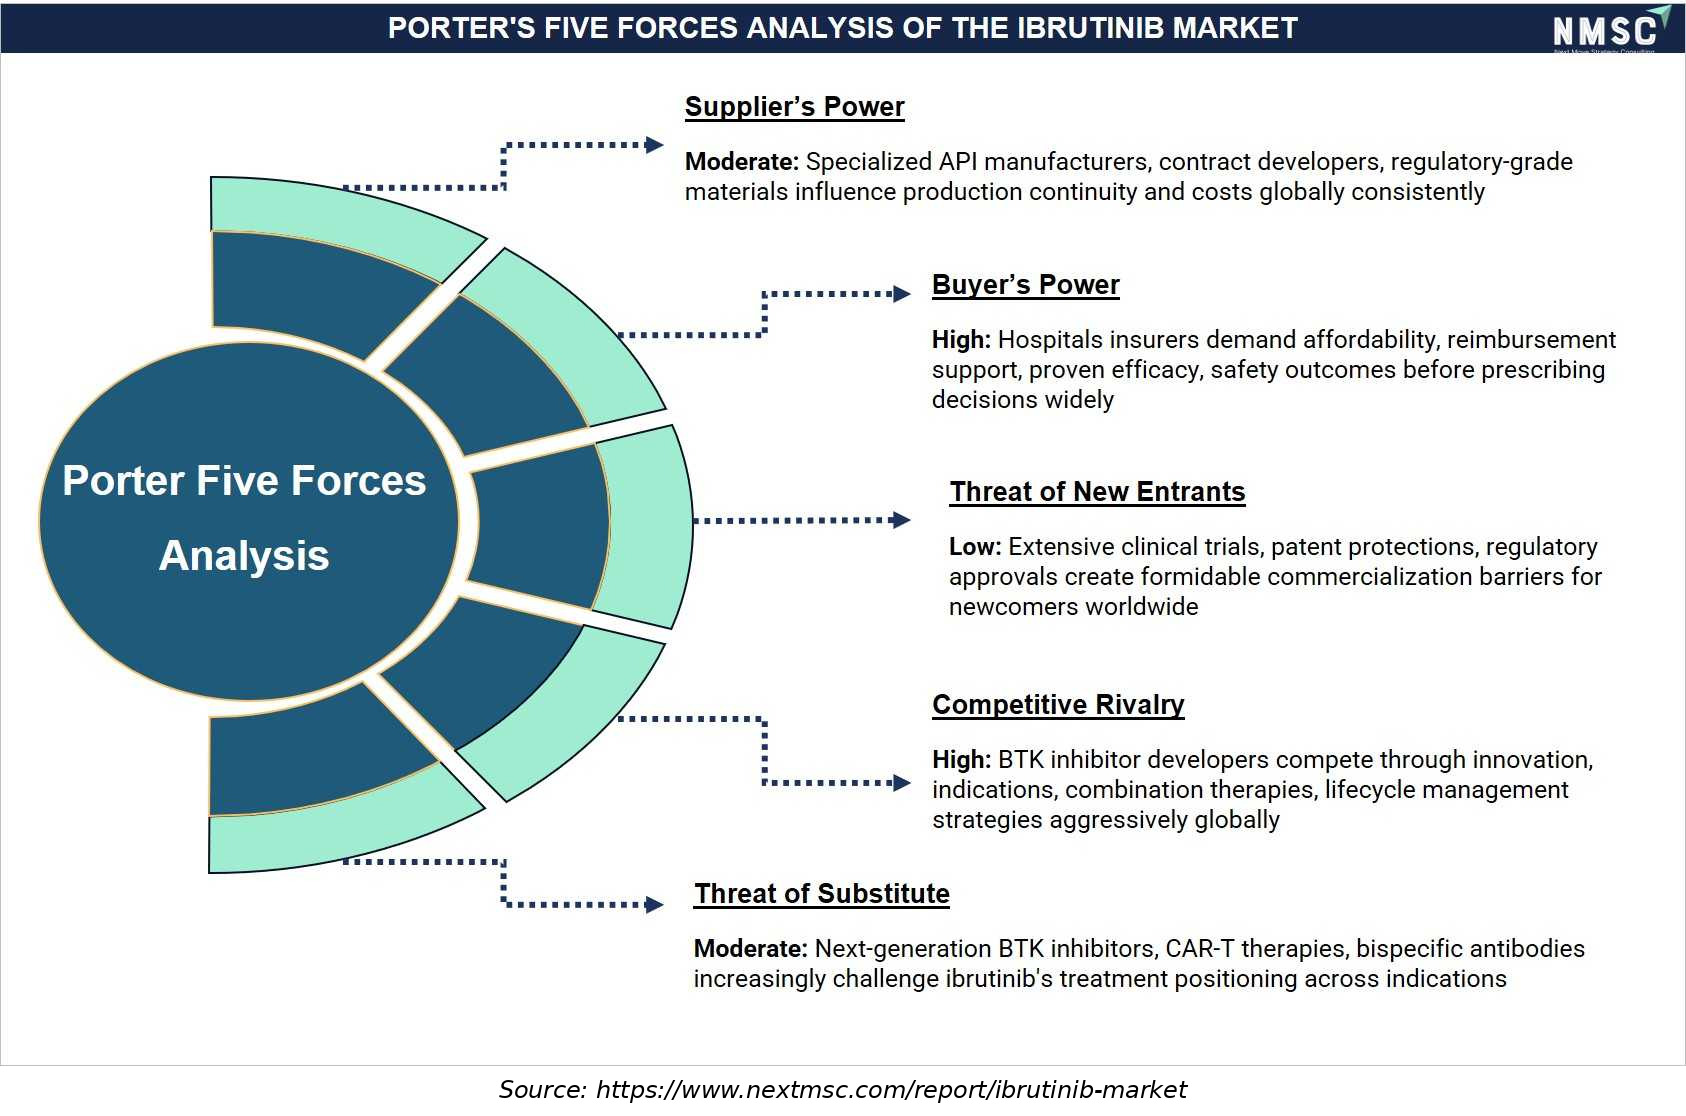
PORTER'S FIVE FORCES ANALYSIS OF THE IBRUTINIB MARKET

Porter's Five Forces analysis indicates that the Ibrutinib Market is characterized by high competitive rivalry due to the presence of established pharmaceutical companies and emerging generic manufacturers. Threat of new entrants remains low because of stringent regulatory requirements and high development costs. Buyer bargaining power is high, while supplier power is moderate owing to specialized API sourcing. Additionally, the threat of substitutes is high, driven by next-generation BTK inhibitors and alternative targeted therapies for hematologic malignancies.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the competitive landscape remains concentrated among the originator companies, with an expanding base of generic manufacturers preparing for entry ahead of the compound's patent expiration.

Dimension Description
Category Assessment
Market Structure Concentrated among originators AbbVie Inc. and Johnson & Johnson, with an expanding base of Indian and multinational generic manufacturers securing tentative regulatory approvals
Innovation Focus Tablet formulation development, bioequivalence study completion, and API manufacturing scale-up ahead of anticipated multi-source competition
M&A Activity Limited direct M&A activity; competitive dynamics instead centered on tentative approval timing and patent litigation settlement outcomes

How Do Companies Compete in the Ibrutinib Market?

Companies compete primarily on regulatory approval timing, manufacturing cost efficiency, and formulation differentiation ahead of anticipated generic entry. We found that securing tentative FDA approval ahead of competitors, as Zydus Lifesciences Limited has done for its tablet formulation, increasingly anchors competitive positioning among generic challengers. Pricing strategies remain closely tied to active pharmaceutical ingredient production costs, pushing manufacturers toward vertically integrated API and finished dose capabilities.

Which Competitive Archetypes Dominate the Ibrutinib Market?

Two archetypes dominate the ibrutinib market: the originator companies that compete on established branded market share and physician familiarity, and generic manufacturers that compete on manufacturing scale, regulatory filing speed, and cost advantage. Our analysis shows that differentiation increasingly centers on tablet-format bioequivalence and tentative approval sequencing, positioning early-filing generic manufacturers to capture disproportionate share once patent barriers clear.

How Are Companies Differentiating Through Innovation?

Leading generic manufacturers are differentiating through tablet formulation development, expanded dosage strength coverage, and API manufacturing scale. During our market evaluation, we noticed that several companies are simultaneously pursuing multiple regional regulatory filings, positioning themselves to serve both developed and emerging markets as patent barriers clear at different times across jurisdictions.

What M&A and Geographic Expansion Activity Is Reshaping the Market?

Geographic expansion through regulatory filings across multiple jurisdictions is reshaping competitive positioning across the industry. We observed that Indian generic manufacturers, including Natco Pharma Limited, Zydus Lifesciences Limited, and Shilpa Medicare Limited, are simultaneously pursuing domestic and export market approvals, reflecting a broader pattern of manufacturing scale-up ahead of the compound's global patent expiration timeline.

Key Market Players

Our assessment indicates that the following companies represent the leading originator and generic manufacturers shaping competitive dynamics across the ibrutinib market.

AbbVie Inc. Johnson & Johnson Cipla Limited Natco Pharma Limited Beacon Pharmaceuticals PLC Zydus Lifesciences Limited Incepta Pharmaceuticals Limited LGM Pharma, LLC (ranking reflects its role as an active pharmaceutical ingredient and contract manufacturing supplier to the ibrutinib value chain) Shilpa Medicare Limited Bluepharma – Indústria Farmacêutica, S.A.

Latest Developments

We found that recent developments within the ibrutinib market are concentrated on branded revenue decline and patent-cliff preparation, reflecting the industry's broader structural transition.

Date Event
July 2025 Zydus Lifesciences received tentative approval from the U.S. FDA for Ibrutinib Tablets in 140 mg, 280 mg, and 420 mg strengths, the generic version of Imbruvica®. The tablets are intended for indications including chronic lymphocytic leukemia/small lymphocytic lymphoma with 17p deletion and Waldenström’s macroglobulinemia. The tentative approval is subject to applicable patent and exclusivity requirements before final approval and U.S. marketing.

Investment Opportunities

Where Are Capital Inflows Concentrated in the Ibrutinib Market?

Capital inflows are concentrated in generic manufacturing capacity and regulatory filing preparation ahead of patent expiration. We observed that Zydus Lifesciences Limited's investment in tablet formulation development and bioequivalence studies, culminating in tentative FDA approval, reflects the broader pattern of generic manufacturer capital deployment ahead of the compound's December 2026 primary patent expiration.

How Is Infrastructure Investment Expanding Generic Manufacturing Capacity?

Infrastructure investment is expanding generic manufacturing capacity across India and other established pharmaceutical manufacturing hubs. We found that companies including Natco Pharma Limited and Shilpa Medicare Limited continue to scale active pharmaceutical ingredient and finished dose production capabilities, positioning themselves to supply both domestic and export markets once global patent barriers clear across major jurisdictions.

What ESG Considerations Are Shaping Ibrutinib Investment?

Environmental, social, and governance considerations are shaping investment as generic entry improves affordability and treatment access for chronic lymphocytic leukemia and related conditions. Our findings suggest that investors and health systems increasingly view timely generic market entry as a positive access and affordability outcome, favoring manufacturers that can demonstrate consistent quality manufacturing standards alongside competitive pricing.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain a structured view of segment-level demand across dosage form, distribution channel, applications, and end-user, supported by Next Move Strategy Consulting's forecasts through 2035. Our analysis shows that this data enables manufacturing and regulatory filing planning decisions, helping companies prioritize investment in the fastest-growing segments, including tablet formulations and online pharmacy distribution.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from validated market sizing, regional growth differentials, and competitive landscape analysis that inform capital allocation decisions. We found that the report's country-level revenue breakdowns and CAGR projections support comparative evaluation of expansion opportunities across North America, Europe, Asia-Pacific, the Middle East & Africa, and Latin America, strengthening due diligence on ibrutinib-related investment targets.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging trends, including tablet formulation development, patent expiration timing, and generic manufacturing scale-up. Our assessment indicates that this analysis helps product teams prioritize research and development roadmaps toward the dosage forms and applications showing the strongest forecast growth, improving alignment between innovation investment and evolving regulatory timelines.

Key Market Segments Evaluated

By Dosage Form

  • Capsules 
    • Hard Gelatin Capsules
    • Soft Gelatin Capsules
  • Tablets 
    • Immediate Release Tablets
    • Extended Release Tablets

By Distribution Channel

  • Hospital
  • Retail
  • Online

By Applications

  • Chronic Lymphocytic Leukemia (CLL)
  • Mantle Cell Lymphoma (MCL)
  • Waldenström's Macroglobulinemia (WM)
  • Others

By End-User

  • Hospitals
  • Clinics
  • Specialty Centers
  • Ambulatory Surgical Centers
  • Others

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico.
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe.
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC.
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA.
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM.

Conclusion & Recommendations

The long-term outlook remains positive, with the market projected to expand from USD 3.95 billion in 2026 to USD 8.70 billion by 2035 at a 9.2% CAGR. Our assessment indicates that this growth will be increasingly shaped by generic market entry following the compound's December 2026 primary patent expiration, transitioning the market from single-source branded dominance toward multi-source competition through 2035.

What Strategic Positioning Should Manufacturers Pursue?

Manufacturers should pursue early regulatory filing positioning that secures tentative approval ahead of patent expiration. We found that companies following Zydus Lifesciences Limited's model of completing tablet formulation bioequivalence studies in advance are best positioned to capture first-mover generic share as the market transitions from branded exclusivity toward multi-source competition.

How Attractive Is the Market for New Investment?

The market presents solid investment attractiveness given its 9.2% forecast CAGR and the approaching generic entry opportunity tied to patent expiration. Our findings suggest that investors focusing on tablet formulation manufacturing, Asia-Pacific generic production capacity, and online pharmacy distribution stand to benefit from above-market growth relative to the broader ibrutinib category.

What Are the Key Market Shifts and Risks?

Key shifts include the approaching transition from branded exclusivity to generic multi-source competition and growing tablet formulation adoption. We observed that principal risks include competition from newer, more selective BTK inhibitors, potential settlement-delayed generic entry in certain jurisdictions, and pricing pressure following generic launch, all of which could shape the pace of the industry's structural transition if unresolved.

What Are the Primary Growth Pathways Through 2035?

Primary growth pathways include scaling generic tablet manufacturing, expanding Waldenström's macroglobulinemia treatment adoption, and deepening online pharmacy distribution for long-term oral oncology therapy. Based on research conducted by Next Move Strategy Consulting, we found that manufacturers combining these three pathways with early regulatory filing strategy are best positioned to capture the USD 4.75 billion absolute dollar opportunity created between 2026 and 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market & Sales Analysis
  • Historical ibrutinib revenue and volume analysis by dosage form (capsule, tablet, oral suspension) and application.
  • Reveals growth patterns and demand shifts to support forecasting and portfolio planning.
Import-Export Trade Assessment
  • Country-wise import and export analysis of ibrutinib and related active pharmaceutical ingredient and formulation trade flows.
  • Identifies key sourcing hubs and supply routes to support sourcing and market-entry decisions.
TAM / SAM / VAM Opportunity Sizing
  • Total, serviceable, and valuable market sizing for ibrutinib by application, end-user, and distribution channel.
  • Prioritizes the highest-value patient and channel segments for targeting and investment.
Indication-Level Treatment Demand Analysis
  • Ibrutinib demand mapped across CLL/SLL, mantle cell lymphoma, Waldenstrom macroglobulinemia, and chronic graft-versus-host disease using public cancer incidence and treatment-guideline data.
  • Pinpoints the indications with the largest treated-patient pools and the strongest expansion potential.
Patent Expiry & Generic Entry Assessment
  • Country-wise ibrutinib patent and exclusivity timelines, regulatory filings, and generic launch status with potential price-erosion scenarios.
  • Guides generic launch timing, licensing, and defense strategies by country.
Channel & End-User Access Mapping
  • Ibrutinib dispensing flow across hospital, retail, and online or specialty pharmacies, mapped to hospitals, cancer centers, and specialty clinics.
  • Shows where distribution and pricing efforts should focus to maximize patient reach and uptake.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Mohit Agarwal

MOHIT AGARWAL

Chief Manager

DryChem India Pvt. Ltd.

Next Move Strategy Consulting is an amazing team of consultants. We required a market study report for our investors on top priority and the team went above and beyond our expectations to deliver the same with ample supporting data within a short time span enabling us to secure the investments and keep our project timeline maintained. Their professionalism, attention to detail, and timely delivery of actionable recommendations have left a lasting impression on our organization.

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖