Internet of Things (IoT) Market

The global Internet of Things (IoT) Market size was USD 1.86 trillion in 2025, projected to reach USD 7.54 trillion by 2035, growing at a CAGR of 13.43% from 2026 to 2035. Key growth drivers include scaling enterprise connected asset deployments, increasing investment in private 5G and edge computing infrastructure, and rising adoption of AI-enabled analytics and digital twin technologies, with Asia-Pacific leading the market with approximately 35% share.
Download Free Sample PDF
Base Year (2025)
$1.86 Trillion
Forecast (2035)
$7.54 Trillion
CAGR (2026-2035)
13.4%
Top Region
Asia-Pacific

What Is the Internet of Things (IoT) Market Size?
The global Internet of Things (IoT) market size was valued at USD 1.86 trillion in 2025 and is estimated at USD 2.42 trillion in 2026, forecast to reach USD 7.54 trillion by 2035, expanding at a 13.43% CAGR between 2026 and 2035. Asia-Pacific leads with approximately 35% share, while IoT Endpoint Hardware dominates the hardware landscape with approximately 62% share.

We observed that enterprise IoT security spending and managed connectivity services are scaling faster than the broader market as organizations extend connected asset deployments beyond initial pilot programs into production-scale operations.

Internet of Things (IoT) Market Revenue Forecast
Values in USD Trillion

2025 $1.86 Trillion
2025
2026 $2.11 Trillion
2026
2027 $2.39 Trillion
2027
2028 $2.71 Trillion
2028
2029 $3.08 Trillion
2029
2030 $3.49 Trillion
2030
2031 $3.96 Trillion
2031
2032 $4.49 Trillion
2032
2033 $5.10 Trillion
2033
2034 $5.78 Trillion
2034
2035 $7.54 Trillion
2035

Key Takeaways

By Hardware: IoT Endpoint Hardware held the largest share of approximately 62% (USD 1.15 trillion) in 2025; IoT Edge Hardware is the fastest-growing sub-segment at 17.2% CAGR from 2026–2035.

By Connectivity: Network Access held the largest share of approximately 78% (USD 1.45 trillion) in 2025; Connectivity Management is the fastest-growing sub-segment at 17.9% CAGR from 2026–2035.

By Software: IoT Platform Software held the largest share of approximately 24% (USD 0.45 trillion) in 2025; Digital Twin Software is the fastest-growing sub-segment at 20.3% CAGR from 2026–2035.

By Services: Implementation Services held the largest share of approximately 28% (USD 0.52 trillion) in 2025; IoT Security Services is the fastest-growing sub-segment at 19.3% CAGR from 2026–2035.

By End-User Industry: Manufacturing held the largest share of approximately 24% (USD 0.45 trillion) in 2025; Agriculture is the fastest-growing sub-segment at 19.0% CAGR from 2026–2035.

By Buyer Type: Enterprise held the largest share of approximately 58% (USD 1.08 trillion) in 2025; Government and Public Sector is the fastest-growing sub-segment at 17.4% CAGR from 2026–2035.

By Sales Channel: Direct Sales held the largest share of approximately 47% (USD 0.87 trillion) in 2025; Marketplace is the fastest-growing sub-segment at 22.4% CAGR from 2026–2035.

Dominant Region: Asia-Pacific dominated with approximately 35% revenue share (USD 0.65 trillion) in 2025.

Fastest-Growing Region: Asia-Pacific is also expected to register the highest CAGR of 17.1% during 2026–2035.

Dominant Country: U.S. led with approximately USD 0.49 trillion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 19.6% CAGR from 2026–2035.

Market Opportunity: The Internet of Things (IoT) market is expected to create an absolute dollar opportunity of USD 5.12 trillion between 2026 and 2035, presenting significant investment potential across edge computing, IoT security, and managed connectivity services.

According to NMSC analysis, enterprises are increasingly consolidating device management, security, and analytics into unified IoT platforms rather than procuring point solutions separately, a shift that is reshaping vendor selection criteria across the broader [edge computing](https: //www.nextmsc.com/report/edge-computing-market) infrastructure that underpins distributed IoT deployments.

What Does the Internet of Things (IoT) Market Encompass?
The Internet of Things (IoT) market encompasses the hardware, connectivity, software, and services required to connect, manage, and derive value from networked physical devices across consumer, enterprise, and industrial environments. Our assessment indicates that the scope spans endpoint and edge hardware, cellular and low-power wide area network connectivity, device management and analytics software, and consulting, implementation, and managed services purchased by enterprise, mid-market, government, and consumer buyers across manufacturing, energy, transportation, and healthcare end markets, supported by the 20 companies profiled in this report.
The category has evolved from isolated machine-to-machine deployments into integrated, platform-based ecosystems as enterprises move from pilot programs into production-scale connected operations. GSMA Intelligence forecasts that global IoT connections will reach 38.7 billion by 2030, underpinned by emerging technologies including ambient IoT, non-terrestrial networks, and eSIM provisioning. We observed that technology adoption is shifting toward AI-enabled edge analytics and digital twin software, extending IoT deployments deeper into the industrial automation value chain.

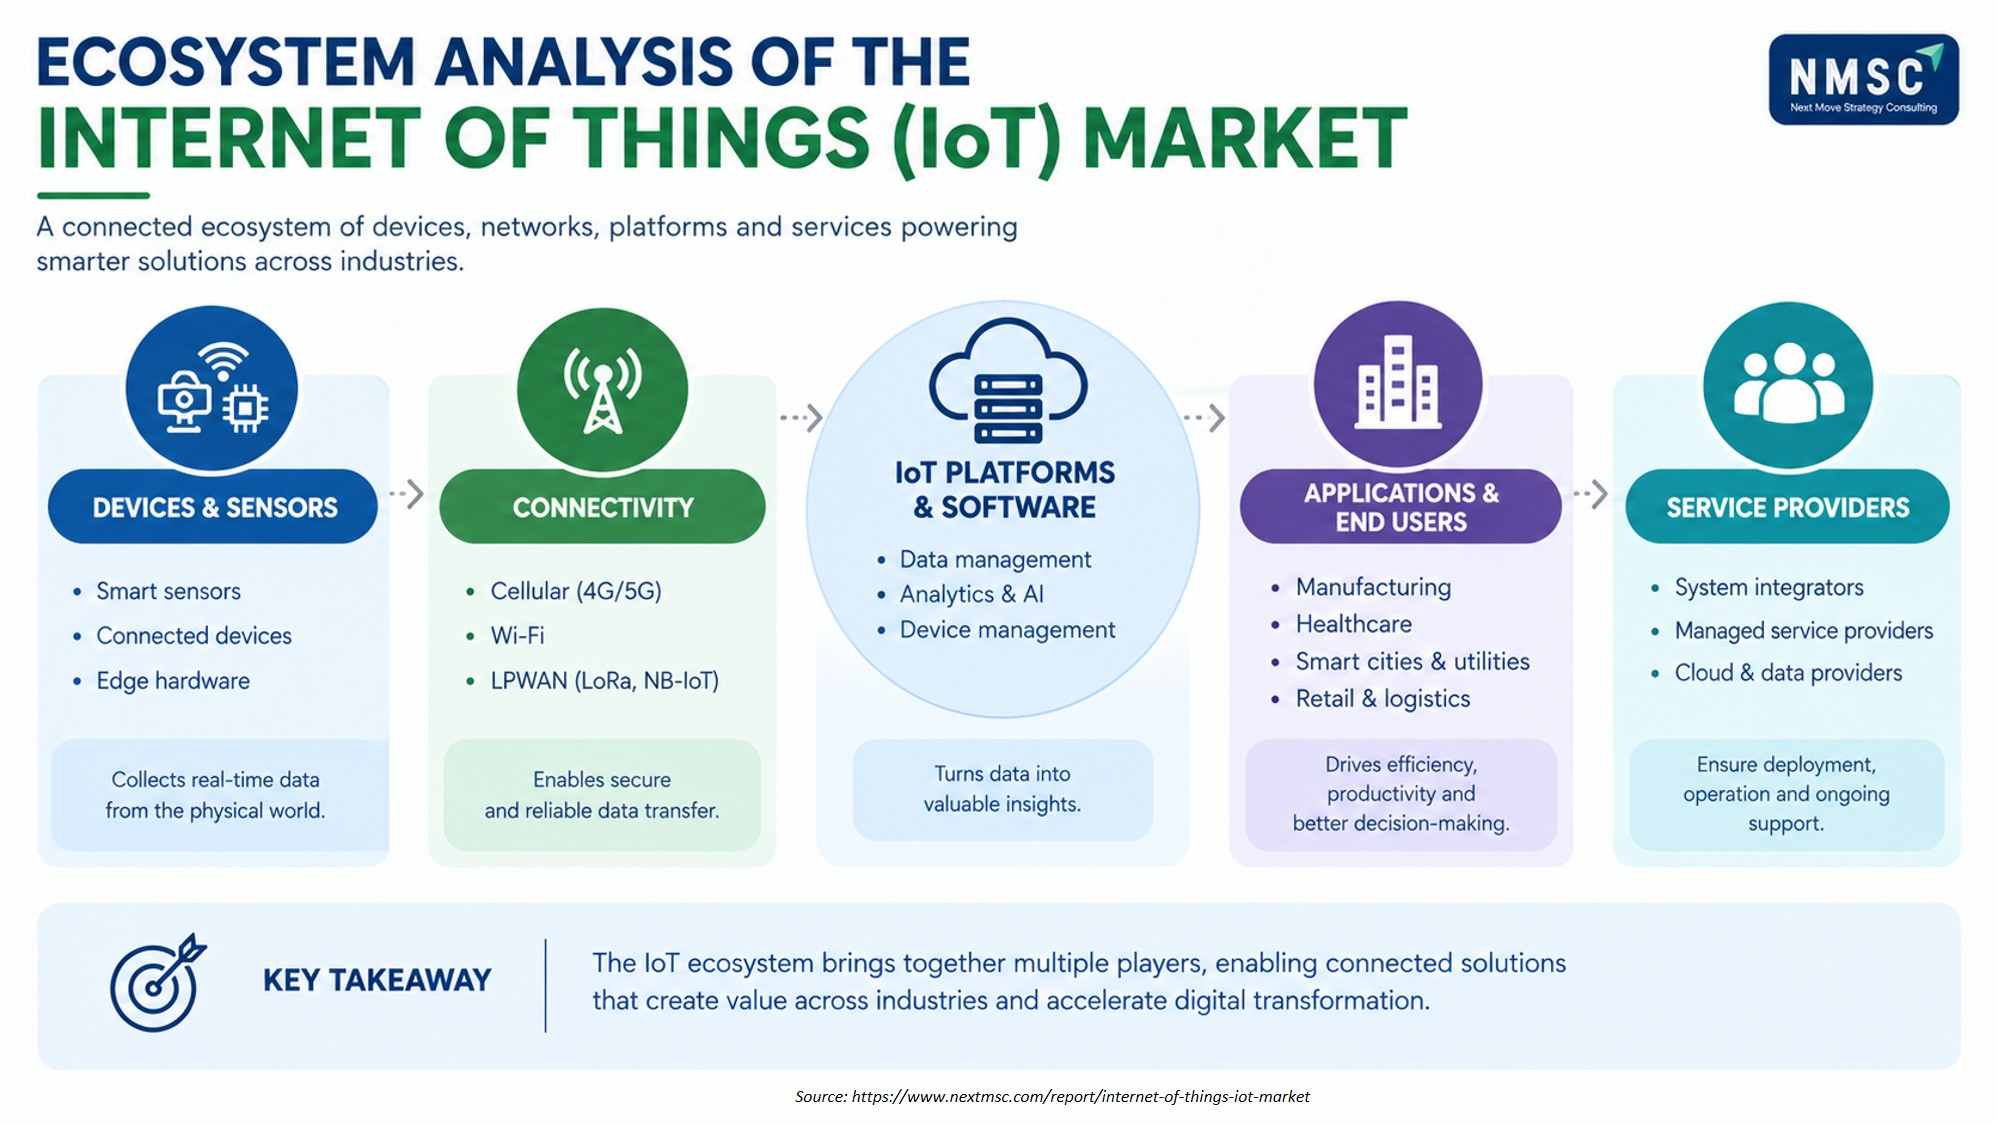
Ecosystem Analysis of the Internet of Things (IoT) Market
The IoT market operates through an interconnected ecosystem spanning devices and sensors, connectivity providers, IoT platforms, software developers, application providers, and service partners. Each layer contributes to data collection, transmission, analysis, and deployment across industries. This ecosystem supports scalable connected solutions while enabling organizations to improve operational efficiency, automate processes, strengthen decision-making, and accelerate digital transformation.

Market Drivers & Dynamics

Interactive Dataset
Enterprise connected asset deployment scaling beyond pilot programs driver +2.8% Global 2026-2035
Private 5G and industrial connectivity infrastructure investment driver +2.1% North America, Europe, Asia-Pacific 2026-2032
Rising IoT security spending amid expanding attack surface driver +1.9% Global 2026-2035
AI-enabled edge analytics and digital twin software adoption driver +2.4% Global 2026-2035
Government smart infrastructure and manufacturing modernization programs driver +1.7% Asia-Pacific, Middle East & Africa 2026-2035
Ambient IoT and low-power connectivity technology commercialization driver +1.5% Global 2028-2035
Fragmented connectivity standards across regions and industries restraint -1.3% Global 2026-2032
Data privacy and cross-border data transfer regulatory complexity restraint -1.0% Europe, Asia-Pacific 2026-2035
High integration cost for legacy operational technology environments restraint -0.8% North America, Europe 2026-2030
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Internet of Things (IoT) Market?

Enterprise connected asset deployment scaling beyond pilot programs is the primary driver of the market. We observed that Samsara Inc. reported 2,990 customers with annual recurring revenue exceeding USD 100,000 as of the third quarter of fiscal year 2026. ARR from customers above this threshold grew 36% year over year. This behavioral shift continues to anchor baseline demand for IoT hardware, connectivity, and application software across transportation, logistics, and industrial customers.

How Is 5G Infrastructure Investment Driving IoT Market Growth?

Private 5G and industrial connectivity infrastructure investment is accelerating market growth as manufacturing, logistics, and utility operators deploy dedicated networks supporting low-latency machine communication. Our assessment indicates that GSMA Intelligence's continued tracking of 5G standalone deployment and enterprise digitalization progress signals sustained infrastructure investment, positioning connectivity providers and network equipment vendors to capture recurring revenue from industrial IoT rollouts through the forecast period.

Growth Inhibitors

What Is Restraining Internet of Things (IoT) Market Expansion?
Fragmented connectivity standards across regions and industries restrain broader market expansion, particularly for enterprises deploying IoT fleets across multiple countries with differing cellular, LPWAN, and spectrum regulations. We found that this fragmentation adds integration cost and certification complexity compared with single-market deployments, slowing the pace at which multinational enterprises can standardize connectivity architecture across global operations.

Segmentation Analysis

2025 (USD Trillion)
2035 (USD Trillion)
IoT Endpoint Hardware 2025: $1.15 Trillion | 2035: $4.15 Trillion
IoT Endpoint
IoT Edge Hardware 2025: $0.35 Trillion | 2035: $1.73 Trillion
IoT Edge Har
IoT Network Hardware 2025: $0.26 Trillion | 2035: $1.21 Trillion
IoT Network
Other IoT Hardware 2025: $0.00 Trillion | 2035: $0.45 Trillion
Other IoT Ha
IoT Endpoint Hardware $1.15 Trillion $4.15 Trillion 13.7%
IoT Edge Hardware $0.35 Trillion $1.73 Trillion 17.2%
IoT Network Hardware $0.26 Trillion $1.21 Trillion 16.6%
Other IoT Hardware $0.00 Trillion $0.45 Trillion 17.1%

Which Hardware Segment Dominates the Internet of Things (IoT) Market?

IoT Endpoint Hardware led the market with USD 1.15 trillion in 2025, reflecting the sheer volume of sensing, identification, and connected consumer and enterprise devices deployed across the installed base. We observed that IoT Edge Hardware is the fastest-growing hardware segment, expanding at a 17.2% CAGR from 2026 to 2035, as enterprises deploy gateways and edge computers to process data closer to the source and reduce dependence on centralized cloud processing.

2025 (USD Trillion)
2035 (USD Trillion)
Network Acce
Cellular
LPWAN
Satellite
Wi-Fi
Segment Item 2025 (USD Trillion) 2035 (USD Trillion) CAGR
Network Access $10.0 USD Trillion $40.0 USD Trillion 25.0%
Cellular $17.1 USD Trillion $51.1 USD Trillion 11.0%
LPWAN $24.2 USD Trillion $62.2 USD Trillion 25.0%
Satellite $31.3 USD Trillion $73.3 USD Trillion 11.0%
Wi-Fi $38.4 USD Trillion $84.4 USD Trillion 16.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By Connectivity.

Unlock Full Data
2025 (USD Trillion)
2035 (USD Trillion)
IoT Platform Software 2025: $0.45 Trillion | 2035: $1.58 Trillion
IoT Platform
IoT Application Software 2025: $0.43 Trillion | 2035: $1.66 Trillion
IoT Applicat
IoT Data and Analytics Software 2025: $0.35 Trillion | 2035: $1.51 Trillion
IoT Data and
Device Management Software 2025: $0.24 Trillion | 2035: $0.75 Trillion
Device Manag
IoT Security Software 2025: $0.21 Trillion | 2035: $1.06 Trillion
IoT Security
Digital Twin Software 2025: $0.13 Trillion | 2035: $0.83 Trillion
Digital Twin
Other IoT Software 2025: $0.05 Trillion | 2035: $0.15 Trillion
Other IoT So
IoT Platform Software $0.45 Trillion $1.58 Trillion 13.5%
IoT Application Software $0.43 Trillion $1.66 Trillion 14.5%
IoT Data and Analytics Software $0.35 Trillion $1.51 Trillion 15.6%
Device Management Software $0.24 Trillion $0.75 Trillion 12.0%
IoT Security Software $0.21 Trillion $1.06 Trillion 17.8%
Digital Twin Software $0.13 Trillion $0.83 Trillion 20.3%
Other IoT Software $0.05 Trillion $0.15 Trillion 10.5%

Which Software Segment Is Growing Fastest in the Internet of Things (IoT) Market?

IoT Platform Software remained the leading software segment, valued at USD 0.45 trillion in 2025, as enterprises consolidate application enablement, data ingestion, and device registry functions onto unified platforms. Our findings suggest that Digital Twin Software is the fastest-growing software segment, registering a 20.3% CAGR from 2026 to 2035, as manufacturers increasingly simulate asset and process behavior ahead of physical deployment to reduce commissioning risk and downtime.

2025 (USD Trillion)
2035 (USD Trillion)
Consulting S
Strategy and
Architecture
Technology A
Implementati
Segment Item 2025 (USD Trillion) 2035 (USD Trillion) CAGR
Consulting Services $10.0 USD Trillion $40.0 USD Trillion 14.0%
Strategy and Assessment $17.1 USD Trillion $51.1 USD Trillion 24.0%
Architecture and Design $24.2 USD Trillion $62.2 USD Trillion 22.0%
Technology Advisory $31.3 USD Trillion $73.3 USD Trillion 12.0%
Implementation Services $38.4 USD Trillion $84.4 USD Trillion 27.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By Services.

Unlock Full Data
2025 (USD Trillion)
2035 (USD Trillion)
Manufacturing 2025: $0.45 Trillion | 2035: $1.66 Trillion
Manufacturin
Energy and Utilities 2025: $0.24 Trillion | 2035: $0.98 Trillion
Energy and U
Transportation and Logistics 2025: $0.22 Trillion | 2035: $0.98 Trillion
Transportati
Buildings and Infrastructure 2025: $0.19 Trillion | 2035: $0.83 Trillion
Buildings an
Retail and Consumer Services 2025: $0.17 Trillion | 2035: $0.60 Trillion
Retail and C
Consumer 2025: $0.17 Trillion | 2035: $0.53 Trillion
Consumer
Healthcare and Life Sciences 2025: $0.15 Trillion | 2035: $0.75 Trillion
Healthcare a
Agriculture 2025: $0.09 Trillion | 2035: $0.53 Trillion
Agriculture
Mining and Natural Resources 2025: $0.07 Trillion | 2035: $0.30 Trillion
Mining and N
Aerospace and Defence 2025: $0.06 Trillion | 2035: $0.23 Trillion
Aerospace an
Other Industries 2025: $0.05 Trillion | 2035: $0.15 Trillion
Other Indust
Manufacturing $0.45 Trillion $1.66 Trillion 14.0%
Energy and Utilities $0.24 Trillion $0.98 Trillion 15.0%
Transportation and Logistics $0.22 Trillion $0.98 Trillion 15.9%
Buildings and Infrastructure $0.19 Trillion $0.83 Trillion 16.1%
Retail and Consumer Services $0.17 Trillion $0.60 Trillion 13.7%
Consumer $0.17 Trillion $0.53 Trillion 12.2%
Healthcare and Life Sciences $0.15 Trillion $0.75 Trillion 17.6%
Agriculture $0.09 Trillion $0.53 Trillion 19.0%
Mining and Natural Resources $0.07 Trillion $0.30 Trillion 15.0%
Aerospace and Defence $0.06 Trillion $0.23 Trillion 15.0%
Other Industries $0.05 Trillion $0.15 Trillion 10.5%

Which End-User Industry Is Growing Fastest in the Internet of Things (IoT) Market?

Manufacturing remained the leading end-user industry, reaching USD 0.45 trillion in 2025 on sustained connected machinery and condition monitoring deployment. We found that Agriculture is the fastest-growing end-user industry, registering a 19.0% CAGR from 2026 to 2035, as environmental sensors and connected irrigation and monitoring systems expand precision farming adoption across both developed and emerging agricultural markets.

2025 (USD Trillion)
2035 (USD Trillion)
Enterprise
Mid-Market
Government a
Consumer
Segment Item 2025 (USD Trillion) 2035 (USD Trillion) CAGR
Enterprise $10.0 USD Trillion $40.0 USD Trillion 23.0%
Mid-Market $17.1 USD Trillion $51.1 USD Trillion 9.0%
Government and Public Sector $24.2 USD Trillion $62.2 USD Trillion 19.0%
Consumer $31.3 USD Trillion $73.3 USD Trillion 13.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By Buyer Type.

Unlock Full Data
2025 (USD Trillion)
2035 (USD Trillion)
Direct Sales
Partner Sale
Marketplace
OEM
Segment Item 2025 (USD Trillion) 2035 (USD Trillion) CAGR
Direct Sales $10.0 USD Trillion $40.0 USD Trillion 21.0%
Partner Sales $17.1 USD Trillion $51.1 USD Trillion 23.0%
Marketplace $24.2 USD Trillion $62.2 USD Trillion 25.0%
OEM $31.3 USD Trillion $73.3 USD Trillion 15.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the Internet of Things (IoT) market over the 2026-2035 forecast period.

Edge Computing Expansion Creates Opportunity for Latency-Sensitive Industrial Deployments

Vendors that scale IoT Edge Hardware and edge analytics capability can capture recurring hardware and software revenue from manufacturing and utility customers requiring real-time, low-latency processing. This positions edge-focused suppliers to benefit as enterprises reduce dependence on centralized cloud processing for time-sensitive industrial control applications.

IoT Security Services Address a Rapidly Expanding Compliance Gap

Managed IoT security offerings present a whitespace opportunity as enterprises confront expanding attack surfaces across large, distributed device fleets. Providers that scale device identity, vulnerability management, and security monitoring services stand to capture share from organizations that previously treated device-level security as an afterthought to core IoT deployments.

Government Smart Infrastructure Programs Expand Public Sector IoT Demand

Vendors that align product portfolios with government smart infrastructure and manufacturing modernization programs can capture recurring public sector contracts, particularly across Asia-Pacific and Middle East & Africa markets. Suppliers offering government-grade security compliance and public sector procurement experience stand to capture share as the Government and Public Sector buyer segment continues to outpace overall market growth.

Regional Outlook

Asia-Pacific $0.65 Trillion $3.17 Trillion 17.1%
North America $0.60 Trillion $2.04 Trillion 13.1%
Europe $0.41 Trillion $1.43 Trillion 13.3%
Middle East & Africa $0.11 Trillion $0.53 Trillion 16.8%
Latin America $0.09 Trillion $0.37 Trillion 15.0%

Competitive Landscape

We observed that the Internet of Things (IoT) Market features a fragmented competitive landscape, with diversified technology conglomerates competing alongside industrial automation specialists, connectivity providers, and connected operations software pioneers. Dimension | Description Market Structure | Fragmented; diversified cloud and technology conglomerates profiled in this report compete alongside industrial automation specialists, telecommunications connectivity providers, and dedicated connected operations software vendors, with no single company commanding a majority share. Innovation Focus | AI-enabled edge analytics, digital twin software, private 5G connectivity, and unified IoT platform consolidation dominate current innovation pipelines across leading vendors. M&A Activity | Selective platform and capability expansion, exemplified by Samsara Inc.'s continued organic customer base growth to 2,990 large enterprise accounts by the third quarter of fiscal year 2026 alongside its first quarter of GAAP profitability. Source: www.nextmsc.com

How Do Companies Compete in the Internet of Things (IoT) Market?

Companies compete primarily on platform breadth, industrial domain expertise, and connectivity network scale across the Industry . Diversified technology providers such as Microsoft Corporation and Amazon.com, Inc. leverage cloud infrastructure to serve broad, horizontal IoT platform demand, while industrial automation specialists such as Siemens AG and Rockwell Automation, Inc. compete on deep manufacturing and process domain expertise embedded into their software and hardware portfolios.

Which Competitive Archetypes Dominate the Internet of Things (IoT) Market?

Three archetypes dominate the market: diversified cloud and technology conglomerates offering horizontal IoT platforms, industrial automation specialists embedding IoT into domain-specific equipment and software, and telecommunications providers offering managed connectivity. Microsoft Corporation and Amazon.com, Inc. exemplify the cloud platform archetype, Siemens AG and ABB Ltd. exemplify the industrial automation archetype, and Verizon Communications Inc. and Vodafone Group Plc exemplify the connectivity provider archetype.

How Are Companies Differentiating Through Innovation in IoT?

Innovation and differentiation strategy increasingly center on AI-enabled analytics and unified platform consolidation. Samsara Inc. exemplifies this direction through its AI-powered Connected Operations Platform, which the company's leadership states is helping customers improve safety and operational efficiency. Our analysis shows that vendors unable to demonstrate integrated AI analytics capability risk exclusion from large enterprise procurement shortlists as connected fleets scale beyond pilot deployments.

What Growth Activity Is Shaping the Internet of Things (IoT) Market?

Organic growth and capability expansion continue to reshape competitive positioning within the Industry . Samsara Inc.'s achievement of its first quarter of GAAP profitability in the third quarter of fiscal year 2026, alongside 29% year-over-year revenue growth, illustrates how connected operations software vendors are scaling toward sustainable profitability as enterprise customer bases mature beyond initial deployment phases.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping product innovation, platform strategy, and connectivity infrastructure within the global Internet of Things (IoT) market.

Microsoft Corporation Amazon.com, Inc. Cisco Systems, Inc. Siemens AG Schneider Electric SE Samsung Electronics Co., Ltd. International Business Machines Corporation Huawei Technologies Co., Ltd. Robert Bosch GmbH Honeywell International Inc. ABB Ltd. Rockwell Automation, Inc. Emerson Electric Co. Apple Inc. Verizon Communications Inc. Vodafone Group Plc Xiaomi Corporation Samsara Inc. AT&T Inc. KORE Group Holdings, Inc.

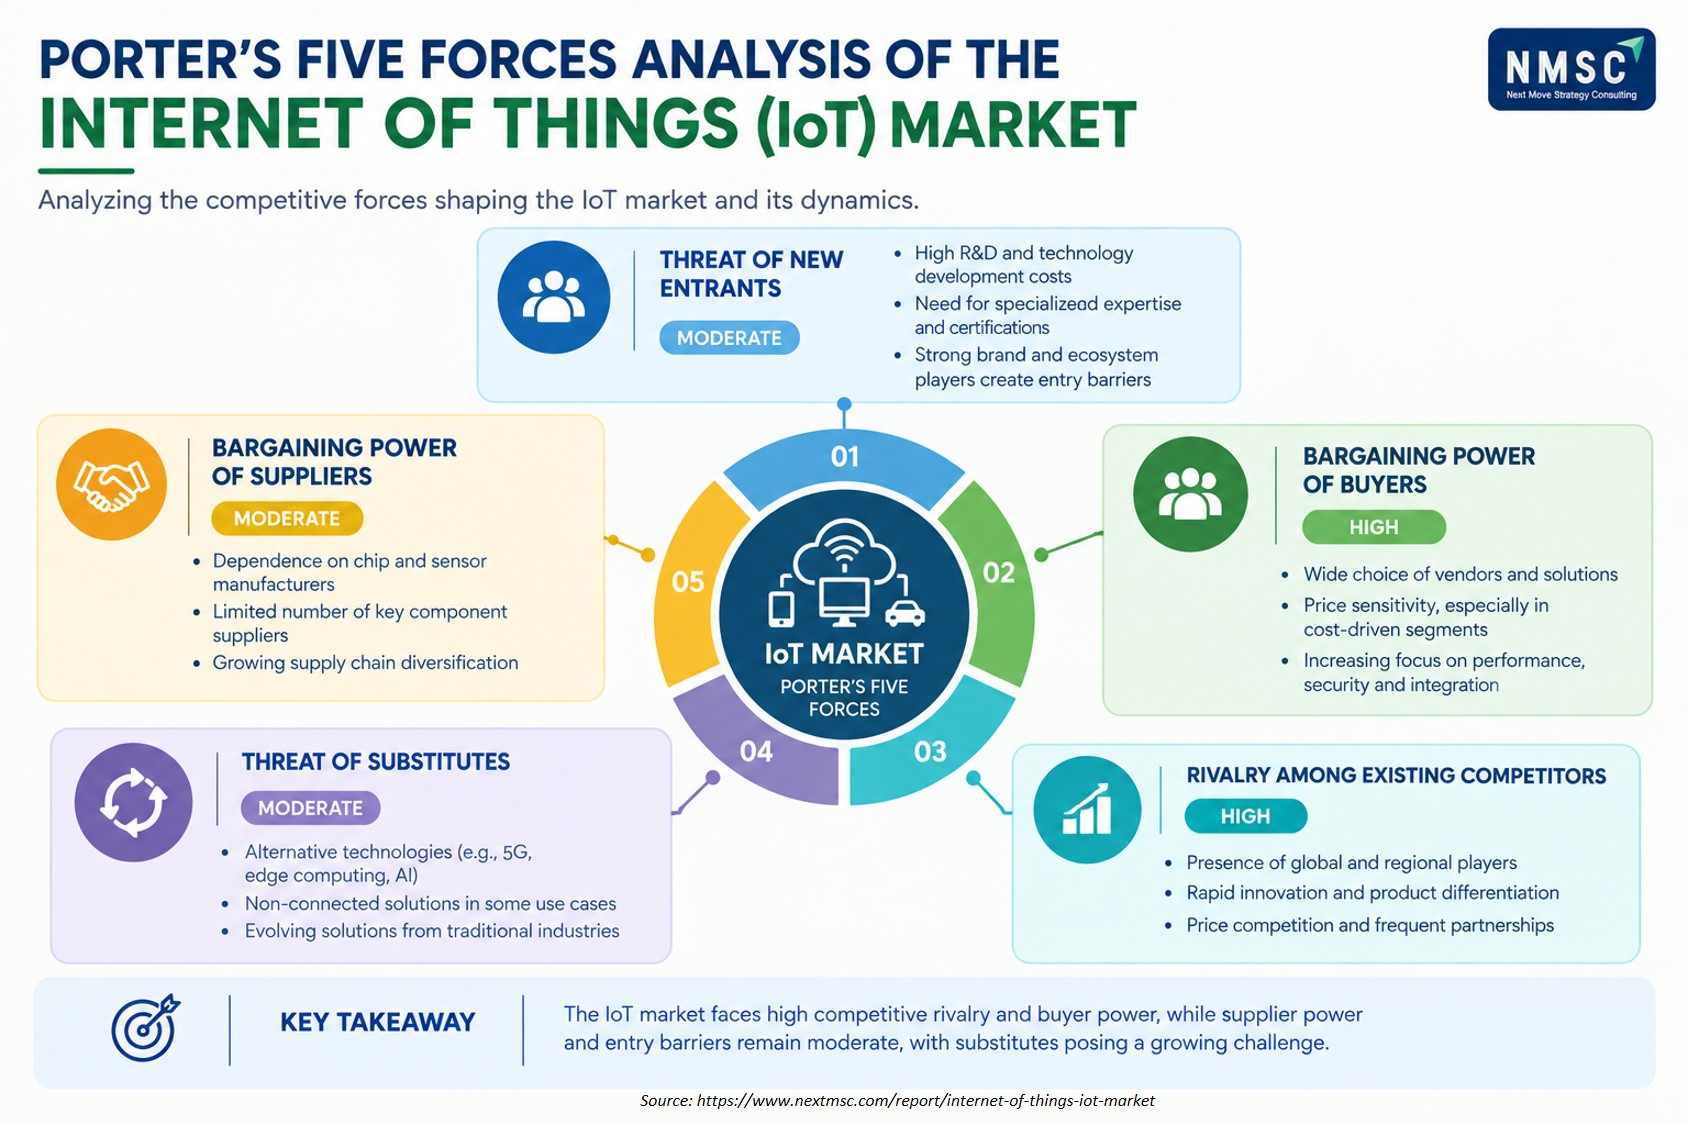
Porter’s Five Forces Analysis of the Internet of Things (IoT) Market

The IoT market demonstrates high competitive rivalry and strong buyer bargaining power, reflecting numerous technology providers, evolving solutions, and increasing demand for performance, security, and integration. Supplier power and the threat of new entrants remain moderate due to component dependencies, technical expertise requirements, and established ecosystems. Substitutes also present a moderate competitive pressure as alternative technologies continue to evolve.

Latest Developments

We found that recent activity within the Internet of Things (IoT) market is concentrated on connected operations platform growth and industry benchmarking, reflecting the industry's broader shift toward AI-supported, production-scale deployments.

Date Event
August 2026 Emerson launched PACEdge 3.0, an IIoT enablement platform that brings AI, machine learning, advanced analytics, containerized workloads, and simplified application deployment to industrial edge devices. The release strengthens edge-based processing of siloed operational data and supports real-time industrial intelligence across manufacturing, energy, life sciences, and other sectors.
June 2026 Huawei outlined a 5G-A IoT foundation strategy at the GSMA IoT Summit, positioning AI-IoT convergence, full-stack 5G-A capabilities, and ecosystem development across chips, modules, devices, and applications as priorities. Huawei said the architecture targets differentiated connectivity across scenarios and a future of up to 100 billion intelligent connections.
June 2026 Rockwell Automation introduced FactoryTalk ResilientEdge , a unified execution architecture combining machine, production, and enterprise intelligence across edge and cloud environments. The platform supports low-latency processing, analytics, AI training, and continued plant operations during connectivity loss, strengthening the infrastructure for scalable, resilient industrial IoT and autonomous manufacturing.
June 2026 ABB and Samsung announced integration between ABB Ability BuildingPro and Samsung SmartThings Pro, linking building data, controls, and enterprise IoT capabilities. The collaboration supports occupancy-based energy management, centralized monitoring, and connected hospitality experiences, with proof-of-concept deployments planned at three sites in Germany, the Netherlands, and Denmark during 2026.
May 2026 AWS introduced direct point-to-point messaging in AWS IoT Core, allowing organizations to send messages directly to connected devices while receiving delivery acknowledgments and detailed observability. The capability lowers messaging costs for one-to-one communication patterns and improves device fleet management by providing clearer delivery status, diagnostics, and failure information.

Investment Opportunities

Capital Inflows Are Concentrating in AI-Enabled Platform Providers

Capital inflows into the market are increasingly directed toward AI-enabled connected operations platforms and industrial automation software. We observed that Samsara Inc.'s sustained annual recurring revenue growth, reaching USD 1.75 billion by the third quarter of fiscal year 2026 alongside its first GAAP-profitable quarter, reflects investor confidence in the commercial maturity of AI-supported IoT platform businesses.

Infrastructure Investment Is Expanding Private 5G and Edge Computing Capacity

Infrastructure investment is expanding private 5G and edge computing capacity across North America, Europe, and Asia-Pacific to serve rising industrial IoT demand. Our findings suggest that connectivity providers are investing in dedicated network infrastructure, complementing adjacent investment in the broader 5G infrastructure supporting low-latency industrial and enterprise IoT deployments.

Device Security and Lifecycle Management Shape ESG and Governance Priorities

Environmental, social, and governance considerations increasingly influence investment decisions, with device security, energy efficiency, and lifecycle management as key criteria for IoT infrastructure investment. We found that investors increasingly favor vendors demonstrating validated device security certification and energy-efficient hardware design, treating these as governance indicators alongside traditional platform scalability and reliability metrics.

Key Benefits for Stakeholders

Enterprise and Industry Leaders Gain Deployment Planning Support

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and deployment-planning decisions across the Internet of Things (IoT) market . Our analysis shows that detailed hardware, software, and services breakdowns help technology teams align platform specifications with rising connected asset requirements while identifying underserved segments for expansion.

Investors and Financial Analysts Gain Consistent Valuation Benchmarks

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the Internet of Things (IoT) Market . We observed that the report's regional and segment-level growth differentials help identify which vendors are best positioned to capture above-market growth in Asia-Pacific and Digital Twin Software categories through 2035.

Technology Vendors and Product Teams Gain Design Requirement Insight

Technology vendors and product teams gain insight into emerging design requirements, including edge analytics integration, digital twin capability, and unified platform consolidation, that are reshaping the industry. Our findings suggest that this analysis helps product teams prioritize development roadmaps around AI-enabled connected operations platforms increasingly required by large enterprise procurement processes.

Key Market Segments Evaluated

By Hardware

  • IoT Endpoint Hardware
  • IoT Edge Hardware
  • IoT Network Hardware
  • Other IoT Hardware

By Connectivity

  • Network Access
  • Cellular
  • LPWAN
  • Satellite
  • Wi-Fi
  • Private Wireless
  • Fixed Connectivity
  • Connectivity Management
  • SIM and eSIM Management
  • Device Provisioning
  • Connectivity Monitoring
  • Roaming Management
  • Connectivity Orchestration
  • Other IoT Connectivity

By Software

  • IoT Platform Software
  • IoT Application Software
  • IoT Data and Analytics Software
  • Device Management Software
  • IoT Security Software
  • Digital Twin Software
  • Other IoT Software

By Services

  • Consulting Services
  • Strategy and Assessment
  • Architecture and Design
  • Technology Advisory
  • Implementation Services
  • Deployment
  • System Integration
  • OT and IT Integration
  • Data Integration
  • Application Integration
  • Managed IoT Services
  • Managed Devices
  • Managed Connectivity
  • Managed Platforms
  • Managed Applications
  • Managed IoT Operations
  • Support Services
  • Technical Support
  • Hardware Support
  • Software Maintenance
  • Lifecycle Support
  • IoT Security Services
  • Managed IoT Security
  • Security Assessment
  • Compliance Services
  • Training Services
  • Technical Training
  • User Training
  • Other IoT Services

By End-User Industry

  • Manufacturing
  • Energy and Utilities
  • Transportation and Logistics
  • Buildings and Infrastructure
  • Retail and Consumer Services
  • Consumer
  • Healthcare and Life Sciences
  • Agriculture
  • Mining and Natural Resources
  • Aerospace and Defence
  • Other Industries

By Buyer Type

  • Enterprise
  • Mid-Market
  • Government and Public Sector
  • Consumer

By Sales Channel

  • Direct Sales
  • Partner Sales
  • Marketplace
  • OEM

Conclusion & Recommendations

The long-term outlook for the market remains strongly positive, with global revenue projected to expand more than fourfold from USD 1.86 trillion in 2025 to USD 7.54 trillion by 2035. The market is projected to grow at a 13.43% CAGR from 2026 to 2035 . We observed that enterprise connected operations scaling, private 5G infrastructure investment, and rising Asia-Pacific manufacturing digitalization will continue underpinning demand across industrial, commercial, and consumer applications through the forecast period.

Strategic Positioning Recommendations Favor Platform Consolidation

Vendors should prioritize unified IoT platform capability and AI-enabled analytics integration to secure long-term enterprise and government contracts. Our assessment indicates that vendors investing early in digital twin software and IoT security services will be best positioned to capture premium pricing within the Internet of Things (IoT) market.

Investment Attractiveness Is Highest for AI-Enabled Platform Providers

The Internet of Things (IoT) market presents a highly attractive investment case, supported by a USD 5.12 trillion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and Digital Twin Software categories. We found that investment attractiveness is highest for vendors combining AI-enabled platform capability with scaled connectivity infrastructure, positioning them to serve both enterprise and government buyer segments simultaneously.

Market Shifts and Key Risks Require Ongoing Monitoring

Stakeholders should monitor fragmented connectivity standards, data privacy and cross-border data transfer regulatory complexity, and high integration costs for legacy operational technology environments as key risks to the Internet of Things (IoT) market. Our analysis shows that vendors unable to demonstrate unified, standards-compliant platform architecture risk losing enterprise contracts to competitors with certified, interoperable solutions.

Growth Pathways Center on Edge, Security, and Government Expansion

Key growth pathways include expanding IoT Edge Hardware and edge analytics capability, scaling IoT Security Services for enterprise customers, and deepening penetration into Government and Public Sector smart infrastructure programs. NMSC's analysis indicates that vendors pursuing these pathways while maintaining interoperability across fragmented regional standards will be best positioned to capture the Internet of Things (IoT) market's projected growth through 2035.

FAQs

About the Author

Mihul Sharma

Mihul Sharma

Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Diana Trejo

DIANA TREJO

Assistant Manager

Sumitomo Corporation de Mexico, S.A. de C.V.

Recently, we purchased a report on the Mexico Data Center Market from Next Move Strategy Consulting. The service has been excellent, with support that is always timely and thoroughly professional. The information provided is interesting, highly useful, and delivered with clarity. I would highly recommend NextMSC for anyone seeking insightful and dependable analysis.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖