Organic Food Market Global Industry Analysis and Forecast (2026-2035)

Organic Food Market size was USD 323.52 Billion in 2025, projected to reach USD 1,330.27 Billion by 2035, growing at a CAGR of 13.5% from 2026 to 2035. Key drivers include rising consumer health and wellness consciousness, increasing willingness to pay for organic products, and expanding direct-to-consumer and e-commerce distribution, with North America leading the market .

Download Free Sample PDF
Base Year (2025)
$323.52 Billion
Forecast (2035)
$1,330.27 Billion
CAGR (2026-2035)
13.5%
Top Country
North America

What Is the Organic Food Market Size?

The global Organic Food Market size was valued at USD 323.52 billion in 2025 and is estimated at USD 424.20 billion in 2026, forecast to reach USD 1,330.27 billion by 2035, expanding at a 13.5% CAGR between 2026 and 2035. North America leads themarket with approximately 35% revenue share, while Fresh Produce dominates all product categories with approximately 28% share.

We observed that themarket is accelerating across every segmentation axis, with direct-to-consumer digital channels and subscription commerce models driving the most significant structural shifts in themarket through 2035.

Organic Food Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $323.52 Billion
2025
2026 $424.20 Billion
2026
2027 $481.47 Billion
2027
2028 $546.47 Billion
2028
2029 $620.24 Billion
2029
2030 $703.97 Billion
2030
2031 $799.01 Billion
2031
2032 $906.87 Billion
2032
2033 $1,029.30 Billion
2033
2034 $1,168.25 Billion
2034
2035 $1,330.27 Billion
2035

Key Takeaways

By Product Category: Fresh Produce held the largest share of approximately 28% (USD 90.59 billion) in the Organic Food Market in 2025; Beverages is the fastest-growing sub-segment at 17.6% CAGR from 2026–2035.

By Product Form: Fresh held the largest share of approximately 34% (USD 110.00 billion) in 2025; Ambient Liquid is the fastest-growing sub-segment at 16.8% CAGR from 2026–2035.

By Sales Channel: Grocery Retail held the largest share of approximately 52% (USD 168.23 billion) in 2025; Direct-to-Consumer is the fastest-growing sub-segment at 18.3% CAGR from 2026–2035.

By Branding Model: Branded held the largest share of approximately 61% (USD 197.35 billion) in the Organic Food Market in 2025; Private Label is the fastest-growing sub-segment at 15.9% CAGR from 2026–2035.

By End User: Household held the largest share of approximately 68% (USD 219.99 billion) in themarket in 2025; Institutional is the fastest-growing sub-segment at 16.7% CAGR from 2026–2035.

Dominant Region: North America dominated themarket with approximately 35% revenue share (USD 113.23 billion) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 17.5% in themarket during 2026–2035.

Dominant Country: The U.S. led themarket with approximately USD 90.58 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country in the Organic Food Market at approximately 20.5% CAGR from 2026–2035.

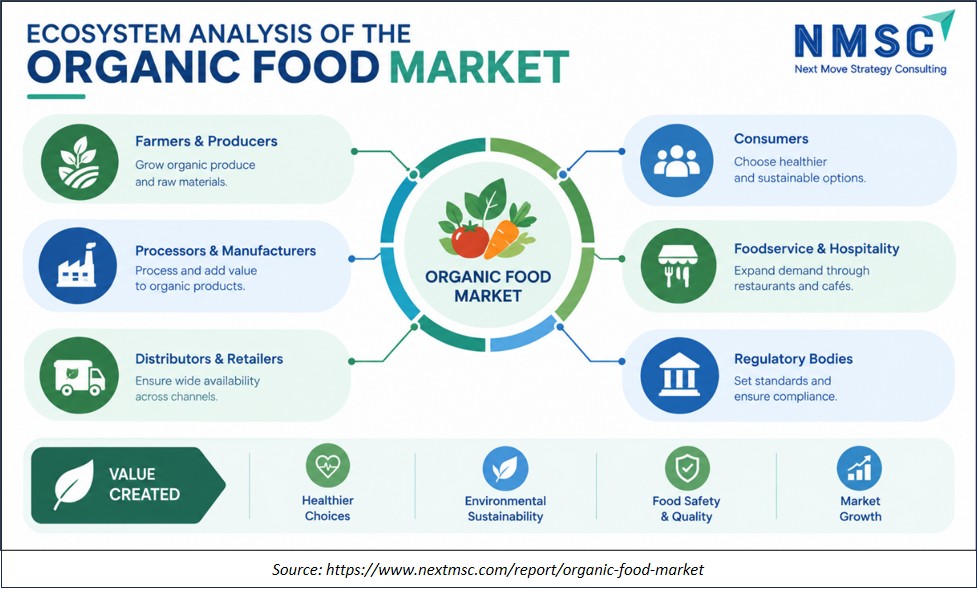
Ecosystem Analysis of the Organic Food Industry

The infographic presents the organic food market ecosystem through six key stakeholder groups: farmers and producers, processors and manufacturers, distributors and retailers, consumers, foodservice and hospitality, and regulatory bodies. It shows how these participants collectively support the movement of organic products from production to consumption while creating value through healthier choices, environmental sustainability, food safety, quality, and market growth .

What Does the Organic Food Market Encompass?

The Organic Food Market encompasses food and beverage products grown, raised, or processed without synthetic pesticides, chemical fertilizers, artificial additives, or genetically modified organisms, certified under national and international organic standards. Our assessment indicates that themarket spans fresh produce, dairy and eggs, meat and seafood, pantry staples, prepared and packaged foods, and beverages, supplied to households, foodservice operators, and institutional buyers through grocery retail, foodservice, direct-to-consumer, and wholesale distribution channels across 38 countries.
Regulatory frameworks including the U.S. Department of Agriculture's National Organic Program and the European Union's Organic Regulation (EU 2018/848) shape labeling , certification, and import equivalency across themarket. We observed that technology adoption is reshaping themarket through blockchain traceability, precision fermentation, and AI-driven supply chain optimization, and NMSC's analysis indicates these capabilities are becoming baseline requirements for premium positioning in the organic food and beverages segment.

Market Drivers & Dynamics

Interactive Dataset
Rising consumer health and wellness consciousness driver +3.2% Global 2026–2035
Expanding direct-to-consumer and e-commerce distribution driver +2.6% North America, Europe, Asia-Pacific 2026–2033
Government subsidies and organic certification support programs driver +1.8% Europe, Asia-Pacific 2026–2035
Growing retailer private label organic programs driver +1.5% Global 2026–2034
Expanding organic farmland and certified supplier base driver +1.2% Asia-Pacific, Latin America 2026–2035
Rising institutional foodservice organic mandates driver +0.9% Europe, North America 2026–2032
Premium price gap limiting mass market penetration restraint −1.8% Global 2026–2035
Supply chain fragmentation and cold chain infrastructure gaps restraint −1.2% Asia-Pacific, Latin America, MEA 2026–2033
Certification fraud and consumer trust erosion risk restraint −0.7% Global 2026–2032
Volatile organic input and certification compliance costs restraint −0.4% Global 2028–2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Organic Food Market?

Rising consumer health and wellness consciousness is the primary driver of themarket. The U.S. Department of Agriculture's Economic Research Service confirms that organic food sales have grown consistently for more than a decade, supported by consumer willingness to pay premiums for products perceived as safer, more nutritious, and environmentally sustainable . We observed that this demand trend is now extending beyond affluent early adopters into mainstream purchasing across themarket, particularly in the fresh produce, dairy, and packaged food segments.

How Is E-Commerce Distribution Driving Organic Food Market Growth?

Expanding direct-to-consumer and e-commerce distribution is acceleratingmarket growth by removing geographic and convenience barriers that previously limited organic food access. Our findings suggest that onlinemarket revenue grew substantially during and after the pandemic and has retained structural gains as subscription box services and digital grocery platforms embed organic options as default or premium tiers. This channel shift benefits themarket by improving brand margin capture and enabling direct consumer data collection.

Growth Inhibitors

What Is Restraining Organic Food Market Expansion?

The persistent premium price gap between organic and conventional products remains the primary restraint onmarket expansion. The U.S. Bureau of Labor Statistics consumer expenditure data confirms that food budget constraints limit organic purchasing frequency among lower- and middle-income households. Our analysis shows that while price gaps are narrowing due to private label growth and scale efficiencies, themarket still faces a significant affordability barrier in price-sensitive markets across Asia-Pacific, Latin America, and the Middle East & Africa.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Fresh Produc
Fruits
Citrus Fruit
Tropical Fru
Other Fruits
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Fresh Produce $10.0 USD Billion $40.0 USD Billion 11.0%
Fruits $17.1 USD Billion $51.1 USD Billion 25.0%
Citrus Fruits $24.2 USD Billion $62.2 USD Billion 19.0%
Tropical Fruits $31.3 USD Billion $73.3 USD Billion 13.0%
Other Fruits $38.4 USD Billion $84.4 USD Billion 22.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Product Category.

Unlock Full Data

Which Product Category Dominates the Organic Food Market?

Fresh Produce led themarket with USD 90.59 billion in 2025, driven by strong consumer preference for organic fruits and vegetables as a first step in organic adoption. Our analysis shows that Beverages is the fastest-growing product category in themarket, registering a 17.6% CAGR from 2026 to 2035, as organic functional drinks and plant-based beverages attract premiumization spending that exceeds other category growth rates.

2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 9.0%
Category B $17.1 USD Billion $51.1 USD Billion 11.0%
Category C $24.2 USD Billion $62.2 USD Billion 21.0%
Category D $31.3 USD Billion $73.3 USD Billion 15.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Product Form.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Grocery Reta
Foodservice
Direct-to-Co
Wholesale Di
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Grocery Retail $10.0 USD Billion $40.0 USD Billion 24.0%
Foodservice $17.1 USD Billion $51.1 USD Billion 10.0%
Direct-to-Consumer $24.2 USD Billion $62.2 USD Billion 8.0%
Wholesale Distribution $31.3 USD Billion $73.3 USD Billion 14.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data

Which Sales Channel Is Reshaping the Organic Food Market?

Grocery Retail remained the largest sales channel in themarket at USD 168.23 billion in 2025, anchored by supermarket and hypermarket distribution depth across North America and Europe. Based on research conducted by NMSC, we found that Direct-to-Consumer is the fastest-growing channel at an 18.3% CAGR from 2026 to 2035, powered by brand websites, online marketplaces, and subscription commerce models that improve margin capture and consumer loyalty across the organic food and vegetables segment.

2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 13.0%
Category B $17.1 USD Billion $51.1 USD Billion 11.0%
Category C $24.2 USD Billion $62.2 USD Billion 25.0%
Category D $31.3 USD Billion $73.3 USD Billion 15.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Branding Model.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Household
Foodservice
Institutiona
Other Commer
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Household $10.0 USD Billion $40.0 USD Billion 26.0%
Foodservice $17.1 USD Billion $51.1 USD Billion 16.0%
Institutional $24.2 USD Billion $62.2 USD Billion 18.0%
Other Commercial $31.3 USD Billion $73.3 USD Billion 8.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data

Which End User Segment Is Most Significant in the Organic Food Market?

Household consumers dominated themarket with USD 219.99 billion in 2025, representing 68% of totalmarket revenue and reflecting the central role of in-home consumption in organic food adoption. Our assessment indicates that Institutional is the fastest-growing end-user segment at a 16.7% CAGR from 2026 to 2035, as schools, hospitals, and corporate cafeterias increasingly mandate certified organic procurement in response to public health policy and ESG commitments.

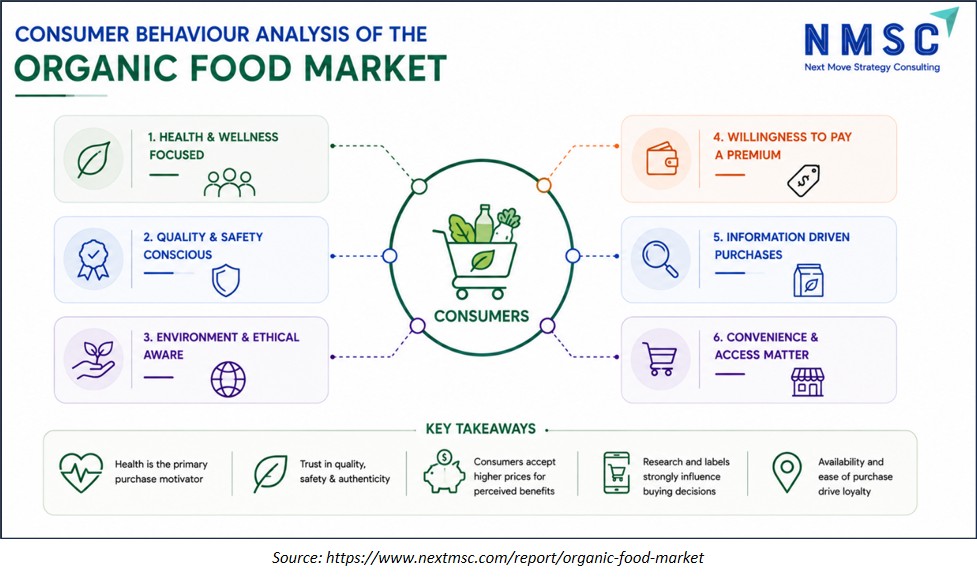
Consumer Behaviour Analysis of the Organic Food Industry

The infographic provides a detailed consumer behavior analysis of the organic food market, centering on six key characteristics that define modern organic shoppers. It illustrates that consumers are primarily driven by health and wellness, quality, and ethical awareness, while also demonstrating a strong willingness to pay a premium for perceived benefits. The analysis further highlights that purchasing decisions are heavily influenced by research, labels, and the convenience of product availability. Ultimately, the key takeaways emphasize that trust in quality and ease of access are essential for driving customer loyalty in this market .

Growth Opportunities

The Organic Food Industry presents three high-priority forward-looking opportunities for brands, retailers, and investors positioning across themarket forecast period 2026–2035.

How Can Subscription Commerce Unlock Organic Food Market Recurring Revenue?

Subscription commerce represents the highest-margin growth pathway, enabling brands to predict demand, reduce waste, and build consumer loyalty simultaneously. Organic food brands that launch curated, auto-replenishment subscription services targeting the household segment can capture higher lifetime customer value than single-transaction models. NMSC's analysis indicates this mechanism is already demonstrating measurable success in North America and is replicable in Europe and Asia-Pacific.

Where Does Institutional Organic Procurement Create New Demand?

Public sector and institutional procurement programs represent a demand pathway for the market. Governments and public authorities in Europe use procurement frameworks and school-food programs that prioritize or incorporate organic products, while institutional procurement activity is also expanding in other markets. Organic food producers and distributors that build institutional supply chain capabilities can secure longer-term contract-based demand in the growing end-user segment .

How Can Organic Beverage Innovation Accelerate Market Premiumization?

Organic beverages are the fastest-growing product category in themarket and represent a premiumization opportunity where consumers consistently accept higher price points than in other organic food categories. Beverage brands introducing functional organic drinks, organic kombucha, and organic plant-based milks can command margins 30 to 50 percent above conventional equivalents. This positions organic beverages as the leading vehicle for margin expansion through 2035.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the Organic Food Market features a moderately fragmented competitive landscape, with diversified food conglomerates competing alongside purpose-built organic brands on certification heritage, supply chain transparency, and consumer trust.

Dimension Description
Market Structure Moderately fragmented; the top companies in this report collectively account for a significant share of global revenue, while numerous regional and specialty brands serve category-specific organic niches.
Innovation Focus Digital traceability, subscription commerce platforms, and organic beverage innovation dominate current product development priorities across themarket.
M&A Activity Selective acquisitions of certified organic brands by large food conglomerates, exemplified by Groupe Lactalis and Danone expanding their organic dairy portfolios through targeted brand investments.

How Do Companies Compete in the Organic Food Market?

Companies compete in themarket primarily on certification credibility, product traceability, and multi-channel distribution reach. Purpose-built organic brands such as Organic Valley and Nature's Path Foods compete on cooperative ownership models and heritage certification, while large diversified companies such as General Mills and Nestlé leverage scale, retail relationships, and R&D investment to expand their presence in themarket across multiple product categories simultaneously.

Which Competitive Archetypes Dominate the Organic Food Market?

Two archetypes are prominent in the Organic Food Market: dedicated organic specialists with deep certification heritage, and diversified food companies with organic brands and portfolio positions. Organic Valley and Nature's Path Foods exemplify the specialist archetype through strong organic brand identities, while General Mills' Annie's brand and Hain's Earth's Best illustrate the diversified-company archetype, leveraging distribution scale and marketing resources to expand organic product availability .

How Are Companies Differentiating Through Innovation in the Market?

Innovation in themarket is increasingly concentrated in three areas: digital traceability platforms that verify organic claims at the product level, subscription commerce models that reduce customer acquisition costs, and organic beverage development that targets premium functionality segments. We observed that companies investing in blockchain-based certification verification are gaining measurable consumer trust advantages in themarket, particularly among millennial and Gen Z organic food buyers who prioritize verifiable sustainability claims.

What M&A Activity Is Shaping the Organic Food Market?

Organic Food Market M&A activity is characterized by large food conglomerates acquiring certified organic brands to accelerate portfolio expansion without building organic certification infrastructure organically. Nestlé and Danone have both pursued selective organic brand acquisitions to strengthen their positions in themarket. Simultaneously, private equity investment in emerging organic brands is increasing, reflecting growing investor confidence in themarket's long-term revenue and margin profile.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping product innovation, distribution strategy, and competitive positioning within the global Organic Food Market.

General Mills, Inc. The Hain Celestial Group, Inc. Dole plc Organic Valley Nature's Path Foods Inc. Arla Foods amba SunOpta Inc. HiPP GmbH & Co. Vertrieb KG Amy's Kitchen, Inc. Groupe Lactalis Aurora Organic Dairy Corporation Driscoll's, Inc. Eden Foods, Inc. Newman's Own, Inc. Sresta Natural Bioproducts Private Limited Lifeway Foods, Inc. Straus Family Creamery Danone S.A. Nestlé S.A. The Kraft Heinz Company

Latest Developments

We found that recent developments in the Organic Food Market reflect continued investment in certification infrastructure, distribution expansion, and product category innovation across themarket's leading companies.

Date Event
May 2026 Nature’s Path launched Love Crunch Dubai Style Chocolate and Dark Chocolate & Blueberry Cream granolas, expanding its premium organic portfolio. The new products use organic whole grains and Fair Trade chocolate, extending the company’s strategy of bringing indulgent, trend-driven flavors into certified organic packaged foods.
May 2026 Earth’s Best launched its first organic snack portfolio specifically designed for children ages four to eight, featuring Organic Crispy Sticks and Organic Veggie Waves.
March 2026 Organic Valley introduced Protein Plus, a line of pasture-raised organic ultra-filtered milk containing 50% more protein and 50% less sugar than regular milk.
June 2025 ITC completed its acquisition of 100% of Sresta Natural Bioproducts, owner of the 24 Mantra Organic brand. Sresta operates across more than 100 organic products, including staples, spices, edible oils, and beverages, with a farmer network spanning about 27,500 farmers and roughly 140,000 acres.

Expert Insights

Ricky Silver

Ricky Silver

CEO | Daily Harvest

"Consumers are more environmentally aware and health-conscious than ever, and organic food, as a byproduct of agricultural practices that holistically improve human and environmental health, is chief among the attributes shoppers look for when making better buying decisions ."

Analyst Interpretation

Thestatement highlights the growing influence of health, wellness, and environmental considerations on organic food purchasing decisions. NMSC’s analysis indicates that consumers are increasingly prioritizing ingredient quality, production practices, perceived health benefits, and sustainability attributes, supporting demand for organic products across fresh produce, dairy, meat, packaged foods, beverages, and other categories. Our findings suggest that manufacturers and retailers strengthening certified organic portfolios, transparent sourcing, and sustainability-focused product positioning will reinforce consumer engagement and support continued expansion of the Organic Food Market .

Investment Opportunities

What Capital Inflows Are Fueling Organic Food Market Development?

Capital investment is accelerating, driven by private equity acquisitions of certified organic brands, venture capital funding for organic subscription commerce platforms, and strategic M&A activity among large food conglomerates expandingmarket portfolio positions. Our findings suggest thatmarket investment activity is concentrated in high-growth sub-segments including organic beverages, direct-to-consumer channels, and institutional foodservice supply, which collectively represent disproportionate return potential within the broadermarket.

How Is Infrastructure Investment Shaping Organic Food Market Expansion?

Infrastructure investment is expanding themarket's addressable opportunity in two ways: organic farmland expansion programs funded by government subsidies in Europe and Asia-Pacific are growing the certified supply base, while cold chain logistics and e-commerce fulfillment infrastructure investment is reducing the distribution cost barriers that have limited penetration in emerging markets. We observed that brands investing in owned distribution infrastructure are capturing structural advantages inmarket margin realization.

What ESG Considerations Influence Organic Food Market Investment?

ESG frameworks are increasingly directing institutional capital toward themarket as organic food production aligns with sustainability, biodiversity, and water quality investment criteria. Our analysis shows thatmarket companies with verified third-party sustainability certifications are attracting lower cost of capital and greater retail shelf priority than conventional food peers. This ESG alignment creates a structural investment tailwind for themarket through 2035, particularly in public market valuations of listed organic food companies.

Key Benefits for Stakeholders

How Does This Report Benefit Organic Food Market Industry Leaders?

Thismarket report provides industry leaders with the segmented revenue forecasts, competitive benchmarking, and regional demand analysis required to prioritize channel investment, product development, and geographic expansion strategies. Our assessment indicates thatmarket leaders can use this report's segmentation analysis and Quick-Stats data to align brand positioning with the fastest-growing product categories, sales channels, and end-user segments identified in this analysis.

How Does This Report Benefit Organic Food Market Investors?

Investors and financial analysts gain a data-driven view ofmarket sizing, CAGR trajectories by segment and region, and competitive positioning across 20 profiled companies to evaluate capital allocation decisions. We found that this report's investment opportunity framework and regional CAGR differentials provide the forecast granularity needed to identify where within themarket the highest risk-adjusted returns are most probable through 2035.

How Does This Report Benefit Market Technology and Product Teams?

Technology vendors and product development teams benefit from this report's detailed segmentation across product form, sales channel, and end-user axes, which clarifies where innovation investment is most commercially viable. Our findings suggest that this report's emerging trends section provides product teams with the foresight needed to prioritize digital traceability, subscription commerce, and organic beverage innovation ahead of competitive adoption curves in themarket.

Key Market Segments Evaluated

By Product Category

  • Fresh Produce 
    • Fruits
      • Citrus Fruits
      • Tropical Fruits
      • Other Fruits
    • Vegetables
      • Leafy Greens
      • Root and Tuber Vegetables
      • Other Vegetables
    • Fresh Herbs
  • Dairy and Eggs 
    • Milk and Cream
    • Yoghurt and Cultured Products
    • Eggs
    • Other Dairy Products
  • Meat, Poultry and Seafood 
    • Red Meat
    • Processed Meat
    • Seafood
    • Other Animal Proteins
  • Pantry Staples 
    • Grains and Flour
    • Pulses and Legumes
    • Nuts and Seeds
    • Edible Oils and Fats
    • Sweeteners
    • Dried Herbs and Spices
    • Other Pantry Staples
  • Prepared and Packaged Foods 
    • Breakfast Cereals
    • Bakery Products
    • Frozen Foods
    • Other Prepared Foods
  • Beverages

By Product Form

  • Fresh
  • Chilled
  • Frozen
  • Ambient Solid
  • Ambient Liquid

By Sales Channel

  • Grocery Retail 
    • Supermarkets and Hypermarkets
    • Mass Merchandisers
  • Foodservice 
    • Restaurants and Cafes
    • Catering
    • Institutional Foodservice
  • Direct-to-Consumer 
    • Brand Websites
    • Online Marketplaces
    • Subscription Commerce
  • Wholesale Distribution

By Branding Model

  • Branded
  • Private Label
  • Contract Manufactured

By End User

  • Household
  • Foodservice
  • Institutional
  • Other Commercial

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico.
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe.
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC.
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA.
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM.

Conclusion & Recommendations

Themarket is projected to expand from USD 424.20 billion in 2026 to USD 1,330.27 billion by 2035 at a 13.5% CAGR, making it one of the highest-growth categories in the global food and beverage industry. We observed that themarket's expansion is structurally supported by regulatory tailwinds, ESG capital flows, and irreversible shifts in consumer values toward health, transparency, and sustainability, all of which provide long-term demand durability well beyond the 2035 forecast horizon.

What Strategic Positioning Should Suppliers Pursue in the Market?

Organic Food Market participants should prioritize building digital-first distribution infrastructure, investing in blockchain-enabled supply chain transparency, and developing subscription commerce models that improve consumer retention. Our findings suggest that brands that combine certified product integrity with a seamless direct-to-consumer purchase experience will command premium pricing resilience and defend market share against private label competition through 2035.

How Attractive Is the Organic Food Market for Investment?

Themarket presents a compelling investment case supported by a USD 906.07 billion absolute dollar opportunity between 2026 and 2035, above-average CAGR across all segments, and strong ESG alignment that is attracting institutional capital at a growing rate. Our assessment indicates that themarket's most attractive investment sub-segments are organic beverages, direct-to-consumer platforms, and institutional supply, each of which is generating a CAGR significantly above 13.5% blended growth rate.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Organic Food Market stakeholders should monitor three primary risk factors: certification fraud that could erode consumer trust in organic labeling , price gap widening that could slow mass market penetration, and supply chain fragmentation that could limit scalability in Asia-Pacific and Latin America. Our analysis shows that companies with owned certification verification technology and diversified supply networks are best positioned to manage these risks through the forecast period.

What Are the Key Growth Pathways for the Organic Food Market?

The Organic Food Market's highest-conviction growth pathways are subscription commerce expansion in direct-to-consumer channels, institutional procurement mandate capitalization in Europe and North America, and organic beverage premiumization in Asia-Pacific. NMSC's analysis indicates that participants pursuing these pathways while maintaining cost competitiveness in grocery retail channels will be best positioned to capture themarket's projected 13.5% CAGR opportunity through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Organic Market & Sales Analysis
  • Historical organic food retail sales and volume analysis across product categories, product forms, and sales channels.
  • Identifies high-growth categories and channels to prioritize for investment and portfolio focus.
Company-Level Organic Sales Volume Analysis
  • Company-level organic food sales volume and revenue benchmarking by product category and branding model, based on annual reports and filings.
  • Shows competitor scale and organic revenue contribution to guide positioning and M&A targeting.
Country-Level Organic Trade Assessment
  • Country-wise import and export analysis of organic food products by category using customs and trade databases.
  • Highlights key sourcing origins and export demand hubs to support supply chain and market entry decisions.
Private Label vs Brand Share Assessment
  • Organic sales split between private label and manufacturer brands by product category and sales channel, drawn from retailer disclosures.
  • Supports branding strategy and retailer partnership decisions by showing where private label is gaining share.
Channel Penetration & Omnichannel Opportunity Mapping
  • Organic sales mapping across supermarkets, specialty stores, online, and direct-to-consumer channels by product form and category.
  • Guides channel prioritization and distribution investment for each product form.
End-User Organic Demand Analysis
  • Organic demand analysis across household, infant and child nutrition, foodservice, and institutional end users by product category, using government surveys and national statistics.
  • Pinpoints priority customer segments and tailors product development and targeting.

FAQs

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖