Polyethylene Resin Market

Polyethylene resin market size was USD 158.40 billion in 2025, and is projected to reach USD 263.80 billion by 2035 at a 5.2% CAGR from 2026 to 2035 globally.

Download Free Sample PDF
Base Year (2025)
$158.40 Billion
Forecast (2035)
$263.80 Billion
CAGR (2026-2035)
5.2%
Top Region
Asia-Pacific

What Is the Polyethylene Resin Market Size?
The global polyethylene resin market size was valued at USD 158.40 billion in 2025 and is estimated at USD 166.60 billion in 2026, forecast to reach USD 263.80 billion by 2035, expanding at a 5.2% CAGR between 2026 and 2035. Asia-Pacific leads with approximately a 43% share, while HDPE dominates all other resin types, also with approximately a 43% share.

We observed that growth is broad-based across every segmentation axis, with pipe-grade HDPE and mono-material flexible packaging film adoption driving the dominant structural shifts through 2035.

Polyethylene Resin Market Revenue Forecast
Values in USD Billion

2025 $158.40 Billion
2025
2026 $166.64 Billion
2026
2027 $175.30 Billion
2027
2028 $184.42 Billion
2028
2029 $194.01 Billion
2029
2030 $204.10 Billion
2030
2031 $214.71 Billion
2031
2032 $225.87 Billion
2032
2033 $237.62 Billion
2033
2034 $249.98 Billion
2034
2035 $263.80 Billion
2035

Key Takeaways

By Type: HDPE held the largest share of approximately 43% (USD 68.11 billion) in 2025; LLDPE is the fastest-growing sub-segment at 7.4% CAGR from 2026–2035.

By Application: Packaging Films held the largest share of approximately 38% (USD 60.19 billion) in 2025; Pipes and Fittings is the fastest-growing sub-segment at 6.7% CAGR from 2026–2035.

By End Use Industry: Packaging held the largest share of approximately 46% (USD 72.86 billion) in 2025; Electrical and Electronics is the fastest-growing sub-segment at 7.2% CAGR from 2026–2035.

By Process: Extrusion held the largest share of approximately 48% (USD 76.03 billion) in 2025; Rotational Molding is the fastest-growing sub-segment at 7.9% CAGR from 2026–2035.

By Distribution Channel: Direct Sales held the largest share of approximately 62% (USD 98.21 billion) in 2025; Online Sales is the fastest-growing sub-segment at 11.3% CAGR from 2026–2035.

Dominant Region: Asia-Pacific dominated with approximately 43% revenue share (USD 68.11 billion) in 2025.

Fastest-Growing Region: Middle East & Africa is expected to register the highest CAGR of 8.6% during 2026–2035.

Dominant Country: China led with approximately USD 39.60 billion in 2025.

Fastest-Growing Country: Saudi Arabia is the fastest-growing country at approximately 9.9% CAGR from 2026–2035.

Market Opportunity: The polyethylene resin market is expected to create an absolute dollar opportunity of USD 97.20 billion between 2026 and 2035, presenting significant investment potential across the packaging, infrastructure, and mobility value chain.

According to NMSC analysis, resin producers are increasingly consolidating polymerization capacity with fewer, feedstock-integrated complexes to secure low-cost ethane and naphtha supply, a shift that favors diversified, geographically balanced producers over single-site specialists as regional trade and tariff dynamics evolve through 2035.

What Does the Polyethylene Resin Market Encompass?
The polyethylene resin market encompasses the production and supply of thermoplastic resins polymerized from ethylene monomer, including high-density polyethylene, low-density polyethylene, and linear low-density polyethylene grades supplied to converters, brand owners, and industrial fabricators. Our assessment indicates that the scope spans film, blow molding, injection molding, pipe, and wire and cable grades consumed across packaging, construction, automotive, agriculture, consumer goods, and electrical and electronics end markets worldwide. The category has evolved from a commodity thermoplastic into a performance-engineered material class, driven by lightweighting demands, recyclability mandates, and premiumization of flexible packaging formats.
Regulatory frameworks such as the European Union's Packaging and Packaging Waste Regulation and the U.S. Environmental Protection Agency's plastics recycling initiatives shape recyclable and recycled-content resin specifications, while the Association of Plastic Recyclers' design guidelines increasingly influence mono-material adoption. We observed that technology adoption is shifting toward advanced and chemical recycling routes that convert post-consumer plastic waste into virgin-quality feedstock. NMSC's analysis indicates that this structural shift, combined with Middle East capacity expansion, is redefining global trade flows across the polyethylene resin market.

Supply Chain Structure of the Polyethylene Resin Industry

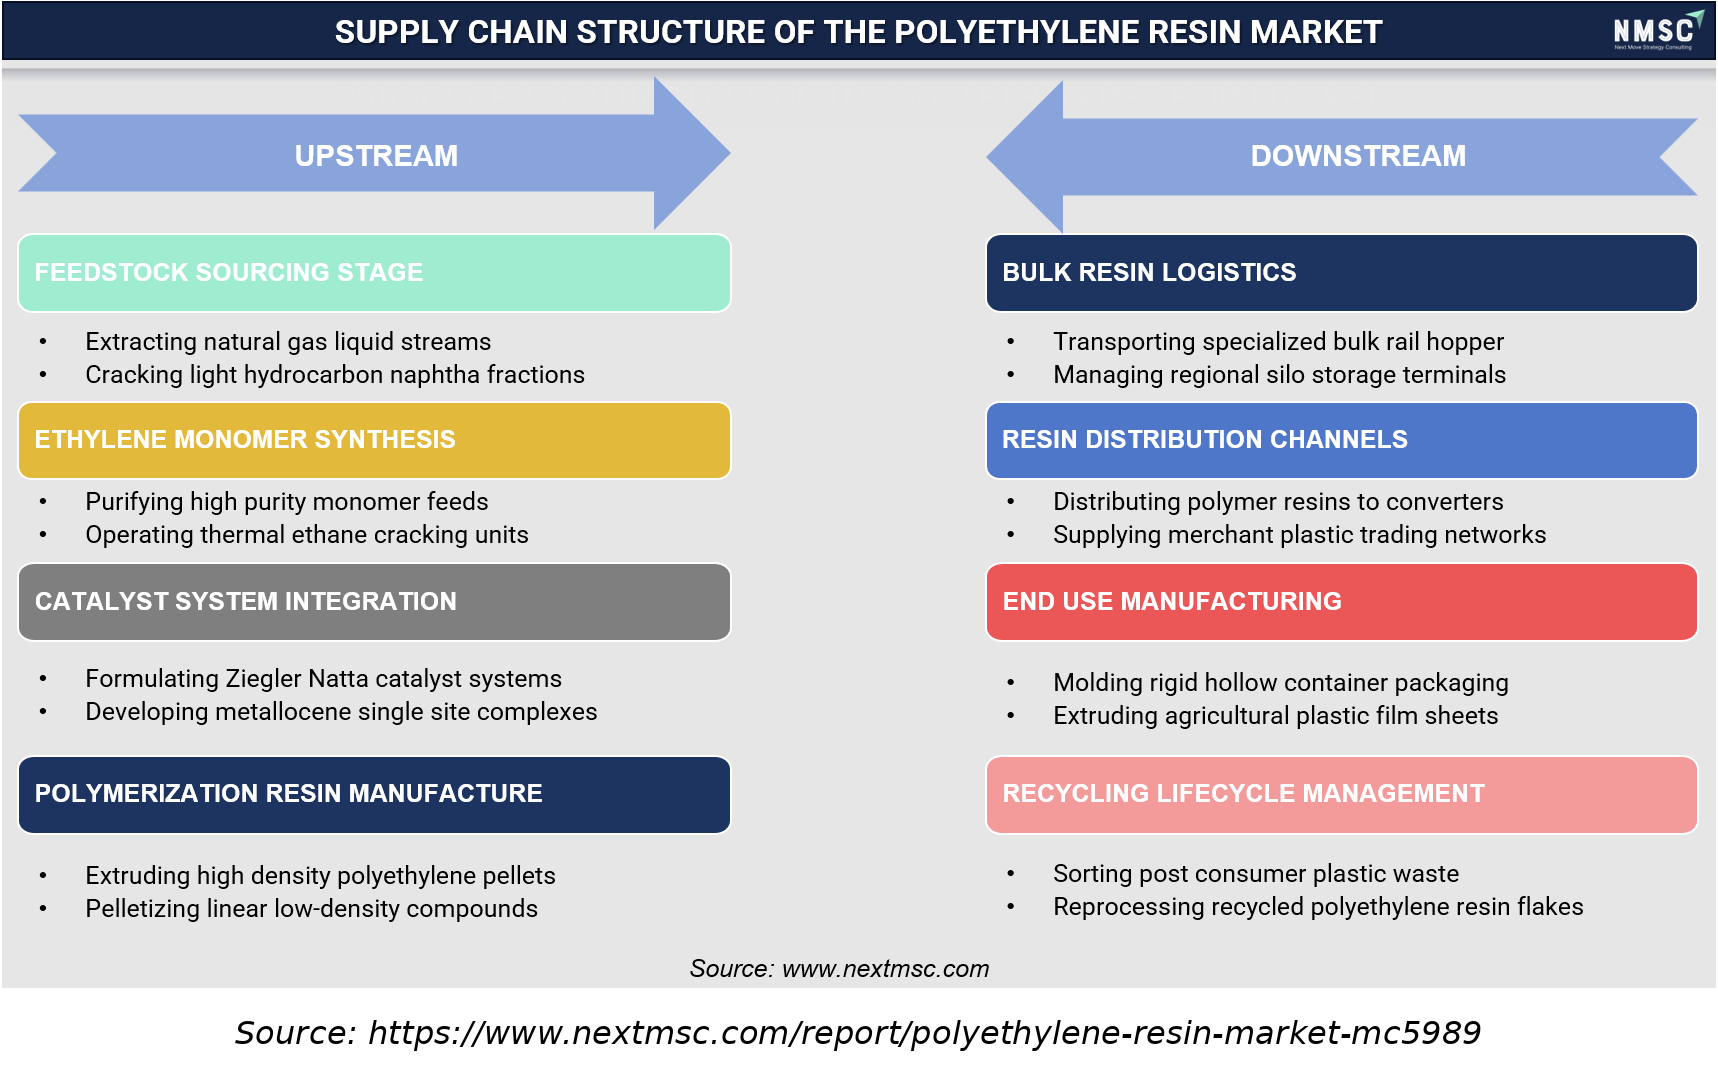
Supply Chain Structure of the Polyethylene Resin Industry
Based on research conducted by NMSC, we found that the supply chain structure of the Polyethylene Resin Market links feedstock extraction, ethylene monomer synthesis, catalyst integration, and pellet polymerization with bulk resin rail logistics. Downstream, distribution channels supply resin to converters for molding rigid containers and extruding agricultural films. Ultimately, sorting post-consumer plastic waste and reprocessing recycled resin flakes complete a sustainable circular lifecycle.
Market Drivers & Dynamics

Interactive Dataset
Rising global packaging and flexible film demand driver +1.6% Global 2026-2035
Expansion of water and gas pipeline infrastructure driver +1.1% Asia-Pacific, Middle East & Africa 2026-2035
Growth of e-commerce and protective packaging driver +0.9% Global 2026-2032
Middle East petrochemical capacity expansion driver +0.8% Middle East & Africa 2026-2033
Rising adoption of mono-material recyclable PE films driver +0.6% Europe, North America 2026-2035
Automotive lightweighting and EV wire and cable demand driver +0.5% Global 2026-2035
Crude oil and naphtha feedstock price volatility restraint -1.0% Global 2026-2035
Tightening single-use plastic and EPR regulations restraint -0.7% Europe 2026-2035
Competition from polypropylene and paper substitutes restraint -0.4% North America, Europe 2026-2032
Overcapacity-driven margin compression among converters restraint -0.3% Asia-Pacific 2026-2030
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Polyethylene Resin Market?

Rising global demand for flexible packaging films is the primary driver of the market. The U.S. Environmental Protection Agency's plastics data continues to show packaging as the largest end use for polyethylene resin in developed economies. We observed that this consumption base, reinforced by e-commerce-driven protective packaging growth, continues to anchor baseline demand for LLDPE and LDPE film grades across developed and emerging economies alike.

How Is Infrastructure Investment Driving Polyethylene Resin Market Growth?
Expanding water distribution, gas distribution, and irrigation infrastructure is accelerating demand for HDPE pipe-grade resin worldwide. Government-backed water infrastructure programs tracked by national statistical agencies continue to fund pipeline replacement and expansion projects across Asia-Pacific and the Middle East. Our assessment indicates that this infrastructure-driven pull, combined with gas distribution network expansion, is sustaining above-average growth for pipe and fitting applications through 2035.

Growth Inhibitors

What Is Restraining Polyethylene Resin Market Expansion?
Volatility in crude oil and naphtha feedstock pricing restrains margin stability across the polyethylene resin value chain. The U.S. Energy Information Administration tracks recurring petrochemical feedstock price swings that compress producer margins and delay capital investment in new cracker capacity. We found that smaller regional producers face particular exposure, as limited feedstock integration reduces their ability to hedge input costs compared with larger, vertically integrated petrochemical groups.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
HDPE 2025: $68.11 Billion | 2035: $105.52 Billion
HDPE
LDPE 2025: $38.02 Billion | 2035: $52.76 Billion
LDPE
LLDPE 2025: $42.77 Billion | 2035: $87.05 Billion
LLDPE
Other Types 2025: $9.50 Billion | 2035: $18.47 Billion
Other Types
HDPE $68.11 Billion $105.52 Billion 4.5%
LDPE $38.02 Billion $52.76 Billion 3.3%
LLDPE $42.77 Billion $87.05 Billion 7.4%
Other Types $9.50 Billion $18.47 Billion 6.9%

Which Type Segment Dominates the Polyethylene Resin Market?

HDPE, encompassing blow molding, injection molding, and pipe grades, led the market with USD 68.11 billion in 2025, supported by its chemical resistance, rigidity, and broad compatibility with pipe, container, and film applications. We observed that LLDPE is the fastest-growing type, expanding at a 7.4% CAGR from 2026 to 2035, as flexible packaging converters increasingly specify LLDPE film grades for stretch film, liners, and heavy-duty sack applications.

2025 (USD Billion)
2035 (USD Billion)
Packaging Fi
Blow Molded
Injection Mo
Pipes and Fi
Wire and Cab
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Packaging Films $10.0 USD Billion $40.0 USD Billion 18.0%
Blow Molded Products $17.1 USD Billion $51.1 USD Billion 16.0%
Injection Molded Products $24.2 USD Billion $62.2 USD Billion 22.0%
Pipes and Fittings $31.3 USD Billion $73.3 USD Billion 12.0%
Wire and Cable Insulation $38.4 USD Billion $84.4 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data

Which Application Segment Leads Polyethylene Resin Market Demand?

Packaging Films remained the leading application within the market, valued at USD 60.19 billion in 2025 on sustained flexible packaging, stretch film, and liner consumption. Our findings suggest that Pipes and Fittings is the fastest-growing application, registering a 6.7% CAGR from 2026 to 2035, as water distribution and gas pipeline infrastructure programs increasingly specify HDPE pipe systems to replace aging metallic networks across developed and emerging economies.

2025 (USD Billion)
2035 (USD Billion)
Packaging
Construction
Agriculture
Automotive
Consumer Goo
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Packaging $10.0 USD Billion $40.0 USD Billion 15.0%
Construction $17.1 USD Billion $51.1 USD Billion 13.0%
Agriculture $24.2 USD Billion $62.2 USD Billion 23.0%
Automotive $31.3 USD Billion $73.3 USD Billion 9.0%
Consumer Goods $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End Use Industry.

Unlock Full Data

Which End Use Industry Leads Polyethylene Resin Consumption?

Packaging remained the dominant end use industry, reaching USD 72.86 billion in 2025 due to sustained food, consumer goods, and e-commerce packaging consumption. Based on research conducted by NMSC, we found that Electrical and Electronics is the fastest-growing end use industry at a 7.2% CAGR from 2026 to 2035, reflecting rising demand for polyethylene wire and cable insulation tied to grid expansion and electric vehicle charging infrastructure buildout.

2025 (USD Billion)
2035 (USD Billion)
Extrusion
Injection Mo
Blow Molding
Rotational M
Others
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Extrusion $10.0 USD Billion $40.0 USD Billion 16.0%
Injection Molding $17.1 USD Billion $51.1 USD Billion 26.0%
Blow Molding $24.2 USD Billion $62.2 USD Billion 8.0%
Rotational Molding $31.3 USD Billion $73.3 USD Billion 18.0%
Others $38.4 USD Billion $84.4 USD Billion 21.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Process.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct Sales
Distributors
Online Sales
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Sales $10.0 USD Billion $40.0 USD Billion 25.0%
Distributors $17.1 USD Billion $51.1 USD Billion 19.0%
Online Sales $24.2 USD Billion $62.2 USD Billion 25.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Distribution Channel.

Unlock Full Data

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the polyethylene resin market over the 2026-2035 forecast period.

How Can Circular and Bio-Based Resin Systems Unlock Value for Brand Owners?

Certified circular and bio-based polyethylene systems present a whitespace opportunity for consumer goods and food packaging brand owners pursuing decarbonization targets. Producers that scale advanced recycling and mass-balance certified renewable capacity stand to capture premium pricing as brands shift toward recycled-content packaging commitments, particularly across food, beverage, and personal care packaging categories seeking differentiated, sustainability-led resin sourcing.

Where Does HDPE Pipe Infrastructure Create New Demand in the Polyethylene Resin Market?

Water and gas utilities represent an underpenetrated opportunity for HDPE pipe resin engineered to long-service-life infrastructure standards. Producers that develop validated, high-pressure pipe grades for utility and irrigation networks can secure long-term supply contracts with municipal and industrial end users, benefiting from recurring replacement-cycle revenue tied to aging pipeline infrastructure across North America and Europe.

How Can Mono-Material Film Structures Benefit Flexible Packaging Converters?

Mono-material polyethylene film structures create an opportunity for resin suppliers and converters offering recyclable, single-polymer laminate alternatives. Early movers that secure Association of Plastic Recyclers or RecyClass validation for mono-material film systems can differentiate with flexible packaging converters pursuing circular packaging commitments across their branded product portfolios.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

PESTEL Analysis of the Polyethylene Resin Industry

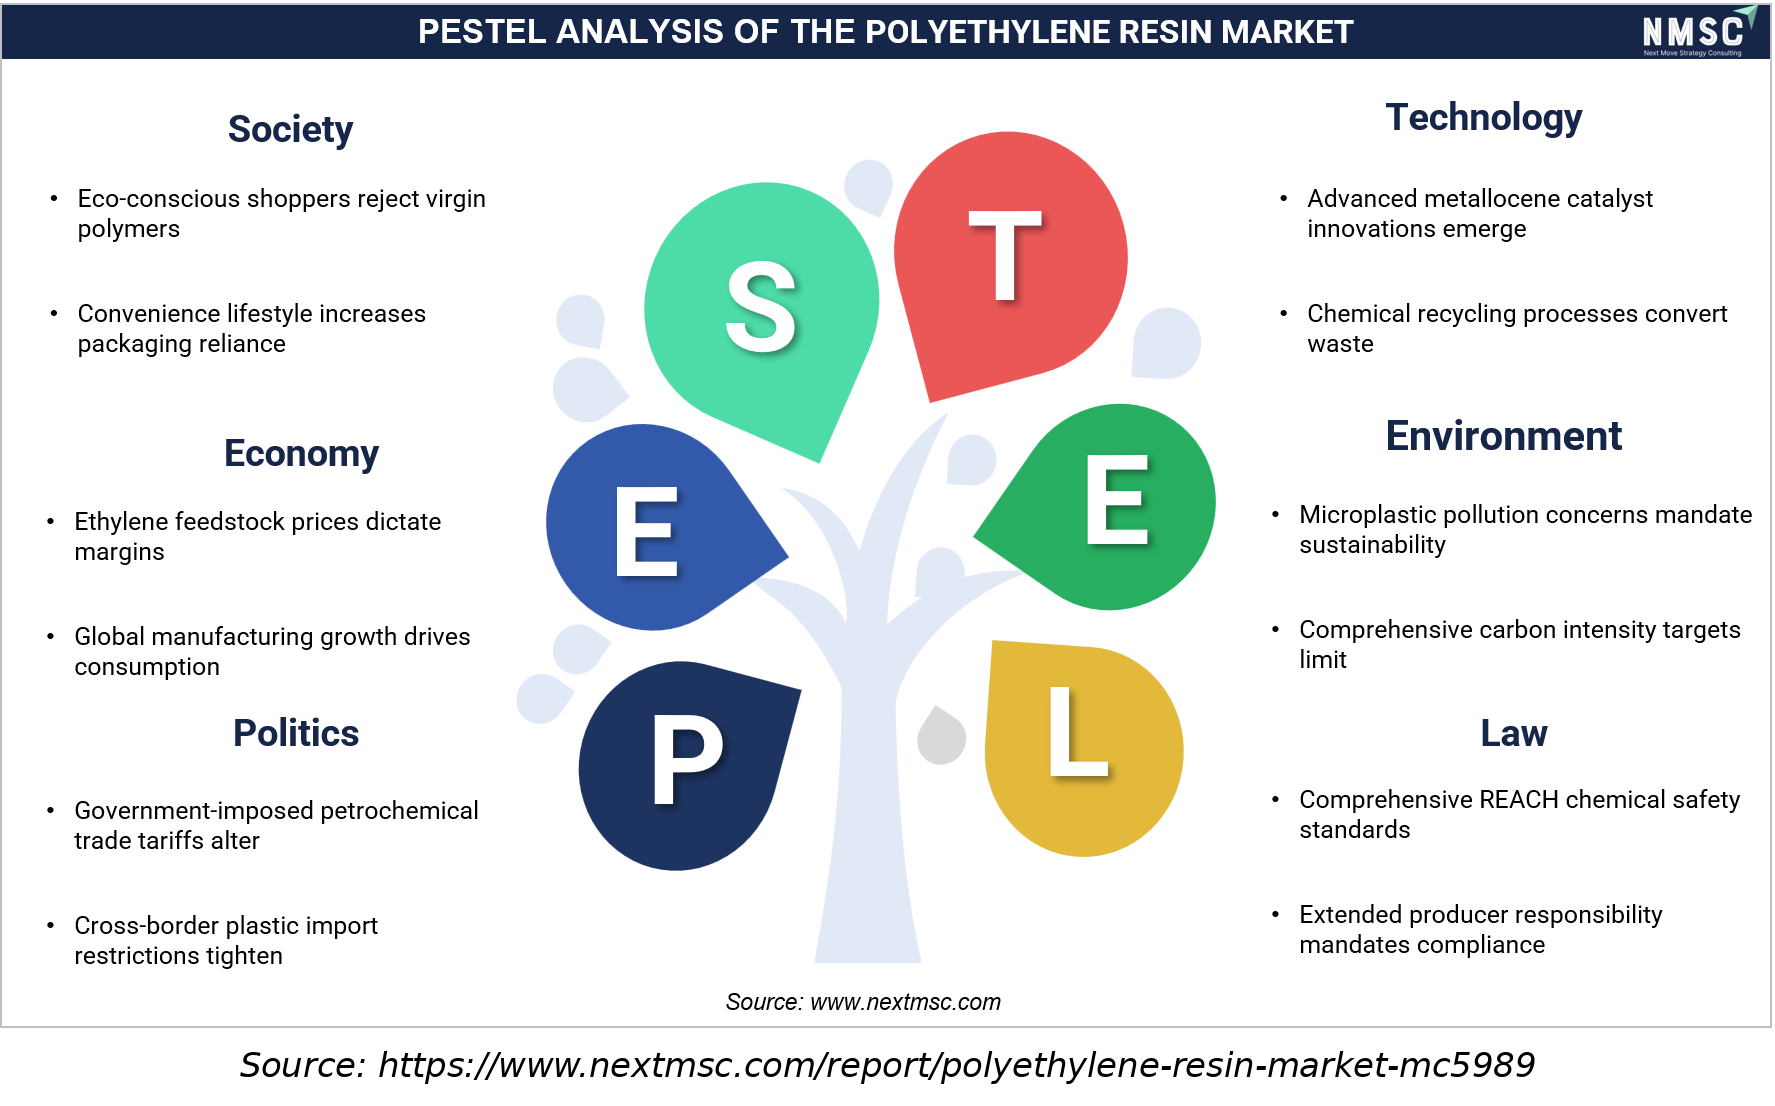
PESTEL Analysis of the Polyethylene Resin Industry
NMSC's analysis indicates that societal shifts toward eco-conscious packaging alongside global manufacturing growth drive the Polyethylene Resin Market. Furthermore, advanced metallocene catalysts and chemical recycling technologies enhance operational capabilities. Concurrently, fluctuating ethylene feedstock costs impact profit margins, while strict REACH safety standards, government trade tariffs, microplastic pollution mandates, and extended producer responsibility regulations enforce strict legal compliance worldwide.

Competitive Landscape

We found that the polyethylene resin market remains moderately consolidated, with large integrated petrochemical groups competing alongside regional producers across the industry.

Dimension Description
Market Structure Moderately consolidated, led by vertically integrated petrochemical majors with feedstock-to-resin capacity, alongside regional national oil company-backed producers.
Innovation Focus Chemical recycling, mono-material film technology, and mass-balance certified bio-based and circular resin platforms.
M&A Activity Feedstock integration, advanced recycling partnerships, and Middle East joint-venture capacity consolidation.

How Do Companies Compete in the Polyethylene Resin Market?

Companies compete primarily on feedstock cost advantage, recyclability credentials, and production scale across the industry. Global players such as LyondellBasell and ExxonMobil leverage integrated ethylene-to-polyethylene complexes to serve multinational converters, while Middle East producers compete on low-cost ethane feedstock and export-oriented capacity supplied to Asia-Pacific and African packaging and construction markets.

Which Competitive Archetypes Dominate the Polyethylene Resin Market?

Two archetypes dominate the market: diversified global petrochemical majors offering full-service technical and regulatory support, and integrated regional producers focused on large-scale, cost-competitive commodity resin. LyondellBasell and Dow exemplify the diversified archetype through integrated feedstock-to-resin manufacturing, while Borouge and SABIC exemplify the regional cost-leadership archetype serving Asia-Pacific and African export demand.

How Are Companies Differentiating Through Innovation in Polyethylene Resin?

Innovation and differentiation strategy increasingly center on chemical recycling and mono-material film engineering. Borealis' Borstar Nextension platform and Dow's mono-polyethylene packaging solutions both target recyclability certification to secure long-term brand owner contracts. Our analysis shows that producers unable to demonstrate credible circularity pathways risk exclusion from brand owner request-for-proposal shortlists in Europe and North America.

What M&A and Expansion Activity Is Shaping the Polyethylene Resin Market?

Mergers, acquisitions, and capacity expansion continue to consolidate resin production capabilities within the industry. Dow's equity investment in advanced recycler Xycle broadened its circular feedstock access, while OMV and ADNOC's continued integration of Borouge Group International illustrates how diversified groups pursue geographic expansion and feedstock-cost leverage across packaging, construction, and mobility end markets.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping capacity expansion, feedstock strategy, and circularity investment within the global polyethylene resin market.

LyondellBasell Industries N.V. ExxonMobil Corporation Dow Inc. Saudi Basic Industries Corporation (SABIC) China Petroleum & Chemical Corporation (Sinopec) Chevron Phillips Chemical Company LLC INEOS Group Holdings S.A. Borealis AG TotalEnergies SE Braskem S.A. Reliance Industries Limited Formosa Plastics Corporation Westlake Chemical Corporation NOVA Chemicals Corporation PetroChina Company Limited Indorama Ventures Public Company Limited LG Chem Ltd. Sasol Limited Mitsui Chemicals, Inc. PTT Global Chemical Public Company Limited

Latest Developments

We found that recent capacity and product developments within the polyethylene resin market are concentrated on circular feedstock integration and recyclable resin technology, reflecting the industry's broader sustainability transition.

Date Event
September 2025 Borealis launched its proprietary Borstar Nextension Polyethylene technology platform featuring single-site catalysts. The advanced technology enhances toughness, sealing performance, and processability in flexible packaging. It enables product downgauging, mono-material designs for circular recycling, and cost efficiency, supporting strict European Union packaging and packaging waste regulations.
September 2025 NOVA Chemicals launched polyethylene resins featuring next-generation non-fluorinated polymer processing aids across its SURPASS, SCLAIR, and NOVAPOL product lines. The formulation delivers enhanced melt fracture clearing, frost line control, and processing stability while enabling film converters and brand owners to comply with global regulations phasing out fluoropolymer additives.

Investment Opportunities

What Capital Inflows Are Targeting the Polyethylene Resin Market?

Capital inflows into the polyethylene resin market are increasingly directed toward advanced recycling and circular feedstock capacity. Strategic acquirers continue to fund recycling technology consolidation, as seen in Dow's investment in Xycle and earlier acquisition of Circulus. We observed that investors favor producers demonstrating validated circularity credentials, viewing regulatory alignment as a proxy for long-term contract retention with multinational brand owners.

How Is Infrastructure Investment Supporting Polyethylene Resin Manufacturing?

Infrastructure investment is expanding integrated cracker and polymerization capacity across the Middle East and Asia-Pacific to serve rising export demand. Our findings suggest that regional producers are investing in world-scale polymer complexes to improve feedstock integration, supporting the cost competitiveness required for HDPE and LLDPE grade production at global scale.

What ESG Considerations Are Shaping Polyethylene Resin Investment Decisions?

Environmental, social, and governance considerations are central to investment decisions across the industry, with feedstock decarbonization and recycled-content sourcing as key criteria. The U.S. Environmental Protection Agency's plastics recycling data continues to inform brand owner sustainability disclosures. We found that investors increasingly favor producers with third-party circularity certification, treating it as a governance indicator alongside safety and emissions compliance.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and capacity-planning decisions across the polyethylene resin industry. Our analysis shows that detailed type, application, and process breakdowns help procurement teams align specifications with regulatory and sustainability requirements while identifying underserved end use segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the polyethylene resin supply chain. We observed that the report's regional and segment-level growth differentials help identify which producers and geographies are best positioned to capture above-market growth in pipe, film, and specialty resin categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging resin design requirements, including chemical recycling integration, mono-material film engineering, and bio-based feedstock adoption, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around recyclability certification and specialty grade development increasingly required by brand owner request-for-proposal processes.

Key Market Segments Evaluated

By Type

  • HDPE
  • LDPE
  • LLDPE
  • Other Types

By Application

  • Packaging Films
  • Blow Molded Products
  • Injection Molded Products
  • Pipes and Fittings
  • Wire and Cable Insulation
  • Others

By End Use Industry

  • Packaging
  • Construction
  • Agriculture
  • Automotive
  • Consumer Goods
  • Electrical and Electronics
  • Others

By Process

  • Extrusion
  • Injection Molding
  • Blow Molding
  • Rotational Molding
  • Others

By Distribution Channel

  • Direct Sales
  • Distributors
  • Online Sales

HDPE

Blow Molding Grade
Injection Molding Grade
Pipe Grade
Film Grade

LDPE

Film Grade
Extrusion Coating Grade
Injection Molding Grade

LLDPE

Film Grade
Rotomolding Grade
Wire and Cable Grade
Other Types
UHMWPE
MDPE
VLDPE
By Application
Packaging Films
Blow Molded Products
Injection Molded Products
Pipes and Fittings
Wire and Cable Insulation
Others
By End Use Industry
Packaging
Construction
Agriculture
Automotive
Consumer Goods
Electrical and Electronics
Others
By Process
Extrusion
Injection Molding
Blow Molding
Rotational Molding
Others
By Distribution Channel
Direct Sales
Distributors
Online Sales
By Region
North America: U.S., Canada, Mexico
Europe: UK, Germany, France, Italy, Spain, Sweden, Denmark, Finland, Netherlands, Rest of Europe
Asia-Pacific: China, India, Japan, South Korea, Taiwan, Indonesia, Vietnam, Australia, Philippines, Malaysia, Rest of APAC
Middle East & Africa: Saudi Arabia, UAE, Egypt, Israel, Turkey, Nigeria, South Africa, Rest of MEA
Latin America: Brazil, Argentina, Chile, Colombia, Rest of LATAM

Conclusion & Recommendations

The long-term outlook for the market remains positive, with global revenue projected to grow from USD 158.40 billion in 2025 to USD 263.80 billion by 2035 at a 5.2% CAGR. We observed that sustained packaging demand, infrastructure-driven pipe consumption, and circular resin adoption will continue underpinning growth across packaging, construction, and automotive applications through the forecast period.

What Strategic Positioning Should Polyethylene Resin Producers Pursue?

Producers should prioritize feedstock-integrated capacity and chemical recycling investment while pursuing Association of Plastic Recyclers or RecyClass certification to secure long-term brand owner contracts. Our assessment indicates that producers investing early in circular feedstock capability and mono-material film technology will be best positioned to capture premium pricing within the polyethylene resin market.

How Attractive Is the Polyethylene Resin Market for New Investment?

The polyethylene resin industry presents an attractive investment case, supported by a USD 97.20 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Middle East & Africa and pipe application categories. We found that investment attractiveness is highest for producers combining feedstock-cost advantage with scaled circular capacity, positioning them to serve both cost-sensitive and premium packaging segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor feedstock-price volatility, tightening single-use plastic regulations, and overcapacity-driven margin compression as key risks to the polyethylene resin market. Our analysis shows that producers unable to adapt to recycled-content specifications risk losing shelf space to competitors with certified circular platforms, particularly within Europe's increasingly regulated packaging environment.

What Are the Key Growth Pathways for the Polyethylene Resin Market?

Key growth pathways include expanding chemical recycling capacity, scaling bio-based and mass-balance certified resin production, and deepening penetration into pipe and wire and cable applications. NMSC's analysis indicates that producers pursuing these pathways while maintaining cost competitiveness in standard resin categories will be best positioned to capture the polyethylene resin market's projected growth through 2035.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖