Railway Signalling System Market

Railway Signalling System Market size was USD 26.48 billion in 2025, projected to reach USD 65.32 billion by 2035, growing at a CAGR of 9.45% from 2026 to 2035. Key drivers include European ERTMS deployment mandates, increasing adoption of digital signalling systems, and long-term infrastructure framework contracting, with Asia-Pacific leading the market .

Download Free Sample PDF
Base Year (2025)
$26.48 Billion
Forecast (2035)
$65.32 Billion
CAGR (2026-2035)
9.5%
Top Country
Asia-Pacific

What Is the Railway Signalling System Market Size?

The global railway signalling system market size was valued at USD 26.48 billion in 2025 and is estimated at USD 28.98 billion in 2026, projected to reach USD 65.32 billion by 2035, growing at a CAGR of 9.45% from 2026 to 2035. Asia-Pacific led the market with an approximate 42% revenue share in 2025, while the Hardware component segment dominated at roughly 58% share.

Our findings suggest that the following key takeaways summarize the market's segment-level and geographic dynamics as of 2025.

Railway Signalling System Market Revenue Forecast

Values in USD Billion

2025 $26.48 Billion
2025
2026 $28.98 Billion
2026
2027 $31.72 Billion
2027
2028 $34.72 Billion
2028
2029 $38.00 Billion
2029
2030 $41.59 Billion
2030
2031 $45.52 Billion
2031
2032 $49.82 Billion
2032
2033 $54.53 Billion
2033
2034 $59.68 Billion
2034
2035 $65.32 Billion
2035

Key Takeaways

By Component: Hardware held the largest share, expanding from USD 15.36 billion in 2025 to USD 31.35 billion by 2035, representing approximately 58% of the market; Software is the fastest-growing sub-segment at 14.0% CAGR from 2026–2035.

By Technology: Interlocking held the largest share, accounting for approximately 26% of the market with revenue of USD 6.89 billion in 2025; Signaling Communications is the fastest-growing sub-segment at 14.5% CAGR from 2026–2035.

By Deployment Type: Modernization and Retrofit (Brownfield) held the largest share, accounting for approximately 56% of the market with revenue of USD 14.83 billion in 2025; New Installation (Greenfield) is the fastest-growing sub-segment at 11.3% CAGR from 2026–2035.

By Application: Wayside and Trackside Systems held the largest share, accounting for approximately 34% of the market with revenue of USD 9.00 billion in 2025; Onboard Train Systems is the fastest-growing sub-segment at 13.6% CAGR from 2026–2035.

By End Use: Mainline Rail held the largest share, accounting for approximately 54% of the market with revenue of USD 14.30 billion in 2025; Urban Transit is the fastest-growing sub-segment at 11.3% CAGR from 2026–2035.

Dominant Region: Asia-Pacific dominated with approximately 42% revenue share in 2025, generating USD 11.12 billion in market revenue.

Fastest-Growing Region: Latin America is expected to register the highest CAGR of 12.6% during 2026–2035.

Dominant Country: China led the market with revenue of USD 4.45 billion in 2025, supported by extensive railway infrastructure and ongoing signaling modernization.

Fastest-Growing Country: India is the fastest-growing country, registering a CAGR of 13.0% during 2026–2035, supported by railway modernization and network expansion.

Market Opportunity: The railway signalling system market presents an absolute dollar opportunity of approximately USD 36.34 billion between 2026 and 2035, calculated as the difference between the 2035 forecast value and the 2026 base value, an investment window favoring vendors scaling ETCS Level 2 digital signalling and FRMCS-ready communications infrastructure.

According to NMSC analysis, we found that the gap between Europe's accelerating ERTMS deployment framework agreements and the still-limited pool of qualified signalling contractors is widening the addressable market for suppliers with proven multi-corridor delivery capability, even as national infrastructure managers pursue cost discipline through long-term volume commitments.
Ecosystem Analysis of the Railway Signalling System Industry

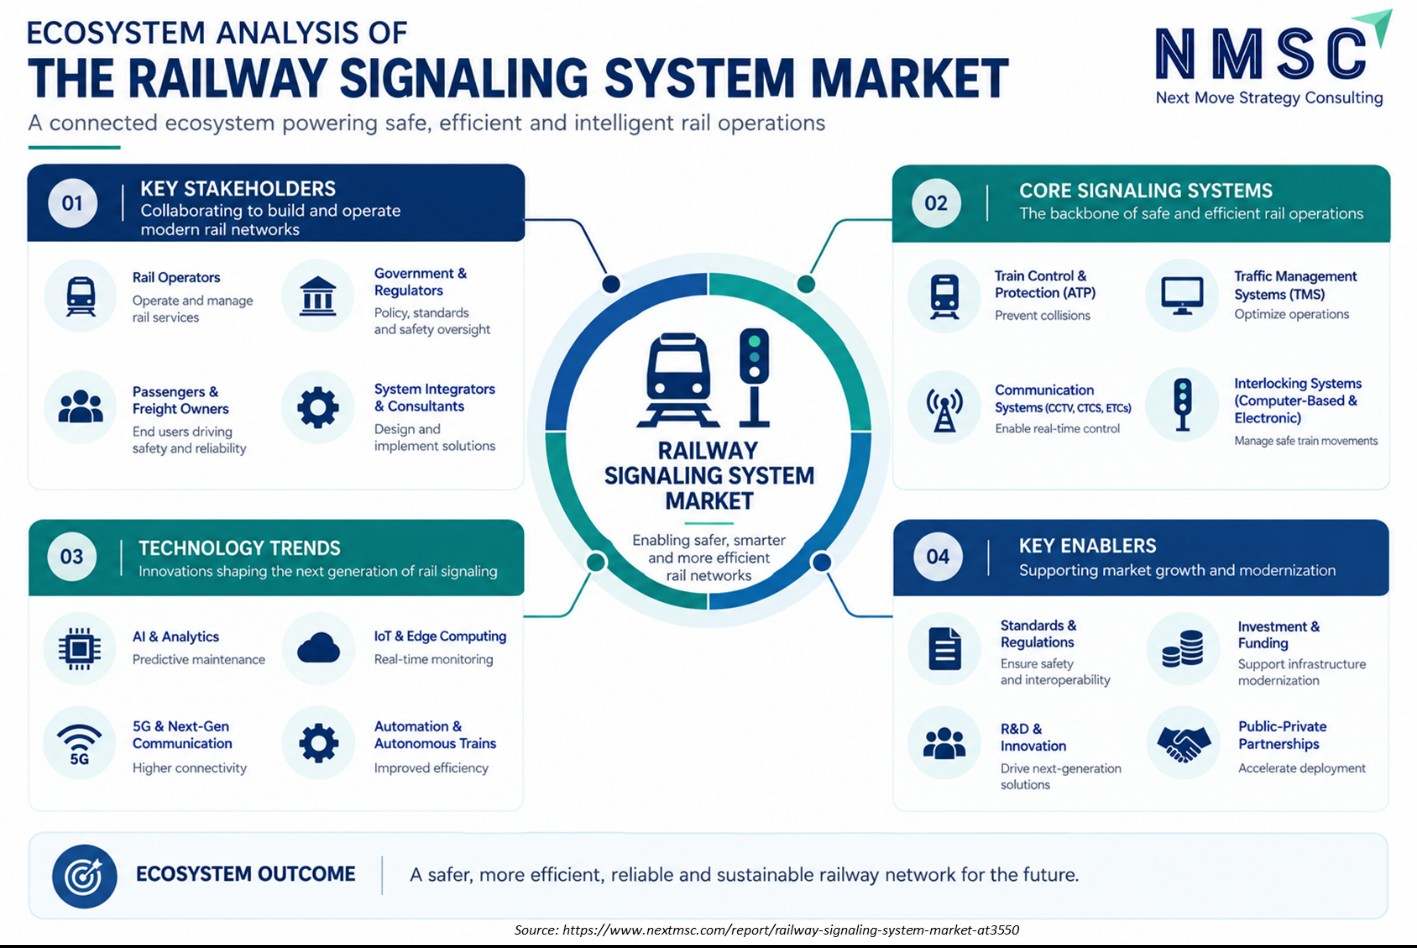
The above infographic presents a detailed ecosystem analysis of the railway signaling system market, mapping out the key stakeholders, market drivers, and core signaling technologies. It highlights how digital transformation and AI are emerging as crucial technology trends alongside critical enablers like investment and skilled talent. Overall , the diagram illustrates how this interconnected network of people and technology ensures safe, efficient, and sustainable rail operations .

What does the Railway Signalling System Market Encompass?

The railway signalling system market encompasses wayside, onboard, control center , and communications hardware, together with train control, interlocking, and traffic management software and associated installation, maintenance, and engineering services that enable safe train movement, spacing, and route control across mainline, urban transit, and high-speed rail networks. We observed that the market has structurally evolved from lineside colored -light signals toward cab-based digital signalling under the European Train Control System, as demonstrated by Deutsche Bahn's approx. USD 7.35 billion digital signalling framework agreement awarded to Siemens Mobility and Alstom in 2025.

Regulatory frameworks such as the European Rail Traffic Management System deployment plan coordinated by the European Union Agency for Railways continue to standardize cross-border signalling interoperability, while national infrastructure managers across Asia-Pacific and Latin America pursue parallel digitalization programs. During our market evaluation, we noticed that smart railway technology adoption is accelerating fastest in Automatic Train Operation over ETCS Level 2, following Siemens Mobility's landmark 2025 deployment for São Paulo's commuter rail network.

Market Drivers & Dynamics

Interactive Dataset
European ERTMS deployment mandate driving standardized digital signalling driver +2.8% Europe 2026–2032
Long-term infrastructure manager framework agreements securing volume driver +2.2% Europe, North America 2026–2032
Rapid urban transit and metro network expansion across Asia-Pacific driver +2.0% Asia-Pacific 2026–2033
Automatic Train Operation adoption increasing commuter rail capacity driver +1.6% Asia-Pacific, Latin America, Europe 2026–2032
5G and FRMCS communications modernization programs driver +1.1% Asia-Pacific, Europe 2027–2035
High capital cost and long delivery timelines for corridor-wide upgrades restraint −1.5% Global 2026–2031
Legacy system interoperability constraints slowing brownfield modernization restraint −1.0% Europe, North America 2026–2030
Limited pool of qualified signalling contractors constraining delivery capacity restraint −0.6% Global 2026–2029
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Railway Signalling System Market?

European ERTMS deployment mandates are the single largest driver of railway signalling system market growth, as infrastructure managers across the continent commit to standardized digital signalling under coordinated national programs. The European Union Agency for Railways' published ERTMS Third Work Plan documents the coordinated pace of deployment progress across member states, while Germany's Rhine-Alpine Corridor rollout alone targets an initial 43-kilometer segment through 2029 under DB's broader framework. We observed that this regulatory mandate provides multi-decade demand visibility for signalling suppliers.

How Is Long-Term Framework Contracting Driving Market Growth?

Long-term infrastructure manager framework agreements are driving sustained procurement volume, exemplified by Deutsche Bahn's €6.3 billion digital signalling framework awarded to Siemens Mobility, Leonhard Weiss, and Alstom, with individual project delivery running into 2032. Our analysis shows that the Signaling Communications technology segment is growing at a 14.5% CAGR from 2026 to 2035, well above the broader market average of 9.45%, as these framework agreements increasingly bundle communications modernization alongside core interlocking and train control upgrades.

Growth Inhibitors

What Is Restraining Railway Signalling System Market Growth?

High capital costs and long delivery timelines restrain the pace of corridor-wide signalling upgrades, with major European framework agreements spanning delivery windows extending to 2032 and beyond. Legacy system interoperability constraints also restrain brownfield modernization, as evidenced by Hitachi Rail's development of a Specific Transmission Module for Portugal enabling ETCS-equipped trains to operate on lines still using legacy train protection systems during the country's phased ERTMS transition. We found that these pressures extend average project timelines well beyond initial contract award.

What Are the Growth Opportunities?

How Can Vendors Capture Value from Latin American Digital Signalling Expansion?

Latin America's rapid adoption of ETCS Level 2 and Automatic Train Operation, following landmark deployments in Brazil, Chile, and Mexico, creates a mechanism for vendors to capture first-mover advantage across a region with substantial remaining signalling modernization potential. Vendors with proven cloud-ready platforms are best positioned to capture this fastest-growing regional opportunity.

What Opportunity Exists in Legacy Interoperability Solutions?

Specific Transmission Modules and other interoperability solutions that allow ETCS-equipped trains to operate on legacy-signalled lines create a mechanism for vendors to capture transition-period revenue during phased national ERTMS rollouts. Vendors with proven onboard interface technology are best positioned to capture this opportunity as countries manage multi-decade legacy-to-digital transitions.

How Can Suppliers Benefit from Long-Term Framework Agreement Positioning?

Multi-year infrastructure manager framework agreements create a mechanism for suppliers to secure predictable, large-scale procurement volume years in advance of individual project delivery. Vendors with demonstrated large-corridor delivery capability, such as those securing shares of Deutsche Bahn's €6.3 billion framework, are best positioned to capture this durable, policy-anchored opportunity.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Hardware
Wayside Equi
Signals
Track Circui
Point Machin
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Hardware $10.0 USD Billion $40.0 USD Billion 13.0%
Wayside Equipment $17.1 USD Billion $51.1 USD Billion 19.0%
Signals $24.2 USD Billion $62.2 USD Billion 13.0%
Track Circuits and Axle Counters $31.3 USD Billion $73.3 USD Billion 11.0%
Point Machines $38.4 USD Billion $84.4 USD Billion 12.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Component.

Unlock Full Data

Which Component Segment Dominates the Railway Signalling System Market?

Hardware dominates the railway signalling system market with approximately 58% share in 2025, valued at USD 15.36 billion, reflecting the substantial cost of wayside, onboard, and control center equipment relative to software and services across large-scale corridor deployments. Software is the fastest-growing component segment at a 14.0% CAGR from 2026 to 2035, driven by increasing adoption of traffic management, diagnostics, and cybersecurity software as signalling systems become more data-driven and network-connected.
2025 (USD Billion)
2035 (USD Billion)
Train Contro
CBTC
ETCS
PTC
Conventional
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Train Control $10.0 USD Billion $40.0 USD Billion 16.0%
CBTC $17.1 USD Billion $51.1 USD Billion 22.0%
ETCS $24.2 USD Billion $62.2 USD Billion 16.0%
PTC $31.3 USD Billion $73.3 USD Billion 26.0%
Conventional ATP and ATC $38.4 USD Billion $84.4 USD Billion 25.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Technology.

Unlock Full Data

Which Technology Segment Is Growing Fastest?

Interlocking leads the technology segmentation with approximately 26% share in 2025 at USD 6.89 billion, reflecting its role as the foundational safety-critical system governing route setting and conflict prevention across every signalled railway network. Signaling Communications is the fastest-growing technology segment at a 14.5% CAGR, propelled by 5G and FRMCS modernization programs such as Indonesia's tripartite railway digitalization partnership with Huawei, which support the higher-bandwidth communications required by advanced train control applications.

2025 (USD Billion)
2035 (USD Billion)
New Installa
Modernizatio
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
New Installation (Greenfield) $10.0 USD Billion $40.0 USD Billion 17.0%
Modernization and Retrofit (Brownfield) $17.1 USD Billion $51.1 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Deployment Type.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Control Cent
Wayside and
Onboard Trai
Station Syst
Depot and Ya
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Control Center Systems $10.0 USD Billion $40.0 USD Billion 18.0%
Wayside and Trackside Systems $17.1 USD Billion $51.1 USD Billion 16.0%
Onboard Train Systems $24.2 USD Billion $62.2 USD Billion 22.0%
Station Systems $31.3 USD Billion $73.3 USD Billion 12.0%
Depot and Yard Systems $38.4 USD Billion $84.4 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Urban Transi
Metro & Subw
Light Rail &
Mainline Rai
Conventional
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Urban Transit $10.0 USD Billion $40.0 USD Billion 15.0%
Metro & Subway $17.1 USD Billion $51.1 USD Billion 13.0%
Light Rail & Tram $24.2 USD Billion $62.2 USD Billion 23.0%
Mainline Rail $31.3 USD Billion $73.3 USD Billion 9.0%
Conventional Passenger Rail $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End Use.

Unlock Full Data

Which End Use Segment Leads the Railway Signalling System Market?

Mainline Rail leads the end-use segmentation with approximately 54% share in 2025 at USD 14.30 billion, anchored by the sheer scale of national mainline networks requiring both new signalling installation and ongoing modernization. Urban Transit is the fastest-growing end-use segment at an 11.3% CAGR, driven by rapid metro and light rail network expansion across Asia-Pacific and continued Automatic Train Operation deployment on commuter rail corridors such as Sao Paulo's CPTM network.

Growth Opportunities

Beyond the core drivers shaping overall demand, three whitespace opportunities stand out for signalling vendors positioning portfolios toward 2035.

How Can Vendors Capture Value from Latin American Digital Signalling Expansion?

Latin America's rapid adoption of ETCS Level 2 and Automatic Train Operation, following landmark deployments in Brazil, Chile, and Mexico, creates a mechanism for vendors to capture first-mover advantage across a region with substantial remaining signalling modernization potential. Vendors with proven cloud-ready platforms are best positioned to capture this fastest-growing regional opportunity.

What Opportunity Exists in Legacy Interoperability Solutions?

Specific Transmission Modules and other interoperability solutions that allow ETCS-equipped trains to operate on legacy-signalled lines create a mechanism for vendors to capture transition-period revenue during phased national ERTMS rollouts. Vendors with proven onboard interface technology are best positioned to capture this opportunity as countries manage multi-decade legacy-to-digital transitions.


How Can Suppliers Benefit from Long-Term Framework Agreement Positioning?

Multi-year infrastructure manager framework agreements create a mechanism for suppliers to secure predictable, large-scale procurement volume years in advance of individual project delivery. Vendors with demonstrated large-corridor delivery capability, such as those securing shares of Deutsche Bahn's €6.3 billion framework, are best positioned to capture this durable, policy-anchored opportunity.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Regulatory Framework Impacting the Railway Signaling System Industry

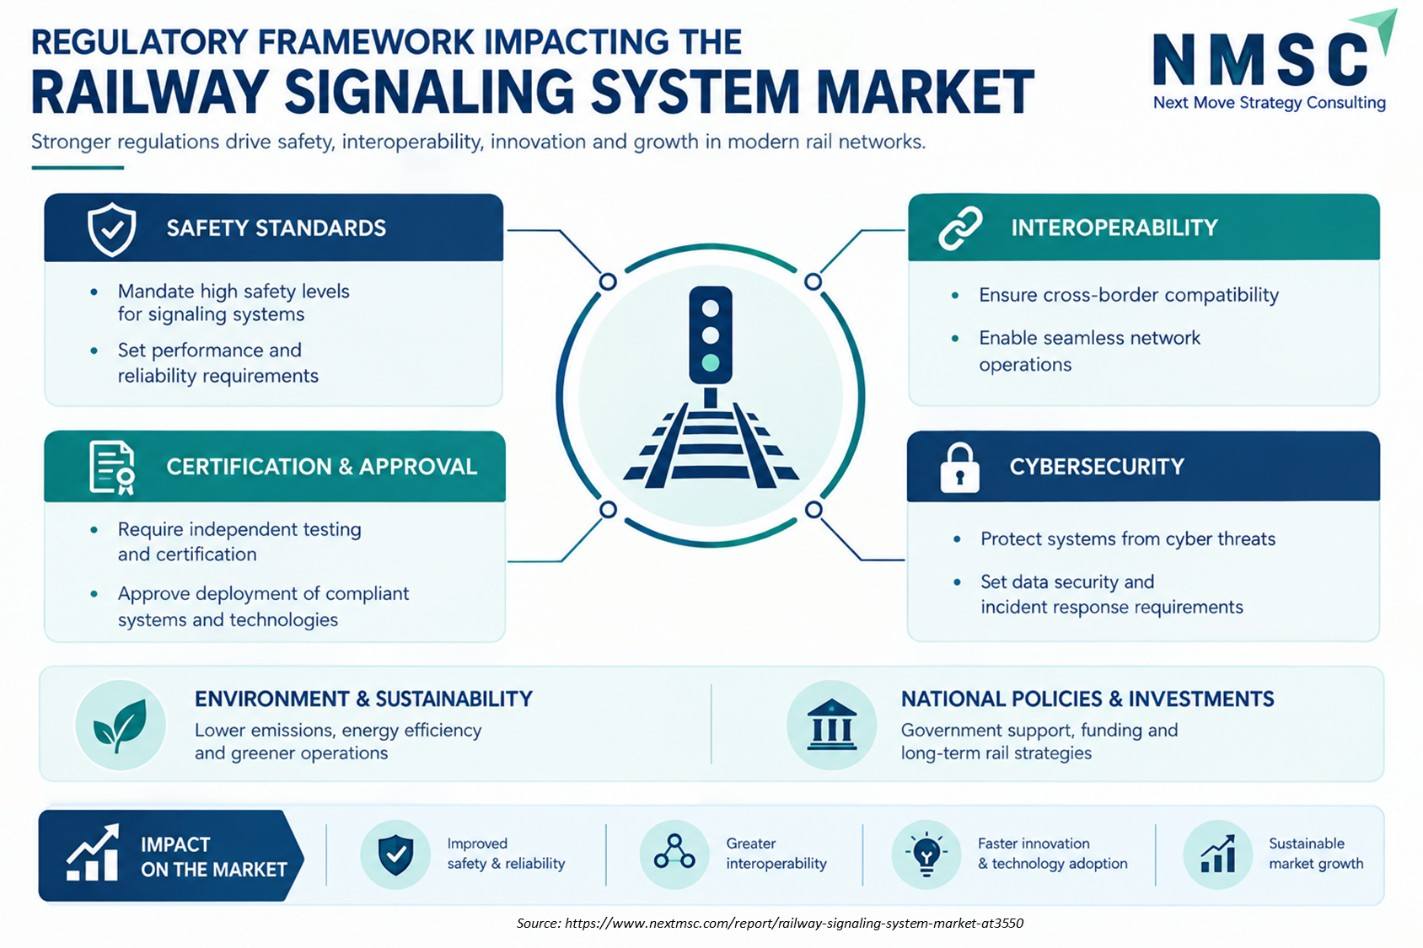
The above infographic outlines the regulatory framework impacting the railway signalling system market by categorizing six key areas, from safety standards to government policies. It illustrates how these regulations directly drive safety, interoperability, and innovation within the sector. Overall, the diagram shows that strong regulations lead to positive market outcomes, such as sustained growth, technological advancement, and safer rail operations.

Competitive Landscape

Our assessment indicates that competitive intensity in the railway signalling system market is shaped by a small number of global rolling stock and signalling conglomerates alongside specialized regional signalling vendors competing across mainline, urban transit, and high-speed rail verticals within the broader rail equipment industry. Dimension | Assessment Market Structure | Concentrated among a small number of global rolling stock and signalling conglomerates at the large-corridor tier, fragmented among specialized regional vendors at the component and niche-application tier. Innovation Focus | ETCS Level 2 and Automatic Train Operation integration, cloud-ready platform architecture, and FRMCS communications modernization. M&A Activity | Long-term framework agreement partnerships and consortium bidding rather than large-scale horizontal consolidation. Source: www.nextmsc.com

Dimension Description
Market Structure Concentrated among a small number of global rolling stock and signalling conglomerates at the large-corridor tier, fragmented among specialized regional vendors at the component and niche-application tier.
Innovation Focus ETCS Level 2 and Automatic Train Operation integration, cloud-ready platform architecture, and FRMCS communications modernization.
M&A Activity Long-term framework agreement partnerships and consortium bidding rather than large-scale horizontal consolidation.

How Do Companies Compete in the Railway Signalling System Market?

Companies compete primarily on proven multi-corridor delivery track record, ETCS interoperability certification, long-term maintenance capability, and established infrastructure manager relationships built over decades of national rail programs. Our analysis shows that Siemens Mobility and Alstom compete heavily on large-framework delivery scale and proprietary digital signalling platforms, while regional specialists including AZD Praha and Indra Sistemas compete on deep national market knowledge and established local regulatory relationships.

Which Competitive Archetypes Dominate the Railway Signalling System Industry?

Two archetypes dominate the market: global rolling stock and signalling conglomerates offering integrated, multi-corridor digital signalling platforms, and specialized regional vendors offering deep national market expertise and component-level technology. Siemens Mobility exemplifies the global-conglomerate archetype through its SignalingX platform and multi-billion-euro framework agreements, while AZD Praha exemplifies the regional-specialist archetype through its established Central European interlocking and train control expertise.

How Are Companies Differentiating Through Innovation?

Innovation and differentiation increasingly center on cloud-ready, AI-prepared signalling architecture and integrated Automatic Train Operation capability. Siemens Mobility's SignalingX platform, built on the SIL4-certified DS3 architecture with cloud integration readiness, and its landmark ATO over ETCS Level 2 deployments across Brazil and the UK's HS2 both illustrate how vendors are embedding next-generation architecture to differentiate beyond conventional interlocking and train protection technology.

What M&A and Expansion Activity Is Shaping the Railway Signalling System Market?

Expansion activity is concentrated in long-term framework agreements and consortium partnerships rather than large-format acquisitions, following the European Commission's 2019 prohibition of the proposed Siemens-Alstom mobility combination. Deutsche Bahn's multi-vendor €6.3 billion framework, awarded jointly to Siemens Mobility with Leonhard Weiss and separately to Alstom, illustrates how infrastructure managers now structure large programs to preserve competitive vendor diversity rather than consolidate around a single supplier.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping signalling technology innovation, large-corridor delivery capability, and regional market expansion within the global railway signalling system market.

China Railway Signal & Communication Corporation Limited Siemens Mobility GmbH Hitachi Rail Limited Alstom SA Wabtec Corporation Knorr-Bremse AG Mitsubishi Electric Corporation Nippon Signal Co., Ltd. Toshiba Corporation CAF Signalling, S.L. Stadler Signalling AG voestalpine Railway Systems GmbH MERMEC S.p.A. Scheidt & Bachmann Signalling Systems GmbH Hyundai Rotem Company Kyosan Electric Manufacturing Co., Ltd. PINTSCH GmbH AŽD Praha s.r.o. Indra Sistemas, S.A. ALTPRO d.o.o.

Latest Developments

We found that recent contract awards within the railway signalling system market are concentrated on ETCS Level 2 deployment and long-term framework agreements across 2025 and 2026.

Date Event
June 2026 Alstom secured a contract to deliver ETCS Level 2 digital signalling for Stage 1 of Queensland’s The Wave program. The signalling scope includes an integrated 5G digital radio system, positioning Alstom to deploy advanced train-control technology on a major Australian mainline railway project supporting the Brisbane 2032 Olympics.
May 2026 Alstom signed a contract to replace Lausanne m2’s signalling system with a new communications-based train control (CBTC) system. The new signalling technology will allow trains to operate closer together and increase service frequency while maintaining safety and reliability, directly upgrading the metro’s train-control infrastructure.
November 2024 Hitachi Rail announced a USD 100 million investment supported by Invest Ontario to develop the next generation of its SelTrac CBTC signalling technology in Toronto. The initiative includes 100 new highly skilled jobs and focuses on advancing the company’s next-generation communications-based train-control capabilities.

Investment Opportunities

What Capital Inflows Are Targeting the Railway Signalling System Market?

Capital inflows are increasingly directed toward large, multi-year framework agreements, with Deutsche Bahn's approx. USD 7.35 billion digital signalling framework representing one of the largest coordinated national signalling investment programs globally. We observed that investors favor vendors demonstrating confirmed framework-agreement positions, viewing multi-year committed volume as a proxy for durable, predictable revenue visibility extending into the next decade.

How Is Infrastructure Investment Supporting Railway Signalling System Market Growth?

Infrastructure investment tied to national ERTMS deployment plans and urban transit expansion programs continues to underwrite signalling procurement across Europe and Asia-Pacific. Germany's Rhine-Alpine Corridor rollout and Indonesia's 5G and AI railway digitalization partnership both illustrate how government-anchored infrastructure investment is directly translating into signalling contract volume. Our findings suggest that vendors with established public-infrastructure-manager relationships are best positioned to capture this policy-anchored investment flow through 2035.

What ESG Considerations Are Shaping Investment Decisions?

Rail safety performance and modal shift toward lower-carbon transport are central governance considerations shaping investment decisions, as advanced signalling directly enables higher train frequency and capacity that supports rail's role in reducing transport-sector emissions. We found that investors increasingly treat demonstrated safety-integrity certification, such as Signaling X's SIL4 compliance, as a governance indicator alongside conventional financial performance metrics when evaluating signalling vendors.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support technology-investment and vendor-selection decisions across the railway signalling system industry. Our analysis shows that detailed component, technology, and end-use breakdowns help infrastructure manager procurement teams align modernization strategy with the fastest-growing segments, including Signaling Communications and Urban Transit.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the railway signalling system supply chain. We observed that the report's regional and segment-level growth differentials help identify which vendors are best positioned to capture above-market growth in Latin American digital signalling expansion and European framework agreement positioning through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including cloud-ready architecture, ATO over ETCS Level 2 integration, and FRMCS communications readiness, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around the Software component and Onboard Train Systems application segments showing the strongest above-market growth trajectories.

Key Market Segments Evaluated

By Component

  • Hardware
  • Services
  • Software

By Technology

  • Interlocking
  • Train Control
  • Train Detection
  • Signaling Communications
  • ATO
  • Level Crossing

By Deployment Type

  • New Installation (Greenfield)
  • Modernization and Retrofit (Brownfield)

By Application

  • Control Center Systems
  • Wayside and Trackside Systems
  • Onboard Train Systems
  • Station Systems
  • Depot and Yard Systems
  • Level Crossing Systems

By End Use

  • Mainline Rail
  • Urban Transit
  • High-Speed Rail

Conclusion & Recommendations

The long-term outlook for the railway signalling system market remains positive, with global revenue projected to grow more than twofold from USD 26.48 billion in 2025 to USD 65.32 billion by 2035 at a 9.45% CAGR. We observed that European ERTMS mandates, Asia-Pacific urban transit expansion, and accelerating Latin American digital signalling adoption will continue underpinning demand across mainline, urban transit, and high-speed rail applications through the forecast period.

What Strategic Positioning Should Railway Signalling System Vendors Pursue?

Vendors should prioritize cloud-ready, ATO-integrated platform architecture while pursuing long-term framework agreement positions with major infrastructure managers to secure multi-year revenue visibility. Our assessment indicates that vendors investing early in FRMCS-ready communications technology will be best positioned to capture premium modernization contracts while retaining established mainline signalling relationships.

How Attractive Is the Railway Signalling System Market for New Investment?

The railway signalling system market presents an attractive investment case, supported by a USD 36.34 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Latin America and Signaling Communications. We found that investment attractiveness is highest for vendors combining proven large-corridor delivery capability with demonstrated ETCS Level 2 and ATO integration experience, positioning them to serve both mature European framework programs and fast-growing Latin American and Asia-Pacific markets simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor high capital costs and extended delivery timelines, legacy interoperability constraints slowing brownfield modernization, and a limited pool of qualified signalling contractors as key risks to the railway signalling system market. Our analysis shows that vendors unable to demonstrate proven multi-corridor delivery capacity risk losing large framework agreements to better-resourced competitors as infrastructure managers consolidate procurement around fewer, larger suppliers.

What Are the Key Growth Pathways for the Railway Signalling System Market?

Key growth pathways include scaling cloud-ready, SIL4-certified signalling platforms, deepening ATO over ETCS Level 2 deployment following precedents set in Sao Paulo and on HS2, and expanding FRMCS-ready communications infrastructure to support future AI-enabled train control. Next Move Strategy Consulting's analysis indicates that vendors pursuing these pathways while securing long-term framework agreement positions will be best positioned to capture the market's projected growth through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market Growth Analysis
  • Historical revenue and installed-base analysis of railway signalling systems across component, technology, deployment type, and application segments.
  • Reveals high-growth segments and supports investment and portfolio prioritization.
Company-Level Signalling Revenue Split by Technology
  • Company-wise revenue attribution across ETCS, CBTC, PTC, interlocking, and conventional signalling where publicly disclosed.
  • Shows technology positioning of leading suppliers and highlights partnership and M&A targets.
Company-Level Project and Order Volume Analysis
  • Supplier-level benchmarking of awarded contracts, installed route-km, and delivered systems by component and end use.
  • Highlights supplier scale and win-rate differences to sharpen competitive positioning.
Rail Network Modernization Pipeline Assessment
  • Country-wise mapping of announced and funded signalling upgrade and new-line projects by technology, deployment type (new installation vs. retrofit), and application (mainline, urban transit, freight).
  • Pinpoints near-term bid opportunities and prioritizes geographic expansion.
Legacy-to-Digital Signalling Migration Mapping
  • Adoption and migration assessment from conventional signalling to ETCS, CBTC, and PTC by region, including regulatory mandates and interoperability requirements.
  • Identifies replacement-cycle timing and guides technology investment and product roadmap.
Procurement and Tender Landscape Analysis
  • Analysis of railway operator and infrastructure manager procurement models, contract structures, and award patterns across mainline, metro, and freight end users.
  • Supports bid strategy, partner selection, and localization decisions for target markets.

FAQs

What does the Railway Signalling System Market Encompass?

The railway signalling system market encompasses wayside, onboard, control center, and communications hardware, together with train control, interlocking, and traffic management software and associated installation, maintenance, and engineering services that enable safe train movement, spacing, and route control across mainline, urban transit, and high-speed rail networks. We observed that the market has structurally evolved from lineside colored-light signals toward cab-based digital signalling under the European Train Control System, as demonstrated by Deutsche Bahn's approx. USD 7.35 billion digital signalling framework agreement awarded to Siemens Mobility and Alstom in 2025.
Regulatory frameworks such as the European Rail Traffic Management System deployment plan coordinated by the European Union Agency for Railways continue to standardize cross-border signalling interoperability, while national infrastructure managers across Asia-Pacific and Latin America pursue parallel digitalization programs. During our market evaluation, we noticed that smart railway technology adoption is accelerating fastest in Automatic Train Operation over ETCS Level 2, following Siemens Mobility's landmark 2025 deployment for São Paulo's commuter rail network.

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Mohit Agarwal

MOHIT AGARWAL

Chief Manager

DryChem India Pvt. Ltd.

Next Move Strategy Consulting is an amazing team of consultants. We required a market study report for our investors on top priority and the team went above and beyond our expectations to deliver the same with ample supporting data within a short time span enabling us to secure the investments and keep our project timeline maintained. Their professionalism, attention to detail, and timely delivery of actionable recommendations have left a lasting impression on our organization.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖