South Korea Agriculture Robots Market By Type (Unmanned Aerial Vehicles (UAVs), Milking Robots, Driverless Tractors, Automated Harvest Robots and Others), By Farming Type (Indoor Farming, Outdoor Farming and Indoor & Outdoor), and By Application (Aerial Monitoring & Scouting, Dairy & Livestock Automation, Field Operations, Harvest Management and Others): Opportunity Analysis & Industry Forecast, 2025–2035
Industry: Agriculture | Latest Edition: August 20, 2026 | No of Pages: 175 | No. of Tables: 66 | No. of Figures: 60 | Format: PDF | Report Code : AG635
Market Size & Forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 656.21 Million |
|
Market Size in 2026 |
USD 823.41 Million |
|
Revenue Forecast in 2035 |
USD 2,527.78 Million |
|
Growth Rate |
CAGR of 13.27% from 2026 to 2035 |
|
Market Volume in 2025 |
4 thousand Units |
|
Market Volume in 2026 |
6 thousand Units |
|
Volume Forecast in 2035 |
31 thousand Units |
|
Growth Rate |
CAGR of 19.66% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Million (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 Companies |
Industry Outlook
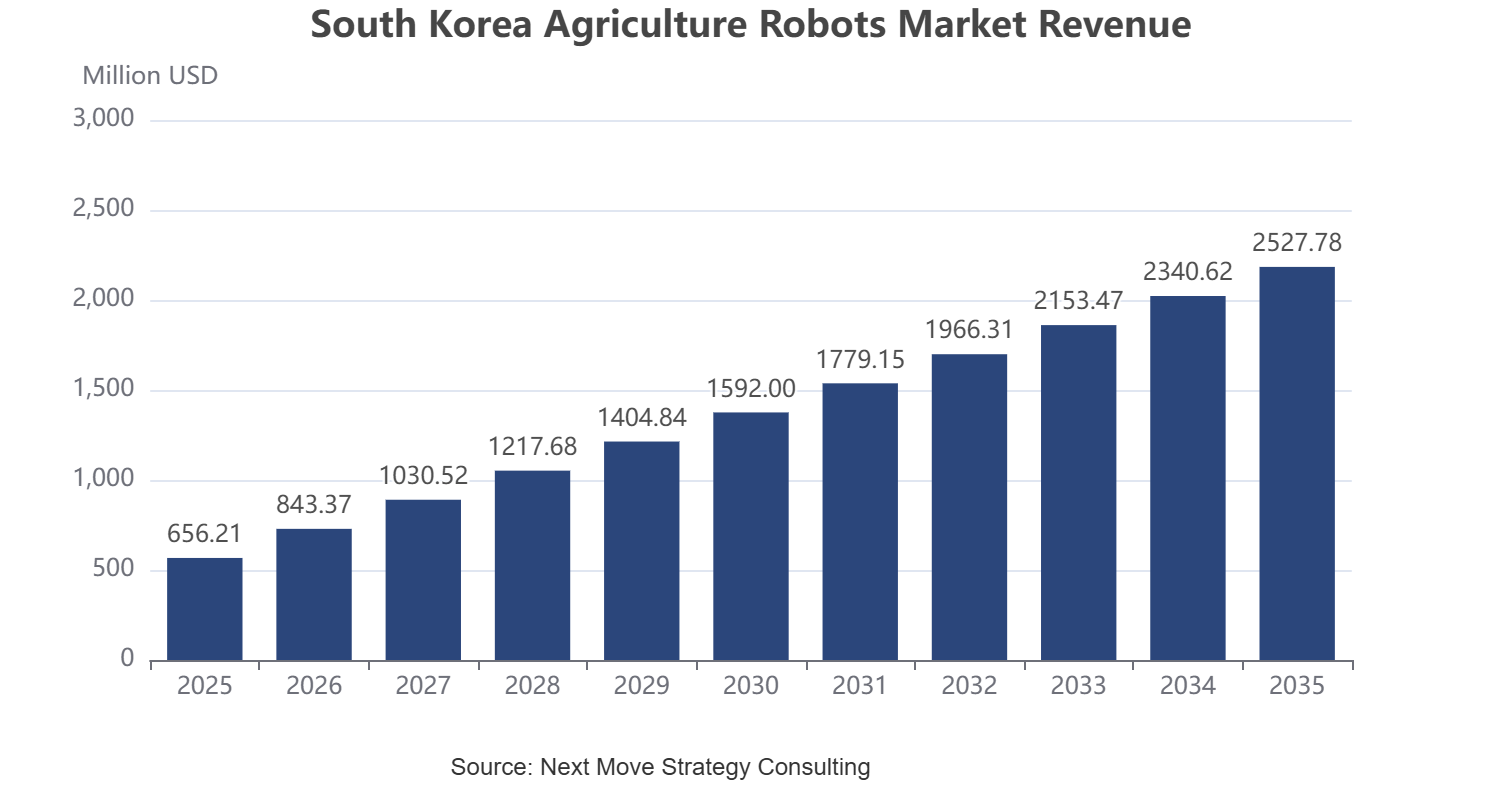
The South Korea Agriculture Robots Market was valued at USD 656.21 million in 2025 and is estimated to reach USD 823.41 million in 2026. The market is projected to reach USD 2,527.78 million by 2035, registering a CAGR of 13.27% during 2026–2035. In volume terms, the market accounted for 4 thousand units in 2025 and is expected to reach 6 thousand units in 2026, with shipments forecast to increase to 31 thousand units by 2035, reflecting a volume CAGR of 19.66%. Growth is driven by government smart farming initiatives, advanced domestic robotics capabilities, an aging agricultural workforce, and increasing adoption of precision farming and autonomous agricultural technologies.
Strategic Framework of the South Korea Agriculture Robots Market
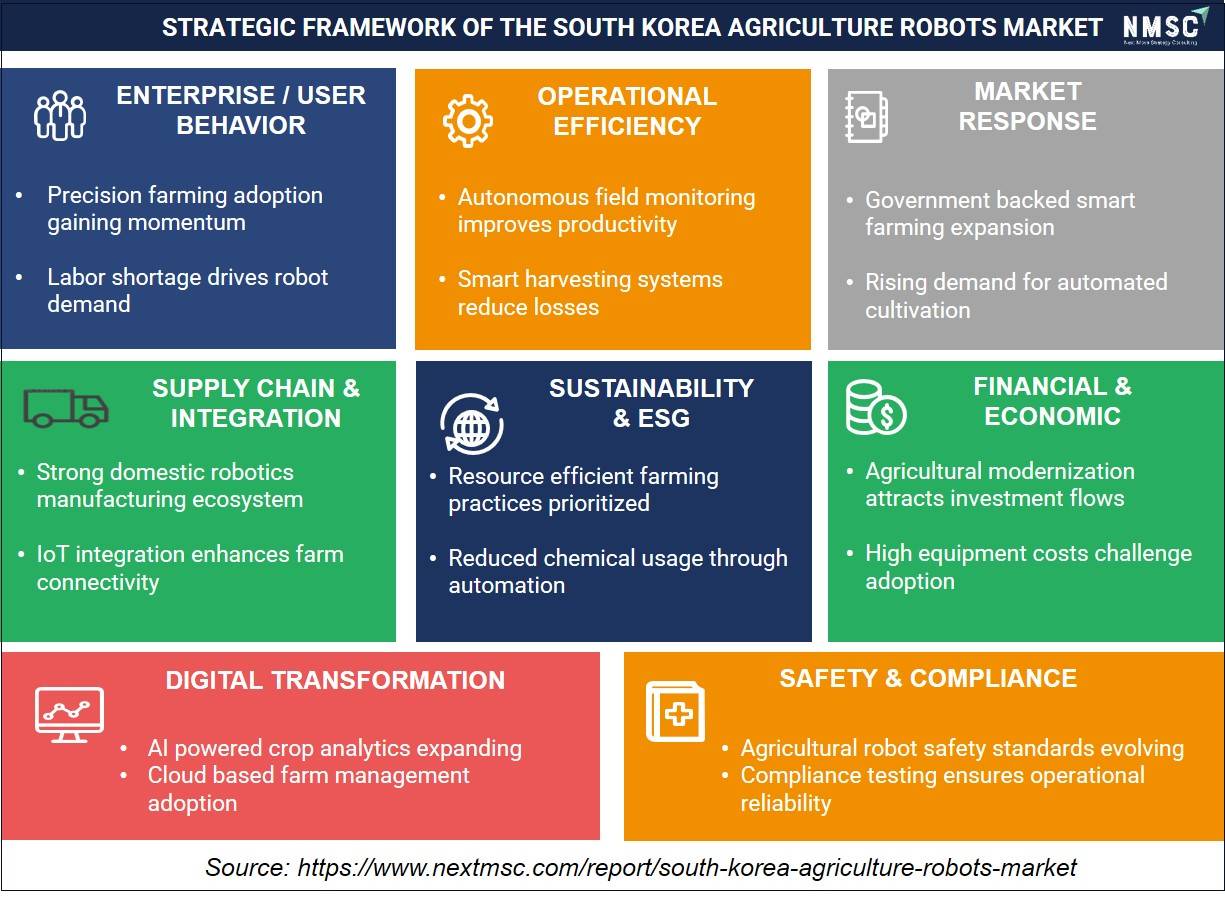
The strategic framework of the South Korea agriculture robots market highlights the drivers supporting advanced agricultural automation and precision farming adoption. Government-backed smart farming initiatives, a strong domestic robotics ecosystem, AI and IoT integration, and sustainability-focused farming practices are accelerating deployment. Although high equipment costs remain a challenge, increasing investment, operational efficiency gains, and evolving safety standards continue to strengthen long-term market growth.
What Are the Key Growth Catalysts, Inhibitors, and Opportunities Shaping the South Korea Agriculture Robots Market?
Growth Catalyst & Risk Assessment Matrix
|
Drivers / Trends / Restraints |
(+/–) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Strong robotics and automation capabilities are supporting growth of agricultural robot deployment. |
+2.00% |
South Korea |
Medium term (2–5 years) |
|
Government-backed smart farming initiatives are accelerating adoption of precision agriculture technologies. |
+1.80% |
South Korea |
Short to medium term (1–4 years) |
|
Aging farming population is increasing reliance on automated agricultural solutions. |
+1.50% |
South Korea |
Medium to long term (3–7 years) |
|
High technology implementation costs can hinder widespread adoption across farming communities. |
–1.40% |
South Korea |
Short to medium term (1–4 years) |
|
Integration of artificial intelligence with agricultural robotics presents significant market potential. |
+1.60% |
South Korea |
Medium term (2–5 years) |
The South Korea Agriculture Robots Market is shaped by a convergence of structural and technological factors that collectively define its competitive and growth trajectory. Advanced national robotics capabilities, proactive government smart farming programs, and demographic shifts toward an aging agricultural workforce are primary drivers of market expansion. However, elevated technology implementation costs remain a constraint for widespread adoption. Simultaneously, the integration of artificial intelligence with robotic systems presents a transformative opportunity for next-generation agricultural automation across South Korea.
Growth Driver
How Are South Korea's Advanced Robotics and Automation Capabilities Supporting the Growth of Agricultural Robot Deployment?
South Korea's globally recognized robotics manufacturing ecosystem and deep industrial automation expertise are providing a strong foundational advantage for agricultural robot development and deployment. Domestic firms benefit from established supply chains, precision engineering capabilities, and automation integration experience derived from electronics and automotive sectors. These competencies are being leveraged to accelerate the design, testing, and commercialization of purpose-built agricultural robotic systems. The resulting technology spillovers are reducing development timelines and enhancing the functional sophistication of agricultural robots deployed across South Korean farms.
How Are Government-Backed Smart Farming Initiatives Accelerating Adoption of Precision Agriculture Technologies in South Korea?
The South Korean government has introduced comprehensive smart farming policy frameworks, including subsidies, pilot programs, and rural digitization initiatives, that are directly accelerating the adoption of precision agriculture technologies. National programs established by the Ministry of Agriculture, Food and Rural Affairs have created infrastructure and funding mechanisms that lower the entry barriers for farmers adopting robotic systems. These policy-driven efforts are creating a structured demand environment that supports market growth across multiple agricultural robot categories throughout the forecast period.
How Is the Aging Farming Population in South Korea Increasing Reliance on Automated Agricultural Solutions?
South Korea's agricultural workforce is undergoing a significant demographic shift, with an increasing proportion of farmers exceeding 65 years of age and a declining influx of younger agricultural workers. This structural labor challenge is compelling farm operators to adopt automated solutions capable of sustaining productivity without dependence on a shrinking manual workforce. Agricultural robots offer a viable pathway to maintaining output levels, reducing physical labor demands, and ensuring operational continuity on aging farms. This demographic imperative represents a fundamental long-term growth driver for the South Korea Agriculture Robots Market.
Growth Inhibitor:
How Do High Technology Implementation Costs Hinder Widespread Adoption of Agricultural Robots across South Korean Farming Communities?
Despite available government support mechanisms, the high upfront costs associated with agricultural robotic systems remain a significant adoption barrier for a substantial segment of South Korean farming communities. Smallholder farms, which constitute a large proportion of the country's agricultural landscape, often face financial constraints that limit their capacity to invest in advanced robotic platforms. System acquisition, maintenance, technical training, and software integration costs collectively represent a substantial capital commitment, creating uneven technology diffusion and limiting market penetration across smaller agricultural enterprises throughout the forecast period.
Growth Opportunity:
How Does the Integration of Artificial Intelligence with Agricultural Robotics Present Significant Market Potential in South Korea?
The convergence of artificial intelligence and agricultural robotics is creating a new generation of autonomous farming systems capable of real-time decision-making, predictive analytics, and adaptive task execution. In South Korea, where strong AI research capabilities and government-backed development programs are prevalent, this integration represents a distinctive market opportunity. AI-enhanced robotic systems capable of precision crop monitoring, autonomous disease detection, and yield optimization are increasingly accessible to commercial farm operators, expected to unlock new application categories and expand total addressable market potential throughout the forecast period.
How Is the South Korea Agriculture Robots Market Segmented in This Report, and What Are the Key Insights from the Segmentation Analysis?
By Type
Which Robot Type Is Driving the Greatest Revenue Growth across the South Korea Agriculture Robots Market?
The South Korea Agriculture Robots Market by type is segmented into Unmanned Aerial Vehicles (UAVs), Milking Robots, Driverless Tractors, Automated Harvest Robots, and Others.
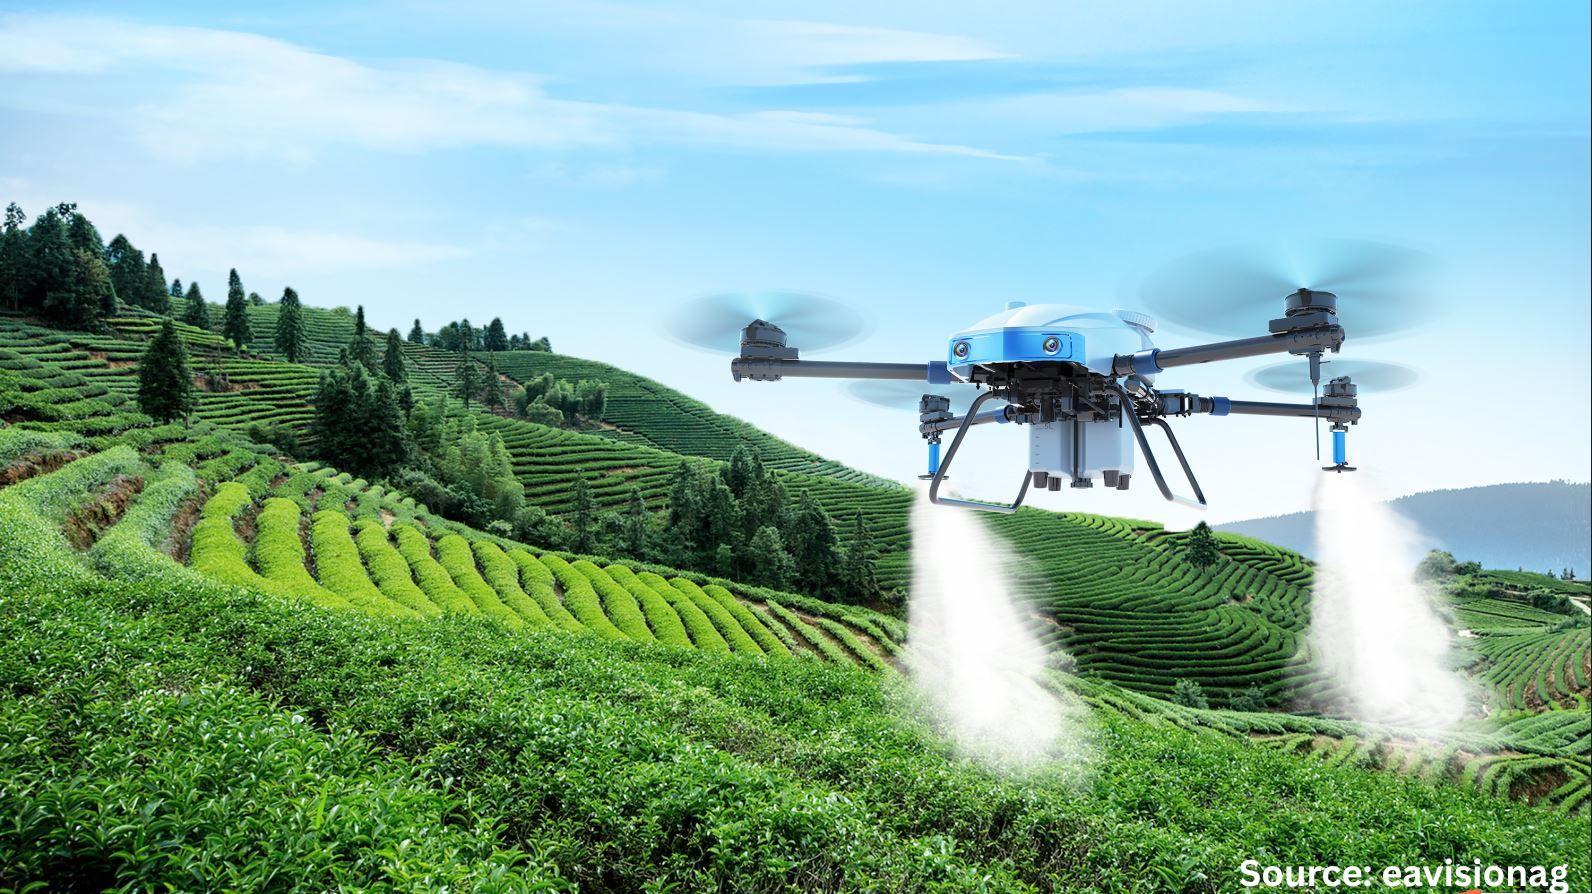
Among all robot types, Unmanned Aerial Vehicles (UAVs) are experiencing the highest growth momentum in South Korea, driven by their broad utility in crop monitoring, precision spraying, and aerial scouting across diverse agricultural landscapes. Driverless Tractors maintain substantial revenue contribution given their widespread applicability across field operations, while Automated Harvest Robots are gaining traction amid intensifying labor shortages. Milking Robots continue to support dairy farm automation, contributing steady incremental growth within the livestock segment throughout the 2026–2035 forecast period.
By Application
Which Application Segment Holds the Largest Share of the South Korea Agriculture Robots Market Revenue?
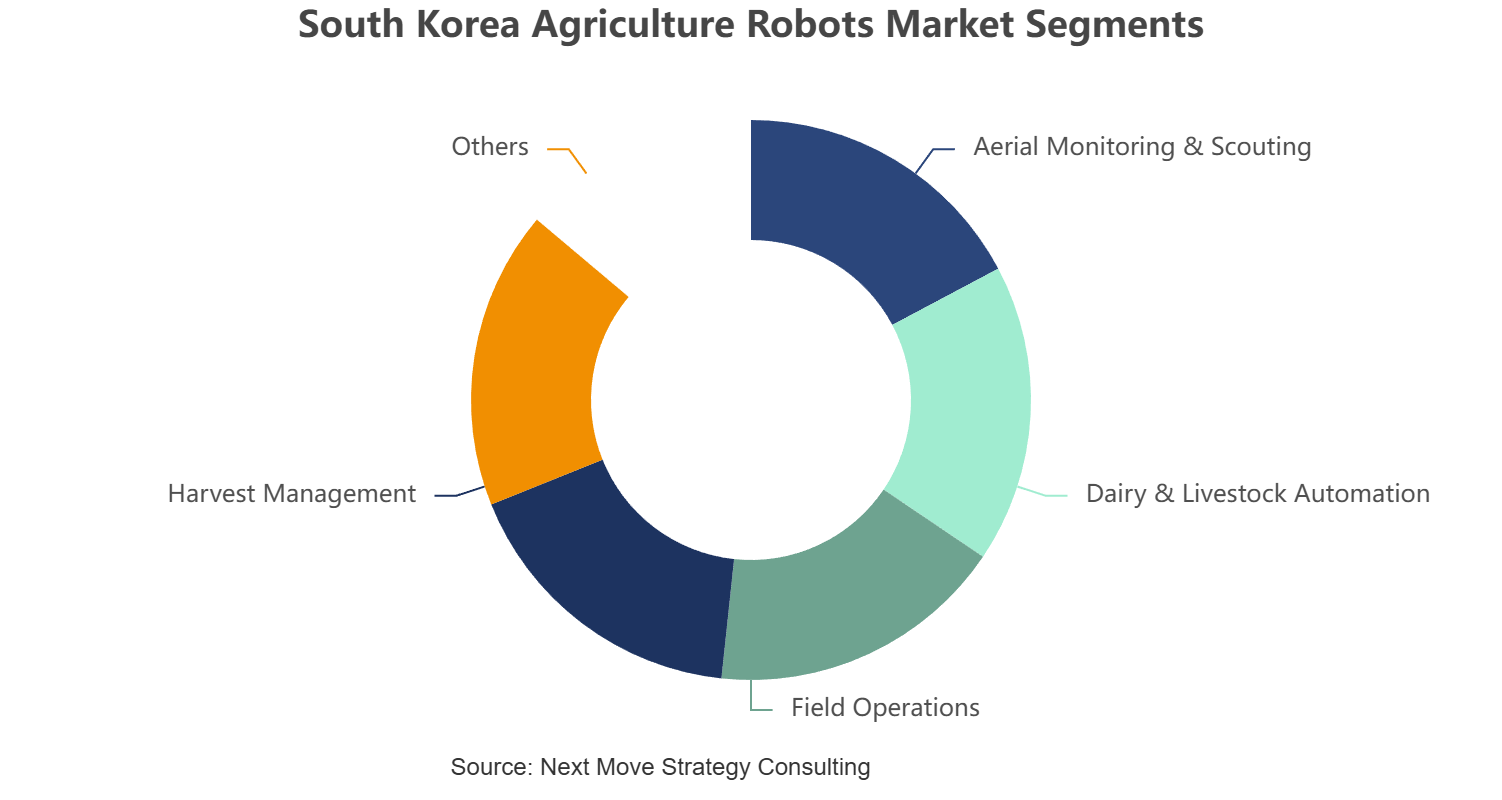
By application, the South Korea Agriculture Robots Market is segmented into Aerial Monitoring & Scouting, Dairy & Livestock Automation, Field Operations, Harvest Management, and Others.
Field Operations represents the dominant application category in South Korea, encompassing plowing, seeding, and soil and irrigation management activities increasingly supported by robotic automation. Aerial Monitoring & Scouting is experiencing strong growth momentum, enabled by UAV-based platforms for crop protection, weed control, and weather tracking. Harvest Management is emerging as a priority segment as aging workforce constraints amplify demand for autonomous harvesting solutions. Dairy & Livestock Automation, including milking and dairy management, continues to demonstrate consistent adoption trends across commercial dairy operations throughout the forecast period.
Key Segments
By Type
-
Unmanned Aerial Vehicles (UAVs)
-
Milking Robots
-
Driverless Tractors
-
Automated Harvest Robots
-
Others
By Farming Type
-
Indoor Farming
-
Outdoor Farming
-
Indoor & Outdoor
By Application
-
Aerial Monitoring & Scouting
-
Crop Protection & Weed Control
-
Crop Scouting & Monitoring
-
Weather Tracking
-
Inventory Management
-
-
Dairy & Livestock Automation
-
Milking
-
Dairy Management
-
Shepherding and Herding
-
-
Field Operations
-
Plowing
-
Seeding
-
Field Farming
-
Soil & Irrigation Management
-
-
Harvest Management
- Others
Competitive Landscape
The South Korea Agriculture Robots Market exhibits a competitive landscape characterized by a diverse mix of domestic agricultural equipment manufacturers, multinational robotics corporations, and specialized agri-tech solution providers. Market participants are actively pursuing research and development investments, technology licensing agreements, and strategic collaborations to strengthen competitive positioning. The market is also characterized by increasing convergence between agricultural robotics and digital farming platforms, compelling participants to integrate advanced data analytics, connectivity, and artificial intelligence capabilities into evolving product portfolios.
Key Players
-
Daedong Corporation
-
TYM Corporation
-
LS Mtron Ltd.
-
SZ DJI Technology Co., Ltd.
-
XAG Co., Ltd.
-
Kubota Corporation
-
Lely Industries N.V.
-
HADA Co., Ltd.
-
GINT Co., Ltd.
-
MetaFarmers Inc.
-
M3sen Co., Ltd.
-
Daesung Hive Co., Ltd.
-
CNH Industrial N.V.
The competitive landscape of the South Korea Agriculture Robots Market includes domestic leaders such as Daedong Corporation, TYM Corporation, and LS Mtron Ltd., which leverage established agricultural equipment expertise. SZ DJI Technology Co., Ltd. and XAG Co., Ltd. lead in UAV-based agricultural solutions, while Kubota Corporation and CNH Industrial N.V. compete across field automation segments. Lely Industries N.V., DeLaval International AB, and GEA Group AG anchor dairy automation, with HADA Co., Ltd., GINT Co., Ltd., MetaFarmers Inc., M3sen Co., Ltd., and Daesung Hive Co., Ltd. advancing specialized agri-tech innovation.
Supply Chain Structure of the South Korea Agriculture Robots Market
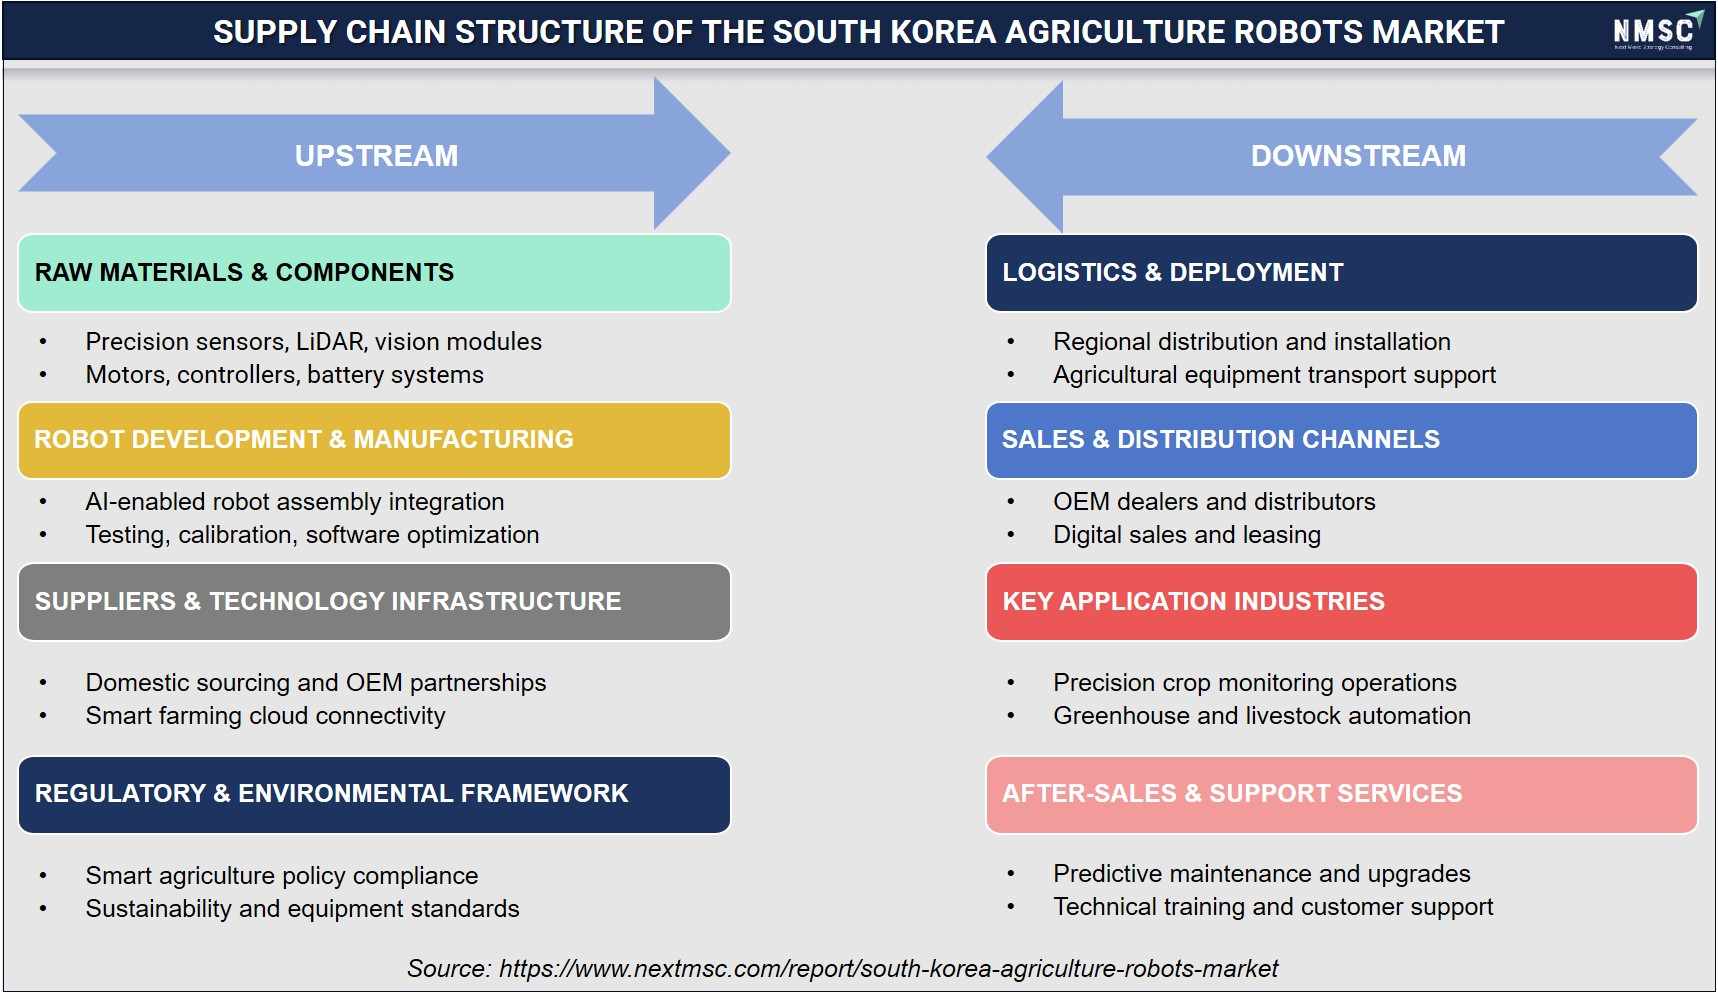
The supply chain structure of the South Korea agriculture robots market reflects a well-developed ecosystem spanning component manufacturing, AI-enabled robot assembly, technology integration, distribution, and after-sales services. Strong domestic sourcing capabilities, OEM partnerships, cloud-connected smart farming infrastructure, and comprehensive maintenance support enable efficient deployment. Regulatory compliance, sustainability standards, and localized technical expertise further enhance supply chain resilience and market competitiveness.
Key Benefits for Stakeholders
This report provides comprehensive market intelligence for stakeholders operating across the South Korea Agriculture Robots Market, supporting informed strategic decision-making throughout the value chain. Agricultural equipment manufacturers, technology developers, and farming enterprises benefit from detailed segmentation analysis, competitive benchmarking, and growth opportunity identification. Investors and venture capital firms gain access to rigorous market sizing data and revenue forecasting across the 2026–2035 period, enabling accurate investment evaluation and resource allocation aligned with South Korea's evolving agricultural automation landscape.
Policymakers and regulatory bodies can leverage report insights to develop evidence-based frameworks supporting sustainable agricultural automation adoption across South Korean farming communities. Research institutions and academic organizations benefit from comprehensive analysis of market trends, innovation trajectories, and technology adoption patterns within the agricultural robotics sector. The customizable segmentation structure enables stakeholders to tailor analytical outputs to specific regional, product, or application requirements, enhancing the relevance and applicability of market intelligence across diverse organizational contexts within the South Korea Agriculture Robots Market.
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter's Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The South Korea Agriculture Robots Market is positioned for sustained and robust growth throughout the forecast period, underpinned by advanced domestic robotics capabilities, government-backed smart farming initiatives, and structural demographic pressures driving automation demand. Revenue is projected to grow from USD 823.41 million in 2026 to USD 2,527.78 million by 2035 at a CAGR of 13.27%, reflecting broad adoption across robot types and applications. Competitive dynamics continue to intensify as domestic and international players invest in AI-integrated agricultural robotic solutions to capture emerging market opportunities.
About the Author
 Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.
About the Reviewer
 Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

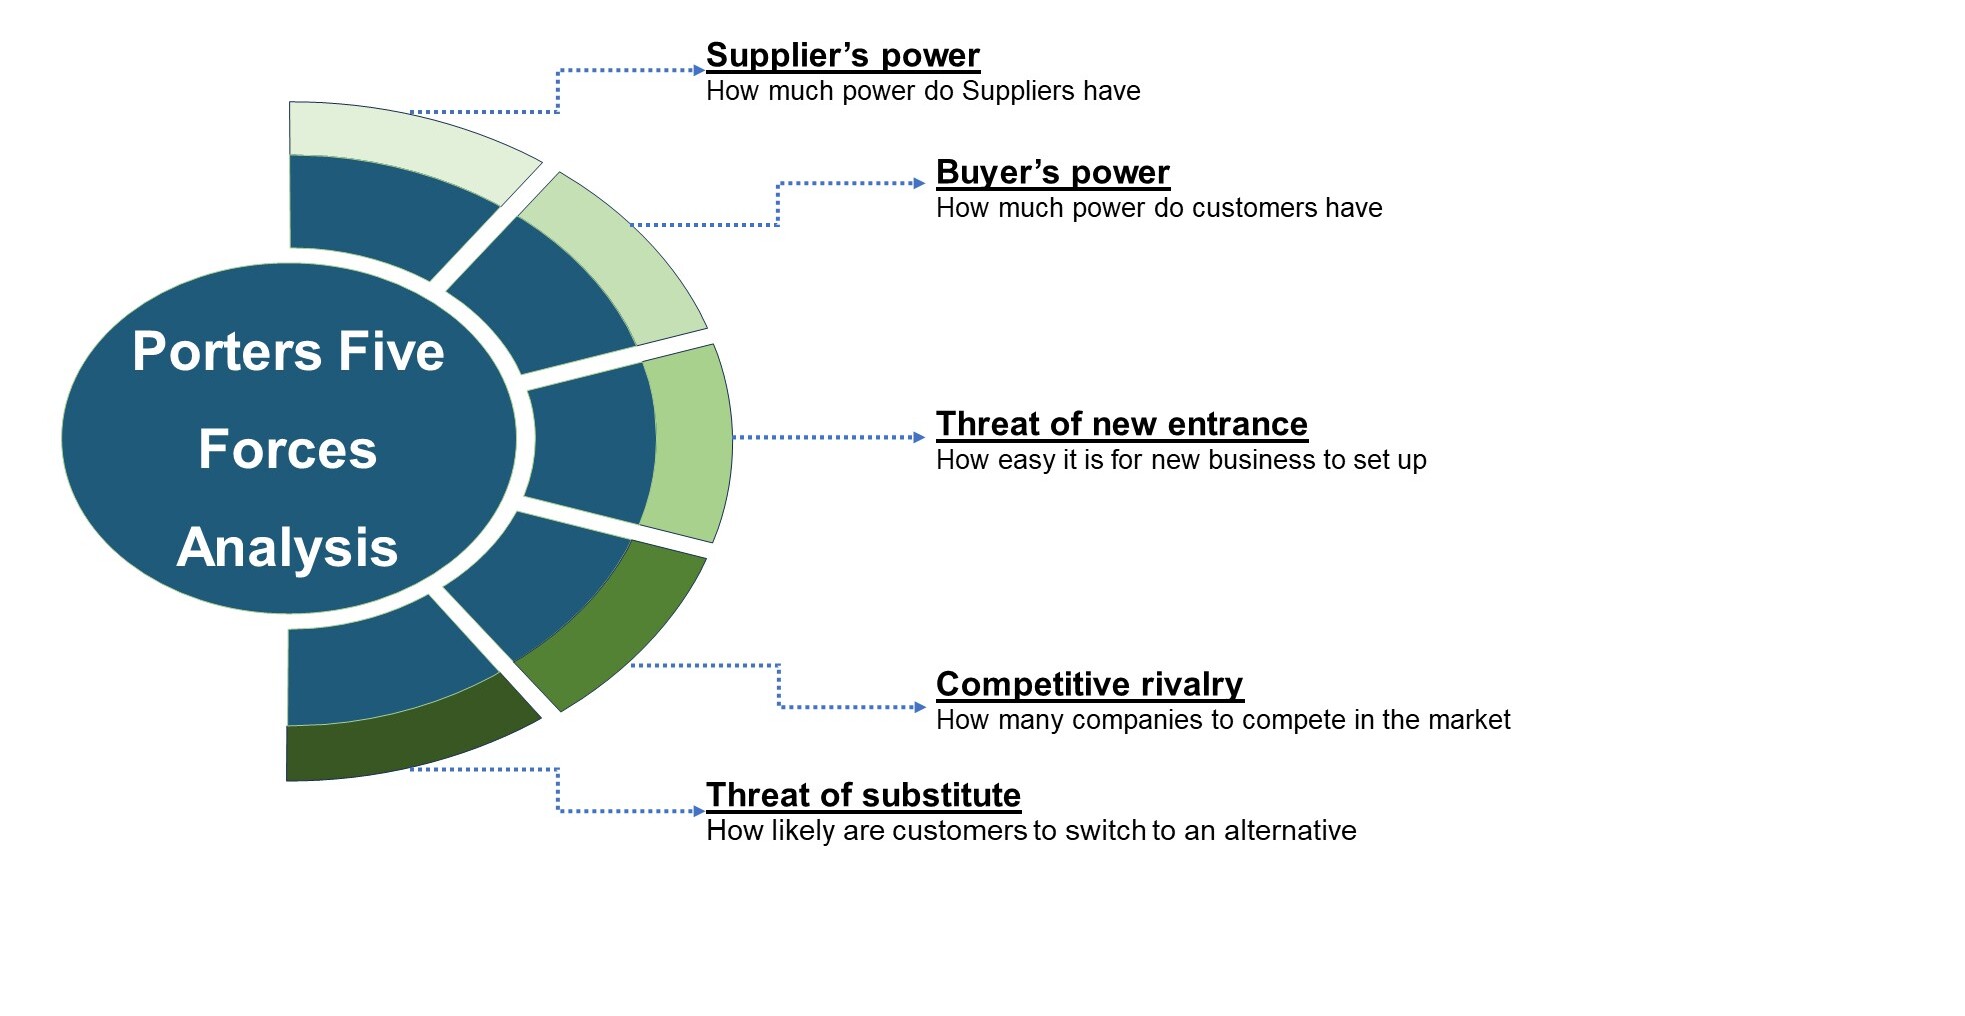
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.



 Speak to Our Analyst