Warehouse Picking Robot Market Global Industry Analysis and Forecast (2026-2035)

The global Warehouse Picking Robot Market size reached USD 2.96 billion in 2025 and is estimated at USD 3.41 billion in 2026, forecast to reach USD 7.53 billion by 2035 at a CAGR of 9.63% from 2026 to 2035. Key drivers include rising e-commerce order volumes, increasing SKU proliferation, persistent warehouse labor shortages, and growing adoption of Robotics as a Service (RaaS) models, with North America leading the market.
Download Free Sample PDF
Base Year (2025)
$2.96 Billion
Forecast (2035)
$7.53 Billion
CAGR (2026-2035)
9.6%
Top Region
North America

What Is the Warehouse Picking Robot Market Size?
The global Warehouse Picking Robot Market size reached USD 2.96 Billion in 2025 and is estimated at USD 3.41 Billion in 2026, forecast to reach USD 7.53 Billion by 2035 at a CAGR of 9.63% between 2026 and 2035, with North America leading at an approximate 40% revenue share and Fixed Picking Robots representing the dominant robot type segment at approximately 58% share in 2025.
We observed that rising e-commerce order volumes and structural labor constraints are reshaping picking infrastructure across all major end-user verticals globally.

Warehouse Picking Robot Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast
Values in USD Billion

2025 $2.96 Billion
2025
2026 $3.41 Billion
2026
2027 $3.74 Billion
2027
2028 $4.10 Billion
2028
2029 $4.49 Billion
2029
2030 $4.93 Billion
2030
2031 $5.40 Billion
2031
2032 $5.92 Billion
2032
2033 $6.49 Billion
2033
2034 $7.12 Billion
2034
2035 $7.53 Billion
2035

Key Takeaways

By Robot Type: Fixed Picking Robots held the largest share, expanding from USD 1.72 Billion in 2025 to USD 4.12 Billion by 2035; Mobile Picking Robots are the fastest-growing sub-segment at 10.89% CAGR from 2026–2035.

By Picking Type: Case Picking held the largest share, expanding from USD 1.28 Billion in 2025 to USD 3.16 Billion by 2035; Piece Picking is the fastest-growing sub-segment at 11.60% CAGR from 2026–2035.

By Payload Capacity: Light Payload held the largest share, expanding from USD 1.28 Billion in 2025 to USD 3.24 Billion by 2035; Medium Payload is the fastest-growing sub-segment at 11.66% CAGR from 2026–2035.

By Deployment: Integrated Deployment held the largest share, expanding from USD 1.54 Billion in 2025 to USD 4.09 Billion by 2035; Integrated Deployment is also the fastest-growing sub-segment at 11.41% CAGR from 2026–2035.

By Business Model: Capital Purchase held the largest share, expanding from USD 2.14 Billion in 2025 to USD 4.71 Billion by 2035; Robotics as a Service (RaaS) is the fastest-growing sub-segment at 14.69% CAGR from 2026–2035.

By End User: E-commerce Retail held the largest share, expanding from USD 1.04 Billion in 2025 to USD 2.85 Billion by 2035; E-commerce Retail is also the fastest-growing sub-segment at 11.79% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 40% revenue share in 2025, led by high-concentration e-commerce and 3PL fulfillment investment.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 12.44% from 2026–2035, anchored by China's e-commerce volumes and India's expanding logistics infrastructure.

Dominant Country: The U.S. led the market at approximately USD 0.93 Billion in 2025, underpinned by high-throughput fulfillment center demand.

Fastest-Growing Country: India is the fastest-growing country, supported by rising e-commerce penetration and government-backed logistics modernization programs.

The market presents an absolute investment opportunity of approximately USD 4.12 Billion between 2026 and 2035, calculated as the 2035 forecast value of USD 7.53 Billion minus the 2026 base of USD 3.41 Billion, positioning warehouse picking automation platforms as a high-conviction category for logistics technology investors.

According to NMSC analysis, the convergence of AI-driven grasping systems with scalable Robotics as a Service commercial models is extending picking robot addressable reach beyond large fulfillment centers into mid-market and regional distribution operations, broadening the total addressable operator base substantially through the 2035 forecast horizon.

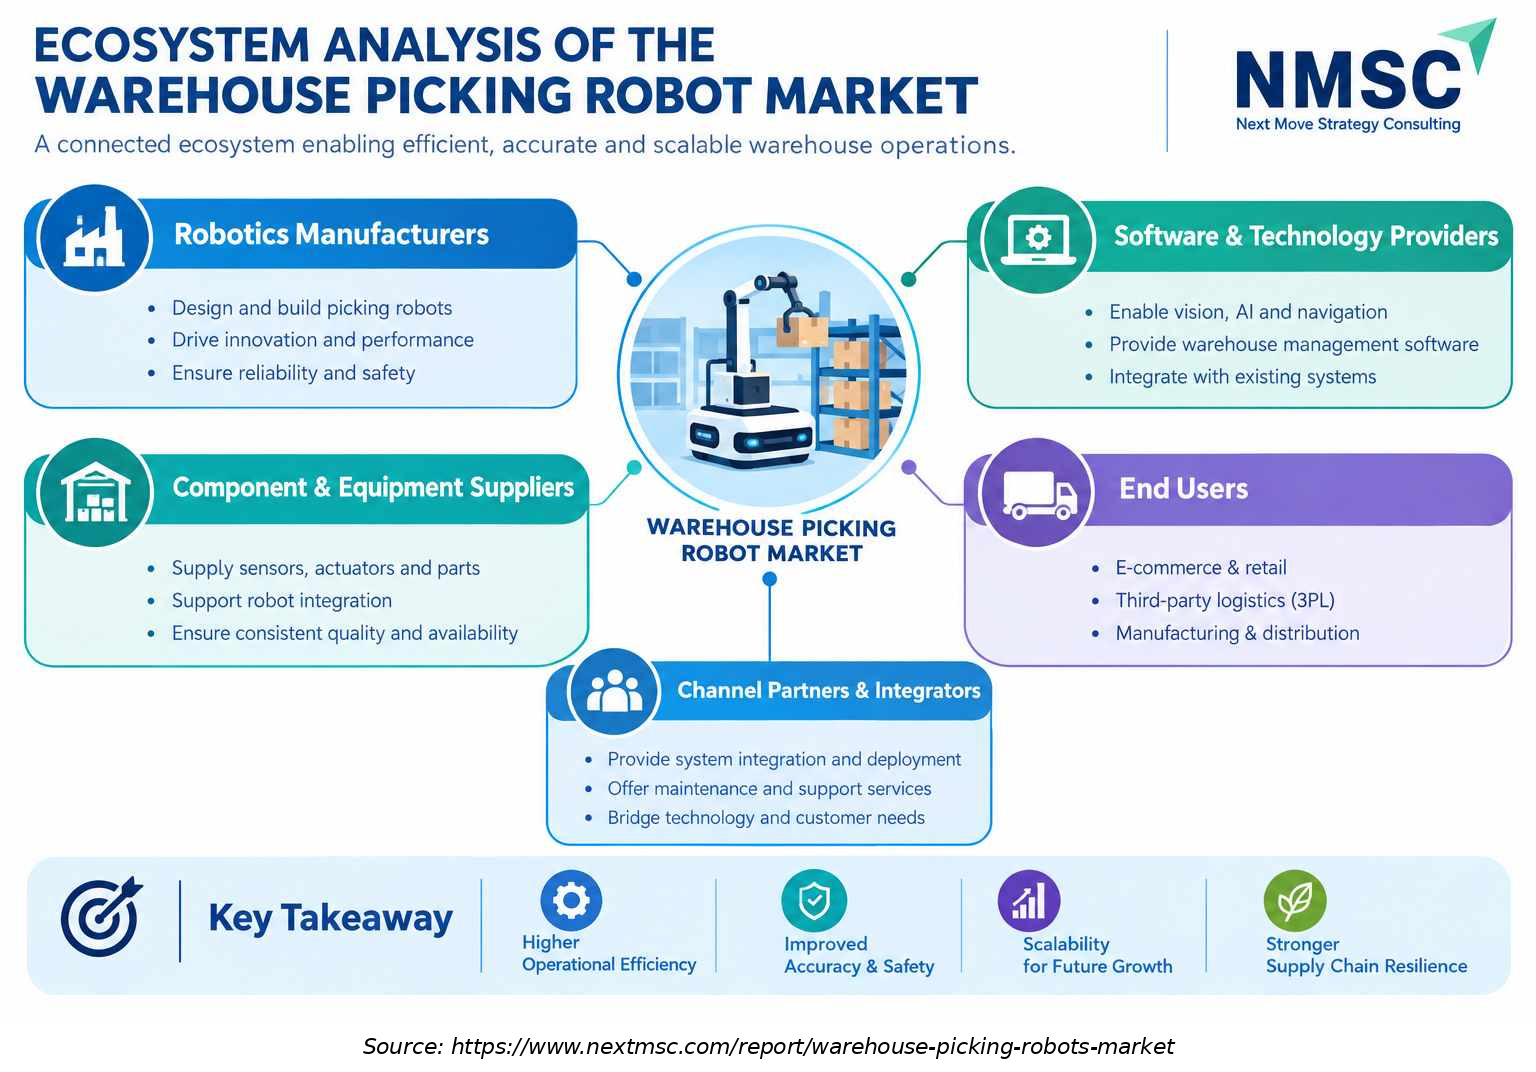
Ecosystem Analysis of the Warehouse Picking Robot Industry

The above infographic provides a detailed ecosystem analysis of the warehouse picking robot market, mapping out five key segments from robotics manufacturers to end users. It illustrates how component suppliers, software providers, and channel partners interact within a connected network to enable efficient and scalable warehouse operations. The analysis further highlights the significant value created by this ecosystem, including higher operational efficiency, improved accuracy, and stronger supply chain resilience. Ultimately, it demonstrates how this interconnected chain drives innovation and supports the future growth of logistics and distribution.

What Does the Warehouse Picking Robot Market Encompass?
The Warehouse Picking Robot Market covers fixed picking robots, articulated, delta, SCARA, and collaborative configurations, alongside mobile picking robots including picking AMRs, mobile manipulation robots, and autonomous case picking robots deployed for piece, case, and pallet handling operations. The market serves e-commerce retailers, third-party logistics providers, grocery and food distributors, pharmaceutical and healthcare operators, and manufacturing and industrial distributors. It excludes automated storage and retrieval systems and general-purpose floor robots not configured for picking workflows.
OSHA warehousing and robotics safety requirements, relevant consensus robotics safety standards, and applicable pharmaceutical quality and distribution regulations shape deployment requirements across end-user verticals. Our findings suggest that technology adoption is advancing along three converging pathways: AI-driven 3D vision for unstructured bin picking, Robotics as a Service commercial models that reduce initial capital barriers, and direct system integration with warehouse execution software platforms across both standalone workstation and full fulfillment system deployment architectures.

Market Parameters

Parameter Details
Market Size in 2025 USD 2.96 Billion
Market Size in 2026 USD 3.41 Billion
Revenue Forecast in 2035 USD 7.53 Billion
Growth Rate CAGR of 9.63% from 2026 to 2035
Analysis Period 2025–2035
Base Year Considered 2025
Forecast Period 2026–2035
Market Size Estimation USD Billion
Companies Profiled 20
Countries Covered 38
Market Share Available for Top 10 Companies
Source: www.nextmsc.com
Key Emerging Trends
During our market evaluation, we noticed that four structural shifts are redefining how warehouse operators design, procure, and scale picking robot deployments across all major end-user verticals.

How Is AI-Driven Vision Transforming Unstructured Bin Picking?

We found that AI-driven 3D vision systems are fundamentally changing unstructured bin picking, the historically most labor-intensive segment of warehouse operations. Deep learning models trained on diverse SKU libraries now achieve grasp-success rates exceeding 90% across mixed-inventory bins, a threshold that previously limited robot deployment to high-SKU-consistency applications. Vendors across the industrial robotics space, including Geekplus, RightHand Robotics, and Mujin, have deployed AI vision picking systems in live e-commerce fulfillment operations, demonstrating that technical barriers on irregular-item grasping are narrowing faster than prior adoption timelines assumed.

What Role Does Robotics as a Service (RaaS) Play in Expanding Market Access?

During our market evaluation, we noticed that Robotics as a Service commercial models are expanding market access beyond tier-one operators to mid-market fulfillment centers and regional distributors. Pay-per-pick and per-robot subscription pricing structures shift capital expenditure to operating expenditure, enabling operators without large upfront budgets to deploy picking automation at scale. Locus Robotics and GreyOrange have been prominent advocates for RaaS structures, while new entrants continue to expand this commercial model into grocery and pharmaceutical distribution verticals as adoption barriers fall.

How Are Mobile Picking Robots Enabling Flexible Goods-to-Person Workflows?

NMSC's analysis indicates that mobile picking robots enabling goods-to-person workflows are displacing legacy person-to-goods order fulfillment architectures across major distribution centers. Picking AMRs navigate dynamically mapped warehouse environments, retrieving inventory totes and presenting them at ergonomic picking stations, reducing operator travel distance by industry-derived estimates of 60-80%. Hai Robotics and Geekplus have deployed HAIPICK and P-series mobile manipulation systems in facilities processing hundreds of thousands of daily order lines, illustrating how mobile architectures support peak-demand scalability that fixed systems cannot match alone.

Why Is Multi-Robot Fleet Orchestration Becoming the Critical Competitive Differentiator?

Our assessment indicates that multi-robot fleet orchestration software is emerging as the decisive competitive differentiator in integrated picking deployments, replacing point solutions with platform architectures. Operators running hybrid fleets of fixed articulated arms, collaborative robots, and picking AMRs require orchestration middleware that dynamically assigns tasks based on real-time throughput, battery status, and order priority. Vendors with proprietary fleet management software, including KNAPP, Vanderlande, Dematic, and TGW, increasingly command premium pricing over hardware-only competitors, as software lock-in and data network effects reinforce customer retention.

Market Drivers & Dynamics

Interactive Dataset
Rising e-commerce order volume and SKU proliferation driver +3.2% Global 2026–2035
Labor cost inflation and warehouse workforce shortages driver +2.4% North America, Europe 2026–2033
Expansion of Robotics as a Service (RaaS) commercial models driver +1.8% Global 2026–2032
Advances in AI-driven grasping and 3D vision systems driver +1.5% North America, Asia-Pacific 2026–2031
Pharmaceutical and cold-chain distribution compliance requirements driver +0.9% North America, Europe 2026–2035
Growing adoption among 3PL and mid-market fulfillment operators driver +0.7% North America, Europe, APAC 2027–2035
High upfront capital expenditure for integrated picking systems restraint −1.4% Global 2026–2030
Low SKU standardization across retail and grocery verticals restraint −0.8% Global 2026–2032
Cybersecurity and system downtime risk in connected picking operations restraint −0.5% North America, Europe 2026–2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the Warehouse Picking Robot Market?

The primary growth driver is rising e-commerce order volume combined with accelerating SKU proliferation across fulfillment operations. The U.S. Census Bureau reported that U.S. e-commerce retail sales reached USD 1.19 Trillion in 2024, reflecting a sustained structural shift toward online order fulfillment that demands faster, higher-accuracy picking at lower labor cost per unit. Supply chain management pressures emerging from labor shortages, particularly post-pandemic attrition in warehouse operations, are further reinforcing capital investment in automated picking to maintain throughput capacity without proportional headcount growth across North America and Europe.

How Is the RaaS Commercial Model Driving Warehouse Picking Robot Market Growth?
Our analysis shows that Robotics as a Service adoption is materially expanding the addressable operator base beyond large integrators. Bureau of Labor Statistics data confirms sustained upward pressure on warehouse and storage worker wages across North America, creating a compelling total cost of ownership case for picking robot deployments even among operators with limited capital budgets. Per-pick subscription pricing structures, as deployed by Locus Robotics and GreyOrange, convert fixed hardware costs into variable operating costs that scale with fulfilment volumes, aligning automation investment with revenue cycles and reducing adoption barriers for mid-market operators significantly.

Growth Inhibitors

What Is Restraining the Warehouse Picking Robot Market?

We found that high upfront capital expenditure for fully integrated picking system deployments remains the primary restraint, particularly for small and mid-sized fulfilment operators evaluating automation for the first time. Industry-derived estimates suggest that a complete integrated picking cell deployment, including robotics hardware, vision systems, conveyor interfaces, and WMS integration, ranges from USD 500,000 to over USD 2 million per site, a capital commitment that materially extends payback periods for operators with moderate order volumes. This cost barrier is narrowing as RaaS adoption grows but remains meaningful through the early forecast period.

What Are the Growth Opportunities?

Can Expanded AI Vision Unlock High-Mix SKU Piece Picking at Scale?

Vendors advancing deep-learning grasping models capable of handling irregular, deformable, and fragile items, categories that currently require human intervention, can capture order picking volume across fashion, grocery, and pharmaceutical verticals that remain underserved by current piece picking automation. This opportunity directly benefits the Piece Picking segment and E-commerce Retail end-user category, where AI vision capability breadth translates directly into incremental order line automation and operating cost reduction at scale.

Does Robotics as a Service Open Mid-Market Fulfilment as a Structural Entry Point?

Companies structuring per-robot or usage-based subscription models can access the mid-market fulfilment operator segment, third-party logistics providers, and regional distributors that currently lack capital budgets for integrated system purchases, while autonomous forklifts and mobile picking robot fleets packaged under RaaS terms create accessible entry paths. This opportunity directly benefits the Robotics as a Service business model segment, and the Third-Party Logistics end-user segment as contract logistics operators compete increasingly on fulfilment speed and unit cost efficiency.

Can Pharmaceutical Distribution Automation Deliver High-Margin Vertical Expansion?

Operators combining certified pharmaceutical-grade collaborative robots with FDA-compliant audit trail and chain-of-custody software can address growing demand for automated picking in pharmaceutical distribution, where accuracy requirements, regulatory mandates, and controlled substance protocols make manual picking costly and error-prone. This opportunity benefits integrated deployment solutions and the Pharmaceuticals & Healthcare end-user segment with premium-priced, compliance-driven deployment contracts that yield higher margins than standard e-commerce fulfilment picking deployments.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Fixed Picking Robots 2025: $1.72 Billion | 2035: $4.12 Billion
Fixed Pickin
Mobile Picking Robots 2025: $1.24 Billion | 2035: $3.41 Billion
Mobile Picki
Fixed Picking Robots $1.72 Billion $4.12 Billion 9.31%
Mobile Picking Robots $1.24 Billion $3.41 Billion 10.89%

Which Robot Type Segment Leads the Warehouse Picking Robot Market?

Fixed Picking Robots account for approximately 58% of total 2025 market value at USD 1.72 Billion, anchored by articulated and SCARA robot deployments in high-throughput, structured bin picking environments across e-commerce and pharmaceutical fulfilment. Mobile Picking Robots, growing at 10.89% CAGR, are expanding faster as goods-to-person architectures gain traction at scale. Collaborative robots within the Fixed Picking segment are gaining share rapidly as workspace safety regulations push operators toward certified human-robot collaborative picking configurations across both North American and European facilities.

2025 (USD Billion)
2035 (USD Billion)
Piece Pickin
Bin Picking
Item Picking
Case Picking
Full Case Pi
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Piece Picking $10.0 USD Billion $40.0 USD Billion 25.0%
Bin Picking $17.1 USD Billion $51.1 USD Billion 11.0%
Item Picking $24.2 USD Billion $62.2 USD Billion 25.0%
Case Picking $31.3 USD Billion $73.3 USD Billion 11.0%
Full Case Picking $38.4 USD Billion $84.4 USD Billion 16.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Picking Type.

Unlock Full Data

Which Picking Type Segment Shows the Fastest Growth?

Case Picking holds the dominant share at USD 1.28 Billion in 2025, reflecting its established use in traditional retail and grocery distribution where standardized carton formats enable reliable robotic case handling. Piece Picking is the fastest-growing segment at 11.60% CAGR, driven by e-commerce SKU diversity demanding AI vision-guided bin and item picking. Our findings suggest that sortation systems integration with robotic piece picking lines is accelerating throughput in high-SKU-count fulfilment centers, creating demand for tighter software coordination between picking robots and downstream sortation infrastructure.

2025 (USD Billion)
2035 (USD Billion)
Light Payloa
Medium Paylo
Heavy Payloa
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Light Payload $10.0 USD Billion $40.0 USD Billion 27.0%
Medium Payload $17.1 USD Billion $51.1 USD Billion 9.0%
Heavy Payload $24.2 USD Billion $62.2 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Payload Capacity.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Standalone
Robot-Only D
Workstation
Integrated
Picking Cell
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Standalone $10.0 USD Billion $40.0 USD Billion 14.0%
Robot-Only Deployment $17.1 USD Billion $51.1 USD Billion 24.0%
Workstation Deployment $24.2 USD Billion $62.2 USD Billion 22.0%
Integrated $31.3 USD Billion $73.3 USD Billion 12.0%
Picking Cell Integration $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Deployment.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Capital Purc
Robot Sale
System Sale
Robotics as
Per-Robot Su
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Capital Purchase $10.0 USD Billion $40.0 USD Billion 24.0%
Robot Sale $17.1 USD Billion $51.1 USD Billion 22.0%
System Sale $24.2 USD Billion $62.2 USD Billion 20.0%
Robotics as a Service $31.3 USD Billion $73.3 USD Billion 22.0%
Per-Robot Subscription $38.4 USD Billion $84.4 USD Billion 13.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Business Model.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
E-commerce R
E-commerce F
Retail Distr
Third-Party
Contract Log
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
E-commerce Retail $10.0 USD Billion $40.0 USD Billion 23.0%
E-commerce Fulfillment $17.1 USD Billion $51.1 USD Billion 9.0%
Retail Distribution $24.2 USD Billion $62.2 USD Billion 19.0%
Third-Party Logistics $31.3 USD Billion $73.3 USD Billion 13.0%
Contract Logistics $38.4 USD Billion $84.4 USD Billion 10.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data

Which End-User Segment Dominates the Warehouse Picking Robot Market?

E-commerce Retail leads both dominance and growth, accounting for USD 1.04 Billion in 2025, approximately 35% of total market value, and growing at 11.79% CAGR toward USD 2.85 Billion by 2035. High order velocity, broad SKU ranges, and intense fulfillment cost competition among e-commerce operators drive concentrated picking automation investment in this segment. Third-Party Logistics is the second-largest end user at USD 0.69 Billion, with contract logistics operators investing in picking robots to compete on speed and unit cost across multi-client fulfillment mandates. Pharmaceuticals & Healthcare at 10.16% CAGR reflects compliance-driven automation momentum.

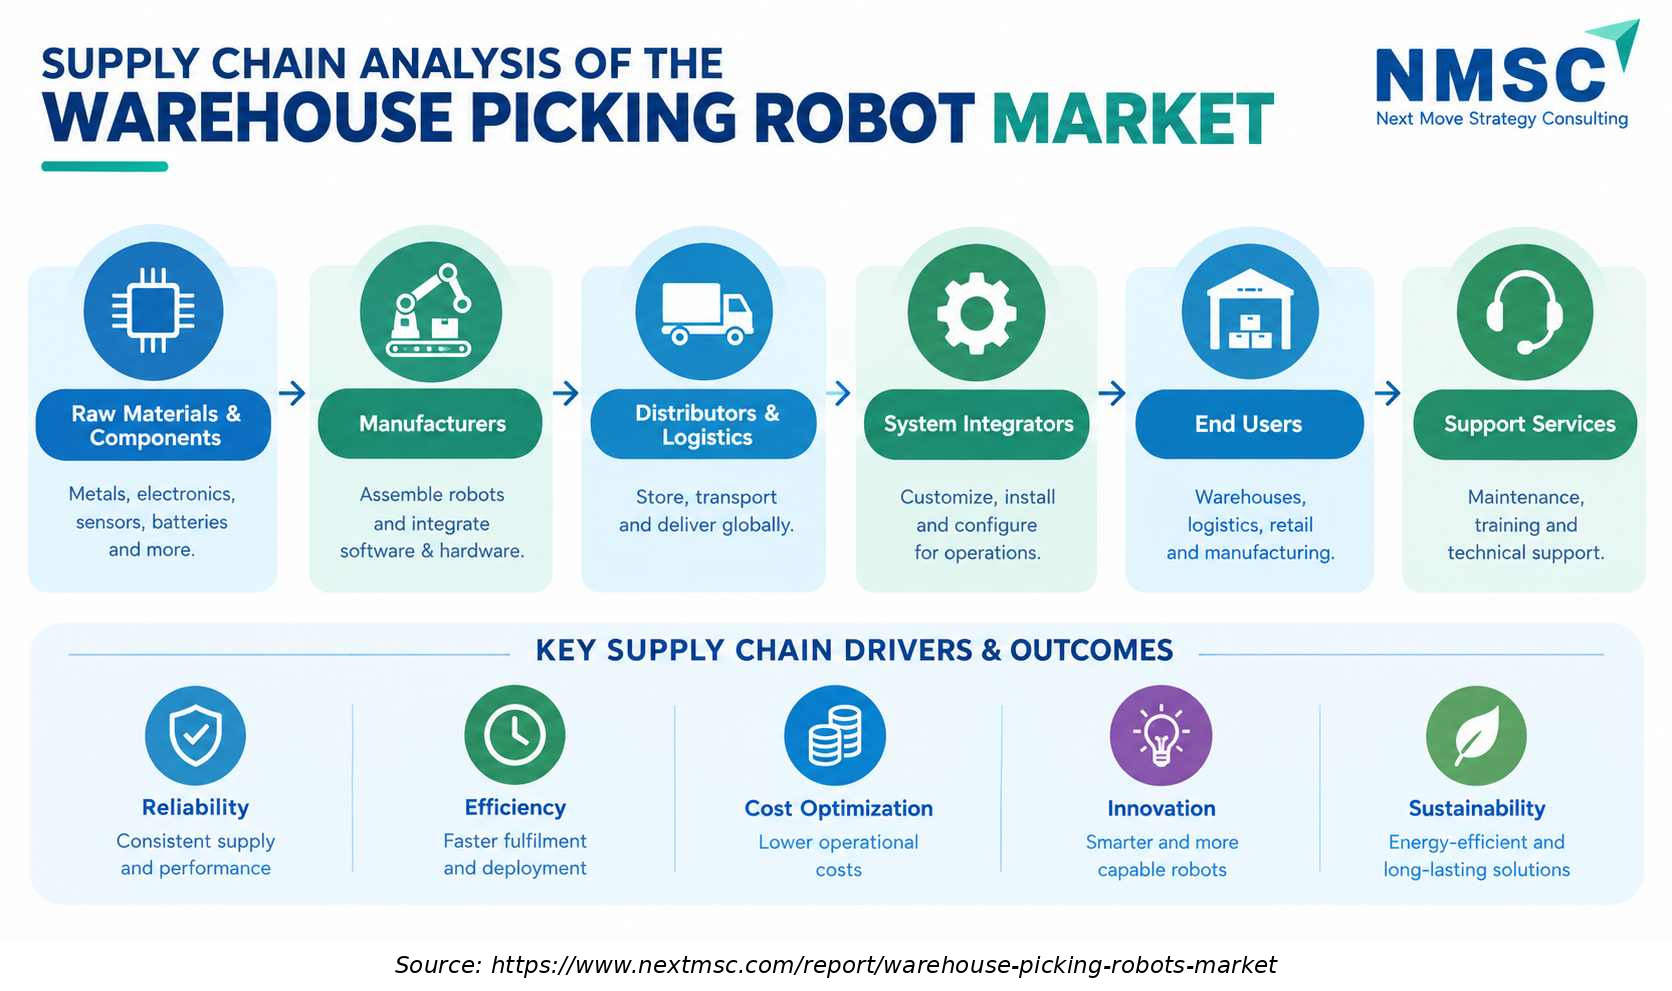
Supply Chain Analysis of the Warehouse Picking Robot Industry

Supply Chain Analysis of the Warehouse Picking Robot Industry
The above infographic provides a detailed supply chain analysis of the warehouse picking robot market, outlining a six-step flow from raw materials to support services. It traces the process from sourcing components and manufacturing through distribution, system integration, and final deployment in warehouses. The analysis further highlights key supply chain drivers such as reliability, cost optimization, and efficiency that shape the industry. Ultimately, it demonstrates how this interconnected chain delivers smarter, more capable robots that drive consistent performance and sustainable logistics operations.

Growth Opportunities

Three forward-looking opportunities represent the highest-value whitespace for vendors, investors, and operators in the Warehouse Picking Robot Market through 2035.
Can Expanded AI Vision Unlock High-Mix SKU Piece Picking at Scale?

Vendors advancing deep-learning grasping models capable of handling irregular, deformable, and fragile items, categories that currently require human intervention, can capture order picking volume across fashion, grocery, and pharmaceutical verticals that remain underserved by current piece picking automation. This opportunity directly benefits the Piece Picking segment and E-commerce Retail end-user category, where AI vision capability breadth translates directly into incremental order line automation and operating cost reduction at scale.

Does Robotics as a Service Open Mid-Market Fulfilment as a Structural Entry Point?

Companies structuring per-robot or usage-based subscription models can access the mid-market fulfilment operator segment, third-party logistics providers, and regional distributors that currently lack capital budgets for integrated system purchases, while autonomous forklifts and mobile picking robot fleets packaged under RaaS terms create accessible entry paths. This opportunity directly benefits the Robotics as a Service business model segment, and the Third-Party Logistics end-user segment as contract logistics operators compete increasingly on fulfilment speed and unit cost efficiency.

Can Pharmaceutical Distribution Automation Deliver High-Margin Vertical Expansion?

Operators combining certified pharmaceutical-grade collaborative robots with FDA-compliant audit trail and chain-of-custody software can address growing demand for automated picking in pharmaceutical distribution, where accuracy requirements, regulatory mandates, and controlled substance protocols make manual picking costly and error-prone. This opportunity benefits integrated deployment solutions and the Pharmaceuticals & Healthcare end-user segment with premium-priced, compliance-driven deployment contracts that yield higher margins than standard e-commerce fulfilment picking deployments.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Asia-Pacific
Europe
Latin Americ
Middle East
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Asia-Pacific $17.1 USD Billion $51.1 USD Billion 27.0%
Europe $24.2 USD Billion $62.2 USD Billion 25.0%
Latin America $31.3 USD Billion $73.3 USD Billion 23.0%
Middle East & Africa $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

Our assessment indicates that the competitive landscape spans integrated fulfillment automation platform leaders, specialized industrial robot manufacturers, and regional mobile robot specialists, each competing on grasping capability breadth, fleet orchestration software depth, and end-user vertical account penetration.

Dimension Description
Market Structure Moderately consolidated; top 10 companies hold the majority of market share, led by platform integrators alongside established industrial robot OEMs and regional mobile robot specialists
Innovation Focus AI-driven 3D grasping, multi-robot fleet orchestration middleware, expanded payload handling, RaaS commercial model development, and WMS deep-integration capability
M&A Activity Strategic acquisitions of vision AI software firms and system integrators to expand fulfillment platform breadth; PE-backed consolidation among mid-market system integrators

How Do Companies Compete in the Warehouse Picking Robot Market Industry?
Companies compete primarily on three dimensions: grasping accuracy and SKU handling breadth for piece picking applications, depth of fleet orchestration and WMS integration capability for integrated deployment contracts, and commercial flexibility across capital purchase and RaaS models for mid-market operator access. During our market evaluation, we noticed that vendors with proprietary fleet management software hold structural advantages over hardware-only competitors, as software network effects and data-driven picking optimization create durable switching costs that reinforce customer retention through long-term service contracts.

Which Competitive Archetypes Dominate the Warehouse Picking Robot Industry?

Diversified fulfillment automation platform leaders such as Daifuku, KNAPP, Dematic, and Vanderlande dominate through integrated conveyor, storage, and picking system packages spanning multiple robot types and deployment scales. Specialized mobile robot vendors including Geekplus, Hai Robotics, GreyOrange, and Locus Robotics differentiate through proprietary AMR fleet management software and scalable goods-to-person architectures, while industrial robot OEMs including FANUC, ABB, KUKA, and Yaskawa compete on arm-level hardware precision and reliability for high-throughput fixed picking cell applications.

What Innovation and Differentiation Strategies Are Shaping the Competitive Dynamic?

Based on research conducted by NMSC, we found that generative AI and foundation model techniques are beginning to enter picking robot grasping systems, enabling models trained on broad object datasets to transfer to novel SKU categories with reduced retraining burden. Exotec and Mujin are among vendors publishing results on AI-assisted picking accuracy improvements, while RightHand Robotics has positioned its AI-first RightPick platform directly against conventional rule-based vision systems in high-SKU-variety bin picking environments.

What M&A Activity Has Characterized the Warehouse Picking Robot Market?

M&A activity has been characterized by selective capability acquisitions focused on AI vision and fleet management software rather than large-scale hardware manufacturer consolidation. Strategic investments by logistics system integrators in grasping AI startups and software platform companies signal vendor intent to build end-to-end orchestration capability, while private equity investment activity reflects sustained confidence in mid-market picking automation demand. Geographic expansion through regional system integrator partnerships has been another key strategic mechanism, particularly for Asian vendors entering European and North American markets.

Key Market Players

Based on research conducted by NMSC, we found that the following 20 companies represent the leading participants across platform integration, hardware manufacturing, mobile robotics, and software-driven picking automation in the global Warehouse Picking Robot Market.

Geekplus Technology Co., Ltd. Locus Robotics Corporation Daifuku Co., Ltd. KNAPP AG SSI SCHAEFER GmbH Vanderlande Industries B.V. Dematic GmbH Exotec SAS Hai Robotics Co., Ltd. GreyOrange Pte. Ltd. Quicktron Intelligent Technology Co., Ltd. Mujin, Inc. Fives Group TGW Logistics Group GmbH RightHand Robotics, Inc. FANUC Corporation ABB Ltd KUKA AG OMRON Corporation Yaskawa Electric Corporation

Latest Developments

We observed that 2024–2025 saw a concentration of product launches, fleet expansion announcements, and strategic partnership activity among leading Warehouse Picking Robot Market participants, with AI vision integration and RaaS model scale being the dominant themes.

Date Event
September 2026 SSI SCHAEFER integrated its SSI Piece Picking robotic solution into Würth Industrie Service’s logistics center. The robotic cell automates consolidation of pre-picked items, using real-time item identification and automated pick-and-place operations.
September 2026 Hai Robotics was selected to deploy more than 1,500 HaiPick Climb robots for a major European fashion retailer’s e-commerce fulfillment center.
March 2026 Geekplus launched RoboShuttle V5, integrating its Robot Arm Picking Station with tote-to-person automation. The system uses AI vision and zero-shot learning for autonomous item picking, with stated accuracy of 99.99% and throughput of up to 700 units per hour.

Expert Insights

Amit Kalra

Executive Vice President and Chief Supply Chain Officer | Staples

"When the arms are not picking orders for our customers, they are picking thousands of items to practice, learn and perfect the picking approach for new items, just like a human would learn."

Analyst Interpretation

We observed that continuous learning is expanding the functional capabilities of robotic picking systems in warehouses handling diverse product assortments. NMSC’s analysis indicates that AI, machine vision, and adaptive grasping technologies are enabling picking robots to recognize and handle greater variations in product shape, size, weight, and packaging while reducing dependence on manual intervention. This evolution is strengthening the application of robotic picking across high-SKU fulfillment environments, particularly as e-commerce and retail operators pursue higher picking accuracy, faster order processing, and greater automation flexibility.

Investment Opportunities

Where Are the Highest-Return Capital Inflows Flowing in Warehouse Picking Automation?

Capital inflows are concentrating in three areas: AI vision and grasping software platforms, RaaS fleet financing structures, and integrated fulfillment system integrators building multi-site deployment capability at scale. Venture and growth equity investment in picking robot software platforms sustained high activity through 2024–2025, reflecting investor confidence in software-driven recurring revenue models over hardware-only market exposures. RaaS-structured assets generate predictable, volume-correlated cash flows that align well with infrastructure-style investment mandates, positioning AI picking platforms as premium targets within the broader logistics technology investment universe.

What Infrastructure Investment Is Required to Support Picking Robot Scale Deployment?

Scaling Warehouse Picking Robot Market adoption requires investment in three infrastructure layers: structured warehouse physical environments with defined pick zones, tote-conveyor, and sortation system interfaces; robust connectivity and real-time data infrastructure for robot fleet telemetry and WMS communication; and e-commerce packaging standardization that optimizes SKU presentation for consistent robotic pick execution. Warehouse ergonomics requirements and robot-ready distribution-center design represent additional infrastructure enablers that reduce retrofit complexity.

How Are ESG Considerations Shaping Investment Decisions in Picking Automation?

Our findings suggest that ESG criteria are beginning to influence picking automation investment decisions, as operators quantify energy efficiency gains from robot-operated versus labor-intensive fulfillment, reduced workplace injury claims from automation of ergonomically stressful pick tasks, and carbon footprint reductions from optimized routing within automated fulfillment centers. GRI-aligned sustainability reporting frameworks and investor ESG due diligence processes are creating additional disclosure incentives for operators to document and quantify automation-driven workplace and environmental performance improvements across portfolio fulfillment assets.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise Warehouse Operators and Logistics Leaders?

Warehouse operators and logistics leaders gain precise market sizing and segmentation-level revenue data across robot type, picking type, payload capacity, deployment model, business model, and end-user vertical axes, enabling evidence-based capital planning for picking automation programs. The report's competitive landscape analysis and Growth Catalyst & Risk Assessment Matrix support vendor selection decisions and risk-adjusted ROI modelling across both capital purchase and RaaS deployment structures, with regional and country-level insights informing multi-site expansion sequencing through 2035.

What Value Do Investors and Financial Analysts Derive from This Analysis?

Investors and financial analysts access the report's USD 4.12 Billion absolute investment opportunity quantification, segment-level CAGR differentiation across six segmentation axes, and competitive archetype analysis mapping platform leaders, hardware OEMs, and mobile robot specialists. The 2026–2035 forecast horizon, underpinned by identified drivers including e-commerce volume growth, labor inflation, and RaaS commercial model expansion, provides the quantitative foundation for portfolio construction, target screening, and due diligence processes in warehouse automation and logistics technology investment. Rich sensors and vision technology data embedded within segment analysis add further technical depth for deeptech and robotics-focused investment mandates.

How Do Technology Vendors and Product Teams Benefit from This Market Report?

Technology vendors and product teams use this report's segmentation analysis, spanning By Robot Type, By Picking Type, By Deployment, By Business Model, and By End User axes, to identify whitespace opportunities, benchmark pricing against business model norms, and prioritize vertical market entry strategies. The competitive landscape analysis, innovation focus assessment, and M&A activity review provide product roadmap context for positioning differentiated AI vision, fleet orchestration, and RaaS commercial model capabilities against the incumbent and emerging vendor set through the 2035 forecast horizon.

Key Market Segments Evaluated

By Robot Type

  • Fixed Picking Robots 
    • Articulated Robots
    • Delta Robots
    • SCARA Robots
    • Collaborative Robots
  • Mobile Picking Robots 
    • Picking AMRs
    • Mobile Manipulation Robots
    • Autonomous Case Picking Robots

By Picking Type

  • Piece Picking 
    • Bin Picking
    • Item Picking
  • Case Picking 
    • Full Case Picking
    • Mixed Case Picking
  • Pallet Picking 
    • Layer Picking
    • Full Pallet Picking

By Payload Capacity

  • Light Payload
  • Medium Payload
  • Heavy Payload

By Deployment

  • Standalone 
    • Robot-Only Deployment
    • Workstation Deployment
  • Integrated 
    • Picking Cell Integration
    • Fulfillment System Integration

By Business Model

  • Capital Purchase 
    • Robot Sale
    • System Sale
  • Robotics as a Service 
    • Per-Robot Subscription
    • Usage-Based Subscription

By End User

  • E-commerce Retail 
    • E-commerce Fulfillment
    • Retail Distribution
  • Third-Party Logistics 
    • Contract Logistics
    • Fulfillment Services
  • Grocery Food 
    • Grocery Distribution
    • Food Distribution
  • Pharmaceuticals Healthcare 
    • Pharmaceutical Distribution
    • Healthcare Distribution
  • Manufacturing Industrial 
    • Industrial Distribution
    • Component Distribution
    • Others

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook remains structurally positive, with the market expanding from USD 3.41 Billion in 2026 to USD 7.53 Billion by 2035 at a 9.63% CAGR, driven by sustained e-commerce volume growth, labor cost inflation, and accelerating RaaS adoption. We observed that this growth trajectory reflects durable operational and demographic tailwinds rather than speculative technology cycles, supporting sustained capital investment in AI-driven grasping systems, mobile picking architectures, and integrated fleet orchestration platforms across all major end-user verticals through the 2035 forecast horizon.

What Strategic Positioning Do We Recommend in the Market?

Our assessment indicates that vendors should prioritize AI grasping capability development and fleet orchestration software depth to capture the fastest-growing Piece Picking and Mobile Picking Robots segments. Companies without established software ecosystems should pursue platform partnerships or targeted acquisitions rather than standalone hardware strategies, given the market's structural shift toward integrated deployment models where orchestration software creates recurring revenue and customer retention advantages that hardware-only competitors cannot replicate through the forecast period.

How Attractive Is the Warehouse Picking Robot Market for Investment?

Investment attractiveness is high in Asia-Pacific given a superior CAGR of 12.44%, while North America offers the largest absolute revenue base at USD 2.97 Billion by 2035 with strong RaaS-driven recurring demand. NMSC's analysis indicates that Robotics as a Service revenue streams and AI vision software platforms offer stronger margin and growth profiles than mature fixed picking hardware segments, positioning software-first vendors and RaaS platforms as premium investment targets within the broader logistics automation market through 2035.

What Are the Key Market Shifts and Risks?

Key risks include persistent high upfront capital expenditure constraining integrated system adoption among mid-market operators, and low SKU standardization across retail and grocery verticals limiting AI grasping generalization performance at commercially acceptable error rates. Our analysis shows that vendors unable to demonstrate verifiable grasping accuracy and system uptime guarantees across diverse SKU environments risk losing integrated deployment contracts to platform vendors with documented, auditable performance track records across live fulfillment operations throughout the forecast period.

What Are the Primary Growth Pathways Through 2035?

Primary growth pathways include AI-driven expansion of piece picking capability to high-mix, irregular-item SKU categories; RaaS commercial model scale among mid-market 3PL and fulfillment operators; and pharmaceutical distribution automation tied to regulatory compliance mandates. We found that companies combining all three pathways, technical grasping breadth, commercial model flexibility, and vertical-specific compliance expertise, are best positioned to capture a disproportionate share of the USD 4.12 Billion absolute opportunity created between 2026 and 2035 in the Warehouse Picking Robot Market.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market Growth Analysis
  • Historical revenue and unit shipment analysis of warehouse picking robots by robot type, picking type, and payload capacity.
  • Identifies fastest-growing robot categories and sets investment and portfolio priorities.
Company-Level Robot Shipment Analysis
  • Company-level picking robot shipments and installed units benchmarking across key vendors by robot type and deployment mode.
  • Shows vendor scale and share shifts to guide competitive positioning and partnership choices.
Company-Level Product Share Analysis
  • Share of leading vendors' picking robot models and product lines across robot type, picking type, and payload capacity.
  • Reveals product portfolio gaps and white-space opportunities for new launches.
End-User Adoption and Use Case Mapping
  • Mapping of picking robot adoption by end user, picking type, and payload capacity, covering e-commerce, retail, 3PL, grocery, and manufacturing warehouses.
  • Prioritizes target verticals and matches robot configurations to customer needs.
Business Model and Pricing Benchmarking
  • Benchmarking of Robots-as-a-Service versus outright purchase offerings, with pricing, contract structures, and deployment type comparisons from public vendor disclosures.
  • Supports pricing strategy and commercial model design to speed up customer adoption.
Deployment Economics and ROI Assessment
  • Comparison of cloud-based versus on-premise deployments and brownfield versus greenfield warehouse use, with payback and labor-productivity benchmarks from published case studies.
  • Helps build the investment case for buyers and refines go-to-market messaging for vendors.

FAQs

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Mohit Agarwal

MOHIT AGARWAL

Chief Manager

DryChem India Pvt. Ltd.

Next Move Strategy Consulting is an amazing team of consultants. We required a market study report for our investors on top priority and the team went above and beyond our expectations to deliver the same with ample supporting data within a short time span enabling us to secure the investments and keep our project timeline maintained. Their professionalism, attention to detail, and timely delivery of actionable recommendations have left a lasting impression on our organization.

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖