AI CCTV Trends: Smarter Surveillance for Safer Cities

As per NMSC analysis, the AI CCTV market was valued at USD 14.79 billion in 2023 and is projected to reach USD 63.68 billion by 2030, growing at a CAGR of 21.3% from 2024 to 2030. That growth is no longer just about adding more cameras 2026 has been the year video-surveillance vendors shipped agentic AI that acts on what a camera sees, rather than simply flagging it for a human to review.
Asia Pacific continues to hold the largest regional share, anchored by China's domestic manufacturing base and government-funded smart-city programs, while North America has seen substantial growth on the back of school, retail, and public-safety investment. Here is where the technology stands today, who is moving fastest, and what the next few years of adoption look like.
AI CCTV Market Overview
AI CCTV refers to closed-circuit video systems that use machine learning to interpret footage in real time recognizing objects, faces, and behavior patterns rather than just recording passively. NMSC segments the market by component (hardware, including cameras and storage devices, and software, including video analytics and video management platforms), by camera type (dome, bullet, and box), by deployment (cloud-based and on-premise), and by end user (commercial, residential, and industrial).
AI CCTV Market Size and Forecast, 2023–2030
|
Parameter |
2023 |
2030 |
CAGR (2024–2030) |
|
Global AI CCTV Market Size |
$14.79B |
$63.68B |
21.3% |
|
Companies Profiled / With Market Share Data |
15 profiled |
10 with disclosed share |
|
Section takeaway: the market's growth is arriving alongside a genuine shift in what a camera does from passive recording toward autonomous detection and response.
-
Market more than quadruples between 2023 and 2030 at a 21.3% CAGR
-
Fifteen companies are profiled in NMSC's competitive landscape; ten have disclosed market-share data
-
Software video analytics and video management is the fastest-growing component as vendors push deeper into AI
What's Driving AI CCTV Market Growth?
How Are Smart City Programs Fueling Adoption?
Government-funded urban surveillance remains the single biggest growth driver. India's Smart Cities Mission identified 100 cities for development, and Seoul's government has moved to outfit its entire public CCTV network including parks and hiking trails with AI capable of autonomously identifying suspects and assault incidents. NMSC's dedicated Smart Cities Market research tracks this broader infrastructure spend in more depth than the AI CCTV category alone.
How Is Cloud-Based Storage Changing AI CCTV Deployment?
Cloud-based video is steadily displacing on-site hardware for organizations that need multi-location access without maintaining local servers. Platforms such as Coram illustrate how modern cloud systems let organizations centralize footage, search incidents across sites, and cut reliance on on-premise infrastructure a shift that is also reshaping how smaller businesses budget for surveillance, since cloud deployment lowers the upfront hardware cost that has historically limited adoption.
How Do 5G and Edge Computing Expand What's Possible?
Edge processing paired with 5G connectivity lets cameras analyze footage on-device rather than routing everything to a central server, cutting the latency between detection and response. Buying guides such as Pelco's overview of AI security cameras point to the same trend from the integrator side: edge AI processing is now a baseline expectation for new commercial camera deployments, not a premium feature.
Section takeaway: smart-city funding, cloud storage economics, and edge/5G convergence are reinforcing each other each makes AI CCTV cheaper or more capable to deploy at scale.
-
Government smart-city and public-safety programs remain the largest single demand driver
-
Cloud-based deployment is lowering the up-front cost barrier that limited adoption among smaller organizations
-
Edge AI processing paired with 5G is now a baseline feature in new commercial camera lines, not a premium add-on
Regional AI CCTV Adoption
China holds the largest share within Asia Pacific, reflecting the domestic presence of Hikvision and other major manufacturers alongside sustained government R&D funding for AI-powered surveillance. Japan and South Korea have both run high-profile public deployments Japanese police piloted AI-equipped cameras to protect public figures, while South Korea committed roughly $287 million toward digital-transformation projects that included expanded AI-CCTV deployment. North America has also seen substantial growth, driven by education, retail, and public-safety spending U.S. school districts, for instance, have allocated dedicated budget lines specifically for AI-equipped camera infrastructure.
Section takeaway: Asia Pacific's lead is structural it’s where the largest manufacturers are based while North America's growth is being pulled forward by sector-specific safety spending.
-
Asia Pacific holds the largest overall regional share, led by China
-
Japan and South Korea have both run notable public-sector AI CCTV pilots and funding programs
-
North America's growth is concentrated in education, retail, and public-safety deployments
Industry Leader Moves: How Top AI CCTV Vendors Are Competing in 2026
2026 has been a year of both product launches and corporate restructuring across the sector. Enterprises evaluating a camera-fleet upgrade are increasingly weighing not just AI features but which vendors' ownership structures and roadmaps are actually stable.
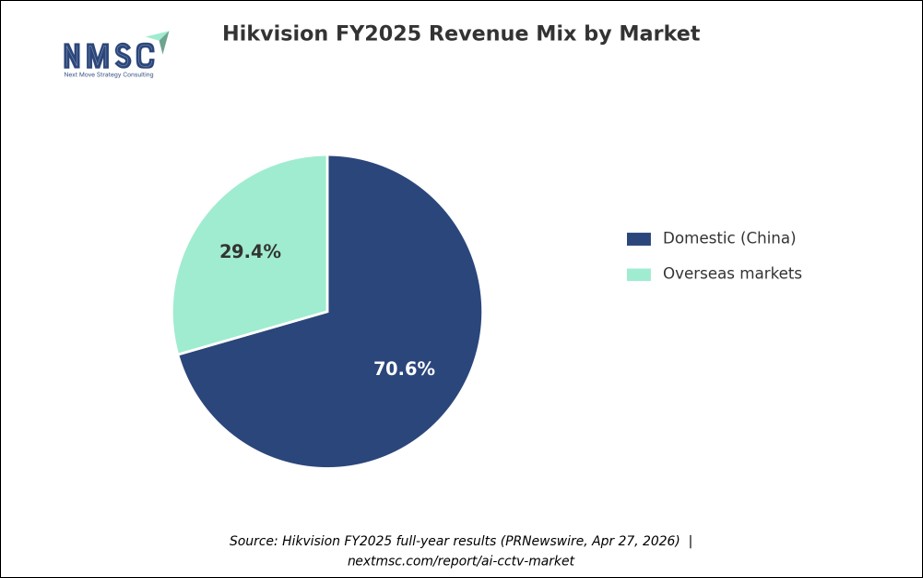
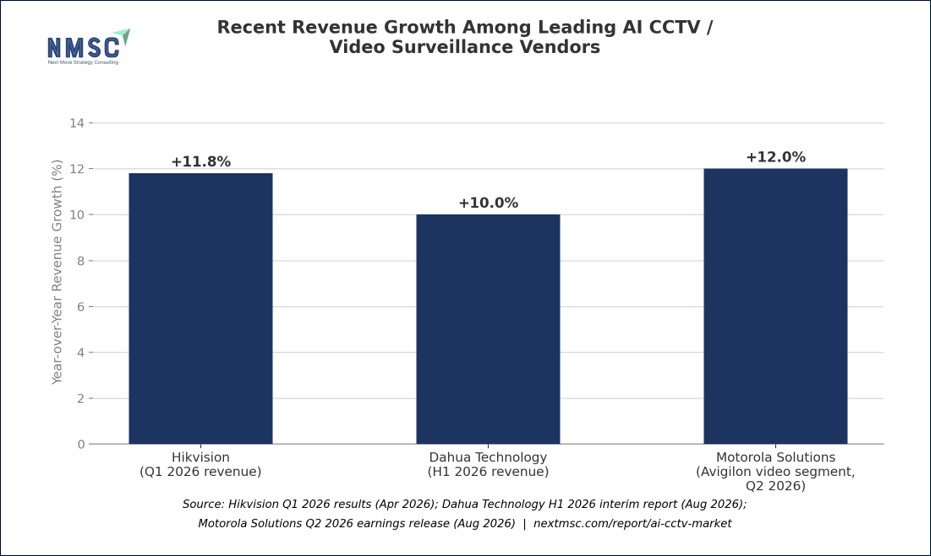
Hikvision closed fiscal 2025 with revenue of RMB 92.51 billion (~$12.95B), essentially flat year-over-year, but entered 2026 with clearly stronger momentum: Q1 2026 revenue rose 11.78% to RMB 20.72 billion, with net profit up 36.42%, driven partly by across-the-board product price increases and continued growth in its AIoT and non-video product lines (access control, alarms, commercial displays), which together contributed over a quarter of total revenue. On the product side, Hikvision partnered with Neural Labs in March 2026 to embed vehicle analytics and automatic number-plate recognition into its DeepinView camera line for smart-city and intelligent-transportation use cases, and has continued expanding its Guanlan large-scale AI model across its camera portfolio.
Dahua Technology, the world's second-largest video-surveillance manufacturer by most industry accounts, reported first-half 2026 revenue of RMB 16.7 billion (~$2.5B), up 10.03% year-over-year, though net profit slipped 3.74% on higher costs. Dahua's 2026 product push has centered on its Xinghan Large-Scale AI Model 2.0 unveiled at Intertraffic Amsterdam in March 2026 which combines vision, multimodal, and language-understanding components for intelligent transportation applications, and its September 2026 WITHS wireless AI camera series aimed at SME customers across the GCC and wider MENA region.
Hanwha Vision underwent the sector's most significant corporate restructuring of 2026: on August 3, 2026, its parent group launched Hanwha M&S, a new standalone holding company combining Hanwha Vision's AI camera business with Hanwha Semitech's semiconductor equipment operations. The combined 57 affiliates generated roughly ₩6 trillion (~$4.2B) in sales, and the new entity is positioned by multiple 2026 NDAA-compliance procurement guides as the leading alternative to Hikvision for U.S. government buyers, built around Hanwha's Wisenet 9 dual-NPU chip. On the product side, Hanwha Vision spent 2026 rolling out 2nd-generation X-series AI compact, fisheye, and thermal cameras.
Axis Communications used ISC West 2026 (March 25–27) to introduce a wave of edge-AI hardware including the ARTPEC-9-powered AXIS P1486-LE global shutter camera and a private-cellular back box that lets cameras connect to enterprise networks without wired infrastructure but its most distinctive 2026 move was continuing its collaboration with UC San Diego's ALERTCalifornia program, which now runs AI-based early wildfire detection across a statewide network of more than 1,200 cameras.
Bosch's video-surveillance business is no longer part of Bosch: the divestment to European investment firm Triton, first announced in 2023, completed in 2025, and the unit now operates independently as Keenfinity Group. In late 2025 Keenfinity restructured into a four-business holding company, and in February 2026 launched IQSIGHT, a new AI-enabled layer added to the (still Bosch-branded) video portfolio designed to reduce blind spots in monitoring.
Honeywell spent 2026 in the middle of a broader corporate breakup rather than camera-specific announcements: it spun off Solstice Advanced Materials, agreed to sell its Productivity Solutions and Services business to Brady Corporation for $1.4 billion in April 2026, and is proceeding with a planned Aerospace spin-off, all aimed at leaving Honeywell as a pure-play automation company. None of the disclosed 2026 transactions directly name its building-security or video product lines.
Panasonic unveiled its most comprehensive camera ecosystem to date at Intersec Dubai in January 2026 E-, V-, and P-series cameras spanning SME to critical-infrastructure use cases, with the P-series adding automatic number-plate recognition and thermal imaging for the first time. It's worth noting that Panasonic's dedicated video-surveillance engineering has operated as an independent company, i-PRO, since 2019, even where products are still marketed regionally under the Panasonic name.
Cisco Systems deepened its Meraki MV smart-camera integration in an April 2026 update that centralized camera administration through the Meraki dashboard and Vision portal, adding AI-enabled license-plate recognition, cross-camera tracking, and faster footage export.
Avigilon Corporation, owned by Motorola Solutions, launched Avigilon Visual Alerts in January 2026 an on-premises system using conversational AI to let security teams define custom, site-specific alert scenarios without cloud connectivity and followed with an "Assist Chat" AI query interface at ISC West in March. The business line's momentum shows up in Motorola Solutions' own numbers: Video Security and Access Control segment revenue reached $584 million in Q2 2026, up 12% year-over-year, part of a quarter in which Motorola's total revenue rose 13% to $3.13 billion and the company agreed to acquire counter-drone firm D-Fend Solutions for $1.5 billion.
The remaining named vendors Aetherica Jakarta Indonesia, SECOM Indonesia, Ademco Security Group, Johnson Controls, Anviz Global, and MOBOTIX AG continue to compete primarily on regional integration and industry-specific deployments rather than headline AI announcements; NMSC's own competitive assessment found no comparably material, primary-sourced developments for these players in the trailing six months, and has flagged them for the next refresh rather than including unverified claims.
Section takeaway: the leaders that once competed mainly on camera resolution and price are now converging on the same battleground how much a camera can autonomously detect and act on, and how stable each vendor's ownership structure is.
-
Hikvision and Dahua both returned to double-digit revenue growth in their most recent reported periods
-
Hanwha Vision's spinoff into Hanwha M&S is 2026's most significant corporate restructuring in the category
-
Bosch's video business now operates independently as Keenfinity a change worth knowing before assuming "Bosch Security Systems" is still the counterparty
-
Avigilon's video-specific revenue growth (+12% YoY) outpaced Motorola Solutions' already-strong total company growth (+13%)
Structural and Investment Moves
Beyond product launches, 2025–2026 has been marked by real changes in who owns which camera brands worth tracking separately from the AI feature race above.
Notable Structural and Investment Moves in Video Surveillance, 2025–2026
|
Company / Brand |
Move |
Detail |
|
Bosch Security Systems |
Divestment completed (2025) |
Now operates independently as Keenfinity Group; Bosch-branded products continue, new AI layer (IQSIGHT) launched Feb 2026 |
|
Hanwha Vision |
Corporate spinoff (Aug 2026) |
Combined with Hanwha Semitech into new standalone holding company, Hanwha M&S (~$4.2B combined sales) |
|
Motorola Solutions / Avigilon |
Acquisition (Aug 2026) |
Agreed to acquire counter-drone firm D-Fend Solutions for $1.5 billion |
|
Panasonic video business |
Historical spinoff (2019) |
Dedicated camera engineering operates as i-PRO; still regionally co-branded as Panasonic |
Future Outlook for the AI CCTV Market
NMSC's analysis points to continued convergence of 5G and edge computing as the clearest structural driver through 2030, enabling real-time analysis with minimal latency and supporting deployment across the wide geographic areas smart-city and critical-infrastructure programs require. The high installation and maintenance cost that has historically limited adoption among smaller businesses and homeowners remains the market's clearest restraint which is exactly the gap cloud-based deployment (see Coram above) is positioned to close over the next several years.
Section takeaway: the next few years of growth depend less on new camera categories and more on making existing AI capability cheaper to deploy and easier to act on autonomously.
-
5G/edge convergence is the clearest technology driver identified through the 2030 forecast window
-
Installation and maintenance cost remains the primary adoption restraint, especially for SMEs
-
Cloud deployment models are the most likely path to closing that cost gap
Conclusion
The AI CCTV market's growth through 2030 is being shaped less by new hardware categories than by how autonomously a camera can act on what it sees and by real changes in who owns the cameras themselves. Hikvision and Dahua have returned to double-digit growth, Hanwha Vision has restructured into a new NDAA-focused holding company, and Bosch's video business now operates under an entirely different name. For buyers evaluating a fleet upgrade, understanding a vendor's corporate structure is now as relevant as comparing its AI feature list.
Download Free Sample for the full segment-level data, vendor profiles, and country-level forecasts behind this analysis.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment