AI CCTV Market Global Industry Analysis and Forecast (2026–2035)

AI CCTV Market size was USD 17.21 Billion in 2025, projected to reach USD 135.29 Billion by 2035, growing at a CAGR of 22.9% from 2026 to 2035. Key drivers include edge AI analytics adoption, smart city and public safety programs, replacement of legacy analog systems, with North America leading the global market.
Download Free Sample PDF
Base Year (2025)
$17.21 Billion
Forecast (2035)
$135.29 Billion
CAGR (2026-2035)
22.9%
Top Region
North America

What Is the AI CCTV Market Size?

The global AI CCTV Market reached USD 17.21 Billion in 2025 and is estimated at USD 21.15 Billion in 2026, forecast to reach USD 135.29 Billion by 2035 at a CAGR of 22.9% between 2026 and 2035. North America leads with approximately 34% revenue share in 2025, while Hardware is the dominant component type, holding approximately 47% of total market revenue.

We observed that technological shifts in AI CCTV are reshaping camera design, processing architecture and deployment models across the value chain. Camera manufacturers are adopting dedicated neural processing units, advanced CMOS sensors with low-light capability, and weather-sealed housings that tolerate wide temperature ranges. Moreover, deployment scale is expanding as municipalities, transport hubs, and industrial campuses replace legacy analog systems with intelligent multi-sensor networks capable of continuous real-time monitoring.

AI CCTV Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast

Values in USD Billion

2025 $17.21 Billion
2025
2026 $21.15 Billion
2026
2027 $25.99 Billion
2027
2028 $31.95 Billion
2028
2029 $39.26 Billion
2029
2030 $48.25 Billion
2030
2031 $59.30 Billion
2031
2032 $72.88 Billion
2032
2033 $89.57 Billion
2033
2034 $110.08 Billion
2034
2035 $135.29 Billion
2035

Key Takeaways

By Component Type: Hardware held the largest share, expanding from USD 8.10 Billion in 2025 to USD 41.84 Billion by 2035; Services is the fastest-growing at 29.4% CAGR from 2026–2035.

By Camera Type: PTZ Cameras held the largest share, expanding from USD 7.53 Billion in 2025 to USD 43.19 Billion by 2035; Other Camera Types is the fastest-growing at 28.3% CAGR from 2026–2035.

By AI Analytics Function: Identity Analytics held the largest share, expanding from USD 5.77 Billion in 2025 to USD 33.85 Billion by 2035; Video Intelligence and Forensics is the fastest-growing at 30.5% CAGR from 2026–2035.

By Deployment: Cloud-Based held the largest share, expanding from USD 9.55 Billion in 2025 to USD 52.66 Billion by 2035; Hybrid is the fastest-growing at 26.8% CAGR from 2026–2035.

Dominant Region: North America dominated the market with approximately 34% revenue share (USD 5.85 Billion) in 2025, anchored by mature commercial infrastructure, early institutional adoption of advanced platforms, and high concentrations of leading technology vendors.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 26.1% during 2026–2035, driven by rapid infrastructure expansion, massive public programs, and expanding commercial adoption across high-density markets.

Dominant Country: The U.S. led the market with an estimated USD 4.45 Billion in 2025 (~76% of North America), supported by extensive commercial adoption, dense vendor presence, and early technology deployment.

Fastest-Growing Country: India is among the fastest-growing major countries, projected to expand from USD 0.93 Billion in 2025 at a CAGR of approximately 27.9%, driven by rapid operational modernization, supportive public programs, and expanding commercial infrastructure rollouts.

Ecosystem Analysis of the AI CCTV Industry

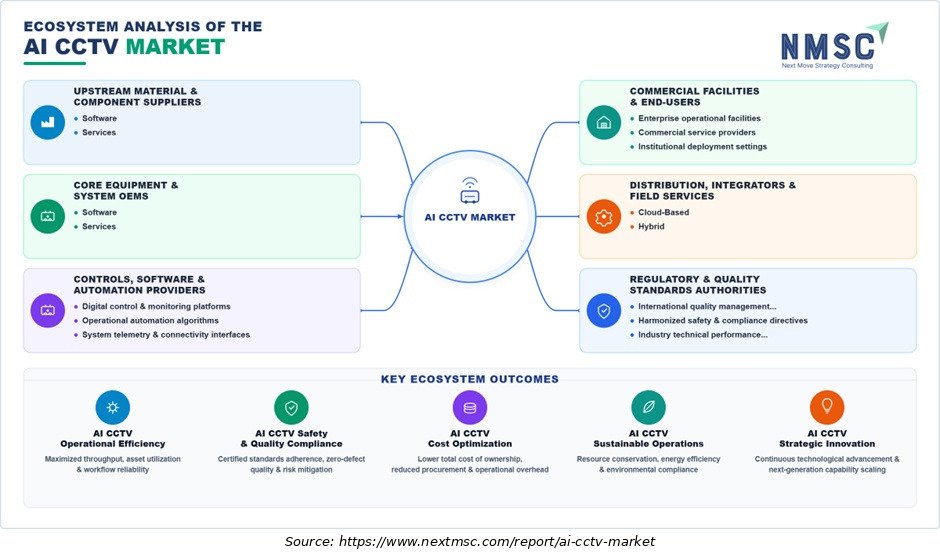
The infographic presents the AI CCTV market ecosystem in a structured format, focusing on six core stakeholder groups: upstream material & component suppliers, core equipment & system OEMs, controls, software & automation providers, commercial facilities & end-users, distribution, integrators & field services, regulatory & quality standards authorities., commercial facilities & end-users, distribution, integrators & field services, regulatory & quality standards authorities. It shows how these participants support operations while contributing to operational efficiency, safety, cost optimization, sustainability, and technological innovation across diverse operating environments.

What Does the AI CCTV Market Encompass?

The AI CCTV market encompasses intelligent video surveillance cameras, network video recorders, video management software, and edge analytics modules that interpret visual data in real-time. Product types range from fixed bullet and dome cameras to pan-tilt-zoom units, thermal imaging systems, and multi-sensor panoramic arrays. Core technologies include deep learning-based object detection, optical character recognition for license plates, people counting, and perimeter intrusion analytics deployed across both on-device and server-based architectures. Design specifications in AI CCTV emphasize ruggedized housings rated for ingress protection, wide dynamic range imaging, and infrared illumination for night operation. Material innovations include corrosion-resistant aluminum alloys, high-clarity optical glass, and heat-dissipating chassis that sustain continuous processing loads.

Technical standards and regulatory requirements influence AI CCTV product design and procurement. The IEC 62676 series establish standards for video surveillance systems, including system performance and interoperability. For products placed on the European market, CE marking indicates conformity with applicable EU harmonisation legislation where required. ISO 9001 quality management certification may also support procurement assessments of manufacturers. Data protection requirements under the General Data Protection Regulation (GDPR) influence the handling of identifiable video footage, including access controls, lawful processing, privacy safeguards and retention practices.

Market Drivers & Dynamics

Interactive Dataset
Edge AI Analytics Adoption driver High Immediate
Smart City and Public Safety Programs driver High Immediate
Replacement of Legacy Analog Systems driver Medium Medium-term
Data Privacy and Biometric Regulation restraint High Immediate
Semiconductor Supply Volatility restraint Medium Medium-term
Cybersecurity Vulnerability Concerns restraint Low Long-term
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the AI CCTV Industry?

The primary catalyst propelling AI CCTV is the shift from passive recording toward active event detection embedded directly in surveillance hardware. Security operators seek systems that identify threats and generate structured alerts without constant human observation. This demand is particularly strong across transportation networks, logistics centers, and large industrial campuses where staffing constraints make manual video review impractical. Next Move Strategy Consulting's analysis indicates that this operational requirement will continue to anchor the market expansion through 2035.

How Are Industry Standards and Directives Driving the Market?

Regulatory frameworks increasingly shape procurement and product design in AI CCTV. Standards such as IEC 62676 define performance and interoperability requirements for video surveillance systems, while CE marking governs conformity for products sold within the European Economic Area. Data protection regulations, including the General Data Protection Regulation (GDPR), require organizations to process identifiable video footage lawfully and apply appropriate privacy safeguards, access controls and retention policies. Compliance with these benchmarks therefore functions as a compliance floor that sustains baseline demand rather than serving as the primary growth vector.

Growth Inhibitors

What Is Restraining the AI CCTV Market?

The availability and sourcing of image sensors, system-on-chips and AI accelerators can affect AI CCTV camera production and deployment schedules. Broader semiconductor supply-chain disruptions and capacity constraints may increase component lead times, although exposure varies by component type and supplier. Additionally, the cost premium associated with analytics-capable cameras relative to conventional models can slow adoption among price-sensitive commercial buyers. Our assessment indicates that supply stability for processing components will influence near-term deployment across regions.

What Are the Growth Opportunities?

Can Multi-Sensor Edge Platforms Capture High Density Deployments?

Multi sensor edge platforms combining visual, thermal, and radar inputs offer a compelling opportunity in dense urban and industrial environments. These systems consolidate several monitoring functions into a single intelligent node, reducing installation footprint and cabling requirements. Vendors capable of synchronizing sensor fusion with onboard analytics can address high-density zones such as airports, ports, and large manufacturing complexes where conventional camera arrays struggle to deliver reliable coverage.

How Is Mid-Tier and Regional Facility Adoption Unlocking New Market Volume?

Mid-tier commercial properties, regional hospitals, and secondary distribution hubs represent an expanding segment of AI CCTV demand. Facilities that previously relied on basic recording now seek affordable analytics packages that improve loss prevention and access control. Simplified installation models and cloud free local storage options allow regional integrators to serve these customers efficiently, broadening deployment volume beyond major metropolitan centers and large enterprise accounts.

Can Specialized Vertical Implementations Become Distinct Premium Markets?

Specialized vertical implementations, such as cameras tailored for rail platforms, mining operations, or marine ports, may evolve into distinct premium segments within AI CCTV. These applications demand ruggedized hardware, extended temperature tolerance, and analytics trained on sector specific behaviors. Premium pricing for such configurations can support healthier margins for manufacturers and encourage long term service agreements with operators who require uninterrupted surveillance in demanding physical conditions.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Hardware 2025: $8.10 Billion | 2035: $41.84 Billion
Hardware
Software 2025: $6.20 Billion | 2035: $56.90 Billion
Software
Services 2025: $2.91 Billion | 2035: $36.55 Billion
Services
Hardware $8.10 Billion $41.84 Billion 17.8%
Software $6.20 Billion $56.90 Billion 24.4%
Services $2.91 Billion $36.55 Billion 29.4%

Which Component Type Segment Dominates the Market?

Hardware anchors the installed base of AI CCTV, accounting for roughly 47% of market value and USD 8.10 billion in 2025, as operators continue to fund AI cameras, edge processing units and recording infrastructure. Software and Services record faster trajectories, with Software expanding at a 24.4% CAGR and Services at a 29.4% CAGR through 2035, driven by licensed detection and video management platforms alongside integration, system calibration, managed monitoring, and lifecycle support that enterprises require to operate complex deployments reliably.

2025 (USD Billion)
2035 (USD Billion)
Single-Senso
Dome Cameras
Bullet Camer
Turret Camer
Box Cameras
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Single-Sensor Fixed Cameras $10.0 USD Billion $40.0 USD Billion 18.0%
Dome Cameras $17.1 USD Billion $51.1 USD Billion 12.0%
Bullet Cameras $24.2 USD Billion $62.2 USD Billion 26.0%
Turret Cameras $31.3 USD Billion $73.3 USD Billion 8.0%
Box Cameras $38.4 USD Billion $84.4 USD Billion 11.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Camera Type.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Security Ana
Intrusion De
Perimeter Pr
Anomaly and
Identity Ana
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Security Analytics $10.0 USD Billion $40.0 USD Billion 16.0%
Intrusion Detection $17.1 USD Billion $51.1 USD Billion 10.0%
Perimeter Protection $24.2 USD Billion $62.2 USD Billion 24.0%
Anomaly and Threat Detection $31.3 USD Billion $73.3 USD Billion 10.0%
Identity Analytics $38.4 USD Billion $84.4 USD Billion 21.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By AI Analytics Function.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
On-Premises
Cloud-Based
Hybrid
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
On-Premises $10.0 USD Billion $40.0 USD Billion 10.0%
Cloud-Based $17.1 USD Billion $51.1 USD Billion 24.0%
Hybrid $24.2 USD Billion $62.2 USD Billion 26.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Deployment.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Residential
Retail and E
BFSI
Hospitality
Commercial a
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Residential $10.0 USD Billion $40.0 USD Billion 26.0%
Retail and E-Commerce $17.1 USD Billion $51.1 USD Billion 16.0%
BFSI $24.2 USD Billion $62.2 USD Billion 18.0%
Hospitality and Leisure $31.3 USD Billion $73.3 USD Billion 8.0%
Commercial and Professional Services $38.4 USD Billion $84.4 USD Billion 23.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data

Supply Chain Analysis of the AI CCTV Industry

Supply Chain Analysis of the AI CCTV Industry
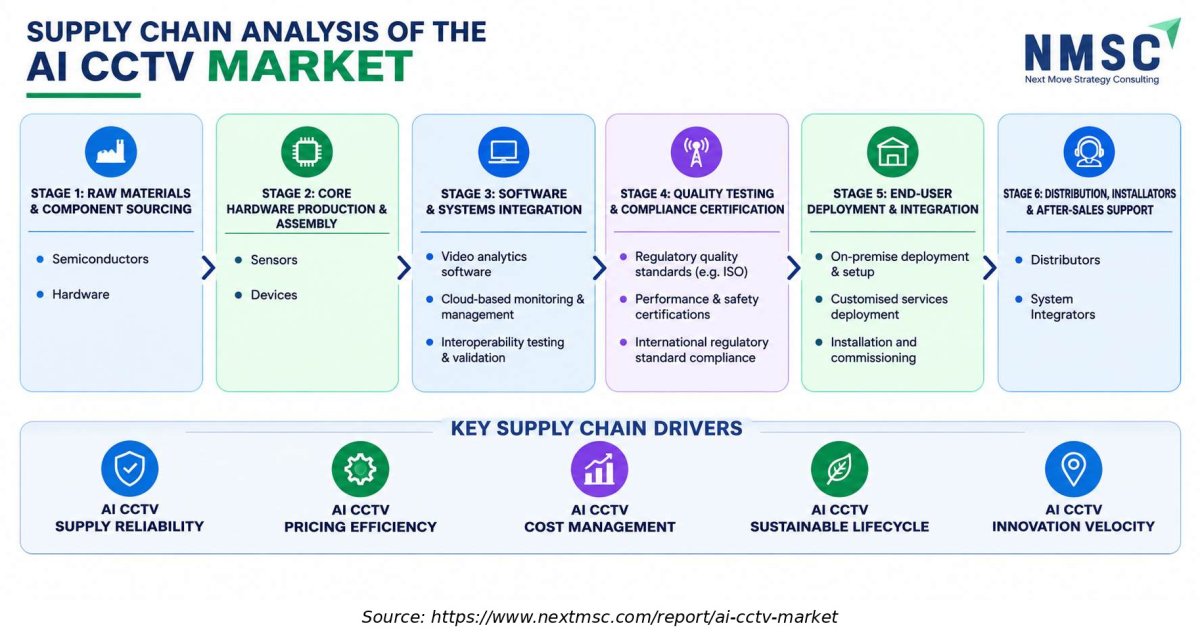
The above infographic maps the AI CCTV market supply chain across six sequential stages: stage 1: raw materials & component sourcing, stage 2: core manufacturing & assembly, stage 3: software & systems integration, stage 4: quality testing & compliance certification, stage 5: end-user deployment & utilization, stage 6: distribution, integrators & lifecycle support. It illustrates how these stages connect to ensure component reliability, manufacturing precision, supply stability, cost control, and rapid technological deployment across end-user environments.

Growth Opportunities

Our analysis shows that three structural whitespace opportunities are positioned to generate disproportionate commercial returns in the AI CCTV Market through 2035:

Can Multi-Sensor Edge Platforms Capture High Density Deployments?

Multi sensor edge platforms combining visual, thermal, and radar inputs offer a compelling opportunity in dense urban and industrial environments. These systems consolidate several monitoring functions into a single intelligent node, reducing installation footprint and cabling requirements. Vendors capable of synchronizing sensor fusion with onboard analytics can address high-density zones such as airports, ports, and large manufacturing complexes where conventional camera arrays struggle to deliver reliable coverage.

How Is Mid-Tier and Regional Facility Adoption Unlocking New Market Volume?

Mid-tier commercial properties, regional hospitals, and secondary distribution hubs represent an expanding segment of AI CCTV demand. Facilities that previously relied on basic recording now seek affordable analytics packages that improve loss prevention and access control. Simplified installation models and cloud free local storage options allow regional integrators to serve these customers efficiently, broadening deployment volume beyond major metropolitan centers and large enterprise accounts.

Can Specialized Vertical Implementations Become Distinct Premium Markets?

Specialized vertical implementations, such as cameras tailored for rail platforms, mining operations, or marine ports, may evolve into distinct premium segments within AI CCTV. These applications demand ruggedized hardware, extended temperature tolerance, and analytics trained on sector specific behaviors. Premium pricing for such configurations can support healthier margins for manufacturers and encourage long term service agreements with operators who require uninterrupted surveillance in demanding physical conditions.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Latin Americ
Middle East
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Latin America $31.3 USD Billion $73.3 USD Billion 23.0%
Middle East & Africa $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

The competitive structure of the AI CCTV market features a concentrated group of established manufacturers alongside specialized analytics participants. Hangzhou Hikvision Digital Technology Co., Ltd., Zhejiang Dahua Technology Co., Ltd., Axis Communications AB, Robert Bosch GmbH, and Hanwha Vision Co., Ltd. hold prominent positions due to broad product portfolios and extensive installed bases. Zhejiang Uniview Technologies Co., Ltd., i-PRO Co., Ltd., VIVOTEK Inc., Teledyne FLIR LLC, and MOBOTIX AG compete through targeted technological specialization and regional channel strength.

How Do Companies Compete in the AI CCTV Market?

Companies in the AI CCTV market differentiate primarily through analytics accuracy, sensor performance, and platform openness rather than through hardware alone. Pricing strategies increasingly bundle software licenses, support services, and cloud subscriptions to protect recurring revenue. Distribution relies on integrator partnerships, value added resellers, and direct enterprise sales teams, with regional presence and certification status shaping competitive win rates in government and critical infrastructure tenders.

Which Competitive Archetypes Dominate the AI CCTV Market?

Market participants in AI CCTV fall into distinct archetypes. Full line camera manufacturers such as Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. combine imaging hardware with proprietary analytics. Premium infrastructure producers including Axis Communications AB, Robert Bosch GmbH, and Hanwha Vision Co., Ltd. emphasize engineering quality and enterprise integration. Specialized imaging innovators such as Teledyne FLIR LLC and MOBOTIX AG focus on thermal or distinctive sensor architectures for niche operational requirements.

What Innovation and Differentiation Strategies Are Companies Pursuing?

Sustainable advantages in AI CCTV stem from proprietary training datasets, validated analytics accuracy, and deep integration with video management ecosystems. Manufacturers that maintain long product lifecycles and dependable firmware update programs build customer loyalty that resists price competition. Certified interoperability with third-party platforms and strong service networks further raise switching costs, allowing established participants to protect margins as commoditized hardware pressures intensify across mature segments.

What M&A and Partnership Activity Is Shaping the Market?

Strategic collaboration in the AI CCTV ecosystem may involve camera manufacturers, analytics software developers, semiconductor suppliers and cloud platform providers. These relationships can support product integration, edge-processing capabilities and the development of intelligent surveillance platforms. Company-specific acquisitions, investments and partnerships should be assessed using official announcements or regulatory disclosures to establish their relevance to the competitive landscape.

Key Market Players

Based on research conducted by NMSC, the following 20 companies represent the validated leadership set across AI CCTV Market developers, manufacturers, and solution providers:

Hangzhou Hikvision Digital Technology Co., Ltd. Zhejiang Dahua Technology Co., Ltd. Axis Communications AB Robert Bosch GmbH Hanwha Vision Co., Ltd. Zhejiang Uniview Technologies Co., Ltd. i-PRO Co., Ltd. VIVOTEK Inc. Teledyne FLIR LLC MOBOTIX AG Verkada Inc. Motorola Solutions, Inc. Eagle Eye Networks, Inc. Genetec Inc. Milestone Systems A/S BriefCam Ltd Ambient.ai, Inc. Spot AI, Inc. NEC Corporation Avigilon Corporation

Latest Developments

Recent AI CCTV product launches during 2026 have focused on modular camera architectures, compact AI-enabled cameras, and multi-lens surveillance platforms with embedded analytics.

Date Event
July 2026 Hanwha Vision launched its second-generation X Series compact AI cameras, powered by the Wisenet 9 system-on-chip and dual neural processing units. The cameras provide AI-based image enhancement, object classification and Dynamic Privacy Masking, including automated masking of people, vehicles, faces and license plates.

Investment Opportunities

Where Are Capital Inflows Concentrating in the AI CCTV Market?

Capital inflows in the AI CCTV market are concentrating in analytics software, edge processing hardware, and cloud intelligence platforms that deliver recurring revenue. Investors favor participants able to demonstrate validated detection accuracy and scalable subscription economics. Consequently, funding increasingly flows toward software specialists and sensor innovators rather than commodity camera assembly, reflecting the market's structural shift toward intelligence led value creation.

How Is Infrastructure Investment Shaping Market Capacity?

Infrastructure investment in the AI CCTV market centers on automated production lines for camera modules, dedicated edge computing assembly, and regional distribution hubs that shorten delivery cycles. Manufacturers expand testing facilities to validate analytics performance under diverse environmental conditions. These capacity additions enable faster response to enterprise and public sector demand while supporting consistent quality across geographically dispersed production and fulfillment networks.

What ESG Considerations Are Influencing Market Investment?

Environmental and governance considerations are gradually shaping investment decisions across the AI CCTV ecosystem. Energy-efficient edge processors reduce power consumption for continuously operating surveillance networks, which lowers operational footprints for large deployments. Responsible data handling, privacy safeguards, and safety compliance also influence procurement, as buyers increasingly assess vendors on governance credentials alongside technical performance.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders and Enterprise Operators?

Operational executives, procurement directors, and commercial operators in the AI CCTV market gain empirical benchmarks that clarify segment priorities and deployment economics. The report's forecasts support capital planning for camera refresh cycles, analytics licensing, and hybrid architecture decisions. Such grounded evidence helps enterprise leaders evaluate vendor proposals with greater confidence and align technology investments with measurable operational outcomes.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts can use the AI CCTV market trajectory, which expands from USD 17.21 billion in 2025 to USD 135.29 billion by 2035, as a reference for valuation modeling. The segmentation data reveals where margin profiles are strongest, particularly within software and services. Comparing these benchmarks against competitor positioning allows analysts to assess relative attractiveness across participants and identify durable earnings potential.

How Does This Report Benefit Technology Vendors and Solution Platform Teams?

Technology vendors and solution platform teams can translate the segment analysis into focused product roadmaps for the AI CCTV market. High growth categories such as Video Intelligence and Forensics and hybrid deployment offer clear targets for engineering investment. Understanding competitive differentiation dimensions helps teams prioritize interoperability, analytics accuracy, and service capabilities that strengthen positioning against established market participants.

Key Market Segments Evaluated

By Component Type

  • Hardware 
    • AI Cameras
    • AI Processing Hardware
    • Recording and Storage Hardware
    • Other AI CCTV Hardware
  • Software 
    • Video Management Software
    • Video Analytics Software
    • Device Management Software
    • Other AI CCTV Software
  • Services 
    • Installation and Integration
    • Maintenance and Support
    • Managed Video Surveillance
    • Consulting and Design Services

By Camera Type

  • Single-Sensor Fixed Cameras 
    • Dome Cameras
    • Bullet Cameras
    • Turret Cameras
    • Box Cameras
    • Fisheye Cameras
    • Panoramic Cameras
    • Other Single-Sensor Fixed Cameras
  • PTZ Cameras
  • Multi-Sensor Cameras
  • Other Camera Types

By AI Analytics Function

  • Security Analytics 
    • Intrusion Detection
    • Perimeter Protection
    • Anomaly and Threat Detection
  • Identity Analytics 
    • Face Detection
    • Face Recognition
  • Vehicle Analytics 
    • License Plate Recognition
    • Vehicle Detection and Classification
    • Speed Detection
  • People Analytics 
    • People Counting
    • Occupancy Monitoring
    • Crowd Analytics
    • Queue and Dwell Analysis
  • Safety Analytics 
    • Personal Protective Equipment Compliance
    • Fire and Smoke Detection
    • Slip and Fall Detection
  • Business Analytics 
    • Heat Mapping
    • Customer Journey Analytics
    • In-Store Behavior Analytics
  • Video Intelligence and Forensics 
    • AI Video Search
    • Event Reconstruction
    • Forensic Indexing
  • Other AI Analytics

By Deployment

  • On-Premises
  • Cloud-Based
  • Hybrid

By End User

  • Residential
  • Retail and E-Commerce
  • BFSI
  • Hospitality and Leisure
  • Commercial and Professional Services
  • Industrial and Manufacturing
  • Government and Public Safety
  • Transportation and Logistics
  • Healthcare
  • Education
  • Energy and Utilities
  • Telecom and Data Centers
  • Other End Users

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico.
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Rest of Europe.
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Australia
    • Rest of APAC.
  • Latin America 
    • Brazil
    • Argentina
    • Colombia
    • Rest of Latin America.
  • Middle East & Africa 
    • UAE
    • Saudi Arabia
    • South Africa
    • Rest of MEA.

Conclusion & Recommendations

What Is the Long-Term Outlook for the AI CCTV Market?

The long-term outlook for the AI CCTV Market is strongly positive, with revenue expanding from USD 21.15 billion in 2026 to USD 135.29 billion by 2035 at a 22.9% CAGR. Growth is underpinned by durable commercial demand expansion, the structural shift toward high-performance specialized solutions, and continuous technological innovation across core operational workflows. Participants that align portfolios with intelligence led value creation are best positioned to benefit from this trajectory.

What Strategic Positioning Recommendations Does NMSC Offer?

Market participants in the AI CCTV market should prioritize analytics software and services, the segments delivering the strongest growth momentum. OEMs should invest in edge processing and interoperable platforms that support hybrid deployments. Distributors should build integrator certification programs and regional service coverage to capture enterprise and public sector demand, sustaining competitive advantage as the market matures across geographies.

How Attractive Is the AI CCTV Market for Investment?

Investment attractiveness is high, supported by the USD 114.14 billion absolute growth opportunity between 2026 and 2035 in the AI CCTV market. Recurring software and service revenues strengthen margin resilience relative to commodity hardware. Demand drivers including workflow automation, security modernization, and forensic efficiency underpin durable commercial interest, making the sector compelling for long horizon capital allocation.

What Are the Key Market Shifts and Risks in the AI CCTV Market?

The AI CCTV market is shifting from standalone camera sales toward integrated analytics ecosystems and subscription models. This transition introduces risks around component supply continuity for semiconductors and imaging sensors, which influence production schedules. Pricing pressure in mature camera categories and dependence on accurate training data also present operational challenges that participants must manage carefully.

What Are the Primary Growth Pathways Through 2035?

Primary growth pathways in the AI CCTV market include expanding services offerings, scaling video intelligence and forensic capabilities, and advancing hybrid deployment architectures. Participants that bundle analytics with managed services can capture recurring revenue across the installed base. Targeting the USD 114.14 billion absolute growth opportunity requires disciplined focus on these high momentum categories rather than broad hardware replacement alone.

FAQs

About the Author

Mihul Sharma

Mihul Sharma

Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖