FedNow's Record Quarter and Stripe Pay Move B2B Payments onto Instant Rails
FedNow's 6.38 Million Settled Payments Worth $370.9 Billion in Q3 and Stripe's Free Instant Business Transfers Mark a Shift From Batch to Real-Time B2B Settlement
On October 20, 2026, Federal Reserve Financial Services published third-quarter statistics showing that the FedNow Service settled 6,376,467 customer credit transfers worth $370.9 billion between July and September 2026, increases of 27.6% in volume and 35.0% in value over the second quarter. Both totals are the highest in the series, which begins with a partial third quarter of 2023, and the average value per payment reached $58,161. One week later, on October 27, 2026, Stripe announced a plug-in called stripe pay that lets businesses find other companies by Stripe profile handle and send funds for free, as PYMNTS reported that day. Together, the two events show instant settlement moving from an option offered by bank networks to a payment feature that businesses can address directly, a shift that reaches into the accounts payable, supplier payment and cross-border workflows at the centre of B2B payments.
According to Next Move Strategy Consulting's B2B Payments Market report, the global B2B payments market was valued at USD 145.0 billion in 2025 and is projected to reach USD 385.0 billion by 2035, growing at a CAGR of 10.5% from 2026 to 2035. NextMSC primary research and analysis puts the 2026 value at USD 157.0 billion and identifies expanding real-time payment infrastructure, rising accounts payable and receivable automation, and the digitization of cross-border payments as the structural drivers, with North America holding approximately 38% of 2025 revenue.
For More Information: Download FREE Sample on B2B Payments Market Report
The Financial Logic: Settlement Speed, Ticket Size and Check Fatigue
The quarterly path matters as much as the headline total. FedNow settled 2,506,002 payments worth $307.3 billion in the third quarter of 2025, then 2,466,494 payments in the fourth quarter, the only quarter in the published series with a fall in both volume and value. Volume rose 10.6% in the first quarter of 2026 and 83.2% in the second quarter, to 4,997,811 payments, while value rose only 1.3%, which pulled the average value per payment from $99,414 to $54,957. In the third quarter, volume rose a further 27.6% and value 35.0%, lifting the average to $58,161, with average daily volume of 69,309 payments and average daily value of $4.03 billion.
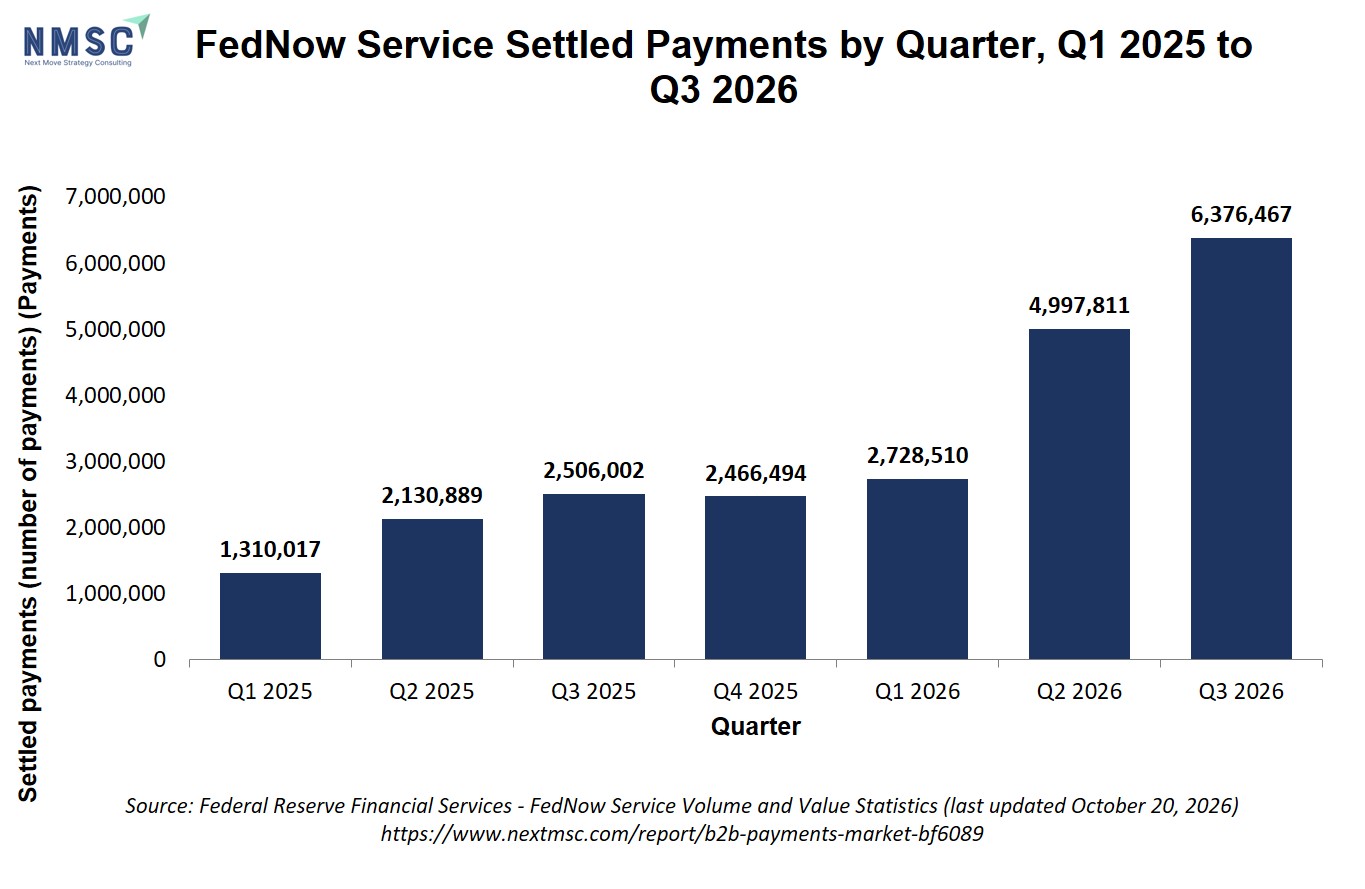
FedNow Service Quarterly Statistics, Third Quarter 2025 to Third Quarter 2026
|
Quarter |
Settled payments |
Value of settled payments (USD) |
Average value per payment (USD) |
Quarterly volume growth |
Quarterly value growth |
|
Q3 2025 |
2,506,002 |
$307,275,281,996 |
$122,616 |
17.6% |
25.0% |
|
Q4 2025 |
2,466,494 |
$251,776,175,998 |
$102,079 |
-1.6% |
-18.1% |
|
Q1 2026 |
2,728,510 |
$271,252,920,121 |
$99,414 |
10.6% |
7.7% |
|
Q2 2026 |
4,997,811 |
$274,663,803,964 |
$54,957 |
83.2% |
1.3% |
|
Q3 2026 |
6,376,467 |
$370,862,703,867 |
$58,161 |
27.6% |
35.0% |
NextMSC primary research and analysis reads the second-quarter divergence between volume and value as a broadening of use: the number of payments grew far faster than the dollars they carried, the pattern expected when lower-value and recurring payments join a rail that already carries large transfers. The Federal Reserve statistics cover all customer credit transfers and do not separate business payments, so NextMSC treats them as a measure of rail adoption rather than as a direct count of B2B volume.
Corporate payment behaviour explains why the rail matters. The Association for Financial Professionals' 2025 AFP Digital Payments Survey, a triennial report underwritten by J.P. Morgan with 223 responses from organizations in the United States and Canada, found that 26% of B2B payments were made by check in 2025, down from 33% in 2022, and that 25% of B2B payments received arrived by check, down from 30%. The same survey reported that 87% of organizations engage in cross-border B2B payments, up 9 percentage points from 2022. Every check that converts to an electronic payment lands on ACH, wire, card or an instant rail, and the choice among them is now the commercial question for providers.
The incumbent rail is growing in parallel. Nacha reported that the ACH Network carried 9.3 billion payments valued at $25.9 trillion in the second quarter of 2026, up 6.2% and 11.1% respectively from a year earlier, with B2B payments reaching 2.2 billion, up 9.9%. Same Day ACH grew faster than the network as a whole, at 435.7 million payments worth $1.3 trillion, up 29.5% and 28.1%. For the first half of 2026, Nacha counted 4.3 billion B2B payments, up 10.3%.
ACH Network Statistics, Second Quarter 2026
|
Metric |
Second quarter 2026 |
Reported growth |
|
Total ACH Network payments |
9.3 billion |
6.2% |
|
Total ACH Network value |
$25.9 trillion |
11.1% |
|
B2B payments |
2.2 billion |
9.9% |
|
Same Day ACH payments |
435.7 million |
29.5% |
|
Same Day ACH value |
$1.3 trillion |
28.1% |
|
B2B payments, first half of 2026 |
4.3 billion |
10.3% |
In NextMSC's reading, the pairing of FedNow's 27.6% quarterly volume increase with Same Day ACH's 29.5% annual increase indicates demand for faster settlement on more than one rail at the same time, rather than a straight displacement of one rail by another.
Key Industry Developments: Four Launches That Reframe the Rail Contest
Product announcements since June 2026 point in the same direction. On June 16, 2026, Adyen introduced Adyen Agentic, a three-layer API suite made up of Agentic Feed, Agentic Cart and Agentic Payments that lets enterprises sell through conversational AI platforms without rebuilding commerce systems for each channel. The payments layer handles authentication, token portability, merchant-of-record preservation and risk management for agent-led transactions, and Adyen described the product as in limited availability for U.S. enterprise merchants, with global expansion planned.
On July 23, 2026, Mastercard expanded its In Control virtual card platform with Issuer Enforced Controls, which let issuers set spend limits, transaction caps and validity periods when a virtual card number is created, and with enhanced Clearing Controls that extend validation to the clearing stage. A Commercial Connect API lets users create virtual cards and initiate payments in one step. Mastercard stated that its virtual card number ecosystem spans 43 countries and 174 currencies, that fraud rates on virtual cards are less than one-fifth of those on non-virtual cards, and that Citi is the first issuer live with both control sets, with a global rollout expected later this year. SAP and HSBC were named among the partners, including an HSBC mobile virtual card launched in the United Arab Emirates.
Also on July 23, 2026, Visa and Airwallex announced a collaboration to build embedded-finance solutions for freight and shipping platforms, combining Visa's commercial payments, acceptance and risk expertise with Airwallex's embedded-finance and multi-currency technology. The Airwallex announcement states that payments in shipping take an average of 42 days to reach the invoicing company, citing a CSIS analysis, and that processing and administrative costs can account for nearly one-fifth of total transportation costs.
“Cash sitting in limbo while payments clear across borders is capital that should be funding the next shipment.”
— Christos Chamberlain, General Manager, UK and Europe, Airwallex, Airwallex newsroom announcement of the collaboration with Visa, July 23, 2026.
The fourth launch came from Stripe. In its October 27, 2026 post on LinkedIn, Stripe said businesses can find companies by their Stripe profile handle and send funds for free, available in the Dashboard and CLI. Stripe's own documentation describes the plug-in as in preview for eligible U.S. and UK businesses, supporting same-currency transfers in USD, GBP and USDC. Senders need a funded Stripe Treasury financial account, and recipients need either a Treasury financial account or a payout-enabled bank account linked to their Stripe profile.
Four 2026 B2B Payment Launches at a Glance
|
Launch |
Date |
What changed |
Scope as announced |
|
Adyen Agentic |
June 16, 2026 |
Three-layer API suite for selling through conversational AI platforms; payments layer covers authentication, token portability, merchant-of-record preservation and risk |
Limited availability for U.S. enterprise merchants; global expansion planned |
|
Mastercard In Control expansion |
July 23, 2026 |
Issuer Enforced Controls, enhanced Clearing Controls and a Commercial Connect API that creates virtual cards and starts payments in one step |
43 countries and 174 currencies; Citi first issuer live with both control sets |
|
Visa and Airwallex freight collaboration |
July 23, 2026 |
Embedded-finance solutions for freight and shipping platforms combining Visa commercial payments with Airwallex multi-currency technology |
Freight and shipping platforms; repeatable model for industry-specific B2B solutions |
|
Stripe Pay |
October 27, 2026 |
Free instant transfers between businesses, addressed by Stripe profile handle |
Preview for eligible U.S. and UK businesses; USD, GBP and USDC transfers in the same currency |
Segment Dynamics: Real-Time Rails Grow Fastest While Wires and Cloud Anchor Revenue
According to NextMSC primary research and analysis, Wire Transfer was the largest payment method in 2025 with approximately 27% of revenue, or USD 39.15 billion, while Real-Time Payments is the fastest-growing method at an 18.4% CAGR from 2026 to 2035. Domestic Payments held approximately 68% of 2025 revenue, or USD 98.60 billion, yet Cross-Border Payments is the fastest-growing payment type at 13.8%. Large Enterprises accounted for approximately 61% of 2025 revenue, or USD 88.45 billion, while Small and Medium Enterprises are the fastest-growing enterprise-size segment at 12.8%.
On deployment and application, NextMSC primary research and analysis shows Cloud holding approximately 72% of 2025 revenue, or USD 104.40 billion, and also growing fastest among deployment modes at 12.9%. Accounts Payable led applications with approximately 32%, or USD 46.40 billion, while Supply Chain Payments is the fastest-growing application at 12.7%. Banks held approximately 47% of 2025 revenue, or USD 68.15 billion, among provider types, yet Payment Processors and Fintech Providers are growing fastest at 12.9%. BFSI led end-use industries at approximately 21%, or USD 30.45 billion, while Construction is growing fastest at 12.5%.
The launches above map onto these segments directly. FedNow and Stripe Pay address the real-time payment method, Mastercard's In Control platform addresses virtual card supplier payments, and the Visa and Airwallex collaboration targets cross-border payments in a single industry, freight. In NextMSC's assessment, each of these products is aimed at a segment that is growing faster than the 10.5% market average.
Regional Outlook: North America Leads, Latin America Grows Fastest
According to NextMSC primary research and analysis, North America led with approximately 38% of 2025 revenue, or USD 55.10 billion, growing at a 9.9% CAGR. The U.S. market was approximately USD 44.63 billion in 2025 and is projected to reach USD 99.95 billion by 2035 at a 9.4% CAGR. FedNow, the Nacha figures and the Stripe Pay preview all concern the United States, which anchors this outlook, and Stripe's preview also covers the UK, which NextMSC sizes at approximately USD 7.61 billion in 2025 with a 9.6% CAGR.
NextMSC primary research and analysis sizes Europe at USD 36.25 billion in 2025 with a 10.2% CAGR, shaped by the EU Instant Payments Regulation, and Asia-Pacific at USD 39.15 billion with a 13.2% CAGR, led by China at USD 11.35 billion and a 14.2% CAGR and India at USD 7.44 billion and a 15.3% CAGR. Latin America is the fastest-growing region at 15.5% from a USD 5.80 billion base, with Argentina the fastest-growing country covered at 16.6%, while Middle East & Africa grows at 14.3% from USD 8.70 billion. Mastercard's virtual card ecosystem across 43 countries and 174 currencies is the kind of multi-region footprint that these faster-growing regions will draw on.
Growth Drivers and Restraints
The matrix below draws only on independently published figures. It pairs each catalyst or restraint with the measurable evidence announced or surveyed in 2025 and 2026.
B2B Payments Growth Catalysts and Restraints: Evidence Matrix
|
Factor |
Type |
Evidence |
Reported by |
|
Instant settlement uptake |
Driver |
FedNow settled 6,376,467 payments in Q3 2026, up 27.6% on Q2, with value up 35.0% |
Federal Reserve Financial Services |
|
Decline of paper in B2B |
Driver |
26% of B2B payments were made by check in 2025, down from 33% in 2022 |
Association for Financial Professionals |
|
ACH scale in B2B |
Driver |
2.2 billion B2B ACH payments in Q2 2026, up 9.9% |
Nacha |
|
Controls built into cards |
Driver |
Virtual card fraud rates are less than one-fifth of non-virtual card rates, according to Mastercard |
Mastercard |
|
Payments fraud exposure |
Restraint |
76% of U.S. organizations faced attempted or actual payments fraud in 2025; checks 58%, ACH debits 30%, wires 25% |
Association for Financial Professionals |
|
Slow cross-border cash cycles |
Restraint |
Shipping payments take an average of 42 days to reach the invoicing company |
Airwallex |
NMSC Strategic Perspective: Rail Access Is Becoming Counterparty Access
NextMSC primary research and analysis identifies the third-quarter FedNow data as evidence that instant settlement has passed from capacity building to routine use. The second-quarter pattern, in which volume rose 83.2% while value rose 1.3%, shows new payment types joining the rail, and the third-quarter rise in value of 35.0% shows larger transfers returning alongside them. That combination is consistent with NextMSC's finding that Real-Time Payments is the fastest-growing payment method at an 18.4% CAGR from 2026 to 2035, well above the 10.5% growth of the market as a whole.
The more consequential change is in how a business finds and instructs a counterparty. Stripe Pay addresses a recipient by profile handle instead of bank details, Mastercard's Commercial Connect API collapses card creation and payment initiation into one step, and Adyen Agentic gives agent-led transactions a dedicated payments layer. NextMSC's analysis indicates that advantage is shifting from owning a settlement rail to controlling the workflow that selects the rail, which is why NextMSC expects providers that bundle accounts payable and receivable automation with embedded real-time payment execution to gain share over single-function processors.
Fraud economics will shape which providers benefit. The Association for Financial Professionals' 2026 AFP Payments Fraud and Control Survey, published on April 14, 2026 from 465 treasury practitioners at U.S. organizations, found that 76% of organizations experienced attempted or actual payments fraud in 2025, with checks affected at 58%, ACH debits at 30% and wire transfers at 25%, and business email compromise affecting 74%. NextMSC's analysis reads these figures as a design requirement: as paper declines, controls such as Mastercard's issuer-enforced limits and clearing-stage validation become part of the product, and NextMSC identifies data-security and fraud-prevention compliance burden as a restraint that weighs most heavily on smaller fintech providers.
For vendors and investors, NextMSC's model projects an absolute dollar opportunity of USD 228.0 billion between 2026 and 2035. NextMSC's recommendation is to prioritize interoperability with real-time rails and API-based orchestration, the two capabilities that this quarter's announcements have in common.
Competitive Landscape
NextMSC primary research and analysis describes the B2B payments market as moderately consolidated, with card networks and large banks competing alongside fintech platforms on payment rail reach, enterprise-software integration depth and transaction security. Visa and J.P. Morgan Chase exemplify the infrastructure archetype, while Bill.com Holdings and Tipalti serve accounts payable and receivable automation workflows.
The 2026 announcements show the two archetypes converging. Mastercard and Visa are extending card infrastructure into embedded virtual card and freight programs with partners including Citi, SAP, HSBC and Airwallex, while Stripe and Adyen are extending fintech platforms into instant business transfers and agent-led transactions. Each event in this article traces to the announcing company's own release or documentation, to Federal Reserve Financial Services, Nacha or the Association for Financial Professionals, or, for Stripe's LinkedIn post, to the report by PYMNTS.
Bottom Line
Instant settlement became measurable business volume in the third quarter of 2026. FedNow settled 6,376,467 payments worth $370.9 billion, up 27.6% in volume and 35.0% in value on the second quarter, and Stripe followed on October 27 with a free instant transfer preview addressed by profile handle. Nacha's second-quarter data shows the incumbent rail growing too, with 2.2 billion B2B ACH payments, up 9.9%, and Same Day ACH payments up 29.5%. According to NextMSC primary research and analysis, the global B2B payments market will grow from USD 145.0 billion in 2025 to USD 385.0 billion by 2035 at a 10.5% CAGR, with Real-Time Payments the fastest-growing method at 18.4% and Latin America the fastest-growing region at 15.5%. Fraud exposure, reported by 76% of U.S. organizations in 2025, makes built-in controls the condition for share gains. Providers that bundle workflow automation, real-time execution and embedded controls are best placed to capture the USD 228.0 billion absolute opportunity through 2035.
About Next Move Strategy Consulting
Next Move Strategy Consulting is a premier market research and management consulting firm that has been committed to provide strategically analysed well documented latest research reports to its clients. The research industry is flooded with many firms to choose from, what makes NMSC different from the rest is its top-quality research and the obsession of turning data into knowledge by dissecting every bit of it and providing fact-based research recommendation that is supported by information collected from over 500 million websites, paid databases, industry journals and one on one consultations with industry experts across a diverse range of industry sectors. The high-quality customized research reports with actionable insights and excellent end-to-end customer service help our clients to take critical business decisions that enables them to move beyond time and have competitive edge in the industry.
We have been servicing over 1000 customers globally that includes 90% of the Fortune 500 companies over a decade. Our analysts are constantly tracking various high growth markets and identifying hidden opportunities in each sector or the industry. We provide one of the industry’s best quality syndicate as well as custom research reports across 10 different industry verticals. We are committed to deliver high quality research solutions in accordance to your business needs. Our industry standard delivery solutions that ranges from the pre consultation to after-sales services, provide an excellent client experience and ensure right strategic decision making for businesses.
For more information, please contact:
Next Move Strategy Consulting
5th Floor 867 Boylston St, STE 500,
Boston, MA 02116, U.S.
E-Mail: [email protected]
Direct: +1-217-650-7991
Website: www.nextmsc.com
About the Author
 Priyanshu Das
— Priyanshu Das is SEO Executive at Next Move Strategy Consulting, where he has led on-page and off-page SEO, keyword research, and SEO audits for the firm's B2B market research publications for 2 years. His audit process combines technical crawl analysis, backlink profile review, and competitor keyword gap mapping — using tools including Screaming Frog and Google Search Console — to prioritize fixes by organic search-visibility impact, informed by his own prior in-house and agency SEO experience.
About the Reviewer
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.














Add Comment