PVC Antitrust Battle and EPA Pipe Mandate Reshape Plumbing Supply Chains
PVC Antitrust Settlements Top $415M as EPA's $2.9B Lead Pipe Mandate Reshapes the Plumbing Components Supply Chain
A landmark antitrust case that has shaken the foundations of the U.S. PVC pipe and fittings distribution network — with proposed settlements now exceeding $415 million and six of the country's largest plumbing distributors named as alleged co-conspirators — is colliding with a federally mandated lead service line replacement programme backed by $2.9 billion in new EPA funding, creating simultaneous disruption and structural demand acceleration across the global plumbing components sector.
According to Next Move Strategy Consulting's Plumbing Components Market report, the global plumbing components market was valued at USD 83.90 billion in 2024 and is projected to reach USD 116.33 billion by 2030, growing at a CAGR of 5.6% from 2025 to 2030. The forecast reflects compounding demand from urban infrastructure investment, regulatory-driven pipe replacement programmes, and a measurable shift in product mix toward water-efficient and smart-enabled components — forces that are now being tested by the most significant antitrust enforcement action the PVC pipe supply chain has faced in decades.
For More Information: Download FREE Sample on Plumbing Components Market Report
PVC Antitrust Litigation: A $415M Reckoning for the Distribution Channel
On September 24, 2026, Supply House Times reported that the antitrust litigation consolidated in the U.S. District Court for the Northern District of Illinois under In re PVC Pipe Antitrust Litigation had expanded materially, with six major distributors — Core & Main, Ferguson Enterprises, Fortiline Waterworks, Hajoca Corp., Porter Pipe & Supply, and United Pipe & Steel — identified by plaintiffs as alleged co-conspirators in a scheme to fix, raise, maintain, and stabilise prices for PVC pipe, conduit, and fittings.
The six distributors are not currently defendants in the litigation, and the allegations against them have not been proven. However, the amended complaint filed on August 18, 2025 alleges that these distributors collectively control more than 70% of direct PVC Pipe Systems purchases in the United States, and that they supplied pricing information to the Oil Price Information Service (OPIS) publication PetroChem Wire PVC & Pipe Weekly, which plaintiffs allege was used as a mechanism for coordinating price signals across the market.
Proposed settlements involving manufacturers Atkore, Westlake, Otter Tail and its subsidiaries, Pipelife Jet Stream, and OPIS now total approximately $415.4 million across various purchaser groups, with some remaining subject to final court approval. A separate federal grand jury investigation by the U.S. Department of Justice Antitrust Division — triggered by subpoenas issued to Otter Tail in August 2024 and Atkore in February 2025 — remains pending as of October 2026.
The case carries direct implications for the plumbing components market's pricing architecture. PVC pipe and fittings represent one of the most volume-intensive product categories within the broader components ecosystem, and any structural repricing — whether through litigation-driven transparency mandates or distributor consolidation — will alter the cost basis for residential rough-in, municipal water infrastructure, and commercial construction projects simultaneously.
EPA's $2.9B Lead Pipe Mandate: A Structural Demand Catalyst for Pipes and Fittings
While the antitrust case introduces near-term pricing uncertainty, a parallel regulatory development is generating durable, non-discretionary demand for replacement pipes and fittings at a scale that few infrastructure programmes have matched in recent memory.
On May 20, 2026, the U.S. Environmental Protection Agency announced $2.9 billion in funding to help states support lead service line replacement, distributed through the Drinking Water State Revolving Fund (DWSRF). The funding enables communities to identify lead pipes, plan removal projects, and replace lead service lines delivering drinking water to homes.
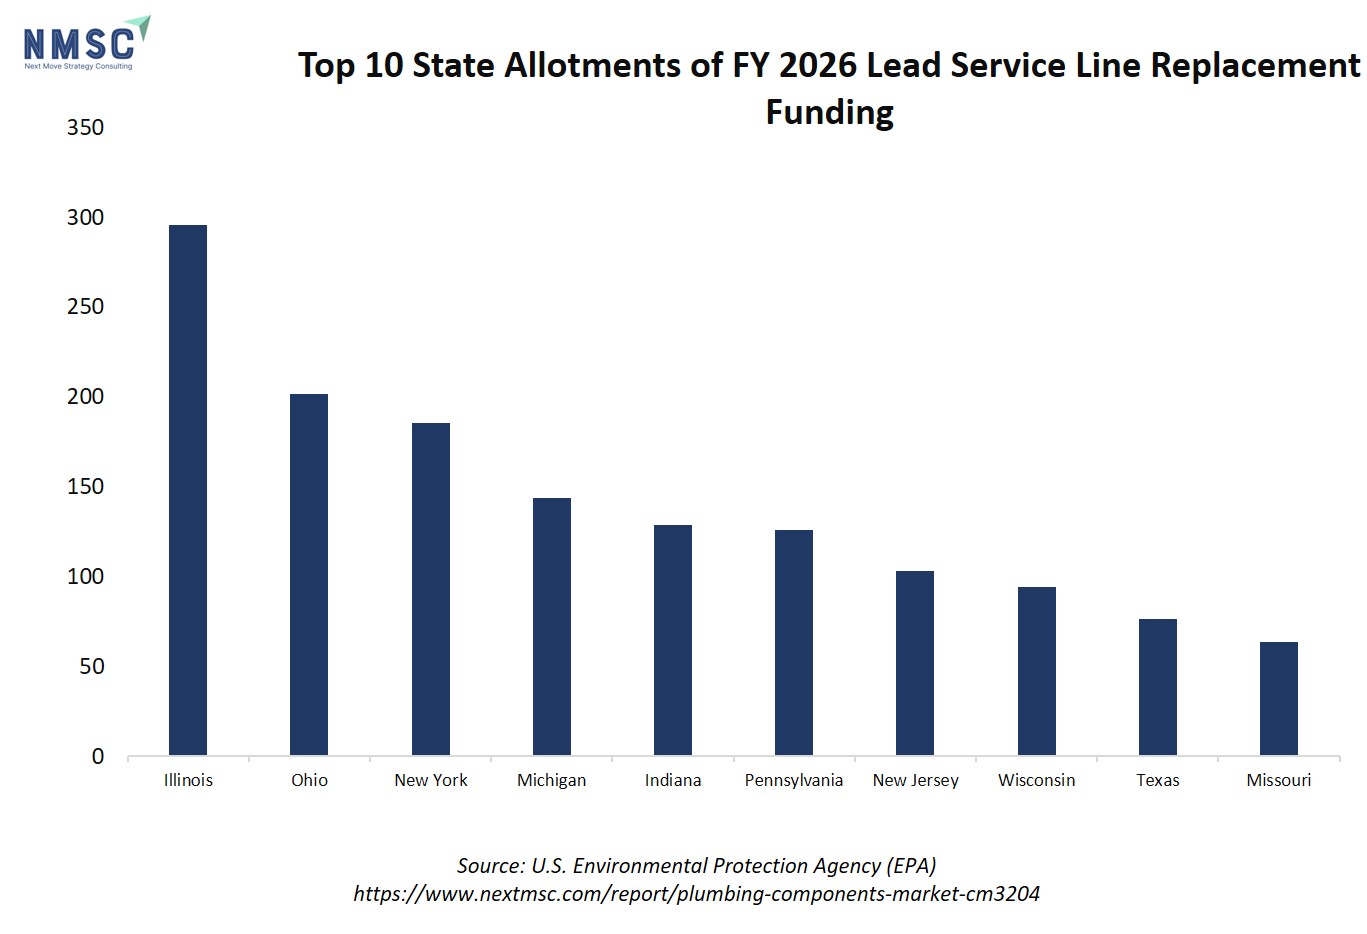
On August 21, 2026, the EPA followed with additional compliance guidance for water systems operating under the 2024 Lead and Copper Rule Improvements (LCRI), which requires all public water systems to complete a full baseline inventory of service line materials by November 1, 2027, and to begin replacing lead service lines on a mandatory schedule. The guidance clarifies how water agencies must assess, identify, and access service lines — including provisions for systems where replacement is constrained by state law, private property access limitations, or physical feasibility challenges.
The funding backstop for this mandate is substantial. The 2021 Infrastructure Investment and Jobs Act (IIJA) provided $15 billion specifically for lead service line replacement. With IIJA authorisation expiring on September 30, 2026, the U.S. Senate in July 2026 began the reauthorisation process through the Water Resources Development Act of 2026 (WRDA 2026; S. 4949), which would authorise $16.5 billion for the DWSRF over five years — a figure that, if enacted, would sustain replacement-driven pipe demand well into the next decade.
For manufacturers of copper, PEX, and HDPE pipes — the materials most commonly specified as lead service line replacements — this regulatory pipeline represents a committed, multi-year order book that is insulated from the interest-rate sensitivity and discretionary spending cycles that constrain residential new construction.
Kohler's KBIS 2026 Showcase: Sustainability and Smart Technology Redefine the Fixtures Segment
At the Kitchen and Bath Industry Show (KBIS) in February 2026, Kohler Co. unveiled its "Step into Possibility" brand experience across a 15,600-square-foot booth, presenting a product portfolio that signals where the premium fixtures segment is heading: water efficiency measured in precise percentages, recycled-content manufacturing, and health-sensing integration embedded directly into plumbing hardware.
The centrepiece water-efficiency product was the Anthem EvoCycle smart shower, a recirculating dual-mode system that delivers up to 80% water savings in Cycle Mode while maintaining full flow — a specification that directly addresses the DOE 2026 efficiency standards and EPA water mandates that Plumbing Manufacturers International CEO Kerry Stackpole described as "prompting manufacturers to redesign core product lines." The Parallel 1.25 gpm showerhead delivers a full-pressure spray at half the flow rate of a standard showerhead, while the WasteLAB Vox sink is composed of more than 70% recycled materials generated from Kohler's own manufacturing operations.
Kohler also debuted Kohler Health Dekoda, a health-sensing system that attaches to the toilet bowl and provides insights into hydration, gut health, and blood detection — a product category that extends the addressable market for plumbing fixtures beyond water management into preventive healthcare monitoring.
These product introductions are consistent with the broader industry trajectory described by Kerry Stackpole, CEO of Plumbing Manufacturers International, in Supply House Times: "Decarbonisation goals are driving innovations in product manufacturing," with LEED-certified facilities from Viega and TOTO and Duravit's climate-neutral ceramic plant — which alone will eliminate 11,000 tons of annual carbon emissions — representing the manufacturing-side commitment to sustainability that is now embedded in product specifications.
The 500,000-Plumber Deficit: How Labour Scarcity Is Accelerating Press-Connect Fitting Adoption
Underlying every segment of the plumbing components market is a structural labour constraint that is reshaping which products gain share. A study by John Dunham & Associates, cited by Plumbing Manufacturers International, documents a deficit of more than 500,000 plumbers nationwide, costing the U.S. economy over $38 billion annually.
Kerry Stackpole, CEO of Plumbing Manufacturers International, stated in Supply House Times (December 12, 2025): "Filling this gap will require rekindled vocational programs, expanded apprenticeships, and more collaboration among the plumbing industry."
The practical market consequence is a measurable shift in fitting specification. Press-connect fittings — which eliminate the need for open-flame soldering, reduce installation time per joint, and require significantly less trade-specific training than traditional copper sweat connections — are gaining adoption precisely because they allow contractors to deploy less-experienced labour on plumbing rough-in without compromising joint integrity. This dynamic is expanding the addressable market for press-connect fittings in both new commercial construction and the retrofit segment, where the volume of aging residential and institutional buildings requiring pipe upgrades is substantial.
Matt Baranuk, Commercial Portfolio Director at A. O. Smith, noted in Supply House Times (December 12, 2025): "We are definitely seeing a shift toward a more technologically advanced workforce; an education in controls, automation, data, and systems thinking is essential for every role."
Market Segmentation and Regional Dynamics
|
Event |
Date |
Market Impact |
|
EPA announces $2.9B DWSRF funding for lead pipe replacement |
May 20, 2026 |
Non-discretionary demand for copper, PEX, HDPE pipes across U.S. municipal systems |
|
EPA releases LCRI compliance guidance; Nov. 2027 inventory deadline confirmed |
August 21, 2026 |
Accelerates procurement planning for replacement pipes and fittings by county water agencies |
|
Senate introduces WRDA 2026 (S. 4949) authorising $16.5B for DWSRF over 5 years |
July 2026 |
Sustains federal funding pipeline for lead service line replacement beyond IIJA expiry |
|
Kohler unveils Anthem EvoCycle (80% water savings) and WasteLAB Vox sink at KBIS 2026 |
February 17, 2026 |
Raises efficiency benchmark for showerhead and sink categories; accelerates DOE compliance product redesign |
|
PVC antitrust settlements reach $415.4M; six distributors named alleged co-conspirators |
September 24, 2026 |
Pricing transparency pressure on PVC pipe/fittings distribution; potential channel restructuring |
|
PMI cites 500,000+ plumber deficit costing U.S. economy $38B+ annually |
December 2025 |
Accelerates press-connect fitting adoption; expands addressable market for installation-efficient components |
NMSC Strategic Perspective: Three Structural Shifts Redefining the Plumbing Components Market
NextMSC primary research and analysis identifies three structural shifts that will determine competitive positioning in the plumbing components market through 2030:
1. Regulatory Demand Is Now the Most Reliable Growth Engine — But It Favours Specific Materials
The EPA's LCRI mandate and the $2.9 billion in DWSRF funding announced in May 2026 represent a category of demand that is qualitatively different from construction-cycle-dependent growth: it is legally compelled, federally funded, and time-bound by a November 2027 inventory deadline. However, this demand is not uniformly distributed across the product landscape. It flows specifically to copper, PEX, and HDPE pipe manufacturers whose products are approved as lead service line replacements under EPA specifications. Manufacturers of PVC pipe — already under pricing scrutiny from the antitrust litigation — face a more complex environment, as PVC is not a primary replacement material for lead service lines in potable water applications. NMSC's analysis indicates that the regulatory demand wave will structurally shift the product mix within the pipes and tubes segment toward cross-linked polyethylene and copper alloys over the 2025–2030 forecast period.
2. The PVC Antitrust Case Will Accelerate Distribution Channel Consolidation — and Create Pricing Transparency That Reshapes Manufacturer Margins
The In re PVC Pipe Antitrust Litigation case is not merely a legal proceeding; it is a forced transparency event for a distribution channel that has historically operated with limited public pricing visibility. With proposed settlements exceeding $415 million and a DOJ grand jury investigation still active, the six distributors named as alleged co-conspirators — who collectively control more than 70% of direct PVC Pipe Systems purchases in the United States — face reputational and operational pressure that will accelerate the private equity-driven consolidation already reshaping the sector. NMSC's analysis suggests that the post-litigation distribution landscape will feature fewer, larger platforms with more standardised pricing protocols, compressing distributor margins on commodity PVC products while creating differentiation opportunities for manufacturers of higher-specification materials (PEX, HDPE, press-connect fittings) that are less susceptible to commodity price coordination.
3. Smart and Health-Sensing Fixtures Are Expanding the Plumbing Components Addressable Market Beyond Water Management
Kohler's debut of the Kohler Health Dekoda health-sensing toilet system at KBIS 2026 — a device that monitors hydration, gut health, and blood detection from the toilet bowl — represents a category boundary expansion that NMSC views as a leading indicator of where premium fixture demand is heading. When plumbing hardware becomes a health data collection point, the competitive set for fixture manufacturers expands from bath and kitchen specialists to medical device and digital health companies. This convergence will require plumbing components manufacturers to invest in sensor integration, data security compliance, and healthcare-grade materials certification — capabilities that will differentiate the premium segment from commodity fixture production and support above-market pricing power for early movers.
Geographical Analysis
Asia-Pacific remains the highest-volume growth region for plumbing components, driven by urbanisation rates that are translating directly into new residential and commercial construction. India's plumbing sector is experiencing demand acceleration from government spending on water supply and sanitation infrastructure, with companies such as Prince Pipes & Fittings — the fifth-largest plastic pipes manufacturer in India, holding approximately 7% domestic market share — expanding capacity and distribution networks to capture both the agricultural and building materials segments. China's construction activity, while moderating from peak levels, continues to generate substantial demand for PPR pipes and fittings in both new builds and infrastructure projects.
North America presents a bifurcated demand picture. The residential new construction segment faces persistent affordability headwinds — Keith Prather, MBA, Managing Partner and Co-Founder of Armada Corporate Intelligence, stated in Supply House Times (December 12, 2025): "Residential headwinds continue. Higher home prices, construction and borrowing costs are keeping many buyers on the sidelines." However, the remodelling segment is structurally stronger, with the National Association of Home Builders noting that remodelling's share of residential construction is now structurally higher, not merely a pandemic-era anomaly. Non-residential construction in data centres, healthcare, education, and warehouse facilities is providing stable commercial demand.
Europe is characterised by a focus on durability, sustainability certification, and advanced materials. TOTO and Duravit's investments in climate-neutral manufacturing — including Duravit's ceramic plant targeting elimination of 11,000 tons of annual carbon emissions — reflect the regulatory and consumer pressure on European manufacturers to embed sustainability credentials into their production processes, not merely their product specifications.
Rest of World markets in the Middle East, Africa, and Latin America are experiencing infrastructure investment-driven demand for PPR pipes and basic fittings, with economic development and urbanisation creating a long-duration growth runway for manufacturers willing to invest in regional distribution and local specification compliance.
Competitive Landscape
Key players profiled in NMSC's Plumbing Components Market report include Finolex Industries Ltd., Kohler Co., American Standard, Delta Faucet Company, Moen Incorporated, GROHE Pacific Pte Ltd., Watts, Zurn Water LLC, Toto Ltd., Ideal Standard International, Jaquar, Hansgrohe, Pfister Faucets, Caleffi S.p.a., and Geberit Plumbing Technology.
Across this competitive field, the strategic divergence is sharpening. Manufacturers investing in press-connect fittings, smart shower systems, and health-sensing fixtures are targeting the labour-constrained, efficiency-mandated, and wellness-oriented demand vectors that NMSC's analysis identifies as the primary growth drivers through 2030. Those remaining concentrated in commodity PVC pipe production face the dual headwinds of antitrust-driven pricing transparency and regulatory preference for alternative materials in the largest federally funded replacement programme in U.S. water infrastructure history.
Bottom Line
The global plumbing components market, valued at USD 83.90 billion in 2024 and projected to reach USD 116.33 billion by 2030 at a 5.6% CAGR per NextMSC primary research and analysis, is navigating a period of simultaneous structural disruption and durable demand creation. The PVC antitrust litigation — with proposed settlements exceeding $415 million and six major distributors named as alleged co-conspirators controlling more than 70% of U.S. direct PVC pipe purchases — is forcing pricing transparency into a distribution channel that has historically operated with limited public visibility, accelerating consolidation and compressing commodity margins. Concurrently, the EPA's $2.9 billion DWSRF funding announcement and the LCRI's November 2027 compliance deadline are generating non-discretionary, federally backed demand for copper, PEX, and HDPE replacement pipes that is insulated from construction-cycle volatility. Kohler's KBIS 2026 product launches — including an 80%-water-saving smart shower and a health-sensing toilet system — signal that the premium fixtures segment is expanding its addressable market beyond water management into preventive healthcare. Against a backdrop of a 500,000-plumber labour deficit costing the U.S. economy over $38 billion annually, press-connect fittings and installation-efficient components are gaining structural market share. The manufacturers and distributors best positioned for the 2025–2030 forecast period are those who have already aligned their product portfolios with regulatory compliance requirements, smart technology integration, and the labour-efficiency imperative.
About Next Move Strategy Consulting
Next Move Strategy Consulting is a premier market research and management consulting firm that has been committed to provide strategically analysed well documented latest research reports to its clients. The research industry is flooded with many firms to choose from, what makes NMSC different from the rest is its top-quality research and the obsession of turning data into knowledge by dissecting every bit of it and providing fact-based research recommendation that is supported by information collected from over 500 million websites, paid databases, industry journals and one on one consultations with industry experts across a diverse range of industry sectors. The high-quality customized research reports with actionable insights and excellent end-to-end customer service help our clients to take critical business decisions that enables them to move beyond time and have competitive edge in the industry.
We have been servicing over 1000 customers globally that includes 90% of the Fortune 500 companies over a decade. Our analysts are constantly tracking various high growth markets and identifying hidden opportunities in each sector or the industry. We provide one of the industry's best quality syndicate as well as custom research reports across 10 different industry verticals. We are committed to deliver high quality research solutions in accordance to your business needs. Our industry standard delivery solutions that ranges from the pre consultation to after-sales services, provide an excellent client experience and ensure right strategic decision making for businesses.
For more information, please contact:
Next Move Strategy Consulting
5th Floor 867 Boylston St, STE 500,
Boston, MA 02116, U.S.
E-Mail: [email protected]
Direct: +1-217-650-7991
Website: www.nextmsc.com
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment