Recent Mergers, Launches and Partnerships in the CRO Services Industry
McKesson's USD 2.25 Billion Precision Medicine Group Deal, Worldwide's Medidata AI Alliance and Strong Q2 Bookings at IQVIA and Medpace Show CRO Outsourcing Entering a Capital-Led Phase
On August 25, 2026, McKesson Corporation announced a definitive agreement to acquire Precision Medicine Group, LLC, a global provider of clinical research and biopharma commercialization services, for approximately USD 2.25 billion. According to McKesson's news release of August 25, 2026, the target combines biomarker intelligence, laboratory services and a global contract research organization, and it will report within McKesson's Oncology & Multispecialty segment once customary closing conditions, including regulatory clearances, are met. McKesson Chair and Chief Executive Officer Brian Tyler said the acquisition would strengthen clinical trial execution and broaden the company's clinical service offerings. The buyer is a healthcare distributor moving upstream into trial execution, a direction that Irving Levin Associates' LevinPro Healthcare M&A described on October 12, 2026 as giving McKesson capabilities in biomarker research, laboratory services and early trial design.
According to Next Move Strategy Consulting's CRO Services Market report, the global contract research organization (CRO) services market was valued at USD 77.86 billion in 2024 and is projected to reach USD 131.17 billion by 2030, growing at a CAGR of 9.1% from 2025 to 2030. NextMSC primary research and analysis places the 2025 market at USD 84.92 billion and attributes the trajectory to rising pharmaceutical R&D investment, regulatory pressure for faster drug approvals and the spread of decentralized clinical trials, three forces now visible in the scale of capital being committed to trial-execution assets.
For More Information: Download FREE Sample on CRO Services Market Report
The Financial Logic: Deal Flow, Biopharma Funding and Bookings
Capital is arriving ahead of reported revenue. In its October 12, 2026 review titled Top CRO & CDMO Deals of 2026 (So Far), Irving Levin Associates' LevinPro Healthcare M&A recorded 56 transactions across the first three quarters of 2026, made up of 31 CDMO deals and 25 CRO deals, a count that already matches the full-year 2025 volume. The publication attributes buyer appetite to the fragmented structure of the sector and to biopharma companies outsourcing entire clinical trial and manufacturing pipelines to develop complex drugs.
The demand signal behind those prices is emerging biopharma funding. On IQVIA's second-quarter 2026 earnings call on July 28, 2026, Chairman and Chief Executive Officer Ari Bousbib cited BioWorld data showing emerging biopharma funding of USD 35 billion in the second quarter, more than double the second quarter of 2025, and said such funding usually converts into CRO awards between six months and three quarters later. Bousbib added that emerging biopharma companies now account for about 70% of global clinical trial starts, against about 45% a decade earlier, and that their trials are awarded on a full-service outsourcing basis. On the same call IQVIA disclosed that large pharma represents approximately 50% of its R&D Solutions revenue, mid-size companies approximately 15% and emerging biopharma 35%, under a new classification in which large pharma is the top 20 companies by prescription sales and mid-size is the next 60.
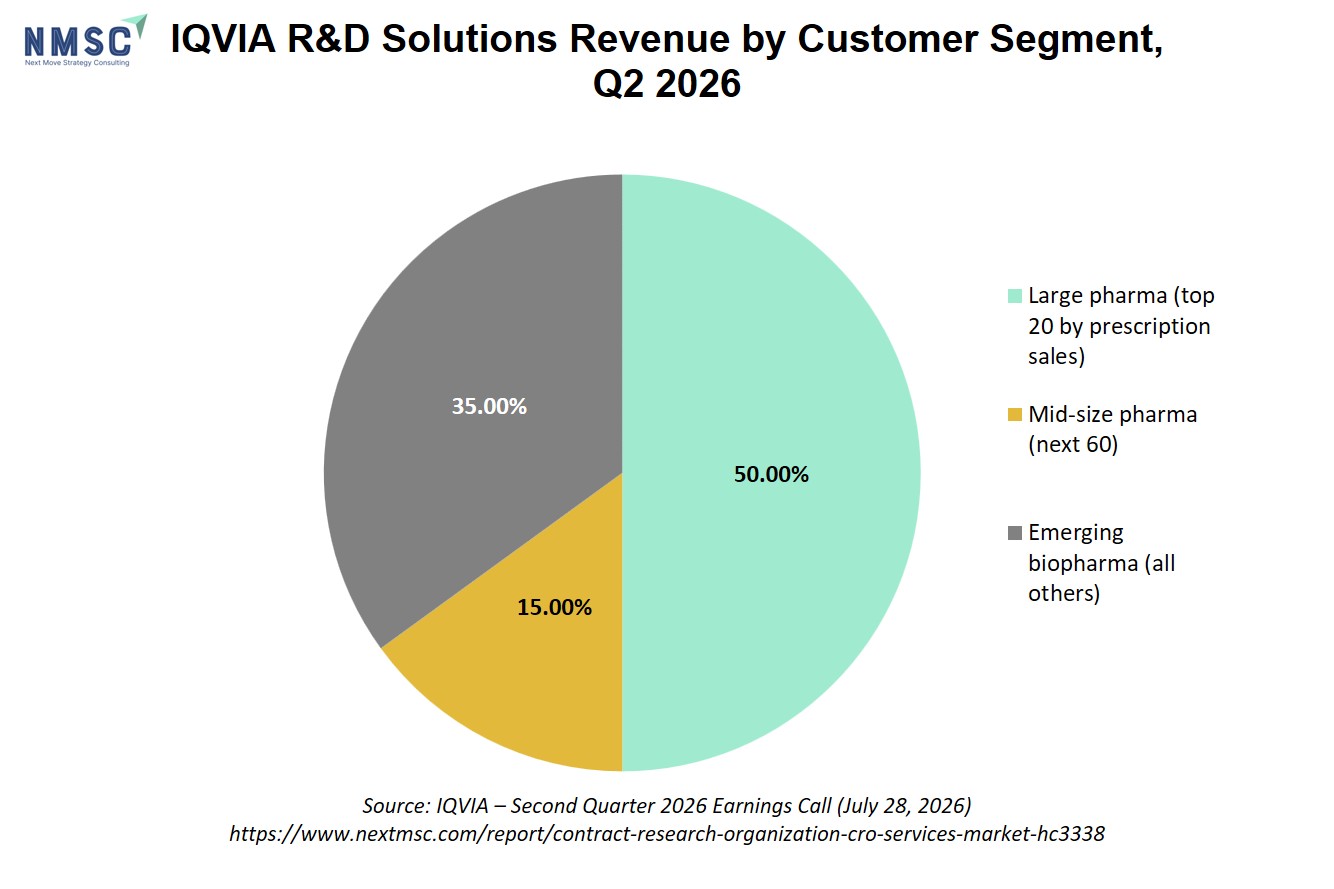
IQVIA stated that the split applies to R&D Solutions revenue and follows a customer-segment definition introduced on its second-quarter 2026 call, which it said is designed to help investors benchmark the company against other CROs.
The sequencing explains the timing of the deals. If awards follow funding by two to three quarters, the second-quarter 2026 funding surge points to a larger booking flow in late 2026 and through 2027, a reading consistent with IQVIA Chief Financial Officer Mike Fedock's statement on the same call that the quarter's bookings are more an indicator for 2027 and beyond. NextMSC primary research and analysis reads this lag as a plausible reason acquirers are paying for execution capacity before the revenue appears in reported results.
Key Industry Developments: Deals, Alliances and Reported Demand
Earlier in the year, on March 24, 2026, Thermo Fisher Scientific announced completion of its acquisition of Clario Holdings, a provider of endpoint data solutions for clinical trials, for USD 8.875 billion in cash plus potential earn-out and other payments. Thermo Fisher stated that Clario's platform has supported approximately 70% of FDA and EMA novel drug approvals over the past decade and that the business will sit within its Laboratory Products and Biopharma Services segment.
On April 23, 2026, Worldwide Clinical Trials and Medidata, a Dassault Systèmes brand, announced an expanded partnership under which Worldwide became the first global CRO to implement Medidata Plus, extending Medidata's AI layer across study, data and patient-experience workflows. Worldwide Chief Executive Officer Alistair Macdonald described the arrangement as grounded in trust, technology and execution discipline. Fierce Biotech reported on March 19, 2026 that Syneos Health had acquired the Chinese CRO Bestudy, which will operate as a standalone company under the Syneos umbrella, and a Syneos spokesperson said the deal strengthens the company's ability to serve customers in China's fast-growing biopharma market.
Selected 2026 CRO Services Transactions and Alliances
|
Event |
Date |
Scale or Scope |
|
McKesson to acquire Precision Medicine Group, LLC |
August 25, 2026 |
Approximately USD 2.25 billion; subject to regulatory clearances |
|
Worldwide Clinical Trials and Medidata AI partnership |
April 23, 2026 |
First global CRO to implement Medidata Plus |
|
Thermo Fisher Scientific completes Clario acquisition |
March 24, 2026 |
USD 8.875 billion in cash, plus potential earn-out payments |
|
Syneos Health acquires Bestudy (China) |
March 19, 2026 |
Bestudy retained as a standalone company within Syneos Health |
|
IQVIA completes acquisition of Charles River Laboratories discovery assets |
Second quarter 2026 |
Reported on IQVIA's July 28, 2026 earnings call |
Reported demand at the three listed CROs supports the funding thesis, with one caveat on how bookings are measured. IQVIA reported on July 28, 2026 that R&D Solutions net new bookings reached USD 3.15 billion, up 19% year over year, for a book-to-bill ratio of 1.22x and a contracted backlog of USD 34.2 billion.
“In a strengthening market environment, the IQVIA team executed well and delivered outstanding results”
- Ari Bousbib, Chairman and Chief Executive Officer, IQVIA, IQVIA Reports Second-Quarter 2026 Results, July 28, 2026.
Medpace Holdings reported on July 22, 2026 that second-quarter revenue rose 17.2% to USD 707.3 million and net new business awards climbed 28.2% to USD 795.7 million, lifting its net book-to-bill ratio to 1.13x from 0.88x in the first quarter of 2026. Its backlog stood at USD 3,014.2 million at June 30, 2026, up 4.9% year over year. ICON plc reported on July 29, 2026 net business wins of USD 3,120 million and a net book-to-bill of 1.51 for the quarter, but stated that higher pass-through activity lifted revenue and bookings and that its direct-fee book-to-bill ratio was 1.2x. ICON's adjusted EBITDA fell 21.7% year over year to USD 327.2 million, or 15.9% of revenue.
IQVIA also said it is reviewing its backlog for inactive trials. Fedock said any adjustment would be in the ballpark of 5%, would be finalized on the third-quarter call and would not affect historical results, guidance or next-twelve-month revenue from backlog.
Second-Quarter 2026 Demand Indicators at Three Listed CROs
|
Company |
Report Date |
Net New Bookings |
Book-to-Bill |
Quarterly Revenue |
|
IQVIA (R&D Solutions) |
July 28, 2026 |
USD 3.15 billion |
1.22x |
USD 2.575 billion |
|
Medpace |
July 22, 2026 |
USD 795.7 million |
1.13x |
USD 707.3 million |
|
ICON plc |
July 29, 2026 |
USD 3,120 million |
1.51x (direct-fee 1.2x) |
USD 2,063.5 million |
Segment and Regional Dynamics
NextMSC segments the market by type into clinical research services (split by Phase I to IV and by interventional and real-world evidence studies), early phase development services (chemistry, manufacturing and controls, preclinical services and discovery studies), laboratory services (analytical and bioanalytical testing), consulting services and data management services. According to NextMSC primary research and analysis, rising trial complexity and the push for faster approvals are moving sponsors toward outsourced execution, and AI applied to patient recruitment, trial monitoring and outcome prediction is the principal efficiency opportunity for providers.
NextMSC primary research and analysis identifies North America as the leading region by market share, supported by the concentration of pharmaceutical companies and research institutions in the United States. Europe is another significant region, with Germany, the United Kingdom and France investing in clinical trial management systems and patient recruitment technologies while decentralized trials gain ground. Asia-Pacific, led by China and India, is growing on large patient populations, lower operating costs and rising oncology and immunology trial activity, and the Rest of the World, covering Latin America, the Middle East and Africa, is gradually increasing its share of global clinical research.
Growth Drivers and Restraints
CRO Services Market: Growth Catalyst and Risk Assessment Matrix
|
Factor |
Type |
Named Evidence |
Geography |
|
Emerging biopharma funding converting into full-service awards |
Driver |
BioWorld-reported funding of USD 35 billion in the second quarter of 2026, cited by IQVIA; awards follow funding by six months to three quarters |
Global |
|
Pharmaceutical R&D outsourcing and demand for faster approvals |
Driver |
NextMSC primary research and analysis |
Global |
|
AI-enabled trial operations |
Driver |
Worldwide Clinical Trials and Medidata partnership (April 23, 2026); IQVIA reported 294 agents deployed across 90 use cases (July 28, 2026) |
North America, Europe, Asia-Pacific |
|
High operating costs and pass-through distortion |
Restraint |
ICON adjusted EBITDA margin of 15.9% (July 29, 2026); IQVIA cited an 80 basis point pass-through margin headwind (July 28, 2026) |
Global |
|
BIOSECURE implementation |
Restraint |
Section 851 of the FY2026 NDAA; initial OMB list of biotechnology companies of concern due by December 18, 2026 (K&L Gates, January 20, 2026) |
United States federal contracting |
|
Backlog quality |
Restraint |
IQVIA review of inactive trials, potential adjustment near 5% (July 28, 2026) |
Global |
NMSC Strategic Perspective: Capacity, Capital and Compliance Converge
NextMSC primary research and analysis reads the McKesson transaction as a change in who wants to own clinical execution capacity. McKesson's stated rationale is to add clinical research and commercialization services to an oncology-focused segment. NextMSC's therapeutic-area segmentation begins with oncology, and its Asia-Pacific analysis cites oncology and immunology trials as demand drivers, which supports the view that providers pairing biomarker laboratories with trial operations hold a scarce combination when patient selection depends on assay data generated before and during enrolment.
NextMSC's analysis also indicates that reported bookings need careful reading. Medpace's net book-to-bill moved from 0.88x in the first quarter to 1.13x in the second, which shows quarterly volatility inside a rising year. ICON's headline 1.51x compares with a direct-fee ratio of 1.2x because pass-through costs carry no profit, and IQVIA put the margin drag from pass-throughs at 80 basis points. For investors and sponsors, direct-fee bookings and backlog quality, including the outcome of IQVIA's inactive-trial review, are more reliable indicators of earnings power than headline ratios.
Regulation adds a vendor-selection criterion. Section 851 of the FY2026 National Defense Authorization Act, signed on December 18, 2025, restricts federal procurement of biotechnology equipment and services from designated biotechnology companies of concern. K&L Gates stated in its January 20, 2026 analysis that the Office of Management and Budget must publish the initial list by December 18, 2026 and that life sciences companies relying on contract research partners are among those most likely to be affected. Arnold & Porter's December 2025 advisory flagged whether WuXi AppTec would be designated as a question to watch. NextMSC's analysis indicates that sponsors with federal exposure are likely to map CRO vendors against the list during 2027 planning, and that implementation lags in federal acquisition rules make near-term revenue effects limited.
The three signals point the same way: funding is rising, buyers are paying for scale, and the compliance perimeter is about to be drawn. NextMSC's analysis suggests that CROs combining full-service capacity, AI-enabled operations and transparent supply-chain provenance are best placed to convert the 2026 funding cycle into 2027 revenue.
Competitive Landscape
NextMSC's report profiles 15 companies, including IQVIA, Thermo Fisher Scientific, Labcorp, WuXi AppTec, Syneos Health, Charles River Laboratories, Pharmaron, Eurofins Scientific, Worldwide Clinical Trials, Fortrea, Parexel, ICON, SGS and others, with market share data for ten of them. According to NextMSC primary research and analysis, the competitive field is separating into scaled full-service providers and specialists, and recent transactions show each group buying what it lacks: Thermo Fisher bought clinical endpoint data, IQVIA bought discovery assets, Syneos bought a China presence, and McKesson is buying a biomarker-led CRO. Each event is traceable to the company announcements cited above.
Bottom Line
The CRO services market is moving from steady outsourcing into a capital-led phase. McKesson's USD 2.25 billion agreement for Precision Medicine Group, announced on August 25, 2026, joins Thermo Fisher's USD 8.875 billion Clario completion and IQVIA's Charles River discovery asset purchase as evidence that buyers value execution capacity and trial data. Emerging biopharma funding of USD 35 billion in the second quarter, as cited by IQVIA, points to stronger awards in late 2026 and 2027. According to NextMSC primary research and analysis, the market was valued at USD 77.86 billion in 2024 and is projected to reach USD 131.17 billion by 2030 at a CAGR of 9.1%. Three dates matter next: IQVIA's third-quarter update and inactive-trial review, its December 2, 2026 Investor Day, and the December 18, 2026 deadline for the BIOSECURE list.
About Next Move Strategy Consulting
Next Move Strategy Consulting is a premier market research and management consulting firm that has been committed to provide strategically analysed well documented latest research reports to its clients. The research industry is flooded with many firms to choose from, what makes NMSC different from the rest is its top-quality research and the obsession of turning data into knowledge by dissecting every bit of it and providing fact-based research recommendation that is supported by information collected from over 500 million websites, paid databases, industry journals and one on one consultations with industry experts across a diverse range of industry sectors. The high-quality customized research reports with actionable insights and excellent end-to-end customer service help our clients to take critical business decisions that enables them to move beyond time and have competitive edge in the industry.
We have been servicing over 1000 customers globally that includes 90% of the Fortune 500 companies over a decade. Our analysts are constantly tracking various high growth markets and identifying hidden opportunities in each sector or the industry. We provide one of the industry’s best quality syndicate as well as custom research reports across 10 different industry verticals. We are committed to deliver high quality research solutions in accordance to your business needs. Our industry standard delivery solutions that ranges from the pre consultation to after-sales services, provide an excellent client experience and ensure right strategic decision making for businesses.
For more information, please contact:
Next Move Strategy Consulting
5th Floor 867 Boylston St, STE 500,
Boston, MA 02116, U.S.
E-Mail: [email protected]
Direct: +1-217-650-7991
Website: www.nextmsc.com
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.










Add Comment