Gelatin Capsule Market Global Industry Analysis and Forecast (2026-2035)

Gelatin Capsule Market size was USD 5.02 Billion in 2025, projected to reach USD 10.32 Billion by 2035, growing at a CAGR of 7.14% from 2026 to 2035. Key drivers include rising nutraceutical consumption, expanding pharmaceutical manufacturing capacity, and CDMO outsourcing, with North America leading the market and Asia-Pacific registering the fastest growth .

Download Free Sample PDF
Base Year (2025)
$5.02 Billion
Forecast (2035)
$10.32 Billion
CAGR (2026-2035)
7.1%
Top Country
North America

What Is the Gelatin Capsule Market Size?

The global gelatin capsule market size was valued at USD 5.02 billion in 2025 and is estimated at USD 5.55 billion in 2026, forecast to reach USD 10.32 billion by 2035, expanding at a 7.14% CAGR between 2026 and 2035. North America leads with approximately 32% share, while hard gelatin capsules dominate all other capsule types with approximately 62% share.

We observed that growth is broad-based across every segmentation axis, with soft gelatin capsule adoption and nutraceutical-linked demand driving the dominant structural shifts through 2035. The market's competitive environment remains moderately consolidated, led by global empty-capsule manufacturers expanding pharmaceutical and nutraceutical production capacity across North America, Europe, and Asia-Pacific.

Gelatin Capsule Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $5.02 Billion
2025
2026 $5.38 Billion
2026
2027 $5.76 Billion
2027
2028 $6.17 Billion
2028
2029 $6.61 Billion
2029
2030 $7.09 Billion
2030
2031 $7.59 Billion
2031
2032 $8.14 Billion
2032
2033 $8.72 Billion
2033
2034 $9.34 Billion
2034
2035 $10.32 Billion
2035

Key Takeaways

By Capsule Type: Hard Gelatin Capsules held the largest share of approximately 62% (USD 3.11 billion) in 2025; Soft Gelatin Capsules is the fastest-growing sub-segment at 9.6% CAGR from 2026–2035.

By Application: Pharmaceuticals held the largest share of approximately 56% (USD 2.81 billion) in 2025; Nutraceuticals is the fastest-growing sub-segment at 10.8% CAGR from 2026–2035.

By Gelatin Source: Bovine Gelatin held the largest share of approximately 46% (USD 2.31 billion) in 2025; Marine Gelatin is the fastest-growing sub-segment at 13.6% CAGR from 2026–2035.

By Release Profile: Immediate Release held the largest share of approximately 72% (USD 3.61 billion) in 2025; Modified Release is the fastest-growing sub-segment at 10.8% CAGR from 2026–2035.

By Fill Material: Solid Fill held the largest share of approximately 48% (USD 2.41 billion) in 2025; Liquid Fill is the fastest-growing sub-segment at 9.6% CAGR from 2026–2035.

By Distribution Channel: Indirect Sales held the largest share of approximately 58% (USD 2.91 billion) in 2025; Direct Sales is the fastest-growing sub-segment at 8.9% CAGR from 2026–2035.

By End User: Pharmaceutical Companies held the largest share of approximately 48% (USD 2.41 billion) in 2025; CDMOs is the fastest-growing sub-segment at 12.9% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 32% revenue share (USD 1.61 billion) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 9.9% during 2026–2035.

Dominant Country: U.S. led with approximately USD 1.32 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 12.1% CAGR from 2026–2035.

Market Opportunity: The gelatin capsule market is expected to create an absolute dollar opportunity of USD 4.77 billion between 2026 and 2035, presenting significant investment potential across soft gelatin, marine-sourced, and CDMO-serviced capsule categories.

According to NMSC analysis, empty-capsule manufacturers are increasingly divesting or restructuring capsule divisions to pure-play private equity ownership to accelerate independent capacity investment, a shift that favors specialized capsule producers over diversified life-science conglomerates as dedicated capital flows into pharmaceutical and nutraceutical capsule manufacturing through 2035.

What Does the Gelatin Capsule Market Encompass?

The gelatin capsule market encompasses empty and filled two-piece hard gelatin capsules and one-piece soft gelatin capsules manufactured from bovine, porcine, or marine gelatin, used to encapsulate solid, liquid, or semi-solid pharmaceutical and nutraceutical fill materials. Our assessment indicates that the scope spans capsule shell manufacturing, capsule filling services, and finished dosage forms sold to pharmaceutical companies, nutraceutical companies, and contract development and manufacturing organizations across direct and indirect distribution channels. This report defines the market strictly around gelatin-based capsule shells and their filled derivatives; it excludes non-gelatin vegetarian capsule shells made from hydroxypropyl methylcellulose or pullulan, raw gelatin sold as a standalone food or industrial ingredient, and finished pharmaceutical products whose value is driven primarily by active ingredient formulation rather than the capsule shell itself.

The category has evolved from simple two-piece hard capsules into functionally engineered formats, including liquid-fill hard capsules, enteric and modified-release softgels, and capsule-in-capsule technologies that improve bioavailability and taste masking. Regulatory frameworks such as U.S. Food and Drug Administration current good manufacturing practice requirements and European Pharmacopoeia gelatin monographs shape sourcing, traceability, and quality standards for capsule manufacturers. We observed that technology adoption is shifting toward plant-based and marine-derived alternatives alongside conventional bovine and porcine gelatin, as manufacturers respond to religious, dietary, and sustainability-driven customer requirements. NMSC's analysis indicates that this structural shift, combined with private equity-driven capacity investment, is redefining sourcing and manufacturing priorities across the gelatin capsule market.

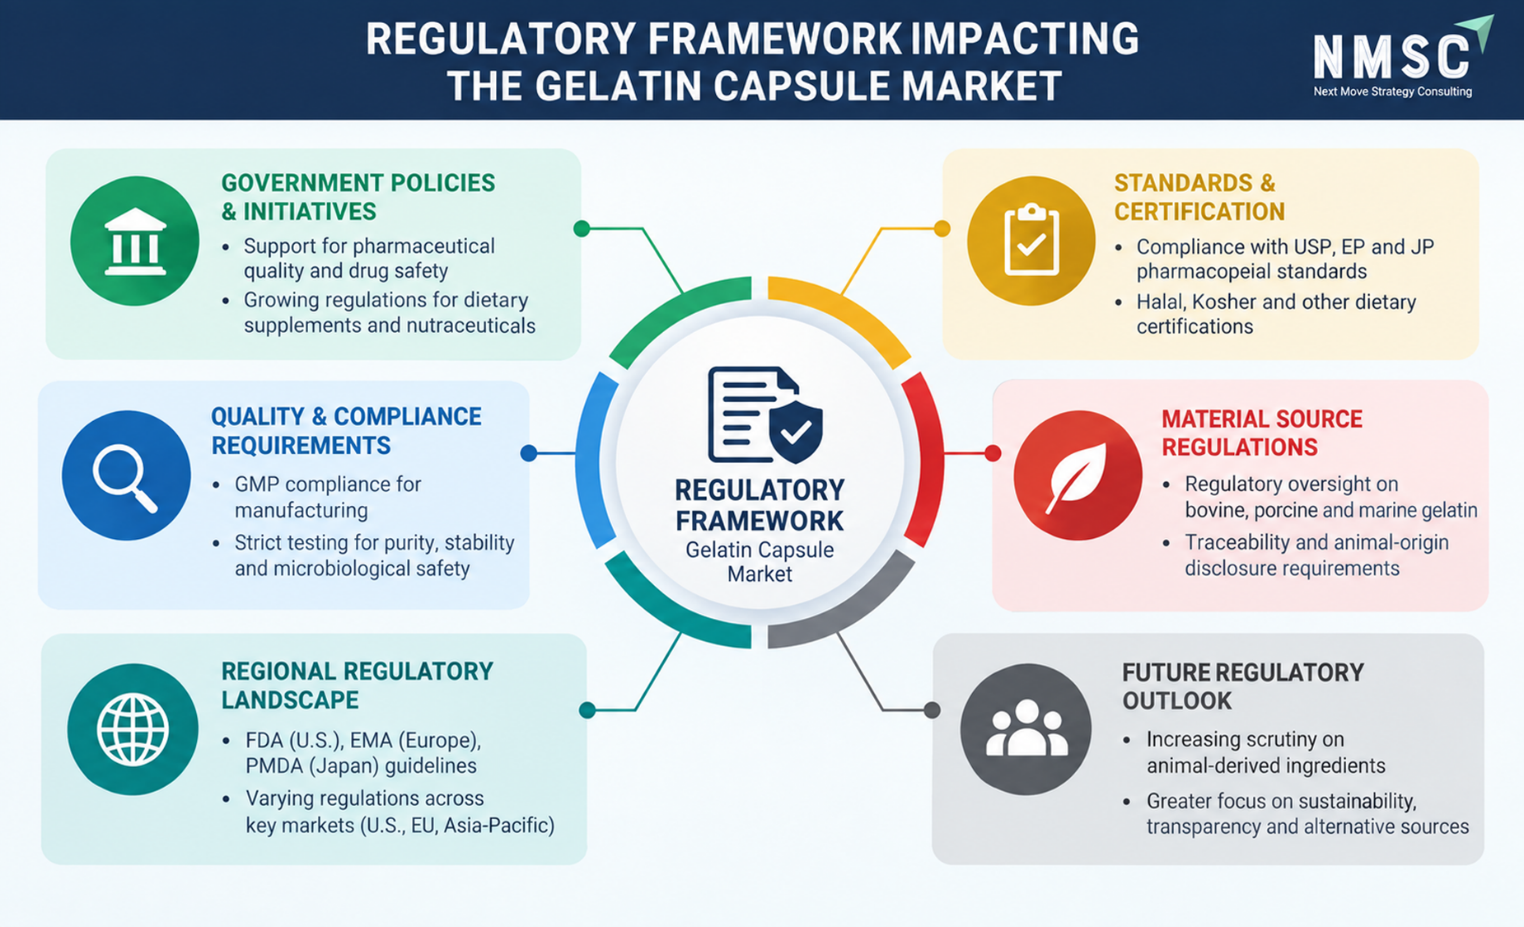
Regulatory Framework Impacting the Gelatin Capsule Market

The infographic presents the key regulatory factors shaping the global gelatin capsule market. It highlights pharmaceutical quality and safety requirements, GMP compliance, pharmacopeial standards, gelatin-source traceability, and certifications such as Halal and Kosher. It also outlines regional regulatory differences across major markets and emphasizes the future focus on animal-derived ingredients, sustainability, transparency, and alternative capsule materials.

Market Drivers & Dynamics

Interactive Dataset
Rising global nutraceutical and dietary supplement consumption driver +1.8% North America, Asia-Pacific 2026–2035
Expanding pharmaceutical dosage form manufacturing capacity driver +1.5% Global 2026–2035
Growing marine and plant-based gelatin alternative adoption driver +1.2% Europe, Asia-Pacific 2026–2035
Rising CDMO-serviced pharmaceutical outsourcing demand driver +1.0% North America, Europe 2026–2035
Expanding Asia-Pacific manufacturing capacity investment driver +0.9% Asia-Pacific 2026–2035
Growing modified-release and functional capsule adoption driver +0.6% Global 2026–2032
Dietary and religious restrictions on animal-derived gelatin restraint −1.1% Middle East & Africa, Asia-Pacific 2026–2032
Raw material price volatility in bovine and porcine gelatin restraint −0.7% Global 2026–2030
Competition from non-gelatin vegetarian capsule alternatives restraint −0.5% North America, Europe 2026–2032
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Gelatin Capsule Market?

Rising global nutraceutical and dietary supplement consumption is the primary driver of the market. U.S. Food and Drug Administration dietary supplement facility registration data continues to reflect sustained growth in the number of registered supplement manufacturing sites requiring capsule encapsulation services. We observed that this consumption pattern, reinforced by expanding softgel-based vitamin and omega-3 supplement demand, continues to anchor baseline investment in both hard and soft gelatin capsule production across developed and emerging economies alike.

How Is Pharmaceutical Manufacturing Capacity Expansion Driving Market Growth?

Expanding pharmaceutical dosage form manufacturing capacity is accelerating market growth toward high-volume, quality-certified capsule production. Company disclosures show Lonza's Capsules & Health Ingredients business returning to positive constant-exchange-rate growth in the third quarter of 2025, supported by higher pharmaceutical capsule volumes. Our assessment indicates that this recovery, combined with continued Asia-Pacific capacity expansion, is compressing lead times for pharmaceutical and nutraceutical customers scaling new product launches.

Growth Inhibitors

What Is Restraining Gelatin Capsule Market Expansion?

Dietary and religious restrictions on animal-derived gelatin restrain adoption among consumers and manufacturers serving halal, kosher, and vegetarian-preference markets. Industry disclosures continue to highlight rising consumer preference for plant-based capsule alternatives as a structural constraint on conventional bovine and porcine gelatin demand growth. We found that raw material price volatility in bovine and porcine gelatin further restrains margin stability, though marine and organic plant-based alternatives are gradually diversifying manufacturers' raw material exposure.

What Are the Growth Opportunities?

How Can Marine Gelatin Sourcing Unlock Value for Halal and Kosher Markets?

Marine gelatin capsules present a whitespace opportunity for manufacturers seeking to serve halal, kosher, and allergen-conscious pharmaceutical and nutraceutical customers. Suppliers that scale fish-derived gelatin sourcing stand to capture premium pricing as religious and dietary certification becomes a decisive purchasing criterion across Middle Eastern and Asian markets.

Where Does CDMO-Serviced Capsule Manufacturing Create New Demand?

Pharmaceutical and nutraceutical brands outsourcing formulation and manufacturing represent an underpenetrated opportunity for capsule producers offering integrated contract development and manufacturing services. Providers that secure long-term CDMO capacity agreements can capture recurring volume as smaller brands increasingly rely on external manufacturing rather than building in-house capsule-filling infrastructure.

How Can Asia-Pacific Capacity Investment Benefit Regional Manufacturers?

Asia-Pacific pharmaceutical and nutraceutical manufacturers scaling production create an opportunity for capsule producers expanding regional manufacturing footprints. Early movers that secure joint-venture or greenfield capacity in India and China can differentiate ahead of import-dependent competitors as regional self-sufficiency becomes a strategic procurement priority.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Hard Gelatin
Standard Cap
Liquid-Fill
Modified-Rel
Soft Gelatin
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Hard Gelatin Capsules $10.0 USD Billion $40.0 USD Billion 8.0%
Standard Capsules $17.1 USD Billion $51.1 USD Billion 14.0%
Liquid-Fill Capsules $24.2 USD Billion $62.2 USD Billion 16.0%
Modified-Release Capsules $31.3 USD Billion $73.3 USD Billion 18.0%
Soft Gelatin Capsules $38.4 USD Billion $84.4 USD Billion 13.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Capsule Type.

Unlock Full Data

Which Capsule Type Segment Dominates the Gelatin Capsule Market?

Hard Gelatin Capsules led the market with USD 3.11 billion in 2025, supported by their established role in prescription and over-the-counter solid-dose pharmaceutical manufacturing. We observed that Soft Gelatin Capsules is the fastest-growing capsule type, expanding at a 9.6% CAGR from 2026 to 2035, as omega-3, vitamin, and herbal supplement manufacturers increasingly favor softgel formats for liquid-fill bioavailability and consumer swallowability preferences.

2025 (USD Billion)
2035 (USD Billion)
Pharmaceutic
Prescription
OTC Drugs
Clinical Tri
Nutraceutica
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Pharmaceuticals $10.0 USD Billion $40.0 USD Billion 18.0%
Prescription Drugs $17.1 USD Billion $51.1 USD Billion 16.0%
OTC Drugs $24.2 USD Billion $62.2 USD Billion 22.0%
Clinical Trials $31.3 USD Billion $73.3 USD Billion 12.0%
Nutraceuticals $38.4 USD Billion $84.4 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data

Which Application Segment Leads Market Demand?

Pharmaceuticals remained the leading application within the market, valued at USD 2.81 billion in 2025 on sustained demand for prescription and over-the-counter capsule dosage forms. Our findings suggest that Nutraceuticals is the fastest-growing application, registering a 10.8% CAGR from 2026 to 2035, as vitamin, mineral, herbal, omega-3, and probiotic supplement manufacturers scale capsule-based product lines to meet consumer wellness demand.

2025 (USD Billion)
2035 (USD Billion)
Bovine Gelat
Pharmaceutic
Nutraceutica
Porcine Gela
Pharmaceutic
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Bovine Gelatin $10.0 USD Billion $40.0 USD Billion 17.0%
Pharmaceutical Grade $17.1 USD Billion $51.1 USD Billion 11.0%
Nutraceutical Grade $24.2 USD Billion $62.2 USD Billion 13.0%
Porcine Gelatin $31.3 USD Billion $73.3 USD Billion 23.0%
Pharmaceutical Grade $38.4 USD Billion $84.4 USD Billion 12.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Gelatin Source.

Unlock Full Data

Which Gelatin Source Is Most Widely Adopted?

Bovine Gelatin remained the dominant source across the market, reaching USD 2.31 billion in 2025 due to its established availability and compatibility with pharmaceutical-grade quality standards. Based on research conducted by NMSC, we found that Marine Gelatin represents the fastest-growing category at a 13.6% CAGR from 2026 to 2035, reflecting rising halal, kosher, and allergen-conscious customer demand for fish-derived alternatives to conventional bovine and porcine sourcing.

2025 (USD Billion)
2035 (USD Billion)
Immediate Re
Standard Rel
Rapid Releas
Modified Rel
Delayed Rele
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Immediate Release $10.0 USD Billion $40.0 USD Billion 27.0%
Standard Release $17.1 USD Billion $51.1 USD Billion 13.0%
Rapid Release $24.2 USD Billion $62.2 USD Billion 15.0%
Modified Release $31.3 USD Billion $73.3 USD Billion 25.0%
Delayed Release $38.4 USD Billion $84.4 USD Billion 14.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Release Profile.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Solid Fill
Powders
Granules
Pellets
Mini-Tablets
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Solid Fill $10.0 USD Billion $40.0 USD Billion 14.0%
Powders $17.1 USD Billion $51.1 USD Billion 16.0%
Granules $24.2 USD Billion $62.2 USD Billion 26.0%
Pellets $31.3 USD Billion $73.3 USD Billion 24.0%
Mini-Tablets $38.4 USD Billion $84.4 USD Billion 11.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Fill Material.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct Sales
Indirect Sal
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Sales $10.0 USD Billion $40.0 USD Billion 25.0%
Indirect Sales $17.1 USD Billion $51.1 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Distribution Channel.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Pharmaceutic
Nutraceutica
CDMOs
Other
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Pharmaceutical Companies $10.0 USD Billion $40.0 USD Billion 26.0%
Nutraceutical Companies $17.1 USD Billion $51.1 USD Billion 16.0%
CDMOs $24.2 USD Billion $62.2 USD Billion 18.0%
Other $31.3 USD Billion $73.3 USD Billion 8.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the gelatin capsule market over the 2026–2035 forecast period.

How Can Marine Gelatin Sourcing Unlock Value for Halal and Kosher Markets?

Marine gelatin capsules present a whitespace opportunity for manufacturers seeking to serve halal, kosher, and allergen-conscious pharmaceutical and nutraceutical customers. Suppliers that scale fish-derived gelatin sourcing stand to capture premium pricing as religious and dietary certification becomes a decisive purchasing criterion across Middle Eastern and Asian markets.

Where Does CDMO-Serviced Capsule Manufacturing Create New Demand?

Pharmaceutical and nutraceutical brands outsourcing formulation and manufacturing represent an underpenetrated opportunity for capsule producers offering integrated contract development and manufacturing services. Providers that secure long-term CDMO capacity agreements can capture recurring volume as smaller brands increasingly rely on external manufacturing rather than building in-house capsule-filling infrastructure.

How Can Asia-Pacific Capacity Investment Benefit Regional Manufacturers?

Asia-Pacific pharmaceutical and nutraceutical manufacturers scaling production create an opportunity for capsule producers expanding regional manufacturing footprints. Early movers that secure joint-venture or greenfield capacity in India and China can differentiate ahead of import-dependent competitors as regional self-sufficiency becomes a strategic procurement priority.

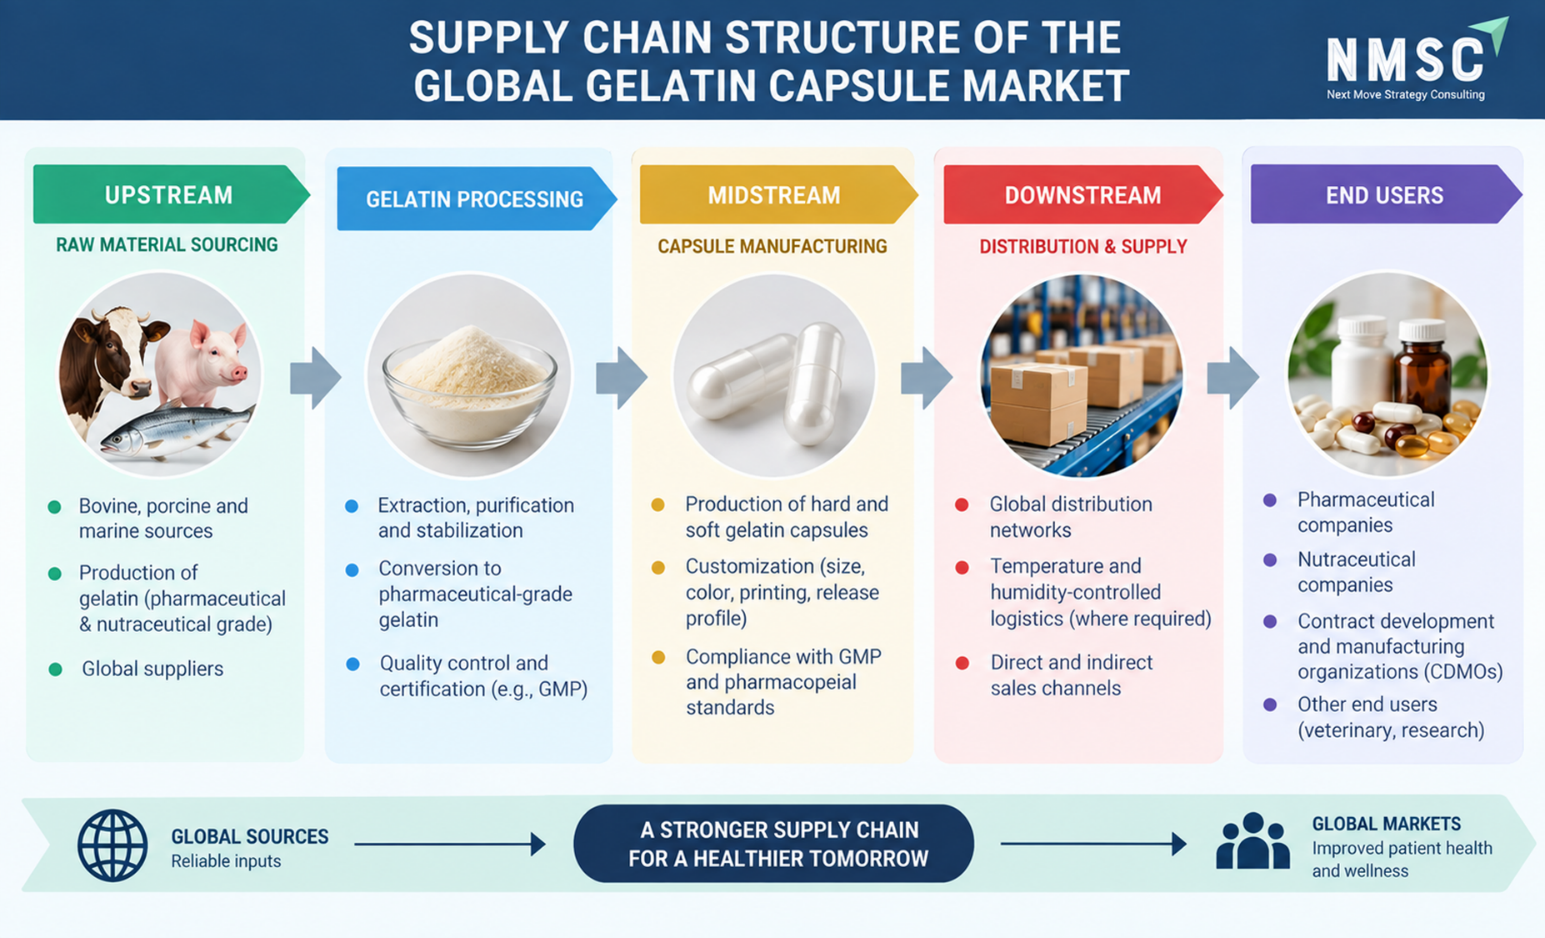
Supply Chain Structure of the Global Gelatin Capsule Market

The infographic illustrates the global supply chain structure of the gelatin capsule market, from raw material sourcing through gelatin processing and capsule manufacturing to distribution and end users. It highlights bovine, porcine, and marine gelatin sources, pharmaceutical-grade processing, hard and soft capsule production, global logistics, and direct and indirect sales channels. The downstream network serves pharmaceutical companies, nutraceutical manufacturers, CDMOs, veterinary applications, and research organizations worldwide.

Ecosystem Analysis

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Asia-Pacific
Europe
Latin Americ
Middle East
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Asia-Pacific $17.1 USD Billion $51.1 USD Billion 27.0%
Europe $24.2 USD Billion $62.2 USD Billion 25.0%
Latin America $31.3 USD Billion $73.3 USD Billion 23.0%
Middle East & Africa $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the gelatin capsule market features a moderately consolidated competitive landscape, with global empty-capsule specialists competing alongside regional manufacturers on scale, quality certification, and technology differentiation. Dimension | Details Market Structure | Moderately consolidated; global specialists such as Lonza Group Ltd. and ACG Associated Capsules Private Limited compete alongside regional manufacturers such as SUHEUNG Co., Ltd. and Qualicaps Co., Ltd. across pharmaceutical and nutraceutical customer segments. Innovation Focus | Organic and plant-based certification, capsule-in-capsule bioavailability technology, and marine gelatin sourcing dominate current innovation pipelines across leading manufacturers. M&A Activity | Active restructuring, exemplified by Lonza's March 2026 agreement to divest its Capsules & Health Ingredients business to Lone Star Funds for an enterprise value of CHF 2.3 billion. Source: www.nextmsc.com

How Do Companies Compete in the Gelatin Capsule Market?

Companies compete primarily on manufacturing scale, quality certification, and product differentiation across the industry. Global specialists such as Lonza Group Ltd. leverage broad manufacturing networks spanning North America, Europe, and Asia to serve multinational pharmaceutical and nutraceutical customers, while regional manufacturers such as ACG Associated Capsules Private Limited and Sunil Healthcare Limited compete on cost efficiency and localized customer relationships within specific geographic markets.

Which Competitive Archetypes Dominate the Gelatin Capsule Market?

Two archetypes dominate the market: diversified global specialists offering broad hard and soft capsule portfolios across multiple gelatin sources, and regional manufacturers focused on cost-competitive, high-volume production for domestic pharmaceutical and nutraceutical customers. Lonza Group Ltd. exemplifies the diversified archetype through its Capsugel brand portfolio spanning organic, marine, and functional capsule technologies, while ACG Associated Capsules Private Limited exemplifies the regional archetype through its strong presence in emerging pharmaceutical manufacturing markets.

How Are Companies Differentiating Through Innovation in Gelatin Capsules?

Innovation and differentiation strategy increasingly center on certified organic sourcing and engineered bioavailability technology. Lonza Capsugel's Organicaps launch and its Licaps DUOCAP capsule-in-capsule technology both illustrate this shift toward functionally differentiated, certification-driven product portfolios. Our analysis shows that manufacturers unable to demonstrate credible sustainability and traceability credentials risk losing premium customers to more certification-focused competitors.

What M&A and Expansion Activity Is Shaping the Gelatin Capsule Market?

Mergers, divestitures, and capacity expansion continue to reshape competitive positioning within the industry. Lonza's planned divestiture of its Capsules & Health Ingredients business to Lone Star Funds, combined with its prior capacity expansions at Rewari, India and Suzhou, China facilities, illustrates how the industry is transitioning toward dedicated, independently capitalized capsule manufacturing structures.

Key Market Players

Our assessment indicates that the following 17 companies are actively shaping product innovation, capacity expansion, and ownership restructuring within the global gelatin capsule market.

Lonza Group Ltd. ACG Associated Capsules Private Limited Procaps Group, S.A. Aenova Holding GmbH SUHEUNG Co., Ltd. Catalent, Inc. Qualicaps Co., Ltd. Sirio Pharma Co., Ltd. Healthcaps India Limited Sunil Healthcare Limited CapsCanada Corporation Medi-Caps Limited Roxlor LLC Soft Gel Technologies, Inc. Qingdao Yiqing Biotechnology Co., Ltd. Zhejiang Tianlong Capsule Co., Ltd. Yueyang Tiantian Capsule Co., Ltd.

Latest Developments

We found that recent capacity expansions and ownership changes within the gelatin capsule market are concentrated on organic certification and independent capitalization, reflecting the industry's transition toward focused, dedicated manufacturing structures.

Date Event
Nov ember 2025 ACG announced that its Personalised Medicine Concept (PMC) combines capsule and beadlet technology, precision engineering, and digital systems to enable customized dosage combinations. The company said the platform can produce tailor-made capsules with unique ingredient combinations and dosages in each batch. Following prototyping and validation, ACG entered an exclusive collaboration with Art of You (AOY) for the European market.
October 2025 CapsCanada highlighted expanded capsule-finish customization, including metallic, pearlized, luminescent, and iridescent effects. The company states that these finishes are available for both gelatin and vegetarian capsules, enabling brands to differentiate products visually while supporting regulatory requirements and consumer preferences. CapsCanada also states that the finishes are designed to enhance visual identity without affecting capsule performance.
December 2024 Lonza announced additional hard gelatin capsule manufacturing capacity at its Rewari, India, and Suzhou, China facilities. The company stated that lines at both sites were operational from Q4 2024, with additional lines scheduled to start operations in Q3 2025. The highly automated expansion is intended to increase annual capacity and enhance flexibility and reliability for pharmaceutical and nutraceutical customers in the APAC region .

Investment Opportunities

What Capital Inflows Are Targeting the Gelatin Capsule Market?

Capital inflows into the gelatin capsule market are increasingly directed toward independent, dedicated capsule manufacturing capitalization rather than diversified conglomerate ownership. Lonza's planned divestiture of its Capsules & Health Ingredients business to Lone Star Funds for CHF 2.3 billion illustrates this trend toward focused private equity investment. We observed that investors favor manufacturers demonstrating validated volume recovery, such as Lonza CHI's Q3 2025 growth return, as a proxy for long-term demand stability.

How Is Infrastructure Investment Supporting Gelatin Capsule Market Expansion?

Infrastructure investment is expanding hard and soft gelatin capsule manufacturing capacity across North America, Europe, and Asia-Pacific to serve rising pharmaceutical and nutraceutical demand. Our findings suggest that manufacturers are investing in regional production lines, exemplified by Lonza's expanded Rewari and Suzhou facilities, to compress lead times for customers facing tightening global supply chain conditions, supporting the reliability required for large-scale pharmaceutical dosage form manufacturing.

What ESG Considerations Are Shaping Gelatin Capsule Investment Decisions?

Environmental, social, and governance considerations are increasingly relevant to investment decisions across the industry, with sustainable sourcing and renewable energy adoption as key criteria. Lonza Capsugel's local wind power agreement supporting its hard empty capsule manufacturing operations illustrates this sustainability-linked investment trend. We found that investors increasingly favor manufacturers with transparent, certified organic and traceable sourcing, treating sustainability credentials as a governance indicator alongside manufacturing quality.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and manufacturing-investment decisions across the gelatin capsule industry. Our analysis shows that detailed capsule type, application, and gelatin source breakdowns help procurement and formulation teams align sourcing priorities with soft gelatin and marine-sourced growth categories.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the gelatin capsule supply chain. We observed that the report's regional and segment-level growth differentials help identify which manufacturers are best positioned to capture above-market growth in Asia-Pacific and CDMO-serviced categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging formulation requirements, including organic certification, capsule-in-capsule bioavailability technology, and marine gelatin sourcing, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around certification and functional performance increasingly required by pharmaceutical and nutraceutical customer specifications.

Key Market Segments Evaluated

By Capsule Type

  • Hard Gelatin Capsules
  • Soft Gelatin Capsules

By Application

  • Pharmaceuticals
  • Nutraceuticals
  • Cosmeceuticals
  • Other Applications

By Gelatin Source

  • Bovine Gelatin
  • Porcine Gelatin
  • Marine Gelatin

By Release Profile

  • Immediate Release
  • Standard Release
  • Rapid Release
  • Modified Release
  • Delayed Release
  • Sustained Release
  • Controlled Release

By Fill Material

  • Solid Fill
  • Powders
  • Granules
  • Pellets
  • Mini-Tablets
  • Liquid Fill
  • Oils
  • Solutions
  • Suspensions
  • Semi-Solid Fill
  • Pastes
  • Gels

By Distribution Channel

  • Direct Sales
  • Indirect Sales

By End User

  • Pharmaceutical Companies
  • Nutraceutical Companies
  • CDMOs
  • Other

Conclusion & Recommendations

The long-term outlook for the market remains positive, with global revenue projected to almost double from USD 5.02 billion in 2025 to USD 10.32 billion by 2035 at a 7.14% CAGR. We expect soft gelatin capsules, nutraceutical applications, and marine gelatin sourcing to lead category growth, while Asia-Pacific gains regional share as manufacturing capacity investment continues to shift toward China and India through the forecast period.

What Strategic Positioning Should Gelatin Capsule Suppliers Pursue?

Suppliers should prioritize organic and marine gelatin certification while pursuing CDMO service expansion to secure long-term pharmaceutical and nutraceutical contracts. Our assessment indicates that manufacturers investing early in capsule-in-capsule bioavailability technology and regional capacity balance, alongside independent capitalization structures, will be best positioned to capture premium pricing within the gelatin capsule market.

How Attractive Is the Gelatin Capsule Market for New Investment?

The gelatin capsule industry presents an attractive investment case, supported by a USD 4.77 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and marine gelatin categories. We found that investment attractiveness is highest for manufacturers combining validated volume recovery with proven certification and regional capacity capability.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor dietary and religious restrictions on animal-derived gelatin, raw material price volatility, and vegetarian capsule competition as key risks to the gelatin capsule market. Our analysis shows that manufacturers unable to adapt to certification and traceability expectations risk losing customers to competitors with stronger marine and plant-based sourcing credentials, particularly within Middle Eastern and Asian markets.

What Are the Key Growth Pathways for the Gelatin Capsule Market?

Key growth pathways include expanding marine gelatin sourcing, scaling CDMO-serviced manufacturing capacity, and deepening penetration into Asia-Pacific pharmaceutical and nutraceutical channels. NMSC's analysis indicates that manufacturers pursuing these pathways while maintaining cost competitiveness in core bovine and porcine gelatin categories will be best positioned to capture the gelatin capsule market's projected growth through 2035.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Henri Knyphausen

HENRI KNYPHAUSEN

Partner at Singulier [Ex-BCG]

Singulier

I recently engaged NEXTMSC.com for a commercial due diligence project within the intralogistics sector, and I am pleased to provide a reference based on my experience. In utilizing NEXTMSC.com's services, I found their report to offer valuable insights into market dynamics and key industry players. The initial report provided a solid foundation for our analysis. However, as we were investigating a smaller target in the market, and I had specific customization requests requiring additional research. These requests included detailed information on product portfolios of various players and sub-market sizes, both inclusive and exclusive of certain product categories. NEXTMSC.com demonstrated commendable responsiveness and agility in accommodating these customization requests. Within a timeframe of 1-2 weeks, they delivered a revised report that met our specific needs. Furthermore, they were receptive to my follow-up inquiries, ensuring clarity and understanding of the data provided. The final deliverable significantly contributed to our due diligence efforts. One of NEXTMSC.com's notable strengths lies in their qualitative research capabilities. However, for future engagements, I would recommend the inclusion of a quantified market model in Excel format. Such a model would offer the ability to conduct in-depth analyses and explore various market segments, including country-specific data and subcomponent breakdowns. Based on my positive experience, I would not hesitate to work with NEXTMSC.com again. Their responsiveness, willingness to accommodate customization requests, and commitment to delivering actionable insights make them a reliable partner for commercial research projects.


Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Diana Trejo

DIANA TREJO

Assistant Manager

Sumitomo Corporation de Mexico, S.A. de C.V.

Recently, we purchased a report on the Mexico Data Center Market from Next Move Strategy Consulting. The service has been excellent, with support that is always timely and thoroughly professional. The information provided is interesting, highly useful, and delivered with clarity. I would highly recommend NextMSC for anyone seeking insightful and dependable analysis.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖