Graphite Market Global Industry Analysis and Forecast (2026-2035)

Graphite Market size was USD 21.85 billion in 2025, projected to reach USD 58.47 billion by 2035, growing at a CAGR of 10.4% from 2026 to 2035. Key drivers include rising demand for lithium-ion battery anode materials, expanding electric arc furnace steelmaking capacity, and increasing graphite electrode consumption, with Asia-Pacific leading the market.

Download Free Sample PDF
Base Year (2025)
$21.85 Billion
Forecast (2035)
$58.47 Billion
CAGR (2026-2035)
10.4%
Top Region
Asia-Pacific

What Is the Graphite Market Size?

The global graphite market size was valued at USD 21.85 billion in 2025 and is estimated at USD 23.94 billion in 2026, forecast to reach USD 58.47 billion by 2035, expanding at a 10.4% CAGR between 2026 and 2035. Asia-Pacific leads with approximately a 60% share, while graphite materials dominate all other product categories with approximately a 42% share.

We observed that growth is broad-based across every segmentation axis, with battery anode material demand and synthetic graphite capacity expansion driving the dominant structural shifts through 2035.

Graphite Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $21.85 Billion
2025
2026 $23.94 Billion
2026
2027 $26.43 Billion
2027
2028 $29.18 Billion
2028
2029 $32.21 Billion
2029
2030 $35.56 Billion
2030
2031 $39.26 Billion
2031
2032 $43.34 Billion
2032
2033 $47.85 Billion
2033
2034 $52.83 Billion
2034
2035 $58.47 Billion
2035

Key Takeaways

By Product: Graphite Materials held the largest share with approximately 42% (USD 9.10 Billion) in 2025; Battery Anode Materials is the fastest-growing sub-segment at 16.1% CAGR from 2026-2035.

By Application: Batteries held the largest share with approximately 28% (USD 6.20 Billion) in 2025; Batteries is also the fastest-growing sub-segment at 15.5% CAGR from 2026-2035.

By Battery Anode Materials: Synthetic Graphite Anode Materials held the largest share with approximately 48% (USD 2.55 Billion) in 2025; Recycled Graphite Anode Materials is the fastest-growing sub-segment at 24.0% CAGR from 2026-2035.

Dominant Region: Asia-Pacific dominated with approximately 60% revenue share (USD 13.20 Billion) in 2025.

Fastest-Growing Region: Asia-Pacific is also the fastest-growing region at 11.7% CAGR from 2026-2035.

Dominant Country: China led with approximately USD 7.80 Billion in 2025, representing the largest single covered country within Asia-Pacific.

Fastest-Growing Country: India is the fastest-growing country within the fastest-growing region, Asia-Pacific, at approximately 13.5% CAGR from 2026-2035.

Market Opportunity: The graphite market is expected to create an incremental value opportunity of approximately USD 34.53 Billion between 2026 and 2035, representing a substantial addressable window for anode material producers, electrode manufacturers, and mine-to-material integrators investing in synthetic and natural graphite processing capacity.

According to NMSC analysis, brand and cell manufacturers are increasingly consolidating graphite sourcing with fewer, vertically integrated suppliers to reduce exposure to single-country mineral concentration, a shift that favors diversified producers over single-region specialists as critical mineral policy scrutiny intensifies through 2035.

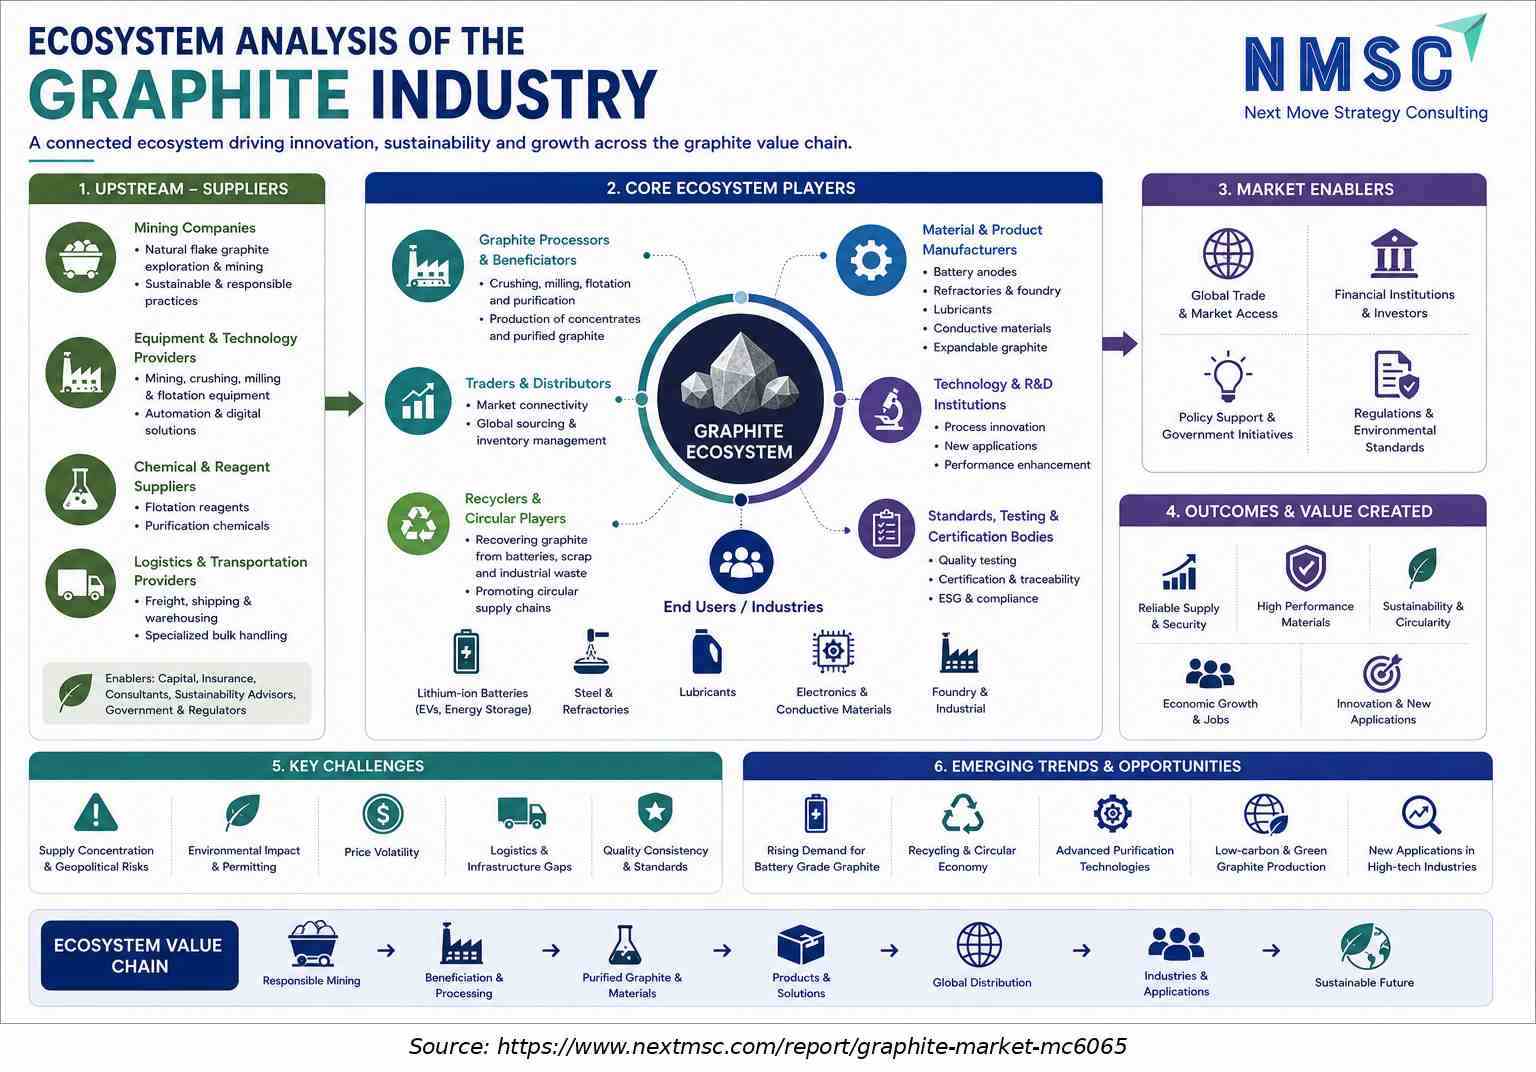
Ecosystem Analysis of the Graphite Industry

The infographic illustrates the graphite industry ecosystem by connecting mining companies, processors, equipment and chemical suppliers, traders, recyclers, manufacturers, technology institutions, and end-use industries. It also highlights the market enablers, value created across the ecosystem, major challenges, and emerging opportunities such as battery-grade demand, circularity, advanced purification, green production, and high-tech applications.

What Does the Graphite Market Encompass?

The graphite market encompasses the mining, purification, and synthetic manufacturing of carbon materials supplied as electrodes, battery anode materials, finished components, and flexible sealing products. Our assessment indicates that the scope spans flake, amorphous, vein, and synthetic graphite processed for battery, steel, foundry, semiconductor, solar, and industrial end markets. The category has evolved from a bulk industrial mineral into a strategically critical battery material, driven by electric vehicle adoption, energy storage deployment, and government critical minerals policy worldwide.

Regulatory frameworks such as the U.S. Inflation Reduction Act's critical mineral sourcing provisions and China's graphite export licensing regime shape supply chain localization decisions, while the European Union's Critical Raw Materials Act increasingly influences battery anode material sourcing diversification. We observed that technology adoption is shifting toward synthetic graphite and recycled anode material pathways that reduce dependence on natural flake graphite mining concentrated in China. NMSC's analysis indicates that this structural shift, combined with electric arc furnace steelmaking growth, is redefining sourcing criteria across the graphite market.

Market Drivers & Dynamics

Interactive Dataset
Rising demand for lithium-ion battery anode materials driver +3.1% Global 2026-2035
Global EV production and battery gigafactory expansion driver +2.4% North America, Europe, Asia-Pacific 2026-2035
Growth of electric arc furnace steelmaking capacity driver +1.5% Asia-Pacific, North America 2026-2035
China's graphite export licensing and mineral security policy driver +1.1% Global 2026-2032
Expansion of synthetic graphite capacity outside China driver +0.9% North America, Europe 2026-2035
Growing solar photovoltaic silicon processing demand driver +0.7% Asia-Pacific 2026-2035
Volatility in natural graphite mining supply concentration restraint -1.4% Global 2026-2035
High energy intensity and cost of synthetic graphitization restraint -0.9% Global 2026-2035
Stringent environmental permitting for new graphite mines restraint -0.6% North America, Europe 2026-2032
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Graphite Market?

Rising demand for lithium-ion battery anode materials is the primary driver of the market. The U.S. Department of Energy has issued critical minerals loans supporting domestic active anode material processing capacity, sustaining investment in graphite-based anode manufacturing for electric vehicle and energy storage batteries. We observed that this policy-backed demand, reinforced by battery gigafactory expansion across North America, Europe, and Asia-Pacific, continues to anchor consumption growth for both natural and synthetic graphite anode materials.

How Is Electric Arc Furnace Steelmaking Driving Market Growth?

Expansion of electric arc furnace steelmaking capacity is accelerating demand for ultra-high power graphite electrodes across developed and emerging steel markets. GrafTech International's annual filings report stated a production capacity of approximately 178 thousand metric tons across its Calais, Pamplona, and Monterrey facilities as of December 2025. Our assessment indicates that steelmakers' continued transition from blast furnace to electric arc furnace routes, particularly in the United States, is sustaining baseline graphite electrode consumption despite near-term pricing pressure.

Growth Inhibitors

What Is Restraining Graphite Market Expansion?

Volatility in natural graphite mining supply concentration, with a substantial share of global flake graphite production and processing based in China, restrains supply security and pricing stability across the value chain. Regulatory filings from graphite electrode producers describe persistent overcapacity and export-driven pricing pressure originating from Chinese producers. We found that smaller regional converters face particular exposure, as limited scale reduces their ability to hedge feedstock procurement compared with larger, vertically integrated graphite producers.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Graphite Materials 2025: $9.10 Billion | 2035: $18.30 Billion
Graphite Mat
Graphite Electrodes 2025: $5.20 Billion | 2035: $10.80 Billion
Graphite Ele
Battery Anode Materials 2025: $5.35 Billion | 2035: $22.50 Billion
Battery Anod
Finished Graphite Components 2025: $1.65 Billion | 2035: $4.90 Billion
Finished Gra
Flexible Graphite Materials 2025: $0.55 Billion | 2035: $1.97 Billion
Flexible Gra
Graphite Materials $9.10 Billion $18.30 Billion 7.0%
Graphite Electrodes $5.20 Billion $10.80 Billion 7.4%
Battery Anode Materials $5.35 Billion $22.50 Billion 16.1%
Finished Graphite Components $1.65 Billion $4.90 Billion 11.7%
Flexible Graphite Materials $0.55 Billion $1.97 Billion 14.1%

Which Product Segment Will Dominate the Market Through 2035?

Graphite Materials, encompassing flake, amorphous, vein, purified, and micronized forms, led the market with USD 9.10 billion in 2025, supported by broad consumption across electrodes, refractories, and lubricants. We observed that Battery Anode Materials are the fastest-growing product category, expanding at a 16.1% CAGR from 2026 to 2035, as electric vehicle and energy storage cell production scales globally and anode qualification programs accelerate across North America and Asia-Pacific.

2025 (USD Billion)
2035 (USD Billion)
Electric Veh
Consumer Ele
Energy Stora
Other Batter
Electric Arc
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Electric Vehicles $10.0 USD Billion $40.0 USD Billion 15.0%
Consumer Electronics $17.1 USD Billion $51.1 USD Billion 21.0%
Energy Storage $24.2 USD Billion $62.2 USD Billion 11.0%
Other Batteries $31.3 USD Billion $73.3 USD Billion 21.0%
Electric Arc Furnace Steelmaking $38.4 USD Billion $84.4 USD Billion 14.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data

Which Application Segment Will Drive Graphite Market Growth Through 2035?

Batteries remained the leading application within the market, valued at USD 6.20 billion in 2025 on sustained electric vehicle and consumer electronics cell production. Our findings suggest that Batteries are also the fastest-growing application, registering a 15.5% CAGR from 2026 to 2035, as energy storage deployment and electric vehicle penetration increasingly specify high-purity natural and synthetic anode-grade graphite to improve cell energy density and cycle life.

2025 (USD Billion)
2035 (USD Billion)
Natural Grap
Synthetic Gr
Blended Grap
Recycled Gra
Other Graphi
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Natural Graphite Anode Materials $10.0 USD Billion $40.0 USD Billion 27.0%
Synthetic Graphite Anode Materials $17.1 USD Billion $51.1 USD Billion 17.0%
Blended Graphite Anode Materials $24.2 USD Billion $62.2 USD Billion 19.0%
Recycled Graphite Anode Materials $31.3 USD Billion $73.3 USD Billion 21.0%
Other Graphite Anode Materials $38.4 USD Billion $84.4 USD Billion 26.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Battery Anode Materials.

Unlock Full Data

Which Battery Anode Material Segment Will Grow Fastest in the Market Through 2035?

Synthetic Graphite Anode Materials led the battery anode category, reaching USD 2.55 billion in 2025 due to their consistent purity, cycling performance, and qualification maturity with major cell manufacturers. Based on research conducted by NMSC, we found that Recycled Graphite Anode Materials represent the fastest-growing sub-segment at a 24.0% CAGR from 2026 to 2035, reflecting battery makers' efforts to meet recycled-content and carbon-footprint disclosure mandates across Europe and North America.

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the graphite market over the 2026-2035 forecast period.

How Can Domestic Anode Material Capacity Unlock Value for North American Cell Makers?

Domestic active anode material capacity presents a whitespace opportunity for North American battery cell manufacturers seeking to reduce foreign entity of concern exposure under critical mineral sourcing rules. Producers that scale qualified, IRA-compliant anode material capacity stand to capture long-term offtake agreements as automakers diversify supply away from single-country sourcing, particularly within the electric vehicle and energy storage battery segments.
Where Does Recycled Graphite Anode Material Create New Demand?

Battery recyclers and cell manufacturers represent an underpenetrated opportunity for closed-loop recycled graphite anode material recovery. Companies that develop validated, high-purity recycled anode processes can secure long-term procurement contracts with battery makers pursuing recycled-content and carbon-disclosure compliance, benefiting from recurring feedstock supply tied to end-of-life battery recovery programs.

How Can Synthetic Graphite Capacity Diversification Benefit Steel and Semiconductor Buyers?

Steel producers and semiconductor component buyers seeking supply diversification create an opportunity for synthetic graphite manufacturers expanding capacity outside traditional production hubs. Early movers that secure needle coke feedstock integration and regional graphitization capacity can differentiate with electric arc furnace steelmakers and semiconductor equipment makers pursuing supply chain resilience across their procurement portfolios.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the graphite market features a moderately consolidated competitive landscape, with vertically integrated Chinese battery material producers competing alongside established electrode and specialty graphite manufacturers on scale, purity, and sustainability credentials.

Dimension Description
Market Structure Moderately consolidated; the top companies profiled in this report collectively account for a majority of global graphite market revenue, while numerous regional Asia-Pacific producers serve cost-sensitive electrode and materials demand.
Innovation Focus Synthetic graphite capacity expansion, recycled anode material recovery, and vertically integrated mine-to-material processing dominate current innovation pipelines across leading suppliers.
M&A Activity Selective consolidation through equity stakes and offtake partnerships, exemplified by Graphite India Limited's acquisition of a stake in GrafTech International to broaden global electrode manufacturing access.

How Do Companies Compete in the Graphite Market?

Companies compete primarily on purity credentials, feedstock integration, and manufacturing scale across the industry. Global players such as SGL Carbon SE and Tokai Carbon Co., Ltd. leverage broad electrode and specialty graphite portfolios to serve multinational steel and semiconductor buyers, while Chinese anode material producers such as BTR New Material Group Co., Ltd. and Ningbo Shanshan Co., Ltd. compete on scale and cost efficiency for battery-grade material.

Which Competitive Archetypes Dominate the Graphite Market?

Two archetypes dominate the market: vertically integrated battery anode material producers offering mine-to-material processing, and specialized electrode and industrial graphite manufacturers focused on steel and semiconductor supply chains. Shanghai Putailai New Energy Technology Co., Ltd. and POSCO Future M Co., Ltd. exemplify the integrated battery-materials archetype, while GrafTech International Ltd. and HEG Limited exemplify the electrode-focused cost-leadership archetype serving electric arc furnace demand.

How Are Companies Differentiating Through Innovation in Graphite?

Innovation and differentiation strategy increasingly center on synthetic graphite scale-up and recycled-content validation. Syrah Resources Limited's Vidalia, Louisiana facility and Resonac Corporation's capacity realignment both target qualification-ready, IRA-aligned anode material supply. Our analysis shows that suppliers unable to demonstrate credible traceability and purity pathways risk exclusion from cell manufacturer qualification shortlists in North America and Europe.

What M&A and Expansion Activity Is Shaping the Graphite Market?

Mergers, acquisitions, and geographic expansion continue to consolidate graphite capabilities within the industry. Graphite India Limited's equity investment in GrafTech International in September 2025 broadened its access to global electrode manufacturing and distribution, while Resonac Corporation's decision to close legacy graphite electrode plants in China and Malaysia illustrates how diversified groups are reallocating capital toward higher-value synthetic anode material production.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping product innovation, capacity expansion, and sustainability strategy within the global graphite industry.

BTR New Material Group Co., Ltd. Ningbo Shanshan Co., Ltd. Shanghai Putailai New Energy Technology Co., Ltd. Fangda Carbon New Material Co., Ltd. SGL Carbon SE Resonac Corporation GrafTech International Ltd. Tokai Carbon Co., Ltd. POSCO Future M Co., Ltd. Graphite India Limited HEG Limited Imerys S.A. Mersen SA Toyo Tanso Co., Ltd. SEC Carbon, Limited Nippon Carbon Co., Ltd. Nacional de Grafite Ltda. Syrah Resources Limited Asbury Carbons, Inc. EL 6 LLC

Latest Developments

We found that recent capacity and supply agreement developments within the graphite market are concentrated on battery anode material qualification and electrode capacity realignment, reflecting the industry's broader battery-driven transition.

Date Event
August 2026 SGL Carbon and X-energy agreed to expand manufacturing capacity for medium-grain isotropic graphite used in X-energy’s advanced nuclear reactors. The program includes increased European graphite billet production and additional U.S. machining capacity, supported by milestone payments of up to USD 8 million.
August 2026 Resonac Graphite signed a graphite-electrode bundle agreement with Tosyalı Holding, strengthening its supply relationship with the steel producer. The agreement covers graphite electrodes used in electric-arc-furnace steelmaking, directly expanding Resonac’s commercial graphite-electrode business in the European and Turkish steel markets.
April 2026 Resonac Graphite secured a graphite-electrode bundle contract with Soma Steel in EMEA. The agreement strengthens Resonac’s supply position with an electric-arc-furnace steel producer and expands its graphite-electrode customer base in the European, Middle Eastern and African steel markets.
October 2025 Asbury Carbons signed an agreement to acquire Graphit Kropfmühl GmbH, a German graphite producer and processor. The transaction expanded Asbury’s graphite portfolio and European capabilities.
September 2025 Imerys Graphite & Carbon and Shanghai Shanshan established a partnership to supply synthetic graphite anode materials to Europe’s battery market. The collaboration combines Imerys’ graphite expertise and European industrial presence with Shanshan’s battery-anode capabilities to develop regional graphite-anode supply.

Expert Insights

Anthony Huston

Anthony Huston

CEO | Graphite One Inc.

"Graphite One is not developing a single project. We are building an integrated U.S. graphite platform designed to connect America's largest known graphite resource with domestic advanced anode materials manufacturing and, ultimately, recycling."

Analyst Interpretation

Huston's statement underscores the graphite industry's transition toward integrated, end-to-end supply chains, extending from mining and processing to advanced anode material manufacturing and recycling. The emphasis on domestic integration reflects increasing efforts to strengthen supply security and reduce reliance on geographically concentrated graphite processing capacity. For the graphite market, this development is expanding investment opportunities across graphite mining, purification, anode material production, and recycling, supported by rising demand for secure, traceable, and diversified sources of battery-grade graphite.

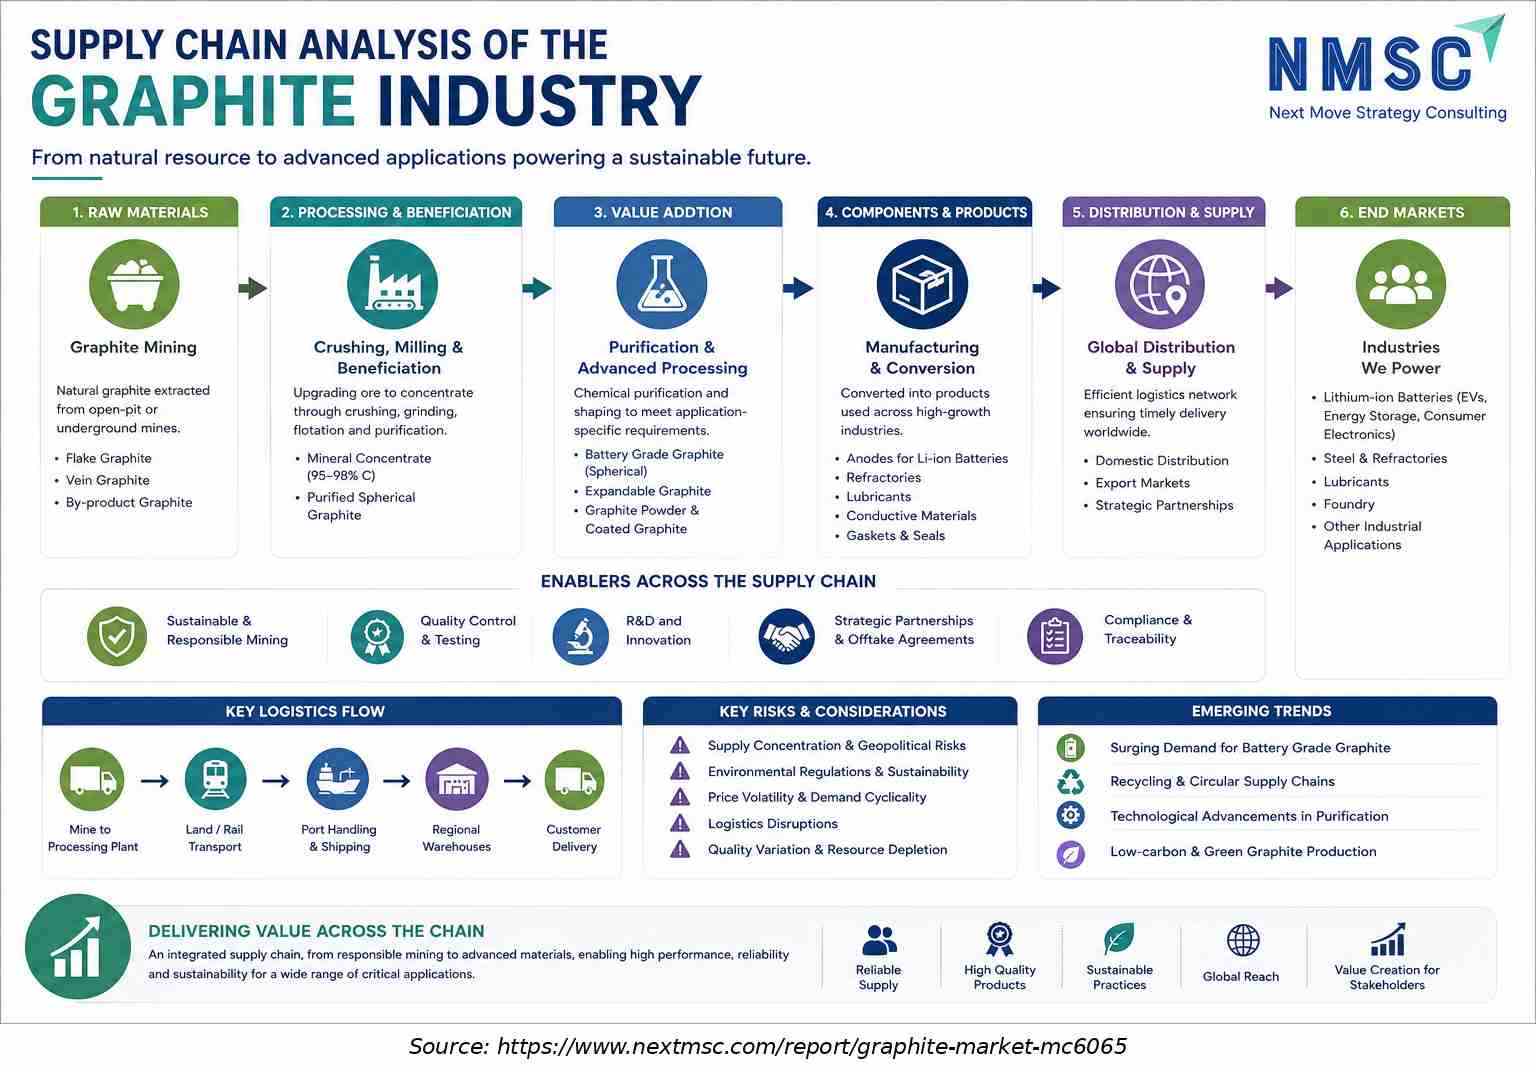
Supply Chain Analysis of the Graphite Industry

Supply Chain Analysis of the Graphite Industry
The infographic maps the graphite industry’s supply chain from mining and raw material sourcing through processing, grading, downstream applications, distribution, and end markets. It highlights the main supply chain drivers, operational challenges, geographic diversification, technology needs, and emerging opportunities while showing how sustainable sourcing, capacity expansion, value addition, and strategic partnerships can strengthen resilience.

Investment Opportunities

What Capital Inflows Are Targeting the Graphite Market?

Capital inflows into the graphite market are increasingly directed toward battery anode material qualification and synthetic graphite capacity upgrades. The U.S. Department of Energy's Loan Programs Office has extended critical minerals financing to domestic anode material processors, reinforcing federal policy support for supply chain localization. We observed that investors favor suppliers demonstrating validated purity and traceability credentials, viewing regulatory alignment as a proxy for long-term contract retention with battery cell manufacturers.

How Is Infrastructure Investment Supporting Graphite Manufacturing?

Infrastructure investment is expanding purification, graphitization, and active anode material processing capacity across North America and Asia-Pacific to serve rising battery and steel demand. Our findings suggest that producers are investing in automated qualification and testing infrastructure to meet the dimensional and purity consistency required for high-nickel and high-energy-density battery cell formats.

What ESG Considerations Are Shaping Graphite Investment Decisions?

Environmental, social, and governance considerations are central to investment decisions across the industry, with recycled anode material sourcing and reduced carbon-intensity processing as key criteria. The U.S. Environmental Protection Agency's critical minerals recycling initiatives continue to inform battery maker sustainability disclosures. We found that investors increasingly favor manufacturers with third-party traceability certification, treating it as a governance indicator alongside labor and safety compliance.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and product-portfolio decisions across the graphite industry. Our analysis shows that detailed product, application, and battery anode material breakdowns help procurement teams align specifications with qualification and sustainability requirements while identifying underserved application segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the graphite market supply chain. We observed that the report's regional and segment-level growth differentials help identify which producers and anode material suppliers are best positioned to capture above-market growth in battery and synthetic graphite categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design and processing requirements, including synthetic graphite engineering, recycled anode recovery, and traceability systems, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around purity certification and qualification protocols increasingly required by cell manufacturer procurement processes.

Key Market Segments Evaluated

By Product

  • Graphite Materials
  • Flake Graphite
  • Amorphous Graphite
  • Vein Graphite
  • Graphite Powder
  • Graphite Granules
  • Graphite Blocks
  • Graphite Blanks
  • Micronized Graphite
  • Expandable Graphite
  • Purified Graphite
  • Recycled Graphite Materials
  • Other Graphite Materials
  • Graphite Electrodes
  • Battery Anode Materials
  • Natural Graphite Anode Materials
  • Synthetic Graphite Anode Materials
  • Blended Graphite Anode Materials
  • Recycled Graphite Anode Materials
  • Other Graphite Anode Materials
  • Finished Graphite Components
  • Semiconductor and Solar Components
  • Thermal Process Components
  • Metallurgical Components
  • Mechanical Components
  • Chemical Process Components
  • EDM Components
  • Sealing Components
  • Flexible Graphite Materials

By Application

  • Batteries
  • Electric Vehicles
  • Consumer Electronics
  • Energy Storage
  • Other Batteries
  • Iron and Steel
  • Electric Arc Furnace Steelmaking
  • Ladle Metallurgy
  • Other Steel Applications
  • Foundry and Metallurgy
  • Foundry
  • Ferroalloys
  • Recarburizing
  • Non-Ferrous Metallurgy
  • Semiconductor and Electronics
  • Semiconductor Manufacturing
  • LED Manufacturing
  • Other Electronics
  • Solar
  • Silicon Processing
  • Solar Cell Manufacturing
  • Chemical Processing
  • Industrial Manufacturing
  • Heat Treatment
  • Sintering
  • Industrial Furnaces
  • Friction and Lubrication
  • Aerospace and Defense
  • Other Industrial Applications

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook for the market remains positive, with global revenue projected to more than double from USD 21.85 billion in 2025 to USD 58.47 billion by 2035 at a 10.4% CAGR. We observed that sustained battery cell manufacturing growth, critical minerals policy support, and synthetic graphite capacity expansion will continue underpinning demand across battery, steel, and industrial applications through the forecast period.

What Strategic Positioning Should Graphite Suppliers Pursue?

Suppliers should prioritize synthetic graphite and recycled anode material platforms while pursuing regional qualification with battery cell manufacturers to secure long-term offtake contracts. Our assessment indicates that producers investing early in vertically integrated, traceable processing capability will be best positioned to capture premium pricing within the graphite market.

How Attractive Is the Graphite Market for New Investment?

The graphite industry presents an attractive investment case, supported by a USD 34.53 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and battery anode material categories. We found that investment attractiveness is highest for producers combining traceability credentials with scaled processing capacity, positioning them to serve both cost-sensitive industrial and premium battery segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor natural graphite supply concentration, tightening critical minerals export policy, and competitive pressure from alternative anode chemistries as key risks to the market. Our analysis shows that suppliers unable to adapt to synthetic and recycled-content specifications risk losing qualification slots to competitors with certified, traceable production platforms, particularly within North America's increasingly policy-driven battery supply chain.

What Are the Key Growth Pathways for the Graphite Market?

Key growth pathways include expanding synthetic graphite and recycled anode material capacity, scaling domestic battery-grade processing, and deepening penetration into semiconductor and solar silicon processing channels. NMSC's analysis indicates that suppliers pursuing these pathways while maintaining cost competitiveness in electrode and industrial graphite categories will be best positioned to capture the market's projected growth through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Country-Level Graphite Trade Assessment
  • Country-wise import and export analysis of natural flake, synthetic, and spherical graphite, including anode-grade material flows.
  • Reveals sourcing dependencies, trade corridors, and supplier diversification options.
Historical Graphite Market Growth Analysis
  • Historical sales volume and revenue analysis across natural and synthetic graphite products and key applications.
  • Identifies high-growth product-application pairs and supports demand planning.
Company-Level Graphite Sales Volume Analysis
  • Company-level graphite production and sales volume benchmarking by product type for leading producers.
  • Highlights producer scale and share differences to guide partnership and competitive positioning.
Battery Anode Material Supply-Demand Assessment
  • Supply-demand balance for natural, synthetic, and silicon-blended anode materials, linked to battery capacity growth and cell-maker requirements.
  • Pinpoints anode supply gaps and capacity investment timing.
Natural vs Synthetic Graphite Cost and Pricing Benchmarking
  • Price and cost-structure benchmarking by graphite grade, purity, and form, covering energy, feedstock, and purification inputs.

  • Supports procurement strategy, pricing decisions, and make-or-buy choices.

Graphite Export Control and Localization Impact Assessment
  • Mapping of export controls, tariffs, and domestic-content policies on graphite and anode supply chains by key producing and consuming country.

  • Supports supply risk mitigation and localization or new-capacity siting decisions.

FAQs

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖