Industrial Automation Services Market Global Industry Analysis and Forecast (2026-2035)

Industrial automation services market size is estimated at USD 288.89 billion in 2026, projected to reach USD 586.56 billion by 2035, growing at a CAGR of 8.19% from 2026 to 2035. Key drivers include brownfield modernization demand, expanding managed operational technology cybersecurity adoption, and system integrator capacity growth, with Asia-Pacific leading the market and Middle East & Africa registering the fastest growth.

Download Free Sample PDF
Base Year (2025)
$255.82 Billion
Forecast (2035)
$586.56 Billion
CAGR (2026-2035)
8.2%
Top Region
Asia-Pacific

What Is the Industrial Automation Services Market Size?

The global industrial automation services market size was valued at USD 255.82 billion in 2025 and is estimated at USD 288.89 billion in 2026, forecast to reach USD 586.56 billion by 2035, expanding at an 8.19% CAGR between 2026 and 2035. Asia-Pacific leads with approximately 34% share, while Project Engineering and Implementation dominates all other service types with approximately 42% share.

We observed that growth is broad-based across every segmentation axis, with managed operations and automation software services driving the most pronounced structural shifts through 2035.

Industrial Automation Services Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $255.82 Billion
2025
2026 $288.89 Billion
2026
2027 $312.55 Billion
2027
2028 $338.15 Billion
2028
2029 $365.84 Billion
2029
2030 $395.80 Billion
2030
2031 $428.22 Billion
2031
2032 $463.29 Billion
2032
2033 $501.24 Billion
2033
2034 $542.29 Billion
2034
2035 $586.56 Billion
2035

Key Takeaways

By Service Type: Project Engineering and Implementation held the largest share of approximately 42% (USD 107.44 billion) in 2025; Managed Operations is the fastest-growing segment at a 16.1% CAGR from 2026–2035.

By Technology: Programmable Logic Controllers held the largest share of approximately 22% (USD 56.28 billion) in 2025; Automation Software is the fastest-growing segment at a 17.1% CAGR from 2026–2035.

By End User Industry: General Manufacturing held the largest share of approximately 18% (USD 46.05 billion) in 2025; Electronics and Semiconductors is the fastest-growing segment at a 13.6% CAGR from 2026–2035.

By Contracting Buyer: End User Operator held the largest share of approximately 48% (USD 122.79 billion) in 2025; System Integrator and Automation Contractor is the fastest-growing segment at a 10.8% CAGR from 2026–2035.

By Delivery Channel: Direct Delivery held the largest share of approximately 54% (USD 138.14 billion) in 2025; Partner Delivered is the fastest-growing segment at a 9.6% CAGR from 2026–2035.

Dominant Region: Asia-Pacific dominated the market with approximately 34% revenue share (USD 86.98 billion) in 2025.

Fastest-Growing Region: Middle East & Africa is expected to register the highest CAGR of 15.8% from 2026–2035.

Dominant Country: China held the largest country-level market size at approximately USD 38.50 billion in 2025.

Fastest-Growing Country: Saudi Arabia is expected to register the highest country-level CAGR of approximately 12.2% from 2026–2035.

What Does the Industrial Automation Services Market Encompass?

The industrial automation services market encompasses consulting, engineering, integration, maintenance, and managed operations services. These solutions design, implement, and sustain automation and control systems across process and discrete manufacturing industries. Our assessment indicates that the scope spans distributed control systems, programmable logic controllers, SCADA, robotics, and automation software technologies delivered to end user operators, OEMs, and engineering contractors worldwide. The category has evolved from discrete, project-based engineering work into an increasingly recurring, outcome-based service model, driven by aging installed base modernization needs and rising operational technology cybersecurity exposure.
We observed that industrial cybersecurity regulatory frameworks increasingly shape managed operational technology service requirements, while functional safety standards inform control system engineering practices. NMSC's analysis indicates that technology adoption is shifting toward remote supervision, predictive maintenance, and automation software platforms. This structural shift extends service relationships beyond initial commissioning and redefines sourcing criteria across the market.

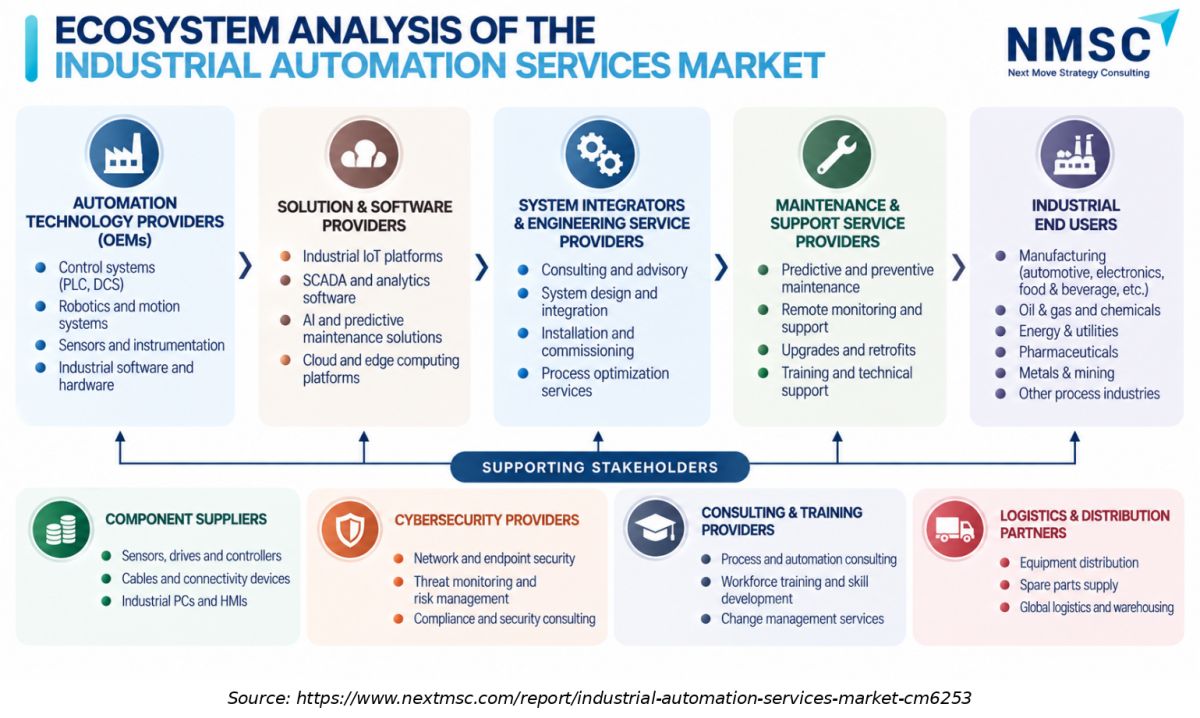
Ecosystem Analysis of the Industrial Automation Services Market
This infographic presents the Ecosystem Analysis of the Industrial Automation Services Market, highlighting automation technology providers, solution and software providers, system integrators and engineering service providers, maintenance and support providers, and industrial end users. It also includes supporting stakeholders such as component suppliers, cybersecurity providers, consulting and training firms, and logistics and distribution partners that enable automation deployment and ongoing operations.

Market Drivers & Dynamics

Interactive Dataset
Aging installed base driving brownfield modernization demand driver +1.9% North America, Europe 2026–2035
Rising managed operational technology cybersecurity adoption driver +1.6% Global 2026–2032
Expanding Middle East industrial diversification investment driver +1.3% Middle East & Africa 2026–2032
Growing automation software and analytics integration demand driver +1.1% North America, Asia-Pacific 2026–2032
Rising electronics and semiconductor manufacturing capacity investment driver +0.9% Asia-Pacific 2026–2035
Expanding system integrator and automation contractor capacity driver +0.7% Global 2026–2035
Skilled automation engineering workforce shortages restraint −0.8% North America, Europe 2026–2032
High capital cost sensitivity delaying modernization projects restraint −0.6% Latin America, Asia-Pacific 2026–2032
Cybersecurity compliance complexity across legacy control systems restraint −0.4% Global 2026–2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Industrial Automation Services Market?

Aging installed base driving brownfield modernization demand is the primary driver of the market. The U.S. Department of Energy continues to publish industrial energy efficiency guidance that encourages manufacturers to modernize control systems alongside broader facility upgrades. We observed that this modernization trajectory, reinforced by rising managed cybersecurity adoption, continues to anchor demand for industrial automation services across developed and emerging manufacturing hubs alike.

How Is Operational Technology Cybersecurity Driving Industrial Automation Services Market Growth?

Rising managed operational technology cybersecurity adoption is accelerating growth in recurring service categories. The U.S. Cybersecurity and Infrastructure Security Agency continues to publish guidance urging critical infrastructure operators to strengthen operational technology network monitoring and incident response capability. Our assessment indicates that this regulatory and advisory pathway is compressing adoption timelines for managed cybersecurity services across oil and gas, power, and water utility operators.

Growth Inhibitors

What Is Restraining Industrial Automation Services Market Expansion?
Skilled automation engineering workforce shortages restrain market expansion, particularly among system integrators serving multiple simultaneous modernization projects. National labor statistics agencies report persistent shortages in specialized industrial engineering occupations relative to manufacturing sector demand. Service providers lacking structured training pipelines face operational bottlenecks, as persistent shortages of qualified automation engineers extend project delivery timelines.

What Are the Growth Opportunities?

How Can Managed Cybersecurity Bundles Unlock Value for Utility Operators?

Managed operational technology cybersecurity bundles present a whitespace opportunity for service providers serving power, water, and wastewater utility operators facing tightening critical infrastructure security expectations. Providers that commercialize bundled remote monitoring and cybersecurity services stand to capture recurring contracts as utilities seek continuous operational technology network visibility.

Where Does Semiconductor Fabrication Automation Create New Demand?

Semiconductor fabrication automation engineering represents an underpenetrated opportunity for system integrators targeting electronics manufacturers scaling new fabrication capacity. Providers that package specialized cleanroom automation and robotics integration expertise can secure long-term facility commissioning contracts, benefiting from recurring maintenance revenue tied to expanding global fabrication investment.

How Can Workforce Training-as-a-Service Benefit Mid-Size Manufacturers?

Workforce training-as-a-service creates an opportunity for providers serving mid-size manufacturers unable to maintain large internal automation engineering teams. Early movers that bundle operator training, competency assessment, and engineering support into subscription-based offerings can differentiate ahead of broader workforce development investment through 2035.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Consulting and Advisory 2025: $46.05 Billion | 2035: $93.85 Billion
Consulting a
Project Engineering and Implementation 2025: $107.44 Billion | 2035: $222.89 Billion
Project Engi
Maintenance and Support 2025: $71.63 Billion | 2035: $152.51 Billion
Maintenance
Managed Operations 2025: $30.70 Billion | 2035: $117.31 Billion
Managed Oper
Consulting and Advisory $46.05 Billion $93.85 Billion 7.3%
Project Engineering and Implementation $107.44 Billion $222.89 Billion 7.5%
Maintenance and Support $71.63 Billion $152.51 Billion 7.8%
Managed Operations $30.70 Billion $117.31 Billion 16.1%

Which Service Type Dominates the Industrial Automation Services Market?

Project Engineering and Implementation led the market with USD 107.44 billion in 2025, supported by sustained capital project activity across system integration and control system migration work. We observed that Managed Operations is the fastest-growing service type, expanding at a 16.1% CAGR from 2026 to 2035, as operators increasingly outsource remote supervision, managed infrastructure, and managed cybersecurity responsibilities to specialized service providers.

2025 (USD Billion)
2035 (USD Billion)
Distributed
Programmable
SCADA and HM
Robotics and
Instrumentat
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Distributed Control Systems $10.0 USD Billion $40.0 USD Billion 25.0%
Programmable Logic Controllers $17.1 USD Billion $51.1 USD Billion 11.0%
SCADA and HMI $24.2 USD Billion $62.2 USD Billion 25.0%
Robotics and Motion Control $31.3 USD Billion $73.3 USD Billion 11.0%
Instrumentation and Measurement $38.4 USD Billion $84.4 USD Billion 16.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Technology.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Oil and Gas
Chemicals
Pharmaceutic
Food and Bev
Mining and M
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Oil and Gas $10.0 USD Billion $40.0 USD Billion 27.0%
Chemicals $17.1 USD Billion $51.1 USD Billion 9.0%
Pharmaceuticals and Life Sciences $24.2 USD Billion $62.2 USD Billion 19.0%
Food and Beverage $31.3 USD Billion $73.3 USD Billion 17.0%
Mining and Metals $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User Industry.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
End User Ope
OEM and Mach
EPC and Engi
System Integ
Other Contra
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
End User Operator $10.0 USD Billion $40.0 USD Billion 14.0%
OEM and Machine Builder $17.1 USD Billion $51.1 USD Billion 24.0%
EPC and Engineering Contractor $24.2 USD Billion $62.2 USD Billion 22.0%
System Integrator and Automation Contractor $31.3 USD Billion $73.3 USD Billion 12.0%
Other Contracting Buyers $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Contracting Buyer.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct Deliv
Partner Deli
Hybrid Deliv
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Delivery $10.0 USD Billion $40.0 USD Billion 24.0%
Partner Delivered $17.1 USD Billion $51.1 USD Billion 22.0%
Hybrid Delivery $24.2 USD Billion $62.2 USD Billion 20.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Delivery Channel.

Unlock Full Data

Growth Opportunities

Three forward-looking whitespace opportunities stand out for suppliers positioning ahead of 2035 demand across the market.

How Can Managed Cybersecurity Bundles Unlock Value for Utility Operators?

Managed operational technology cybersecurity bundles present a whitespace opportunity for service providers serving power, water, and wastewater utility operators facing tightening critical infrastructure security expectations. Providers that commercialize bundled remote monitoring and cybersecurity services stand to capture recurring contracts as utilities seek continuous operational technology network visibility.

Where Does Semiconductor Fabrication Automation Create New Demand?

Semiconductor fabrication automation engineering represents an underpenetrated opportunity for system integrators targeting electronics manufacturers scaling new fabrication capacity. Providers that package specialized cleanroom automation and robotics integration expertise can secure long-term facility commissioning contracts, benefiting from recurring maintenance revenue tied to expanding global fabrication investment.

How Can Workforce Training-as-a-Service Benefit Mid-Size Manufacturers?

Workforce training-as-a-service creates an opportunity for providers serving mid-size manufacturers unable to maintain large internal automation engineering teams. Early movers that bundle operator training, competency assessment, and engineering support into subscription-based offerings can differentiate ahead of broader workforce development investment through 2035.

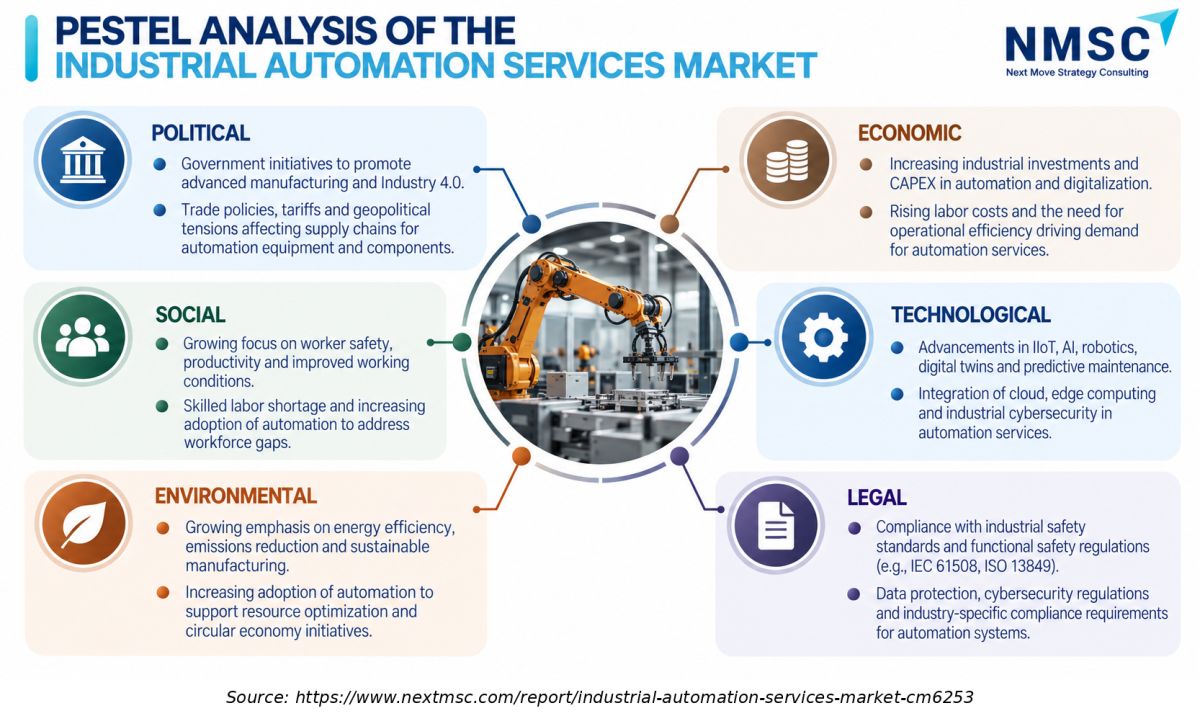
PESTEL Analysis of the Industrial Automation Services Market

PESTEL Analysis of the Industrial Automation Services Market

This infographic presents the PESTEL Analysis of the Industrial Automation Services Market, covering political, economic, social, technological, environmental, and legal factors. It highlights the influence of Industry 4.0 initiatives, industrial investment, labor costs and workforce availability, AI and robotics, IIoT and digital twins, energy efficiency, emissions reduction, functional safety, cybersecurity, and industry-specific compliance requirements on market development.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the market features a moderately consolidated competitive landscape, with established global automation majors competing alongside specialized robotics and instrumentation providers on service breadth, technology depth, and installed base reach.

Dimension Description
Dimension Assessment
Market Structure Moderately consolidated; leading companies profiled in this report account for a substantial share of Industry revenue, while numerous regional system integrators serve fragmented project-based demand.
Innovation Focus Managed operational technology cybersecurity, remote supervision, and automation software integration dominate current innovation pipelines across leading providers.
M&A Activity Selective consolidation through service capability acquisition, exemplified by continued automation vendor investment in managed services and cybersecurity-focused service units.

How Do Companies Compete in the Industrial Automation Services Market?

Companies compete primarily on service breadth, technology depth, and installed base reach across the Industry. Established vendors such as Siemens AG and Schneider Electric SE leverage decades of installed control system relationships in mature North American and European markets. Meanwhile, diversified automation majors such as ABB Ltd and Emerson Electric Co. compete on cross-portfolio integration across process and discrete manufacturing sectors.

Which Competitive Archetypes Dominate the Industrial Automation Services Industry?

Two archetypes dominate the Industry: established global automation majors with decades of installed base relationships and broad service portfolios, and specialized robotics and instrumentation providers offering deep technical expertise in specific technology categories. Siemens AG and Rockwell Automation exemplify the full-portfolio archetype, while FANUC Corporation and Endress+Hauser Group Services AG exemplify the specialized technology archetype.

How Are Companies Differentiating Through Innovation in Industrial Automation Services?

Innovation and differentiation strategy increasingly center on managed operations and software-enabled service delivery. Rockwell Automation's remote monitoring and diagnostics platform and Honeywell Technologies' managed cybersecurity services both demonstrate how providers differentiate through recurring, outcome-based service models. Our analysis shows that providers unable to demonstrate credible managed service capability risk exclusion from long-term operator procurement shortlists.

What M&A and Expansion Activity Is Shaping the Industrial Automation Services Market?

Strategic service capability expansion, software integration, and geographic expansion continue to shape capabilities within the Industry. Leading automation vendors continue to invest in managed cybersecurity and remote supervision units. This strategy allows established providers to rapidly scale capabilities and meet rising demand for recurring, software-enabled service engagements.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping service delivery innovation, technology integration, and geographic expansion within the global industrial automation services market.

Siemens AG Schneider Electric SE ABB Ltd Emerson Electric Co. Rockwell Automation, Inc. Honeywell Technologies Yokogawa Electric Corporation Mitsubishi Electric Corporation FANUC Corporation KUKA SE & Co. KGaA OMRON Corporation Yaskawa Electric Corporation Fuji Electric Co., Ltd. Bosch Rexroth AG Endress+Hauser Group Services AG Hitachi, Ltd. GE Vernova Inc. Phoenix Contact GmbH & Co. KG Beckhoff Automation GmbH & Co. KG Delta Electronics, Inc.

Latest Developments

We found that recent developments within the industrial automation services market are concentrated on managed service launches and cybersecurity capability expansion, reflecting the industry's broader recurring-revenue transition.

Date Event
August 2026 ABB and Vale formed a strategic alliance to expand advanced automation, AI, digitalization, and integrated IT/OT solutions across Vale’s iron ore operations in Brazil. Having previously served as systems integrator at Conceição II, ABB created a proven blueprint for replicating plant-wide automation modernization.
July 2026 Performance with Agentic AI — Rockwell Automation and Augury announced a strategic technology and go-to-market partnership combining Augury’s Industrial AI Workforce with Rockwell’s Fiix CMMS and FactoryTalk Optix.

Expert Insights

Matt Fordenwalt

Matt Fordenwalt

Senior Vice President, Lifecycle Services | Rockwell Automation

"“The lifecycle services segment is a dramatically different business than it was 10 years ago. We now have cyber. We have digital services, AI-driven solutions.”"

Analyst Interpretation

The statement highlights the transformation of the Industrial Automation Services Market from traditional maintenance and support toward digitally enabled lifecycle services. Industrial customers increasingly require cybersecurity, digital transformation, AI-enabled solutions and continuous technical support in addition to conventional automation maintenance. This evolution is expanding service providers' role across the entire automation lifecycle and creating opportunities for remote support, predictive services, cybersecurity, digital engineering and AI-enabled optimization.

Market Interpretation:

The statement highlights the transformation of the Industrial Automation Services Market from traditional maintenance and support toward digitally enabled lifecycle services. Industrial customers increasingly require cybersecurity, digital transformation, AI-enabled solutions and continuous technical support in addition to conventional automation maintenance. This evolution is expanding service providers' role across the entire automation lifecycle and creating opportunities for remote support, predictive services, cybersecurity, digital engineering and AI-enabled optimization.
Investment Opportunities

What Capital Inflows Are Targeting the Industrial Automation Services Market?

Capital inflows into the industrial automation services market are increasingly directed toward managed operations and cybersecurity service capability development. We observed that strategic investors continue to fund service portfolio expansion, as seen in continued automation vendor investment in remote monitoring and managed infrastructure offerings. Investors favor providers demonstrating validated recurring-revenue service credentials, viewing long-term operator contracts as a proxy for sustainable market access.

How Is Infrastructure Investment Supporting Industrial Automation Services Delivery?

Infrastructure investment is expanding regional engineering and remote operations center capacity to serve rising brownfield modernization and managed service demand. Our findings suggest that providers are scaling regional delivery hubs to improve responsiveness for system integration and managed operations contracts across Asia-Pacific and Middle East & Africa markets.

What ESG Considerations Are Shaping Industrial Automation Services Investment Decisions?

Environmental, social, and governance considerations are increasingly central to investment decisions across the Industry, with energy optimization services and workforce safety training as key criteria. We found that investors increasingly favor providers demonstrating measurable improvements in client facility energy efficiency, treating it as a governance indicator alongside operational technology cybersecurity compliance.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and vendor-selection decisions across the industrial automation services Industry. Our analysis shows that detailed service type, technology, and end user industry breakdowns help procurement teams align specifications with modernization and cybersecurity requirements while identifying underserved contracting buyer and delivery channel segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the industrial automation services supply chain. We observed that the report's regional and segment-level growth differentials help identify which providers are best positioned to capture above-market growth in managed operations and Middle East & Africa categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including managed cybersecurity and automation software integration, that are reshaping the Industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around remote supervision and predictive maintenance capability increasingly required by operator procurement processes.

Key Market Segments Evaluated

By Service Type

  • Consulting and Advisory 
    • Strategy and Architecture
      • Automation Strategy
      • Automation Architecture
      • Control Strategy
      • Operational Technology Architecture
    • Optimization and Reliability
      • Process Optimization
      • Reliability Optimization
      • Energy Optimization
    • Training and Workforce Development
      • Operator Training
      • Engineering Training
      • Competency Assessment
  • Project Engineering and Implementation 
    • Automation Engineering
      • Detailed Automation Engineering
      • Control System Configuration
      • Panel and Cabinet Engineering
    • System Integration
      • PLC and PAC Integration
      • DCS Integration
      • SCADA and HMI Integration
      • Robotics and Motion Integration
      • Industrial Network Integration
    • Installation, Testing and Commissioning
    • Modernization and Migration
      • Control System Migration
      • Obsolescence Replacement
      • Brownfield Retrofit
  • Maintenance and Support 
    • Preventive and Predictive Maintenance
    • Corrective Repair and Refurbishment
    • Technical Support
    • Service Parts and Logistics
      • Spare Parts Management
      • Service Inventory Management
      • Expedited Replacement
  • Managed Operations 
    • Remote Supervision and Diagnostics
    • Managed Automation Infrastructure
    • Managed Operational Technology Cybersecurity
    • Managed Performance and Operations

By Technology

  • Distributed Control Systems
  • Programmable Logic Controllers
  • SCADA and HMI
  • Robotics and Motion Control
  • Instrumentation and Measurement
  • Industrial Networking
  • Functional Safety
  • Automation Software
  • Other Automation Technologies

By End User Industry

  • Oil and Gas
  • Chemicals
  • Pharmaceuticals and Life Sciences
  • Food and Beverage
  • Mining and Metals
  • Power and Utilities
  • Water and Wastewater
  • Automotive
  • Electronics and Semiconductors
  • Aerospace and Defense
  • Industrial Machinery
  • Logistics and Transportation
  • General Manufacturing
  • Other Industrial Applications

By Contracting Buyer

  • End User Operator
  • OEM and Machine Builder
  • EPC and Engineering Contractor
  • System Integrator and Automation Contractor
  • Other Contracting Buyers

By Delivery Channel

  • Direct Delivery
  • Partner Delivered
  • Hybrid Delivery

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico.
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe.
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC.
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA.
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM.

Conclusion & Recommendations

The long-term outlook for the industrial automation services market remains highly positive, supported by a USD 297.67 billion absolute dollar opportunity between 2026 and 2035 and sustained modernization momentum. NMSC's analysis indicates that providers combining managed operations with automation software integration will be best positioned to capture the market's projected growth from USD 288.89 billion in 2026 to USD 586.56 billion by 2035.

What Strategic Positioning Should Suppliers Pursue in the Industrial Automation Services Market?

Suppliers should prioritize recurring, outcome-based service models to secure long-term access to operator procurement channels. Providers investing early in managed cybersecurity, remote supervision, and expanded partner delivery networks will secure strong competitive positioning. These capabilities enable service providers to command premium pricing as brownfield modernization demand intensifies through 2035.

How Attractive Is the Industrial Automation Services Market for New Investment?
The industrial automation services Industry presents a highly attractive investment case, supported by a USD 297.67 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Middle East & Africa and managed operations categories. We found that investment attractiveness is highest for providers combining validated managed service credentials with scaled regional delivery infrastructure, positioning them to serve both mature North American and emerging Middle Eastern segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor skilled engineering workforce shortages, capital cost sensitivity, and competitive pressure from low-cost regional system integrators as key risks to the industrial automation services market. Our analysis shows that providers unable to scale structured training pipelines risk losing project delivery capacity to competitors with stronger engineering talent pipelines, particularly within increasingly demand-constrained North American and European markets.

What Are the Key Growth Pathways for the Industrial Automation Services Market?

Key growth pathways include expanding managed operations and cybersecurity service portfolios, scaling delivery capacity across Middle East & Africa industrial diversification programs, and deepening penetration into electronics and semiconductor fabrication automation. NMSC's analysis indicates that providers pursuing these pathways while maintaining cost competitiveness in standard project engineering will be best positioned to capture the industrial automation services market's projected growth through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Service Revenue Analysis
  • Historical industrial automation service revenue by service type and technology, covering major global regions.
  • Identifies the fastest-growing service categories and the technology areas driving historical growth.
Market Sizing and Addressable Opportunity Assessment
  • Total, serviceable, and value-addressable market sizing for industrial automation services by service type and end-user industry.
  • Clarifies the addressable opportunity to prioritize market entry and investment allocation.
Technology Service Revenue Benchmarking
  • Company-level revenue split across automation service offerings and technology lines where publicly disclosed in annual reports and filings.
  • Benchmarks where leading providers concentrate technology-led service investment and where gaps remain.
Contracting Model Revenue Mix Benchmarking
  • Recurring versus project-based service revenue mix for listed automation providers, mapped by contracting buyer type (OEM, end user, and channel partner).
  • Shows which contracting models deliver recurring revenue and margin resilience, guiding service portfolio and contract strategy.
End-User Industry Service Demand Mapping
  • Automation service demand mapping by end-user industry and country, using robot density and industrial output indicators from IFR and national statistics.
  • Prioritizes the end-user verticals and countries with the highest automation service intensity for targeted go-to-market efforts.
Delivery Channel Footprint Assessment
  • Mapping of service delivery channels across OEM-direct, system integrator, and distributor networks by region, based on public partner directories and company disclosures.
  • Guides partnership, channel, and localization investment decisions for entering or expanding in target regions.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖