Data Center Services Market Global Industry Analysis and Forecast (2026–2035)

Valued at USD 161.18 Billion in 2025, the Data Center Services Market is forecast to climb to USD 1,356.52 Billion by 2035 at a 19.13% CAGR over 2026 to 2035, as AI workloads, hyperscaler spending and sovereign hosting rules lift demand, with North America leading the global landscape.
Download Free Sample PDF
Base Year (2025)
$161.18 Billion
Forecast (2035)
$1,356.52 Billion
CAGR (2026-2035)
19.1%
Top Region
North America

What Is the Data Center Services Market Size?
The global Data Center Services Market reached USD 161.18 Billion in 2025 and is estimated at USD 280.71 Billion in 2026, forecast to reach USD 1,356.52 Billion by 2035 at a CAGR of 19.13% between 2026 and 2035. North America leads with approximately 44% revenue share in 2025, while colocation is the dominant service type, accounting for approximately 45% of revenue.
We observed that AI driven capacity growth is pulling operations, cooling, commissioning and maintenance work forward faster than floor space itself. Operators cannot staff, certify and run high density halls on schedule without outside specialists, so service revenue is expanding at a pace above the facility build rate across every major region.

Data Center Services Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast
Values in USD Billion

2025 $161.18 Billion
2025
2026 $280.71 Billion
2026
2027 $334.41 Billion
2027
2028 $398.38 Billion
2028
2029 $474.59 Billion
2029
2030 $565.38 Billion
2030
2031 $673.54 Billion
2031
2032 $802.39 Billion
2032
2033 $955.89 Billion
2033
2034 $1,138.75 Billion
2034
2035 $1,356.52 Billion
2035

Key Takeaways

By Service Type: Colocation services held the largest share, expanding from USD 72.52 Billion in 2025 to USD 515.48 Billion by 2035; the maintenance and support services segment is the fastest-growing, at a 20.91% CAGR from 2026–2035.

By Data Center Type: Hyperscale held the largest share, expanding from USD 78.98 Billion in 2025 to USD 732.52 Billion by 2035; Edge is the fastest growing at 21.30% CAGR from 2026–2035.

By End User Industry: IT and telecom held the largest share, expanding from USD 66.09 Billion in 2025 to USD 529.05 Billion by 2035; Manufacturing and energy is the fastest growing at 22.12% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 44% revenue share in 2025, valued at USD 70.60 Billion, anchored by hyperscale campus demand and enterprise outsourcing.

Fastest-Growing Region: Middle East & Africa is expected to register the highest CAGR of 24.05% during 2026–2035, driven by national digital programs and new cloud capacity.

Dominant Country: The U.S. led the market with an estimated USD 57.89 Billion in 2025, supported by the deepest base of hyperscale and enterprise tenants.

Fastest-Growing Country: India is among the fastest growing major countries, projected to expand from USD 4.61 Billion in 2025 at a CAGR of 27.09%, driven by rapid capacity additions in new metros.

The Data Center Services Market presents an absolute investment opportunity of approximately USD 1,075.81 Billion between 2026 and 2035. That figure equals the 2035 forecast of USD 1,356.52 Billion less the 2026 base of USD 280.71 Billion, which positions managed operations and maintenance platforms as capital efficient entry points for investors.
According to NMSC analysis, the shift from enterprise owned server rooms to outsourced capacity is the most structurally important change in the market. Operators that once ran their own halls now buy engineering, operations and maintenance from specialists able to staff liquid cooling, power and security certification at scale, which favors scaled providers.

What Does the Data Center Services Market Encompass?
The market covers colocation, managed, professional and maintenance and support services that design, build, operate and sustain data center facilities for enterprises, cloud providers and public agencies. Our scope counts provider revenue from retail and wholesale colocation, managed infrastructure, consulting, systems integration and facility maintenance. It excludes sales of servers, network gear and power equipment, and it excludes electricity resale, which prevents double counting with adjacent hardware and energy markets.

Operators such as Equinix, Digital Realty and NTT DATA keep adding campuses for cloud and AI tenants, which widens the base of facilities that need continuous operation. Regulation now shapes siting and operations as well. The EU recast Energy Efficiency Directive requires data centers of 500 kW or more to report energy performance, which raises compliance work for operators and creates audit and optimization demand for service firms.

Market Drivers & Dynamics

Interactive Dataset
Hyperscale and AI capacity demand driver +4.20% Global, led by North America 2026–2030
Enterprise cloud migration and hybrid outsourcing driver +3.10% Europe, Asia-Pacific 2026–2032
Data sovereignty and localization rules driver +1.80% Europe, Middle East & Africa, India 2026–2035
Edge and low latency workloads driver +1.50% Asia-Pacific, North America 2027–2035
Liquid cooling and high density operations driver +1.20% North America, Europe 2026–2031
Grid interconnection delays restraint −2.90% North America, Europe 2026–2031
Moratoria and efficiency regulation restraint −1.60% Ireland, Singapore, EU 2026–2030
Skilled labor shortage restraint −1.10% North America, Europe 2026–2033
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the Data Center Services Market?

AI workloads are the primary driver. Data center electricity demand is set to more than double to around 945 TWh by 2030, and in the United States data centers account for nearly half of electricity demand growth over that period. Reference projections for U.S. data centers reach 649 TWh in 2030, or 11.8% of national electricity. Each added megawatt requires design, commissioning, operations and maintenance, which sustains the Data Center Services Market.

How Is Hyperscaler Investment Driving Data Center Services Market Growth?
Hyperscalers are funding capacity at a record pace. Microsoft's additions to property and equipment reached USD 115.90 Billion in fiscal 2026, up from USD 64.60 Billion in fiscal 2025, while Amazon's trailing twelve month purchases rose to USD 173.00 Billion from USD 107.70 Billion. We observed that this spending flows into leased capacity, fit out and operations, and AWS sales growth of 37% in the second quarter of 2026 signals continued cloud computing demand.

Growth Inhibitors

What Is Restraining the Data Center Services Market?

Power access is the primary restraint. About 20% of planned data center projects could face delays, and in Ireland data centers consumed 23% of metered electricity in 2025, with annual use rising from 1,240 GWh in 2015 to 7,663 GWh. U.S. regulators issued show cause orders in June 2026 to six grid operators over large load connection rules. Electrician employment is projected to grow 9% over 2025 to 2035, which adds pressure on labor.

What Are the Growth Opportunities?

Can Liquid Cooling and High Density Operations Become a Premium Service Line?

Providers that bundle design, fluid management and recurring maintenance can win contracts that outlast equipment sales cycles. The maintenance and support services segment is forecast to grow at a 20.91% CAGR from 2026 to 2035, and the PurgeRite deal agreed in 2025 shows that large equipment players want this recurring revenue. Colocation operators and independent service firms with certified technicians are the main beneficiaries.

Does Power Led Site Development Create Advisory and Engineering Demand?

Regulators are rewriting connection rules, so operators need partners who can secure power, permits and on site generation. Professional services, forecast at 20.61% CAGR from 2026 to 2035, captures this work through consulting, engineering and project management. Developers and enterprises without in house grid expertise benefit most, and datacenterpower solutions become part of the scope.

Can Emerging Markets Capture Outsourced Capacity Faster Than Mature Regions?

Asia-Pacific is forecast to grow at 22.36% CAGR from 2026 to 2035 and Middle East & Africa at 24.05%, compared with 16.80% in North America. Providers that localize operations, meet data residency rules and bring hyperscale tenants into new metros can capture outsized share. Colocation and managed service firms with local partners are best placed to benefit.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Colocation services 2025: $72.52 Billion | 2035: $515.48 Billion
Colocation s
Managed services 2025: $40.30 Billion | 2035: $366.26 Billion
Managed serv
Professional services 2025: $25.79 Billion | 2035: $257.74 Billion
Professional
Maintenance and support services 2025: $22.57 Billion | 2035: $217.04 Billion
Maintenance
Colocation services $72.52 Billion $515.48 Billion 17.20%
Managed services $40.30 Billion $366.26 Billion 20.15%
Professional services $25.79 Billion $257.74 Billion 20.61%
Maintenance and support services $22.57 Billion $217.04 Billion 20.91%

Which Service Type Leads the Data Center Services Market?

Colocation services led with approximately 45% of 2025 revenue, or USD 72.52 Billion, because tenants still buy space and power first. Our assessment indicates that the maintenance and support services segment is the fastest-growing, at a 20.91% CAGR from 2026 to 2035, driven by liquid cooling upkeep and round the clock operations. Equinix earned USD 6.48 Billion from colocation out of USD 9.22 Billion of total revenue in 2025.

2025 (USD Billion)
2035 (USD Billion)
Hyperscale
Enterprise
Edge
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Hyperscale $10.0 USD Billion $40.0 USD Billion 25.0%
Enterprise $17.1 USD Billion $51.1 USD Billion 11.0%
Edge $24.2 USD Billion $62.2 USD Billion 25.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Data Center Type.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
IT and telec
BFSI
Healthcare a
Government a
Retail and e
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
IT and telecom $10.0 USD Billion $40.0 USD Billion 27.0%
BFSI $17.1 USD Billion $51.1 USD Billion 9.0%
Healthcare and life sciences $24.2 USD Billion $62.2 USD Billion 19.0%
Government and defense $31.3 USD Billion $73.3 USD Billion 17.0%
Retail and ecommerce $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User Industry.

Unlock Full Data

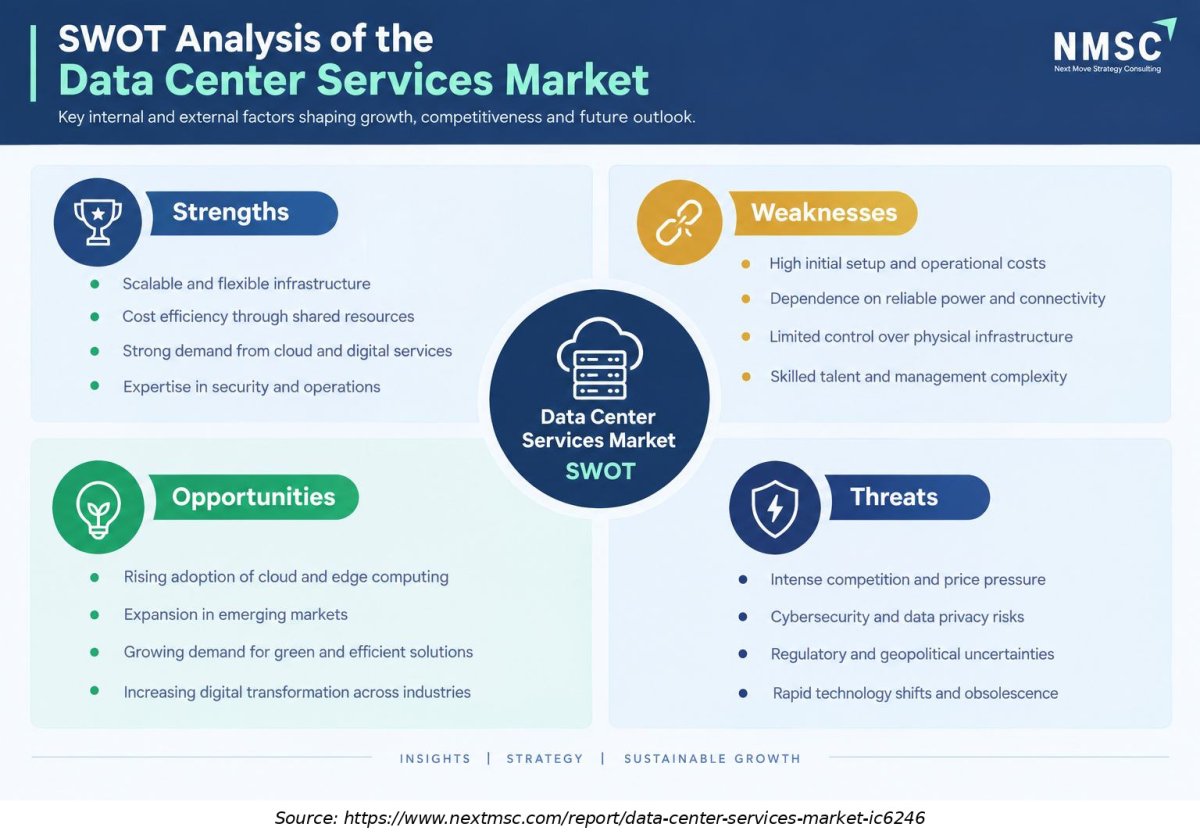
SWOT Analysis

This SWOT view highlights structural strengths, strategic gaps, expansion headroom, and external risks shaping outcomes in the Data Center Services Market Global Industry Analysis and Forecast (2026–2035).
Strengths

Weaknesses

Opportunities

Threats

Growth Opportunities

Our findings suggest that three whitespace opportunities offer the clearest return over the forecast period.

Can Liquid Cooling and High Density Operations Become a Premium Service Line?

Providers that bundle design, fluid management and recurring maintenance can win contracts that outlast equipment sales cycles. The maintenance and support services segment is forecast to grow at a 20.91% CAGR from 2026 to 2035, and the PurgeRite deal agreed in 2025 shows that large equipment players want this recurring revenue. Colocation operators and independent service firms with certified technicians are the main beneficiaries.

Does Power Led Site Development Create Advisory and Engineering Demand?

Regulators are rewriting connection rules, so operators need partners who can secure power, permits and on site generation. Professional services, forecast at 20.61% CAGR from 2026 to 2035, captures this work through consulting, engineering and project management. Developers and enterprises without in house grid expertise benefit most, and datacenterpower solutions become part of the scope.

Can Emerging Markets Capture Outsourced Capacity Faster Than Mature Regions?

Asia-Pacific is forecast to grow at 22.36% CAGR from 2026 to 2035 and Middle East & Africa at 24.05%, compared with 16.80% in North America. Providers that localize operations, meet data residency rules and bring hyperscale tenants into new metros can capture outsized share. Colocation and managed service firms with local partners are best placed to benefit.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

NMSC's analysis indicates that scale, power access and interconnection ecosystems separate leaders from followers.

How Do Companies Compete in the Data Center Services Market?

Providers compete on power availability, location, interconnection density and service quality. Equinix generated USD 9.22 Billion in 2025, including USD 1.66 Billion from interconnection, which shows how ecosystem value supports pricing beyond space and power. Carrier backed and regional operators such as NTT DATA, KDDI and GDS compete through home market relationships and fast construction, and customers increasingly prefer multi region delivery.

Which Provider Archetypes Dominate the Data Center Services Market?

Four archetypes shape the industry. Global platforms such as Equinix and Digital Realty lead on footprint, carrier backed operators such as NTT DATA and KDDI lean on network relationships, and China focused specialists GDS and VNET follow domestic cloud demand. Infrastructure and managed service firms such as American Tower, Iron Mountain and Rackspace differentiate through adjacent tower, records, hosting and cloud operations.

How Do Providers Innovate and Differentiate?

Providers differentiate through AI ready halls, liquid cooling operations and sovereign hosting. Applied Digital, for example, reported USD 0.61 Billion of revenue in the year to 31 May 2026 from hosting and high performance computing capacity. Pricing strategies increasingly mix long dated reservations with consumption based managed fees, and geographic expansion follows where power and tenants converge.

What Is the M&A Activity in the Data Center Services Market?

Deal activity targets capacity, specialist services and new geographies. CPP Investments and Equinix completed the USD 4.00 Billion atNorth acquisition in September 2026, AirTrunk entered India through the Lumina CloudInfra purchase in April 2026, and Vertiv agreed to buy PurgeRite in November 2025. We expect further consolidation as operators pursue powered land and service depth.

Key Market Players

Based on research conducted by NMSC, we found that the following twelve providers form the verified competitive set, listed in ranked order.

Equinix, Inc. Digital Realty Trust, Inc. NTT DATA Group Corporation GDS Holdings Limited VNET Group, Inc. American Tower Corporation Rackspace Technology, Inc. Iron Mountain Incorporated KDDI Corporation Applied Digital Corporation Sify Technologies Limited Macquarie Technology Group Limited

Latest Developments

During our market evaluation, we noticed that capacity, financing and specialist service deals dominated 2025 and 2026 announcements.

Date Event
September 2026 CPP Investments and Equinix completed the acquisition of atNorth, a Nordic data center developer and operator, expanding their presence across the Nordic region through a portfolio of eight operational data centers and additional development projects.
August 2026 Iron Mountain reported that its data center leasing reached 110 MW year to date through July 2026, including 75 MW in new leases signed after the second quarter, reflecting continued demand for its data center capacity.
April 2026 AirTrunk acquired Lumina CloudInfra, marking its entry into India's data center market and adding approximately 600 MW of planned capacity, representing up to USD 5 billion in potential future development.

Investment Opportunities

How Is Capital Flowing Into Data Center Services Market?

Private capital is pooling behind operators. Digital Realty closed its first U.S. hyperscale fund at USD 3.25 Billion in March 2026 and retains a 20% interest while managing it. Our analysis shows that such vehicles favor platforms with long dated tenant contracts, so stable contracted cash flow is the main screen for investors, and service lines tied to those platforms gain from the inflow.

Where Is Infrastructure Investment Concentrated?

Investment concentrates on powered land and campus build out. NTT DATA is pursuing a USD 10.00 Billion plan through 2027, Equinix reported about 1 GW of powered land at the end of 2025, and Iron Mountain leased 110 MW through July 2026. We found that each gigawatt of capacity creates a long tail of operations, maintenance and engineering contracts for service providers.

Which ESG Considerations Shape Investment Decisions?

Efficiency and clean power conditions now influence capital allocation. Singapore's second capacity call, for at least 200 MW, requires a power usage effectiveness of 1.25 or better and at least 50% eligible green energy for new capacity. Investors increasingly price these conditions into underwriting, which favors operators with efficient green datacenter designs and strong monitoring services.

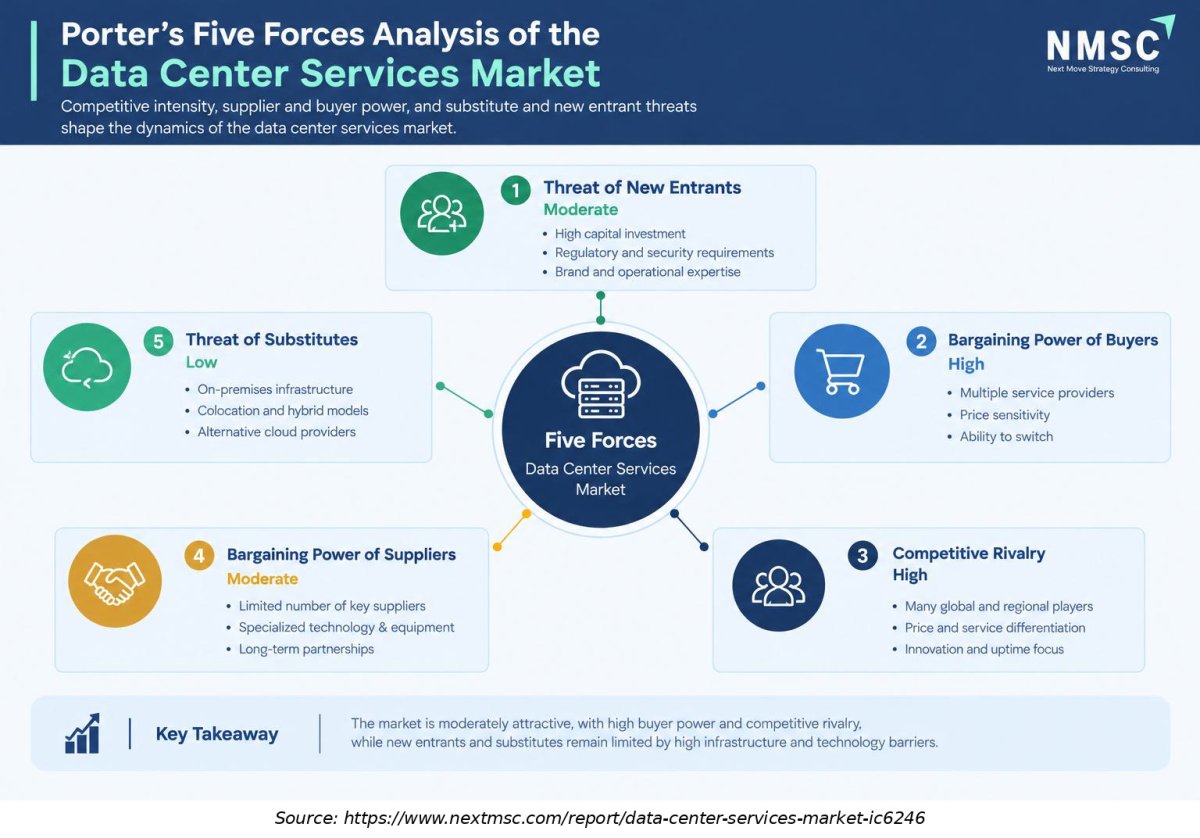
Porter’s Five Forces Analysis of the Data Center Services Market

Porter’s Five Forces analysis examines competitive rivalry, buyer bargaining power, supplier influence, and the threats posed by new entrants and substitutes in the data center services market. High buyer power and competitive intensity encourage service differentiation, pricing discipline, and continuous innovation. Capital requirements, specialized infrastructure, and technical expertise create barriers to entry, while alternative deployment models influence competitive positioning.

Key Benefits for Stakeholders

How Does This Report Help Enterprise and Industry Leaders?

Enterprise leaders can use the segment forecasts to compare colocation, managed, professional and maintenance options and to time outsourcing decisions. The regional and country tables show where capacity is growing fastest, and the competitive analysis helps buyers shortlist providers. Planning teams can also test sourcing strategies against datacenterinfrastructure trends and regulatory conditions.

How Does This Report Help Investors and Financial Analysts?

Investors gain a reconciled view of the market from USD 161.18 Billion in 2025 to USD 1,356.52 Billion by 2035, with segment and regional growth rates that expose where returns concentrate. The developments table and deal analysis highlight active capital themes, while the restraint assessment helps analysts weigh power and regulatory risk when valuing platforms.

How Does This Report Help Service Providers and Technology Vendors?

Providers and vendors can identify the fastest growing service lines, data center types and end user industries to prioritize product roadmaps and sales coverage. The opportunity analysis points to liquid cooling services, power advisory work and emerging market entry, while the competitive section shows how peers differentiate and where partnership gaps remain.

Key Market Segments Evaluated

By Service Type

  • Colocation services
  • Managed services
  • Professional services
  • Maintenance and support services

By Data Center Type

  • Hyperscale
  • Enterprise
  • Edge

By End User Industry

  • IT and telecom
  • BFSI
  • Healthcare and life sciences
  • Government and defense
  • Retail and ecommerce
  • Manufacturing and energy

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

We found that the path to USD 1,356.52 Billion by 2035 rests on durable demand for outsourced capacity, operations and maintenance rather than on a single technology cycle. Growth of 19.13% a year from 2026 reflects AI, cloud and sovereignty needs that compound across regions. Providers should expect the service mix to tilt toward managed, professional and maintenance work as facilities become denser and more complex.

What Strategic Positioning Recommendations Does NMSC Offer?

NMSC recommends that providers secure grid capacity and powered land early, build certified liquid cooling and fluid management teams, and package operations with long term service agreements. Enterprises should diversify across regions and favor partners with strong interconnection and compliance credentials. Entrants can use local partnerships to reduce permitting and power risk in emerging regions.

What Is the Investment Attractiveness of the Data Center Services Market?

Investor appeal is strong because the market adds USD 1,075.81 Billion between 2026 and 2035 with recurring, contract based revenue. Maintenance and support services at 20.91% CAGR and edge capacity at 21.30% CAGR offer the fastest growth, while colocation provides scale and stability. Our assessment indicates that platforms with secured power and long dated tenants deserve the highest conviction.

What Are the Market Shifts and Key Risks in the Data Center Services Market?

Grid constraints, connection conditions and efficiency rules are the main shifts to monitor. Ireland now requires new facilities to bring on site or nearby generation or storage matched to requested grid capacity, and similar conditions could spread. Capital intensity, tenant concentration among a few hyperscalers and labor shortages add execution risk, so providers need disciplined phasing and diversified customers.

What Are the Primary Growth Pathways Through 2035?

Five pathways stand out: retrofitting halls for AI density, expanding sovereign and regulated hosting, rolling out edge sites near users, entering fast growing regions such as India and the Gulf, and acquiring specialist service firms. Our analysis shows that providers combining several pathways, supported by secured power, are best placed to outgrow the market.

FAQs

Sources & References

1.

International Energy Agency (IEA), Energy and AI

iea.org
2.

Lawrence Berkeley National Laboratory, 2025 United States Data Center Energy Usage Report

eta.lbl.gov
3.

Eurostat, Cloud computing use by EU enterprises (2025)

ec.europa.eu
4.

Central Statistics Office Ireland, Data Centres Metered Electricity Consumption 2025

cso.ie
5.

Commission for Regulation of Utilities (CRU), Data centre electricity connection policy

cru.ie
6.

Infocomm Media Development Authority (IMDA), Second Data Centre Call for Application

imda.gov.sg
7.

Federal Energy Regulatory Commission (FERC), Large load integration action

ferc.gov
8.

U.S. Bureau of Labor Statistics, Occupational Outlook Handbook: Electricians

bls.gov
9.

Federal Register, Accelerating Federal Permitting of Data Center Infrastructure

federalregister.gov
10.

EUR-Lex, Directive (EU) 2023/1791 on energy efficiency

eur-lex.europa.eu
11.

Press Information Bureau, Government of India

pib.gov.in
12.

Microsoft Corporation, FY2026 Q4 earnings release

microsoft.com
13.

Amazon.com, Inc., Q2 2026 results

ir.aboutamazon.com
14.

Equinix, Inc., Fiscal 2025 results and 2026 outlook

investor.equinix.com
15.

Equinix, Inc., atNorth acquisition completion

investor.equinix.com
16.

Digital Realty Trust, Inc., U.S. hyperscale fund final close

investor.digitalrealty.com
17.

Digital Realty Trust, Inc., Second quarter 2025 results

investor.digitalrealty.com
18.

NTT DATA Group Corporation, Investor materials fiscal 2025

nttdata.com
19.

NTT DATA, Global Data Centers land acquisition announcement (May 2025)

businesswire.com
20.

Vertiv Holdings Co, PurgeRite acquisition announcement (SEC Form 8-K Exhibit 99.1)

sec.gov
21.

AirTrunk, Lumina CloudInfra acquisition

airtrunk.com
22.

Iron Mountain Incorporated, Q2 2026 earnings presentation (SEC)

sec.gov
23.

GDS Holdings Limited, Fiscal 2025 results (SEC Form 6-K)

sec.gov
24.

VNET Group, Inc., Fiscal 2025 results (SEC Form 6-K)

sec.gov
25.

American Tower Corporation, Fourth quarter and full year 2025 results

businesswire.com
26.

Rackspace Technology, Inc., Fourth quarter and full year 2025 results

globenewswire.com
27.

Iron Mountain Incorporated, Data centers

ironmountain.com/data-centers
28.

KDDI Corporation, Telehouse data center services

biz.kddi.com
29.

Applied Digital Corporation, Fiscal 2026 fourth quarter results (SEC)

sec.gov
30.

Sify Technologies Limited, FY 2025–26 results

sifytechnologies.com
31.

Macquarie Technology Group Limited, FY26 results (ASX)

announcements.asx.com.au

About the Author

Mihul Sharma

Mihul Sharma

Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖