Mouthwash Market

The global Mouthwash Market size was USD 9.47 billion in 2025, projected to reach USD 19.72 billion by 2035, growing at a CAGR of 7.26% from 2026 to 2035. Key growth drivers include rising oral disease prevalence, increasing demand for alcohol-free formulations, expanding e-commerce distribution, and growing adoption of specialized oral-care products, with North America leading the market with approximately 36% share.

Download Free Sample PDF
Base Year (2025)
$9.47 Billion
Forecast (2035)
$19.72 Billion
CAGR (2026-2035)
7.3%
Top Country
North America

What Is the Mouthwash Market Size?

The global mouthwash market size was valued at USD 9.47 billion in 2025 and is estimated at USD 10.49 billion in 2026, forecast to reach USD 19.72 billion by 2035, expanding at a 7.26% CAGR between 2026 and 2035. North America leads with approximately 36% share, while the liquid product format dominates all other formats with approximately 85% share.

We observed that growth is broad-based across every segmentation axis, with alcohol-free formulation demand and online distribution expansion driving the dominant structural shifts through 2035.

Mouthwash Market Revenue Forecast

Values in USD Billion

2025 $9.47 Billion
2025
2026 $10.49 Billion
2026
2027 $11.25 Billion
2027
2028 $12.07 Billion
2028
2029 $12.94 Billion
2029
2030 $13.88 Billion
2030
2031 $14.89 Billion
2031
2032 $15.97 Billion
2032
2033 $17.13 Billion
2033
2034 $18.38 Billion
2034
2035 $19.72 Billion
2035

Key Takeaways

By Product Format: Liquid held the largest share of approximately 85% (USD 8.05 billion) in 2025; Dissolvable and Solid is the fastest-growing sub-segment at 21.4% CAGR from 2026–2035.

By Primary Purpose: Multi-Benefit held the largest share of approximately 34% (USD 3.22 billion) in 2025; Clinical Care is the fastest-growing sub-segment at 17.3% CAGR from 2026–2035.

By Lead Active Ingredient: Essential Oils held the largest share of approximately 26% (USD 2.46 billion) in 2025; Enzymes and Biologics is the fastest-growing sub-segment at 20.1% CAGR from 2026–2035.

By Alcohol Status: Alcohol-Free held the largest share of approximately 58% (USD 5.49 billion) in 2025; Alcohol-Free is also the fastest-growing sub-segment at 10.4% CAGR from 2026–2035.

By End User: Adult held the largest share of approximately 78% (USD 7.39 billion) in 2025; Pediatric is the fastest-growing sub-segment at 12.6% CAGR from 2026–2035.

By Route to Market: Offline Retail held the largest share of approximately 66% (USD 6.25 billion) in 2025; Online Retail is the fastest-growing sub-segment at 13.5% CAGR from 2026–2035.

By Packaging Format: Bottles held the largest share of approximately 82% (USD 7.77 billion) in 2025; Unit-Dose is the fastest-growing sub-segment at 20.1% CAGR from 2026–2035.

By Price Tier: Mid held the largest share of approximately 42% (USD 3.98 billion) in 2025; Premium is the fastest-growing sub-segment at 13.4% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 36% revenue share (USD 3.41 billion) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 11.0% during 2026–2035.

Dominant Country: U.S. led with approximately USD 2.80 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 13.6% CAGR from 2026–2035.

Market Opportunity: The mouthwash market is expected to create an absolute dollar opportunity of USD 9.23 billion between 2026 and 2035, presenting significant investment potential across alcohol-free reformulation, e-commerce distribution, and premium therapeutic product lines.

According to NMSC analysis, manufacturers are increasingly reformulating flagship brands around alcohol-free, essential-oil, and enzyme-based active systems to retain daily-use consumers who associate alcohol content with dryness and irritation, a shift that favors companies with broad reformulation capability over single-formula specialists as retailer shelf space and search demand increasingly favor alcohol-free claims through 2035.

What Does the Mouthwash Market Encompass?

The mouthwash market covers liquid, tablet, powder, and strip oral rinse products formulated for fresh breath, gum health, anticavity protection, sensitivity relief, dry mouth relief, whitening, and clinical care purposes across essential oil, cetylpyridinium chloride, chlorhexidine, fluoride, and peroxide active systems. Our assessment indicates that Dissolvable and Solid mouthwash strips are included within the product-format scope, whereas standalone tooth-whitening strips are excluded. The market spans adult, pediatric , and geriatric end users purchasing through offline retail, online retail, direct selling, and professional and institutional channels worldwide.

The World Health Organization's March 2025 oral health fact sheet estimates that oral diseases affect nearly 3.7 billion people globally, with severe periodontal disease alone affecting more than 1 billion cases, a burden that anchors sustained daily-use demand for preventive oral rinse products. In the U.S., mouthrinse products making antigingivitis , antiplaque, or other therapeutic drug claims may be subject to FDA OTC drug requirements, while cosmetic mouthrinses are regulated differently. These requirements govern applicable product claims and permitted active ingredients. We observed that alcohol-free reformulation and essential oil-based positioning are displacing traditional alcohol-based formats as manufacturers respond to consumer concern about dryness and irritation from repeated use.

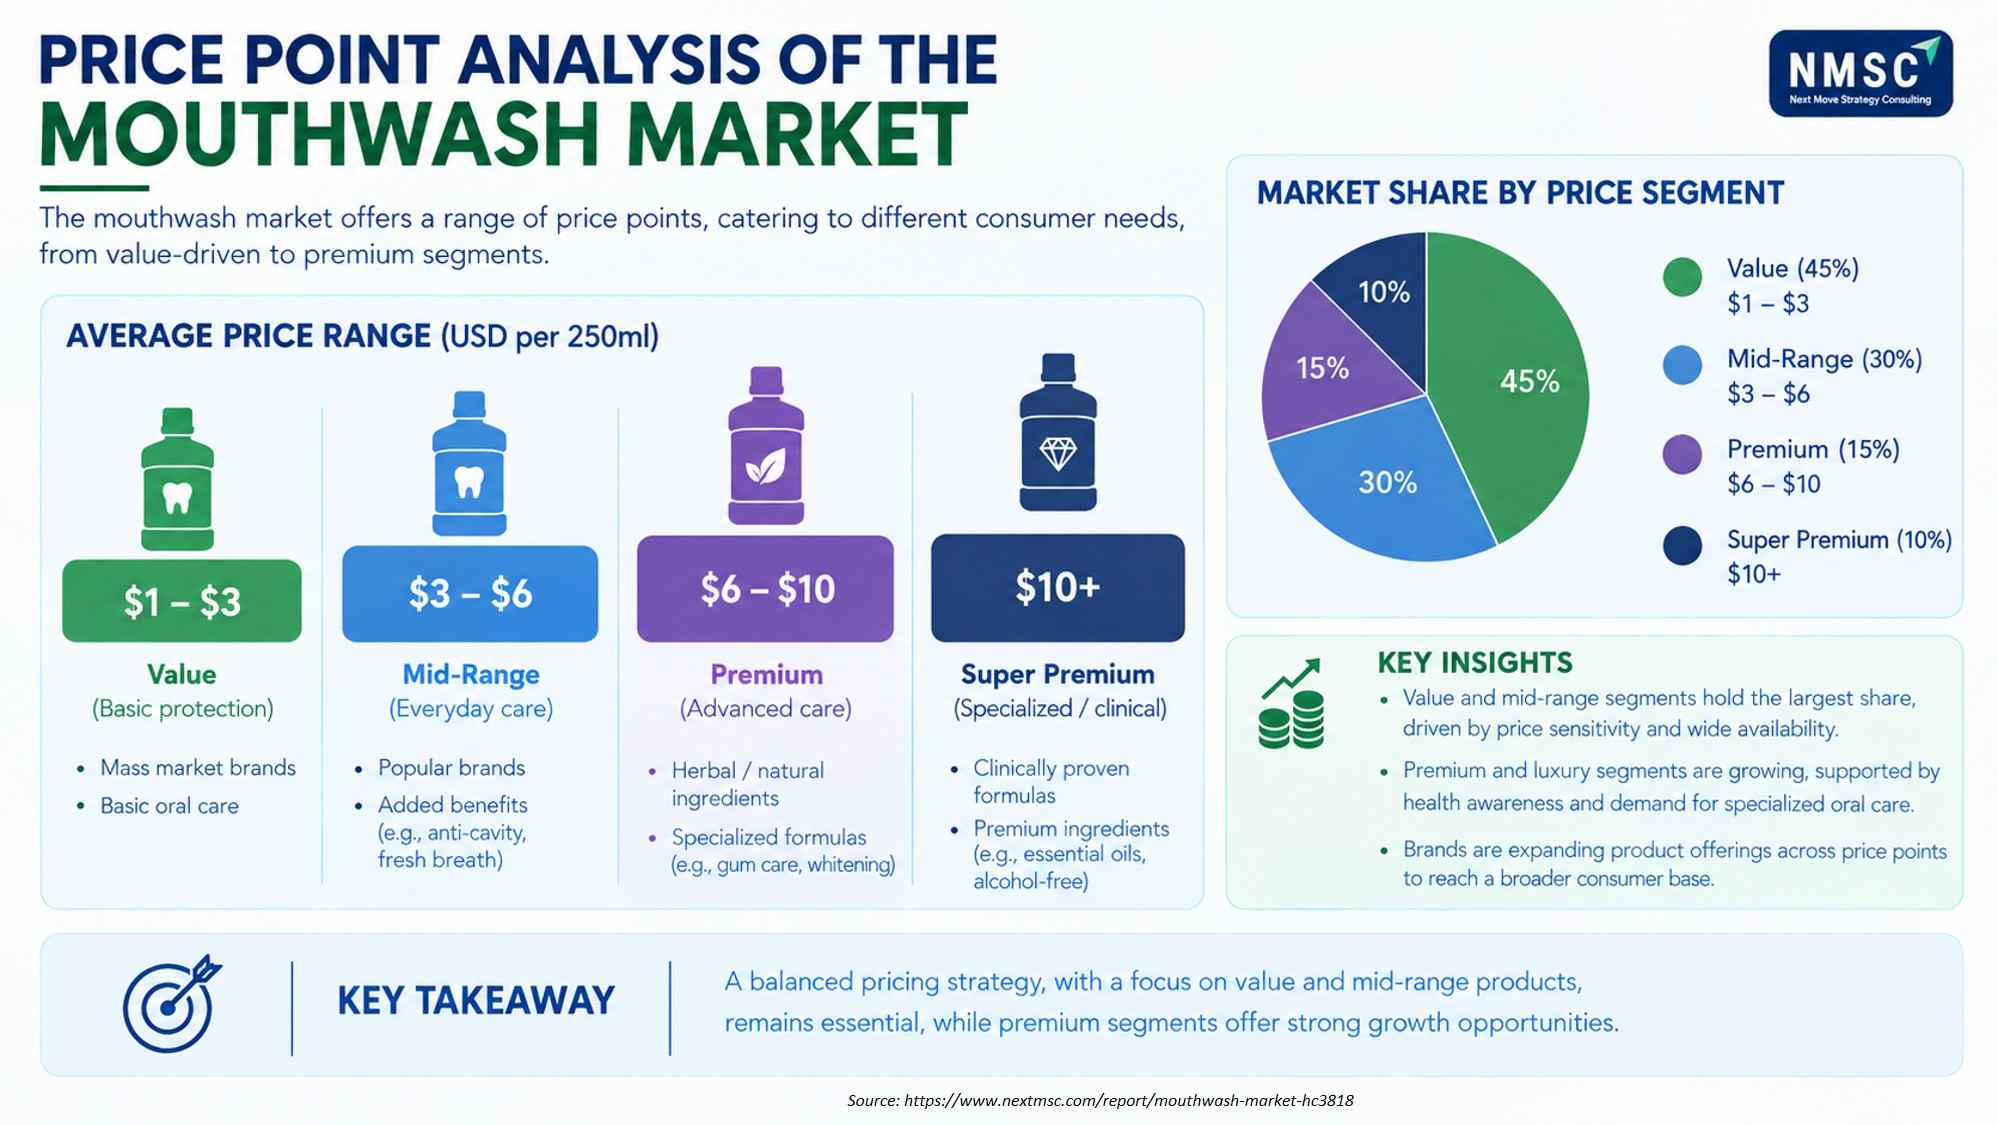
Price Point Analysis of the Mouthwash Market

Price Point Analysis of the Mouthwash Market
The mouthwash market spans value, mid-range, premium, and super-premium price segments, reflecting differences in consumer needs, product benefits, and formulation complexity. Value and mid-range products account for the largest market share due to affordability and broad availability, while premium and super-premium offerings are supported by growing demand for specialized, clinically positioned, and advanced oral-care solutions.

Market Drivers & Dynamics

Interactive Dataset
Rising global prevalence of oral disease and periodontal conditions driver +1.9% Global 2026-2035
Growing demand for alcohol-free and gentle daily-use formulations driver +1.5% North America, Europe 2026-2035
Expanding e-commerce and quick commerce oral care distribution driver +1.2% Asia-Pacific, North America 2026-2035
Rising disposable income and premiumization in emerging markets driver +0.9% Asia-Pacific, Latin America 2026-2035
Growing dentist-recommended and clinical-strength product positioning driver +0.6% North America, Europe 2026-2035
Consumer misconceptions about alcohol-based product efficacy restraint -0.7% Asia-Pacific, Latin America, MEA 2026-2032
Price sensitivity limiting premium adoption in developing markets restraint -0.5% Asia-Pacific, Latin America, MEA 2026-2032
Limited daily-use compliance relative to brushing restraint -0.4% Global 2026-2032
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Mouthwash Market?

Rising global prevalence of oral disease and periodontal conditions is the primary driver of the market. The World Health Organization's March 2025 oral health fact sheet reports that severe periodontal disease affects more than 1 billion cases worldwide, with oral diseases overall affecting nearly 3.7 billion people. We observed that this disease burden, reinforced by dental association guidance recommending oral rinse use alongside brushing, continues to anchor baseline demand for gum health and anticavity mouthwash formulations across developed and emerging economies alike.

How Is Alcohol-Free Formulation Demand Driving Mouthwash Market Growth?

Growing consumer preference for alcohol-free formulations is accelerating market growth as manufacturers reformulate daily-use products to address dryness and irritation concerns. Kenvue Inc. markets its alcohol-free Listerine variants specifically toward consumers seeking gentler daily rinse options, reflecting company-level product strategy responding to this documented consumer preference shift. Our assessment indicates that this formulation shift is compressing replacement cycles for alcohol-based products across mass retail and pharmacy channels.

Growth Inhibitors

What Is Restraining Mouthwash Market Expansion?

Consumer misconceptions about alcohol-based product efficacy, alongside limited daily-use compliance relative to toothbrushing, restrain broader category penetration in several markets. Price sensitivity further limits premium and clinical-positioned product adoption among value-conscious consumers in developing economies. We found that these adoption barriers, combined with inconsistent daily-use habits, are moderating category growth outside markets with established dental association guidance promoting routine oral rinse use.

What Are the Growth Opportunities?

Condition-Specific Therapeutic Formulations Present a Premium Positioning Opportunity

Expanding dry mouth relief, sensitivity relief, and clinical care formulations offers manufacturers a path to premium pricing beyond mass-market multi-benefit products. This opportunity benefits companies with dental practice distribution relationships and consumers seeking condition-specific solutions not addressed by general-purpose rinses.

Tablet and Powder Formats Offer a Sustainability-Led Differentiation Opportunity

Expanding dissolvable tablet and powder mouthwash formats creates opportunity for manufacturers to differentiate on reduced plastic packaging and travel convenience. This mechanism benefits direct-to-consumer specialty brands and environmentally conscious consumers seeking alternatives to liquid bottle formats.

Pediatric -Specific Products Address an Underserved End User Category

Expanding pediatric -formulated mouthwash lines with age-appropriate flavor and alcohol-free positioning creates opportunity for manufacturers to capture a currently underserved end user segment. This mechanism benefits companies with established pediatric oral care brand equity and parents seeking dentist-recommended options for children.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Liquid
Ready-to-use
Concentrated
Dissolvable
Tablet
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Liquid $10.0 USD Billion $40.0 USD Billion 15.0%
Ready-to-use liquid $17.1 USD Billion $51.1 USD Billion 9.0%
Concentrated liquid $24.2 USD Billion $62.2 USD Billion 19.0%
Dissolvable and solid $31.3 USD Billion $73.3 USD Billion 17.0%
Tablet $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Product Format.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Multi-benefi
Fresh breath
Gum health
Anticavity
Sensitivity
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Multi-benefit $10.0 USD Billion $40.0 USD Billion 17.0%
Fresh breath $17.1 USD Billion $51.1 USD Billion 23.0%
Gum health $24.2 USD Billion $62.2 USD Billion 25.0%
Anticavity $31.3 USD Billion $73.3 USD Billion 27.0%
Sensitivity relief $38.4 USD Billion $84.4 USD Billion 20.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Primary Purpose.

Unlock Full Data

Which Primary Purpose Segment Dominates the Mouthwash Market?

Multi-benefit formulations dominate primary purpose segmentation with approximately 34% share, reflecting mainstream consumer preference for a single product addressing fresh breath, gum health, and cavity protection simultaneously rather than purchasing multiple condition-specific rinses. We observed that clinical care is the fastest-growing sub-segment at 17.3% CAGR, as manufacturers including Dentaid S.L. and Curasept S.p.A. expand dentist-recommended, chlorhexidine-based professional-strength formulations that command premium pricing above mass-market multi-benefit products.

2025 (USD Billion)
2035 (USD Billion)
Essential oi
Cetylpyridin
Chlorhexidin
Fluoride com
Peroxides an
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Essential oils $10.0 USD Billion $40.0 USD Billion 22.0%
Cetylpyridinium chloride $17.1 USD Billion $51.1 USD Billion 8.0%
Chlorhexidine $24.2 USD Billion $62.2 USD Billion 18.0%
Fluoride compounds $31.3 USD Billion $73.3 USD Billion 16.0%
Peroxides and chlorine dioxide $38.4 USD Billion $84.4 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Lead Active Ingredient.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Alcohol-base
Alcohol-free
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Alcohol-based $10.0 USD Billion $40.0 USD Billion 18.0%
Alcohol-free $17.1 USD Billion $51.1 USD Billion 16.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Alcohol Status.

Unlock Full Data

Which Alcohol Status Segment Is Fastest-Growing in the Mouthwash Market?

Alcohol-free formulations lead alcohol status segmentation with approximately 58% share in 2025 and are also the fastest-growing sub-segment at 10.4% CAGR, a dual position reflecting sustained consumer migration away from alcohol-based daily-use products. Our findings suggest that this shift is most pronounced in North America and Europe, where manufacturers have concentrated reformulation investment, while alcohol-based products retain stronger relative share in price-sensitive emerging markets where reformulated alternatives carry a price premium.

2025 (USD Billion)
2035 (USD Billion)
Adult
Pediatric
Geriatric
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Adult $10.0 USD Billion $40.0 USD Billion 26.0%
Pediatric $17.1 USD Billion $51.1 USD Billion 16.0%
Geriatric $24.2 USD Billion $62.2 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Offline reta
Supermarkets
Pharmacy and
Convenience
Mass merchan
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Offline retail $10.0 USD Billion $40.0 USD Billion 12.0%
Supermarkets and hypermarkets $17.1 USD Billion $51.1 USD Billion 26.0%
Pharmacy and drugstore $24.2 USD Billion $62.2 USD Billion 12.0%
Convenience stores $31.3 USD Billion $73.3 USD Billion 26.0%
Mass merchants $38.4 USD Billion $84.4 USD Billion 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Route to Market.

Unlock Full Data

Which Route to Market Leads the Mouthwash Market?

Offline retail leads route to market segmentation with approximately 66% share, reflecting the continued importance of supermarket, hypermarket, and pharmacy placement for a low-consideration, frequently repurchased category. We found that online retail is the fastest-growing route at 13.5% CAGR, as e-commerce platforms give specialty and clinical-positioned brands shelf access without dependence on physical retail placement, a shift that particularly benefits condition-specific formulations receiving limited traditional shelf space.

2025 (USD Billion)
2035 (USD Billion)
Bottles
Pouches and
Unit-dose
Other packag
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Bottles $10.0 USD Billion $40.0 USD Billion 25.0%
Pouches and sachets $17.1 USD Billion $51.1 USD Billion 15.0%
Unit-dose $24.2 USD Billion $62.2 USD Billion 25.0%
Other packaging $31.3 USD Billion $73.3 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Packaging Format.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Value
Mid
Premium
Super-premiu
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Value $10.0 USD Billion $40.0 USD Billion 26.0%
Mid $17.1 USD Billion $51.1 USD Billion 24.0%
Premium $24.2 USD Billion $62.2 USD Billion 14.0%
Super-premium $31.3 USD Billion $73.3 USD Billion 12.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Price Tier.

Unlock Full Data

Growth Opportunities

NMSC's analysis indicates that three whitespace opportunities stand out for manufacturers positioning for the next phase of market expansion.

Condition-Specific Therapeutic Formulations Present a Premium Positioning Opportunity

Expanding dry mouth relief, sensitivity relief, and clinical care formulations offers manufacturers a path to premium pricing beyond mass-market multi-benefit products. This opportunity benefits companies with dental practice distribution relationships and consumers seeking condition-specific solutions not addressed by general-purpose rinses.

Tablet and Powder Formats Offer a Sustainability-Led Differentiation Opportunity

Expanding dissolvable tablet and powder mouthwash formats creates opportunity for manufacturers to differentiate on reduced plastic packaging and travel convenience. This mechanism benefits direct-to-consumer specialty brands and environmentally conscious consumers seeking alternatives to liquid bottle formats.

Pediatric -Specific Products Address an Underserved End User Category

Expanding pediatric -formulated mouthwash lines with age-appropriate flavor and alcohol-free positioning creates opportunity for manufacturers to capture a currently underserved end user segment. This mechanism benefits companies with established pediatric oral care brand equity and parents seeking dentist-recommended options for children.

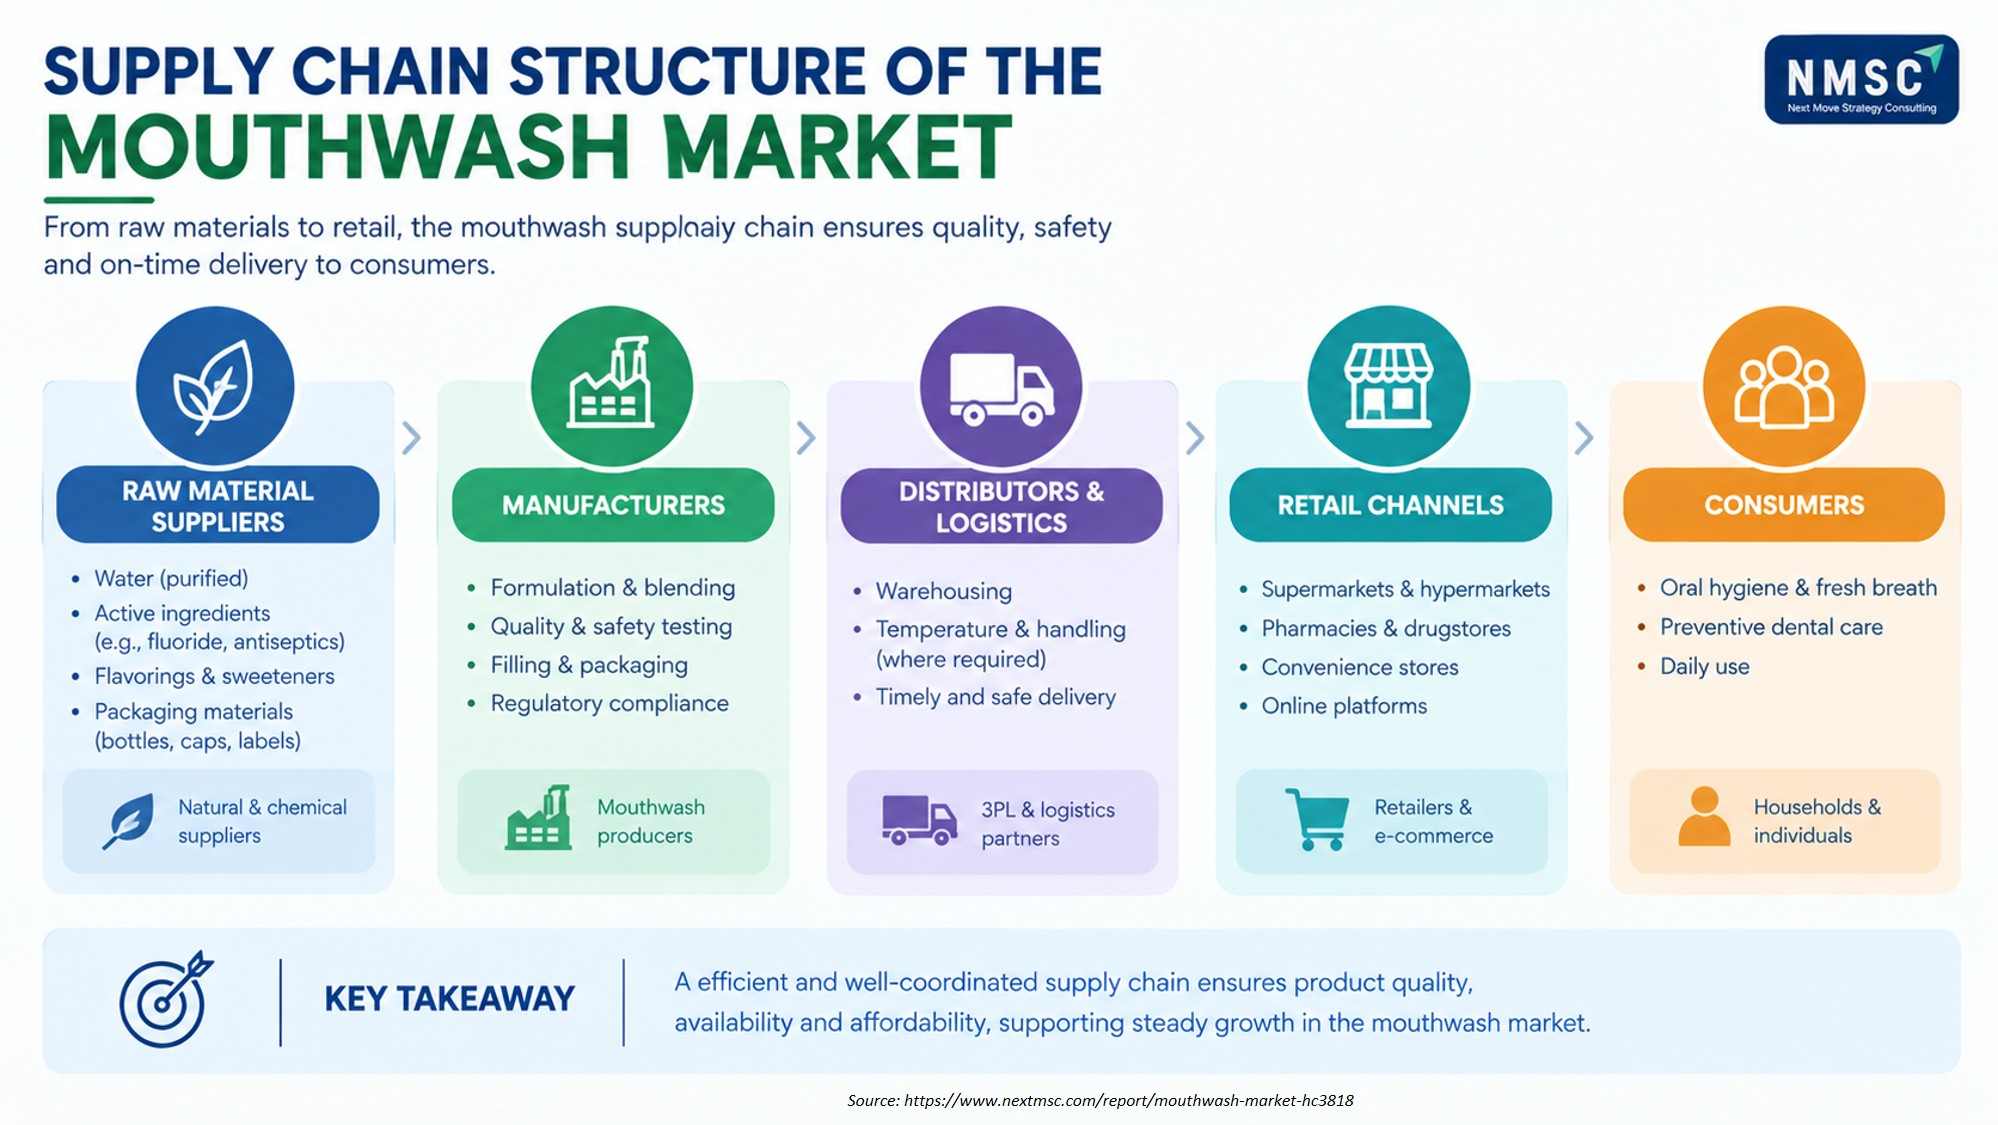
Supply Chain Structure of the Mouthwash Market

Supply Chain Structure of the Mouthwash Market
The mouthwash supply chain connects raw material suppliers, manufacturers, distributors, logistics providers, retail channels, and consumers. Effective coordination across formulation, quality testing, packaging, warehousing, distribution, and retail is essential for maintaining product quality, regulatory compliance, availability, and cost efficiency. Increasing adoption of online platforms is also strengthening direct and omnichannel pathways to consumers.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Asia-Pacific
Europe
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Asia-Pacific $17.1 USD Billion $51.1 USD Billion 27.0%
Europe $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

Our findings suggest that the mouthwash market is moderately consolidated, with global consumer health leaders competing alongside regional and specialty oral care manufacturers. Field | Details Market Structure | The market is moderately consolidated, with leading global and regional companies accounting for a substantial portion of market revenue . Innovation Focus | Alcohol-free reformulation, tablet and powder format development, and clinical-strength therapeutic positioning. M&A Activity | Selective, with consumer health companies continuing to expand mouthwash product lines through brand extension rather than large-scale acquisition. Source: www.nextmsc.com

Dimension Description
Market Structure The market is moderately consolidated, with leading global and regional companies accounting for a substantial portion of market revenue .
Innovation Focus Alcohol-free reformulation, tablet and powder format development, and clinical-strength therapeutic positioning.
M&A Activity Selective, with consumer health companies continuing to expand mouthwash product lines through brand extension rather than large-scale acquisition.

Brand Equity and Reformulation Speed Determine Competitive Position

Companies compete primarily on brand trust, active ingredient credibility, and reformulation speed across fresh breath, gum health, and clinical care categories. NMSC's analysis indicates that manufacturers differentiate through dentist endorsement, alcohol-free product breadth, and distribution reach across offline and online channels. Competitive rivalry is most intense in the multi-benefit category, where several established manufacturers offer comparable core formulations, pushing differentiation toward flavor innovation and packaging format.

Global Consumer Health Leaders and Specialty Dental-Channel Brands Define Market Structure

Two archetypes dominate: global consumer health leaders such as Kenvue Inc. and Colgate-Palmolive Company that combine deep brand equity with mass retail distribution scale, and specialty dental-channel manufacturers such as Dentaid S.L. and Curasept S.p.A. that compete on professional-strength formulation credibility distributed partly through dental practices. Our analysis shows that scale advantages favor global leaders in mass-market multi-benefit categories, while specialists retain share in premium clinical care niches.

Formulation Innovation Centers on Alcohol-Free and Format Diversification

Leading manufacturers are investing in alcohol-free reformulation, tablet and powder format development, and enzyme-based active systems to differentiate beyond conventional liquid rinses. We observed that Kenvue Inc.'s continued expansion of alcohol-free Listerine variants alongside its established alcohol-based Cool Mint line illustrates how established players are broadening formulation portfolios to retain consumers shifting away from traditional alcohol-based daily-use products.

Brand Extension Rather Than Large-Scale Consolidation Characterizes M&A Activity

M&A activity in the category remains selective relative to broader consumer health sector consolidation, with most companies expanding mouthwash portfolios through internal brand extension rather than large acquisitions. We found that continued line extension into alcohol-free, tablet, and clinical care formats is the primary mechanism through which established manufacturers are broadening category presence, rather than acquiring standalone specialty mouthwash brands.

Key Market Players

Our assessment identifies the following companies as the leading participants shaping competitive dynamics in the mouthwash market.

Kenvue Inc. Colgate-Palmolive Company The Procter & Gamble Company Haleon plc Unilever PLC Church & Dwight Co., Inc. Opella HealthCare Group SAS Cooper Consumer Health SAS Lion Corporation Sunstar Inc. LG Household & Health Care Ltd. Kao Corporation Amway Corp. Dabur India Limited Yunnan Baiyao Group Co., Ltd. Dentaid S.L. Pierre Fabre S.A. Perrigo Company plc Himalaya Wellness Company Curasept S.p.A.

Latest Developments

We observed the following recent developments shaping competitive positioning across the mouthwash market .

Date Event
June 2026 Kenvue’s LISTERINE introduced a new Extra Mild variant and an intensity-based portfolio spanning Extra Mild to Intense across the U.S. The launch targets consumers seeking gentler taste without sacrificing efficacy, expanding mouthwash choice and addressing sensory preferences that can influence routine use and category penetration.
March 2026 Haleon launched parodontax Gum Strengthen & Protect toothpaste and mouthwash with hyaluronic acid in the U.S. The alcohol-free Icy Mint mouthwash is formulated to kill plaque bacteria along the gumline, support a stronger gum seal and provide extra freshness, extending parodontax’s specialized preventive gum-care positioning.
November 2025 Sunstar reported that plant-based and recycled plastics accounted for 27% of its product containers and packaging in 2024 , exceeding its 25% target for 2025. Sunstar attributed the progress mainly to expanded use of plant-based plastics in mouthwash bottles in Japan, highlighting sustainability-focused packaging innovation in the mouthwash category.
August 2025 Kao launched Clear Clean Toromi Liquid, a novel thickened mouthwash designed to adhere to teeth and gums longer than conventional rinses. The product claims about 5.2 times greater adhesion versus a conventional Clear Clean rinse and launched through selected Japanese retailers, highlighting texture-led mouthwash innovation.

Investment Opportunities

Capital Inflows Concentrate on Reformulation and Direct-to-Consumer Channel Development

Capital inflows are concentrated in alcohol-free reformulation research and direct-to-consumer e-commerce channel development, as manufacturers seek to retain consumers migrating away from traditional alcohol-based products. We observed that established manufacturers continue allocating research and development budgets toward essential oil and enzyme-based active systems, reflecting sustained brand investment in premium and clinical care product categories.

Retail and E-Commerce Infrastructure Investment Expands Addressable Reach

Retail and e-commerce infrastructure investment, particularly across Asia-Pacific and Latin America, is expanding the addressable base for mouthwash distribution. Our assessment indicates that expanding quick commerce delivery platforms and modern trade access is enabling both global manufacturers and regional specialists to reach a broader base of price-sensitive and premium-seeking households alike.

ESG Considerations Favor Ingredient Transparency and Packaging Reduction

Environmental, social, and governance considerations increasingly favor manufacturers demonstrating ingredient transparency and reduced plastic packaging commitments. We found that investors and regulators are prioritizing companies showing measurable progress on formulation safety disclosure and sustainable packaging formats such as tablets and concentrates, aligning capital allocation with broader consumer trust expectations across the mouthwash value chain.

Key Benefits for Stakeholders

Industry Leaders Gain Segmented Demand Data to Prioritize Portfolio Investment

This report equips mouthwash manufacturer and distributor leadership with segmented demand data, competitive benchmarking, and regional growth projections to prioritize capital allocation across product portfolios. NMSC's analysis indicates that decision-makers can use the segmentation and driver-restraint analysis to align product development timing with consumer preference and regulatory pressures shaping their specific product and geography focus.

Investors Gain Independently Derived Sizing to Support Valuation Work

Investors and financial analysts gain access to independently derived market sizing, CAGR trajectories, and competitive landscape analysis supporting valuation and diligence work across global consumer health leaders and specialty dental-channel brands. Our assessment indicates that the regional and segment-level detail supports comparative analysis of growth exposure across public and private company portfolios.

Technology and Product Teams Gain Segmentation to Guide Formulation Priorities

Technology vendors and product teams can use the segmentation by active ingredient, alcohol status, and packaging format to identify underserved product categories and prioritize reformulation versus new product development investment. We observed that the driver-restraint and opportunity analysis directly informs go-to-market sequencing across regions with differing regulatory and adoption maturity.

Key Market Segments Evaluated

By Product Format

  • Liquid
  • Ready-to-use liquid
  • Concentrated liquid
  • Dissolvable and solid
  • Tablet
  • Powder and strip
  • Other formats

By Primary Purpose

  • Multi-Benefit
  • Fresh Breath
  • Gum Health
  • Anticavity
  • Sensitivity Relief
  • Whitening
  • Dry Mouth Relief
  • Clinical Care

By Lead Active Ingredient

  • Essential oils
  • Cetylpyridinium chloride
  • Chlorhexidine
  • Fluoride compounds
  • Peroxides and chlorine dioxide
  • Zinc and metal salts
  • Desensitizing agents
  • Botanical extracts
  • Enzymes and biologics
  • Other actives and non-medicated

By Alcohol Status

  • Alcohol-Free
  • Alcohol-Based

By End User

  • Adult
  • Pediatric
  • Geriatric

By Route to Market

  • Offline Retail
  • Online Retail
  • Direct Selling
  • Professional and Institutional

By Packaging Format

  • Bottles
  • Pouches and sachets
  • Unit-dose
  • Other packaging

By Price Tier

  • Value
  • Mid
  • Premium
  • Super-premium

Conclusion & Recommendations

The long-term outlook remains steadily positive, with the market expected to grow from USD 10.49 billion in 2026 to USD 19.72 billion by 2035 at a 7.26% CAGR. We observed that structural drivers, including rising oral disease prevalence and alcohol-free reformulation adoption, are durable rather than cyclical, supporting sustained growth across clinical care and online retail categories through the forecast period.

Manufacturers Should Prioritize Reformulation and Format Diversification

Manufacturers should prioritize alcohol-free reformulation and tablet or powder format expansion that address consumer preference shifts, while pursuing clinical-strength positioning to capture premium price tiers. Our assessment indicates that companies combining broad reformulation capability with dentist-endorsed credibility will be best positioned to defend share as competitive intensity rises across commoditizing multi-benefit categories.

Investment Attractiveness Is Strongest in Clinical Care and Online Distribution

The market presents steady investment characteristics given its durable demand base tied to global oral disease prevalence and expanding premium and digital distribution categories. We found that clinical care formulations and online retail distribution, growing at 17.3% and 13.5% CAGR respectively, represent the most attractive entry points for growth-focused investors and strategic acquirers.

Market Shifts and Key Risks Center on Reformulation Pace and Compliance

Stakeholders should monitor the pace of alcohol-free reformulation adoption and the low daily-use compliance that continues to constrain category penetration relative to toothbrushing. Our analysis shows that consumer misconceptions about alcohol-based product efficacy remain a key risk to premium reformulated product adoption in several emerging markets, while price sensitivity continues to limit premium tier growth in developing economies.

Growth Pathways Center on Reformulation, Format Innovation, and Channel Expansion

Companies should prioritize growth pathways centered on alcohol-free reformulation, tablet and powder format innovation, and online retail expansion into Asia-Pacific and Latin American growth markets. NMSC's analysis indicates that these pathways offer the most direct route to capturing the USD 9.23 billion absolute dollar opportunity identified between 2026 and 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market Growth Analysis
  • Historical sales value and volume analysis of mouthwash across product format, primary purpose, and price tier.
  • Identifies high-growth formats and purposes to guide portfolio and investment priorities.
Company-Level Sales Volume Analysis
  • Company-level mouthwash unit and litre shipment benchmarking by product format, alcohol status, and packaging format.
  • Highlights manufacturer scale differences and supports competitive positioning decisions.
Company-Level Product Share Analysis
  • Brand and product-line share analysis of leading mouthwash players by primary purpose, lead active ingredient, and price tier.
  • Reveals share gaps and white-space positioning opportunities across therapeutic and cosmetic ranges.
Active Ingredient Positioning Assessment
  • Mapping of lead active ingredients (such as cetylpyridinium chloride, chlorhexidine, essential oils, fluoride) to primary purpose, alcohol status, and regulatory classification by country.
  • Guides reformulation, claim strategy, and new product development aligned with regulatory and consumer trends.
Alcohol-Free Transition Opportunity Analysis
  • Alcohol-free versus alcohol-based mouthwash adoption tracking by end user and region, with key brand launches and regulatory or cultural drivers.
  • Prioritizes alcohol-free line extensions and markets, including religion-sensitive and pediatric segments.
Route-to-Market and Price Tier Benchmarking
  • Retail price-point and pack-size benchmarking of leading mouthwash brands across route to market, packaging format, and price tier.
  • Supports pricing architecture, channel strategy, and packaging decisions for market entry and expansion.

FAQs

About the Author

Mihul Sharma

Mihul Sharma

Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Henri Knyphausen

HENRI KNYPHAUSEN

Partner at Singulier [Ex-BCG]
Singulier

I recently engaged NEXTMSC.com for a commercial due diligence project within the intralogistics sector, and I am pleased to provide a reference based on my experience. In utilizing NEXTMSC.com's services, I found their report to offer valuable insights into market dynamics and key industry players. The initial report provided a solid foundation for our analysis. However, as we were investigating a smaller target in the market, and I had specific customization requests requiring additional research. These requests included detailed information on product portfolios of various players and sub-market sizes, both inclusive and exclusive of certain product categories. NEXTMSC.com demonstrated commendable responsiveness and agility in accommodating these customization requests. Within a timeframe of 1-2 weeks, they delivered a revised report that met our specific needs. Furthermore, they were receptive to my follow-up inquiries, ensuring clarity and understanding of the data provided. The final deliverable significantly contributed to our due diligence efforts. One of NEXTMSC.com's notable strengths lies in their qualitative research capabilities. However, for future engagements, I would recommend the inclusion of a quantified market model in Excel format. Such a model would offer the ability to conduct in-depth analyses and explore various market segments, including country-specific data and subcomponent breakdowns. Based on my positive experience, I would not hesitate to work with NEXTMSC.com again. Their responsiveness, willingness to accommodate customization requests, and commitment to delivering actionable insights make them a reliable partner for commercial research projects.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖