Public Cloud in BFSI Market By Offering Type (Cloud Service Revenue and Others), By Application (Core Banking, Digital Banking, Payments Processing, Lending, and Others), By End User Vertical (Banking, Insurance, Capital Markets and Investment Services, and Others), By Enterprise Size (Large Enterprises, Mid-Size Enterprises, and Others), and By Provider Type (Hyperscaler Platforms, Cloud Service Providers and Telco Clouds, and Others) – Global Opportunity and Industry Forecast 2025–2030
Industry: Retail and Consumer | Publishing Date: September 18, 2025 | Last Updated: August 24, 2026 | No of Pages: N/A | No. of Tables: N/A | No. of Figures: N/A | Format: PDF | Report Code: RC3487
Public Cloud in BFSI Industry Outlook
The global Public Cloud in BFSI Market size was valued at USD 79.80 billion in 2024, with an estimation of USD 92.73 billion in 2025 and is predicted to reach USD 196.45 billion by 2030 with a CAGR of 16.2% from 2025-2030.
Public cloud adoption in the BFSI sector is being propelled by tightening regulatory requirements, AI-driven innovation, and the shift toward digital banking. Strengthened compliance mandates and expanded oversight from financial regulators are positioning cloud solutions as critical for operational resilience.
The growing use of AI in fraud detection, risk analytics, and personalized services is driving demand for scalable, secure, and compliant infrastructure. At the same time, digital banking modernization and instant payment systems are reinforcing the need for low-latency, high-capacity platforms. While strict data sovereignty laws continue to pose challenges—particularly in multi-jurisdictional markets—open banking initiatives are creating opportunities for cloud-based API ecosystems, enabling faster innovation, stronger partnerships, and enhanced customer experiences.
Regulatory Compliance & Operational Resilience Drive the Public Cloud in BFSI Market Growth
In the banking, financial services, and insurance (BFSI) sector, tightening regulatory frameworks are acting as a catalyst for public cloud migration.
The EU’s Digital Operational Resilience Act (DORA), set to take effect in January 2025, introduces rigorous requirements for incident reporting, resilience testing, and ICT third-party provider oversight capabilities that modern public cloud infrastructures are inherently designed to support.
Simultaneously, bodies such as the European Central Bank (ECB) and the UK’s Financial Conduct Authority (FCA) have broadened their supervision of critical technology vendors, underscoring the need for secure, compliant, and resilient cloud environments. These evolving mandates are positioning public cloud solutions as a strategic imperative for BFSI institutions aiming to maintain operational continuity, meet compliance obligations, and mitigate systemic risk.
AI-Driven Innovation Fuels Public Cloud Growth in the BFSI Industry
The rapid adoption of artificial intelligence in banking, financial services, and insurance spanning fraud detection, risk analytics, personalized banking, and AI-powered assistants is driving demand for the scalable compute, advanced data platforms, and secure tooling best delivered through public cloud.
According to the World Economic Forum, AI investment in financial services is set to nearly triple from USD 35 billion in 2023 to USD 97 billion by 2027, with 32–39% of sector tasks potentially automated or augmented. Such workloads are dynamic, data-intensive, and latency-sensitive, making public cloud elasticity and managed AI services essential. Furthermore, as responsible AI governance becomes critical, covering privacy, cybersecurity, and transparency public cloud platforms offer integrated compliance frameworks and security features that enable BFSI institutions to deploy AI responsibly while maintaining agility in an evolving regulatory landscape.
Digital Banking Transformation Accelerates the Public Cloud in BFSI Market Demand
The rapid expansion of 24×7 digital banking, instant payment systems such as FedNow, RTP, along with ongoing cross-border payment modernization, is fueling demand for low-latency infrastructure, elastic capacity, and real-time data processing capabilities ideally suited to public cloud environments.
Financial institutions are leveraging cloud-native architectures to replace legacy core systems, enabling faster product launches, greater operational agility, and improved customer experiences. This modernization not only supports the seamless execution of high-volume, real-time transactions but also positions BFSI players to adapt quickly to evolving payment regulations and customer expectations, reinforcing public cloud’s role as a strategic enabler in the digital banking era.
Data Sovereignty and Compliance Concerns the Public Cloud in BFSI Market Expansion
Strict data sovereignty regulations and evolving compliance requirements remain a key barrier to public cloud adoption in the banking, financial services, and insurance sector. Many jurisdictions mandate that sensitive financial and personal data be stored and processed within national or regional borders, creating complexities for deploying cloud workloads across multiple geographies.
Compliance with frameworks such as the EU’s GDPR, India’s Digital Personal Data Protection Act, and sector-specific guidelines from central banks requires customized infrastructure configurations, local data centers, and rigorous audit processes. These constraints can limit the scalability benefits of global public cloud platforms, increase operational costs, and slow the pace of migration, particularly for institutions operating in highly regulated or multi-jurisdictional environments.
Open Banking and API Ecosystems Create Growth Opportunities for Public Cloud in BFSI Market
The global shift toward open banking driven by regulations such as the EU’s PSD2, the UK’s Open Banking Standard, and emerging frameworks in markets like Australia, Singapore, and India is unlocking a major opportunity for public cloud adoption in the BFSI sector. Open banking relies on secure, scalable, and interoperable API ecosystems to enable data sharing between banks, fintechs, and third-party providers, supporting innovative services like personalized financial management, embedded finance, and cross-platform payments.
Public cloud platforms are ideally positioned to host these API-driven ecosystems, offering flexible infrastructure, rapid deployment capabilities, and built-in security compliance. As more markets adopt open finance principles and customer demand for seamless digital experiences grows, BFSI institutions leveraging public cloud can accelerate innovation, expand partnerships, and gain a competitive edge in the evolving digital financial landscape.
Market Segmentation and Scope of Study
The public cloud in BFSI market report is divided on the basis of component, technology, deployment model, enterprise size, application, end user, and region. On the basis of component, the market is grouped into software and services. On the basis of technology, the market is categorized into infrastructure as a service, platform as a service, software as a service, and others. On the basis of deployment model, the market is grouped into single-cloud, multi-cloud, and hybrid-cloud. On the basis of enterprise size, the market is categorized into large enterprises and small & medium enterprises. On the basis of application, the market is grouped into data storage & infrastructure, disaster recovery / backup, payment processing platforms, customer relationship management, analytics / AI-driven tools, and others. On the basis of end user, the public cloud in BFSI market is categorized into NBFCs, banking, and others. Regional breakdown and analysis of each of the aforesaid segments includes regions comprising Asia-Pacific, North America, Europe, and Rest of the World (RoW).
Geographical Analysis
In North America, the rapid deployment of AI in banking and financial services is a primary driver of public cloud adoption. Institutions are leveraging cloud-based AI for fraud detection, risk modeling, and hyper-personalized customer experiences. For example, in February 2024, BNY Mellon expanded its strategic alliance with Microsoft to migrate analytics workloads to the cloud and co-develop capital markets data services, enabling faster insights and operational agility. These developments underscore how AI innovation is fueling BFSI cloud demand in the region.
Europe commands a substantial portion of the public cloud in BFSI market, supported by strong regulatory momentum and a focus on operational resilience. The Digital Operational Resilience Act, effective January 2025, compels financial institutions to strengthen ICT third-party oversight, conduct resilience testing, and enhance incident reporting.
In parallel, expanded oversight by UK and EU supervisory bodies ensures cloud services meet strict compliance and security requirements. This regulatory clarity is accelerating migration to public cloud infrastructure, enabling BFSI organizations across the region to modernize systems, safeguard critical operations, and align with evolving digital finance standards.
Asia-Pacific commands a rapidly growing share of the global public cloud in BFSI market, underpinned by aggressive digital banking adoption, instant payments expansion, and large-scale cloud infrastructure investments.
Governments and regulators across the region are promoting cashless transactions, open banking frameworks, and cross-border payment modernization, creating strong demand for low-latency, scalable, and secure cloud services. Massive investments in new data centers and cloud regions are boosting local capacity, ensuring compliance with data residency laws, and enabling BFSI institutions to deliver real-time, AI-enabled financial services. These trends position Asia-Pacific as the fastest-growing region and a future leader in global BFSI cloud adoption.
The Rest of the World, covering Latin America, the Middle East, and Africa is witnessing a surge in public cloud adoption in BFSI as regional financial authorities introduce stricter cybersecurity standards and operational resilience guidelines.
The rise in sophisticated cyber threats, combined with the need to ensure uninterrupted financial services in areas prone to geopolitical or climate-related disruptions, is prompting institutions to turn to public cloud platforms with advanced security, redundancy, and disaster recovery capabilities. These demands are fostering rapid investment in secure cloud infrastructure, positioning the region for accelerated BFSI cloud growth over the next few years.
Strategic Innovations Adopted by Key Players
Key players in public cloud in the BFSI industry are accelerating global growth through AI-driven product innovation, regional infrastructure expansion, and strategic partnerships.
-
In August 2025, NTT DATA has announced a strategic global partnership with Google Cloud to accelerate agentic AI adoption and cloud-native modernization in the banking and financial services sector. The collaboration focuses on enabling banks and NBFCs to execute full-stack cloud migrations while integrating AI-driven tools for compliance, fraud detection, and real-time decision-making. By combining NTT DATA’s Smart AI Agent ecosystem with Google Cloud’s secure, scalable infrastructure, the initiative aims to enhance regulated workload performance and drive broader public cloud adoption in global BFSI markets.
-
In July 2025, Google Cloud has strengthened its position in public cloud in BFSI market through a strategic collaboration with Ecobank, a leading pan-African financial services group. The partnership focuses on deploying advanced analytics and AI to transform financial services and promote digital empowerment across the continent. This initiative, alongside Google Cloud’s regional infrastructure expansions and specialized toolkits for fraud detection, risk management, and payments modernization, is expected to accelerate cloud adoption among banks and insurers seeking secure, scalable, and AI-ready platforms.
Key Benefits
-
The report provides quantitative analysis and estimations of the public cloud in BFSI market from 2025 to 2030, that assists in identifying the prevailing market opportunities.
-
The study comprises a deep-dive analysis of the current and future public cloud in BFSI market trends to depict prevalent investment pockets in the market.
-
Information related to key drivers, restraints, and opportunities and their impact on the public cloud in market is provided in the report.
-
Competitive analysis of the players, along with their market share is provided in the report.
-
SWOT analysis and Porters Five Forces model is elaborated in the study.
-
Value chain analysis in the public cloud in BFSI market study provides a clear picture of roles of stakeholders
Public Cloud in BFSI Market Key Segments
By Offering Type
-
Cloud Service Revenue
-
Infrastructure As A Service
-
Compute
-
Block Storage
-
Object Storage
-
Networking & Connectivity
-
Content Delivery & Load Balancing
-
-
Platform As A Service
-
Application Development Platform
-
Data & Analytics Platform
-
Integration & Middleware
-
Container & Orchestration
-
Function & Event Platform
-
-
Software As A Service
-
Packaged Business Applications
-
Industry Specific Applications
-
Core Banking As A Service
-
-
-
Cloud Related Services Revenue
-
Professional Services
-
Consulting & Advisory
-
Implementation & Migration
-
Support & Training
-
-
Managed Services
-
Managed Infrastructure Services
-
Managed Application Services
-
Managed Security Services
-
Optimization & Maintenance Services
-
-
By Application
-
Core Banking Systems
-
Digital Banking & Channels
-
Mobile Banking Front End
-
Internet Banking Front End
-
Contact Center & Chatbot Platforms
-
-
Payments Processing & Settlement
-
Card Processing & Switches
-
Merchant Acquiring Platforms
-
Card Issuing Platforms
-
Wallets & Digital Payment Apps
-
Real Time Clearing & Settlement
-
-
Lending & Loan Management
-
Loan Origination & Underwriting
-
Mortgage Platforms
-
Loan Servicing & Collections
-
-
Treasury & Cash Management
-
Trading & Capital Markets Systems
-
Order Management & Execution
-
Market Data & Feeds
-
Post Trade Processing
-
-
Insurance Policy & Claims Systems
-
Policy Administration
-
Claims Intake & Processing
-
Underwriting & Pricing
-
-
Risk Management & Regulatory Reporting
-
Fraud Detection & Anti Money Laundering
-
Customer Onboarding & KYC
-
Data Analytics & Business Intelligence
-
Reporting & Dashboards
-
Model Training & Scoring
-
-
Data Storage & Backup
-
Data Lake & Warehouse
-
Archival & Retention
-
-
Disaster Recovery & Business Continuity
-
Support & Back Office Systems
-
Other Applications
By End User Vertical
-
Banking
-
Retail Banking
-
Corporate & Commercial Banking
-
Universal Banks
-
-
Insurance
-
Life Insurance
-
General Insurance
-
Reinsurance
-
-
Capital Markets & Investment Services
-
Investment Banks
-
Brokerage Firms
-
Asset Managers
-
-
Payments Processors & Card Networks
-
Fintech Companies & Neobanks
-
Non Bank Financial Companies
-
Treasury & Asset Managers
-
Other Financial Institutions
By Enterprise Size
-
Large Enterprises
-
Mid Size Enterprises
-
Small & Medium Enterprises
-
Startups & Fintechs
-
By Provider Type
-
Hyperscaler Platforms
-
Cloud Service Providers & Telco Clouds
-
Managed Service Providers
-
Independent Software Vendors & SaaS Providers
By Region
-
North America
-
The U.S
-
Canada
-
Mexico
-
-
Europe
-
The UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Netherlands
-
Finland
-
Sweden
-
Norway
-
Russia
-
Rest of Europe
-
-
Asia-Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Indonesia
-
Singapore
-
Taiwan
-
Thailand
-
Rest of Asia-Pacific
-
-
Rest of the World
-
Latin America
-
Middle East
-
Africa
-
Key Players
-
Amazon Web Services, Inc.
-
Microsoft Corporation
-
Google LLC
-
Oracle Corporation
-
International Business Machines Corporation (IBM)
-
Alibaba Cloud Computing Co., Ltd.
-
Tencent Cloud
-
Huawei Technologies Co., Ltd.
-
Baidu, Inc.
-
OVH Groupe SAS
-
NTT Ltd.
-
Akamai Technologies, Inc.
-
Orange S.A.
-
Rackspace US, Inc.
-
DigitalOcean Holdings, Inc.
-
China Telecom Global Limited
-
Telefónica S.A.
-
Fujitsu Limited
-
Scaleway
-
T-Systems International
Report Scope and Segmentation
|
Parameters |
Details |
|
Market Size in 2025 |
USD 92.73 Billion |
|
Revenue Forecast in 2030 |
USD 196.45 Billion |
|
Growth Rate |
CAGR of 16.2% from 2025 to 2030 |
|
Analysis Period |
2024–2030 |
|
Base Year Considered |
2024 |
|
Forecast Period |
2025–2030 |
|
Market Size Estimation |
Billion (USD) |
|
Growth Factors |
|
|
Countries Covered |
28 |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
|
Customization Scope |
Free customization (equivalent to up to 80 working hours of analysts) after purchase. Addition or alteration to country, regional, and segment scope. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |


About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

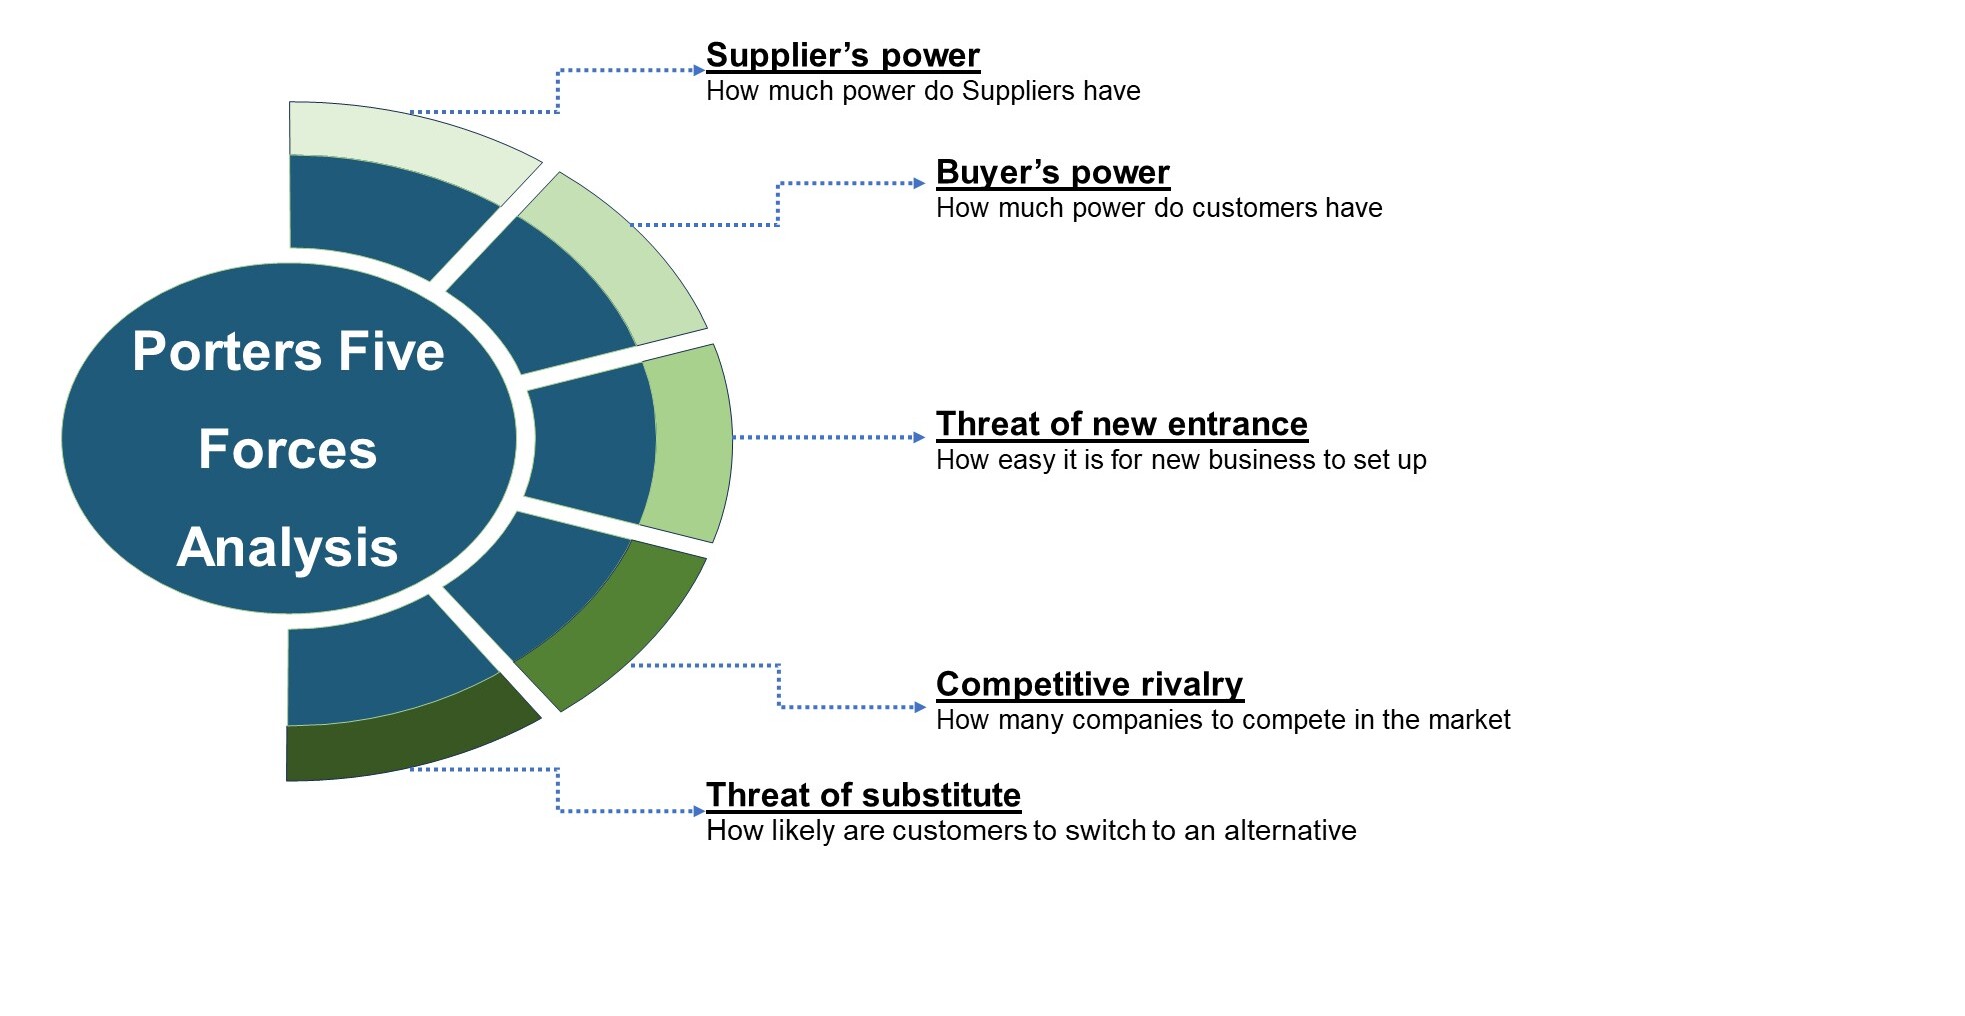
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.



 Speak to Our Analyst