What's Driving the Board Games Market Boom in 2025?
Introduction
The global board games market is undergoing a structural transformation — one driven not by nostalgia alone, but by deliberate corporate strategy, platform convergence, and a measurable shift in the demographic profile of the average tabletop consumer. According to Next Move Strategy Consulting's Board Games Market report, the global board games is projected to reach USD 24.99 billion by 2030, growing at a CAGR of 8.7% from 2024 to 2030.
This trajectory is being shaped by a confluence of forces: major publishers pivoting their entire business models toward adult and collector-oriented gaming, streaming platforms licensing board game IP to reach new audiences, and crowdfunding platforms evolving into primary distribution channels for independent studios. The result is a market that is simultaneously consolidating at the top and diversifying at the base — a dynamic that presents distinct opportunities and risks for investors and operators across the value chain.
For More Information: Download FREE Sample on Board Games Market Report
From Toy Shelves to Collector Ecosystems: The Adult Gaming Pivot Reshaping the Board Games Market
Hasbro's Strategic Reorientation: A Bellwether for the Industry
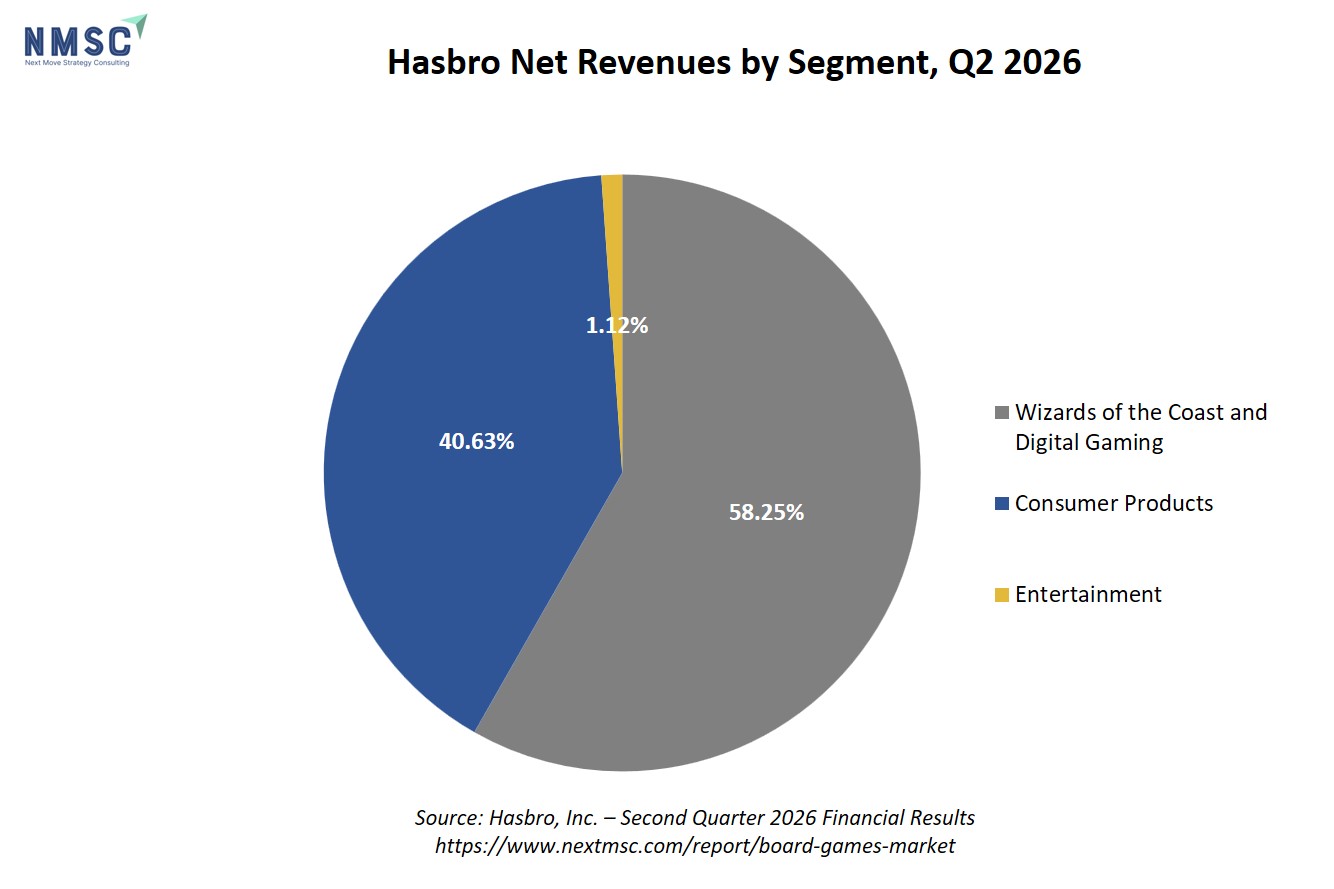
The most consequential signal in the board games market in 2026 came not from a new game launch, but from a fundamental corporate restructuring. In February 2026, Hasbro CEO Chris Cocks told Bloomberg that up to 80% of Hasbro's business and 95% of its investment would be redirected toward the company's "collector/gamified" segment — a category anchored by Magic: The Gathering and Dungeons & Dragons rather than traditional mass-market toys.
This was not a marginal adjustment. Hasbro simultaneously announced plans to reduce its reliance on Chinese manufacturing to 30% of revenue by 2026, down from a significantly higher baseline — a supply chain restructuring that directly reduces the company's exposure to tariff volatility while concentrating investment in IP-driven, digitally extensible game formats, as reported by Reuters in October 2025.
The market validated this strategy decisively. In July 2026, Hasbro reported second-quarter results that beat analyst estimates, with shares surging as much as 14% — the company's strongest single-day gain in years — and management raised its full-year 2026 outlook, citing Magic: The Gathering as the primary growth engine.
The Hasbro pivot illustrates a mechanism that NextMSC primary research and analysis identifies as central to the board games market's growth trajectory: the monetization of adult hobbyist spending, which commands significantly higher average transaction values than mass-market family games and generates recurring revenue through expansions, accessories, and organized play ecosystems.
IP Licensing as a Demand-Generation Engine
Parallel to Hasbro's internal restructuring, the industry is witnessing an acceleration of cross-platform IP licensing that is bringing board games to audiences who would not have discovered them through traditional retail channels.
In October 2026, Czech Games Edition (CGE) announced that its social deduction game Codenames — which has sold nearly 20 million physical copies globally — made its Netflix debut after the streaming platform approached CGE for a licence and ultimately hired the publisher to develop the game format for the platform. This deal is structurally significant: Netflix's involvement does not merely provide a licensing fee — it exposes Codenames to Netflix's global subscriber base as a discovery mechanism, converting passive viewers into active physical game purchasers. A CGE spokesperson confirmed that "the branding benefits and opportunity to reach a new audience" were central to the decision, signaling that publishers are now treating streaming platforms as top-of-funnel marketing infrastructure rather than simply revenue sources.
In October 2026, Renegade Game Studios and Hasbro expanded their tabletop licensing agreement to include Axis & Allies, Acquire, Diplomacy, Heroscape, Robo Rally, and Ikusa, with new games and expansions planned for 2027 and beyond. This arrangement allows Hasbro to monetize dormant IP through a specialist publisher without diverting internal resources from its core Magic: The Gathering and D&D priorities — a capital-efficient model that other major IP holders are positioned to replicate.
The television adaptation of Werewolves of Miller's Hollow, the Zygomatic-published social deduction game, attracted more than two million viewers at its Canal+ launch in 2024 — the best-ever launch for a new Canal+ creation at the time — and the show received an International Emmy nomination in September 2026, further demonstrating the bidirectional value of board game IP in the entertainment ecosystem.
NMSC Strategic Perspective: The Collector Economy and Its Market Implications
NextMSC primary research and analysis identifies the adult (18+) segment as the fastest-growing demographic cohort within the board games market, driven by three reinforcing dynamics: rising disposable income among millennials who grew up with hobby gaming, the social function of tabletop gaming as an offline counterweight to digital fatigue, and the emergence of premium price tiers (above USD 100) that generate disproportionate revenue relative to unit volume.
The Hasbro pivot toward the "collector/gamified" model is not an isolated corporate decision — it reflects a structural shift in where value is being created within the board games market. Publishers that can build recurring engagement ecosystems around their IP (through organized play, expansions, digital companions, and licensed merchandise) are capturing a larger share of consumer wallet than those competing solely on unit price. This dynamic is compressing margins for mass-market producers while expanding them for hobby and premium tier operators.
Section Summary:
The board games market's growth is being structurally reinforced by deliberate corporate strategy, not cyclical consumer trends.
-
Hasbro's focus on its collector and gaming businesses highlights the growing strategic importance of established gaming brands, including Magic: The Gathering and Dungeons & Dragons.
-
Netflix's engagement with Codenames as a development partner (not merely a licensor) establishes streaming platforms as a new demand-generation channel for physical board games, with the title approaching 20 million physical copies sold.
-
The Renegade-Hasbro licensing expansion demonstrates a capital-efficient model for monetizing dormant IP that other major publishers are positioned to replicate.
-
The adult (18+) segment and premium price tier (above USD 100) are generating revenue growth disproportionate to their unit volume, according to NextMSC primary research and analysis.
Industry Impact Analysis
Crowdfunding: Structural Maturation, Not Contraction
The board games crowdfunding ecosystem recorded 1,021 successful projects in 2025 with an 84% success rate, raising a combined USD 173 million — a decline from USD 185 million in 2024, according to crowdfunding analytics published on BoardGameGeek by analyst A.B. West. The revenue decline, however, masks a more nuanced structural shift: the total number of successful campaigns increased and the success rate improved, indicating that the crowdfunding channel is becoming more selective rather than contracting.
Gamefound's emergence as the dominant revenue platform is the most significant structural development within this channel. In 2025, Gamefound accounted for 22% of total campaigns but 53% of total crowdfunding revenue, with The Witcher: Legacy — a licensed IP title — raising USD 10.5 million as the single largest campaign of the year. The average backer spend among the top 30 funded campaigns was approximately USD 230 per backer — a figure more consistent with hobby wargaming than traditional family board games, confirming that crowdfunding has become a premium channel for high-engagement, high-spend consumers.
Publisher Consolidation and Financial Stress
The crowdfunding channel's maturation is occurring alongside significant financial stress among mid-tier publishers. CMON — one of the industry's largest crowdfunded board game publishers — completed a USD 19 million capital raise in September 2026 after recording losses of almost USD 23 million across 2024 and 2025. The capital injection provides financial breathing room but also signals that the economics of miniature-heavy, crowdfunded publishing — which requires significant upfront manufacturing investment — are under pressure as backer acquisition costs rise and delivery timelines extend.
Steamforged Games, another prominent crowdfunded publisher, faced mounting criticism in October 2026 over unresolved refund requests and dwindling project updates following workforce reductions and a strategic refocus toward its Warmachine miniatures line. These developments are creating reputational risk for the crowdfunding channel as a whole, which may accelerate the consolidation of backer trust around established platforms and publishers with proven delivery records.
Live Events as Market Validation
Physical gaming events are providing a counterpoint to the financial turbulence among publishers. The UK Games Expo — one of Europe's largest tabletop gaming conventions — recorded unique attendance of more than 51,000 in 2026, representing a surge of almost 65% since 2023, as reported by BoardGameWire in September 2026. This attendance trajectory directly contradicts the narrative that digital entertainment is displacing physical gaming — it suggests instead that live gaming events function as discovery and community-building infrastructure that sustains long-term consumer engagement with the physical format.
The Asian Board Games Festival, scheduled for December 2026 in Singapore, is positioned as the largest English-speaking board games festival in Asia, reflecting the growing institutional recognition of Asia-Pacific as a strategic growth market for the global board games industry.
Section Summary:
-
The board games market's competitive landscape is bifurcating between well-capitalized IP holders and financially stressed mid-tier publishers.
-
Crowdfunding raised USD 173 million across 1,021 successful projects in 2025, with Gamefound capturing 53% of total revenue despite representing only 22% of campaigns — a concentration of premium spend that favors licensed IP titles.
-
CMON's USD 19 million capital raise after USD 23 million in losses signals that the economics of miniature-heavy crowdfunded publishing require structural reform.
-
UK Games Expo's 65% attendance growth since 2023 to 51,000+ unique visitors in 2026 demonstrates that physical gaming events are expanding the market's consumer base rather than competing with it.
-
Publisher financial stress is accelerating consolidation around established platforms and IP holders with proven delivery records.
Pros and Cons of Recent Market Developments
|
Development |
Pros |
Cons |
|
Hasbro's pivot to adult/collector gaming (80% of business, 95% of investment) |
Unlocks higher average transaction values and recurring revenue through expansions and organized play; reduces tariff exposure by shifting away from mass-market toy manufacturing |
Narrows addressable market by de-emphasizing family and children's segments; concentrates revenue risk on a single IP ecosystem (Magic: The Gathering) |
|
Netflix-Codenames licensing and development deal |
Exposes physical board games to Netflix's global subscriber base as a discovery channel; validates streaming platforms as top-of-funnel marketing infrastructure for publishers |
Revenue from streaming deals may not offset IP development costs; risk of brand dilution if the digital adaptation underperforms with mainstream audiences |
|
Renegade-Hasbro tabletop licensing expansion (Axis & Allies, Diplomacy, Heroscape, and others) |
Allows Hasbro to monetize dormant IP without internal resource allocation; provides Renegade with established brand recognition across multiple titles simultaneously |
Licensing dependency creates vulnerability if either party exits the agreement; new titles must compete in an already crowded hobby market |
|
CMON's USD 19M capital raise |
Provides financial stability to complete delayed projects and restore backer confidence; signals continued institutional investor interest in the board games sector |
Capital raise dilutes existing shareholders; underlying operational losses of USD 23M across 2024–2025 indicate structural cost issues that capital alone cannot resolve |
|
Gamefound capturing 53% of crowdfunding revenue from 22% of campaigns |
Concentrates premium backer spend on platforms with stronger delivery infrastructure; raises the quality bar for new campaigns and reduces low-quality project noise |
Increases barriers to entry for independent designers without established audiences; Kickstarter's declining revenue share may reduce its investment in the tabletop category |
|
UK Games Expo attendance surge (65% growth to 51,000+ since 2023) |
Demonstrates sustained consumer demand for physical gaming experiences; provides publishers with direct-to-consumer sales and marketing opportunities at scale |
Event-driven demand may not translate proportionally to sustained retail sales; high attendance growth creates logistical and capacity challenges for organizers |
Future Outlook & Forecast
Market Trajectory: USD 24.99 Billion by 2030
According to NextMSC primary research and analysis, the global board games market is on a sustained growth trajectory, projected to reach USD 24.99 billion by 2030 at a CAGR of 8.7%. This growth is underpinned by three structural forces that NMSC's model weights as primary drivers: the monetization of adult hobbyist spending through premium and hobby price tiers, the expansion of licensed IP into new consumer touchpoints (streaming, digital companions, organized play), and the geographic diversification of demand into Asia-Pacific markets where rising middle-class disposable income is converting latent interest in tabletop gaming into active purchasing.
The Supply Chain Reconfiguration Imperative
Hasbro's commitment to reducing Chinese manufacturing dependency to 30% of revenue — reported by Reuters in October 2025 — is a leading indicator of a broader supply chain reconfiguration that will affect the entire board games industry. Publishers that rely on Chinese manufacturing for miniature-heavy games face margin compression from tariff exposure, while those with diversified manufacturing footprints or digital-first product lines — card games, print-and-play formats, digital companion apps — are structurally advantaged in the current trade environment.
The Hospitality Channel: An Underappreciated Growth Vector
The board game café segment represents a distribution and discovery channel that is gaining institutional recognition. Luxembourg's hospitality industry association Horesca launched a formal initiative in September 2026 to re-establish tabletop gaming as a "vibrant part" of Luxembourg's hospitality culture, naming Pili Pili as its 2026 winner — a signal that hospitality operators across Europe are treating board games as a differentiated service offering rather than a novelty. As board game cafés expand their footprint across Europe and Asia-Pacific, they function as trial environments that convert casual players into committed purchasers — a demand-generation mechanism that benefits the entire market.
Asia-Pacific: The Next Volume Growth Engine
The Asian Board Games Festival's December 2026 edition in Singapore — positioned as the largest English-speaking board games festival in Asia — reflects the growing institutional infrastructure supporting the Asia-Pacific board games market. NextMSC primary research and analysis identifies Asia-Pacific as a key regional growth driver, supported by large child and teenage populations, rising disposable income among middle-class families in China and India, and increasing penetration of specialty hobby retail and online marketplace channels. The market in this region remains highly fragmented, with significant local player presence — a fragmentation profile that historically precedes consolidation as brand awareness and purchasing power mature.
The Crowdfunding Channel's Next Phase
The crowdfunding ecosystem's structural maturation — with Gamefound capturing 53% of revenue from 22% of campaigns in 2025 — suggests that the channel is evolving from a broad-based funding mechanism into a premium direct-to-consumer platform for high-engagement titles. Publishers that can build pre-launch communities, leverage licensed IP, and deliver on crowdfunding commitments will capture a disproportionate share of the USD 173 million+ annual crowdfunding revenue pool. Those that cannot manage delivery timelines and backer communication — as evidenced by the Steamforged situation — face reputational damage that extends beyond individual campaigns and erodes trust in the channel as a whole.
Section Summary:
The board games market's path to USD 24.99 billion by 2030 is supported by structural demand drivers that are becoming more, not less, entrenched.
-
The adult (18+) and premium price tier segments are generating revenue growth disproportionate to unit volume, according to NextMSC primary research and analysis, and Hasbro's corporate restructuring validates this as the industry's primary value-creation vector.
-
Supply chain reconfiguration away from Chinese manufacturing is a near-term margin risk for miniature-heavy publishers but a medium-term competitive advantage for those who complete the transition.
-
The board game café hospitality channel and live events (UK Games Expo: 51,000+ attendees in 2026) are functioning as demand-generation infrastructure that sustains long-term consumer engagement with physical formats.
-
Asia-Pacific's combination of demographic scale and rising disposable income positions it as the market's next volume growth engine, with Singapore's Asian Board Games Festival serving as a barometer of regional institutional momentum.
Next Steps for Stakeholders
For C-Level Executives and Publishers:
Audit IP portfolio for licensing optionality. The Codenames-Netflix deal and the Renegade-Hasbro licensing expansion demonstrate that dormant or underutilized IP can generate revenue through streaming, digital, and specialist publisher partnerships without diverting internal development resources. Publishers holding established game IP should conduct a systematic assessment of cross-platform licensing opportunities before competitors occupy those distribution channels.
Restructure supply chains before tariff exposure compounds. Hasbro's commitment to reducing Chinese manufacturing to 30% of revenue is a strategic template, not merely a Hasbro-specific response. Publishers with significant Chinese manufacturing exposure should model the margin impact of sustained tariff escalation and identify alternative manufacturing geographies — particularly for miniature-heavy product lines where per-unit costs are most sensitive to import duties.
Invest in crowdfunding delivery infrastructure before launching campaigns. The Steamforged and CMON situations demonstrate that crowdfunding revenue is contingent on delivery credibility. Publishers should not launch campaigns without the operational infrastructure to manage backer communication, manufacturing timelines, and refund processes — the reputational cost of failure now extends beyond individual campaigns to affect future fundraising capacity.
Treat live events as strategic marketing investments, not discretionary costs. UK Games Expo's 65% attendance growth since 2023 demonstrates that physical gaming events are expanding the market's consumer base. Publishers that reduce event presence to cut costs risk ceding discovery and community-building ground to competitors who maintain it.
For Investors:
Differentiate between IP-driven and manufacturing-dependent business models. The board games market's value creation is concentrating in IP-driven, digitally extensible formats (Magic: The Gathering, Codenames, D&D) rather than in manufacturing-intensive, mass-market toy production. Investment theses should reflect this structural bifurcation — the two business models carry fundamentally different margin profiles and tariff risk exposures.
Monitor the Asia-Pacific market for early-stage consolidation opportunities. NextMSC primary research and analysis identifies Asia-Pacific as a key regional growth driver. The market remains highly fragmented, with significant local player presence in China and India — a fragmentation profile that historically precedes consolidation as disposable income and brand awareness mature.
Use live event attendance data as a leading indicator of market health. UK Games Expo's 65% attendance growth since 2023 is a more reliable signal of sustained consumer demand than short-term retail sales data, which is subject to inventory cycle distortions. The Asian Board Games Festival's December 2026 Singapore edition will provide a comparable leading indicator for the Asia-Pacific region.
Conclusion
The global board games market is not simply growing — it is restructuring. The forces reshaping it in 2026 are specific and traceable: Hasbro's deliberate pivot toward adult collector gaming validated by a 14% share price surge on Q2 earnings, Netflix's entry as a board game development partner for Codenames, the Renegade-Hasbro licensing expansion across six dormant IP titles, CMON's USD 19 million capital raise after USD 23 million in losses, and the crowdfunding channel's concentration of revenue around premium licensed IP titles on Gamefound. Each of these developments reflects a market that is maturing in its value-creation logic — moving from volume-driven mass-market competition toward IP-driven, premium-tier ecosystem building.
According to NextMSC primary research and analysis, the global board games market is projected to reach USD 24.99 billion by 2030 at a CAGR of 8.7% — a trajectory supported by structural demand drivers across adult hobbyist spending, Asia-Pacific demographic growth, and the expanding role of streaming platforms and live events as demand-generation infrastructure. For investors and executives navigating this market, the critical distinction is between publishers building durable IP ecosystems and those competing on manufacturing cost alone. The former are positioned to capture the market's growth; the latter face structural margin pressure that capital alone cannot resolve.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment