Utility Pole Market Global Industry Analysis and Forecast (2026–2035)

The global Utility Pole Market size was valued at USD 38.20 billion in 2025 and is estimated at USD 40.65 billion in 2026, forecast to reach USD 72.55 billion by 2035, expanding at a 6.65% CAGR between 2026 and 2035. North America leads with approximately 36.1% share, while Wood Poles dominate all other pole types with approximately 37.2% share.
Download Free Sample PDF
Base Year (2025)
$38.20 Billion
Forecast (2035)
$72.55 Billion
CAGR (2026-2035)
6.7%
Top Region
North America

What Is the Utility Pole Market Size?

The global utility pole market size was valued at USD 38.20 billion in 2025 and is estimated at USD 40.65 billion in 2026, projected to reach USD 72.55 billion by 2035, expanding at a CAGR of 6.65% between 2026 and 2035, with North America holding approximately 36.1% share and Wood poles accounting for nearly 37.2% of 2025 revenue.

We observed that demand is broadening across grid modernization, wildfire-resilient pole replacement, and telecommunications infrastructure expansion as utilities and telecom operators prioritize durable, code-compliant pole structures across distribution, transmission, and network support applications.

Utility Pole Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast

Values in USD Billion

2025 $38.20 Billion
2025
2026 $40.65 Billion
2026
2027 $43.35 Billion
2027
2028 $46.24 Billion
2028
2029 $49.31 Billion
2029
2030 $52.59 Billion
2030
2031 $56.09 Billion
2031
2032 $59.82 Billion
2032
2033 $63.79 Billion
2033
2034 $68.04 Billion
2034
2035 $72.55 Billion
2035

Key Takeaways

By Pole Material: Wood held the largest share of approximately 37.2% (USD 14.20 Billion) in 2025; Composite is the fastest-growing sub-segment at 11.0% CAGR from 2026-2035.

By Application: Electric Distribution held the largest share of approximately 44.0% (USD 16.80 Billion) in 2025; Telecommunications is the fastest-growing sub-segment at 9.1% CAGR from 2026-2035.

By Ownership Model: Utility Owned held the largest share of approximately 64.4% (USD 24.60 Billion) in 2025; Telecom Owned is the fastest-growing sub-segment at 8.3% CAGR from 2026-2035.

Dominant Region: North America dominated with approximately 36.1% revenue share (USD 13.80 Billion) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 8.9% during 2026-2035.

Dominant Country: U.S. led with approximately USD 10.80 Billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 11.2% CAGR from 2026-2035.

What Does the Utility Pole Market Encompass?

The utility pole market encompasses wood, steel, concrete, composite, ductile iron, and hybrid pole structures deployed across electric distribution, transmission, telecommunications, street lighting, transportation, and industrial infrastructure applications. Our analysis shows that the market has evolved from predominantly wood pole installations toward diversified material adoption as utilities balance cost, durability, and wildfire-resilience requirements across aging grid infrastructure.
Regulatory frameworks including the U.S. Department of Energy's grid resilience funding programs and the National Electrical Safety Code shape pole design and replacement standards across covered geographies. We found that technology adoption trends, including smart pole sensors and composite material engineering, are accelerating differentiation among established pole manufacturers and specialty composite fabricators.

Supply Chain Structure of the Utility Pole Market

Supply Chain Structure of the Utility Pole Market

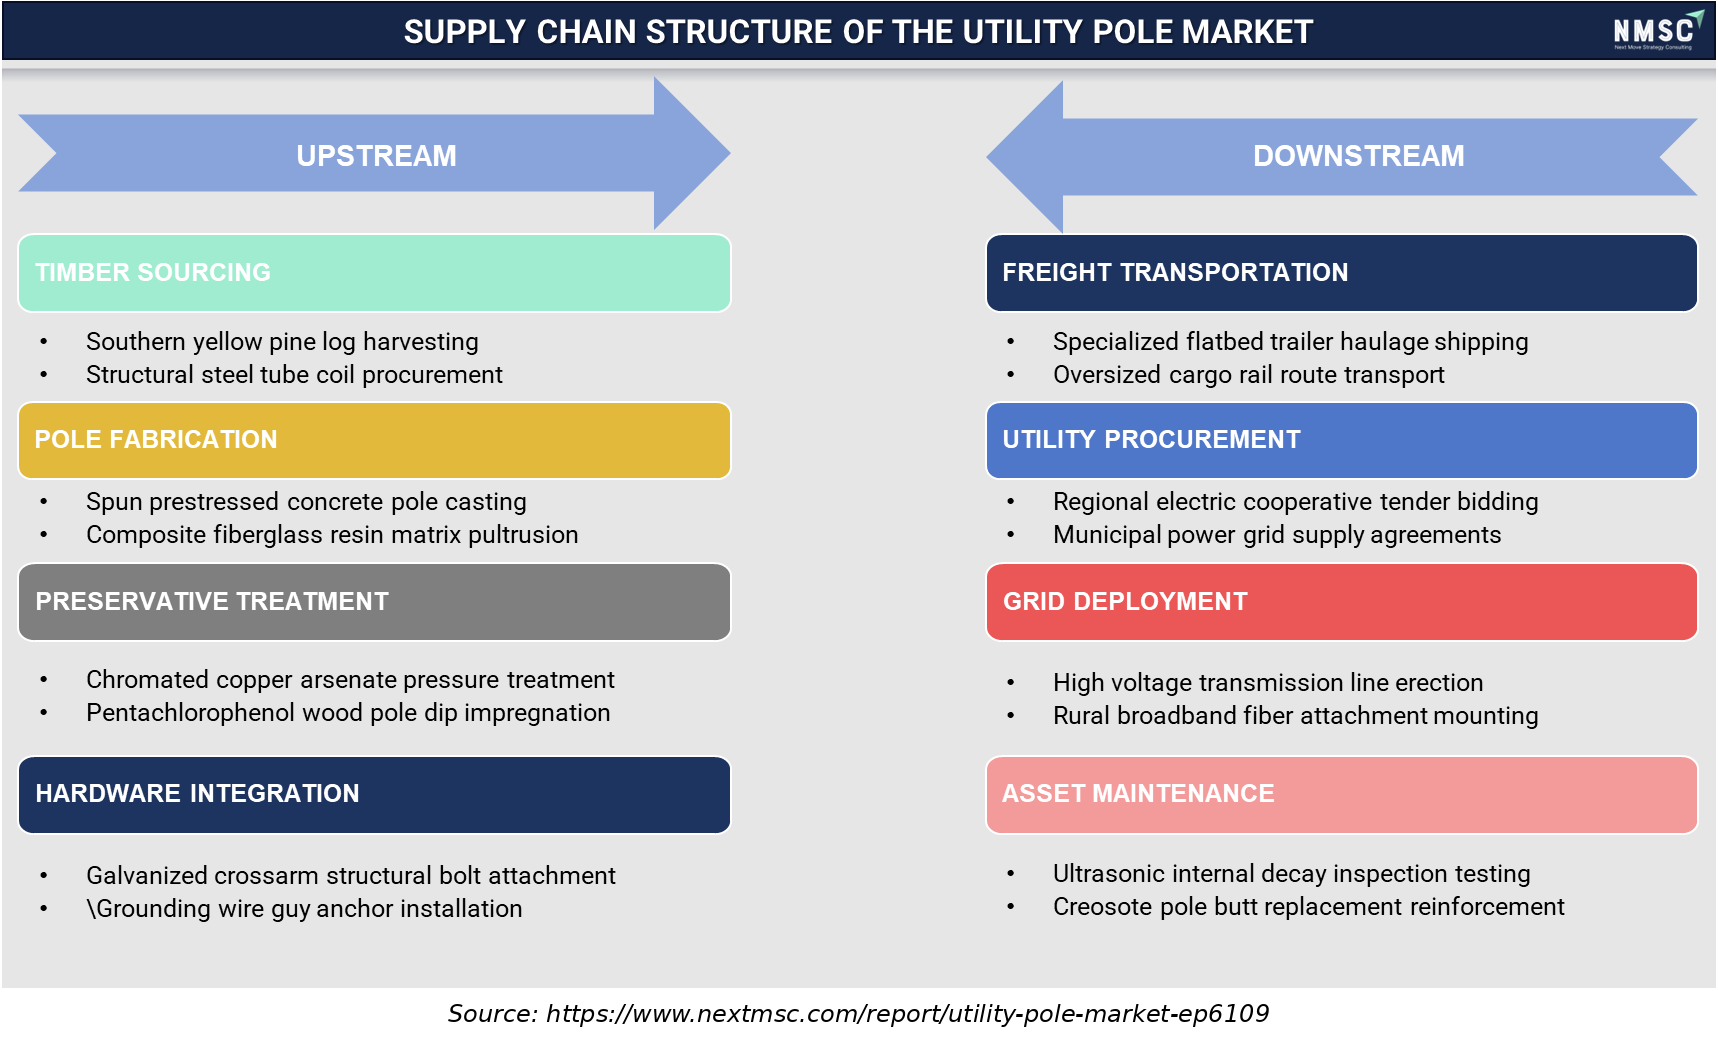
Based on research conducted by NMSC, we found that the supply chain of the Utility Pole Market integrates raw timber, steel tubing, prestressed concrete casting, and preservative treatments with specialized flatbed transport. Downstream, regional cooperatives and power grids deploy poles for high-voltage transmission lines and rural broadband networks. Subsequently, long-term asset maintenance relies on ultrasonic internal decay testing and pole butt replacement reinforcement to maintain structural grid durability.

Market Drivers & Dynamics

Interactive Dataset
Rising grid modernization and resilience investment driver +1.9% North America, Europe 2026-2035
Expanding wildfire-resistant pole replacement programs driver +1.6% North America, Asia-Pacific 2026-2032
Growing 5G and fiber network densification driver +1.4% Global 2026-2033
Government rural electrification funding programs driver +1.1% Asia-Pacific, MEA, Latin America 2026-2031
Rising demand for extended-life composite materials driver +0.8% North America, Europe 2026-2035
High upfront cost of composite and steel poles versus wood restraint -1.2% Latin America, MEA 2026-2030
Regulatory permitting delays for pole replacement projects restraint -0.8% North America, Europe 2026-2029
Volatility in steel and treated timber raw material prices restraint -0.6% Global 2026-2030
Limited skilled labor for utility pole installation restraint -0.5% MEA, Latin America 2026-2028
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Utility Pole Market?

Rising grid modernization and resilience investment is the primary driver of the market, as utilities upgrade aging pole infrastructure to meet reliability and safety standards. The U.S. Department of Energy reports expanding grid resilience funding allocations across major utility service territories, prompting pole manufacturers to fund capacity expansion aimed at meeting replacement demand.

How Is Wildfire-Resistant Pole Replacement Driving Market Growth?

Expanding wildfire-resistant pole replacement programs are driving market growth as utilities in fire-prone regions transition from wood to composite and steel structures. California's Office of Energy Infrastructure Safety has mandated utility wildfire mitigation plans, industry-derived estimate indicating meaningful composite and steel pole demand growth across high-risk service territories.

Growth Inhibitors

What Is Restraining Utility Pole Market Expansion?

High upfront cost of composite and steel poles relative to wood is restraining market expansion, particularly across price-sensitive emerging market utilities. The U.S. Energy Information Administration has noted capital constraints among smaller municipal and cooperative utilities, and industry-derived estimates indicate that cost sensitivity disproportionately affects premium material adoption in developing regions.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Wood 2025: $14.20 Billion | 2035: $22.80 Billion
Wood
Steel 2025: $9.80 Billion | 2035: $19.40 Billion
Steel
Concrete 2025: $6.50 Billion | 2035: $12.60 Billion
Concrete
Composite 2025: $4.10 Billion | 2035: $11.20 Billion
Composite
Ductile Iron 2025: $1.90 Billion | 2035: $3.15 Billion
Ductile Iron
Hybrid 2025: $1.70 Billion | 2035: $3.40 Billion
Hybrid
Wood $14.20 Billion $22.80 Billion 4.7%
Steel $9.80 Billion $19.40 Billion 7.1%
Concrete $6.50 Billion $12.60 Billion 6.9%
Composite $4.10 Billion $11.20 Billion 11.0%
Ductile Iron $1.90 Billion $3.15 Billion 5.1%
Hybrid $1.70 Billion $3.40 Billion 7.3%

Which Pole Material Segment Dominates the Utility Pole Market?

Wood led the market, valued at USD 14.20 billion in 2025 and projected to reach USD 22.80 billion by 2035, supported by established supply chains and lower upfront procurement cost across rural distribution networks. Composite is the fastest-growing sub-segment at a CAGR of 11.0%, driven by rising wildfire-resistant and corrosion-resistant pole specification among utilities in high-risk service territories.

2025 (USD Billion)
2035 (USD Billion)
Low Voltage
Medium Volta
High Voltage
Extra High V
Ultra High V
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Low Voltage Distribution $10.0 USD Billion $40.0 USD Billion 18.0%
Medium Voltage Distribution $17.1 USD Billion $51.1 USD Billion 16.0%
High Voltage Transmission $24.2 USD Billion $62.2 USD Billion 22.0%
Extra High Voltage Transmission $31.3 USD Billion $73.3 USD Billion 12.0%
Ultra High Voltage Transmission $38.4 USD Billion $84.4 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data

Which Application Segment Is Growing Fastest?

Telecommunications is the fastest-growing application segment, expanding at a CAGR of 9.1% between 2026 and 2035, driven by rising 5G small cell and fiber network densification projects. Electric Distribution remains the dominant segment given its established grid infrastructure base, while Electric Transmission continues to expand steadily through high-voltage capacity upgrade projects.

2025 (USD Billion)
2035 (USD Billion)
Utility Owne
Telecom Owne
Government O
Private Infr
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Utility Owned $10.0 USD Billion $40.0 USD Billion 12.0%
Telecom Owned $17.1 USD Billion $51.1 USD Billion 22.0%
Government Owned $24.2 USD Billion $62.2 USD Billion 20.0%
Private Infrastructure Owned $31.3 USD Billion $73.3 USD Billion 14.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Ownership Model.

Unlock Full Data

Why Does Utility Owned Ownership Lead the Market?

Utility Owned pole infrastructure dominated the market, reaching USD 24.60 billion in 2025 due to investor-owned and municipal utilities retaining direct ownership of distribution and transmission pole assets. Telecom Owned is expanding at the fastest CAGR of 8.3% as telecommunications operators increasingly deploy dedicated pole infrastructure to support network densification independent of shared utility assets.

2025 (USD Billion)
2035 (USD Billion)
Pole Only
Pole and Har
Engineered P
Pole System
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Pole Only $10.0 USD Billion $40.0 USD Billion 17.0%
Pole and Hardware Package $17.1 USD Billion $51.1 USD Billion 15.0%
Engineered Pole System $24.2 USD Billion $62.2 USD Billion 17.0%
Pole System with Installation $31.3 USD Billion $73.3 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Commercial Scope.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Under 40 Fee
40 Feet to 7
Above 70 Fee
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Under 40 Feet $10.0 USD Billion $40.0 USD Billion 13.0%
40 Feet to 70 Feet $17.1 USD Billion $51.1 USD Billion 27.0%
Above 70 Feet $24.2 USD Billion $62.2 USD Billion 17.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Pole Height.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
New Build
Replacement
Capacity Upg
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
New Build $10.0 USD Billion $40.0 USD Billion 8.0%
Replacement $17.1 USD Billion $51.1 USD Billion 10.0%
Capacity Upgrade $24.2 USD Billion $62.2 USD Billion 20.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Installation Type.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct Sales
EPC Channel
Distributor
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Sales $10.0 USD Billion $40.0 USD Billion 24.0%
EPC Channel $17.1 USD Billion $51.1 USD Billion 10.0%
Distributor Channel $24.2 USD Billion $62.2 USD Billion 8.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Investor-Own
Municipal Ut
Electric Coo
Telecommunic
EPC Contract
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Investor-Owned Utility $10.0 USD Billion $40.0 USD Billion 22.0%
Municipal Utility $17.1 USD Billion $51.1 USD Billion 12.0%
Electric Cooperative $24.2 USD Billion $62.2 USD Billion 14.0%
Telecommunications Operator $31.3 USD Billion $73.3 USD Billion 12.0%
EPC Contractor $38.4 USD Billion $84.4 USD Billion 15.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Buyer Type.

Unlock Full Data

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the utility pole market.

How Can Sensor-Embedded Smart Poles Unlock Value for Grid Operators?

Sensor-embedded smart poles offering integrated outage detection and structural health monitoring present a whitespace opportunity for grid operators seeking to reduce inspection costs while improving reliability metrics across aging distribution networks.

Where Does Carbon Fiber Composite Pole Adoption Create Demand in High-Wind Regions?

Carbon fiber composite poles engineered for extreme wind-load resistance create an underpenetrated opportunity across hurricane-prone and coastal utility service territories, where conventional wood and concrete poles face accelerated replacement cycles.

How Can Engineered Pole System Bundling Benefit EPC Contractors?

Engineered pole system bundling that combines poles, hardware, and installation services creates an opportunity for EPC contractors to streamline large-scale grid replacement projects while capturing higher margin turnkey service revenue.

Ecosystem Analysis

Other

  • raw timber
  • steel tubing
  • prestressed concrete casting
  • preservative treatments

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

PESTEL Analysis of the Utility Pole Market
PESTEL Analysis of the Utility Pole Market
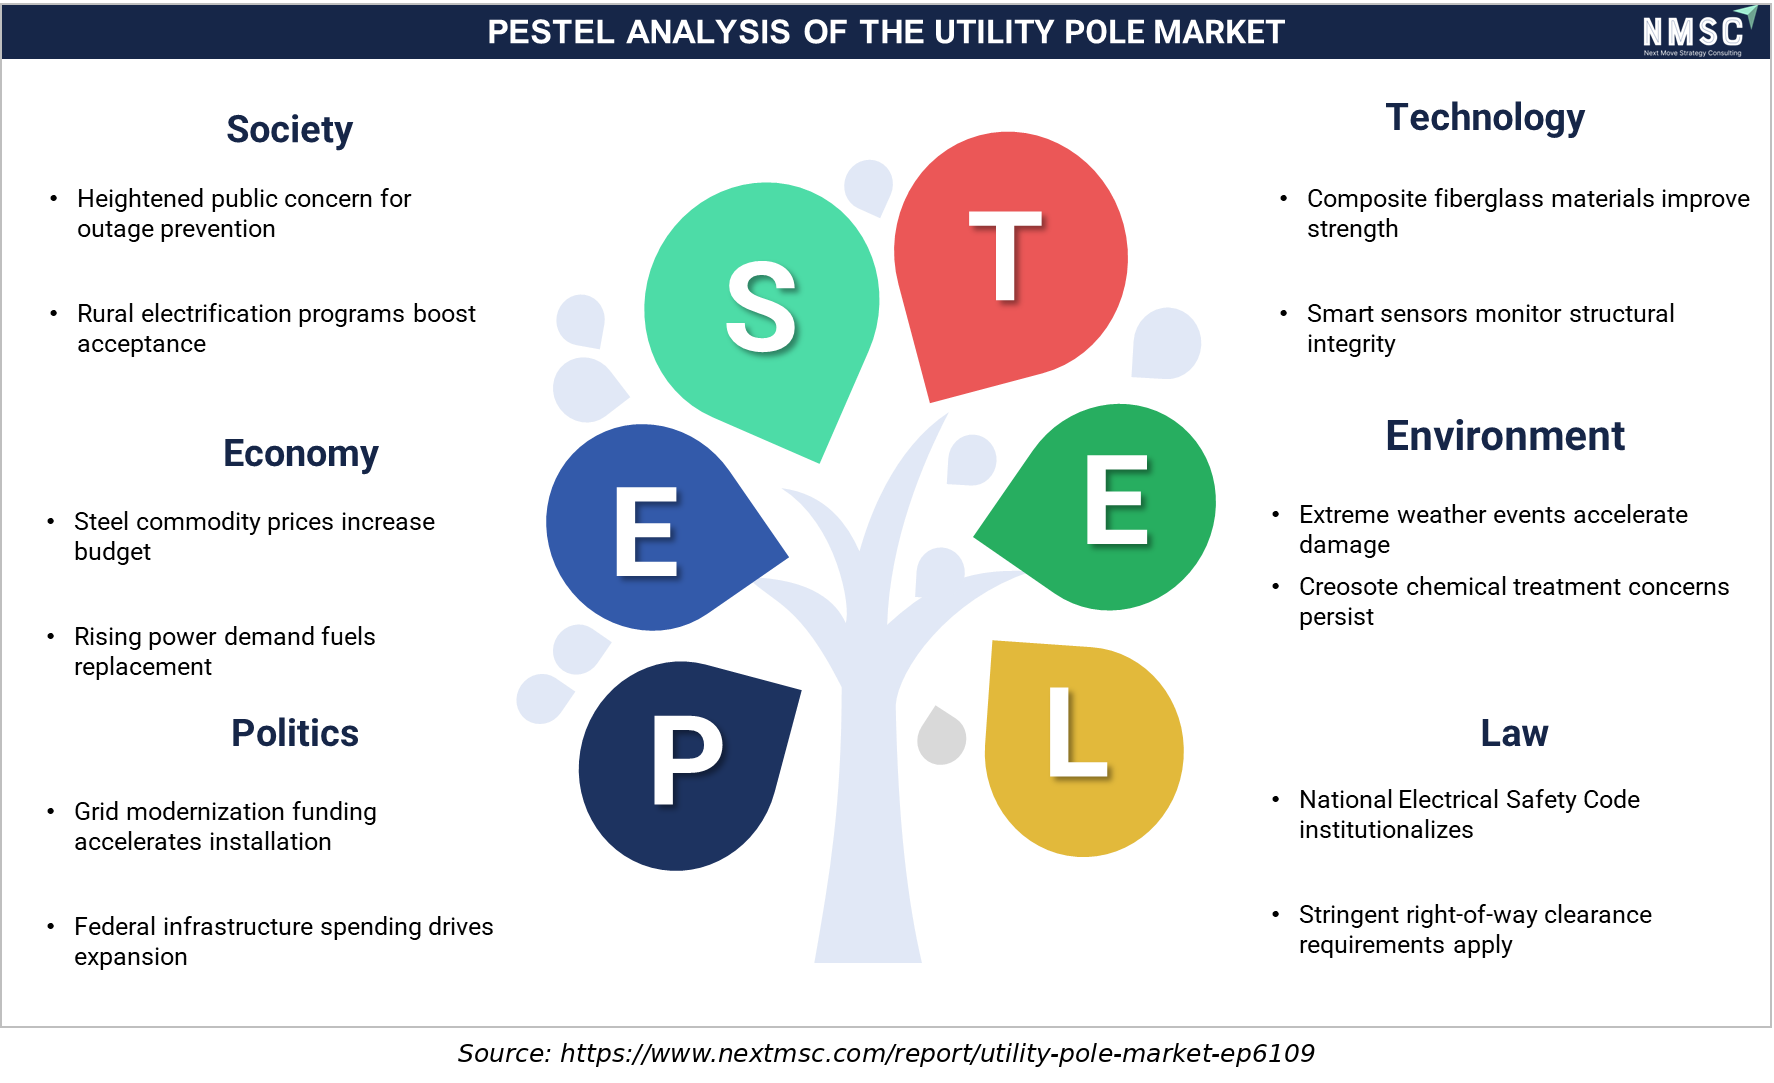
NMSC's analysis indicates that public outage concerns, rural electrification, and government grid modernization funding are driving steady expansion in the Utility Pole Market. Furthermore, composite fiberglass materials and smart structural sensors enhance overall resilience. Concurrently, high steel commodity prices impact utility budgets, while compliance with National Electrical Safety Code standards and stringent right-of-way clearance regulations remains essential to withstand severe weather risks and ongoing environmental scrutiny.

Competitive Landscape

We found that the competitive landscape is moderately fragmented, with global pole manufacturing conglomerates competing alongside regional specialty fabricators across the Industry.

Dimension Description
Market Structure Moderately fragmented, with 20 profiled vendors spanning diversified material manufacturers and regional specialty pole fabricators
Innovation Focus Composite material engineering, smart pole sensor integration, and engineered pole system bundling
M&A Activity Selective acquisitions of composite and specialty pole fabricators by larger diversified infrastructure manufacturers

How Do Companies Compete in the Utility Pole Market?

Companies compete primarily on material durability ratings, regulatory compliance breadth across covered geographies, and depth of engineering support services offered to utility and telecom customers. Pricing strategies increasingly favor volume-based supply agreements tied to multi-year grid modernization contracts.

Which Competitive Archetypes Dominate the Utility Pole Industry?

Three archetypes dominate the Industry: diversified infrastructure manufacturers such as Valmont Industries, Inc. offering integrated steel and composite portfolios, wood treatment specialists such as Stella-Jones Inc. focused on treated timber supply chains, and regional specialty fabricators such as Jiangsu Hongguang Steel Pole Co., Ltd. emphasizing localized steel production.

What Innovation and Differentiation Strategies Are Vendors Pursuing?

Vendors are differentiating through proprietary composite material formulations, expanded smart pole sensor compatibility, and engineered system bundling partnerships with EPC contractors, aiming to strengthen defensibility against commoditized generic pole offerings from smaller entrants.

Key Market Players

We found that the following companies represent the leading providers of utility poles based on market-specific revenue and scale of operations as of 2026.

Valmont Industries, Inc. Stella-Jones Inc. Koppers Holdings Inc. Sabre Industries, Inc. Arcosa, Inc. Nippon Concrete Industries Co., Ltd. Skipper Limited McWane, Inc. FUCHS Europoles GmbH Bell Lumber & Pole Company Utkarsh India Limited Wagners Composite Fibre Technologies Pty Ltd Resilient Structures Inc. R&B Timber Group Ameron Pole Products LLC Jiangsu Hongguang Steel Pole Co., Ltd. Jiangsu Milky Way Steel Poles Co., Ltd. Yixing Futao Metal Structural Unit Co., Ltd. Trans-American Power Poles Inc. Nova Pole International Inc.

Latest Developments

We observed the following recent developments shaping vendor positioning and material capability within the market.

Date Event
November 2025 Stella-Jones completed the acquisition of the assets of Brooks Manufacturing Co. for approximately US$140 million. Brooks manufactures treated wood distribution crossarms and transmission framing components in the U.S. The acquisition broadens Stella-Jones’ portfolio of infrastructure solutions and strengthens its position in the utility sector.
May 2025 Stella-Jones entered into a definitive agreement to acquire Locweld Inc., a leading designer and manufacturer of lattice transmission towers and steel poles. The acquisition significantly expands the company's steel utility structure capabilities alongside its established wood utility pole business.

Expert Insights

Rob Krotee

Rob Krotee

Executive Vice President | Resilient Structures (formerly RS Technologies)

"Old infrastructure coupled with the weather events, wildfires, and then the demand for electricity, just sets up an overwhelming need in the coming years for a resilient and reliable grid."

Analyst Interpretation

The statement highlights the structural transformation occurring in the utility pole market as aging transmission and distribution infrastructure faces mounting pressure from extreme weather events, wildfire risks, and rising electricity demand driven by electrification and data center expansion. These factors are accelerating investments in durable utility pole materials, including composite, steel, and advanced engineered solutions, supporting long-term grid resilience and modernization initiatives across utilities worldwide.

Investment Opportunities

What Capital Inflows Are Supporting Market Expansion?

Corporate and utility capital investment continue to flow into composite material and smart pole sensor technology startups. Our findings suggest that investor interest is concentrated on solutions demonstrating measurable service-life improvements alongside recurring multi-year grid modernization supply agreements.

How Is Infrastructure Investment Shaping Pole Manufacturing Scalability?

Manufacturing capacity investment by established producers, including Koppers Holdings Inc. and Sabre Industries, Inc., underpins pole scalability for expanding grid resilience and telecom densification demand. This infrastructure investment supports consistent material quality across geographically distributed production facilities.

What ESG Considerations Are Relevant to Market Investment?

Environmental, Social, and Governance considerations increasingly influence procurement, with utilities evaluating vendor sustainable sourcing practices and end-of-life recyclability commitments. Government funding programs in several regions now require ESG disclosure as a condition of grid resilience grant eligibility.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders?

Industry leaders gain access to detailed segmentation, regional forecasts, and competitive benchmarking that support material investment and supply agreement decisions across distribution, transmission, and telecommunications pole markets.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from validated market sizing, CAGR forecasts, and company-level competitive positioning that inform capital allocation decisions across the utility pole value chain.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging trends, growth opportunities, and regional demand patterns that inform material formulation prioritization and go-to-market strategy across covered geographies.

Key Market Segments Evaluated

By Pole Material

  • Wood
  • Steel
  • Concrete
  • Composite
  • Ductile Iron
  • Hybrid

By Application

  • Electric Distribution
  • Electric Transmission
  • Telecommunications
  • Street Lighting
  • Transportation Infrastructure
  • Industrial Infrastructure

By Ownership Model

  • Utility Owned
  • Telecom Owned
  • Government Owned
  • Private Infrastructure Owned

By Commercial Scope

  • Pole Only
  • Pole and Hardware Package
  • Engineered Pole System
  • Pole System with Installation

By Pole Height

  • Under 40 Feet
  • 40 Feet to 70 Feet
  • Above 70 Feet

By Installation Type

  • New Build
  • Replacement
  • Capacity Upgrade

By Sales Channel

  • Direct Sales
  • EPC Channel
  • Distributor Channel

By Buyer Type

  • Investor-Owned Utility
  • Municipal Utility
  • Electric Cooperative
  • Telecommunications Operator
  • EPC Contractor
  • Government Authority
  • Industrial Enterprise
  • Other Infrastructure Owner

Conclusion & Recommendations

The long-term outlook remains positive, with the market projected to expand from USD 40.65 billion in 2026 to USD 72.55 billion by 2035 as grid modernization and wildfire-resilient replacement programs deepen across utility service territories.

What Strategic Positioning Should Vendors Pursue?

Vendors should prioritize composite material innovation and smart pole sensor readiness to differentiate against commoditized wood pole offerings, while pursuing strategic partnerships with utilities and EPC contractors to strengthen engineered system credibility.

How Attractive Is the Market for Investment?

Investment attractiveness remains moderate to high given steady mid-single-digit CAGR expectations and expanding grid resilience funding, though investors should weigh raw material price volatility and regulatory permitting delays affecting project timelines.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor evolving wildfire mitigation regulation, steel and treated timber raw material price volatility, and potential grid funding policy shifts, each of which could affect procurement timelines across covered geographies.

What Are the Primary Growth Pathways for Market Participants?

Primary growth pathways include expansion into underpenetrated telecom-owned pole markets, deeper smart pole sensor integration, and strategic acquisition of composite fabrication startups to accelerate proprietary material capability development.

FAQs

About the Author

Saista Faiyaz

Saista Faiyaz

Saista Faiyaz is Research Associate at Next Move Strategy Consulting, where she has covered consumer markets and healthcare technologies for 3 years. Her work includes primary interview review, secondary-source validation, market sizing, and structured analysis of company and industry data. She supports research by comparing evidence across sources, organizing findings into market narratives, and documenting assumptions used in analysis. Her scope includes cross-market benchmarking, and reports.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Diana Trejo

DIANA TREJO

Assistant Manager

Sumitomo Corporation de Mexico, S.A. de C.V.

Recently, we purchased a report on the Mexico Data Center Market from Next Move Strategy Consulting. The service has been excellent, with support that is always timely and thoroughly professional. The information provided is interesting, highly useful, and delivered with clarity. I would highly recommend NextMSC for anyone seeking insightful and dependable analysis.

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖