Cellulosic Additives Market Transformation and Emerging Industry Shifts
Market Transformation in the Cellulosic Additives Market
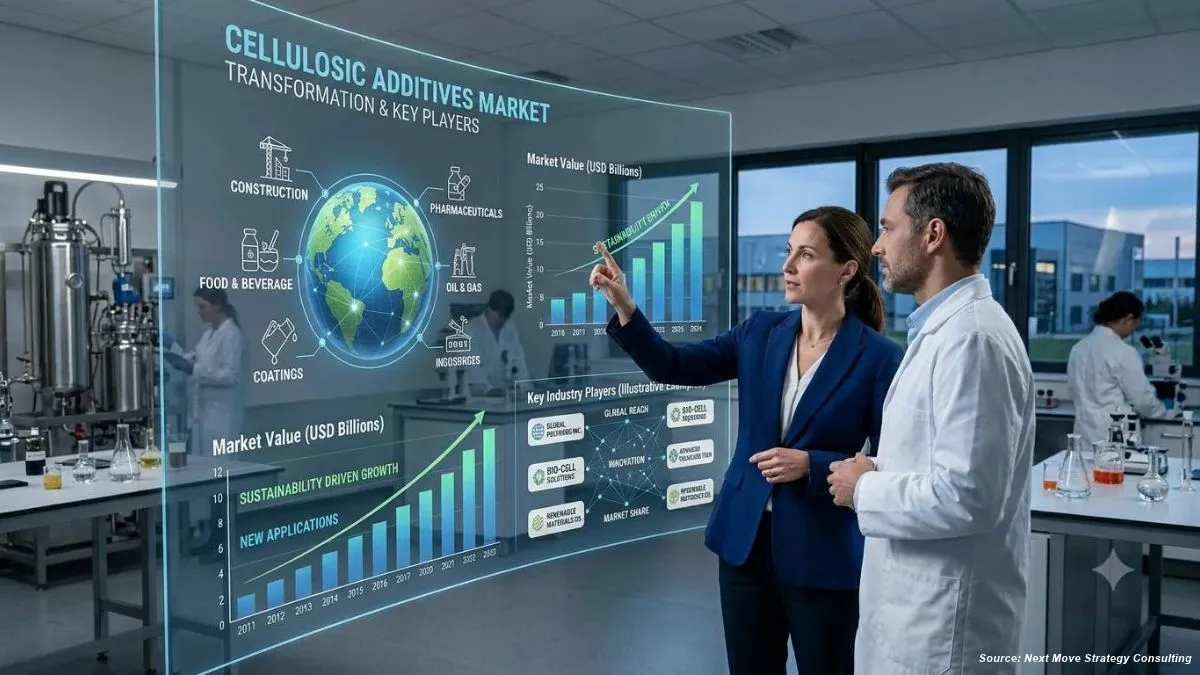
The Cellulosic Additives Market is moving away from legacy commodity production. Producers are shifting capacity toward pharmaceutical, food, and high-performance grades. The market reached USD 6.20 Billion in 2025 and is estimated at USD 6.51 Billion in 2026. It is forecast to reach USD 10.10 Billion by 2035. This represents a 5% CAGR from 2026 to 2035. We observed that this shift favors suppliers with audited quality systems and application-specific grades. Our analysis indicates that value growth will outpace volume growth over the coming decade.
Technological convergence is reshaping how cellulose ethers are developed and qualified. Producers are refining modification chemistry to deliver consistent viscosity, purity, and traceability. Tighter process control now supports low-nitrite and enteric-coating excipient grades. Hydrophobically modified grades are also gaining ground in waterborne paints. Compliance with pharmacopoeia monographs and food additive rules is becoming a core performance requirement. These standards raise qualification costs and reward suppliers that can document every batch.
Value is also migrating beyond physical production toward technical service and supply chain integration. Distributors now provide local stock, formulation support, and regulatory documentation. Software-driven dosing guidance and application modeling help customers optimize usage. Five companies are leading this transition. Ashland, Nouryon, Univar Solutions, Roquette, and Eastman Chemical each pursue distinct strategies. Their approaches illustrate how competitive advantage is shifting toward integrated offerings.
Want Insights on the Cellulosic Additives Market? Access a FREE Sample Instantly
Key takeaway: Pharmaceutical and specialty grades are driving the market's value growth. Suppliers with qualified excipient products and regional distribution networks are best placed to capture the projected USD 3.59 Billion expansion between 2026 and 2035.
The table below shows how 2025 revenue divides across the five major regions.
Regional Revenue Split, 2025 to 2035 (USD Billion)
|
Region |
2025 Revenue (USD Billion) |
|
Asia-Pacific |
2.75 |
|
Europe |
1.45 |
|
North America |
1.30 |
|
Middle East & Africa |
0.35 |
|
Latin America |
0.35 |
|
Total |
6.20 |
The five regional values sum to USD 6.20 Billion, matching the global 2025 base year total.
Ashland
Ashland is headquartered in Wilmington, Delaware, and operates globally across specialty additives and life sciences. Its core businesses include pharmaceutical excipients, personal care, and performance materials. Cellulosics represent a major part of its Life Sciences portfolio. The Cellulosic Additives Market directly shapes how Ashland allocates capacity and prioritizes high-margin excipient grades.
Ashland supplies cellulose ethers, including hydroxyethyl cellulose and carboxymethyl cellulose, to pharmaceutical, food, and construction customers. In November 2025, the company reported fourth quarter fiscal 2025 results and highlighted robust demand for high-value cellulosic excipients, including tablet coatings and injectables. In July 2025, Ashland advanced a USD 60 million network optimization, transferring hydroxyethyl cellulose production from Parlin, New Jersey to its Hopewell, Virginia plant. Ashland sits upstream as a manufacturer, selling directly and through distribution partners.
Ashland's strategy centers on pharmaceutical-grade differentiation and network consolidation. Its qualified excipient portfolio creates switching barriers for formulators. Investment in larger, more efficient plants supports long-term cost discipline. This combination gives Ashland a defensible position in premium segments. Exposure to softer industrial demand remains a watch point.
Nouryon
Nouryon is headquartered in the Netherlands and serves global industrial and specialty markets. Its portfolio spans pulp and paper, coatings, construction, and cleaning ingredients. The company treats cellulose ethers as a strategic growth line within its specialty offering. Demand patterns in the Cellulosic Additives Market guide its product and regional launch decisions.
Nouryon markets Bermocoll cellulose ethers for construction mortars and waterborne paints. It also supplies Akucell cellulose gum for beverages and processed foods. In February 2026, the company launched FinnFix PB MAX, described as the cleaning industry's first 100% biobased, biodegradable carboxymethylcellulose for laundry detergents. Nouryon operates as a producer that sells to formulators and distributors across multiple end markets.
Nouryon is building differentiation through sustainability and application-specific chemistry. Biobased product claims strengthen its appeal in procurement scoring. Its breadth across construction, coatings, and cleaning reduces reliance on any single end use. Consistent innovation in rheology and biodegradability supports a growing technical moat. The company is positioned for steady expansion as formulators seek renewable inputs.
Univar Solutions
Univar Solutions is headquartered in Downers Grove, Illinois, and operates as a global distributor of specialty and essential ingredients. Its business spans chemicals distribution, food and nutrition, and industrial supply. The company does not manufacture most of the cellulose ethers it sells. Its role in the Cellulosic Additives Market centers on distribution, technical support, and supply chain reach.
Univar Solutions distributes cellulosics across food, beverage, and health applications. In November 2026, the company announced a new distribution relationship with Roquette, adding an expanded cellulosics portfolio in North America. The portfolio includes METHOCEL, ETHOCEL, and MICROCEL grades. In January 2026, Univar also formed an exclusive distribution partnership with Ashland for cellulose ethers in food and beverage across EMEA. Univar operates as a downstream channel partner connecting producers to formulators.
Univar's strategy depends on breadth of supplier relationships and regional stock access. Exclusive agreements with major producers strengthen its position in regulated food segments. Its supply chain intelligence helps customers manage lead times and qualification needs. The model reduces inventory risk for smaller formulators. Its long-term moat rests on relationships rather than proprietary chemistry.
Roquette
Roquette is headquartered in Lestrem, France, and is a global leader in plant-based ingredients. Its operations cover starches, plant proteins, fibers, and specialty cellulosics. The company links its food and nutrition expertise to the Cellulosic Additives Market through its METHOCEL and related cellulose ether lines. Plant-based demand trends directly influence its investment priorities.
Roquette supplies a cellulosics portfolio that includes METHOCEL, WELLENCE, ETHOCEL, TABULOSE, and MICROCEL grades. These products deliver texture, stability, and processing performance in food and pharmaceutical applications. In November 2026, Roquette expanded its distribution collaboration with Univar Solutions in North America, adding cellulosics alongside its plant proteins and soluble fibers. Roquette operates as a manufacturer that sells through distribution and direct commercial channels.
Roquette's strength lies in its integrated plant-based platform. Pairing cellulosics with proteins and fibers allows it to offer complete nutrition solutions. Long experience in food innovation supports its credibility with regulated customers. Its portfolio breadth limits exposure to any single ingredient category. This integration gives Roquette a durable advantage in health and nutrition markets.
Eastman Chemical
Eastman Chemical is headquartered in Kingsport, Tennessee, and operates a diversified specialty materials business. Its portfolio includes additives, advanced materials, and fibers. Cellulose-based products form part of its specialty and sustainable materials offering. The Cellulosic Additives Market influences its focus on biodegradable and personal care ingredients.
Eastman manufactures cellulose ester products used in coatings, plastics, and personal care. In June 2025, the company launched Esmeri CC1N10, a readily biodegradable cellulose ester micropowder for color cosmetics. The ingredient is sourced from sustainably managed forests and designed to meet stringent EU requirements. Eastman operates as a producer selling specialty grades to cosmetics formulators and industrial customers.
Eastman's position rests on sustainable specialty chemistry and technical depth. Biodegradability and responsible sourcing support its appeal to brand owners. Its diversified materials base reduces dependence on any one cellulose segment. Careful focus on high-value niches limits direct price competition. Continued investment in sustainable grades strengthens its long-term market standing.
Explore the Full Cellulosic Additives Market Report
Market Summary
The Cellulosic Additives Market was valued at USD 6.20 Billion in 2025 and is expected to reach USD 6.51 Billion in 2026. Demand is primarily driven by applications in pharmaceuticals, construction, food processing, and coatings. Methylcellulose and hydroxypropyl methylcellulose dominate product demand, while construction and building materials lead application revenue. Asia-Pacific accounts for approximately 45% of global market revenue.
The competitive landscape is dominated by a small group of established producers with strong cellulose chemistry expertise. Companies compete through product consistency, technical support, and regulatory compliance. Innovation focuses on specialized grades, including low-spatter paint additives and low-nitrite excipients. Sustainability credentials and regional distribution partnerships are also becoming important factors in procurement and market expansion.
The market is projected to reach USD 10.10 Billion by 2035, growing at a CAGR of 5% during 2026–2035. Pharmaceutical and nutraceutical applications are expected to record the fastest growth, while the Middle East and Africa is projected to be the fastest-growing region. However, feedstock price volatility, compliance costs, and export competition remain key challenges. Suppliers offering specialized grades, reliable regional availability, and sustainable products are expected to gain a competitive advantage.
"By expanding our collaboration beyond cellulosics to include plant proteins and fibers in North America, we're aligning Roquette's leadership in food innovation with our unmatched supply chain and market intelligence to help shape the future of nutrition."
- Aaron Lee, Senior Vice President of Health & Nutrition, Univar Solutions
About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment