Green Anesthesia and Clinical Data Reshape CO2 Absorbent Market | NextMSC
Introduction
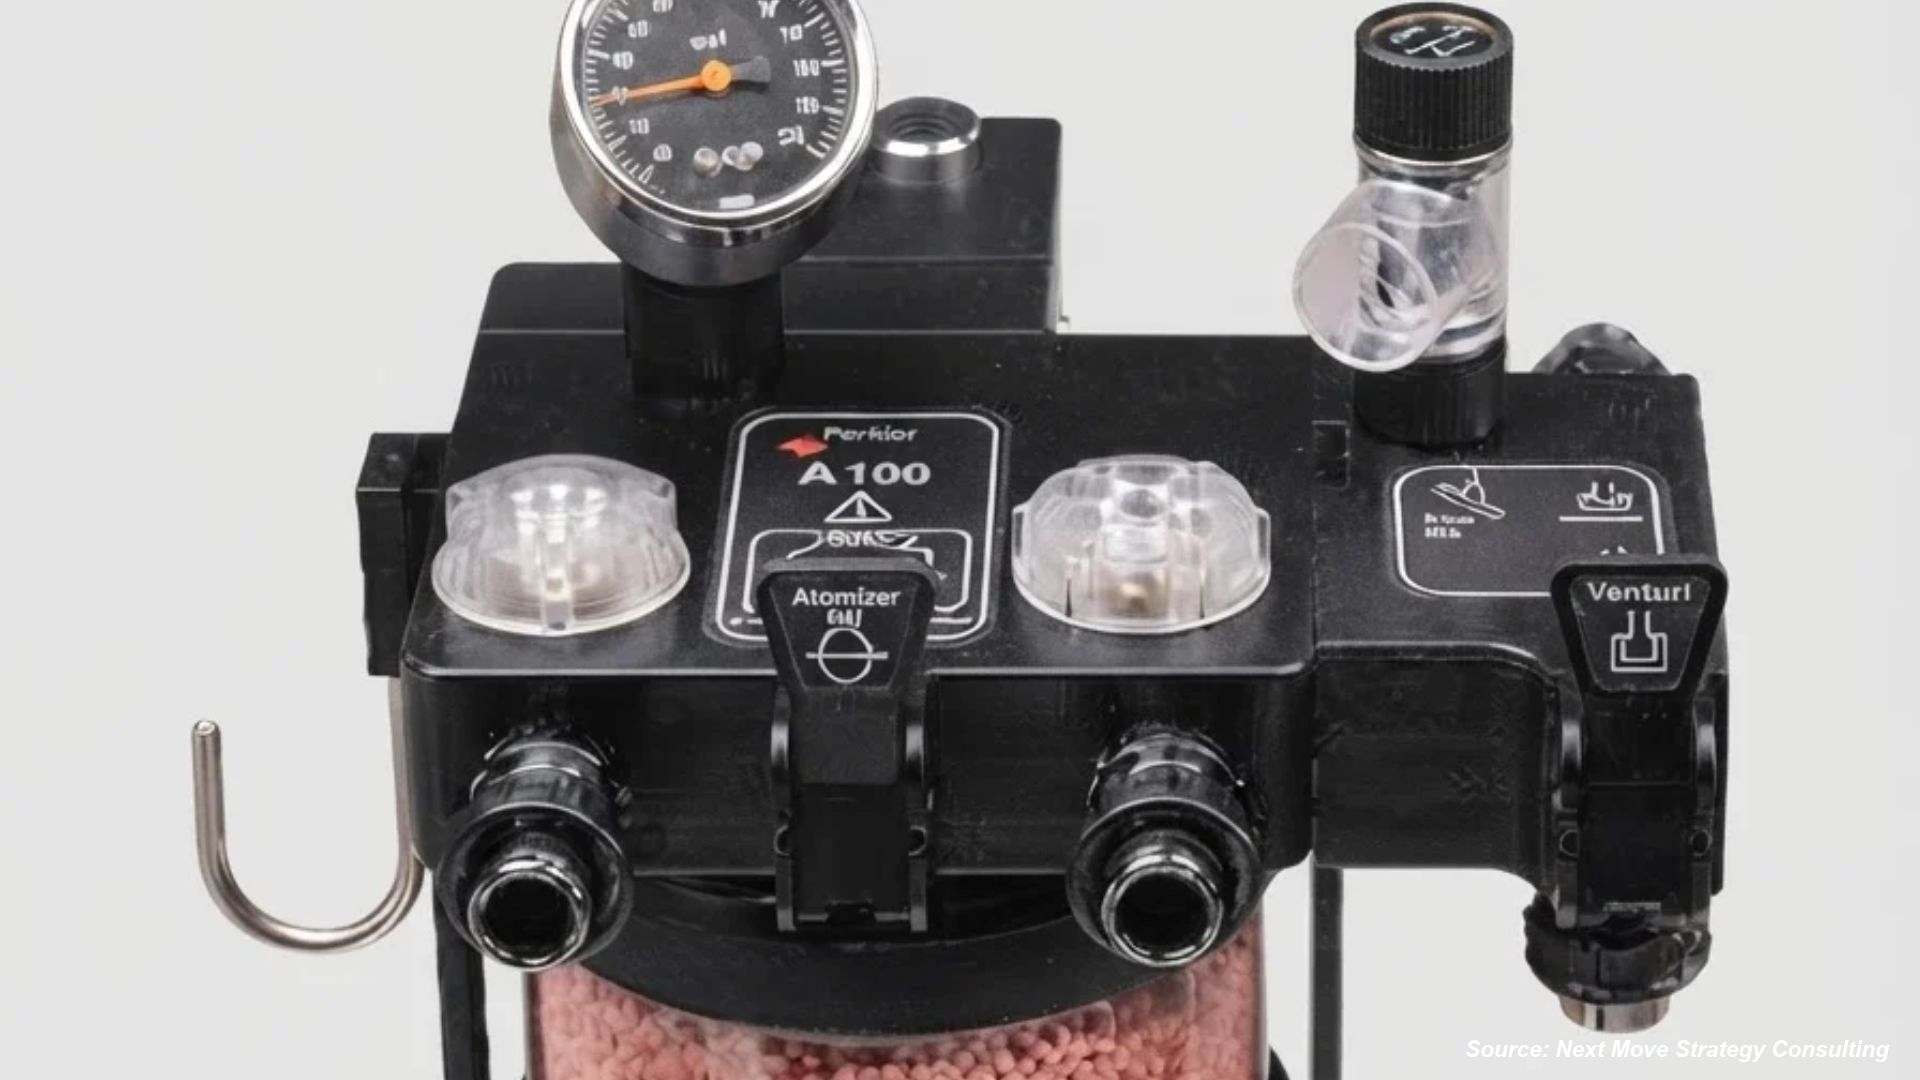
The global operating room is undergoing a quiet but consequential transformation — one driven not only by rising surgical volumes and an aging population, but by an intensifying convergence of patient safety science and environmental accountability. At the center of this shift sits a component that has long been considered a commodity: the anesthesia CO2 absorbent. According to Next Move Strategy Consulting's Anesthesia CO2 Absorbent Market report, the global anesthesia CO2 absorbent market is projected to reach USD 137.65 million by 2030, growing at a CAGR of 8.4% from 2023 to 2030. This trajectory reflects a market that is no longer shaped by volume alone, but by formulation chemistry, device compatibility, and the measurable carbon footprint of every surgical case.
The demand fundamentals are unambiguous. According to the World Health Organization's July 2025 cardiovascular disease fact sheet, an estimated 19.8 million people died from CVDs in 2022 — representing approximately 32% of all global deaths — with 85% of those deaths attributable to heart attack and stroke. Many procedures involving general anesthesia use circle breathing systems with CO2 absorbents, although anesthesia technique and breathing-system configuration vary by procedure and clinical setting. Simultaneously, a landmark 2025 Lancet Commission report confirmed that the global unmet need for surgery has grown to at least 160 million operations per year, with 3.5 million adults dying after surgery annually — a figure that underscores the scale of the surgical infrastructure gap that must be closed. As surgical capacity expands globally to meet this need, the demand for reliable, high-performance CO2 absorbents will scale in parallel.
For More Information: Download FREE Sample on Anesthesia CO2 Absorbent Market Report
Real-World Performance Data Reshapes Absorbent Selection Criteria
A Landmark Clinical Study Redefines How Anesthesiologists Choose CO2 Absorbents
In February 2026, the Journal of Anesthesia published a peer-reviewed, open-access study from Seoul National University Children's Hospital that fundamentally challenged the industry's reliance on in vitro benchmarks for CO2 absorbent selection. The study — conducted across 3,401 surgical cases using GE Avance and Dräger Primus anesthesia machines — compared the real-world clinical performance of four commercially available prefilled CO2 absorbent brands: AMSORB® Plus, SpiraLith®, CLIC Drägersorb® Absorber 800+, and Drägersorb® Free.
The findings were clinically significant. In GE Avance machines, SpiraLith® demonstrated a substantially higher CO2 absorption capacity compared to AMSORB® Plus (435.3 ± 101.6 L versus 280.8 ± 116.9 L; mean difference 154.6 L; p = 0.006), and managed more surgical cases per canister with a significantly longer anesthesia time (71.8 ± 28.8 hours versus 46.8 ± 22.4 hours; p = 0.014). In Dräger Primus machines, CLIC Drägersorb® Absorber 800+ demonstrated the highest overall CO2 absorption capacity (582.5 ± 249.7 L), outperforming both Drägersorb® Free (434.1 ± 138.4 L) and SpiraLith® (379.8 ± 70.4 L), though with considerably higher variability. SpiraLith®, by contrast, provided the most predictable canister replacement intervals — a clinically meaningful advantage for anesthesiologists managing complex, multi-hour procedures.
The study's core conclusion — that in vivo performance may differ substantially from in vitro data and varies according to particle composition and device-specific conditions — has direct procurement implications. Hospitals that select absorbents based solely on laboratory capacity ratings may be systematically underutilizing canister life or accepting unpredictable replacement intervals that disrupt surgical workflow.
NMSC Strategic Perspective: The Shift from Commodity to Clinical Asset
NextMSC primary research and analysis identifies this real-world performance divergence as a structural inflection point for the anesthesia CO2 absorbent market. For the better part of two decades, procurement decisions in this segment were driven primarily by price-per-canister and brand familiarity. The Seoul National University study — and the broader body of clinical evidence it represents — signals a transition toward evidence-based absorbent selection, where device compatibility, granule geometry, and predictable replacement intervals carry measurable economic and patient safety value.
This shift has two direct market consequences. First, it elevates the premium absorbent segment — products engineered for specific machine architectures and formulated without strong alkaline bases — at the expense of undifferentiated soda lime. Second, it creates a competitive opening for manufacturers who can provide machine-specific clinical performance data, not merely in vitro capacity ratings. Procurement officers at high-volume surgical centers are increasingly requesting real-world canister longevity data as part of their supplier evaluation process, a trend that NMSC's analysis indicates will accelerate through the forecast period.
Section Summary: The anesthesia CO2 absorbent market is transitioning from commodity procurement to evidence-based clinical selection, driven by peer-reviewed real-world performance data.
Key Takeaways:
-
A 3,401-case clinical study published in the Journal of Anesthesia (February 2026) demonstrated that in vivo CO2 absorbent performance diverges significantly from in vitro benchmarks, with results varying by both brand and anesthesia machine model.
-
SpiraLith® offered the most predictable canister replacement intervals in Dräger Primus machines, while CLIC Drägersorb® Absorber 800+ delivered the highest raw absorption capacity in the same platform.
-
Device-specific compatibility is now a primary selection criterion, creating differentiation opportunities for manufacturers who can supply machine-matched clinical evidence.
-
NMSC's analysis identifies premium, alkali-free absorbent formulations as the fastest-growing product sub-segment within the broader market.
Industry Impact Analysis
Green Anesthesia Mandates Are Rewriting the Absorbent Value Proposition
The environmental dimension of anesthesia practice has moved from academic discussion to institutional policy with measurable speed. According to Dräger's Green Anesthesia platform, approximately 4.4% of global greenhouse gases originate from the health sector, with volatile anesthetics accounting for 2% of total hospital emissions. In high-income countries, inhaled anesthetic gases are estimated to account for 5% of acute hospital CO2-equivalent emissions and up to 50% of perioperative department emissions — a disproportionate share that has drawn regulatory and institutional attention.
The mechanism connecting CO2 absorbent chemistry to this environmental equation is direct. A February 2026 comprehensive review published in the International Journal of Medical and Pharmaceutical Research (IJMPR) — synthesizing 54 eligible studies — confirmed that alkali-free CO2 absorbents reduce carbon monoxide production by more than 90% compared to traditional soda lime formulations, and that their extended functional lifespan reduces replacement frequency by approximately 20% annually in high-volume operating rooms. Critically, by eliminating the strong bases (sodium hydroxide and potassium hydroxide) that cause volatile anesthetic degradation, these modern formulations enable the safe implementation of ultra-low-flow anesthesia — defined as fresh gas flow below 0.5 L/min — which reduces volatile anesthetic consumption by up to 75% compared to conventional high-flow techniques.
The environmental stakes are substantial. Desflurane — one of the most widely used volatile anesthetics — carries a 20-year global warming potential (GWP20) of approximately 2,540 times that of CO2, with an atmospheric lifetime of approximately 14 years. One hour of desflurane administration at 6 L/min generates approximately 6–8 kg of CO2 equivalents — comparable to driving several hundred kilometers in a conventional vehicle. Institutions that have implemented desflurane phase-out strategies alongside standardized low-flow protocols have reported operating room carbon emission reductions of 50–80%, without adverse effects on perioperative outcomes.
Dräger has operationalized this imperative through its Low Flow Wizard technology — an on-screen fresh gas flow efficiency tool integrated into its anesthesia machines that alerts clinicians when their fresh gas flow is above or below optimal thresholds, standardizing low-flow delivery across users and directly reducing both costs and environmental footprint. Intersurgical, meanwhile, has expanded its alkali-hydroxide-free absorbent portfolio with LoFloSorb™ — a product specifically engineered to support ultra-low-flow anesthesia — alongside a range of prefilled disposable absorbers including the SmartCan™, The Drum™, The AbCan™, and The Pyramid™, each designed for rapid exchange and minimal handling contamination.
The Safety-Sustainability Nexus: Why Absorbent Chemistry Matters More Than Ever
OpenAnesthesia's updated clinical reference (last updated March 2026) confirms that desiccation of traditional soda lime absorbents — particularly when exposed to prolonged high fresh gas flow — can generate circuit carbon monoxide concentrations of 8,800–13,600 ppm when exposed to desflurane, resulting in carboxyhemoglobin levels exceeding 70%. Modern alkali-free formulations such as Amsorb® produce negligible amounts of compound A and carbon monoxide regardless of hydration status, enabling clinicians to implement low-flow techniques without the toxicity constraints that historically limited their adoption.
The IJMPR 2026 review further documented that fewer than 40% of anesthesia professionals correctly ranked anesthetic global warming potentials, and less than one-third consistently considered environmental impact during agent selection — a knowledge gap that structured sustainability education programs have been shown to close, with structured workshops associated with average fresh gas flow reductions of 25–30% within six months.
Section Summary: The anesthesia CO2 absorbent market is being reshaped by the convergence of patient safety science and institutional sustainability mandates, with alkali-free formulations positioned at the intersection of both imperatives.
Key Takeaways:
-
Alkali-free CO2 absorbents reduce carbon monoxide production by more than 90% versus traditional soda lime, enabling safe ultra-low-flow anesthesia that cuts volatile agent consumption by up to 75%.
-
Institutions implementing desflurane phase-out and low-flow protocols have achieved OR carbon emission reductions of 50–80% without compromising clinical outcomes.
-
Dräger's Low Flow Wizard and Intersurgical's LoFloSorb™ represent the commercial translation of green anesthesia principles into procurement-ready solutions.
-
Clinician education remains the most significant behavioral barrier to sustainable absorbent adoption, with fewer than 40% of practitioners correctly ranking anesthetic global warming potentials.
Environmental Impact of Volatile Anesthetics — Comparative Data
|
Anesthetic Agent |
20-Year Global Warming Potential (GWP20) |
Atmospheric Lifetime |
CO2e per Hour at 6 L/min |
Reduction with Low-Flow (<1 L/min) |
|
Desflurane |
~2,540× CO2 |
~14 years |
6–8 kg CO2e |
Up to 75% reduction |
|
Isoflurane |
~510× CO2 |
~3–6 years |
Moderate |
40–70% reduction |
|
Sevoflurane |
~130× CO2 |
~1.1 years |
0.4–1.2 kg CO2e |
40–70% reduction |
|
Nitrous Oxide |
~298× CO2 |
>110 years |
Cumulative burden |
Elimination preferred |
Future Outlook & Forecast
From Surgical Volume Growth to Sustainability-Driven Demand: The Dual Engine of Market Expansion
NextMSC primary research and analysis projects the global anesthesia CO2 absorbent market to reach USD 137.65 million by 2030, growing at a CAGR of 8.4% — a trajectory supported by two structurally distinct but mutually reinforcing demand drivers.
The first is volume-driven: the global burden of cardiovascular disease, neurological disorders, and respiratory conditions continues to expand the pool of patients requiring general anesthesia. According to the WHO's July 2025 cardiovascular disease fact sheet, CVDs remain the leading cause of death globally, accounting for 19.8 million deaths in 2022 — 32% of all global mortality. CO2 absorbents remove exhaled CO2 in anesthesia circle systems, allowing rebreathing and lower fresh-gas flows. In cardiac surgery, CO2 may also be insufflated into the operative field to reduce residual air and the risk of air embolism, but this is a separate surgical application from the anesthesia CO2 absorbent. The Lancet's 2025 surgical health policy commission further confirmed that the global unmet surgical need has reached at least 160 million operations per year, with low- and middle-income countries bearing the largest share of this deficit. As healthcare infrastructure investment accelerates in Asia-Pacific, Latin America, and Sub-Saharan Africa to address this gap, the installed base of anesthesia machines — and the recurring demand for CO2 absorbents — will expand accordingly.
The second driver is formulation-driven: the transition from traditional soda lime to premium alkali-free absorbents is compressing replacement cycles in some settings while extending them in others, but in both cases it is shifting revenue toward higher-margin products. The IJMPR 2026 review confirmed that alkali-free absorbents reduce replacement frequency by approximately 20% annually in high-volume operating rooms — a cost-efficiency argument that accelerates adoption — while simultaneously commanding a price premium that expands market value per unit.
Looking ahead, three structural trends will define the competitive landscape through 2030:
1. Machine-Specific Absorbent Portfolios: The Springer 2026 study's finding that absorbent performance varies significantly by anesthesia machine model will accelerate the development of device-matched product lines. Manufacturers who can demonstrate validated performance data for specific GE, Dräger, and Mindray platforms will command procurement preference in hospital systems with standardized equipment fleets.
2. Digital Integration: Dräger's Gas Consumption Analytics dashboard — which provides real-time insights into fresh gas flow efficiency, volatile agent uptake, and cost per case — represents the leading edge of a broader trend toward data-driven absorbent management. As hospital sustainability reporting requirements expand, the ability to quantify absorbent-related carbon savings will become a procurement differentiator.
3. Asia-Pacific Infrastructure Expansion: North America currently holds the dominant regional share of the anesthesia CO2 absorbent market, supported by high surgical volumes and established green anesthesia policy frameworks. Asia-Pacific, however, represents the highest-growth opportunity, driven by rapidly expanding cardiovascular disease burden — the American College of Cardiology has documented that half of global CVD deaths occur in Asian countries — and accelerating investment in surgical infrastructure across China, India, South Korea, and Southeast Asia.
Section Summary: The anesthesia CO2 absorbent market's 8.4% CAGR through 2030 reflects a dual-engine growth model: expanding surgical volumes driven by chronic disease burden, and a formulation upgrade cycle driven by green anesthesia mandates and evidence-based procurement.
Key Takeaways:
-
The global unmet surgical need of at least 160 million operations per year, confirmed by The Lancet's 2025 commission, represents the structural demand floor for anesthesia consumables including CO2 absorbents.
-
WHO data confirms 19.8 million CVD deaths in 2022, sustaining high demand for cardiac and vascular surgical procedures that require CO2 absorbents.
-
Premium alkali-free absorbents are gaining share at the expense of traditional soda lime, driven by green anesthesia mandates and patient safety requirements — a trend that expands market value per unit even as replacement frequency decreases.
-
Asia-Pacific is the fastest-growing regional market, with cardiovascular disease burden and surgical infrastructure investment as the primary demand catalysts.
Next Steps for Stakeholders
For Hospital Procurement Officers and C-Suite Healthcare Executives:
Transition absorbent procurement frameworks from price-per-canister to total cost of ownership per surgical case. The Springer 2026 clinical data demonstrates that canister longevity varies by up to 55% across brands within the same machine platform — a variance that directly affects annual absorbent expenditure, waste volume, and nursing workflow. Conduct machine-specific performance audits before renewing supplier contracts.
Integrate CO2 absorbent selection into institutional green anesthesia strategies. Institutions that have adopted alkali-free absorbents alongside standardized low-flow protocols have documented OR carbon emission reductions of 50–80%. Given that healthcare contributes 4.4–4.7% of global greenhouse gas emissions, with volatile anesthetics representing a disproportionate share of perioperative emissions, absorbent chemistry is a material lever in hospital sustainability reporting.
For Medical Device Manufacturers and Suppliers:
Invest in real-world clinical evidence generation. The Springer 2026 study's impact on procurement conversations demonstrates that peer-reviewed, machine-specific performance data carries more commercial weight than in vitro capacity ratings. Manufacturers who fund prospective, multi-center clinical studies across diverse machine platforms will establish defensible differentiation in an otherwise commoditized segment.
Develop machine-matched prefilled canister portfolios. Intersurgical's range of prefilled disposable absorbers — SmartCan™, The Drum™, The AbCan™, The Pyramid™, and IS Can™ — illustrates the commercial logic of offering device-specific solutions that eliminate fill variability and reduce handling time. Expanding this approach to cover the full installed base of major anesthesia machine platforms represents a significant revenue opportunity.
For Institutional Investors and Private Equity:
The anesthesia CO2 absorbent market's 8.4% CAGR through 2030 — in a segment with recurring, non-discretionary demand and a structural upgrade cycle from traditional to premium formulations — presents a compelling risk-adjusted return profile. Target companies with proprietary alkali-free formulations, established regulatory clearances across multiple geographies, and documented clinical performance data for major anesthesia machine platforms. The Asia-Pacific expansion opportunity, driven by cardiovascular disease burden and surgical infrastructure investment, represents the highest-growth regional allocation within this market.
Conclusion
The anesthesia CO2 absorbent market is at an inflection point that extends well beyond its modest absolute size. The convergence of three forces — a growing global surgical burden anchored in cardiovascular and neurological disease, a peer-reviewed evidence base that now differentiates absorbent brands by real-world clinical performance rather than in vitro ratings, and institutional sustainability mandates that make absorbent chemistry a material factor in hospital carbon accounting — is reshaping procurement decisions, competitive positioning, and product development priorities across the segment.
NextMSC primary research and analysis projects the market to nearly double from USD 72.14 million in 2022 to USD 137.65 million by 2030, at a CAGR of 8.4%. That growth will not be distributed evenly. It will accrue disproportionately to manufacturers who can demonstrate machine-specific clinical performance, offer alkali-free formulations that enable safe low-flow anesthesia, and integrate their products into the digital sustainability frameworks that hospital systems are increasingly required to maintain. For stakeholders across the value chain — from procurement officers to investors to device manufacturers — the anesthesia CO2 absorbent market rewards precision over generality, and evidence over assumption.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment