What’s Driving the Helicopters Market in 2024–2025?
Introduction
The global rotorcraft industry is navigating one of its most consequential periods of transformation — driven simultaneously by an unprecedented wave of sovereign defense procurement, the commercial debut of next-generation platforms, and the structural integration of uncrewed aerial systems into traditional helicopter mission profiles. According to Next Move Strategy Consulting's Helicopters Market report, the global helicopters market was valued at USD 33.53 billion in 2024 and is projected to reach USD 46.54 billion by 2030, growing at a CAGR of 5.6% from 2025 to 2030.
This trajectory is not the product of broad macroeconomic tailwinds alone. It reflects a specific convergence: European NATO members accelerating fleet modernization at the fastest pace since the Cold War, the commercial EMS segment absorbing a new generation of light-twin platforms, and offshore energy operators locking in decade-long aftermarket agreements that signal sustained operational confidence. Each of these forces carries a distinct demand signature — and together, they are reshaping the competitive and investment landscape of the global helicopters market in ways that will define procurement cycles well into the next decade.
For More Information: Download FREE Sample on Helicopters Market Report
From Dallas to Yeovil: The Defining Market Shifts Reshaping Rotorcraft Demand
The H140 Debut and the Structural Renewal of the Civil Light-Twin Segment
The most consequential product launch in the civil rotorcraft segment in over a decade occurred in March 2025, when Airbus Helicopters unveiled the H140 light twin-engine helicopter at VERTICON in Dallas. The significance of the launch was not merely the platform itself — it was the speed and depth of market validation it received. Airbus closed VERTICON 2025 with 118 total commitments, including 63 firm orders, and more than 74 of those commitments were specifically for the H140. Following its launch in early 2025, the Airbus H140 accumulated over 74 commitments from launch customers including Global Medical Response, ADAC Luftrettung, ÖAMTC, Air Methods, Metro Aviation, and DRF Luftrettung — representing the backbone of the U.S. and European EMS helicopter community.
The H140's T-tail configuration and multi-mission architecture directly address the EMS segment's demand for a platform that can transition from hospital rooftop operations to remote rescue without reconfiguration — a capability gap that had persisted in the light-twin category since the retirement of older Bell and Eurocopter models. The fact that the H140 is expected to enter service in 2028 means that the order pipeline it is building now will translate into a sustained aftermarket revenue stream — MRO, spare parts, and training — that extends well beyond the initial delivery cycle.
Airbus Helicopters' 2025 Order Intake: A 20% Surge Driven by European Rearmament
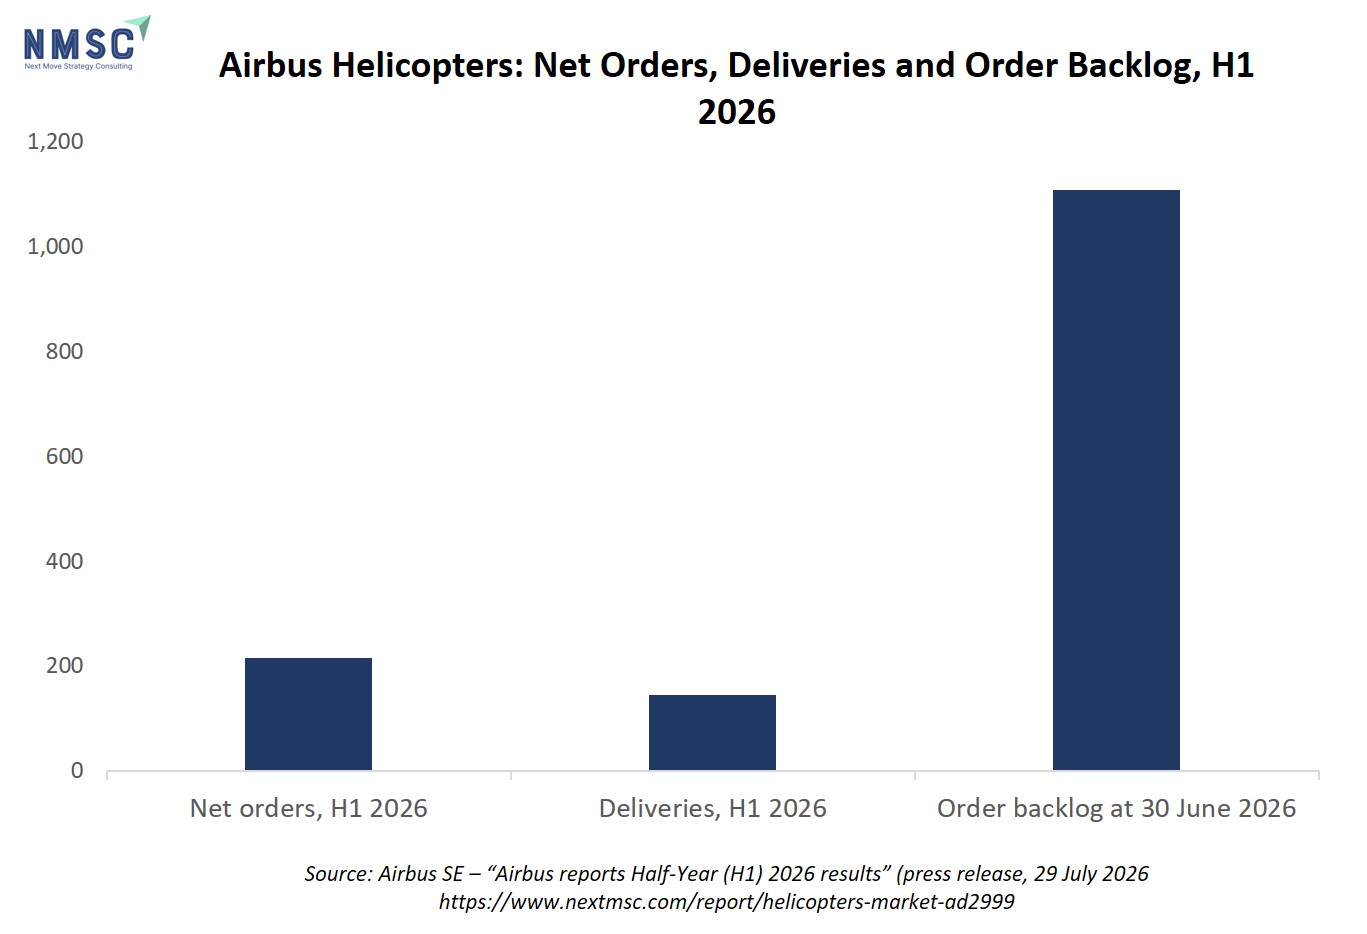
The full-year 2025 order data published by Airbus Helicopters in January 2026 provides the clearest quantitative evidence of how European defense spending is translating into rotorcraft procurement. Airbus logged 544 gross orders (net: 536) in 2025 — an increase of approximately 20% in unit terms over the prior year — from 205 customers across 50 countries. The company delivered 392 helicopters during the year, securing a 51% share of the civil and parapublic market and a 28% share of the military market.
The military order composition is particularly instructive. Spain placed a landmark order for 100 helicopters — including 50 H145Ms, 31 NH90s, 13 H135s, and 6 H175Ms — in a single sovereign procurement decision that reflects Spain's commitment to reaching the NATO 2.0% GDP spending threshold by 2029 [FlightGlobal H175M Spain Launch Customer]. Germany exercised an option for 20 additional H145Ms, bringing its total to 82, with first deliveries already completed. The H145 recorded 149 orders across civil and military variants in 2025, reaffirming its position as the best-selling rotorcraft in the Airbus portfolio.
"Airbus Helicopters' outstanding performance in 2025, marked by an order intake increase close to 20% in units, demonstrates that our modern civil and military portfolios are delivering the precise mission capabilities required in today's complex environment," said Bruno Even, CEO of Airbus Helicopters, in the company's January 2026 press release.
NMSC Strategic Perspective: What the Order Surge Signals for Market Structure
NextMSC primary research and analysis indicates that the 2025 order surge is not a cyclical spike but a structural inflection point driven by three reinforcing mechanisms. First, the retirement of legacy fleets — including the UK's Puma HC2 in March 2025 and Romania's aging IAR-330 Puma — is creating non-deferrable replacement demand that governments can no longer delay without operational capability gaps. Second, the NATO spending target revision agreed in 2025, which raised the benchmark above the previous 2% of GDP threshold, has unlocked defense budget allocations that were previously constrained by fiscal rules. Third, the convergence of crewed and uncrewed systems — exemplified by Airbus's HTeaming capability and the integration of Survey Copter into its core operations — is expanding the addressable mission set for rotorcraft platforms, making each new helicopter order a gateway to a broader ecosystem of drone, sensor, and data services revenue.
Section Summary:
The civil and military rotorcraft segments are simultaneously absorbing demand from two structurally distinct sources: EMS operators replacing aging light-twin fleets with the H140, and European NATO governments executing the fastest military helicopter procurement cycle since the Cold War.
-
Airbus Helicopters recorded a ~20% increase in unit orders in 2025, with 544 gross orders from 205 customers in 50 countries.
-
The H140 launch at VERTICON 2025 generated 74+ commitments and 61 firm orders within its debut year, targeting the EMS segment for 2028 entry into service.
-
Spain's 100-helicopter sovereign order and Germany's 82-unit H145M program represent the largest single-country rotorcraft procurement decisions in Europe in decades.
-
NextMSC primary research and analysis identifies fleet retirement cycles, revised NATO spending targets, and crewed-uncrewed teaming as the three structural drivers sustaining this demand beyond the current procurement wave.
Industry Impact Analysis
The Leonardo AW149 UK NMH Contract: A £1 Billion Capability Gap Closure
In March 2026, the UK Ministry of Defence awarded Leonardo a £1 billion ($1.3 billion) New Medium Helicopter (NMH) contract for the production of 23 AW149 multirole rotorcraft, to be built at Leonardo's Yeovil facility in England. The contract, confirmed in a written statement to the UK Parliament on 3 March 2026, secures 3,300 British jobs and positions Yeovil as Leonardo's global centre for military helicopter production and exports — with a potential export market value of £15 billion over the next decade.
The AW149 was selected to replace the Puma HC2 fleet, which was retired in March 2025, as well as smaller rotary fleets including Bell 212, Bell 412, and Airbus AS365 Dauphins. The platform's ability to consolidate three previously distinct aircraft types into a single airframe — capable of battlefield support, troop transport, Close Air Support, Search and Rescue, Medical Evacuation, and maritime patrol — directly reduces the UK Armed Forces' through-life maintenance cost burden while expanding operational flexibility.
Romania's H225M Order Under the EU SAFE Instrument
On 7 October 2026, the government of Romania signed a contract with Airbus Helicopters for 12 H225M multirole military helicopters, concluded with the French Armament General Directorate (DGA) under the European Commission's Security Action for Europe (SAFE) financial instrument. The SAFE mechanism — designed to accelerate defence readiness by funding urgent investments in European defence industry capacity — is emerging as a significant new procurement channel for rotorcraft, distinct from traditional bilateral government-to-government agreements.
"We are honoured that Romania has chosen the H225M to strengthen its defence capabilities. This selection will also bolster Romania's industrial capabilities through our long-term partnership with IAR, Romania's sole helicopter manufacturer," said Matthieu Louvot, CEO of Airbus Helicopters, in the company's October 2026 press release. The Romania contract is the second signed under the SAFE initiative, following an earlier order for seven H160 and five H145 helicopters for public services missions — demonstrating that the EU's new defence financing architecture is generating a pipeline of rotorcraft orders that bypasses traditional national budget constraints.
SIPRI 2025: The Defense Spending Architecture Underpinning Rotorcraft Demand
The macroeconomic foundation for military helicopter procurement is quantified in SIPRI's April 2026 report on world military expenditure. Global military spending reached $2,887 billion in 2025 — the 11th consecutive year of increase — with Europe recording a 14% rise to $864 billion, the sharpest annual growth in Central and Western European defense spending since the end of the Cold War. Germany's military expenditure grew by 24% year-on-year to $114 billion, exceeding the 2.0% of GDP threshold for the first time since 1990. Spain's defense spending increased by 50% to $40.2 billion, also crossing the 2.0% threshold for the first time since 1994. Asia and Oceania recorded an 8.1% increase to $681 billion — the largest annual rise since 2009.
"Global military spending rose again in 2025 as states responded to another year of wars, uncertainty and geopolitical upheaval with large-scale armament drives," said Xiao Liang, Researcher with SIPRI's Military Expenditure and Arms Production Programme, in the April 2026 SIPRI press release. "Given the range of current crises, as well as many states' long-term military spending targets, this growth will probably continue through 2026 and beyond."
The direct transmission mechanism from defense budget expansion to helicopter procurement is not automatic — it depends on fleet age, capability gaps, and industrial base capacity. However, the combination of legacy fleet retirements (UK Puma, Romanian IAR-330), new NATO spending targets, and the EU SAFE instrument means that the conversion rate from defense budget growth to rotorcraft orders is currently higher than at any point in the post-Cold War era.
Sikorsky S-92 TAP Renewals: The Aftermarket Signal from Offshore Energy
In March 2026, Lockheed Martin's Sikorsky announced that six S-92 helicopter operators had renewed multi-year Total Assurance Program (TAP) contracts during 2025 and early 2026, collectively covering nearly 100 aircraft. Bristow, the largest S-92 operator globally, renewed its TAP agreement in April 2025 to support approximately 60 aircraft. As of early 2026, 155 of the 270 active S-92 helicopters in the global fleet — 57% — are covered by TAP contracts, with nine operators receiving coverage in total.
"The past 10 months have seen strong demand by offshore energy companies to renew TAP aftermarket agreements into the early 2030s," said Leon Silva, Sikorsky Vice President, Global Commercial and Military Systems, in the March 2026 Lockheed Martin press release. "Multi-year coverage signals confidence in the reliability and endurance of the S-92 helicopter." The TAP renewals extending into the early 2030s indicate that offshore energy operators — whose helicopter utilization is directly tied to oil and gas field development cycles — are committing to sustained rotorcraft operations rather than transitioning to alternative transport modes, providing a stable demand floor for the heavy helicopter segment.
FAA Airworthiness Directive: Regulatory Compliance as an Aftermarket Revenue Driver
The FAA's issuance of Airworthiness Directive 2026-12-10 in June 2026, effective August 3, 2026, mandates inspection and potential cargo hook replacement across 898 Airbus AS350-series helicopters on the U.S. registry. The directive, prompted by a non-conformity report regarding cargo hook gap tolerances, requires operators to incur inspection costs of $85 per aircraft or replacement costs of up to $62,561 per aircraft where non-conformity is confirmed. While the individual cost per aircraft is modest, the directive illustrates a broader dynamic: regulatory compliance requirements generate non-discretionary aftermarket demand that is independent of operator fleet expansion decisions, providing MRO providers with a predictable revenue stream that is structurally insulated from market cyclicality.
Section Summary:
Four concurrent developments — the Leonardo AW149 UK NMH contract, Romania's EU SAFE-funded H225M order, SIPRI's documented 14% European defense spending surge, and Sikorsky's TAP renewal wave — collectively demonstrate that both the military and civil segments of the helicopters market are operating from a position of structural demand strength rather than cyclical recovery.
-
The UK's £1 billion AW149 NMH contract consolidates three legacy aircraft types into a single platform, reducing through-life costs while expanding mission capability.
-
Romania's H225M procurement under the EU SAFE instrument establishes a new multilateral financing channel for European rotorcraft orders that bypasses traditional national budget constraints.
-
SIPRI data confirms that 22 of 29 European NATO members now spend at least 2.0% of GDP on defense, creating a sustained procurement pipeline for military rotorcraft.
-
Sikorsky's TAP renewals — covering 57% of the active S-92 global fleet through the early 2030s — signal that offshore energy operators are committing to long-term rotorcraft operations, stabilizing the heavy helicopter aftermarket.
Key Data & Statistics
Key Competitive & Regulatory Events — Helicopters Market
|
Event |
Entity |
Date |
Value / Scale |
|
H140 unveiled at VERTICON; 118 commitments including 63 firm orders |
Airbus Helicopters |
March 2025 |
74+ H140 commitments at show |
|
Full-year 2025 order intake: 544 gross orders, ~20% unit growth |
Airbus Helicopters |
January 2026 |
392 deliveries; 51% civil/parapublic share |
|
UK NMH contract awarded for 23 AW149 helicopters |
Leonardo S.p.A. / UK MoD |
March 2026 |
£1B ($1.3B); 3,300 jobs secured |
|
Romania orders 12 H225M under EU SAFE instrument |
Airbus Helicopters / Romania |
October 2026 |
Undisclosed value; replaces IAR-330 Puma fleet |
|
Six S-92 operators renew multi-year TAP contracts |
Sikorsky (Lockheed Martin) |
2025–early 2026 |
~100 aircraft; 57% of active S-92 fleet covered |
|
FAA AD 2026-12-10: AS350 cargo hook inspection mandate |
FAA / Airbus Helicopters |
June 2026 (eff. Aug 2026) |
898 U.S.-registered aircraft affected |
|
World military expenditure reaches $2,887B; Europe +14% |
SIPRI |
April 2026 |
22 of 29 NATO members at ≥2.0% GDP |
Future Outlook & Forecast
The Path to USD 46.54 Billion: Structural Drivers Through 2030
NextMSC primary research and analysis projects the global helicopters market will reach USD 46.54 billion by 2030, growing at a 5.6% CAGR from 2025. Three structural forces will determine whether the market tracks toward the upper or lower bound of this range.
Military Procurement Continuity: SIPRI's April 2026 data confirms that outside the United States, global military spending grew by 9.2% in 2025. SIPRI researcher Xiao Liang noted that "given the range of current crises, as well as many states' long-term military spending targets, this growth will probably continue through 2026 and beyond." The U.S. Congress has approved military spending of over $1 trillion for 2026 — a substantial increase from 2025 — with the potential to rise further to $1.5 trillion in 2027 under the Trump administration's budget proposal. This trajectory directly supports demand for attack, transport, and maritime helicopter platforms across the U.S. military's rotary-wing fleet.
-
Civil Aviation and Air Transport Growth: The International Civil Aviation Organization (ICAO) projects that demand for air transport will grow at 4.3% annually over the next two decades, with rotorcraft playing an increasingly critical role in connecting remote areas, supporting offshore energy operations, and providing emergency medical services in both urban and rural environments.
-
eVTOL Infrastructure and Electric Propulsion Integration: The development of helicopter-integrated electric charging stations for eVTOL platforms represents the most significant long-term structural opportunity identified in NextMSC's analysis. As eVTOL operators — including those targeting commercial launch in cities such as Dubai in 2026 — require ground infrastructure that is architecturally compatible with existing helicopter operations, traditional rotorcraft OEMs and MRO providers are positioned to capture a share of the eVTOL support ecosystem without requiring fundamental platform redesign.
-
Asia-Pacific as the Growth Frontier: The World Travel & Tourism Council reported that China's travel and tourism sector contributed USD 950 billion to the Chinese economy in 2024. This expansion in premium and remote-access tourism is generating demand for rotorcraft services — particularly in luxury sightseeing, island connectivity, and high-altitude access — that is structurally distinct from the defense-driven demand in Europe. The presence of Airbus Helicopters, Hindustan Aeronautics Limited, and Korea Aerospace Industries in the region, combined with Airbus's new H125 Final Assembly Line in Vemagal, Karnataka, India (inaugurated in 2026), positions Asia-Pacific as the market's fastest-growing regional segment through 2030.
Section Summary:
The helicopters market's path to USD 46.54 billion by 2030 is supported by four concurrent structural forces: sustained European and Asian defense spending growth, ICAO-projected civil air transport expansion, eVTOL infrastructure integration, and Asia-Pacific tourism-driven rotorcraft demand.
-
SIPRI confirms that outside the U.S., global military spending grew 9.2% in 2025, with European NATO members executing the fastest rearmament cycle since 1953.
-
U.S. Congressional military spending for 2026 has been approved at over $1 trillion, with potential to reach $1.5 trillion in 2027.
-
ICAO projects 4.3% annual air transport demand growth over the next two decades, sustaining civil rotorcraft utilization across EMS, offshore, and remote-access missions.
-
Airbus's new H125 FAL in India and the EU SAFE procurement instrument are creating new regional and multilateral demand channels that were not present in the prior market cycle.
Next Steps for Stakeholders
-
For Defense Procurement Executives and Government Ministries: The EU SAFE instrument has demonstrated, through Romania's H225M order, that multilateral EU financing can accelerate rotorcraft procurement decisions that would otherwise be constrained by national budget timelines. Defense ministries in Central and Eastern Europe with aging Soviet-era or legacy Western fleets should assess SAFE eligibility for their rotary-wing modernization programs before the instrument's current funding cycle closes.
-
For OEM Strategy and Business Development Teams: The H140's launch-year order performance — 61 firm orders within nine months of unveiling — establishes a benchmark for how platform launches should be structured: EMS operator co-development, show-floor commitment mechanisms, and a clear entry-into-service timeline. OEMs planning next-generation platform introductions should replicate this customer-co-design model rather than relying on traditional specification-driven procurement cycles.
-
For MRO and Aftermarket Investors: Sikorsky's TAP renewal wave — covering 57% of the active S-92 fleet through the early 2030s — demonstrates that power-by-the-hour aftermarket models generate multi-year revenue visibility that is structurally superior to transactional parts sales. MRO providers serving the offshore energy and search-and-rescue segments should prioritize long-term service agreement structures over spot-market parts supply, particularly as AI-driven Health and Usage Monitoring System (HUMS) data enables condition-based maintenance regimes that reduce unplanned downtime and extend time between major overhauls.
-
For Institutional Investors and Private Equity: The helicopters market's 5.6% CAGR through 2030, as projected by NextMSC primary research and analysis, is underpinned by non-discretionary demand drivers — fleet retirement cycles, regulatory compliance mandates, and sovereign defense commitments — that are structurally insulated from consumer sentiment cycles. The aftermarket segment, in particular, offers margin profiles and revenue predictability that are attractive relative to the OEM segment's exposure to program delays and budget disputes (as illustrated by the UK NMH contract's multi-year delay).
-
For Civil Aviation and Tourism Operators: Asia-Pacific's tourism-driven rotorcraft demand — anchored by China's USD 950 billion travel and tourism contribution in 2024 — is creating commercial opportunities in luxury sightseeing, remote-access transport, and offshore connectivity that are distinct from the EMS and defense segments. Operators entering this market should prioritize platforms with low single-pilot operating costs and high payload flexibility, such as the H125 and H145, which are already supported by Airbus's expanding Asia-Pacific industrial base.
Conclusion
The global helicopters market is not experiencing a single trend — it is experiencing a structural realignment across every major demand segment simultaneously. European NATO rearmament is generating sovereign procurement orders at a pace not seen since the Cold War. The civil EMS segment is absorbing a new generation of light-twin platforms, led by the H140, that will define the competitive landscape for the next two decades. The offshore energy sector is locking in decade-long aftermarket commitments that signal sustained operational confidence in heavy rotorcraft. And the EU SAFE instrument is establishing a new multilateral financing architecture that could fundamentally change how European rotorcraft procurement is funded and sequenced.
According to NextMSC primary research and analysis, the global helicopters market is projected to grow from USD 33.53 billion in 2024 to USD 46.54 billion by 2030 at a 5.6% CAGR — a trajectory that reflects the depth and durability of these structural forces rather than a cyclical recovery. For C-level executives, institutional investors, and defense procurement decision-makers, the strategic imperative is clear: the window for positioning in this market — whether through platform investment, aftermarket consolidation, or sovereign procurement alignment — is open now, and the structural drivers that are widening it will not remain in place indefinitely.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment