Vertiv’s Orders More Than Double as AI Racks Push Power Design to 800 V
Vertiv’s 100%-Plus Organic Order Growth, Schneider Electric’s Triple-Digit Data Center Demand and Infineon’s 27 kW Reference Design Show AI Power Equipment Moving From Specification to Contract
On October 28, 2026, Vertiv Holdings Co reported third-quarter net sales of $4,313 million, 61% above the same quarter a year earlier, and disclosed that its organic orders grew by more than 100% year over year. Vertiv does not publish an absolute order figure, so the growth rate is the signal: customers placed more than twice the organic order value they placed in the third quarter of 2025. Net sales rose 75% in the Americas, 50% in Asia Pacific and 23% in Europe, Middle East and Africa, according to the company’s third-quarter results release filed with the U.S. Securities and Exchange Commission on Form 8-K. Vertiv also raised its full-year 2026 guidance, which now centers on net sales of $14,650 million and organic sales growth of 38%.
According to Next Move Strategy Consulting’s AI Power Management Market report, the global AI power management market was valued at USD 15.80 billion in 2025 and is projected to reach USD 96.00 billion by 2035, growing at a CAGR of 18.2% from 2026 to 2035. NextMSC primary research and analysis places 2026 revenue at USD 21.30 billion and identifies escalating accelerator power draw, the shift from 54 V DC to 800 V DC rack architectures and hyperscale and neocloud capital spending as the three largest forces behind that trajectory, with North America holding about 48% of 2025 revenue. Vertiv’s results show those forces converting into purchase orders.
For More Information: Download FREE Sample on AI Power Management Market Report
The Financial Logic: Prepaid Projects, Rising Inventory and Capital Spending at Vertiv
The balance sheet in Vertiv’s Form 10-Q for the quarter ended September 30, 2026 shows how that demand is being financed and fulfilled. Current deferred revenue, which records customer payments received ahead of delivery, reached $4,120.5 million at September 30, 2026, against $1,814.7 million at December 31, 2025. Inventories rose to $3,288.4 million from $1,456.5 million over the same nine months, and capital expenditures for the nine months ended September 30, 2026 totaled $425.0 million, up from $126.7 million in the same period of 2025. The three lines describe a supplier whose customers are prepaying for equipment that has not yet shipped, and which is building stock and factory capacity to deliver it.
On Vertiv’s October 28, 2026 earnings call, Chief Executive Officer Giordano Albertazzi rejected the reading that the order surge reflects catch-up demand. He said the Americas pipeline grew faster sequentially than at any point this year, that the Europe, Middle East and Africa pipeline roughly doubled from a year earlier, and that organic orders in Asia Pacific rose substantially. He also stated that Vertiv counts as backlog only signed purchase orders, not capacity agreements, which makes its backlog a stricter measure of committed demand.
“We are in the middle of the largest infrastructure buildout and it’s accelerating.”
- Giordano Albertazzi, Chief Executive Officer, Vertiv Holdings Co, Vertiv third-quarter 2026 results press release (Form 8-K), October 28, 2026.
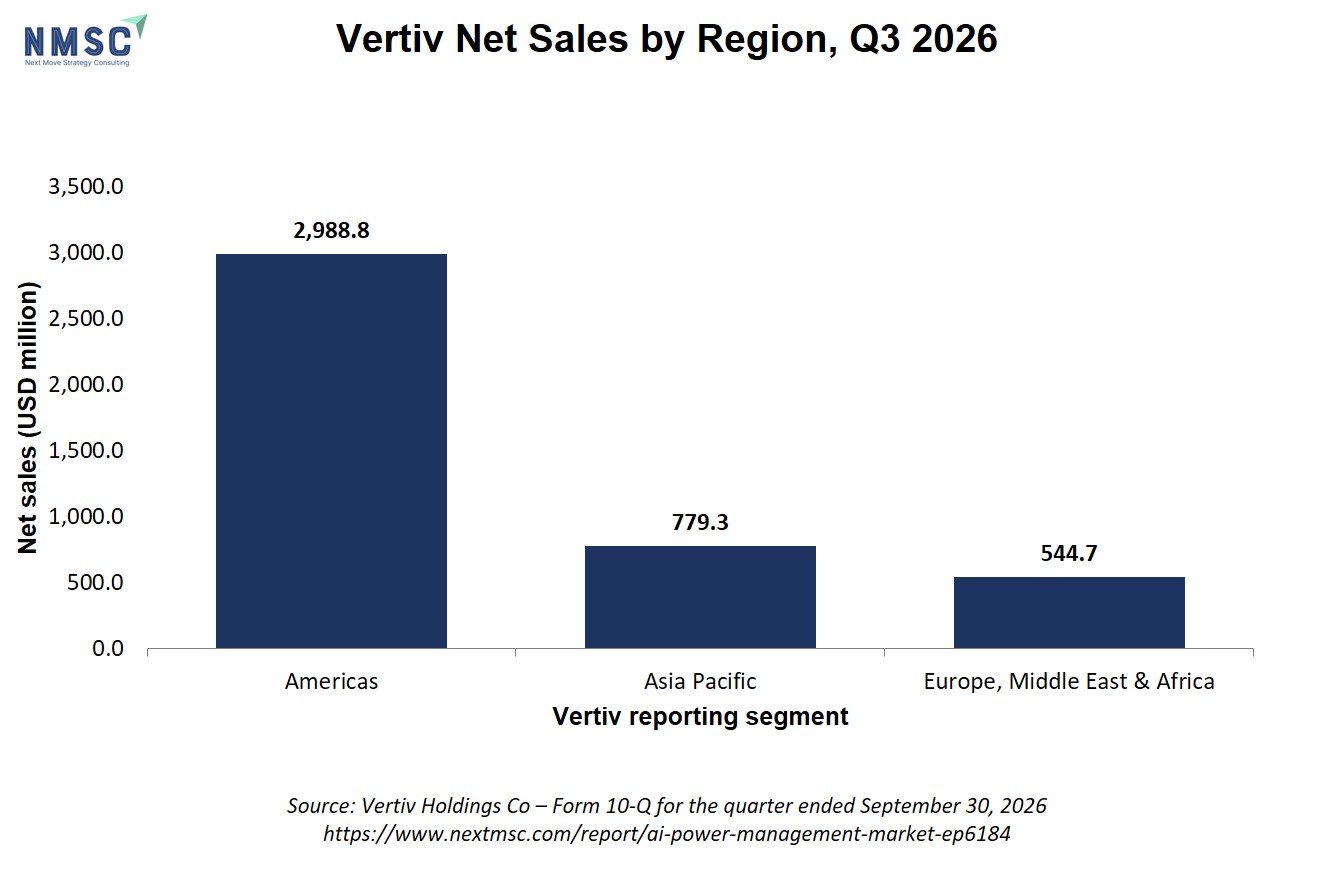
The geography of that growth matters for the power chain. The Form 10-Q reports third-quarter net sales of $2,988.8 million in the Americas, $779.3 million in Asia Pacific and $544.7 million in Europe, Middle East and Africa, compared with $1,712.4 million, $519.8 million and $443.6 million a year earlier. The Americas alone supplied $1,276.4 million of the $1,637.0 million year-over-year increase in net sales. NextMSC primary research and analysis shows the same concentration in the wider market: North America generated USD 7.60 billion of 2025 revenue and is projected to reach USD 42.00 billion by 2035.
Why Rack Power Is Being Redesigned: Grid Load and Copper
The physical constraint behind the orders is electricity. The International Energy Agency (IEA), in its special report Energy and AI (April 2025), put global data center electricity consumption at 415 TWh in 2024, about 1.5% of world electricity, and projected that it would more than double to around 945 TWh by 2030, with demand from AI-optimized data centers more than quadrupling. The IEA found that the United States accounted for 45% of 2024 data center consumption, followed by China at 25% and Europe at 15%, and that data centers account for nearly half of U.S. electricity demand growth to 2030. Across its 2035 cases, the agency’s range for global data center demand spans 700 TWh to 1,700 TWh, a range that bounds how much power equipment the build-out will require.
NVIDIA’s technical blog NVIDIA 800 VDC Architecture Will Power the Next Generation of AI Factories (May 2025, updated July 31, 2025) explained why 54 V DC distribution breaks down at megawatt scale. The blog stated that a single 1 MW rack on 54 VDC requires up to 200 kg of copper busbar, and that moving from 415 VAC to 800 VDC distribution allows 85% more power to pass through the same conductor size. NVIDIA said full-scale production of 800 VDC data centers would coincide with its Kyber rack-scale systems in 2027, and it named Eaton, Schneider Electric and Vertiv among its data center power system partners and Infineon, STMicroelectronics and Texas Instruments among its silicon providers.
Key Industry Developments: Power-Chain Moves From March to October
The supplier announcements of 2026 follow that architecture. On March 16, 2026, Texas Instruments unveiled a complete 800 VDC power architecture built on the NVIDIA 800 VDC reference design, with a topology that requires only two conversion stages between 800 V and processor power, and showed it at NVIDIA GTC 2026. On October 8, 2026, Infineon introduced a 27 kW three-phase power supply unit reference design for AI server racks that meets the Open Compute Project’s Open Rack V3 specification. The design reaches a power density of 116 W/in³ against the specification’s 94 W/in³ minimum and accepts a three-phase input of 311–528 VAC, which Infineon said suits a range of global grid standards.
On October 16, 2026, Schneider Electric reported record third-quarter revenue of €11.46 billion, up 17.9% and 16.9% organically, and raised its 2026 organic revenue growth target to 12–14% from 10–13%, its second increase of the year, according to Reuters. Chief Executive Officer Olivier Blum said data centers remained a key growth driver, with triple-digit demand growth in the quarter. Schneider Electric’s Energy Management segment, which sells power and cooling equipment to data centers, grew 18.8% organically to €9.62 billion. Vertiv closed its acquisition of UtilityInnovation Group on October 26, 2026, paying $1.45 billion in cash with up to $1.15 billion of additional contingent consideration, according to its Form 10-Q. The target designs power systems that balance load and frequency behind the meter for AI data center workloads.
Five Dated Power-Chain Events, March to October 2026
|
Date |
Company |
Event |
Reported detail |
|
March 16, 2026 |
Texas Instruments |
Unveiled an 800 VDC power architecture with NVIDIA |
Two conversion stages from 800 V to processor power |
|
October 8, 2026 |
Infineon |
Introduced a 27 kW three-phase PSU reference design |
116 W/in³ versus the 94 W/in³ Open Rack V3 minimum; 311–528 VAC input |
|
October 16, 2026 |
Schneider Electric |
Reported Q3 results and raised 2026 targets |
Revenue €11.46 billion, up 17.9%; data center demand growth in triple digits |
|
October 26, 2026 |
Vertiv |
Closed the UtilityInnovation Group acquisition |
$1.45 billion in cash plus up to $1.15 billion contingent |
|
October 28, 2026 |
Vertiv |
Reported Q3 results |
Net sales $4,313 million, up 61%; organic orders growth above 100% |
Segment Dynamics: Distribution and 800 V DC Grow Fastest
NextMSC primary research and analysis shows that rack power supplies and systems were the largest offering in 2025 at USD 6.60 billion, about 42% of revenue, because every AI server requires shelf-level conversion. Power distribution systems are the fastest-growing offering at a 21.3% CAGR from 2026 to 2035, as row power centers and 800 VDC busways planned for 2027 reach volume. Power semiconductors and ICs grow from USD 4.30 billion in 2025 to USD 27.50 billion in 2035, and management software and services reach USD 8.50 billion in 2035.
AI Power Management Market by Offering
|
Offering |
2025 (USD billion) |
2035 (USD billion) |
CAGR, 2026–2035 |
|
Power semiconductors and ICs |
4.30 |
27.50 |
18.7% |
|
Rack power supplies and systems |
6.60 |
35.00 |
16.6% |
|
Power distribution systems |
3.30 |
25.00 |
21.3% |
|
Management software and services |
1.60 |
8.50 |
16.2% |
By rack power architecture, up to 54 V DC remains the largest segment at USD 14.20 billion in 2025, expanding to USD 30.00 billion by 2035 at a 6.1% CAGR. NextMSC primary research and analysis shows 800 V DC growing at 50.7% from 2026 to 2035, from USD 1.20 billion in 2026 to USD 48.00 billion in 2035, which lifts its share of revenue from about 6% to 50%. By end user, hyperscale cloud providers led in 2025 at USD 8.90 billion and reach USD 47.00 billion by 2035, while colocation and neocloud providers are the fastest-growing at 19.8%, because operators that sell megawatts gain billable compute by fitting more load inside a fixed grid allocation.
Regional Outlook
North America held about 48% of global revenue in 2025, or USD 7.60 billion, and is projected to reach USD 42.00 billion by 2035 at a 17.3% CAGR, anchored by hyperscale campus buildouts and early 800 V DC platform launches. The U.S. generated USD 6.70 billion in 2025 and is projected to reach USD 36.00 billion by 2035 at 16.9%. Asia-Pacific grows at 19.2% from USD 5.30 billion to USD 35.00 billion, supported by a deep server power supply manufacturing base in Taiwan and China. Middle East & Africa is the fastest-growing region at 21.0%, because greenfield AI campuses in the Gulf can specify 400 V DC and 800 V DC architectures at the design stage, and India is among the fastest-growing major countries at 27.2% from a base of USD 0.35 billion. All figures in this section are NextMSC primary research and analysis.
AI Power Management Market by Region
|
Region |
2025 (USD billion) |
2035 (USD billion) |
CAGR, 2026–2035 |
|
North America |
7.60 |
42.00 |
17.3% |
|
Europe |
1.90 |
11.00 |
17.4% |
|
Asia-Pacific |
5.30 |
35.00 |
19.2% |
|
Middle East & Africa |
0.60 |
5.00 |
21.0% |
|
Latin America |
0.40 |
3.00 |
19.6% |
Growth Drivers and Restraints
The IEA warned that unless electricity grid risks are addressed, around 20% of planned data center projects could be at risk of delays, and grid interconnection is the largest single restraint in NextMSC’s forecast. The matrix below quantifies how much each factor moves the forecast CAGR.
AI Power Management Market: Growth Catalyst and Risk Assessment Matrix
|
Factor |
Type |
Impact on CAGR |
Geography |
Timeline |
|
Escalating accelerator and rack power draw |
Driver |
+4.8% |
Global; strongest in North America and Asia-Pacific |
2026–2035 |
|
Shift to 400 V DC and 800 V DC architectures |
Driver |
+3.9% |
North America, Asia-Pacific |
2026–2032 |
|
Hyperscale and neocloud capital spending |
Driver |
+3.2% |
North America, Middle East & Africa |
2026–2030 |
|
Efficiency and operating cost pressure |
Driver |
+2.1% |
Global |
2026–2035 |
|
Wide bandgap device adoption |
Driver |
+1.6% |
Global |
2026–2033 |
|
Grid interconnection and power availability limits |
Restraint |
−3.4% |
North America, Europe |
2026–2030 |
|
Supply chain concentration and capacity constraints |
Restraint |
−1.8% |
Global |
2026–2028 |
|
Standards fragmentation for high-voltage DC safety |
Restraint |
−1.4% |
Global |
2026–2029 |
|
Volatility in AI capital spending cycles |
Restraint |
−1.2% |
Global |
2027–2035 |
NMSC Strategic Perspective: Rack Power Becomes a Design Decision, Not a Purchase
NextMSC primary research and analysis reads Vertiv’s October 28, 2026 results as evidence that rack power architecture has moved from a downstream procurement item to a core design decision taken at campus level. Prepaid projects at Vertiv, triple-digit data center demand at Schneider Electric, and reference designs from Texas Instruments and Infineon that supply the conversion stages for next-generation racks all point to suppliers being selected before facilities are built. That timing is why NMSC’s forecast has 800 V DC revenue rising from USD 1.20 billion in 2026 to USD 48.00 billion in 2035.
The same analysis separates three vendor archetypes: semiconductor specialists that sell conversion stages, power system makers that sell shelves and racks, and infrastructure groups that sell distribution and services. NMSC’s strategic recommendation is that silicon suppliers secure reference design status for 800 V conversion stages, that power system makers qualify modular racks for both 54 V DC and 800 V DC, and that infrastructure groups invest in row power centers and busway capacity ahead of 2027, while pairing hardware with monitoring software to defend margins.
For investors, NextMSC primary research and analysis identifies an absolute revenue opportunity of USD 74.70 billion between 2026 and 2035. Capacity-constrained suppliers with visible backlog appear better placed than vendors dependent on a single platform launch, and Middle East & Africa at 21.0% adds geographic upside. The principal risks are grid interconnection delays, which NMSC estimates trim the forecast CAGR by about 3.4%, standards fragmentation for high-voltage DC at about 1.4%, and volatility in AI capital spending cycles. The IEA’s 700–1,700 TWh range for 2035 data center demand shows how wide that uncertainty remains.
Competitive Landscape
NextMSC primary research and analysis profiles eight vendors that currently lead the market: Delta Electronics, Vertiv, Eaton, Schneider Electric, Infineon, Monolithic Power Systems, Texas Instruments and STMicroelectronics. Silicon suppliers compete for socket-level design positions, while system and infrastructure vendors compete on delivery capacity and project execution, and pricing favors long-term supply agreements with hyperscalers.
Dated events are consistent with that structure. Vertiv closed the UtilityInnovation Group acquisition on October 26, 2026, extending its portfolio into behind-the-meter load and frequency balancing. Texas Instruments and Infineon published rack power reference designs in March and October 2026. NVIDIA named Eaton, Schneider Electric and Vertiv as 800 VDC data center power partners in its May 2025 technical blog, and two of the three, Vertiv and Schneider Electric, have since reported triple-digit data center order or demand growth in October 2026.
Bottom Line
Vertiv’s October 28, 2026 results, with third-quarter net sales of $4,313 million and organic orders growth above 100%, show AI power management moving from specification to contracted delivery. Schneider Electric’s triple-digit data center demand growth, Infineon’s 27 kW reference design and Texas Instruments’ two-stage 800 VDC architecture show the same shift at the component level. According to NextMSC primary research and analysis, the global AI power management market will expand from USD 15.80 billion in 2025 to USD 96.00 billion by 2035 at an 18.2% CAGR, with 800 V DC rising from USD 1.20 billion in 2026 to USD 48.00 billion, North America holding about 48% of 2025 revenue and Middle East & Africa growing fastest at 21.0%. The IEA’s projection of around 945 TWh of data center electricity demand by 2030 explains why conversion, distribution and control equipment is ordered ahead of facilities. Grid interconnection limits remain the main risk to timing, so vendors with backlog and capacity are best placed to capture the USD 74.70 billion opportunity.
About Next Move Strategy Consulting
Next Move Strategy Consulting is a premier market research and management consulting firm that has been committed to provide strategically analysed well documented latest research reports to its clients. The research industry is flooded with many firms to choose from, what makes NMSC different from the rest is its top-quality research and the obsession of turning data into knowledge by dissecting every bit of it and providing fact-based research recommendation that is supported by information collected from over 500 million websites, paid databases, industry journals and one on one consultations with industry experts across a diverse range of industry sectors. The high-quality customized research reports with actionable insights and excellent end-to-end customer service help our clients to take critical business decisions that enables them to move beyond time and have competitive edge in the industry.
We have been servicing over 1000 customers globally that includes 90% of the Fortune 500 companies over a decade. Our analysts are constantly tracking various high growth markets and identifying hidden opportunities in each sector or the industry. We provide one of the industry’s best quality syndicate as well as custom research reports across 10 different industry verticals. We are committed to deliver high quality research solutions in accordance to your business needs. Our industry standard delivery solutions that ranges from the pre consultation to after-sales services, provide an excellent client experience and ensure right strategic decision making for businesses.
For more information, please contact:
Next Move Strategy Consulting
5th Floor 867 Boylston St, STE 500,
Boston, MA 02116, U.S.
E-Mail: [email protected]
Direct: +1-217-650-7991
Website: www.nextmsc.com
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.










Add Comment