AMR Fleet Management Market Global Industry Analysis and Forecast (2026–2035)

AMR Fleet Management Market size was USD 994.97 Million in 2025, projected to reach USD 3,187.39 Million by 2035, growing at a CAGR of 11.5% from 2026 to 2035. Key drivers include rising AMR deployment density creating multi-robot coordination software demand, accelerating e-commerce fulfilment investment, and the transition from single-vendor to independent multi-vendor fleet architectures, with North America leading the global market.
Download Free Sample PDF
Base Year (2025)
$995.0 Million
Forecast (2035)
$3,187.4 Million
CAGR (2026-2035)
11.5%
Top Region
North America

What Is the AMR Fleet Management Market Size?
The global AMR Fleet Management Market reached USD 994.97 Million in 2025 and is estimated at USD 1,196.05 Million in 2026, forecast to reach USD 3,187.39 Million by 2035 at a CAGR of 11.5% between 2026 and 2035. North America leads with approximately 40% revenue share in 2025, while Fleet Management Software is the dominant offering, holding approximately 60% of total market revenue.
We observed that the maturation of autonomous mobile robot hardware deployments across warehouse and manufacturing environments is now driving proportionally larger investment in the fleet management software and services layer, as operators managing tens or hundreds of robots cannot sustain throughput efficiency without purpose-built coordination, analytics, and maintenance management platforms.

AMR Fleet Management Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast
Values in USD Million

2025 $995.0 Million
2025
2026 $1,196.1 Million
2026
2027 $1,333.6 Million
2027
2028 $1,487.0 Million
2028
2029 $1,658.0 Million
2029
2030 $1,848.6 Million
2030
2031 $2,061.2 Million
2031
2032 $2,298.3 Million
2032
2033 $2,562.6 Million
2033
2034 $2,857.3 Million
2034
2035 $3,187.4 Million
2035

Key Takeaways

By Offering: Fleet Management Software held the largest share, expanding from USD 596.98 Million in 2025 to USD 1,753.06 Million by 2035; Fleet Management Services is the fastest-growing at 13.68% CAGR from 2026–2035.

By Fleet Compatibility: Single-Vendor held the largest share, expanding from USD 497.49 Million in 2025 to USD 1,148.46 Million by 2035; Independent Multi-Vendor is the fastest-growing at 17.77% CAGR from 2026–2035.

By Software Delivery: Vendor Hosted Cloud held the largest share, expanding from USD 447.49 Million in 2025 to USD 1,657.81 Million by 2035; Hybrid is the fastest-growing at 16.30% CAGR from 2026–2035.

By Operating Environment: Indoor held the largest share, expanding from USD 696.48 Million in 2025 to USD 1,689.26 Million by 2035; Hybrid is the fastest-growing at 19.20% CAGR from 2026–2035.

By Primary Workflow: Transportation held the largest share, expanding from USD 397.99 Million in 2025 to USD 1,053.84 Million by 2035; Inspection is the fastest-growing at 16.73% CAGR from 2026–2035.

By End User Industry: Warehousing and Logistics held the largest share, expanding from USD 348.24 Million in 2025 to USD 956.22 Million by 2035; Healthcare and Life Sciences is the fastest-growing at 15.31% CAGR from 2026–2035.

By Buyer Type: End User Operator held the largest share, expanding from USD 497.49 Million in 2025 to USD 1,115.73 Million by 2035; Automation Service Provider is the fastest-growing at 20.41% CAGR from 2026–2035.

By Sales Channel: Direct held the largest share, expanding from USD 348.24 Million in 2025 to USD 860.65 Million by 2035; Distributor or Reseller Led is the fastest-growing at 18.56% CAGR from 2026–2035.

By Revenue Model: Subscription Revenue held the largest share, expanding from USD 447.49 Million in 2025 to USD 1,594.53 Million by 2035; Consumption Revenue is the fastest-growing at 16.21% CAGR from 2026–2035.

By Customer Size: Large Enterprise held the largest share, expanding from USD 746.23 Million in 2025 to USD 2,167.42 Million by 2035; SME is the fastest-growing at 15.18% CAGR from 2026–2035.

By Fleet Scale: Large Fleet held the largest share, expanding from USD 348.24 Million in 2025 to USD 1,020.52 Million by 2035; Small Fleet is the fastest-growing at 14.43% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 40% revenue share in 2025, anchored by large-scale e-commerce and third-party logistics warehouse deployments.

Fastest-Growing Region: Latin America is expected to register the highest CAGR of 20.39% during 2026–2035, driven by expanding organized retail and manufacturing robotics investment.

Dominant Country: The U.S. led the market with an estimated USD 338.29 Million in 2025, supported by the highest AMR installed-base density globally.

Fastest-Growing Country: India is among the fastest-growing major countries, projected to expand from USD 49.75 Million in 2025 at a CAGR of approximately 15.18%, driven by rapid warehouse automation adoption.

The AMR Fleet Management Market presents an absolute investment opportunity of approximately USD 1,991.34 Million between 2026 and 2035, calculated as the difference between the 2035 forecast of USD 3,187.39 Million and the 2026 base of USD 1,196.05 Million, making cloud-based fleet management software and multi-vendor fleet coordination platforms the most capital-efficient categories for robotics technology investors.
According to NMSC analysis, the shift toward independent multi-vendor fleet management platforms is the most structurally significant trend in the market, as operators who have invested in robots from multiple manufacturers are generating demand for vendor-agnostic coordination software that no single AMR hardware vendor can profitably supply on its own.

Ecosystem Analysis of the AMR Fleet Management Industry

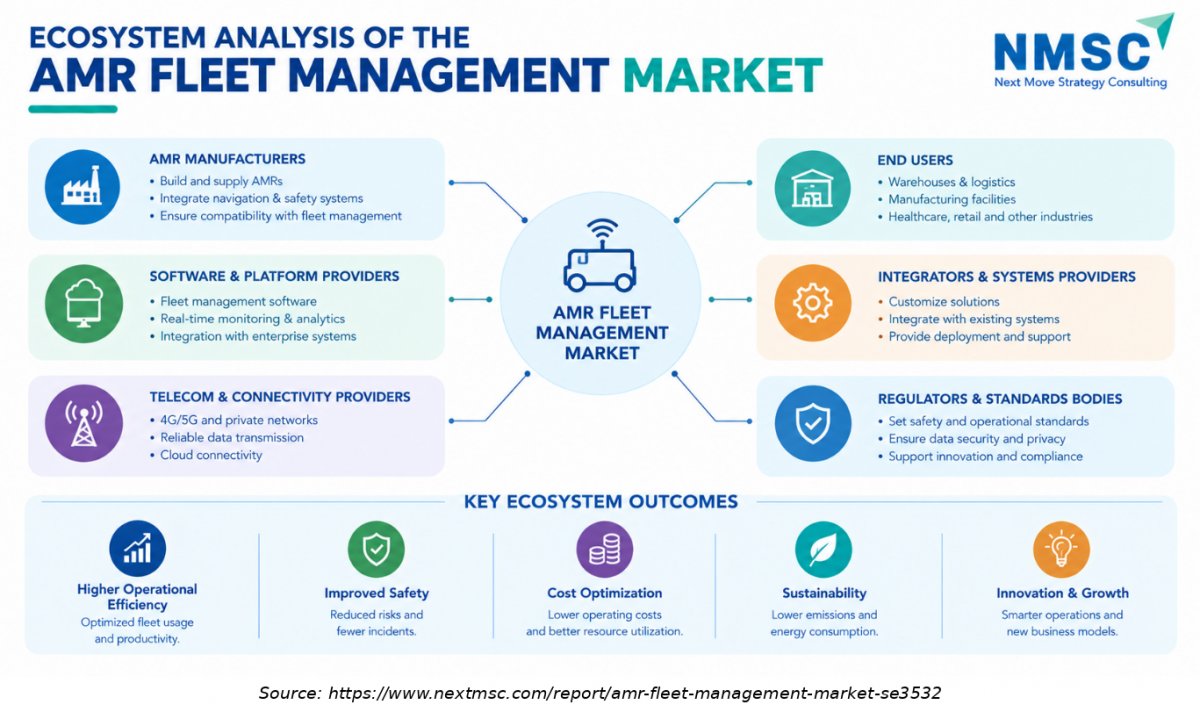
The above infographic presents the AMR Fleet Management Market ecosystem in a simpler format, focusing on six core stakeholder groups: AMR manufacturers, software providers, connectivity providers, end users, systems integrators, and regulators. It shows how these participants support fleet management while contributing to operational efficiency, safety, cost optimization, sustainability, and innovation across automated environments.
What does the AMR Fleet Management Market Encompass?
The AMR Fleet Management Market covers software platforms and associated services designed to coordinate, monitor, optimize, and maintain fleets of autonomous mobile robots across warehousing, manufacturing, healthcare, and other operating environments. It includes standalone and embedded fleet management software, cloud-hosted and on-premises delivery models, and a full range of deployment, managed operations, and support services. The market excludes the AMR hardware itself, capturing only the software and services layer that sits above robot firmware. Growing integration with warehouse management system platforms is expanding the functional scope of fleet management software into task orchestration, inventory visibility, and labor management domains previously handled by adjacent enterprise systems.
Market Drivers & Dynamics

Interactive Dataset
Rising AMR deployment density creating multi-robot coordination software demand driver +3.2% Global 2026–2035
E-commerce order volume growth accelerating warehouse robotics and FMS investment driver +2.4% North America, Asia-Pacific 2026–2035
Shift from single-vendor to multi-vendor fleets creating independent FMS demand driver +1.8% Global 2026–2033
Cloud-based subscription FMS models lowering adoption barrier for SME operators driver +1.4% North America, Europe, Asia-Pacific 2026–2032
AI-enabled fleet optimization and predictive maintenance improving ROI documentation driver +1.1% North America, Europe 2026–2031
Integration complexity with legacy warehouse management and ERP systems slowing adoption restraint −1.2% Global 2026–2035
Cybersecurity risk in cloud-connected robot fleets creating enterprise hesitancy restraint −0.8% North America, Europe 2026–2033
Shortage of qualified robotics integration engineers limiting deployment pace restraint −0.6% Latin America, MEA 2026–2031
High upfront licensing cost for enterprise-scale FMS limiting mid-market adoption restraint −0.4% Latin America, MEA 2026–2030
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the AMR Fleet Management Industry?

Rising AMR deployment density is the primary structural driver of the AMR Fleet Management Market. As warehouse operators scale from pilot fleets of 10 to 20 robots toward production deployments of 100 or more units, manual coordination approaches fail, and purpose-built fleet management software becomes operationally essential. Industry-derived estimates indicate that the global AMR installed base is expanding at above-market rates, creating a compounding software demand signal as each new hardware installation requires ongoing fleet management software licensing or subscription. Integration with intralogistics software platforms is further expanding FMS scope and contract value across large-scale warehouse deployments.

How Is E-Commerce Growth Driving the Market?

E-commerce order volume growth is creating sustained investment pressure on fulfilment operators to deploy and manage larger AMR fleets to meet next-day and same-day delivery service level requirements. Our findings suggest that third-party logistics providers and e-commerce fulfilment operators are among the fastest-growing buyer cohorts for fleet management software, as their multi-site, multi-robot operating environments require centralized fleet visibility, cross-site performance benchmarking, and automated maintenance scheduling at a scale that point-of-deployment AMR OEM tools cannot support. The U.S. Census Bureau's quarterly e-commerce retail sales data confirms sustained growth in online retail share, supporting multi-year AMR fleet expansion investment.

Growth Inhibitors

What Is Restraining the AMR Fleet Management Market?

The primary restraint is integration complexity between AMR fleet management software and the existing layers of enterprise technology, warehouse management systems, ERP platforms, manufacturing execution systems, and SCADA environments that operators require FMS platforms to connect with before deployment can begin. We found that integration projects frequently extend timelines by 30 to 60 days beyond initial estimates, increasing total deployment cost and delaying the software revenue recognition that fleet management software vendors depend on for recurring subscription growth. This friction is most pronounced in brownfield manufacturing environments where legacy system architectures pre-date the API connectivity standards that modern FMS platforms require.

What Are the Growth Opportunities?

Can Independent Multi-Vendor FMS Platforms Capture the Heterogeneous Fleet Transition?

Enterprises operating AMR fleets from two or more hardware vendors represent the fastest-growing buyer cohort in the AMR Fleet Management Market and are generating demand for independent FMS platforms that no single OEM can address without competitive conflict. The concrete mechanism is standardized VDA 5050 and MassRobotics protocol integration, enabling fleet management software to reach all deployed robots regardless of brand. This opportunity primarily benefits the Independent Multi-Vendor segment and the Automation Service Provider buyer type, both of which are positioned to capture contract value from enterprise operators unwilling to rebuild their hardware investment around a single OEM's management stack.

Does SME Adoption of Cloud FMS Represent an Untapped Volume Opportunity?

Small and medium-sized enterprises represent the market's largest untapped buyer segment, as the subscription pricing of cloud-based FMS platforms is now reaching levels accessible to operators with fleets as small as five to ten robots. The mechanism is per-robot monthly subscription pricing that converts upfront licensing cost into a variable operational expense, enabling SME operators to initiate fleet management software adoption at initial deployment scale. This opportunity benefits the Vendor Hosted Cloud software delivery segment and the SME customer size segment, both of which are growing above overall market CAGR. The supply chain management software integration that SME operators require alongside FMS is accelerating bundle adoption through integrator-led channel partnerships.

Can Healthcare Fleet Management Become a Distinct Premium Vertical Market?

Healthcare and Life Sciences is the fastest-growing major end-user industry at 15.31% CAGR, driven by hospital systems, pharmaceutical manufacturers, and healthcare distribution operators deploying AMRs under strict regulatory and safety requirements that general-purpose warehouse FMS platforms cannot fully address without vertical-specific certification and workflow customization. The opportunity mechanism is purpose-built healthcare fleet management software with native EMR connectivity, sterile zone access control, and HIPAA-compliant telemetry logging. Vendors who build validated healthcare FMS solutions benefit from longer contract cycles, higher switching costs, and regulatory credentialing that creates durable account retention relative to general warehouse FMS deployments.

Segmentation Analysis

2025 (USD Million)
2035 (USD Million)
Fleet Management Software 2025: $597.0 Million | 2035: $1,753.1 Million
Fleet Manage
Standalone FMS 2025: $358.2 Million | 2035: $1,051.8 Million
Standalone F
Embedded FMS 2025: $238.8 Million | 2035: $701.2 Million
Embedded FMS
Fleet Management Services 2025: $398.0 Million | 2035: $1,434.3 Million
Fleet Manage
Implementation and Integration 2025: $119.4 Million | 2035: $430.3 Million
Implementati
Managed Fleet Operations 2025: $178.8 Million | 2035: $645.1 Million
Managed Flee
Support and Maintenance 2025: $99.8 Million | 2035: $358.9 Million
Support and
Fleet Management Software $597.0 Million $1,753.1 Million 11.37%
Standalone FMS $358.2 Million $1,051.8 Million 11.37%
Embedded FMS $238.8 Million $701.2 Million 11.37%
Fleet Management Services $398.0 Million $1,434.3 Million 13.68%
Implementation and Integration $119.4 Million $430.3 Million 13.68%
Managed Fleet Operations $178.8 Million $645.1 Million 13.68%
Support and Maintenance $99.8 Million $358.9 Million 13.68%

Segment Sizing: By Offering

Supply Chain Analysis of the AMR Fleet Management Industry

Supply Chain Analysis of the AMR Fleet Management Industry
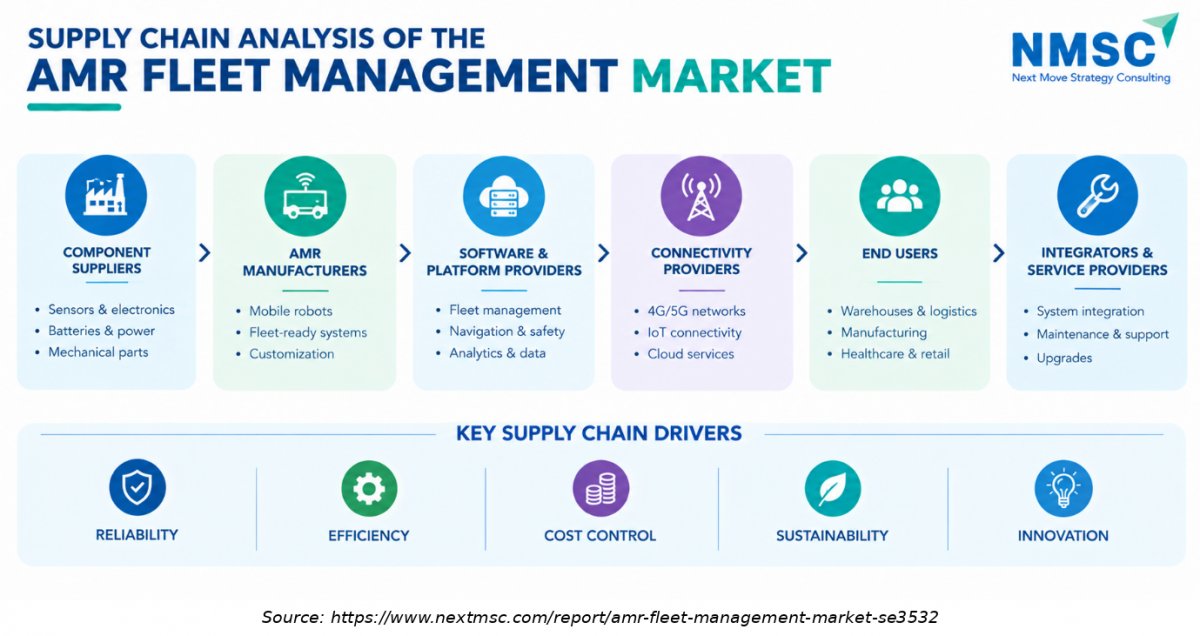
The above infographic maps the AMR Fleet Management Market supply chain across component suppliers, AMR manufacturers, software and platform providers, connectivity providers, end users, and integrators. It keeps the structure simple while showing how these stages connect and support reliability, efficiency, cost control, sustainability, and innovation across autonomous mobile robot operations.

Growth Opportunities

Our analysis shows that three structural whitespace opportunities are positioned to generate disproportionate AMR Fleet Management Market revenue for vendors who invest ahead of the buyer cohort maturation in each category.

Can Independent Multi-Vendor FMS Platforms Capture the Heterogeneous Fleet Transition?

Enterprises operating AMR fleets from two or more hardware vendors represent the fastest-growing buyer cohort in the AMR Fleet Management Market and are generating demand for independent FMS platforms that no single OEM can address without competitive conflict. The concrete mechanism is standardized VDA 5050 and MassRobotics protocol integration, enabling fleet management software to reach all deployed robots regardless of brand. This opportunity primarily benefits the Independent Multi-Vendor segment and the Automation Service Provider buyer type, both of which are positioned to capture contract value from enterprise operators unwilling to rebuild their hardware investment around a single OEM's management stack.

Does SME Adoption of Cloud FMS Represent an Untapped Volume Opportunity?

Small and medium-sized enterprises represent the market's largest untapped buyer segment, as the subscription pricing of cloud-based FMS platforms is now reaching levels accessible to operators with fleets as small as five to ten robots. The mechanism is per-robot monthly subscription pricing that converts upfront licensing cost into a variable operational expense, enabling SME operators to initiate fleet management software adoption at initial deployment scale. This opportunity benefits the Vendor Hosted Cloud software delivery segment and the SME customer size segment, both of which are growing above overall market CAGR. The supply chain management software integration that SME operators require alongside FMS is accelerating bundle adoption through integrator-led channel partnerships.

Can Healthcare Fleet Management Become a Distinct Premium Vertical Market?

Healthcare and Life Sciences is the fastest-growing major end-user industry at 15.31% CAGR, driven by hospital systems, pharmaceutical manufacturers, and healthcare distribution operators deploying AMRs under strict regulatory and safety requirements that general-purpose warehouse FMS platforms cannot fully address without vertical-specific certification and workflow customization. The opportunity mechanism is purpose-built healthcare fleet management software with native EMR connectivity, sterile zone access control, and HIPAA-compliant telemetry logging. Vendors who build validated healthcare FMS solutions benefit from longer contract cycles, higher switching costs, and regulatory credentialing that creates durable account retention relative to general warehouse FMS deployments.

Regional Outlook

2025 (USD Million)
2035 (USD Million)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Million) 2035 (USD Million) CAGR (%)
North America $10.0 USD Million $40.0 USD Million 9.0%
Europe $17.1 USD Million $51.1 USD Million 27.0%
Asia-Pacific $24.2 USD Million $62.2 USD Million 25.0%
Middle East & Africa $31.3 USD Million $73.3 USD Million 23.0%
Latin America $38.4 USD Million $84.4 USD Million 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

Our assessment indicates that the AMR Fleet Management Market industry encompasses three distinct competitive archetypes: AMR OEM-native FMS, independent multi-vendor platforms, and automation system integrators offering FMS as a managed service, with competitive intensity increasing as installed base growth draws new entrants into the software and services layer above the robot hardware.

Dimension Description
Market Structure Moderately fragmented; AMR OEM-native FMS platforms hold the largest installed base, but independent multi-vendor platforms are the fastest-growing competitive category; consolidation pressure is beginning as leading software vendors seek scale
Innovation Focus AI-based multi-robot traffic management, independent multi-vendor protocol integration, digital twin simulation, cloud-native SaaS delivery, and predictive maintenance intelligence embedded within FMS platforms
M&A Activity Strategic acquisitions of fleet management software specialists by automation system integrators and AMR OEMs seeking to internalize recurring software revenue; partnership investments between independent FMS vendors and AMR hardware manufacturers

How Do Companies Compete in the AMR Fleet Management Market?

Companies compete primarily on fleet compatibility breadth, the range of AMR brands the software can natively manage, AI-based coordination intelligence, and total cost of integration with enterprise systems. We found that the vendors who have invested earliest in VDA 5050 and MassRobotics interoperability protocol integration are capturing independent multi-vendor FMS contracts ahead of OEM-native competitors. Collaborative robot fleet management is an emerging adjacency where FMS platform vendors are extending their coordination logic to cover mobile manipulator platforms beyond standard goods-to-person AMR archetypes.

Which Competitive Archetypes Dominate the AMR Fleet Management Market?

AMR OEM-native fleet management platforms, led by Beijing Geekplus, Locus Robotics, MiR's MiR Fleet, HAI ROBOTICS, and GreyOrange, dominate the current installed base by capturing FMS revenue alongside initial hardware sales. Independent multi-vendor platforms, led by InOrbit, Vecna Robotics' VAN platform, and BlueBotics' ANT server, are differentiating on interoperability depth and open API architecture. Automation system integrators, including KNAPP AG, Dematic, and Rockwell Automation, compete by embedding FMS capability within broader warehouse execution and automation control system offerings.

What Innovation and Differentiation Strategies Are Companies Pursuing?

We observed that leading AMR fleet management software vendors are investing in AI-based dynamic task allocation that continuously re-optimizes robot assignments in response to real-time order volumes and robot availability. InOrbit's cloud robotics platform and GreyOrange's Ranger intelligence layer both reflect investment in AI-native fleet optimization architectures that can demonstrate measurable throughput improvements over static task scheduling approaches. Siemens and ABB are embedding AMR fleet management capability within their industrial automation ecosystems, positioning FMS as a module within broader smart factory control environments rather than a standalone application.

What M&A and Partnership Activity Is Shaping the Market?

Our findings suggest that the competitive landscape is evolving through strategic partnerships between independent FMS vendors and AMR hardware manufacturers who want to expand beyond proprietary fleet management without building competing software capabilities. Rockwell Automation's investment in AMR ecosystem integration through its Plex and Logix platforms and OMRON's partnership-led FMS strategy reflect how automation system vendors are embedding fleet management software into established enterprise automation relationships rather than competing as standalone FMS products. Direct acquisitions of smaller FMS software startups by integration-focused industrial automation vendors are beginning to accelerate as recurring software revenue valuation multiples attract acquirers.

Key Market Players

Based on research conducted by NMSC, the following 20 companies represent the validated leadership set across AMR fleet management software development, platform delivery, and associated professional and managed services within this market.

Beijing Geekplus Technology Co., Ltd. Locus Robotics Corporation Mobile Industrial Robots A/S OMRON Corporation KUKA SE & Co. KGaA HAI ROBOTICS Co., Ltd. GreyOrange Pte. Ltd. Seegrid Corporation Rockwell Automation, Inc. ForwardX Robotics Co., Ltd. KNAPP AG Vecna Robotics, Inc. ABB Ltd. Siemens Aktiengesellschaft Dematic Corp. BlueBotics SA Kollmorgen Corporation Addverb Technologies Limited Mujin, Inc. InOrbit, Inc.

Latest Developments

During our market evaluation, we noticed that 2026 AMR fleet management software activity reflects accelerating AI feature integration, cloud platform scale-up, and the emergence of multi-vendor interoperability as a primary competitive marketing claim across leading vendors.

Date Event
August 2026 Geekplus launched RoboShuttle Hyper, a next-generation tote-to-person AMR designed for high-throughput fulfillment. The system delivers up to 6,000 totes per hour per 1,000 square meters. Its scalable architecture is designed to coordinate large robot deployments, directly increasing requirements for sophisticated fleet scheduling and orchestration.
July 2026 ABB launched the Flexley Stack F712 autonomous forklift, extending its Visual SLAM technology into pallet transport and high-bay storage.
June 2026 OMRON announced the LD-150 and LD-300 AMRs, offering payloads of up to 150 kg and 300 kg respectively. The robots integrate with OMRON FLOW Core to simplify deployment and mixed-fleet management.
March 2026 MiR announced the VDA 5050 Adapter, allowing its AMRs to connect with compatible third-party fleet-management platforms. The solution enables MiR robots to operate alongside other manufacturers' AMRs and automated vehicles through a common interoperability framework.

Expert Insights

Justin King

Justin King

Vice President of Product Management, Business Development and Marketing | OMRON Robotics

"“The LD-150 and LD-300 give customers a more flexible AMR platform for heavier transport tasks in tighter spaces, with fast wireless charging and OMRON FLOW Core integration to simplify deployment and mixed-fleet management.”"

Analyst Interpretation

The statement highlights the growing importance of fleet management, interoperability, scalability, and flexible deployment in the AMR Fleet Management Market. As manufacturers expand AMR deployments across different payload classes and workflows, centralized fleet-management platforms are becoming increasingly important for coordinating robot traffic, assigning tasks, managing charging, and integrating multiple AMR models. OMRON’s FLOW Core specifically provides centralized fleet control, dynamic task assignment, traffic management, charging optimization, and real-time operational insights, supporting the shift from individual AMR deployments toward coordinated mixed-fleet operations.

Investment Opportunities

Where Are Capital Inflows Concentrating in the AMR Fleet Management Market?

Capital inflows are concentrating in cloud-native fleet management software platforms with AI-based optimization capability, as evidenced by venture investment activity in InOrbit and Vecna Robotics and the platform expansion investment disclosures of Beijing Geekplus and GreyOrange through 2025. The Subscription Revenue and Consumption Revenue model sub-segments are attracting disproportionate investor attention because their recurring revenue characteristics and net revenue retention metrics closely resemble SaaS business models, enabling fleet management software vendors to access growth-equity valuation multiples above those traditionally applied to industrial automation software.

How Is Infrastructure Investment Shaping Market Capacity?

Infrastructure investment is shifting toward cloud data center capacity for fleet telemetry ingestion and AI model training, as fleet management software vendors with large installed bases generate terabytes of robot operational data that they are using to train performance optimization models. Rockwell Automation and Siemens are investing in industrial IoT platform infrastructure that absorbs AMR fleet management as a workload within broader smart factory connectivity platforms. Manufacturing execution system integration is a key infrastructure investment area, as FMS platforms that can exchange real-time production schedule data with MES systems deliver higher demonstrated ROI for manufacturing end-user customers.

What ESG Considerations Are Influencing Market Investment?

Environmental, Social, and Governance considerations in the AMR Fleet Management Market focus on energy consumption optimization of AMR fleets; fleet management software that intelligently schedules robot charging and optimizes route efficiency reduces total facility energy consumption attributable to robot operations. We found that enterprise operators are beginning to include AMR fleet energy efficiency metrics in their warehouse operational sustainability reporting, creating a structured ESG-driven demand signal for fleet management software vendors who can provide robot energy consumption analytics alongside throughput performance dashboards.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders and Warehouse Operators?

Warehouse operators, manufacturing automation managers, and logistics technology buyers gain segment-level revenue forecasts and CAGR benchmarks across all 11 segmentation axes, enabling technology investment decisions grounded in the consistent 2025–2035 figures used throughout this analysis. The end-user industry breakdown and fleet compatibility segmentation provide specific evidence for make-versus-buy and OEM-versus-independent FMS platform decisions that enterprise operators face when scaling beyond initial pilot deployments in the AMR Fleet Management Market.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts gain a reconciled market-sizing model at USD 994.97 Million in 2025, growing to USD 3,187.39 Million by 2035, competitive landscape assessment, and named-company development tracking that supports robotics software sector valuation and capital-allocation decisions. The Revenue Model segmentation, showing Subscription Revenue as dominant and Consumption Revenue as fastest-growing, provides specific evidence for recurring revenue quality assessments that differentiate FMS software investment targets from one-time professional services revenue profiles.

How Does This Report Benefit Technology Vendors and FMS Platform Teams?

Fleet management software vendors and product teams gain visibility into which segments, notably Independent Multi-Vendor at 17.77% CAGR, Healthcare and Life Sciences at 15.31%, and Small Fleet at 14.43%, are growing fastest, informing roadmap and go-to-market prioritization through 2035. The competitive landscape analysis identifies the protocol integration depth, AI optimization capability, and managed services packaging that enterprise buyers are treating as baseline requirements, providing product strategy evidence for vendors evaluating feature investment priorities within the market.

Key Market Segments Evaluated

By Offering

  • Fleet Management Software 
    • Standalone FMS
    • Embedded FMS
  • Fleet Management Services 
    • Implementation and Integration
    • Managed Fleet Operations
    • Support and Maintenance

By Fleet Compatibility

  • Single-Vendor
  • OEM Multi-Vendor
  • Independent Multi-Vendor

By Software Delivery

  • Customer Hosted
  • Vendor Hosted Cloud
  • Hybrid

By Operating Environment

  • Indoor
  • Outdoor
  • Hybrid

By Primary Workflow

  • Transportation 
    • Point-to-Point Transport
    • Line-Side Delivery
    • Replenishment
    • Staging
  • Pick and Place
  • Putaway and Retrieval
  • Sortation
  • Inspection
  • Other Material Handling

By End User Industry

  • Warehousing and Logistics
  • Manufacturing 
    • Automotive
    • Electronics
    • Aerospace
    • Other Manufacturing
  • Retail and Ecommerce
  • Healthcare and Life Sciences
  • Agriculture
  • Food and Beverage
  • Other Industries

By Buyer Type

  • End User Operator
  • System Integrator
  • AMR OEM
  • Automation Service Provider

By Sales Channel

  • Direct
  • Integrator Led
  • OEM Led
  • Distributor or Reseller Led

By Revenue Model

  • License Revenue
  • Subscription Revenue
  • Consumption Revenue
  • Service Revenue

By Customer Size

  • SME
  • Large Enterprise

By Fleet Scale

  • Small Fleet
  • Medium Fleet
  • Large Fleet
  • Multi-Site Fleet

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook for the AMR Fleet Management Market is strongly positive, with revenue expanding from USD 1,196.05 Million in 2026 to USD 3,187.39 Million by 2035 at an 11.5% CAGR. Growth is underpinned by durable AMR hardware deployment expansion, the structural shift toward multi-vendor fleet architectures, and the maturation of AI-based fleet optimization from a premium feature to a baseline requirement. We observed that this trajectory reflects fundamental warehouse and factory operating model changes, not a cyclical technology adoption wave, supporting sustained software and services investment commitment across all major geographies.

What Strategic Positioning Recommendations Does NMSC Offer?

Fleet management software vendors should prioritize open protocol integration, VDA 5050 and MassRobotics, and AI-based multi-robot coordination capability to capture the Independent Multi-Vendor segment growing at 17.77% CAGR. OEM-native FMS providers should expand beyond proprietary robot integration to avoid losing enterprise accounts to independent platform competitors as operator fleets become heterogeneous. Managed Fleet Operations service packaging should be developed as a standard offering to capture the Services segment growing at 13.68% CAGR among enterprise operators who prefer to outsource day-to-day fleet administration.

How Attractive Is the AMR Fleet Management Market for Investment?
Investment attractiveness is high, supported by the USD 1,991.34 Million absolute growth opportunity between 2026 and 2035 and the SaaS-like revenue model characteristics of cloud-hosted subscription FMS platforms that enable recurring revenue quality at robotics sector growth rates. Asia-Pacific at 13.04% CAGR and Latin America at 20.39% represent the highest relative growth, while North America offers the largest absolute revenue base with the most mature enterprise buyer population and documented FMS ROI benchmarks that accelerate subsequent procurement decisions.

What Are the Key Market Shifts and Risks in the AMR Fleet Management Market?

Key market shifts include the transition from OEM-bundled to independently procured fleet management software, the migration from on-premises to cloud-hosted FMS delivery, and the expansion of addressable fleet management scope to include outdoor and hybrid operating environments beyond traditional warehouse floors. Primary risks include integration complexity with legacy warehouse and ERP systems that extends deployment timelines, cybersecurity exposure from cloud-connected robot fleet telemetry that is driving enterprise hesitancy in regulated industries, and talent shortages in robotics system integration that are moderating deployment pace in Latin America and MEA.

What Are the Primary Growth Pathways Through 2035?

Primary growth pathways include independent multi-vendor FMS platform expansion capturing heterogeneous fleet operators, healthcare fleet management vertical specialization accessing premium-priced regulated market demand, and SME cloud subscription adoption expanding the total buyer population beyond large enterprise initial adopters. Our analysis shows that vendors combining open protocol multi-vendor integration, AI-based fleet optimization, and vertical-specific compliance features are best positioned to capture a disproportionate share of the USD 1,991.34 Million absolute growth opportunity between 2026 and 2035, particularly in Asia-Pacific and Latin America, where first-time AMR fleet management software adoption is accelerating from a low base.

FAQs

2. What is the AMR Fleet Management Market revenue forecast for 2035?

The AMR Fleet Management Market is forecast to reach USD 3,187.39 Million by 2035.

3. What is the CAGR of the AMR Fleet Management Market from 2026 to 2035?

The AMR Fleet Management Market is projected to grow at a CAGR of 11.5% from 2026 to 2035.

4. Which offering segment leads the AMR Fleet Management Market?

Fleet Management Software leads with approximately a 60% share in 2025 at USD 596.98 Million, reflecting higher per-seat licensing and subscription value relative to one-time service engagements.

5. Which fleet compatibility segment is growing fastest in the AMR Fleet Management Market?

Independent Multi-Vendor fleet management software is the fastest-growing segment at 17.77% CAGR from 2026 to 2035, as enterprises managing robots from multiple brands demand vendor-agnostic coordination platforms.

6. Which region dominates the AMR Fleet Management Market?

North America dominates with approximately 40% revenue share in 2025 at USD 397.99 Million, anchored by the world's highest AMR installed-base density across e-commerce fulfilment and manufacturing environments.

7. Which region is growing fastest in the AMR Fleet Management Market?

Latin America is the fastest-growing region at 20.39% CAGR from 2026 to 2035, driven by first-time AMR deployments in Brazil and Mexico and cloud FMS adoption across organized retail and logistics sectors.

8. Which country leads the AMR Fleet Management Market?

The U.S. leads with an estimated USD 338.29 Million in 2025, supported by the largest global concentration of e-commerce fulfilment and manufacturing AMR deployments requiring professional fleet management software.

9. Who are the key players in the AMR Fleet Management Market?

Key players include Beijing Geekplus Technology Co., Ltd., Locus Robotics Corporation, Mobile Industrial Robots A/S, OMRON Corporation, HAI ROBOTICS Co., Ltd., GreyOrange Pte. Ltd., and InOrbit, Inc., among 20 companies profiled in this market report.

10. What are the primary growth drivers for the AMR Fleet Management Market?

Rising AMR deployment density creating multi-robot coordination software demand and e-commerce fulfilment investment are the primary growth drivers, contributing an estimated combined +5.6% impact on CAGR within the AMR Fleet Management Market.

11. What is restraining AMR Fleet Management Market growth?

Integration complexity with legacy WMS and ERP systems and cybersecurity concerns around cloud-connected robot fleets are the primary restraints, with an estimated combined impact of approximately −2.0% on CAGR.

12. What are the biggest opportunities in the AMR Fleet Management Market?

Independent multi-vendor FMS platform expansion, SME cloud subscription adoption, and healthcare fleet management vertical specialization are the three primary addressable opportunities within the USD 1,991.34 Million absolute growth window between 2026 and 2035.

13. How is AI changing the AMR Fleet Management Market?

AI is enabling real-time dynamic task allocation, predictive maintenance scheduling, and autonomous deadlock prevention within fleet management platforms, shifting FMS from passive monitoring tools to active operational optimization systems that measurably improve robot fleet throughput and uptime.

14. What standards and regulations shape the AMR Fleet Management Market?

ANSI/ITSDF B56.5 in North America and ISO 3691-4 in Europe mandate safe human-robot interaction protocols that fleet management software must implement. VDA 5050 and MassRobotics interoperability standards are shaping multi-vendor FMS integration requirements globally.

15. What is the U.S. AMR Fleet Management Market size?

The U.S. AMR Fleet Management Market was valued at approximately USD 338.29 Million in 2025 and is projected to reach USD 797.12 Million by 2035 at a CAGR near 9.0%.

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Mohit Agarwal

MOHIT AGARWAL

Chief Manager

DryChem India Pvt. Ltd.

Next Move Strategy Consulting is an amazing team of consultants. We required a market study report for our investors on top priority and the team went above and beyond our expectations to deliver the same with ample supporting data within a short time span enabling us to secure the investments and keep our project timeline maintained. Their professionalism, attention to detail, and timely delivery of actionable recommendations have left a lasting impression on our organization.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖