Edge Computing Market

Edge computing market was USD 38.8 billion in 2025, projected to reach USD 655.4 billion by 2035 at a 32.3% CAGR from 2026 to 2035, per this market report.

Download Free Sample PDF
Base Year (2025)
$38.80 Billion
Forecast (2035)
$655.40 Billion
CAGR (2026-2035)
32.3%
Top Region
North America

What Is the Edge Computing Market Size?
The global edge computing market size was valued at USD 38.8 billion in 2025 and is estimated at USD 52.9 billion in 2026, forecast to reach USD 655.4 billion by 2035, at a 32.3% CAGR from 2026 to 2035. North America leads with approximately 34% share, while hardware dominates all other components with approximately 47% share.

We observed that growth is accelerating fastest in network edge infrastructure and healthcare applications, reflecting the market's shift toward AI inference workloads that require low-latency processing closer to end devices.

By Component: Hardware held the largest share of approximately 47% (USD 18.23 Billion) in 2025; Software is the fastest-growing sub-segment at 36.3% CAGR from 2026-2035. By Edge Type: On-Premise Edge held the largest share of approximately 38% (USD 14.74 Billion) in 2025; Network Edge is the fastest-growing sub-segment at 37.0% CAGR from 2026-2035. By End-User Industry: Manufacturing held the largest share of approximately 23% (USD 8.92 Billion) in 2025; Healthcare and Life Sciences is the fastest-growing sub-segment at 38.4% CAGR from 2026-2035. Dominant Region: North America dominated with approximately 34% revenue share (USD 13.19 Billion) in 2025. Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 36.2% during 2026-2035. Dominant Country: U.S. led with approximately USD 10.55 Billion in 2025. Fastest-Growing Country: India is the fastest-growing country at approximately 44.4% CAGR from 2026-2035.

Market Opportunity: The edge computing market is expected to create an absolute dollar opportunity of USD 602.5 billion between 2026 and 2035, presenting significant investment potential across distributed AI infrastructure, edge software platforms, and industrial IoT deployment.

According to Next Move Strategy Consulting analysis, enterprises are increasingly consolidating edge deployments around unified hardware-software stacks capable of running AI inference workloads locally, a shift that favors vendors combining GPU-accelerated edge hardware with orchestration software over point-solution providers as real-time AI applications scale through 2035.

Edge Computing Market Revenue Forecast

Values in USD Billion

2025 $38.80 Billion
2025
2026 $52.90 Billion
2026
2027 $69.99 Billion
2027
2028 $92.59 Billion
2028
2029 $122.50 Billion
2029
2030 $162.07 Billion
2030
2031 $214.41 Billion
2031
2032 $283.67 Billion
2032
2033 $375.30 Billion
2033
2034 $496.52 Billion
2034
2035 $655.40 Billion
2035

What Does the Edge Computing Market Encompass?

The edge computing market encompasses hardware, software, and services that process data closer to its point of generation, at devices, on-premise facilities, or network infrastructure, rather than routing all workloads to centralized cloud data centers. Our assessment indicates that the scope spans edge servers, gateways, orchestration software, and managed services supplied to manufacturing, telecommunications, retail, and healthcare operators seeking reduced latency and bandwidth costs. The category has evolved from basic content delivery caching into AI-inference-capable distributed infrastructure, driven by real-time computer vision, autonomous systems, and generative AI applications requiring sub-second response times.
Regulatory frameworks such as data sovereignty and localization requirements across the European Union and Asia-Pacific shape enterprise adoption of on-premise and network edge deployments, while industry standards bodies continue to define interoperability specifications for multi-access edge computing. We observed that technology adoption is shifting toward GPU-accelerated edge platforms capable of running generative and agentic artificial intelligence workloads locally. Next Move Strategy Consulting's analysis indicates that this structural shift is redefining sourcing criteria across the edge computing market as enterprises prioritize unified hardware-software platforms.

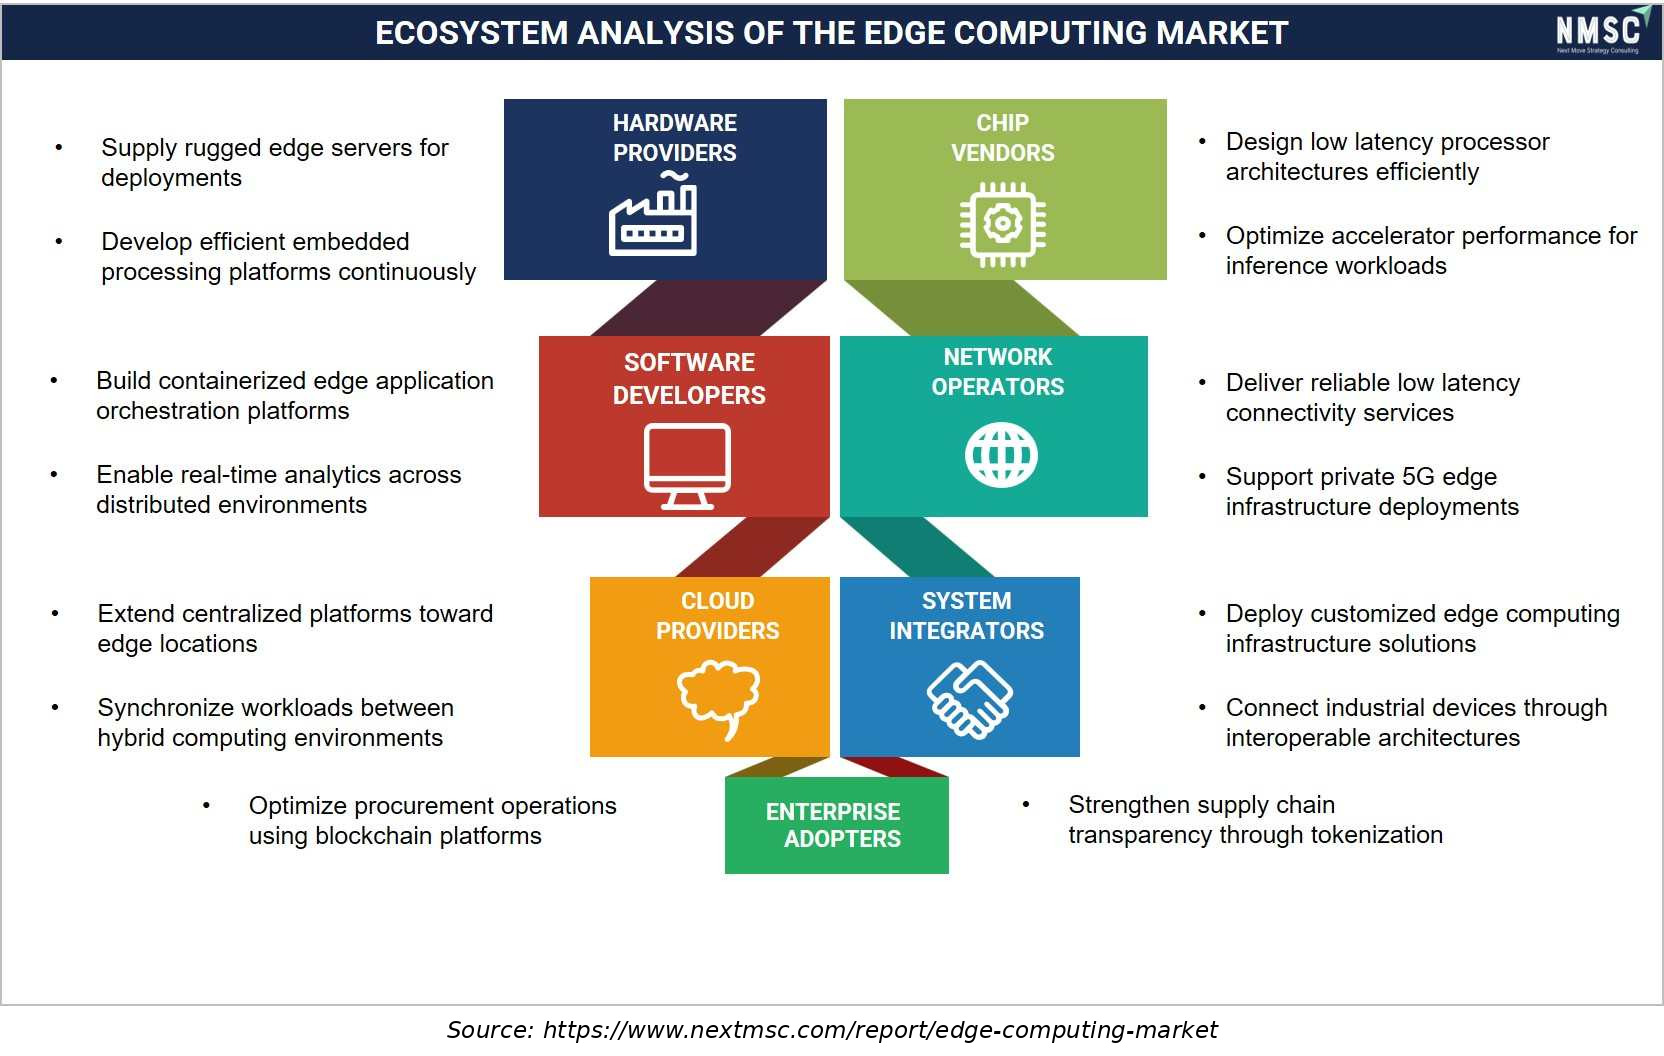
Ecosystem Analysis of the Edge Computing Market

The edge computing ecosystem consists of interconnected stakeholders that enable real-time data processing closer to the data source. Hardware providers and chip vendors supply the underlying infrastructure, while software developers create edge-enabled applications. Network operators ensure low-latency connectivity, and system integrators deploy and manage integrated solutions. Cloud providers extend hybrid computing capabilities, enabling seamless data orchestration. Together, these participants empower enterprise adopters across industries to enhance operational efficiency, reduce latency, strengthen data security, and support AI- and IoT-driven digital transformation.

Market Drivers & Dynamics

Interactive Dataset
Real-time AI inference and physical AI deployment driver +7.5% North America, Asia-Pacific 2026-2035
Industrial IoT and factory automation expansion driver +6.2% Asia-Pacific, North America 2026-2035
5G and network densification enabling network edge driver +5.1% Global 2026-2035
Data sovereignty and localization regulatory requirements driver +4.0% Europe, Asia-Pacific 2026-2035
Hyperscaler capital expenditure in distributed AI infrastructure driver +4.8% North America 2026-2032
Autonomous vehicle and robotics sensor processing demand driver +2.9% North America, Asia-Pacific 2026-2035
High deployment and integration complexity restraint -2.6% Global 2026-2032
Security and management challenges across distributed nodes restraint -1.8% Global 2026-2033
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Edge Computing Market?

Real-time AI inference and physical AI deployment are the primary driver of the market. We observed that AWS announced plans to deploy more than one million NVIDIA GPUs across its regions starting in 2026, including Blackwell and Rubin architectures, alongside new inference networking technology to accelerate disaggregated large language model workloads. This infrastructure buildout continues to anchor baseline procurement of edge servers and AI-capable gateways across enterprise and telecommunications customers.

How Is Industrial Physical AI Driving Market Growth?

Physical AI adoption in manufacturing and industrial settings is accelerating market growth as operators deploy compute directly on factory floors. Our assessment indicates that NVIDIA's IGX Thor platform, generally available since March 2026, delivers real-time sensor processing with enterprise-grade reliability and functional safety certification for industrial deployment. This product validation is compressing adoption timelines for edge AI hardware among manufacturers pursuing computer-vision-based quality control and predictive maintenance.

Growth Inhibitors

What Is Restraining Edge Computing Market Expansion?

High deployment and integration complexity restrains the pace of edge computing adoption across the industry, as enterprises must coordinate hardware, software, and connectivity across geographically distributed nodes with limited on-site technical staff. Security and management challenges further complicate adoption, since distributed edge nodes expand the attack surface relative to centralized cloud data centers. We found that smaller enterprises face particular exposure to these constraints, as limited IT resources reduce their ability to manage distributed infrastructure compared with large, well-resourced organizations.

What Are the Growth Opportunities?

How Can Bedside AI Diagnostics Unlock Value for Healthcare Edge Vendors?

Bedside and point-of-care AI diagnostic deployment presents a whitespace opportunity for vendors offering healthcare-certified, low-latency edge hardware and software. Suppliers that validate regulatory-compliant edge platforms for medical imaging inference stand to capture recurring hospital procurement revenue as providers seek sub-second diagnostic response times unattainable through centralized cloud architectures.

Where Does Autonomous Industrial Robotics Create New Demand?

Autonomous robotics and computer-vision-based quality control in manufacturing represent an underpenetrated opportunity for vendors integrating GPU-accelerated edge hardware with industrial software. Suppliers that secure qualified-vendor status with manufacturers deploying robotics and automation systems can access long-term contracts, benefiting from recurring software and lifecycle support revenue tied to Industry 4.0 modernization programs.

How Can Network Edge Orchestration Benefit Telecommunications Operators?

Network edge orchestration software creates an opportunity for vendors serving telecommunications operators deploying multi-access edge computing to support 5G-enabled applications. Early movers that validate carrier-grade orchestration platforms can differentiate with operators pursuing new enterprise revenue streams, capturing recurring software revenue tied to the segment's above-market growth through 2035.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Hardware 2025: $18.23 Billion | 2035: $222.84 Billion
Hardware
Software 2025: $12.42 Billion | 2035: $275.26 Billion
Software
Services 2025: $8.15 Billion | 2035: $157.30 Billion
Services
Hardware $18.23 Billion $222.84 Billion 27.6%
Software $12.42 Billion $275.26 Billion 36.3%
Services $8.15 Billion $157.30 Billion 34.2%

Which Component Dominates the Edge Computing Market?

Hardware led the market with USD 18.23 billion in 2025, supported by continued enterprise procurement of edge servers, gateways, and GPU-accelerated appliances for on-site deployment. We observed that Software is the fastest-growing component, expanding at a 36.3% CAGR from 2026 to 2035, as enterprises prioritize orchestration, AI inference, and management platforms capable of unifying increasingly distributed hardware fleets across cloud-to-edge architectures.

2025 (USD Billion)
2035 (USD Billion)
Device Edge
On-Premise E
Network Edge
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Device Edge $10.0 USD Billion $40.0 USD Billion 25.0%
On-Premise Edge $17.1 USD Billion $51.1 USD Billion 15.0%
Network Edge $24.2 USD Billion $62.2 USD Billion 13.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Edge Type.

Unlock Full Data

Which Edge Type Leads Edge Computing Deployment?

On-Premise Edge led the market, valued at USD 14.74 billion in 2025, reflecting established enterprise demand for local data processing in manufacturing plants and retail facilities. Our findings suggest that Network Edge is the fastest-growing edge type, registering a 37.0% CAGR from 2026 to 2035, as telecommunications operators and hyperscalers expand multi-access edge computing infrastructure to support low-latency AI inference and 5G-enabled applications.

2025 (USD Billion)
2035 (USD Billion)
Smart Manufa
Autonomous V
Smart Cities
Content Deli
Remote Healt
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Smart Manufacturing $10.0 USD Billion $40.0 USD Billion 18.0%
Autonomous Vehicles and Transportation $17.1 USD Billion $51.1 USD Billion 16.0%
Smart Cities and Infrastructure $24.2 USD Billion $62.2 USD Billion 22.0%
Content Delivery and Media $31.3 USD Billion $73.3 USD Billion 12.0%
Remote Healthcare Monitoring $38.4 USD Billion $84.4 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Large Enterp
Small and Me
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Large Enterprises $10.0 USD Billion $40.0 USD Billion 10.0%
Small and Medium Enterprises $17.1 USD Billion $51.1 USD Billion 24.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Organization Size.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Manufacturin
IT and Telec
Retail and E
Healthcare a
BFSI
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Manufacturing $10.0 USD Billion $40.0 USD Billion 20.0%
IT and Telecommunications $17.1 USD Billion $51.1 USD Billion 26.0%
Retail and E-commerce $24.2 USD Billion $62.2 USD Billion 24.0%
Healthcare and Life Sciences $31.3 USD Billion $73.3 USD Billion 26.0%
BFSI $38.4 USD Billion $84.4 USD Billion 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End-User Industry.

Unlock Full Data

Which End-User Industry Leads Edge Computing Demand?

Manufacturing remained the leading end-user industry, valued at USD 8.92 billion in 2025 on sustained factory automation and industrial IoT deployment. Our analysis shows that Healthcare and Life Sciences is the fastest-growing end-user segment, registering a 38.4% CAGR from 2026 to 2035, as hospitals deploy bedside AI imaging and diagnostic systems requiring sub-second inference latency unattainable through centralized cloud processing.

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the edge computing market over the 2026-2035 forecast period.

How Can Bedside AI Diagnostics Unlock Value for Healthcare Edge Vendors?

Bedside and point-of-care AI diagnostic deployment presents a whitespace opportunity for vendors offering healthcare-certified, low-latency edge hardware and software. Suppliers that validate regulatory-compliant edge platforms for medical imaging inference stand to capture recurring hospital procurement revenue as providers seek sub-second diagnostic response times unattainable through centralized cloud architectures.

Where Does Autonomous Industrial Robotics Create New Demand?

Autonomous robotics and computer-vision-based quality control in manufacturing represent an underpenetrated opportunity for vendors integrating GPU-accelerated edge hardware with industrial software. Suppliers that secure qualified-vendor status with manufacturers deploying robotics and automation systems can access long-term contracts, benefiting from recurring software and lifecycle support revenue tied to Industry 4.0 modernization programs.

How Can Network Edge Orchestration Benefit Telecommunications Operators?

Network edge orchestration software creates an opportunity for vendors serving telecommunications operators deploying multi-access edge computing to support 5G-enabled applications. Early movers that validate carrier-grade orchestration platforms can differentiate with operators pursuing new enterprise revenue streams, capturing recurring software revenue tied to the segment's above-market growth through 2035.

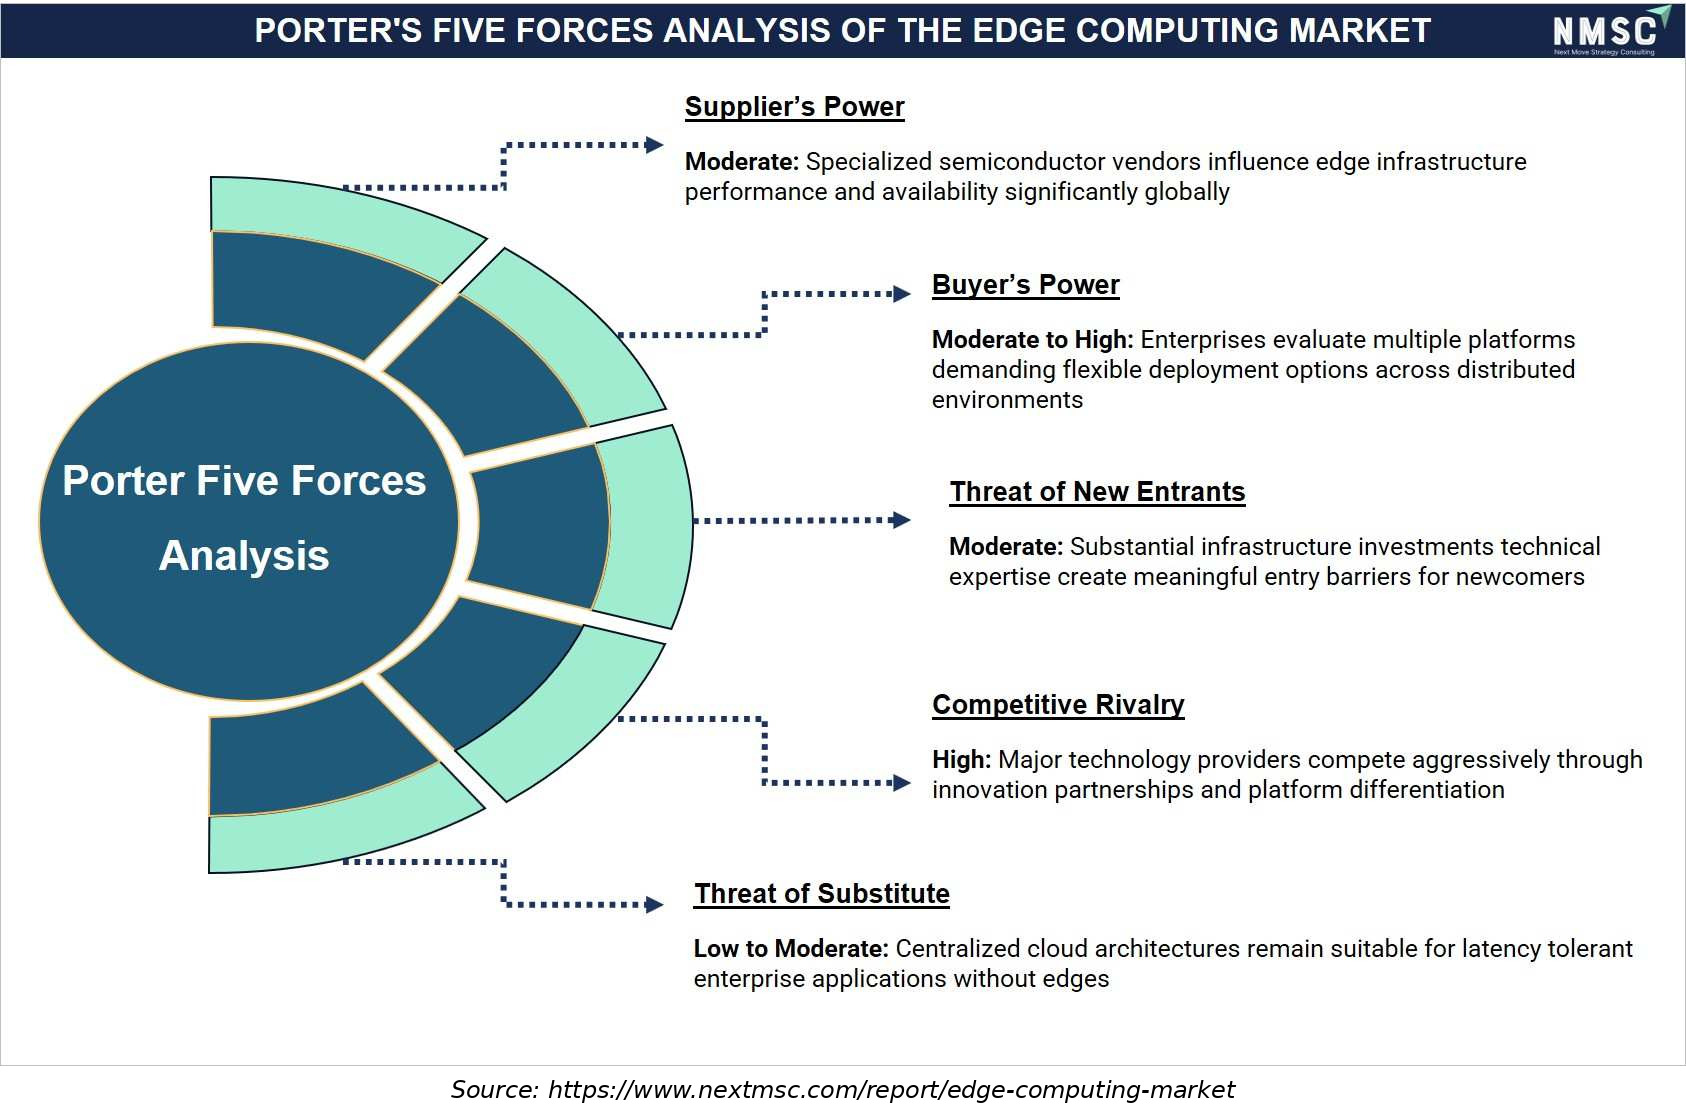
Porter's Five Forces Analysis of the Edge Computing Market

Porter’s Five Forces analysis indicates that the edge computing market is shaped by intense competition, rapid technological innovation, and evolving enterprise demand. The bargaining power of buyers is moderate to high due to the availability of multiple solution providers, while suppliers hold moderate influence because of reliance on specialized hardware and semiconductor technologies. The threat of new entrants remains moderate owing to high infrastructure and R&D requirements, substitutes are limited for latency-sensitive applications, and competitive rivalry is high as leading technology, cloud, and telecom companies continue expanding their edge computing portfolios.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the edge computing market features a moderately consolidated competitive landscape, with diversified global technology groups competing alongside specialized networking and infrastructure vendors on platform breadth, AI capability, and deployment scale.

Dimension Description
Market Structure Moderately consolidated; the leading companies profiled in this report collectively account for a significant share of global revenue, while specialized regional systems integrators serve niche deployment demand.
Innovation Focus GPU-accelerated edge hardware, unified cloud-to-edge orchestration software, and industrial physical AI platforms dominate current innovation pipelines across leading suppliers.
M&A Activity Selective consolidation and strategic partnership activity, exemplified by NVIDIA's multiyear strategic partnership with Meta spanning on-premises, cloud, and AI infrastructure deployment announced in 2026.

How Do Companies Compete in the Edge Computing Market?

Companies compete primarily on AI processing capability, platform breadth, and deployment scale across the industry. Hyperscalers such as Amazon.com, Inc. and Microsoft Corporation leverage broad cloud-to-edge portfolios spanning centralized data centers to on-premise appliances to serve multinational enterprises, while networking and infrastructure specialists such as Cisco Systems, Inc. compete on validated edge-to-core reference architectures and carrier-grade reliability.

Which Competitive Archetypes Dominate the Edge Computing Market?

Two archetypes dominate the market: diversified cloud hyperscalers offering unified centralized-to-distributed compute platforms, and specialized hardware and networking vendors focused on edge-specific infrastructure. Amazon.com, Inc. and Microsoft Corporation exemplify the hyperscaler archetype through AWS Outposts and Azure Stack offerings, while NVIDIA Corporation and Cisco Systems, Inc. exemplify the specialized archetype, concentrating on GPU-accelerated edge hardware and edge-to-core networking respectively.

How Are Companies Differentiating Through Innovation in Edge Computing?

Innovation and differentiation strategy increasingly center on unified hardware-software platforms capable of running AI inference workloads consistently from data center to edge. NVIDIA Corporation's IGX Thor platform, generally available since March 2026, illustrates how suppliers are engineering industrial-grade reliability and functional safety directly into edge AI hardware. Our analysis shows that suppliers unable to demonstrate credible AI inference capability risk exclusion from enterprise edge deployment shortlists.

What M&A and Investment Activity Is Shaping the Edge Computing Market?

Strategic partnerships and capital investment continue to reshape capability within the industry. NVIDIA Corporation's multiyear, multigenerational partnership with Meta spanning on-premises, cloud, and AI infrastructure, alongside AWS's commitment to deploy more than one million GPUs across its regions starting in 2026, illustrate how infrastructure vendors are securing long-term capacity commitments ahead of broader edge AI deployment cycles.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping product innovation, infrastructure investment, and geographic expansion within the global edge computing market.

Amazon.com, Inc. Microsoft Corporation Alphabet Inc. International Business Machines Corporation Cisco Systems, Inc. Dell Technologies Inc. Hewlett Packard Enterprise Company Intel Corporation NVIDIA Corporation Huawei Technologies Co., Ltd. Schneider Electric SE Vertiv Holdings Co Equinix, Inc. Akamai Technologies, Inc. Fastly, Inc. Verizon Communications Inc. AT&T Inc. Nokia Corporation Telefonaktiebolaget LM Ericsson Lenovo Group Limited

Latest Developments

We found that recent developments within the edge computing market are concentrated on AI-inference-capable edge hardware and expanded cloud-to-edge infrastructure commitments, reflecting the industry's shift toward distributed AI deployment.

Date Event
March 2026 AWS announced plans to deploy more than one million NVIDIA GPUs across its regions starting in 2026, including Blackwell and Rubin architectures, alongside new inference networking technology.

Expert Insights

Pallavi Mahajan

corporate vice president | Intel

"“The edge is the next frontier of digital transformation, being further fueled by AI. We are building on our strong customer base in the market and consolidating our years of software initiatives to the next level in delivering a complete edge-native platform, which is needed to enable infrastructure, applications and efficient AI deployments at scale. Our modular platform is exactly that, driving optimal edge infrastructure performance and streamlining application management for enterprises, giving them both improved competitiveness and improved total cost of ownership.”"

Analyst Interpretation

The statement highlights the growing convergence of edge computing and artificial intelligence, emphasizing the need for scalable edge-native platforms that support distributed AI workloads and real-time data processing. As enterprises increasingly deploy connected devices across manufacturing, telecommunications, healthcare, retail, transportation, and smart city applications, demand for integrated edge infrastructure is rising to reduce latency, improve operational efficiency, simplify application management, and lower total cost of ownership. This reflects the broader market trend toward intelligent, decentralized computing architectures that enable faster decision-making and support large-scale digital transformation initiatives.

Investment Opportunities

What Capital Inflows Are Targeting the Edge Computing Market?

Capital inflows into the market are increasingly directed toward AI-inference-capable edge infrastructure and strategic hyperscaler-chipmaker partnerships. We observed that Amazon committed USD 200 billion in capital expenditure for 2026, with the majority directed at AWS infrastructure expansion to meet AI-driven demand spanning centralized and distributed compute tiers. Investors favor vendors demonstrating validated AI inference capability as a proxy for long-term enterprise contract retention.

How Is Infrastructure Investment Supporting Edge Computing Deployment?

Infrastructure investment is expanding GPU-accelerated edge and data center manufacturing capacity to serve rising industrial and enterprise AI demand. Our findings suggest that NVIDIA's partnership with Nebius, including a USD 2 billion investment to support deployment of more than five gigawatts of NVIDIA systems by 2030, supports the precision infrastructure buildout required for distributed AI inference across cloud-to-edge architectures.

What ESG Considerations Are Shaping Edge Computing Investment Decisions?

Environmental, social, and governance considerations are increasingly relevant to investment decisions across the industry, particularly regarding energy-efficient liquid-cooled infrastructure for high-density AI workloads. Microsoft has integrated NVIDIA's latest accelerated computing platforms into its liquid-cooled Azure data centers to manage power and cooling efficiency. We found that investors increasingly favor vendors with transparent energy efficiency disclosures, treating them as governance indicators alongside data security and sovereignty compliance.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and product-portfolio decisions across the edge computing industry. Our analysis shows that detailed component, edge type, and end-user breakdowns help procurement teams align specifications with data sovereignty and latency requirements while identifying underserved industry verticals for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the edge computing supply chain. We observed that the report's regional and segment-level growth differentials help identify which vendors are best positioned to capture above-market growth in network edge and healthcare applications through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including AI inference capability, functional safety certification, and cloud-to-edge interoperability, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around GPU-accelerated architecture and orchestration software increasingly required by enterprise procurement processes.

Key Market Segments Evaluated

By Component

  • Hardware
  • Software
  • Services

By Edge Type

  • Device Edge
  • On-Premise Edge
  • Network Edge

By Application

  • Smart Manufacturing
  • Autonomous Vehicles and Transportation
  • Smart Cities and Infrastructure
  • Content Delivery and Media
  • Remote Healthcare Monitoring
  • Retail Analytics and Personalization
  • Industrial IoT
  • Other Applications

By Organization Size

  • Large Enterprises
  • Small and Medium Enterprises

By End-User Industry

  • Manufacturing
  • IT and Telecommunications
  • Retail and E-commerce
  • Healthcare and Life Sciences
  • BFSI
  • Government and Defense
  • Energy and Utilities
  • Transportation and Logistics
  • Other Industries

Conclusion & Recommendations

The long-term outlook for the market remains exceptionally strong, with global revenue projected to expand from USD 38.8 billion in 2025 to USD 655.4 billion by 2035 at a 32.3% CAGR. We observed that sustained hyperscaler infrastructure investment, industrial physical AI deployment, and rising healthcare and manufacturing adoption will continue underpinning demand across the forecast period.

What Strategic Positioning Should Edge Computing Suppliers Pursue?

Suppliers should prioritize unified, AI-inference-capable hardware-software platforms while pursuing validated partnerships across the cloud-to-edge value chain to secure long-term enterprise contracts. Our assessment indicates that vendors investing early in GPU-accelerated edge hardware and orchestration software, alongside functional safety certification, will be best positioned to capture premium pricing within the edge computing market.

How Attractive Is the Edge Computing Market for New Investment?

The edge computing industry presents a highly attractive investment case, supported by a USD 602.5 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and healthcare applications. We found that investment attractiveness is highest for vendors combining validated AI inference capability with scaled cloud-to-edge platform reach, positioning them to serve both cost-sensitive and premium enterprise segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor deployment complexity, distributed security management challenges, and data sovereignty regulatory shifts as key risks to the edge computing market. Our analysis shows that suppliers unable to demonstrate credible security and interoperability across distributed nodes risk losing enterprise contracts to competitors with validated cloud-to-edge reference architectures, particularly as regulatory scrutiny of data localization intensifies.

What Are the Key Growth Pathways for the Edge Computing Market?

Key growth pathways include expanding network edge and AI inference software portfolios, scaling functional-safety-certified industrial edge hardware, and deepening penetration into healthcare and transportation verticals. Next Move Strategy Consulting's analysis indicates that suppliers pursuing these pathways while maintaining hardware cost competitiveness will be best positioned to capture the edge computing market's projected growth through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market Growth Analysis
  • Historical revenue analysis of edge computing across hardware, software, and services components, with edge type and end-user industry splits.
  • Reveals growth patterns by component and industry to prioritize investment and portfolio focus.
Company-Level Technology Revenue Benchmarking
  • Revenue attributable to edge-related offerings (hardware, platforms, services) for leading vendors, based on disclosed segment and business-line reporting.
  • Shows vendor edge exposure and monetization strength to guide partnership and competitive positioning.
TAM / SAM / VAM Opportunity Sizing
  • Total, serviceable, and value-addressable market sizing by component, edge type, organization size, and end-user industry.
  • Pinpoints the most attainable revenue pools and sets realistic targets for market entry and expansion.
Edge Deployment Use Case Prioritization
  • Application-wise adoption mapping (e.g., IoT analytics, video analytics, content delivery, predictive maintenance, AR/VR) against edge type and end-user industry, using public deployment announcements and case studies.
  • Ranks high-value applications by industry so product and go-to-market effort goes where demand is strongest.
Organization Size Adoption Assessment
  • Edge adoption and spending patterns for SMEs versus large enterprises by component and edge type, using national statistics and institutional enterprise technology surveys.
  • Identifies underserved SME segments and informs pricing, packaging, and channel strategies.
Edge Ecosystem and Partnership Mapping
  • Mapping of hardware vendors, cloud and telecom providers, software platform firms, and system integrators across edge types, with announced partnerships and alliances.
  • Highlights partnership, alliance, and M&A opportunities across the edge value chain.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖