Europe Autonomous Mobile Robot (AMR) Market By Product Type (Autonomous Transport Robots, Autonomous Picking Robots, & Others), By Navigation Technology (LiDAR, Vision Navigation, & Others), By Payload Capacity (<100 KG, 100–1000 KG, & Others), By Deployment Environment (Indoor & Outdoor), By Commercial Model (Direct Sales, System Integrator Sales, & Others), By End-User Industry (Warehousing and Distribution, Manufacturing, & Others) – Opportunity Analysis & Forecast, 2025–2035
Industry: Semiconductor & Electronics | Latest Edition: August 21, 2026 | No of Pages: 1139 | No. of Tables: 578 | No. of Figures: 562 | Format: PDF | Report Code: SE4275
What Is the Europe Autonomous Mobile Robot (AMR) Market Size?
The Europe Autonomous Mobile Robot (AMR) Market size was valued at USD 1.29 billion in 2025 and is estimated at USD 1.56 billion in 2026, forecast to reach USD 5.43 billion by 2035, expanding at a 14.85% CAGR between 2026 and 2035. Autonomous Transport Robots dominate the market by product type, driven by strong pallet and tote movement demand across European warehouses. In terms of volume, the Europe AMR market recorded 39 thousand units in 2025, with forecasts indicating growth to 50 thousand units by 2026 and further to 231 thousand units by 2035, reflecting a CAGR of 18.58% over the forecast period.
|
Key Takeaways |
|
By Product Type: Autonomous Transport Robots is the dominant segment, while Autonomous Mobile Manipulators is the fastest-growing segment. |
|
By Navigation Technology: LiDAR is the dominant segment, while Sensor Fusion Navigation is the fastest-growing segment. |
|
By Payload Capacity: 100 Kgs to 1000 Kgs is the dominant segment, while 1001 Kgs to 5000 Kgs is the fastest-growing segment. |
|
By Deployment Environment: Indoor Autonomous Mobile Robots is the dominant segment, while Outdoor Autonomous Mobile Robots is the fastest-growing segment. |
|
By Commercial Model: Direct Sales is the dominant segment, while Robotics as a Service is the fastest-growing segment. |
|
By Revenue Stream: Robot Hardware is the dominant segment, while Software is the fastest-growing segment. |
|
By End User Industry: Warehousing and Distribution is the dominant segment, while Healthcare is the fastest-growing segment. |
Market Opportunity: The Europe autonomous mobile robot (AMR) market is expected to create an absolute dollar opportunity of USD 3.87 billion between 2026 and 2035, presenting significant investment potential across fleet orchestration software, robotics-as-a-service commercial models, and warehousing automation deployments.
According to NMSC's analysis, companies are increasingly bundling navigation software and maintenance services with hardware sales, strengthening recurring revenue streams across the Europe autonomous mobile robot (AMR) market through 2035.
What Does the Europe Autonomous Mobile Robot (AMR) Market Encompass?
The Europe autonomous mobile robot (AMR) market encompasses wheeled, self-navigating robotic systems including transport robots, picking robots, mobile manipulators, and forklift robots deployed across manufacturing plants, warehouses, and distribution centers without fixed infrastructure such as rails or magnetic strips. Our assessment indicates that the market spans robot hardware, fleet-management and navigation software, and installation, integration, and maintenance services, sold through direct sales, system integrators, and robotics-as-a-service commercial models. Coverage extends across product type, navigation technology, payload capacity, deployment environment, commercial model, revenue stream, and end-user industry segments.
Regulation (EU) 2023/1230 on machinery, which fully replaces the 2006 Machinery Directive from January 2027, explicitly addresses autonomous mobile machinery, requiring documented supervisory functions, obstacle-detection validation, and cybersecurity protections for sensor-based navigation systems. We observed that manufacturers are accelerating compliance-by-design engineering, sensor-fusion navigation, and lithium-ion opportunity-charging architectures ahead of this deadline. NMSC's analysis indicates that rising labor shortages, e-commerce fulfillment throughput requirements, and EU Chips Act-linked semiconductor capacity expansion continue to reshape technology adoption and commercial-model preferences across the Europe autonomous mobile robot (AMR) market.
|
Parameters |
Details |
|
Market Size in 2025 |
USD 1.29 Billion |
|
Market Size in 2026 |
USD 1.56 Billion |
|
Revenue Forecast in 2035 |
USD 5.43 Billion |
|
Market Size Growth Rate |
CAGR of 14.85% from 2026 to 2035 |
|
Market Volume in 2025 |
39 Thousand Units |
|
Market Volume in 2026 |
50 Thousand Units |
|
Volume Forecast in 2035 |
231 Thousand Units |
|
Market Volume Growth Rate |
CAGR of 18.58% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Billion (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
Key Emerging Trends
Based on research conducted by NMSC, we found that four structural trends are reshaping product architecture, commercial models, and competitive dynamics across the Europe autonomous mobile robot (AMR) market.
How Is Sensor Fusion Navigation Transforming Deployment Flexibility?
Sensor fusion navigation, combining LiDAR, vision cameras, and inertial measurement data, is enabling AMRs to operate reliably across mixed indoor-outdoor environments without dedicated infrastructure. We observed that vendors including KUKA are integrating multi-sensor navigation stacks that reduce dependency on magnetic strips and markers. This shift toward infrastructure-free navigation lowers deployment lead times, benefiting warehouse operators seeking rapid reconfiguration between seasonal fulfillment layouts.
Why Is Robotics-as-a-Service Gaining Commercial Traction?
Subscription-based robotics-as-a-service models are gaining traction as small and mid-sized manufacturers seek automation without large upfront capital outlays. We observed that vendors are bundling robot hardware, fleet-management software, and maintenance services into per-pick or per-hour pricing structures. This commercial shift is broadening the addressable customer base beyond large enterprises toward mid-sized logistics and manufacturing operators previously unable to justify direct capital purchases.
How Is the Machinery Regulation Reshaping Compliance Requirements?
Regulation (EU) 2023/1230, applicable from 20 January 2027, introduces mandatory cybersecurity protections, AI safety-review obligations, and detailed documentation for sensor-based autonomous navigation. Our findings suggest that manufacturers are front-loading technical file preparation, including validation evidence for obstacle detection and supervisory functions, to avoid disruption when the regulation takes full effect. This compliance timeline is influencing procurement cycles as European end-users seek certainty on post-2027 conformity.
What Role Do Mobile Manipulators Play in Expanding Use Cases?
Autonomous mobile manipulators, combining robotic arms with mobile bases, are expanding AMR use cases beyond transport into inspection and maintenance tasks. Our analysis indicates that manufacturers are piloting manipulator-equipped AMRs for machine tending and quality inspection in automotive and electronics facilities. This trend broadens the addressable application base beyond pure material movement, positioning mobile manipulators as a differentiated growth segment for hardware and integration vendors.
Ecosystem Analysis of the Europe Autonomous Mobile Robot (AMR) Market
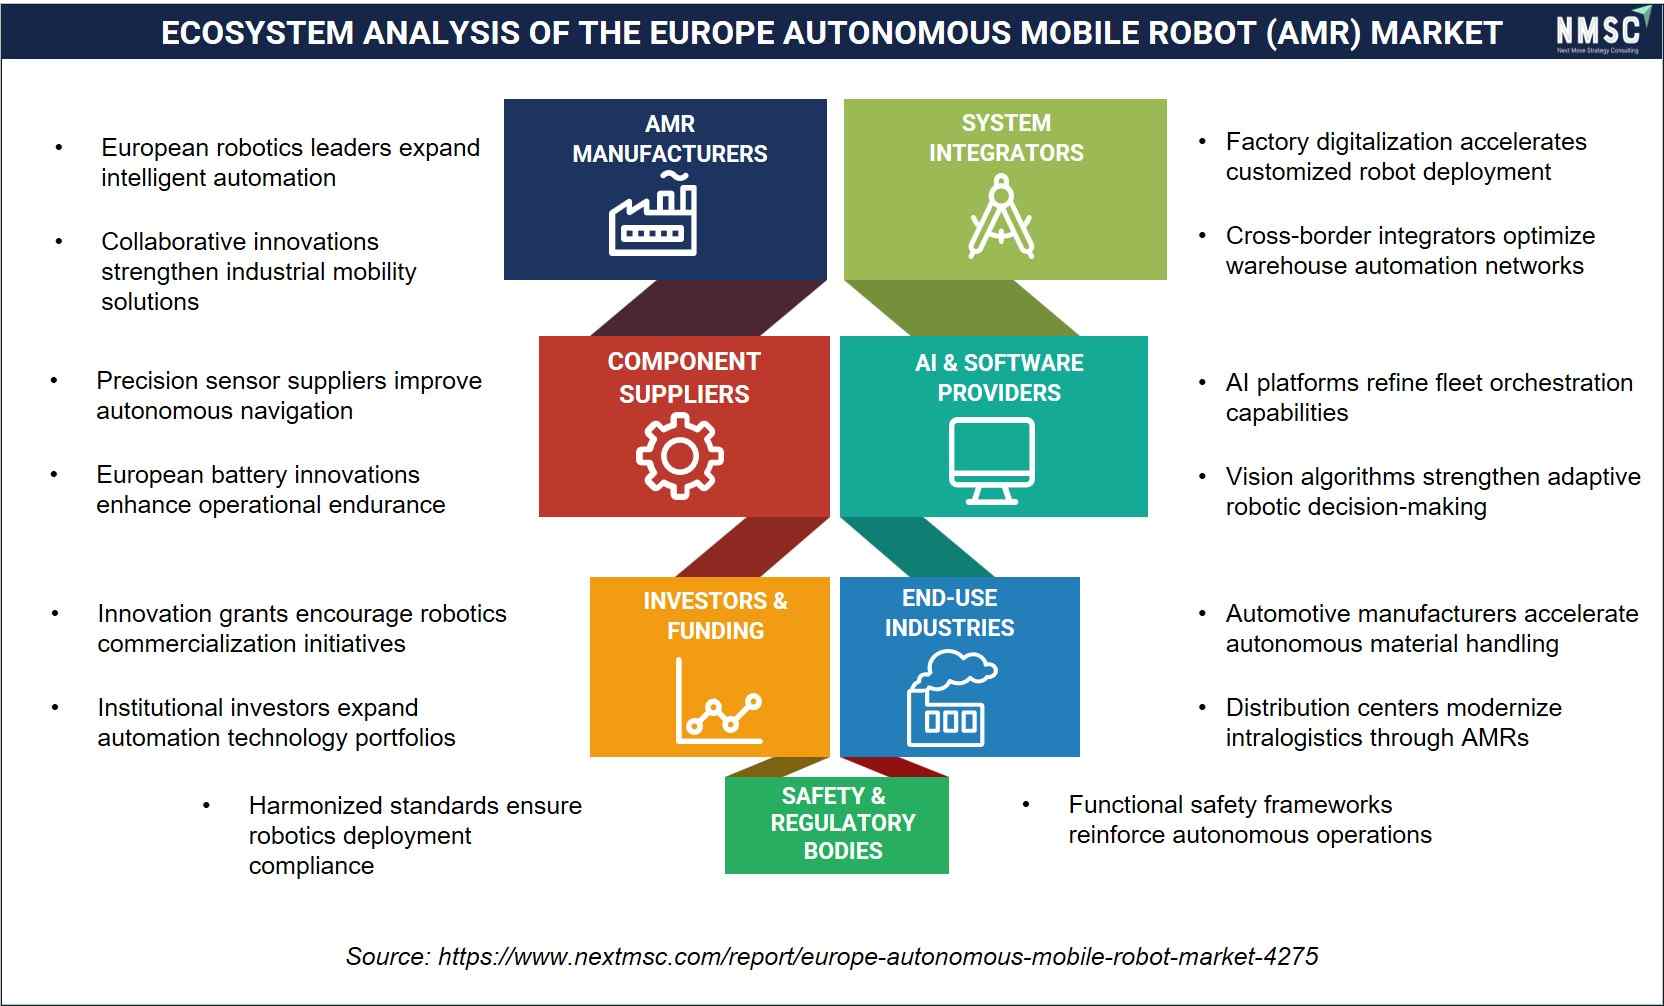
The above ecosystem analysis maps the key operational components, such as AMR manufacturers, system integrators, component suppliers, AI and software providers, investors and funding, end-use industries, and safety and regulatory bodies, shaping the Europe AMR market. From our analysis, we observed that AMR manufacturers and component suppliers drive production advancements, while AI and software providers enhance autonomous capabilities. System integrators ensure seamless deployment, whereas investors and funding support market expansion. End-use industries across logistics, manufacturing, and automotive drive adoption, while safety and regulatory bodies ensure compliance standards across the market ecosystem.
Growth Drivers and Restraints
Growth Catalyst and Risk Assessment Matrix
|
Factors |
Type |
(+/−) % Impact on CAGR |
Geographic Relevance |
Impact Timeline |
|
Labor shortages and rising wage costs accelerating warehouse and manufacturing automation adoption |
Driver |
+3.28% |
Europe (strongest in Germany, France, and the Nordics) |
Medium to Long term (2–6 years) |
|
E-commerce order volumes and same-day fulfillment expectations driving flexible picking and transport robot investment |
Driver |
+2.61% |
Europe (nationwide; strongest in urban distribution hubs) |
Medium term (2–5 years) |
|
Growth of robotics-as-a-service commercial models lowering capital entry barriers for mid-sized enterprises |
Driver |
+2.34% |
Europe (nationwide) |
Long term (2–8 years) |
|
Sensor fusion and vision-navigation advances reducing infrastructure dependency and deployment lead times |
Driver |
+1.92% |
Europe (nationwide) |
Long term (2–7 years) |
|
Automotive sector electrification requiring reconfigurable intralogistics for battery and EV component handling |
Driver |
+1.65% |
Germany, France, Central Europe |
Medium to Long term (2–6 years) |
|
Regulation (EU) 2023/1230 compliance costs and validation timelines slowing new-model deployment ahead of 2027 |
Restraint |
−1.48% |
Europe (nationwide) |
Short term (1–2 years) |
|
High upfront integration costs and warehouse infrastructure retrofitting limiting adoption among smaller enterprises |
Restraint |
−1.31% |
Europe (strongest among SMEs) |
Short to Medium term (1–4 years) |
|
Shortage of skilled robotics integration and fleet-management personnel constraining deployment pace |
Restraint |
−1.07% |
Europe (nationwide) |
Short to Medium term (1–3 years) |
What Is the Primary Growth Driver of the Europe Autonomous Mobile Robot (AMR) Market?
Persistent labor shortages across European manufacturing and logistics is the primary growth driver of the Europe autonomous mobile robot (AMR) market. According to Eurostat's labor market indicators, several EU manufacturing sectors have reported job vacancy rates exceeding 2% for consecutive quarters, encouraging facility operators to pursue automation. We observed that facilities are deploying autonomous transport and picking robots for tasks previously reliant on manual labor, reducing dependency on hard-to-fill warehouse and production-line roles.
How Is E-Commerce Fulfillment Growth Driving Europe Autonomous Mobile Robot (AMR) Market Growth?
Rising e-commerce order volumes are accelerating demand for goods-to-person picking robots and transport robots within fulfillment centers. We observed that operators are prioritizing flexible, software-orchestrated fleets capable of scaling during peak seasonal demand without permanent infrastructure investment. Our assessment indicates that this demand is particularly strong within third-party logistics and retail distribution sub-segments, where order variability requires rapid reconfiguration of picking and transport workflows.
What Is Restraining Europe Autonomous Mobile Robot (AMR) Market Expansion?
Compliance costs and validation timelines associated with Regulation (EU) 2023/1230, which applies fully from 20 January 2027, are restraining near-term expansion. Manufacturers must document sensor-based navigation validation, cybersecurity protections, and supervisory-function evidence within technical files before that deadline. We found that smaller integrators face particular pressure, as documentation and testing requirements demand engineering resources that larger, established vendors can absorb more readily.
Segmentation Analysis
By Product Type Insights
How Is the Europe Autonomous Mobile Robot (AMR) Market Segmented by Product Type?
Based on product type, the Europe Autonomous Mobile Robot (AMR) market is segmented into autonomous transport robots, autonomous picking robots, autonomous mobile manipulators, autonomous forklift robots, and specialized AMRs.
Transport robots, spanning tugger, cart, pallet, shelf and rack, and conveyor formats, serve broad material-movement needs across warehouses and production floors. Picking robots, covering goods-to-person, person-to-goods, piece-picking, and case-picking formats, are seeing accelerated adoption as fulfillment centers seek to reduce manual walking time. We observed that mobile manipulators and forklift robots are expanding into inspection, maintenance, and heavy-load applications, while specialized AMRs serving healthcare, laboratory, retail, and security use cases represent a smaller but growing niche.
By Commercial Model Insights
How Is the Europe Autonomous Mobile Robot (AMR) Market Segmented by Commercial Model?
Based on commercial model, the Europe Autonomous Mobile Robot (AMR) market is segmented into direct sales, system integrator sales, and robotics as a service.
Direct sales remain common among large enterprises with dedicated automation budgets and in-house integration capability, while system integrator sales support mid-sized manufacturers requiring turnkey deployment support. We observed that robotics-as-a-service arrangements are expanding rapidly, particularly among logistics operators and smaller manufacturers seeking predictable operating costs over large upfront capital commitments. This shift is reshaping vendor revenue models toward subscription-based, service-inclusive contracts that bundle hardware, software, and maintenance.
Growth Opportunities
We found that three whitespace opportunities are emerging as key differentiators for stakeholders across the Europe autonomous mobile robot (AMR) market.
How Can Robotics-as-a-Service Models Expand Market Access?
Subscription-based robotics-as-a-service models are lowering capital entry barriers for small and mid-sized manufacturers, creating substantial opportunity for vendors that develop flexible leasing and per-pick pricing structures. This mechanism benefits software and services revenue-stream providers by converting one-time hardware sales into recurring relationships with warehousing and manufacturing end-users.
Where Does Sensor Fusion Navigation Create New Demand?
Advances in sensor fusion navigation, combining LiDAR, vision, and inertial data, are creating demand for infrastructure-free AMRs deployable across both indoor and outdoor environments. This opportunity particularly benefits navigation-technology vendors and hardware manufacturers developing multi-sensor platforms, positioning them to capture growing outdoor deployment-environment spending across logistics terminals and industrial yards.
How Can Mobile Manipulator Platforms Capture Inspection Demand?
Growing demand for automated inspection and maintenance tasks is creating opportunity for autonomous mobile manipulator platforms combining robotic arms with mobile bases. This mechanism benefits hardware vendors and system integrators serving manufacturing end-users, particularly within automotive and electronics and semiconductors sub-segments seeking to automate quality-inspection workflows beyond simple material transport.
Which Country is Dominating the Europe Autonomous Mobile Robot (AMR) Market?
Through our market assessment, we observed that Germany dominates the Europe Autonomous Mobile Robot (AMR) Market, supported by its highly developed manufacturing sector, strong industrial automation ecosystem, and early adoption of Industry 4.0 technologies. As manufacturers and logistics operators increasingly prioritize productivity, flexibility, and efficient material handling, demand for AMRs is expanding across factories, warehouses, and distribution centers. This momentum is further reinforced by Germany's established automotive and engineering industries, significant investments in smart manufacturing, and the presence of leading robotics and automation providers, strengthening its position as Europe's key AMR market.
Which Country is Set to Witness the Fastest Growth?
Our findings suggest that Denmark is set to witness the fastest growth in the Europe Autonomous Mobile Robot (AMR) Market through 2035, driven by its strong focus on automation, smart manufacturing, and digitalization. As labor availability constraints encourage businesses to improve operational efficiency, manufacturers and logistics operators are increasingly adopting AMRs for material movement and warehouse processes. This shift is further supported by Denmark's advanced industrial ecosystem, growing e-commerce activity, and emphasis on Industry 4.0 technologies, creating favorable conditions for rapid AMR adoption across diverse end-use industries.
Competitive Landscape
We observed that the Europe autonomous mobile robot (AMR) market features a highly competitive landscape, with established material handling equipment manufacturers competing alongside specialized robotics companies and systems integrators.
|
Key Takeaways |
Description |
|
Market Structure |
Moderately consolidated, with global material handling equipment manufacturers holding significant share alongside specialized AMR and intralogistics robotics companies expanding through organic innovation and acquisition. |
|
Innovation Focus |
Sensor fusion navigation, fleet-orchestration software, mobile manipulation, and robotics-as-a-service commercial models dominate current product and go-to-market strategies. |
|
M&A Activity |
Strategic acquisitions and integration of mobility specialists into established material handling groups continue to shape the competitive landscape, strengthening combined hardware, software, and services portfolios. |
How Do Companies Compete in the Europe Autonomous Mobile Robot (AMR) Market?
Companies compete primarily through navigation technology, product-type breadth, service quality, and commercial-model flexibility. Leading manufacturers such as Jungheinrich Aktiengesellschaft, KUKA Aktiengesellschaft, and Toyota Material Handling Europe AB leverage extensive research capabilities, established distribution networks, and integrated hardware-software-services portfolios to maintain market leadership. Meanwhile, specialized entrants including AGILOX Italia S.r.l., Addverb Technologies B.V., and PAL Robotics S.L. differentiate through swarm routing, application-specific engineering, and agile product development cycles.
Which Competitive Archetypes Dominate the Europe Autonomous Mobile Robot (AMR) Market?
Two primary competitive archetypes characterize the market. The first comprises diversified material handling and industrial automation groups offering comprehensive AMR portfolios spanning transport, picking, and forklift robots supported by extensive service networks. Companies such as Jungheinrich Aktiengesellschaft, KUKA Aktiengesellschaft, Toyota Material Handling Europe AB, and Dematic GmbH represent this category. The second includes specialized robotics and navigation-technology companies such as AGILOX Italia S.r.l., Addverb Technologies B.V., PAL Robotics S.L., and Lowpad B.V., which focus on application-specific engineering and software-defined navigation.
How Are Companies Differentiating Through Innovation?
Innovation strategies increasingly center on sensor fusion navigation, cloud fleet-orchestration platforms, and mobile manipulator development that extend AMR use cases beyond transport. Companies are investing in navigation technologies incorporating LiDAR and machine vision while expanding robotics-as-a-service commercial offerings to serve customers across warehousing, manufacturing, and healthcare end-user industries. Our analysis indicates that manufacturers combining hardware reliability with software orchestration capability are strengthening competitive positioning.
What M&A Activity Is Shaping the Market?
Strategic acquisitions and integration of mobility specialists into established material handling groups continue to shape competition, following patterns such as the earlier integration of Swisslog's intralogistics business within the KUKA Group. Leading companies are strengthening positions through acquisitions of navigation-software specialists and expansion of systems-integration services, enabling broader product portfolios and more effective response to evolving robotics-as-a-service demand.
Key Market Players
Our assessment indicates that the following 15 companies are actively shaping product innovation, commercial-model development, and competitive dynamics within the Europe autonomous mobile robot (AMR) market.
-
Jungheinrich Aktiengesellschaft
-
AGILOX Italia S.r.l.
-
KUKA Aktiengesellschaft
-
Toyota Material Handling Europe AB
-
OMRON Electronics Limited
-
ABB AG
-
Addverb Technologies B.V.
-
AGVE AB
-
Swisslog GmbH
-
Dematic GmbH
-
SSI SCHAEFER Automation GmbH
-
ek robotics UK Ltd
-
Kivnon Logística S.L.U.
-
PAL Robotics S.L.
-
Lowpad B.V.
Investment Opportunities
What Capital Inflows Are Targeting the Europe Autonomous Mobile Robot (AMR) Market?
Capital inflows are increasingly directed toward fleet-orchestration software, sensor fusion navigation, and robotics-as-a-service commercial platforms. Leading material handling groups continue to invest in research and development to expand compliance-ready portfolios ahead of Regulation (EU) 2023/1230's January 2027 deadline. We observed that investors favor companies demonstrating strong software integration capability and diversified end-user exposure across warehousing, manufacturing, and healthcare applications.
How Is Infrastructure Investment Supporting the Europe Autonomous Mobile Robot (AMR) Market?
Infrastructure investment is expanding manufacturing capacity, navigation-software development centers, and systems-integration service networks across the European AMR industry. Our findings suggest that companies are investing in advanced sensor manufacturing and regional service hubs to improve deployment speed and after-sales support. Manufacturers are also strengthening partnerships with warehouse operators and automotive assemblers to accelerate large-scale fleet rollouts under robotics-as-a-service arrangements.
What ESG Considerations Are Shaping Investment Decisions in the Europe Autonomous Mobile Robot (AMR) Market?
Environmental, social, and governance considerations are increasingly integral to investment decisions, with energy-efficient lithium-ion battery systems, extended hardware lifecycles through software upgrades, and workplace safety improvements emerging as key priorities. We found that investors increasingly favor companies demonstrating measurable progress in reducing energy consumption per operating hour and improving human-robot collaborative safety, reinforcing long-term value creation across the market.
Key Benefits for Stakeholders
How Does This Report Benefit Enterprise and Industry Leaders?
Enterprise and industry leaders gain access to validated market segmentation, competitive benchmarking, and technology-adoption analysis that support strategic planning and fleet-procurement decisions across the Europe autonomous mobile robot (AMR) market. Our analysis shows that detailed assessments of product-type, navigation-technology, and commercial-model segments help companies identify high-growth deployment opportunities and strengthen long-term automation roadmaps.
How Does This Report Benefit Investors and Financial Analysts?
Investors and financial analysts benefit from consistent market size estimates, growth forecasts, and competitive assessments that support investment evaluation and capital allocation decisions. We observed that the report's detailed analysis of robotics-as-a-service, software, and compliance-ready segments enables stakeholders to identify companies with the strongest long-term growth potential through 2035.
How Does This Report Benefit Technology Vendors and Product Teams?
Technology vendors and product development teams gain valuable insights into emerging navigation, commercial-model, and compliance trends transforming the European AMR industry. Our findings suggest that this analysis helps research and development teams prioritize product pipelines and align offerings with evolving regulatory and end-user requirements.
Regulatory Framework Impacting the Europe Autonomous Mobile Robot (AMR) Market
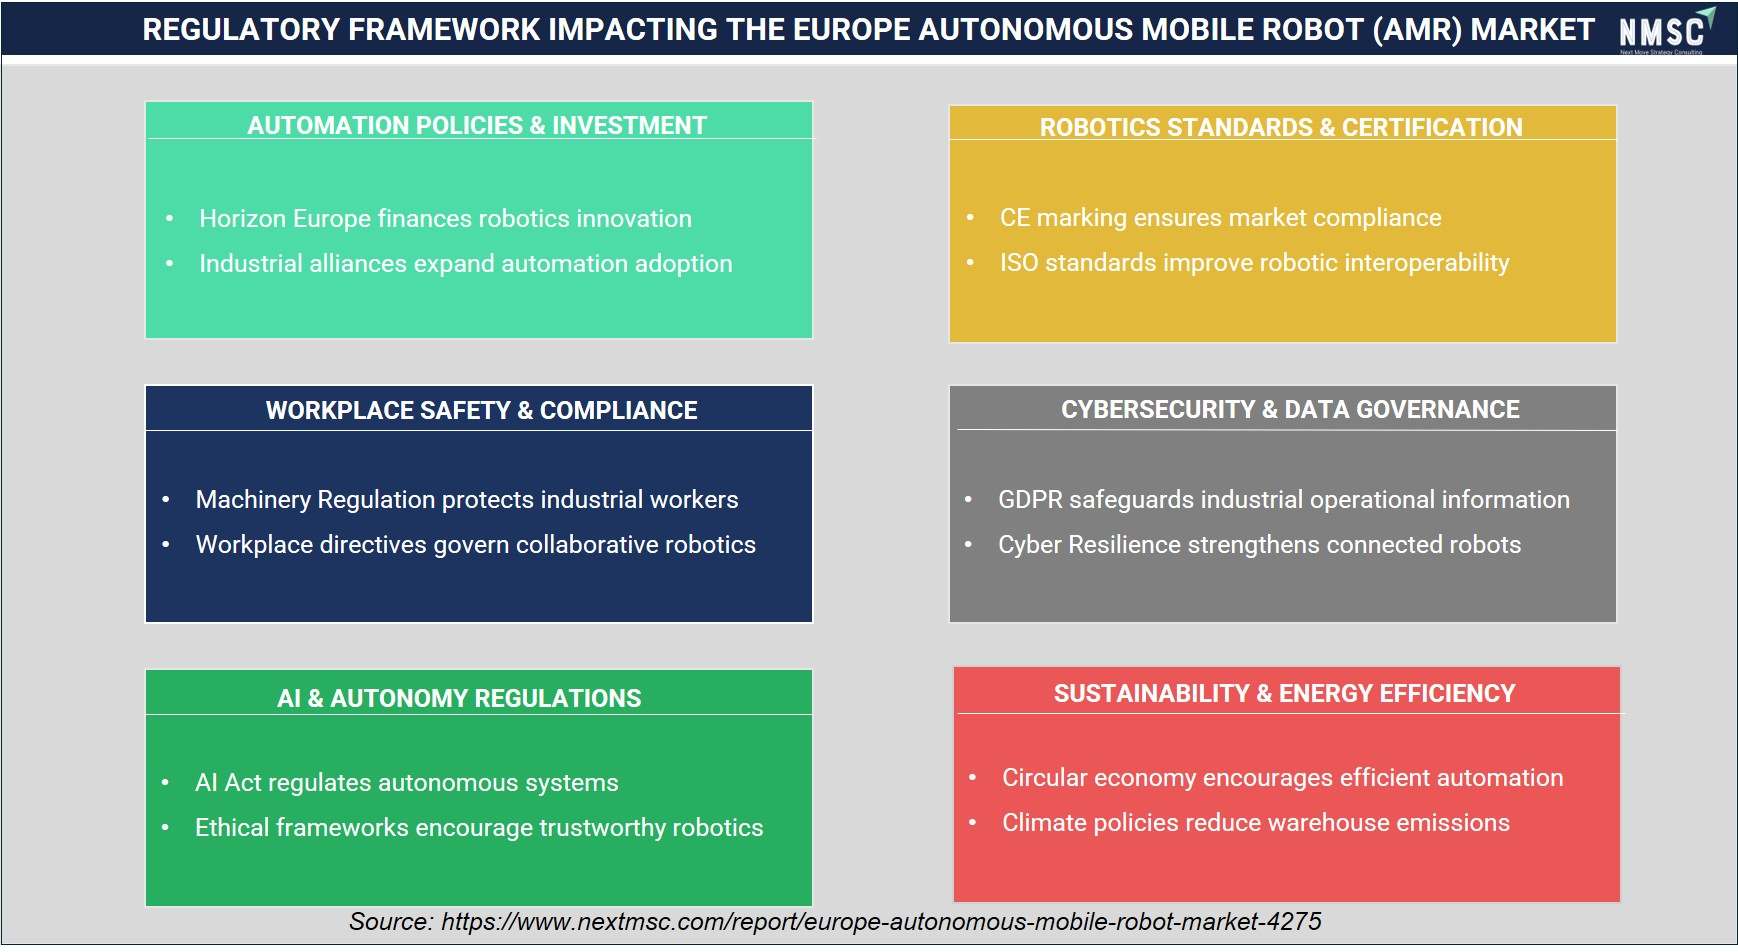
The above regulatory framework analysis maps the key regulatory components, such as automation policies and investment, workplace safety and compliance, AI and autonomy regulations, robotics standards and certification, cybersecurity and data governance, and sustainability and energy efficiency, shaping the Europe AMR market. From our analysis, we observed that Horizon Europe finances robotics innovation and industrial alliances expand automation adoption, while Machinery Regulation protects industrial workers and workplace directives govern collaborative robotics. The AI Act regulates autonomous systems, and CE marking ensures market compliance, whereas GDPR safeguards industrial operational information and the circular economy encourages efficient automation.
Key Market Segments
By Product Type
-
Autonomous Transport Robots
-
Tugger
-
Cart
-
Pallet
-
Shelf and Rack
-
Conveyor
-
Other Transport Robots
-
-
Autonomous Picking Robots
-
Goods to Person
-
Person to Goods
-
Piece Picking
-
Case Picking
-
Other Picking Robots
-
-
Autonomous Mobile Manipulators
-
Robotic Arm
-
Inspection Manipulators
-
Maintenance Manipulators
-
Other Mobile Manipulators
-
-
Autonomous Forklift Robots
-
Counterbalance Forklift
-
Reach Forklift
-
Stacker Forklift
-
Pallet Truck
-
Other Forklift Robots
-
-
Specialized AMRs
-
Healthcare Robots
-
Laboratory Robots
-
Retail Robots
-
Security Robots
-
Other Specialized Robots
-
By Navigation Technology
-
LiDAR
-
Vision Navigation
-
Sensor Fusion Navigation
-
Magnetic and Marker Navigation
-
Other Navigation Technology
By Payload Capacity
-
< 100 Kgs
-
100 Kgs to 1000 Kgs
-
1001 Kgs to 5000 Kgs
-
> 5000 Kgs
By Deployment Environment
-
Indoor Autonomous Mobile Robots
-
Warehouse Environment
-
Manufacturing Environment
-
Healthcare Environment
-
Retail Environment
-
Laboratory Environment
-
-
Outdoor Autonomous Mobile Robots
-
Industrial Yard Environment
-
Logistics Terminal Environment
-
Other Outdoor Environment
-
By Commercial Model
-
Direct Sales
-
System Integrator Sales
-
Robotics as a Service
By Revenue Stream
-
Robot Hardware
-
Software
-
Fleet Management Software
-
Navigation Software
-
Robot Operating Software
-
Analytics Software
-
AI Software
-
-
Services
-
Installation and Deployment
-
Integration Services
-
Maintenance Services
-
Robotics as a Service
-
By End User Industry
-
Warehousing and Distribution
-
E-commerce Fulfillment
-
Third Party Logistics
-
Retail Distribution
-
-
Manufacturing
-
Automotive
-
Electronics and Semiconductors
-
Machinery and Equipment
-
Food and Beverage Manufacturing
-
Other Manufacturing
-
-
Healthcare
-
Hospitals
-
Laboratories
-
Pharmaceutical Facilities
-
-
Retail
-
Other Industries
By Region
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Netherlands
-
Finland
-
Sweden
-
Rest of Europe
Conclusion and Recommendations
What Is the Long-Term Outlook for the Europe Autonomous Mobile Robot (AMR) Market?
The long-term outlook remains positive, supported by persistent labor shortages, expanding e-commerce fulfillment demand, and continued innovation in sensor fusion navigation and robotics-as-a-service commercial models. We observed that growing adoption of picking robots and mobile manipulators will continue to drive market expansion across warehousing, manufacturing, and healthcare end-user industries throughout the forecast period.
What Strategic Positioning Should Europe Autonomous Mobile Robot (AMR) Market Companies Pursue?
Manufacturers should prioritize investments in fleet-orchestration software, compliance-ready hardware, and flexible robotics-as-a-service commercial models while strengthening systems-integration capabilities. Our assessment indicates that companies expanding software-defined orchestration and application-specific engineering will be well positioned to strengthen customer retention and capture premium end-user segments within the market.
How Attractive Is the Europe Autonomous Mobile Robot (AMR) Market for New Investment?
The market presents an attractive investment opportunity, supported by growing capital expenditure on warehouse and manufacturing automation and continued innovation in sensor fusion navigation solutions. We found that investment potential is particularly strong for companies focused on robotics-as-a-service models, mobile manipulator platforms, and compliance-ready hardware, enabling them to capitalize on long-term growth.
What Market Shifts and Key Risks Should Stakeholders Monitor?
Stakeholders should closely monitor Regulation (EU) 2023/1230 compliance timelines, evolving navigation-technology standards, and intensifying competition from emerging robotics entrants. Our analysis shows that companies unable to demonstrate documented safety validation or meet growing demand for robotics-as-a-service commercial models may face increasing competitive pressure ahead of the January 2027 regulatory deadline.
What Are the Key Growth Pathways for the Europe Autonomous Mobile Robot (AMR) Market?
Key growth pathways include expanding robotics-as-a-service commercial offerings, accelerating innovation in sensor fusion navigation and mobile manipulator platforms, and strengthening compliance-ready engineering ahead of 2027. NMSC's analysis indicates that companies successfully combining hardware reliability, software orchestration, and regulatory readiness will be best positioned to capture the market's projected growth through 2035.


About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

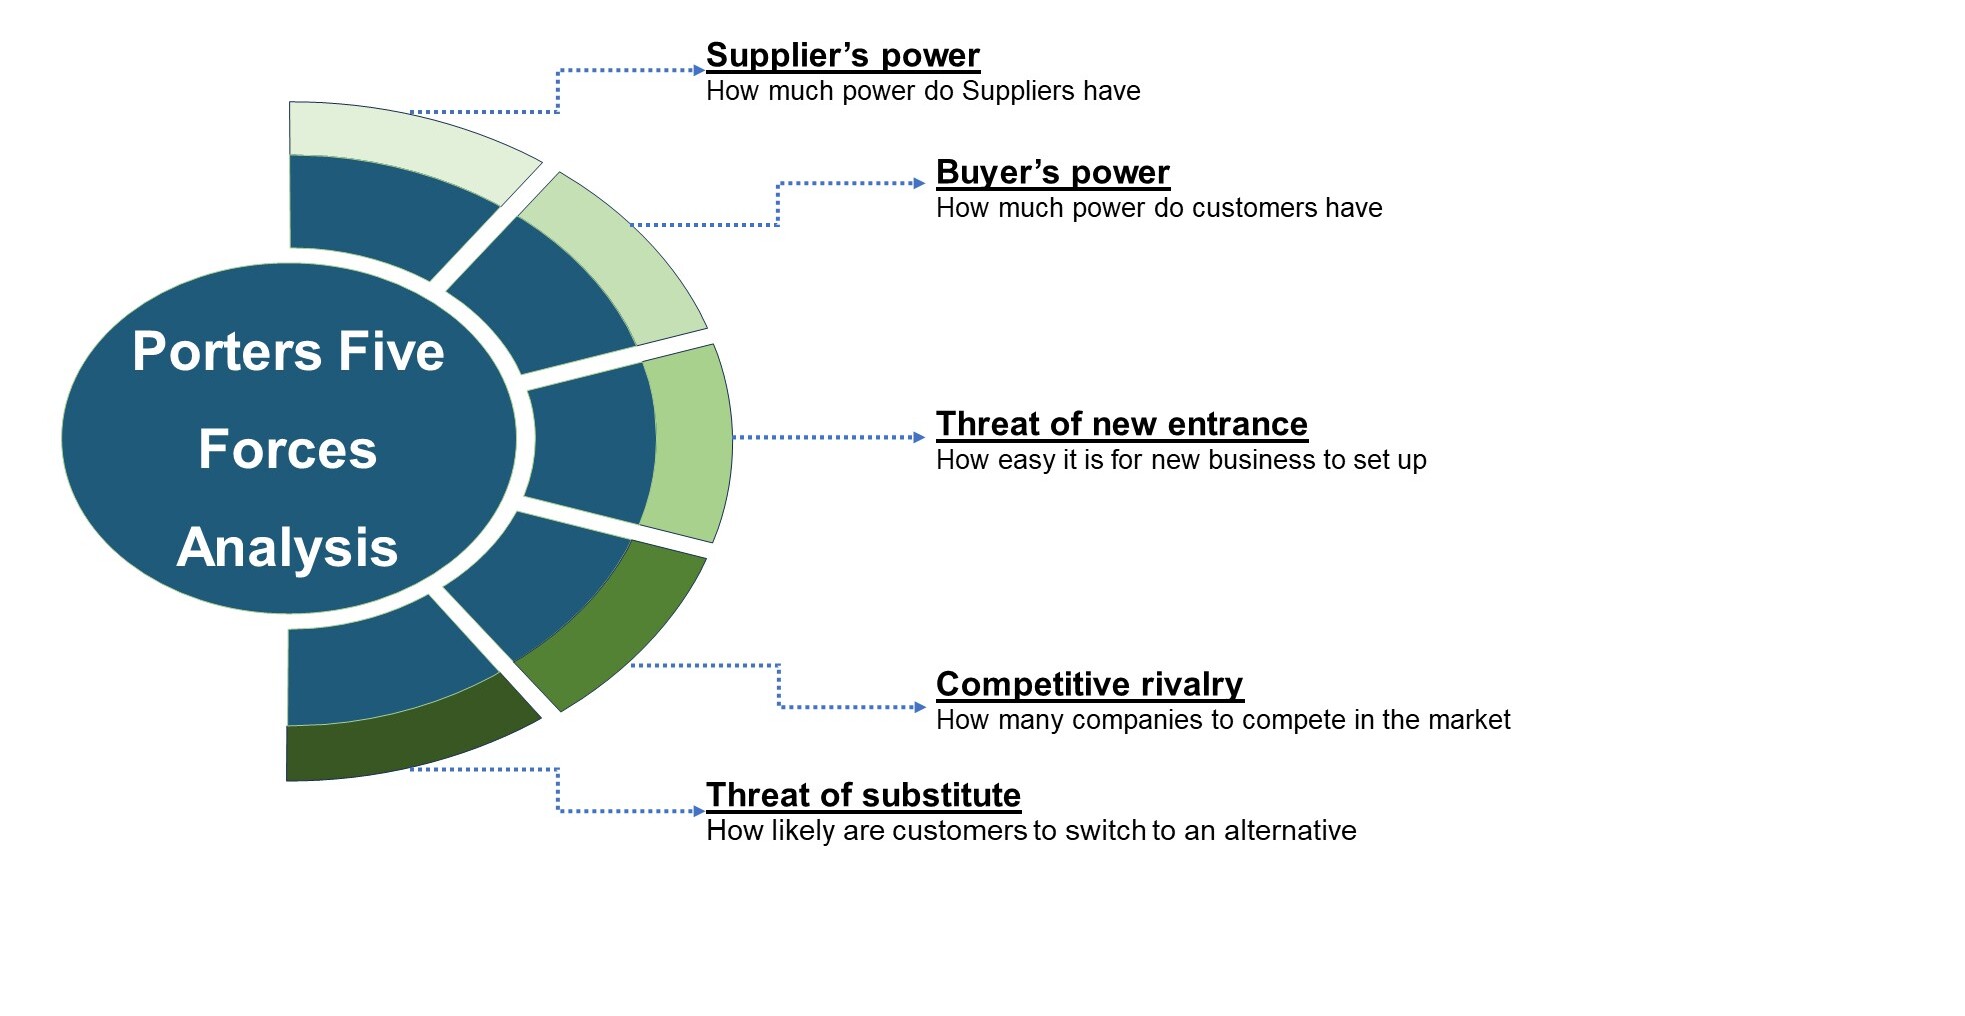
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.



 Speak to Our Analyst