Insurance Platform Market

Insurance platform market size was USD 118.50 billion in 2025, projected to reach USD 362.00 billion by 2035, and is growing at a 11.8% CAGR from 2026-2035

Download Free Sample PDF
Base Year (2025)
$118.50 Billion
Forecast (2035)
$362.00 Billion
CAGR (2026-2035)
11.8%
Top Region
North America

What Is the Insurance Platform Market Size?
The global insurance platform industry size was valued at USD 118.50 billion in 2025 and is estimated at USD 132.90 billion in 2026, forecast to reach USD 362.00 billion by 2035, expanding at a 11.8% CAGR between 2026 and 2035. North America leads with approximately 44% share, while Policy Administration Systems dominates all other components with approximately 22% share.

We observed that growth is broad-based across every segmentation axis, with agentic underwriting automation and cloud-native core modernization driving the dominant structural shifts through 2035.

Insurance Platform Market Revenue Forecast
Values in USD Billion

2025 $118.50 Billion
2025
2026 $132.48 Billion
2026
2027 $148.12 Billion
2027
2028 $165.59 Billion
2028
2029 $185.13 Billion
2029
2030 $206.98 Billion
2030
2031 $231.40 Billion
2031
2032 $258.71 Billion
2032
2033 $289.24 Billion
2033
2034 $323.37 Billion
2034
2035 $362.00 Billion
2035

Key Takeaways

By Component: Policy Administration Systems held the largest share of approximately 22% (USD 26.07 billion) in 2025; Data and Analytics Systems is the fastest-growing sub-segment at 16.4% CAGR from 2026–2035.

By Deployment Mode: Cloud/SaaS held the largest share of approximately 58% (USD 68.73 billion) in 2025; Cloud/SaaS is also the fastest-growing sub-segment at 14.5% CAGR from 2026–2035.

By Insurance Type: Property and Casualty held the largest share of approximately 38% (USD 45.03 billion) in 2025; Travel and Specialty is the fastest-growing sub-segment at 18.9% CAGR from 2026–2035.

By Enterprise Size: Large Enterprises held the largest share of approximately 70% (USD 82.95 billion) in 2025; Small and Medium Enterprises is the fastest-growing sub-segment at 13.7% CAGR from 2026–2035.

By End User: Insurance Carriers held the largest share of approximately 64% (USD 75.84 billion) in 2025; Third-Party Administrators is the fastest-growing sub-segment at 16.0% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 44% revenue share (USD 52.14 billion) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 15.9% during 2026–2035.

Dominant Country: U.S. led with approximately USD 44.50 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 19.1% CAGR from 2026–2035.

Market Opportunity: The insurance platform market is expected to create an absolute dollar opportunity of USD 229.10 billion between 2026 and 2035, presenting significant investment potential across the core system modernization and agentic underwriting value chain.

According to NMSC analysis, carriers are increasingly favoring composable, API-first platform architectures over monolithic core system replacements, a shift that favors vendors with modular deployment models over single-suite incumbents as [digital transformation budgets](https: //www.nextmsc.com/report/digital-transformation-market) tighten through 2035.

What Does the Insurance Platform Market Encompass?
The insurance platform industry encompasses software and services that enable insurers, brokers, and third-party administrators to manage policy administration, claims, underwriting, billing, and distribution across the insurance lifecycle. We observed that the scope spans cloud-native core systems, software-as-a-service delivery models, and legacy on-premise platforms procured by carriers writing life, property and casualty, health, and specialty lines. The category has evolved from siloed policy and claims administration modules into unified, API-first ecosystems that integrate underwriting, billing, and customer engagement on a single data foundation.
Regulatory frameworks such as IFRS 17 and Solvency II shape platform data and reporting architecture in Europe, while the NAIC's AI Model Bulletin increasingly influences governance requirements for AI-driven underwriting and claims decisions in the U.S. We observed that technology adoption is shifting toward agentic AI and low-code configuration platforms that let business users design products without heavy IT dependency. NMSC's analysis indicates that this structural shift, combined with rising InsurTech ecosystem partnerships, is redefining vendor selection criteria across the insurance platform industry.

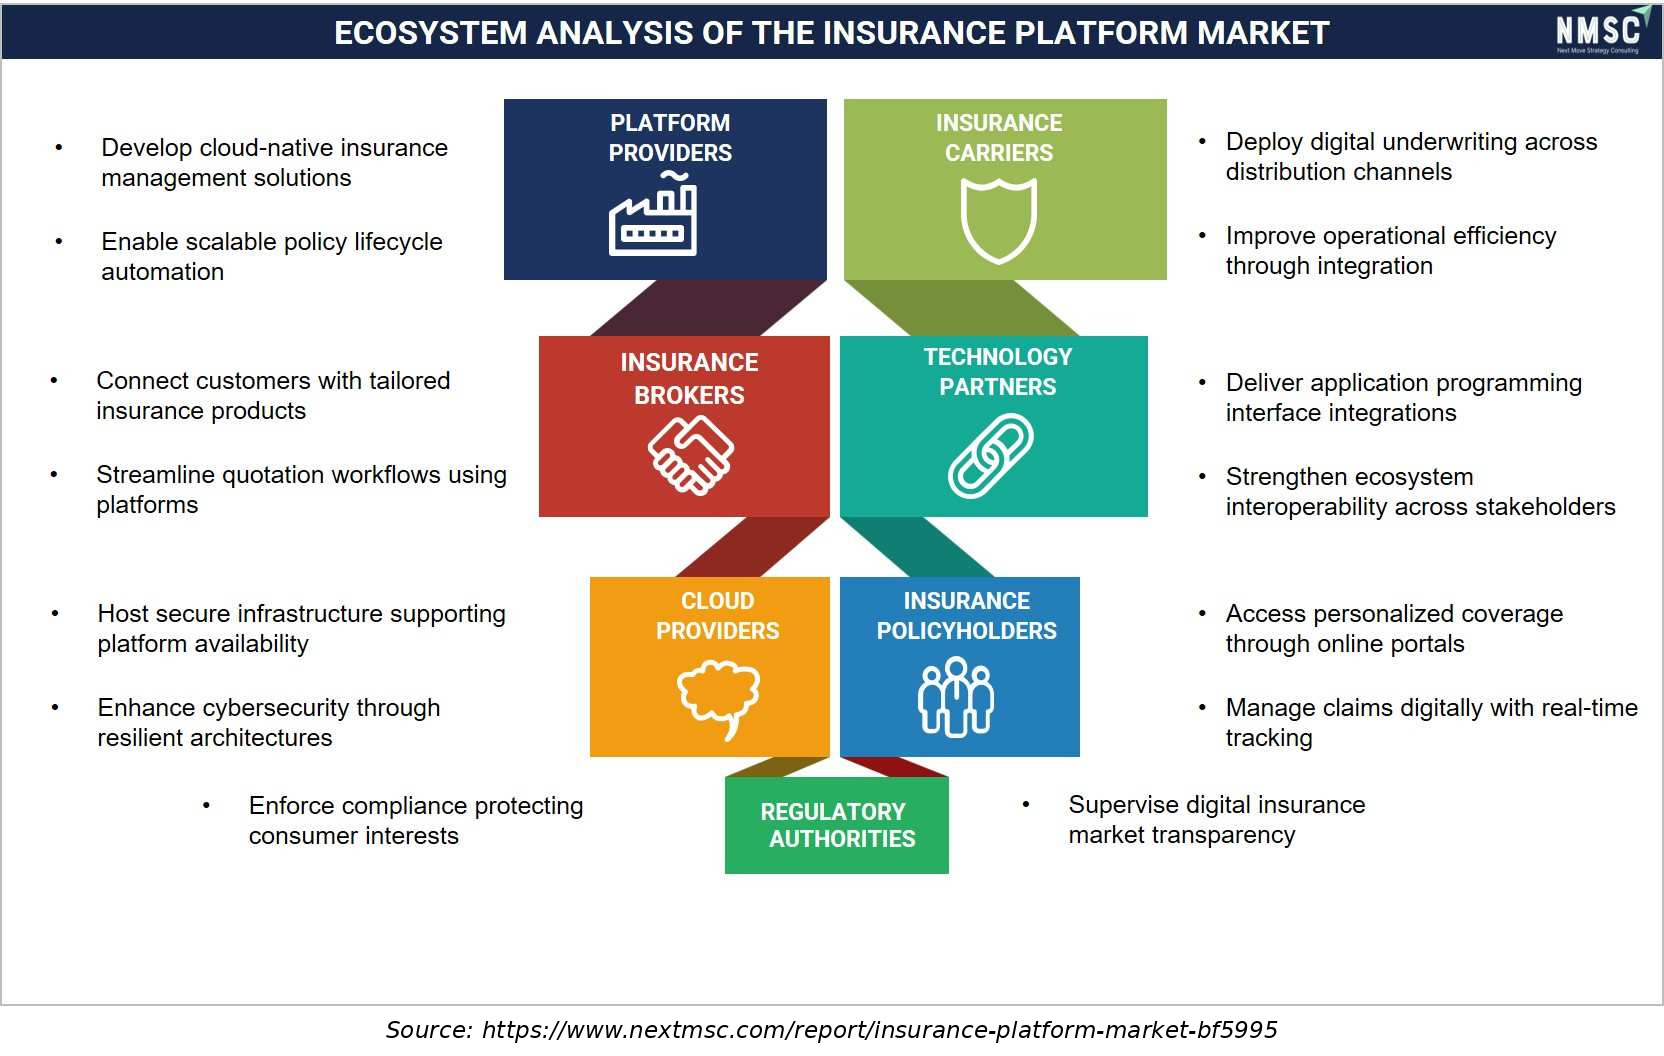
Ecosystem Analysis of the Insurance Platform Market
The insurance platform market ecosystem connects platform providers, insurance carriers, brokers, technology partners, cloud providers, policyholders, and regulatory authorities. Collaboration among these stakeholders enables seamless policy administration, digital distribution, secure data exchange, and automated claims processing. Continuous technological innovation and regulatory compliance strengthen operational efficiency, improve customer experience, and accelerate digital transformation across the insurance value chain.

Market Drivers & Dynamics

Interactive Dataset
Accelerating replacement of legacy core systems with cloud-native platforms driver +2.3% Global 2026-2035
Rising agentic AI and automation adoption in underwriting and claims driver +2.0% Global 2026-2035
Increasing insurer demand for real-time data and analytics platforms driver +1.5% Global 2026-2035
Growing embedded and usage-based insurance distribution models driver +1.4% North America, Europe 2026-2033
Expanding InsurTech investment and API-first ecosystem partnerships driver +1.2% North America, Asia-Pacific 2026-2035
Tightening regulatory compliance requirements including IFRS 17 and Solvency II driver +1.1% Europe, Asia-Pacific 2026-2032
High cost and complexity of core system migration projects restraint -1.4% Global 2026-2035
Data security and regulatory fragmentation across jurisdictions restraint -0.9% Global 2026-2032
Shortage of skilled implementation and integration talent restraint -0.7% North America, Europe 2026-2030
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Insurance Platform sector?

Accelerating replacement of legacy core administration systems is the primary driver of the market. The U.S. Securities and Exchange Commission's public filings from core system vendors continue to document sustained double-digit annual recurring revenue growth tied to carrier modernization contracts. We observed that this replacement cycle, reinforced by rising claims complexity, continues to anchor baseline demand for policy administration and claims management platforms across large and mid-tier carriers alike.

How Is Agentic AI Adoption Driving Insurance Platform Market Growth?
Agentic AI adoption is accelerating market growth as carriers seek to embed automated decisioning directly into underwriting and claims workflows. Duck Creek Technologies' April 2026 launch of its insurance-native Agentic AI Platform, developed in collaboration with Google Cloud, illustrates this shift toward governed, auditable AI agents. NMSC's analysis indicates that this automation trajectory, combined with rising InsurTech deal activity, is compressing adoption timelines for data and analytics-centric platform components.

Growth Inhibitors

What Is Restraining Insurance Platform industry Expansion?

High upfront cost and multi-year complexity associated with core system migration projects restrain broader deployment across smaller and mid-tier carriers. Regulatory filings reviewed via the U.S. Securities and Exchange Commission document recurring implementation timeline extensions tied to data migration and regulatory testing requirements. We found that limited availability of skilled systems integration talent particularly constrains small and medium enterprise carriers, which have fewer internal resources than large, multi-line insurance groups.

What Are the Growth Opportunities?

How Can Agentic Underwriting Unlock Value for Mid-Tier Carriers?

Agentic underwriting automation presents a whitespace opportunity for mid-tier carriers and managing general agents that lack the scale to justify full core system replacement. Vendors that commercialize core-system-agnostic AI underwriting layers stand to capture recurring subscription revenue as carriers deploy automation without disrupting existing policy administration infrastructure, particularly across commercial property and casualty insurance lines.

Where Does Embedded Insurance Distribution Create New Platform Demand?

Embedded insurance distribution represents an underpenetrated opportunity for vendors offering API-first distribution and CRM modules engineered for real-time, point-of-sale policy issuance. Platform providers that develop validated, high-availability embedded connectors can secure long-term integration contracts with digital-first insurers and travel, automotive, and retail partners seeking usage-based coverage.

How Can Third-Party Administrator Outsourcing Benefit Claims Platform Providers?

Rising claims and policy servicing outsourcing to third-party administrators creates an opportunity for vendors offering dedicated, multi-tenant claims management platforms. Early movers that secure configurable, carrier-agnostic administration capacity can differentiate with third-party administrators pursuing scalable technology infrastructure to support growing outsourced service portfolios. Vendors that pair claims automation with flexible billing integration stand to capture recurring, multi-year servicing contracts.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Policy Administration Systems 2025: $26.07 Billion | 2035: $72.40 Billion
Policy Admin
Claims Management Systems 2025: $20.15 Billion | 2035: $57.92 Billion
Claims Manag
Underwriting and Rating Systems 2025: $15.41 Billion | 2035: $43.44 Billion
Underwriting
Distribution and CRM Systems 2025: $13.04 Billion | 2035: $36.20 Billion
Distribution
Data and Analytics Systems 2025: $10.67 Billion | 2035: $47.06 Billion
Data and Ana
Billing and Payments Systems 2025: $9.48 Billion | 2035: $25.34 Billion
Billing and
Other Software 2025: $3.53 Billion | 2035: $7.24 Billion
Other Softwa
Services 2025: $20.15 Billion | 2035: $72.40 Billion
Services
Policy Administration Systems $26.07 Billion $72.40 Billion 10.6%
Claims Management Systems $20.15 Billion $57.92 Billion 11.0%
Underwriting and Rating Systems $15.41 Billion $43.44 Billion 10.8%
Distribution and CRM Systems $13.04 Billion $36.20 Billion 10.6%
Data and Analytics Systems $10.67 Billion $47.06 Billion 16.4%
Billing and Payments Systems $9.48 Billion $25.34 Billion 10.1%
Other Software $3.53 Billion $7.24 Billion 6.9%
Services $20.15 Billion $72.40 Billion 13.8%

Which Component Segment Dominates the Insurance Platform Market?

Policy Administration Systems led the market with USD 26.07 billion in 2025, supported by carriers' continued reliance on policy issuance and endorsement processing as the core transactional backbone of every platform deployment. We observed that Data and Analytics Systems is the fastest-growing component, expanding at a 16.4% CAGR from 2026 to 2035, as carriers increasingly deploy embedded analytics and generative AI models to support real-time risk scoring, pricing, and portfolio monitoring across underwriting operations.

2025 (USD Billion)
2035 (USD Billion)
Cloud/SaaS
On-Premise
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Cloud/SaaS $10.0 USD Billion $40.0 USD Billion 9.0%
On-Premise $17.1 USD Billion $51.1 USD Billion 23.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Deployment Mode.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Life and Ann
Property and
Health Insur
Travel and S
Other Insura
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Life and Annuity Insurance $10.0 USD Billion $40.0 USD Billion 18.0%
Property and Casualty Insurance $17.1 USD Billion $51.1 USD Billion 12.0%
Health Insurance $24.2 USD Billion $62.2 USD Billion 18.0%
Travel and Specialty Insurance $31.3 USD Billion $73.3 USD Billion 12.0%
Other Insurance Types $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Insurance Type.

Unlock Full Data

Which Insurance Type Segment Leads Insurance Platform Industry's Demand?

Property and Casualty remained the leading insurance type within the market, valued at USD 45.03 billion in 2025 on sustained core system modernization spending among auto, home, and commercial P&C carriers. Our findings suggest that Travel and Specialty is the fastest-growing insurance type, registering an 18.9% CAGR from 2026 to 2035, as embedded and parametric travel insurance programs increasingly require real-time, API-first policy issuance integrated into airline and travel booking platforms.

2025 (USD Billion)
2035 (USD Billion)
Large Enterp
Small and Me
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Large Enterprises $10.0 USD Billion $40.0 USD Billion 27.0%
Small and Medium Enterprises $17.1 USD Billion $51.1 USD Billion 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Enterprise Size.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Insurance Ca
Brokers and
Third-Party
Other End Us
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Insurance Carriers $10.0 USD Billion $40.0 USD Billion 26.0%
Brokers and Agents $17.1 USD Billion $51.1 USD Billion 16.0%
Third-Party Administrators $24.2 USD Billion $62.2 USD Billion 18.0%
Other End Users $31.3 USD Billion $73.3 USD Billion 8.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data

Which End User Segment Dominates the Insurance Platform ecosystem?

Insurance Carriers remained the dominant end user within the market, valued at USD 75.84 billion in 2025 as direct platform licensees responsible for core policy, claims, and billing operations. Our assessment indicates that Third-Party Administrators is the fastest-growing end user, expanding at a 16.0% CAGR from 2026 to 2035, as carriers increasingly outsource claims and policy servicing functions to specialized administrators seeking dedicated, configurable platform capacity.

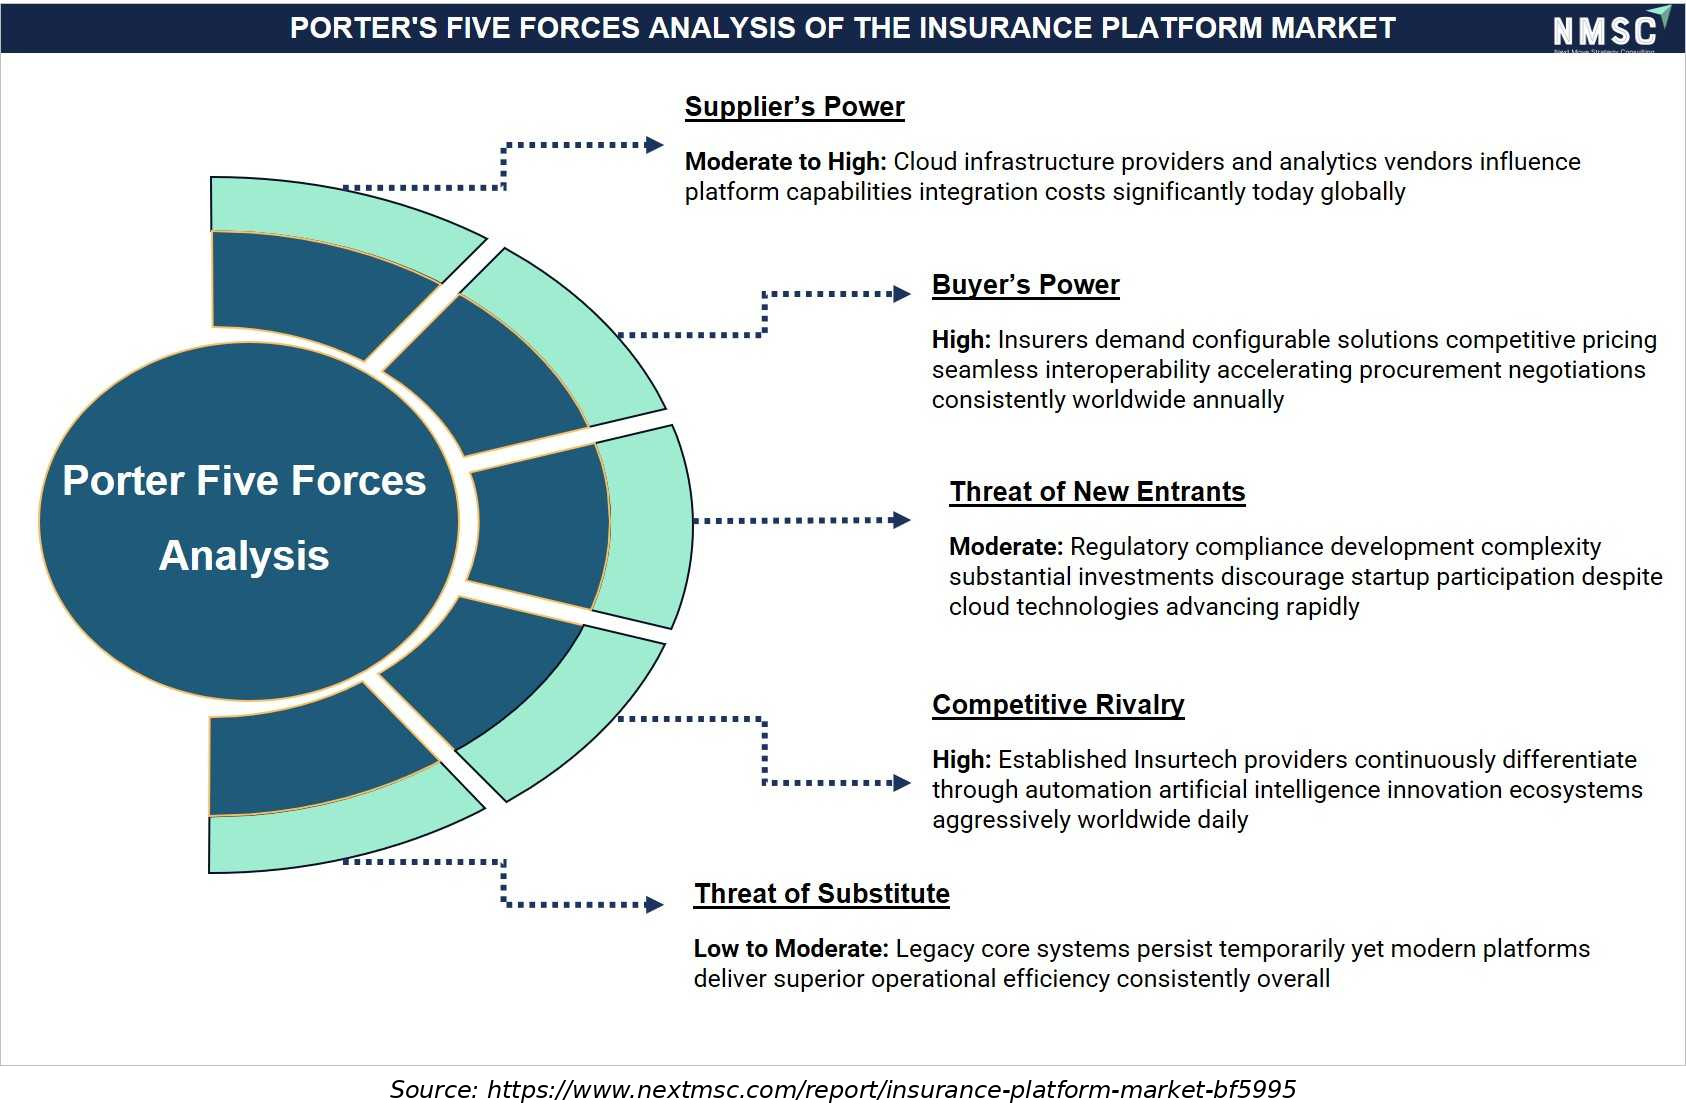
Porter's Five Forces Analysis of the Insurance Platform Market

Porter's Five Forces analysis highlights the competitive dynamics shaping the insurance platform market by evaluating supplier influence, buyer bargaining power, competitive rivalry, substitution risks, and barriers to new entrants. The assessment indicates that cloud technologies, digital innovation, regulatory requirements, and platform differentiation significantly influence market competition, profitability, and long-term growth opportunities.

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the insurance platform market over the 2026-2035 forecast period.

How Can Agentic Underwriting Unlock Value for Mid-Tier Carriers?

Agentic underwriting automation presents a whitespace opportunity for mid-tier carriers and managing general agents that lack the scale to justify full core system replacement. Vendors that commercialize core-system-agnostic AI underwriting layers stand to capture recurring subscription revenue as carriers deploy automation without disrupting existing policy administration infrastructure, particularly across commercial property and casualty insurance lines.

Where Does Embedded Insurance Distribution Create New Platform Demand?

Embedded insurance distribution represents an underpenetrated opportunity for vendors offering API-first distribution and CRM modules engineered for real-time, point-of-sale policy issuance. Platform providers that develop validated, high-availability embedded connectors can secure long-term integration contracts with digital-first insurers and travel, automotive, and retail partners seeking usage-based coverage.

How Can Third-Party Administrator Outsourcing Benefit Claims Platform Providers?

Rising claims and policy servicing outsourcing to third-party administrators creates an opportunity for vendors offering dedicated, multi-tenant claims management platforms. Early movers that secure configurable, carrier-agnostic administration capacity can differentiate with third-party administrators pursuing scalable technology infrastructure to support growing outsourced service portfolios. Vendors that pair claims automation with flexible billing integration stand to capture recurring, multi-year servicing contracts.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the insurance platform market features a moderately consolidated competitive landscape, with diversified enterprise technology groups competing alongside specialized core system vendors on configurability, cloud delivery, and AI integration depth.

Dimension Description
Market Structure Moderately consolidated; the top companies profiled in this report collectively account for a majority of global insurance platform market revenue, while several specialized mid-tier vendors serve carrier-specific policy administration and claims demand.
Innovation Focus Agentic AI underwriting and claims automation, cloud-native core modernization, and low-code configuration environments dominate current innovation pipelines across leading vendors.
M&A Activity Selective consolidation through capability acquisitions, exemplified by Guidewire Software's definitive agreement to acquire ProNavigator to expand its AI-driven customer engagement capabilities.

How Do Companies Compete in the Insurance Platform Market?

Companies compete primarily on cloud delivery maturity, configurability, and AI integration depth across the industry. Global technology groups such as Microsoft Corporation and Oracle Corporation leverage broad enterprise cloud and data platforms to serve multinational carriers, while specialized vendors such as Sapiens International Corporation N.V. and Duck Creek Technologies, Inc. compete on insurance-specific domain depth and rapid, low-code product configuration for mid-tier carriers.

Which Competitive Archetypes Dominate the Insurance Platform Market?

Two archetypes dominate the market: diversified enterprise technology conglomerates offering broad cloud, data, and CRM infrastructure adapted for insurance, and specialized core system vendors focused exclusively on carrier workflows. SAP SE and Salesforce, Inc. exemplify the diversified archetype through integrated enterprise software portfolios, while Guidewire Software, Inc. and Sapiens International Corporation N.V. exemplify the specialized archetype through purpose-built policy, billing, and claims architecture.

How Are Companies Differentiating Through Innovation in Insurance Platforms?

Innovation and differentiation strategy increasingly center on agentic AI and governed automation validated for regulatory auditability. Duck Creek Technologies' Agentic AI Platform and Guidewire Software's Olos pricing release both target faster, AI-supported underwriting and claims decisioning. Our analysis shows that vendors unable to demonstrate credible AI governance and explainability risk exclusion from carrier request-for-proposal shortlists across North America and Europe.

What M&A and Expansion Activity Is Shaping the Insurance Platform Market?

Mergers, acquisitions, and geographic expansion continue to consolidate core system and AI capabilities within the industry. Guidewire Software's definitive agreement to acquire ProNavigator broadened its AI-driven customer engagement capacity, while Sapiens International's continued European contract wins illustrate how specialized vendors pursue geographic expansion and multi-line capability across life, health, and P&C insurance markets.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping platform innovation, cloud delivery, and AI integration strategy within the global insurance platform market.

Microsoft Corporation Oracle Corporation SAP SE International Business Machines Corporation Salesforce, Inc. Accenture plc Alphabet Inc. Adobe Inc. Guidewire Software, Inc. DXC Technology Company Sapiens International Corporation N.V. Pegasystems Inc. Duck Creek Technologies LLC Mphasis Limited Applied Systems, Inc. Majesco EIS Group, Inc. Insurity, Inc. Appian Corporation OneShield, Inc.

Latest Developments

We found that recent product launches and contract wins within the insurance platform market are concentrated on agentic AI capability and cloud-native core modernization, reflecting the industry's broader digital transformation transition.

Date Event
Jul 2026 Sapiens launched Arrow, an embedded expert decision intelligence solution to enhance automated insurance decision-making.

Expert Insights

Hardeep Gulati

Hardeep Gulati

Chief Executive Officer | Duck Creek Technologies

"“Every insurer wants the upside of AI, including faster underwriting, smarter claims and better operations. The difference is whether they can deploy AI with the governance their regulators, customers and boards demand.”"

Analyst Interpretation

The statement highlights that artificial intelligence has become a strategic priority for insurers seeking to modernize underwriting, claims processing, and operational workflows. However, realizing these benefits depends on deploying AI within secure, compliant, and well-governed insurance platforms. As insurers face increasing regulatory scrutiny and customer expectations around transparency, demand is growing for cloud-native insurance platforms that integrate AI with robust governance, security, and compliance capabilities, accelerating investment in next-generation policy administration and digital insurance ecosystems.

Investment Opportunities

What Capital Inflows Are Targeting the Insurance Platform Market?

Capital inflows into the insurance platform market are increasingly directed toward agentic AI development and cloud infrastructure capacity supporting real-time underwriting decisioning. Private equity-backed vendors, including Vista Equity Partners' portfolio holding Duck Creek Technologies, continue to fund platform innovation, as seen in its April 2026 Agentic AI Platform launch. We observed that investors favor vendors demonstrating validated AI governance credentials, viewing regulatory alignment as a proxy for long-term carrier contract retention.

How Is Infrastructure Investment Supporting Insurance Platform Deployment?

Infrastructure investment is expanding cloud computing capacity across North America, Europe, and Asia-Pacific to serve rising core system modernization demand. Our findings suggest that vendors are investing in multi-country deployment capability, supporting cross-border carrier groups that require unified policy, billing, and claims data foundations across regulatory jurisdictions with differing reporting requirements.

What ESG Considerations Are Shaping Insurance Platform Investment Decisions?

Environmental, social, and governance considerations are increasingly relevant to investment decisions across the industry, with AI explainability and data governance cited as key criteria under frameworks such as the NAIC's AI Model Bulletin. We found that investors increasingly favor vendors with demonstrated algorithmic accountability and cybersecurity governance, treating certification as a proxy indicator alongside environmental performance in vendor selection.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support procurement and product-portfolio decisions across the insurance platform industry. Our analysis shows that detailed component, insurance type, and end-user breakdowns help program managers align specifications with regulatory and AI governance requirements while identifying underserved segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the insurance platform market supply chain. We observed that the report's regional and segment-level growth differentials help identify which vendors are best positioned to capture above-market growth in data and analytics and third-party administrator categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including agentic AI governance, low-code configuration, and embedded distribution connectors, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around AI explainability and cloud-native deployment mechanisms increasingly required by carrier request-for-proposal processes.

Key Market Segments Evaluated

By Component

  • Software 
    • Policy Administration Systems
    • Claims Management Systems
    • Underwriting and Rating Systems
    • Billing and Payments Systems
    • Distribution and CRM Systems
    • Data and Analytics Systems
    • Other Software
  • Services 
    • Implementation and Integration Services
    • Consulting and Advisory Services
    • Support and Maintenance Services
    • Managed Services

By Deployment Mode

  • Cloud/SaaS
  • On-Premise

By Insurance Type

  • Life and Annuity Insurance
  • Property and Casualty Insurance
  • Health Insurance
  • Travel and Specialty Insurance
  • Other Insurance Types

By Enterprise Size

  • Large Enterprises
  • Small and Medium Enterprises

By End User

  • Insurance Carriers
  • Brokers and Agents
  • Third-Party Administrators
  • Other End Users

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook for the market remains positive, with global revenue projected to more than triple from USD 118.50 billion in 2025 to USD 362.00 billion by 2035 at a 11.8% CAGR. We observed that sustained core system modernization, agentic AI adoption, and embedded distribution expansion will continue underpinning demand across carrier, broker, and third-party administrator segments through the forecast period.

What Strategic Positioning Should Insurance Platform Vendors Pursue?

Vendors should prioritize cloud-native, API-first architectures while pursuing governed AI capability to secure long-term carrier contracts. Our assessment indicates that vendors investing early in agentic underwriting automation and low-code configuration will be best positioned to capture premium pricing within the insurance platform market. Vendors should also deepen partnerships with hyperscale cloud providers and specialty distribution platforms to broaden addressable reach across mid-tier carriers and managing general agents seeking rapid, configurable deployment options.

How Attractive Is the Insurance Platform Market for New Investment?

The insurance platform industry presents an attractive investment case, supported by a USD 229.10 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and travel and specialty categories. We found that investment attractiveness is highest for vendors combining AI governance credentials with scaled cloud delivery capacity, positioning them to serve both enterprise carriers and mid-tier segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor core system migration cost overruns, tightening AI governance requirements, and competitive pressure from point-solution AI vendors as key risks to the insurance platform market. Our analysis shows that vendors unable to adapt to explainability and audit-trail specifications risk losing contract eligibility to competitors with certified, governed AI platforms, particularly within North America's increasingly regulated procurement environment.

What Are the Key Growth Pathways for the Insurance Platform Market?

Key growth pathways include expanding agentic AI underwriting portfolios, scaling embedded distribution connectors, and deepening penetration into third-party administrator and specialty insurance categories. NMSC's analysis indicates that vendors pursuing these pathways while maintaining cost competitiveness in core policy administration categories will be best positioned to capture the insurance platform market's projected growth through 2035.

FAQs

About the Author

Mihul Sharma

Mihul Sharma

Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Diana Trejo

DIANA TREJO

Assistant Manager

Sumitomo Corporation de Mexico, S.A. de C.V.

Recently, we purchased a report on the Mexico Data Center Market from Next Move Strategy Consulting. The service has been excellent, with support that is always timely and thoroughly professional. The information provided is interesting, highly useful, and delivered with clarity. I would highly recommend NextMSC for anyone seeking insightful and dependable analysis.

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖