Japan Fabric Care Market Size, By Product Type {Fabric Detergents (General Purpose, Baby Laundry Detergent, and Delicate Laundry Detergent), Fabric Softeners/Conditioners, and Others}, By Form (Liquid, Powder, Unit-Dose, Sheet & Wipe, and Spray), By Nature (Conventional and Eco-friendly / Organic), By Price Tier (Value, Mid-range, and Premium), By Distribution Channel (Online and Offline), and By End-User (Residential, Commercial, and Others) – Analysis & Forecast, 2025–2035
Industry: Retail and Consumer | Latest Edition: August 21, 2026 | No of Pages: 152 | No. of Tables: 49 | No. of Figures: 43 | Format: PDF | Report Code : RC4577
Japan Fabric Care Market size & forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 4.75 Billion |
|
Market Size in 2026 |
USD 5.37 Billion |
|
Revenue Forecast in 2035 |
USD 7.81 Billion |
|
Growth Rate |
CAGR of 4.26% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Revenue (USD Billion) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
Industry outlook
The Japan Fabric Care Market was valued at USD 4.75 billion in 2025 and is estimated to reach USD 5.37 billion in 2026, supported by high household penetration and a mature consumer base with strong brand loyalty toward established detergent and softener lines. The market is projected to advance to USD 7.81 billion by 2035, registering a CAGR of 4.26% from 2026 to 2035. Growth is driven by rising adoption of concentrated unit-dose formats, expansion of quick-commerce grocery delivery, and increasing consumer preference for compact, eco-conscious packaging across residential and commercial end-use segments.
Ecosystem Analysis of the Japan Fabric Care Market:
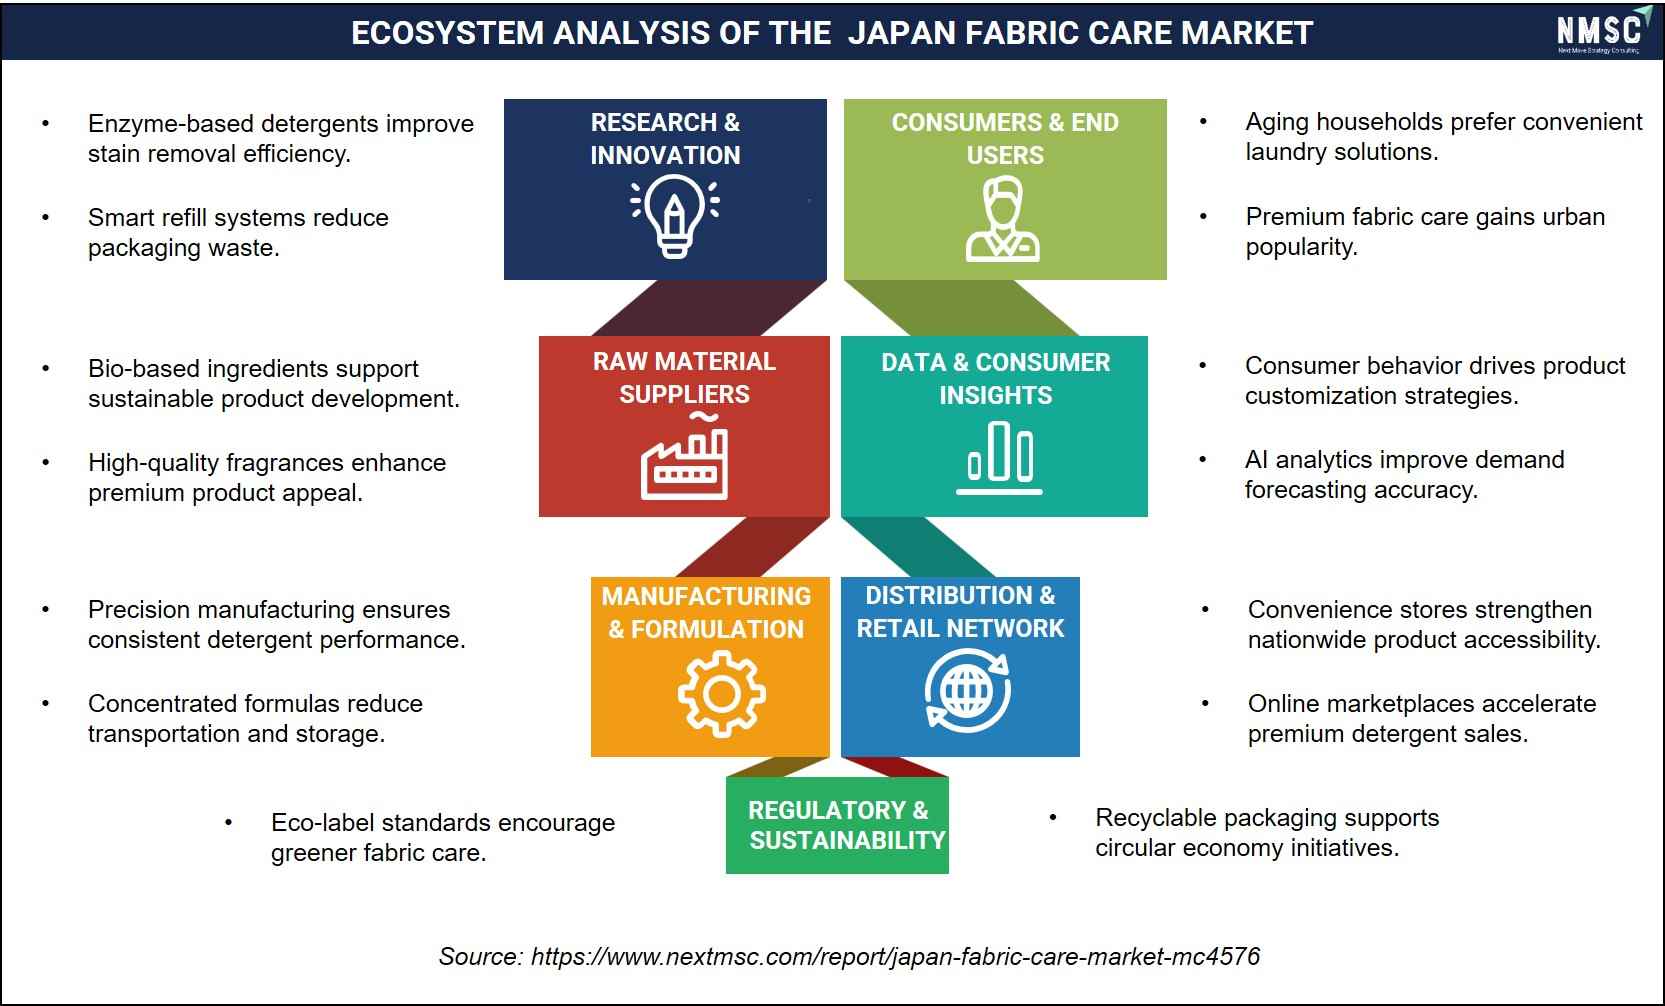
The above ecosystem analysis maps the key operational pillars, such as research and innovation, raw material suppliers, manufacturing and formulation, regulatory and sustainability, distribution and retail network, data and consumer insights, and consumers and end users, shaping the Japan fabric care industry. From our analysis, we observed that research drives innovation in convenient laundry solutions, while raw material suppliers ensure quality inputs. Manufacturing focuses on efficient formulation, whereas regulatory frameworks enforce sustainability standards. Distribution through retail networks expands market reach, while data insights guide strategic decisions. Finally, aging households prefer convenient solutions, and premium fabric care gains urban popularity.
What Are the Key Market Drivers, Restraints, and Opportunities Shaping the Japan Fabric Care Market Through 2035?
Growth Catalyst & Risk Assessment Matrix
|
Driver / Restraint / Opportunity |
(+/–) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Demand for compact formulations driving concentrated product innovation |
+1.3% |
Nationwide; strongest in Tokyo, Osaka, Yokohama |
Long term (4–8 years) |
|
Quick commerce expansion accelerating fabric care replenishment cycles |
+0.9% |
Tokyo, Osaka, Nagoya, Fukuoka |
Medium term (2–5 years) |
|
Growing adoption of unit-dose pods and sachets |
+1.1% |
Nationwide, particularly urban households |
Medium to long term (3–7 |
|
Demographic stagnation limiting organic volume growth |
−1.0% |
Nationwide; most evident in rural regions |
Long term (5–10 years) |
|
Refill stations and subscription commerce expanding recurring revenue opportunities |
+1.2% |
Tokyo, Osaka and other major metropolitan areas |
Medium to long term (3–7 years) |
The Japan Fabric Care Industry is shaped by a combination of structural demand drivers, demographic restraints, and emerging commercial opportunities that together determine category growth through 2035. Household penetration of fabric care products is effectively saturated in Japan, shifting competitive focus toward format innovation, compact packaging, and channel expansion rather than pure category growth. These dynamics are explored in detail across the drivers, inhibitor, and opportunity discussion below.
Growth Driver:
How is compact formulation demand reshaping product design?
Japanese consumers are increasingly prioritising space-efficient, concentrated fabric care formulations suited to smaller urban households, prompting manufacturers to reformulate flagship detergent and softener lines around higher-concentration surfactants and reduced packaging volume. This shift is most pronounced in the premium price tier, where willingness to pay for compact, high-performance formats is highest. Kao Corporation and Lion Corporation have both expanded concentrated product lines in Japan, reinforcing this driver's influence on category-wide innovation spending through the forecast period.
How is quick commerce accelerating category sales?
The rapid expansion of quick commerce grocery delivery across Tokyo, Osaka, and other major Japanese urban centres is shortening replenishment cycles for fabric care products, particularly liquid detergents and unit-dose pods suited to compact delivery formats. This channel is capturing incremental volume from traditional supermarket trips, particularly among younger, time-constrained urban households. Brands optimising packaging for quick commerce fulfilment are gaining shelf visibility disproportionate to their offline market share.
How is unit-dose format adoption changing purchase behaviour?
Pods and sachets are gaining share from traditional liquid and powder formats due to dosing convenience and reduced spillage, appealing strongly to value and mid-range consumers seeking simplicity. Manufacturers are expanding unit-dose manufacturing capacity in response, with format innovation increasingly serving as a key competitive lever. This shift is also reducing packaging waste per wash cycle, aligning with broader sustainability expectations among Japanese retailers and consumers alike.
Growth Inhibitor:
How does demographic stagnation constrain market growth?
Japan's slow population growth and aging demographic profile limit organic volume expansion for fabric care products, constraining the category to value growth through premiumisation rather than unit growth through new household formation. This constraint is particularly acute outside major urban centres, where population decline is most pronounced. Sustained demographic pressure risks capping category-wide revenue growth below levels seen in faster-growing Asia-Pacific markets through the forecast period.
Growth Opportunity:
How does refill and subscription commerce create new revenue streams?
Refill stations and subscription-based replenishment models present a meaningful opportunity for premium fabric care brands to build recurring revenue while reinforcing compact-packaging and sustainability positioning. Early entrants in brand e-commerce refill programmes report strong repeat-purchase rates among environmentally conscious, convenience-seeking consumers. Scaling these models across mid-range price tiers could meaningfully expand premium category penetration beyond its current urban, higher-income consumer base.
How Is the Japan Fabric Care Market Segmented in This Report, and What Are the Key Insights from the Segmentation Analysis?
By Product Type Insight
How Does Product Type Segmentation Reflect Consumer Laundry Needs?
Based on product type, the Japan Fabric Care Market is segmented into fabric detergents, general-purpose, baby laundry detergent, and delicate laundry detergent, fabric softeners/conditioners, stain removers/bleach, sanitizer, and other products.
The market comprises a diverse portfolio of fabric care solutions designed to address routine laundry, specialized garment care, and evolving hygiene requirements. According to our analysis, we found that fabric detergents support general purpose, baby laundry, and delicate laundry applications across varying household needs, while fabric softeners and conditioners enhance fabric softness and fragrance. Stain removers, bleach, and sanitizers provide targeted cleaning and hygiene benefits, whereas other products cater to specialized fabric care applications, contributing to a comprehensive product landscape.
By Distribution Channel Insight
How Is Distribution Channel Segmentation Reshaping Consumer Purchase Behavior?
Based on distribution channel, the Japan Fabric Care Market is segmented into online and offline.
The market reflects a well-integrated retail ecosystem where physical stores and digital platforms collectively support evolving consumer purchasing preferences. In our observation, offline channels, including supermarkets, hypermarkets, and department stores, continue to provide convenient access to everyday fabric care products through established retail networks. Meanwhile, online channels are expanding steadily, with marketplaces offering wider product choices, brand e-commerce strengthening direct consumer engagement, and quick commerce enhancing shopping convenience through faster delivery and seamless repeat purchases.
Consumer Behavior Analysis of the Japan Fabric Care Market:
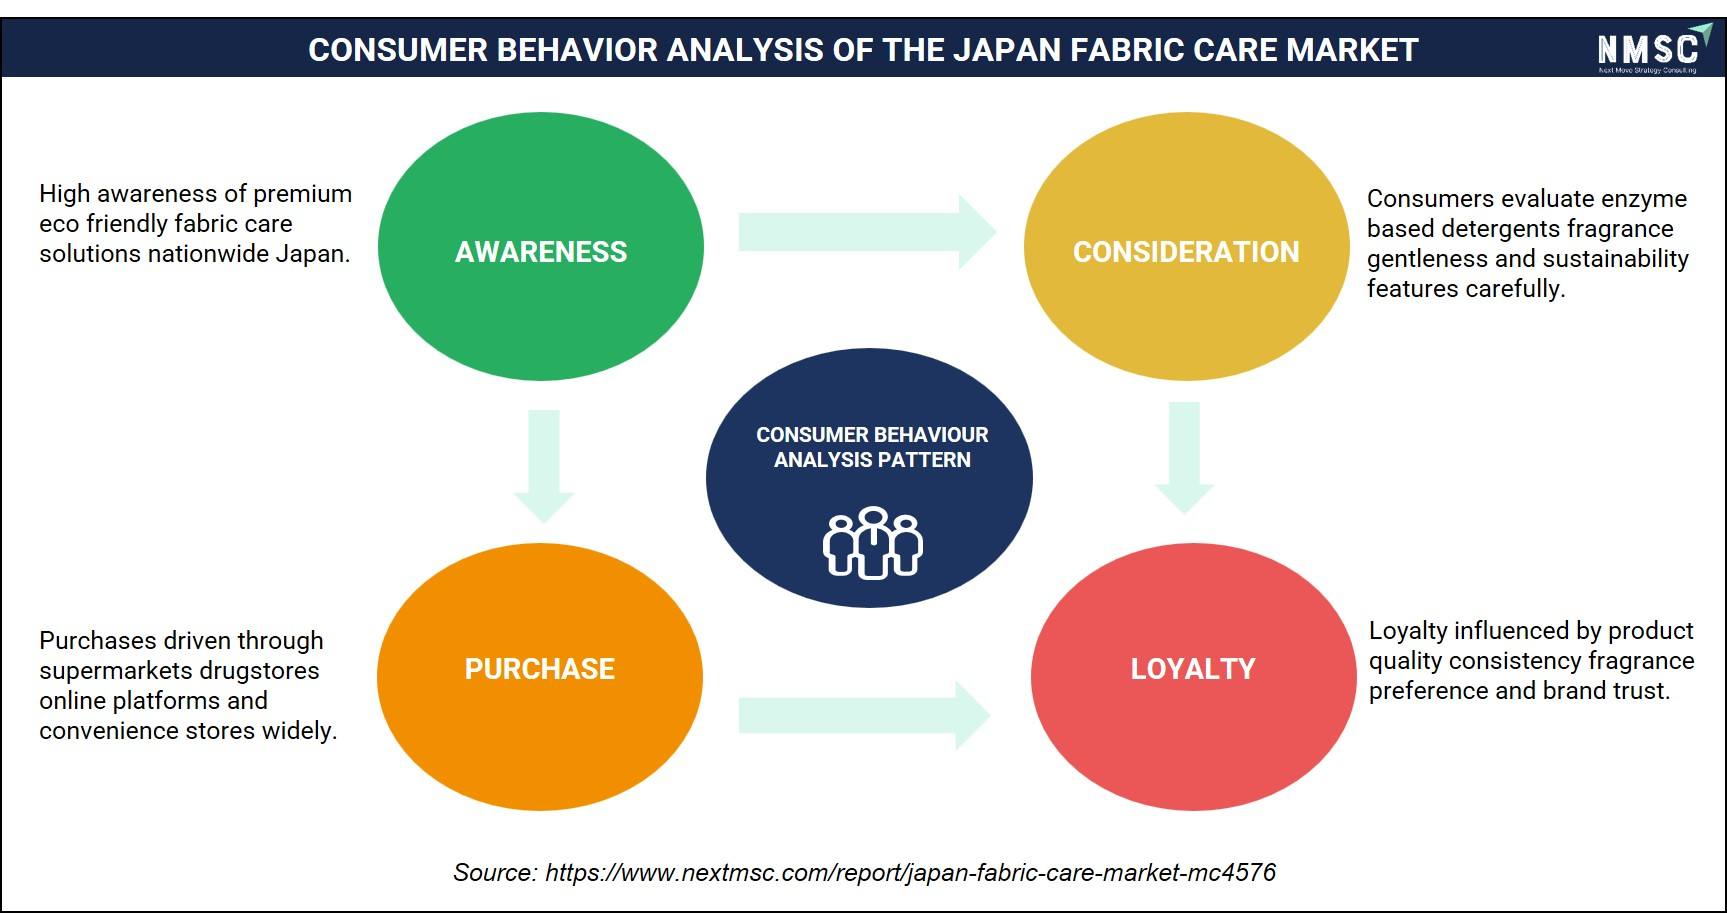
The below consumer behavior analysis maps the key decision-making stages, such as awareness, consideration, purchase, and loyalty, shaping the Japan fabric care industry. From our analysis, we observed that awareness reflects high recognition of premium eco-friendly fabric care solutions nationwide, while consideration involves evaluation of product quality, fragrance, and fabric protection benefits. During purchase, consumers shop through supermarkets, drugstores, online platforms, and convenience stores, whereas brand loyalty is ultimately driven by product quality consistency, fragrance preference, and brand trust.
Key segments
By Product Type
-
Fabric Detergents
-
General Purpose
-
Baby Laundry Detergent
-
Delicate Laundry Detergent
-
-
Fabric Softeners/Conditioners
-
Stain Removers/Bleach
-
Sanitizer
-
Other Products
By Form
-
Liquid
-
Powder
-
Unit-Dose
-
Pods
-
Sachets
-
-
Sheet & Wipe
-
Spray
By Nature
-
Conventional
-
Eco-friendly / Organic
By Price Tier
-
Value
-
Mid-range
-
Premium
By Distribution Channel
-
Online
-
Marketplaces
-
Brand E-com
-
Quick Commerce
-
-
Offline
-
Supermarkets
-
Hypermarkets
-
Department Stores
-
By End-User
-
Residential
-
Commercial
-
Others
Competitive landscape overview
The Japan Fabric Care Market is moderately consolidated, with a small number of domestic and multinational manufacturers accounting for the majority of category revenue alongside a long tail of specialty and regional producers. Competitive intensity centres on compact formulation innovation, expansion into unit-dose and refill formats, and deeper penetration of online and quick commerce channels. Brand loyalty remains exceptionally high in this category, making innovation and long-standing retail relationships the primary levers for share gain rather than price competition alone.
Strategic Developments:
-
February 2025 – Lion Corporation announced the launch of Acron Yasashisa Premium delicate laundry detergent, scheduled for nationwide release. The new zero-rinse formulation minimizes wrinkles, stretching, shrinking, fading, and pilling while reducing water, energy, and CO₂ emissions, strengthening Lion's premium and sustainable fabric care portfolio in Japan.
Key players of the Japan Fabric Care Market:
-
Reckitt Benckiser Japan Ltd.
-
Kao Corporation
-
Johnson K.K.
-
Lion Corporation
-
Nice Group Co., Ltd.
-
Patanjali Ayurved Limited
-
Nihon Amway LLC
-
Croda Japan K.K.
-
NS FaFa Japan Co., Ltd.
-
Saraya Co., Ltd.
-
Arkema K.K.
-
Miyoshi Soap Co., Ltd.
-
Daiichi Sekken Co., Ltd.
Leading manufacturers including Kao Corporation, Lion Corporation, P&G Japan GK, and Unilever Japan K.K. continue to anchor category innovation through compact-formulation development and unit-dose expansion. Reckitt Benckiser Japan Ltd. and Johnson K.K. compete on targeted stain-treatment and specialty softener positioning, while Nice Group Co., Ltd. and Saraya Co., Ltd. maintain strength in adjacent commercial hygiene applications. Patanjali Ayurved Limited, Nihon Amway LLC, Croda Japan K.K., NS FaFa Japan Co., Ltd., Arkema K.K., and others round out a competitive set spanning direct-selling, ingredient-supply, and traditional soap-making positioning across the category.
Key benefits for stakeholders
This report equips manufacturers, retailers, and investors with a structured view of demand shifts across product type, format, and distribution channel within the Japan Fabric Care Market. Stakeholders evaluating innovation or capacity investment can use the segmentation and driver analysis to prioritise compact, unit-dose formulation development ahead of category-wide premiumisation trends identified in this report.
Retail and e-commerce stakeholders can use the distribution channel findings to guide assortment and fulfilment strategy as quick commerce and brand e-com channels expand faster than the category average. Competitive landscape findings further support benchmarking against the fifteen key players profiled, helping stakeholders identify white space in specialty, compact-format, and direct-to-consumer positioning within a moderately consolidated market structure.
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter's Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The Japan Fabric Care Market is set for steady expansion from USD 4.75 billion in 2025 to USD 7.81 billion by 2035, growing at a CAGR of 4.26%. Growth will be led by compact and concentrated formulation innovation, unit-dose format adoption, and accelerating online and quick commerce distribution, tempered by demographic stagnation limiting volume expansion. Competitive dynamics remain anchored by established domestic and multinational manufacturers, though refill and subscription commerce present a durable opportunity for premium-tier differentiation through the forecast period.
About the Author
 Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

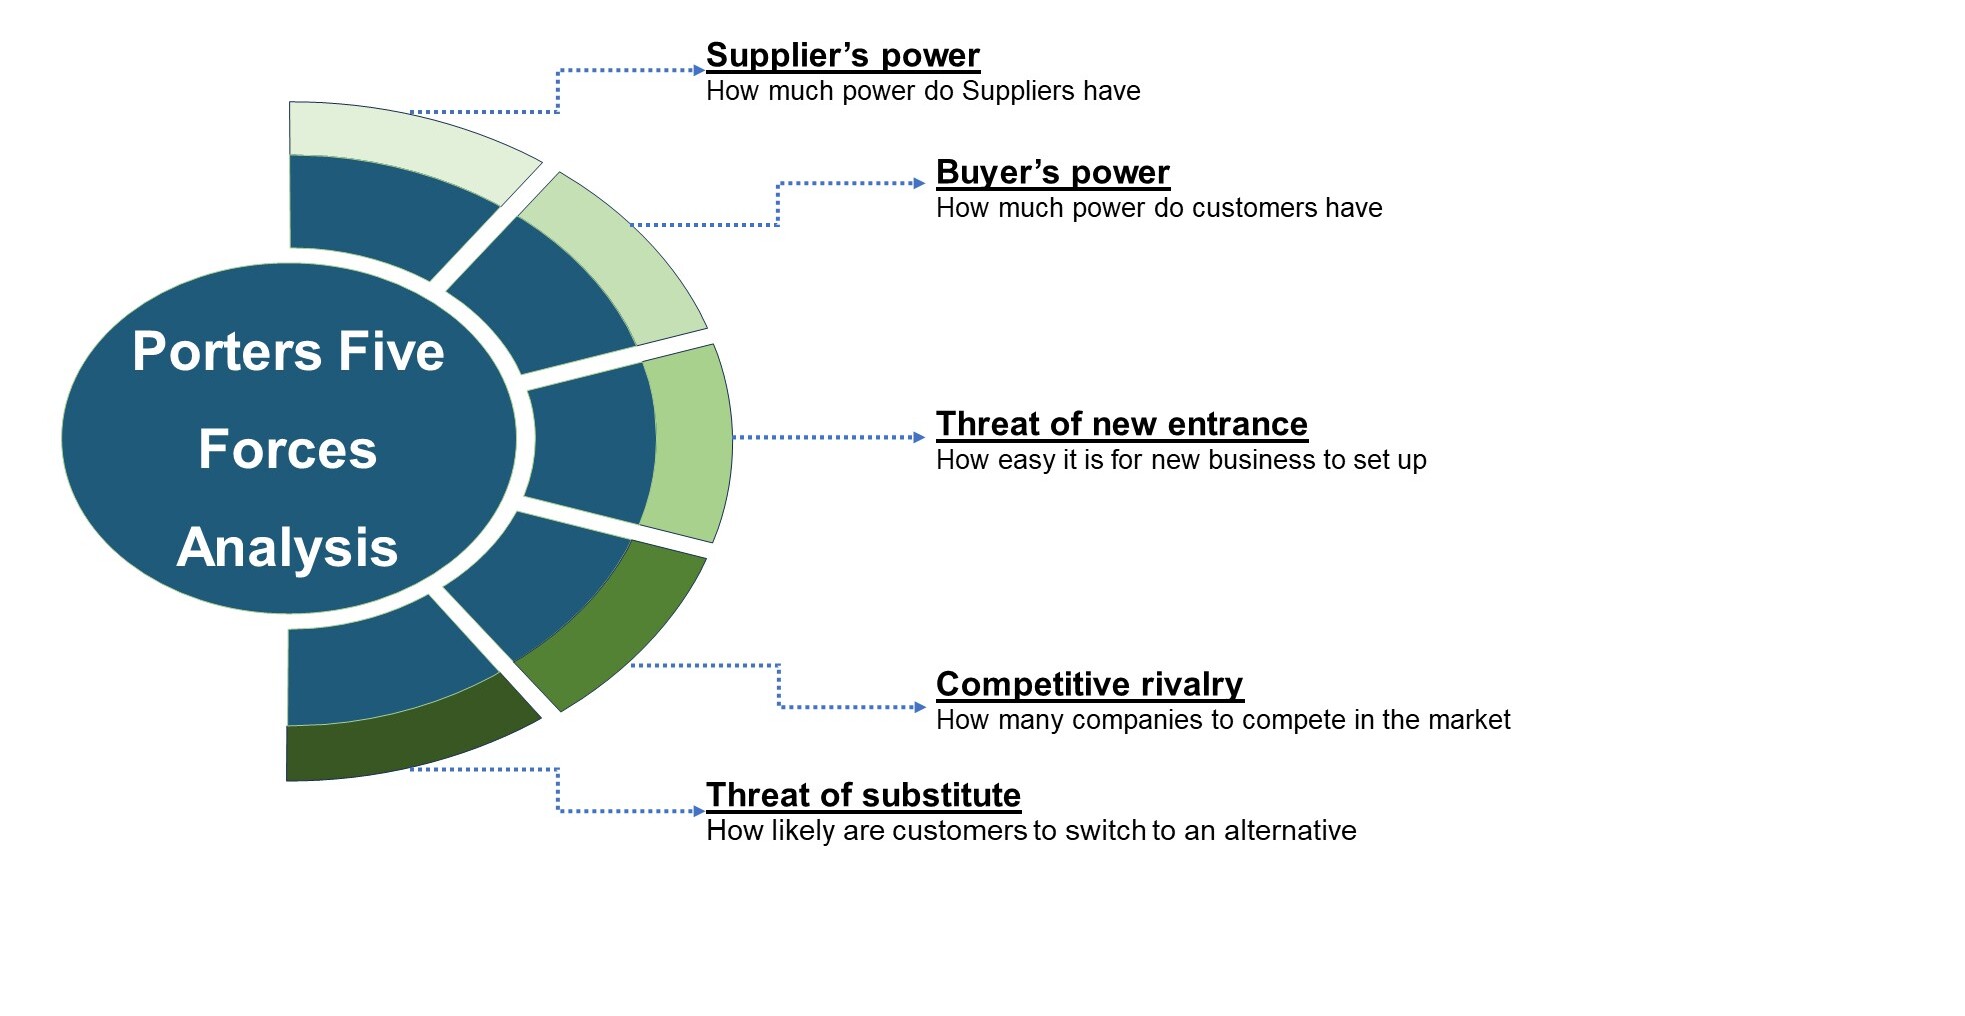
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.



 Speak to Our Analyst