Latin America Healthcare Cybersecurity Market By Component (Software, Hardware, and Services), By Deployment Model (Cloud, On-Premises, and Hybrid), By Organization Size (Small, Medium, and Large), By Commercial Model (Subscription, Perpetual License, Consumption Based, Appliance Sale, Project-Based, Managed Service Contract, and Support Contract), By Customer Type, By Buyer Type, and By Sales Channel – Opportunity Analysis & Forecast, 2025–2035
Industry: Healthcare | Latest Edition: August 13, 2026 | No of Pages: 731 | No. of Tables: 345 | No. of Figures: 337 | Format: PDF | Report Code: HC4119
What Is the Latin America Healthcare Cybersecurity Market Size?
The Latin America healthcare cybersecurity market size was valued at USD 2.86 Billion in 2025 and is estimated at USD 3.66 Billion in 2026, forecast to reach USD 9.12 Billion by 2035, expanding at a 10.67% CAGR between 2026 and 2035. Software dominates the market by component, driven by strong health system demand for identity, endpoint, and network security platforms.
We observed that market growth is supported by the region's disproportionately high exposure to ransomware, expanding digital health infrastructure across Brazil and Mexico, and tightening data protection enforcement under Brazil's LGPD through 2035.
|
Key Takeaways |
|
By Component: Software is the dominant segment, while Services is the fastest-growing segment. |
|
By Deployment Model: On-Premises is the dominant segment, while Cloud is the fastest-growing segment. |
|
By Organization Size: Large is the dominant segment, while Small is the fastest-growing segment. |
|
By Commercial Model: Subscription is the dominant segment, while Consumption Based is the fastest-growing segment. |
|
By Customer Type: Healthcare Providers is the dominant segment, while Medical Technology is the fastest-growing segment. |
|
By Buyer Type: Chief Information Security Officer is the dominant segment, while Clinical Engineering is the fastest-growing segment. |
|
By Sales Channel: Direct Sales is the dominant segment, while Managed Security Service Providers is the fastest-growing segment. |
Market Opportunity: The Latin America healthcare cybersecurity market is expected to create an absolute dollar opportunity of USD 5 billion between 2026 and 2035, presenting significant investment potential across identity security, cloud security, and managed detection and response segments.
According to NMSC's analysis, healthcare providers across Brazil and Mexico are increasingly prioritizing ransomware-focused security operations investment as the region continues to record the highest proportion of ransomware-affected organizations of any world region.
What Does the Latin America Healthcare Cybersecurity Market Encompass?
The Latin America healthcare cybersecurity market encompasses software, hardware, and services deployed to protect hospital networks, electronic health records, connected medical devices, and healthcare payer systems from unauthorized access, data theft, and operational disruption. Our assessment indicates that the market spans identity security, endpoint and network protection, cloud security, application security, data security, email security, security operations, exposure management, and dedicated operational technology security for clinical devices. Solutions are delivered through direct sales, value-added resellers, systems integrators, and managed security service providers to healthcare providers, payers, life sciences firms, medical technology companies, and public health agencies across the region.
Brazil's Lei Geral de Proteção de Dados, enforced by the Autoridade Nacional de Proteção de Dados, and the Agência Nacional de Vigilância Sanitária's cybersecurity guidance for medical devices govern data protection and device security obligations for healthcare organizations across the region. We observed that the market has evolved from perimeter-focused network defense into an integrated discipline spanning cloud security, identity governance, and medical device protection as health systems accelerate digital health adoption. NMSC's analysis indicates that growing deployment of connected clinical Internet of Things devices, telehealth platforms, and artificial intelligence-enabled diagnostic tools continues to expand the attack surface, reinforcing sustained investment in threat detection, incident response, and security operations capabilities across Latin America.
|
Parameter |
Details |
|
Market Size in 2025 |
USD 2.86 Billion |
|
Market Size in 2026 |
USD 3.66 Billion |
|
Revenue Forecast in 2035 |
USD 9.12 Billion |
|
Growth Rate |
CAGR of 10.67% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
USD Billion |
|
Companies Profiled |
15 |
|
Market Share |
Available for Top 10 Companies |
Key Emerging Trends
Based on research conducted by NMSC, we found that four structural trends are reshaping threat detection, security architecture, and vendor selection across the Latin America healthcare cybersecurity market.
How Is Artificial Intelligence Transforming Threat Detection Across Latin American Health Systems?
Artificial intelligence-enabled threat detection is becoming central to healthcare security operations as hospitals face growing volumes of alerts across clinical and administrative networks. We observed that security teams are deploying AI-driven analytics to correlate signals across identity, endpoint, and network telemetry, shortening investigation timelines and reducing analyst fatigue. Vendors including CrowdStrike and Microsoft have introduced agentic AI-based platforms designed to triage signals autonomously while preserving human oversight for high-severity incidents. This shift is strengthening detection accuracy across resource-constrained hospital security teams throughout the region.
Why Is Medical Device and Clinical IoT Security Becoming a Board-Level Priority Across the Region?
Connected medical devices, including infusion pumps, imaging systems, and remote patient monitors, are expanding the healthcare attack surface across Latin American hospitals and health systems. Brazil's Agência Nacional de Vigilância Sanitária published cybersecurity guidance for medical device manufacturers, healthcare services, and users to support proactive risk management across the device lifecycle. Our findings suggest that healthcare providers are increasingly adopting dedicated operational technology security solutions to inventory, segment, and monitor clinical assets separately from administrative information technology networks. Boards and clinical engineering leaders are now treating device security as a direct patient-safety issue.
How Is Zero Trust Architecture Reshaping Healthcare Network Security in Latin America?
Zero trust security models are gaining traction as Latin American healthcare organizations move away from perimeter-based defenses toward continuous identity verification and least-privilege access. We observed that hospitals and healthcare payers are prioritizing multi-factor authentication, privileged access management, and network segmentation to limit lateral movement following credential compromise. This approach is particularly relevant for integrated delivery networks operating hybrid infrastructure that spans legacy on-premises systems and cloud-hosted electronic health record platforms. Vendors offering identity governance and network access control solutions are benefiting from this architectural shift regionally.
What Role Is Ransomware Resilience Playing in Latin America Healthcare Cybersecurity Investment?
Ransomware resilience has become a defining investment priority as Latin America recorded the highest proportion of ransomware-affected organizations of any world region in 2025, according to Kaspersky threat research. Our analysis indicates that healthcare organizations are expanding investment in security information and event management, automation and response, and immutable backup strategies to reduce recovery time following an incident. Attackers are increasingly favoring data theft and extortion over encryption alone, reinforcing sustained demand for managed detection and response services among hospitals and clinics. This dynamic is accelerating adoption of security operations and incident response capabilities across health systems regionally.
Which Country is Dominating the Latin America Healthcare Cybersecurity Market?
Our comprehensive market assessment indicates that Brazil holds the dominant share of the Latin America healthcare cybersecurity market, accounting for the largest regional market revenue. The country's leadership is driven by its extensive healthcare infrastructure, increasing adoption of electronic health records (EHRs), and growing investments in digital health technologies. Rising cyber threats targeting healthcare organizations, expanding implementation of cloud-based healthcare platforms, and strengthening data protection initiatives further reinforce Brazil's leading position in the market.
Which Country is Set to Witness the Fastest Growth?
Based on our assessment of healthcare digitalization, cybersecurity investments, and market growth projections, Brazil is also expected to witness the fastest growth in the Latin America healthcare cybersecurity market during the forecast period. The country's accelerating healthcare IT modernization, increasing deployment of AI-powered cybersecurity solutions, expanding adoption of telehealth services, and growing emphasis on protecting sensitive patient data are driving market expansion. Furthermore, rising investments in cyber resilience, regulatory compliance, and secure digital healthcare infrastructure are expected to support sustained market growth throughout the forecast period.
PESTEL Analysis of the Latin America Healthcare Cybersecurity Market
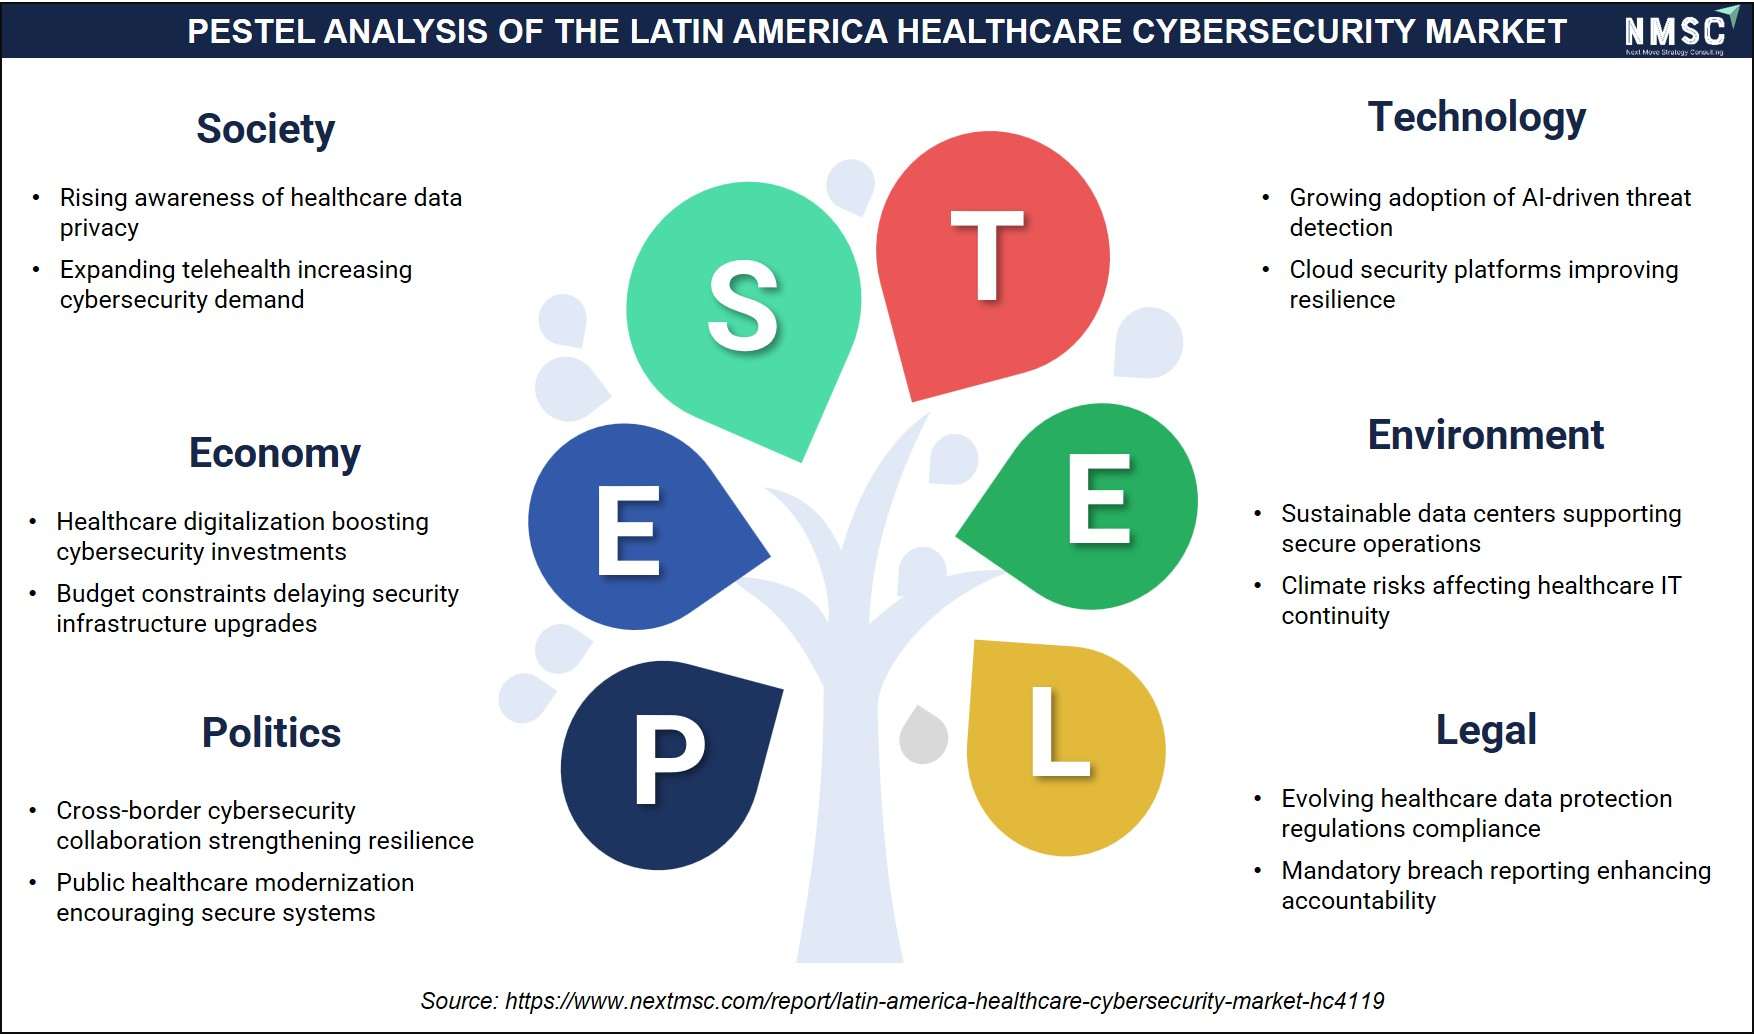
This infographic presents a PESTEL analysis of the Latin America healthcare cybersecurity market, highlighting the political, economic, social, technological, environmental, and legal factors influencing market growth. It emphasizes the impact of healthcare digitalization, evolving cybersecurity regulations, increasing cyber threats, technological advancements, and growing investments in secure healthcare infrastructure, all of which are driving cybersecurity adoption and strengthening cyber resilience across the region.
Growth Drivers and Restraints
Growth Catalyst and Risk Assessment Matrix
|
Factors |
Type |
(+/−) % Impact on CAGR |
Geographic Relevance |
Impact Timeline |
|
Escalating ransomware attacks positioning the region as the most affected globally driving urgent cybersecurity budget increases |
Driver |
+2.6% |
Latin America (nationwide; concentrated in Brazil, Mexico, and Argentina) |
2026–2030 |
|
Brazil's LGPD security incident notification requirements enforced by the ANPD compelling healthcare providers to formalize breach response programs |
Driver |
+2.3% |
Latin America (strongest in Brazil) |
2026–2030 |
|
ANVISA's medical device cybersecurity guidance expanding compliance-driven security investment among device manufacturers and hospitals |
Driver |
+2.0% |
Latin America (strongest in Brazil) |
2026–2031 |
|
Rapid digital health infrastructure expansion across Brazil and Mexico increasing baseline cybersecurity investment requirements |
Driver |
+1.8% |
Latin America (strongest in Brazil and Mexico) |
2026–2032 |
|
Accelerating cloud migration of electronic health records and telehealth platforms increasing demand for cloud security |
Driver |
+1.6% |
Latin America (nationwide; strongest in Brazil, Mexico, and Chile) |
2026–2033 |
|
Growing adoption of managed security services amid a persistent cybersecurity talent shortage |
Driver |
+1.4% |
Latin America (strongest among small and mid-sized providers) |
2026–2030 |
|
Budget constraints across public hospital systems limiting cybersecurity capital expenditure |
Restraint |
−1.7% |
Latin America (nationwide; strongest across smaller and public health systems) |
2026–2030 |
|
Shortage of skilled cybersecurity professionals within the healthcare sector slowing implementation timelines |
Restraint |
−1.4% |
Latin America (nationwide) |
2026–2031 |
|
Integration complexity between legacy hospital IT systems and modern security architectures constraining deployment speed |
Restraint |
−1.1% |
Latin America (strongest in Brazil and Argentina) |
2026–2029 |
What Is the Primary Growth Driver of the Latin America Healthcare Cybersecurity Market?
Escalating ransomware attacks are the primary growth driver of the Latin America healthcare cybersecurity market. Kaspersky's regional threat research found that 8.13% of organizations in Latin America registered ransomware attacks in 2025, the highest proportion of any world region and ahead of Asia Pacific, Africa, and Europe. We observed that hospitals are responding by increasing budget allocation toward security operations, endpoint detection and response, and managed detection and response services. This shift toward proactive threat containment continues to drive demand across identity security, network security, and security operations categories throughout the region.
How Is Regulatory Compliance Driving Latin America Healthcare Cybersecurity Market Growth?
Brazilian regulatory requirements are accelerating compliance-driven cybersecurity investment across the region's largest healthcare market. The Autoridade Nacional de Proteção de Dados approved a Security Incident Communication Regulation under the LGPD requiring controllers to report qualifying incidents within three business days. The Agência Nacional de Vigilância Sanitária has separately published cybersecurity guidance for medical device manufacturers and healthcare services. Our assessment indicates that these overlapping national requirements are compelling healthcare providers, payers, and device manufacturers to formalize risk assessment, access control, and incident response programs across Latin America.
What Is Restraining Latin America Healthcare Cybersecurity Market Expansion?
Budget constraints across public hospital systems continue to restrain the pace of cybersecurity investment across Latin America. Many healthcare providers operate with legacy information technology infrastructure that is costly to replace and complex to integrate with modern security architectures. We found that a persistent shortage of skilled cybersecurity professionals within the healthcare sector further slows implementation timelines, particularly for smaller providers outside major metropolitan centers. These constraints are prompting many healthcare organizations to prioritize managed security services over in-house capability building to bridge resource and expertise gaps.
SWOT Analysis of the Latin America Healthcare Cybersecurity Market
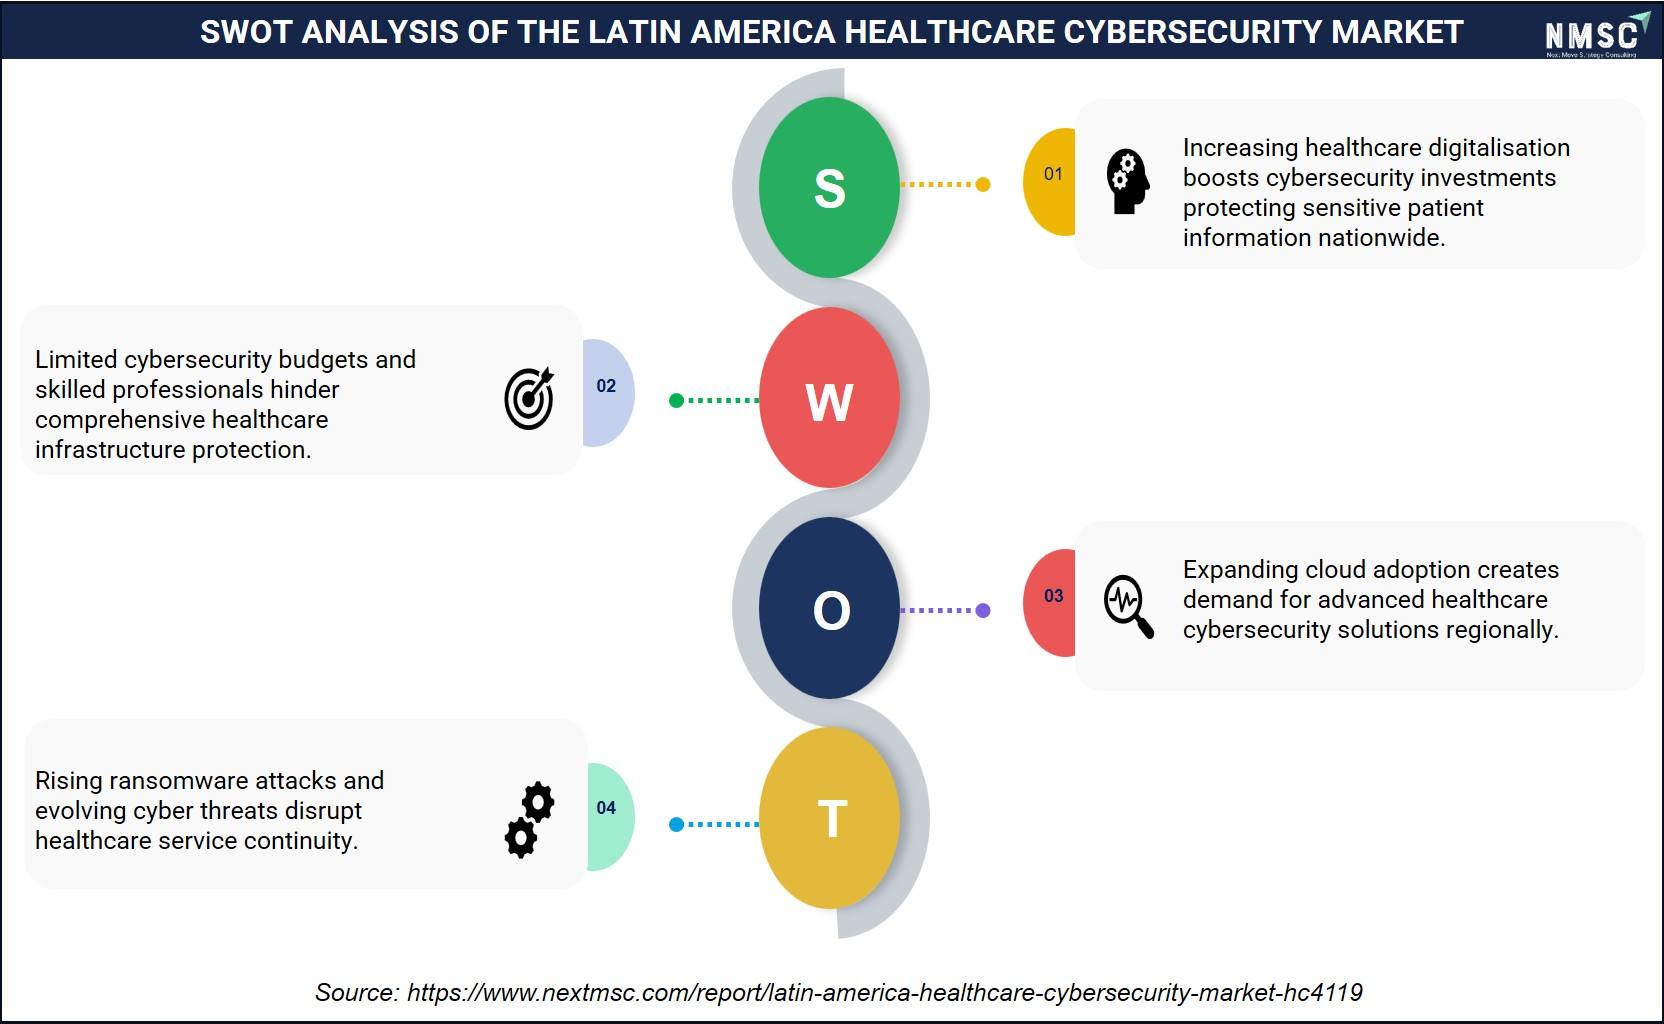
This infographic presents a SWOT analysis of the Latin America healthcare cybersecurity market. It highlights strengths such as increasing healthcare digitalization, weaknesses including limited cybersecurity budgets and skilled workforce shortages, opportunities arising from expanding cloud adoption, and threats posed by rising ransomware attacks and evolving cyber risks. Together, these factors illustrate the region's evolving cybersecurity landscape and the growing need for resilient healthcare security solutions.
Segmentation Analysis
By Component Insights
How Is the Latin America Healthcare Cybersecurity Market Segmented by Component?
Based on component, the Latin America healthcare cybersecurity market is segmented into software, hardware, and services, with software further divided into identity security, endpoint security, network security, cloud security, application security, data security, email security, security operations, exposure management, and operational technology security.
Software is the dominant component as Latin American health systems prioritize identity governance, endpoint detection and response, and network security platforms to protect distributed clinical and administrative environments. We observed that services, particularly managed security services and professional consulting, represent the fastest-growing component as healthcare organizations facing persistent staffing shortages increasingly outsource security operations, detection and response, and compliance advisory functions to specialized providers. This shift reflects a broader preference among small and mid-sized healthcare providers for outcome-based security partnerships over standalone software licensing.
By Customer Type Insights
How Is the Latin America Healthcare Cybersecurity Market Segmented by Customer Type?
Based on customer type, the market is segmented into healthcare providers, healthcare payers, life sciences, medical technology, and healthcare public sector organizations, spanning integrated delivery networks, hospitals, physician practices, health insurers, pharmaceutical companies, and public health agencies.
Healthcare providers represent the dominant customer type, reflecting the sheer scale of hospital networks, ambulatory centers, and long-term care facilities operating interconnected clinical and administrative systems across the region. Our analysis indicates that medical technology companies constitute the fastest-growing customer type as device manufacturers face intensifying regulatory scrutiny and expanding connectivity requirements for diagnostic imaging and monitoring equipment. Growing digital health adoption among physician practices and ambulatory surgery centers is further reinforcing demand for scalable, cloud-delivered security solutions tailored to smaller care settings.
Growth Opportunities
Our analysis shows that three forward-looking opportunities stand out for stakeholders operating in the Latin America healthcare cybersecurity market over the 2026–2035 forecast period.
How Can Managed Detection and Response Unlock New Growth for Smaller Providers?
Managed detection and response presents a significant opportunity as small and mid-sized healthcare providers seek enterprise-grade protection without expanding internal security teams. Vendors offering outcome-based managed security contracts can capture demand from ambulatory surgery centers, physician practices, and long-term care facilities facing constrained budgets and cybersecurity talent shortages. Companies that combine 24/7 monitoring with healthcare-specific threat intelligence are well positioned to capture this underserved segment.
Where Does Medical Device Security Create New Demand for Vendors?
Growing regulatory scrutiny of connected medical devices creates substantial opportunity for vendors offering dedicated operational technology and clinical IoT security solutions. Companies that provide asset inventory, network segmentation, and continuous monitoring tailored to biomedical and clinical engineering teams can capture demand from hospitals expanding connected diagnostic and monitoring equipment. This opportunity is reinforced by ANVISA's cybersecurity expectations for device manufacturers and healthcare services across Brazil.
How Can Cloud Security Solutions Benefit Vendors Serving Latin American Health Systems?
Accelerating migration of electronic health records and telehealth platforms to cloud infrastructure creates opportunity for vendors offering cloud security posture management, workload protection, and access broker solutions. Companies that address LGPD data protection requirements alongside cloud-native security architecture can strengthen positioning with integrated delivery networks and healthcare payers pursuing digital transformation. Early movers combining compliance expertise with cloud security depth are best positioned to capture this expanding opportunity.
Competitive Landscape
We observed that the Latin America healthcare cybersecurity market features a highly competitive landscape, with diversified global cybersecurity platform vendors competing alongside specialized point-solution providers with deep regional distribution networks.
|
Dimension |
Description |
|
Market Structure |
Moderately consolidated with global platform vendors such as Microsoft, Cisco Systems, and Palo Alto Networks holding significant share alongside endpoint security specialists ESET and Kaspersky, which maintain long-standing distribution and brand presence across Brazil, Mexico, and Argentina. |
|
Innovation Focus |
Agentic AI-driven threat detection, identity governance, medical device and clinical IoT security, and ransomware-focused security operations dominate current product development strategies across leading vendors. |
|
M&A Activity |
Channel expansion, managed security service portfolio growth, and strategic distribution partnerships continue to shape competitive positioning as vendors deepen local market presence across the region. |
How Do Companies Compete in the Latin America Healthcare Cybersecurity Market?
Companies compete primarily through platform breadth, regional distribution depth, and local compliance capabilities. Leading vendors such as Microsoft, Cisco Systems, Palo Alto Networks, and Fortinet leverage integrated security platforms spanning network, endpoint, and cloud protection to serve large integrated delivery networks across Brazil and Mexico. Meanwhile, specialized providers including ESET, Kaspersky, and Thales differentiate through endpoint protection, threat intelligence, and identity and data encryption capabilities backed by decades of regional channel presence.
Which Competitive Archetypes Dominate the Latin America Healthcare Cybersecurity Market?
Two primary competitive archetypes characterize the market. The first comprises diversified global platform vendors offering comprehensive security portfolios spanning network, endpoint, identity, and cloud protection, including Microsoft, Cisco Systems, Palo Alto Networks, International Business Machines Corporation, and Check Point Software Technologies. The second includes specialized point-solution providers such as Proofpoint, Qualys, Cloudflare, Radware, ESET, and Kaspersky, which focus on email security, exposure management, edge network protection, and endpoint threat intelligence tailored to the region's distribution-driven go-to-market model.
How Are Companies Differentiating Through Innovation in Latin America Healthcare Cybersecurity?
Innovation strategies increasingly focus on agentic artificial intelligence for autonomous threat triage, unified security operations platforms, and ransomware-focused resilience capabilities. Vendors including CrowdStrike and Trend Micro are expanding cloud-native security architectures to support healthcare organizations migrating electronic health records and telehealth applications. Our analysis indicates that companies combining automated detection with Portuguese and Spanish-language local support are strengthening competitive positioning across Brazil, Mexico, and other regional markets.
What M&A and Expansion Activity Is Shaping the Latin America Healthcare Cybersecurity Market?
Strategic partnerships, channel expansion, and distribution investment continue to shape competition across the market. Leading vendors are expanding managed security service portfolios and forming partnerships with regional systems integrators and value-added resellers to reach smaller health systems across Brazil, Mexico, Colombia, and Argentina. These initiatives enable vendors to broaden healthcare-specific offerings, deepen local language support, and respond more effectively to evolving compliance and ransomware resilience requirements across Latin America.
Key Market Players
Our assessment indicates that the following 15 companies are actively shaping platform innovation, regional distribution expansion, and competitive dynamics within the Latin America healthcare cybersecurity market.
-
Microsoft
-
Fortinet
-
International Business Machines Corporation
-
CrowdStrike
-
Check Point Software Technologies
-
Trend Micro
-
Thales
-
Proofpoint
-
Qualys
-
Cloudflare
-
Radware
-
ESET
-
Kaspersky
Latest Developments
We found that recent developments within the Latin America healthcare cybersecurity market are concentrated on regional threat intelligence findings, data protection enforcement, and expanding operational technology risk awareness, reflecting the industry's growing emphasis on ransomware resilience and regulatory compliance.
|
Date |
Event |
|
July 2025 |
Fortinet released its 2025 State of Operational Technology and Cybersecurity Report, surveying OT professionals across Brazil, Mexico, Argentina, and Colombia, including respondents from the healthcare and pharmaceutical sector. |
Investment Opportunities
What Capital Inflows Are Targeting the Latin America Healthcare Cybersecurity Market?
Capital inflows into the Latin America healthcare cybersecurity market are increasingly directed toward ransomware-focused security operations, agentic AI-driven threat detection, and identity governance platforms tailored to healthcare compliance needs. Leading vendors continue to invest in regional distribution capacity and local-language support to address the region's fragmented, multi-country regulatory landscape. We observed that investors favor companies demonstrating healthcare-specific threat intelligence, proven containment outcomes, and scalable managed service delivery models as indicators of long-term growth potential.
How Is Infrastructure Investment Supporting the Latin America Healthcare Cybersecurity Market?
Infrastructure investment is expanding regional security operations center capacity, cloud security infrastructure, and managed detection and response delivery capabilities across the healthcare cybersecurity ecosystem. Our findings suggest that vendors are investing in automation, threat intelligence platforms, and integration capabilities to support hospitals migrating legacy on-premises systems toward hybrid and cloud-based architectures. These investments are strengthening service delivery capacity while enabling faster onboarding of healthcare providers, payers, and life sciences organizations across Brazil, Mexico, and other regional markets.
What ESG Considerations Are Shaping Investment Decisions in the Latin America Healthcare Cybersecurity Market?
Environmental, social, and governance considerations are increasingly integrated into investment decisions across the Latin America healthcare cybersecurity market, with data privacy, patient safety, and workforce development emerging as key priorities. We found that investors increasingly favor vendors demonstrating measurable commitments to responsible data handling, transparent breach disclosure practices, and cybersecurity workforce training programs addressing the region's persistent talent shortage. These governance-focused priorities are strengthening vendor reputation while supporting long-term value creation across an increasingly compliance-conscious healthcare buyer base.
Key Benefits for Stakeholders
How Does This Report Benefit Enterprise and Industry Leaders?
Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support strategic planning, vendor selection, and security investment prioritization across the Latin America healthcare cybersecurity market. Our analysis shows that detailed assessments of component, deployment model, customer type, and buyer type help hospital and payer organizations identify high-priority investment areas and strengthen long-term security posture planning across diverse national markets.
How Does This Report Benefit Investors and Financial Analysts?
Investors and financial analysts benefit from consistent market size estimates, growth forecasts, and competitive assessments that support investment evaluation and capital allocation decisions across the Latin America healthcare cybersecurity market. We observed that the report's detailed analysis of managed security services, cloud security, and identity governance segments enables stakeholders to identify companies and market categories with the strongest long-term growth potential through 2035.
How Does This Report Benefit Technology Vendors and Product Teams?
Technology vendors and product development teams gain valuable insight into emerging innovation trends, including agentic AI-driven security operations, medical device protection, and cloud security architectures transforming the Latin American healthcare cybersecurity industry. Our findings suggest that this analysis helps research and development teams prioritize product roadmaps, accelerate region-specific compliance features, and align offerings with evolving regulatory expectations across national markets.
Key Market Segments
By Component
-
Software
-
Identity Security
-
Identity Governance and Administration
-
Privileged Access Management
-
Multi-Factor Authentication
-
Single Sign-On
-
Identity Threat Detection and Response
-
-
Endpoint Security
-
Endpoint Protection
-
Endpoint Detection and Response
-
Extended Detection and Response
-
Mobile Threat Defense
-
-
Network Security
-
Network Firewall
-
Network Detection and Response
-
Network Access Control
-
Secure Remote Access
-
Network Segmentation
-
-
Cloud Security
-
Cloud Security Posture Management
-
Cloud Workload Protection
-
Cloud Access Security Broker
-
Container Security
-
Kubernetes Security
-
-
Application Security
-
Web Application Firewall
-
API Security
-
Runtime Application Protection
-
Application Security Testing
-
-
Data Security
-
Data Loss Prevention
-
Encryption
-
Database Security
-
File Security
-
Tokenization
-
-
Email Security
-
Secure Email Gateway
-
Anti-Phishing
-
Business Email Protection
-
Email Encryption
-
-
Security Operations
-
Security Information and Event Management
-
Automation and Response
-
Threat Intelligence
-
Log Management
-
Threat Hunting
-
-
Exposure Management
-
Vulnerability Management
-
Attack Surface Management
-
Configuration Compliance
-
Security Validation
-
-
Operational Technology Security
-
Medical Device Security
-
Clinical Internet of Things Security
-
Network Monitoring
-
Biomedical Asset Protection
-
-
Other Security Software
-
-
Hardware
-
Network Security Appliances
-
Firewall Appliances
-
Secure Web Gateways
-
Secure Remote Access Appliances
-
-
Identity Security Appliances
-
Hardware Security Modules
-
Authentication Appliances
-
-
OT Security Appliances
-
Passive Network Sensors
-
Dedicated Monitoring Appliances
-
-
Other Security Hardware
-
-
Services
-
Managed Security Services
-
Detection and Response
-
Security Operations Center
-
Firewall
-
Endpoint Security
-
Cloud Security
-
Exposure Management
-
Other Managed Security Services
-
-
Professional Services
-
Security Consulting
-
Risk Assessment
-
Compliance Advisory
-
Security Architecture
-
Deployment
-
System Integration
-
Incident Response
-
Digital Forensics
-
Security Awareness Training
-
Other Professional Services
-
-
Support and Maintenance
-
Technical Support
-
Software Maintenance
-
Hardware Maintenance
-
Premium Support
-
-
By Deployment Model
-
Cloud
-
On-Premises
-
Hybrid
By Organization Size
-
Small
-
Medium
-
Large
By Commercial Model
-
Subscription
-
Perpetual License
-
Consumption Based
-
Appliance Sale
-
Project-Based
-
Managed Service Contract
-
Support Contract
By Customer Type
-
Healthcare Providers
-
Integrated Delivery Networks
-
General Hospitals
-
Specialty Hospitals
-
Physician Practices
-
Ambulatory Surgery Centers
-
Diagnostic Imaging Centers
-
Long-Term Care Facilities
-
Home Healthcare Providers
-
-
Healthcare Payers
-
Commercial Health Insurers
-
Government Health Payers
-
-
Life Sciences
-
Pharmaceutical Companies
-
Biotechnology Companies
-
Contract Research Organizations
-
-
Medical Technology
-
Medical Device Manufacturers
-
Digital Health Companies
-
-
Healthcare Public Sector
-
Public Health Agencies
-
Academic Medical Centers
-
Research Institutes
-
By Buyer Type
-
Chief Information Officer
-
Chief Information Security Officer
-
Information Technology Infrastructure
-
Security Operations Center
-
Clinical Engineering
-
Biomedical Engineering
-
Risk and Compliance
-
Procurement
By Sales Channel
-
Direct Sales
-
Value-Added Resellers
-
Systems Integrators
-
Managed Security Service Providers
-
Cloud Marketplaces
-
Original Equipment Manufacturer Partners
By Country
-
Brazil
-
Argentina
-
Chile
-
Colombia
Conclusion and Recommendations
What Is the Long-Term Outlook for the Latin America Healthcare Cybersecurity Market?
The long-term outlook for the Latin America healthcare cybersecurity market remains positive, supported by the region's disproportionate ransomware exposure, expanding national regulatory obligations, and accelerating digital health adoption across hospitals and healthcare payers. We observed that sustained investment in identity security, cloud security, and managed detection and response will continue to drive market expansion across healthcare providers, medical technology companies, and public health agencies throughout the forecast period.
What Strategic Positioning Should Healthcare Cybersecurity Companies Pursue?
Vendors should prioritize investment in agentic AI-driven threat detection, ransomware resilience capabilities, and healthcare-specific compliance expertise while strengthening managed security service portfolios for resource-constrained providers across the region. Our assessment indicates that companies expanding medical device and clinical IoT security capabilities alongside cloud-native architectures will be well positioned to strengthen competitive positioning and capture premium healthcare accounts within the Latin America healthcare cybersecurity market.
How Attractive Is the Latin America Healthcare Cybersecurity Market for New Investment?
The Latin America healthcare cybersecurity market presents an attractive investment opportunity, supported by growing hospital security budgets, expanding medical device connectivity, and continued innovation in AI-driven detection and response solutions. We found that investment potential is particularly strong for companies focused on managed security services, identity governance, and cloud security, enabling them to capitalize on evolving compliance requirements and long-term market growth across the region.
What Market Shifts and Key Risks Should Stakeholders Monitor?
Stakeholders should closely monitor evolving national privacy and cybersecurity requirements, persistent cybersecurity talent shortages, and increasing sophistication of ransomware targeting healthcare infrastructure. Our analysis shows that companies unable to continuously innovate, demonstrate measurable containment outcomes, or address legacy system integration challenges may face increasing competitive pressure within the Latin America healthcare cybersecurity market.
What Are the Key Growth Pathways for the Latin America Healthcare Cybersecurity Market?
Key growth pathways include expanding managed detection and response portfolios, accelerating medical device and clinical IoT security innovation, strengthening cloud security capabilities, and enhancing regional distribution and local-language support. NMSC's analysis indicates that companies successfully combining agentic AI innovation, healthcare-specific compliance expertise, and strong channel partnerships will be best positioned to capture the Latin America healthcare cybersecurity market's projected growth through 2035.


About the Author
 Liza Phukan
— Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

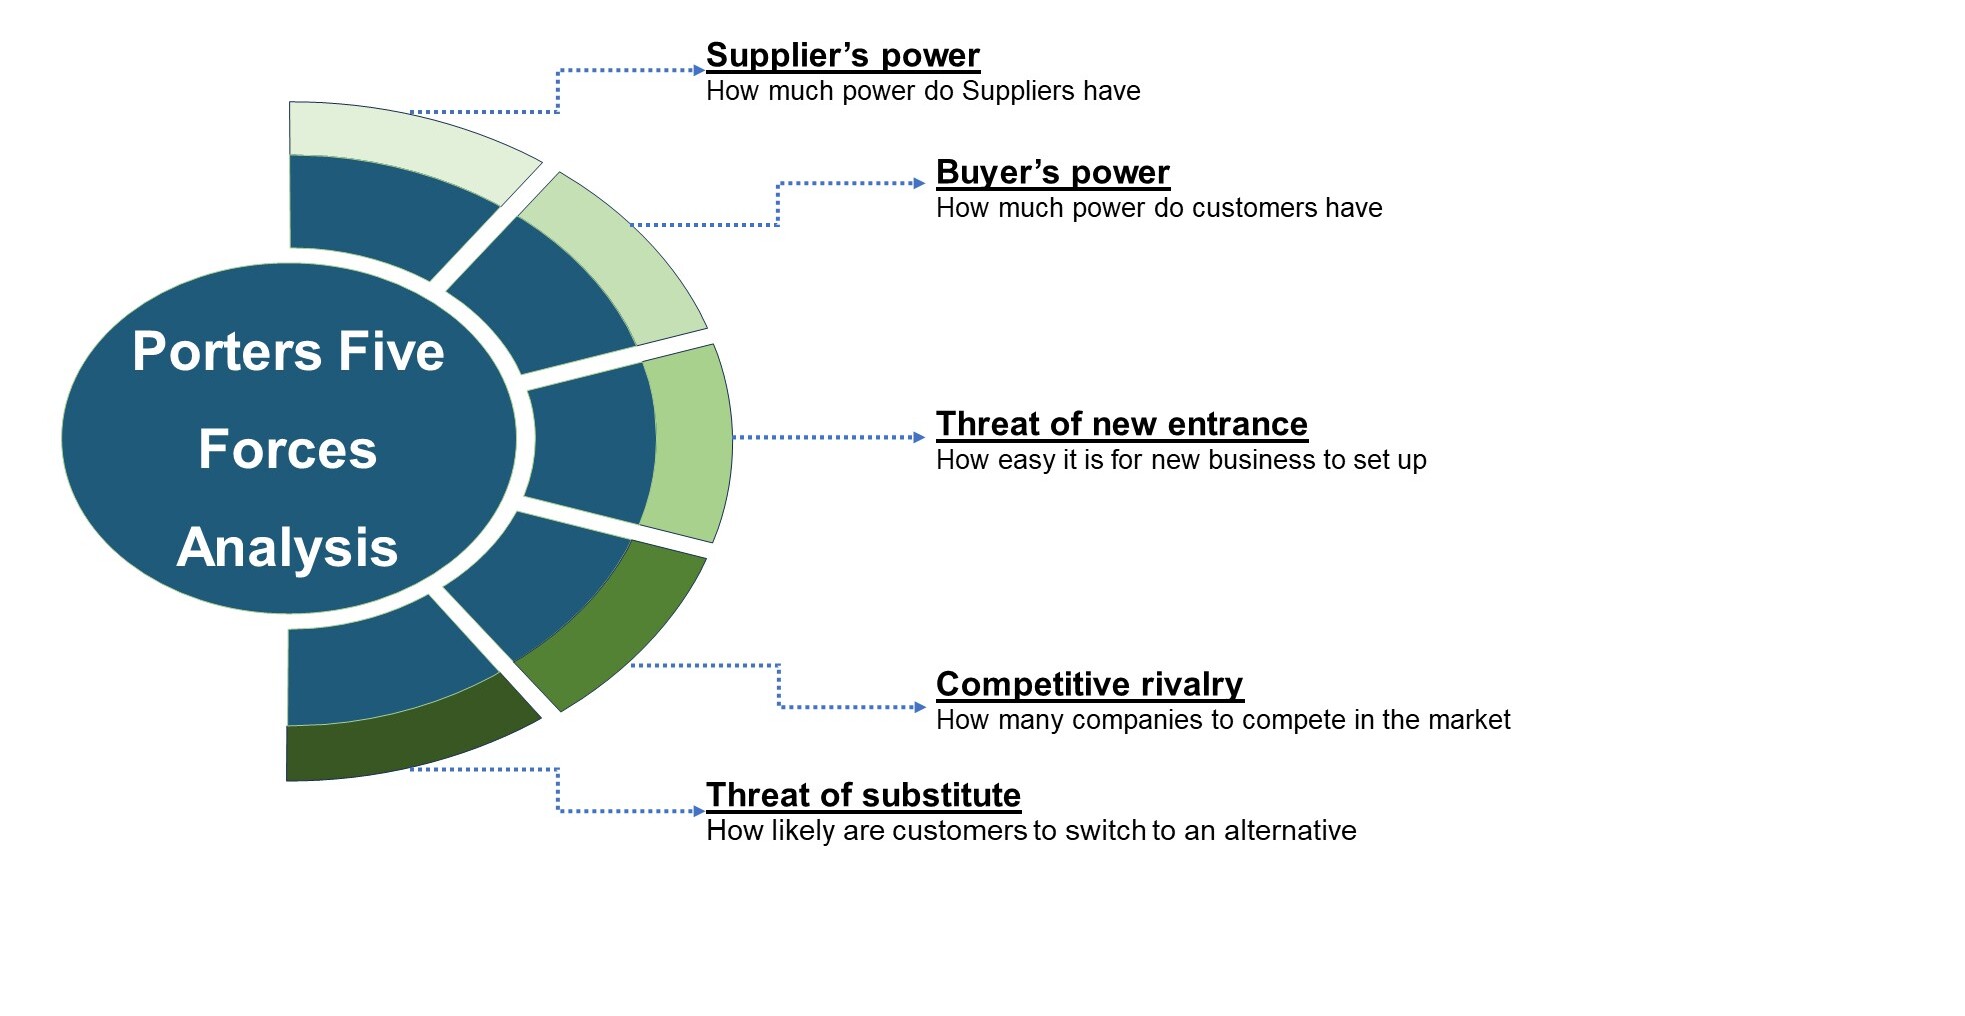
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.




 Speak to Our Analyst