Pharmaceutical Stability & Storage Services Market Global Industry Analysis and Forecast (2026–2035)

The global Pharmaceutical Stability & Storage Services Market size was valued at USD 2.05 billion in 2025 and is estimated at USD 2.19 billion in 2026, forecast to reach USD 4.05 billion by 2035, expanding at a 7.1% CAGR between 2026 and 2035. North America leads with approximately 41% share, while Stability Testing Services dominates all other offerings with approximately 44% share.

Download Free Sample PDF
Base Year (2025)
$2.05 Billion
Forecast (2035)
$4.05 Billion
CAGR (2026-2035)
7.1%
Top Region
North America

What Is the Pharmaceutical Stability & Storage Services Market Size?

The global Pharmaceutical Stability & Storage Services Market size was valued at USD 2.05 billion in 2025 and is estimated at USD 2.19 billion in 2026, forecast to reach USD 4.05 billion by 2035, expanding at a 7.1% CAGR between 2026 and 2035. North America leads with approximately 41% share, while Stability Testing Services dominates all other offerings with approximately 44% share.

We observed that growth is broad-based across every segmentation axis, with expanding biologics pipelines and cryogenic storage demand for advanced therapies driving the dominant structural shifts through 2035.

Pharmaceutical Stability & Storage Services Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast

Values in USD Billion

2025 $2.05 Billion
2025
2026 $2.20 Billion
2026
2027 $2.35 Billion
2027
2028 $2.52 Billion
2028
2029 $2.70 Billion
2029
2030 $2.89 Billion
2030
2031 $3.09 Billion
2031
2032 $3.31 Billion
2032
2033 $3.55 Billion
2033
2034 $3.80 Billion
2034
2035 $4.05 Billion
2035

Key Takeaways

By Offering: Stability Testing Services held the largest share of approximately 44% (USD 0.90 billion) in 2025; Regulatory and Quality Services is the fastest-growing sub-segment at 10.2% CAGR from 2026–2035.

By Temperature Condition: Controlled Room Temperature held the largest share of approximately 38% (USD 0.78 billion) in 2025; Cryogenic Storage is the fastest-growing sub-segment at 15.8% CAGR from 2026–2035.

By Molecule Class: Small Molecules held the largest share of approximately 55% (USD 1.13 billion) in 2025; Advanced Therapies is the fastest-growing sub-segment at 12.6% CAGR from 2026–2035.

By Development Stage: Commercial held the largest share of approximately 34% (USD 0.69 billion) in 2025; Phase III is the fastest-growing sub-segment at 8.3% CAGR from 2026–2035.

By Customer Type: Pharmaceutical Companies held the largest share of approximately 46% (USD 0.95 billion) in 2025; Biotechnology Companies is the fastest-growing sub-segment at 8.8% CAGR from 2026–2035.

By Revenue Model: Contract Revenue held the largest share of approximately 36% (USD 0.74 billion) in 2025; Capacity-Based Revenue is the fastest-growing sub-segment at 9.5% CAGR from 2026–2035.

By Regulatory Framework: ICH Standards held the largest share of approximately 38% (USD 0.79 billion) in 2025; Other National Standards is the fastest-growing sub-segment at 13.4% CAGR from 2026–2035.

By Sales Channel: Direct Enterprise Sales held the largest share of approximately 41% (USD 0.85 billion) in 2025; Clinical Supply Partnerships is the fastest-growing sub-segment at 12.6% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 41% revenue share (USD 0.85 billion) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 10.0% during 2026–2035.

Dominant Country: U.S. led with approximately USD 0.70 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 12.2% CAGR from 2026–2035.

Market Opportunity: The Pharmaceutical Stability & Storage Services Market is expected to create an absolute dollar opportunity of USD 1.86 billion between 2026 and 2035, presenting significant investment potential across the cryogenic and biologics-focused stability infrastructure value chain.

According to NMSC analysis, contract service providers are increasingly bundling stability testing, storage, and regulatory documentation into single dedicated-capacity agreements, a shift that favors integrated providers with cGMP-compliant chamber networks over standalone testing labs as biologics and advanced therapy pipelines expand through 2035.

What Does the Pharmaceutical Stability & Storage Services Market Encompass?

The Pharmaceutical Stability & Storage Services Market encompasses the testing, storage, analytical support, sample management, regulatory documentation, and clinical depot services used to demonstrate product shelf life and maintain compliant storage conditions across the drug development lifecycle. We observed that the scope spans real-time and accelerated stability studies, ambient through cryogenic storage conditions, and chain of custody and depot management services supporting clinical and commercial supply chains, often delivered through outsourced contract research organizations rather than in-house teams. The category has evolved from in-house quality control into a specialized outsourced service model as pipelines diversify into biologics and advanced therapies.
Regulatory frameworks such as ICH Q1A, Q1B, and Q5C guidelines, alongside FDA and EMA stability requirements, continue to define study design and storage condition standards across the industry. We observed that technology adoption is shifting toward real-time environmental monitoring and digital chain of custody systems that reduce manual documentation burden. NMSC's analysis indicates that this structural shift, combined with expanding cell and gene therapy pipelines requiring cryogenic storage, is redefining capacity planning criteria across the Pharmaceutical Stability & Storage Services Market.

Market Drivers & Dynamics

Interactive Dataset
Expanding biologics and advanced therapy development pipelines driver +1.9% Global 2026-2035
Rising outsourcing of stability testing and storage functions driver +1.6% North America, Europe 2026-2035
Growing regulatory complexity across ICH, FDA, and national frameworks driver +1.3% Global 2026-2033
Expanding cryogenic and cold chain infrastructure investment driver +1.2% North America, Asia-Pacific 2026-2035
Increasing clinical trial globalization and depot network complexity driver +1.0% Asia-Pacific, Latin America 2026-2035
Rising demand for real-time environmental monitoring systems driver +0.8% Global 2026-2032
High capital cost of cGMP-compliant chamber and storage infrastructure restraint -1.2% Global 2026-2035
Capacity constraints during peak biologics stability testing demand restraint -0.8% North America, Europe 2026-2032
Fragmented national regulatory requirements complicating multi-country studies restraint -0.6% Asia-Pacific, Middle East & Africa 2026-2030
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Pharmaceutical Stability & Storage Services Market?

Expanding biologics and advanced therapy development pipelines are the primary driver of the market. U.S. Securities and Exchange Commission filings from contract service providers continue to document sustained double-digit revenue growth tied to biostorage and bioservices demand. We observed that this pipeline expansion, reinforced by growing commercial cell and gene therapy approvals, continues to anchor baseline demand for cryogenic and ultra-low temperature storage capacity across the industry.

How Is Outsourcing Adoption Driving Pharmaceutical Stability & Storage Services Market Growth?

Rising outsourcing of stability testing and storage functions is accelerating market growth as sponsors seek to avoid capital investment in dedicated chamber infrastructure, often through life sciences business process outsourcing arrangements. Eurofins BioPharma Product Testing's 2025 and 2026 facility expansions across North America illustrate how providers are scaling capacity to absorb this outsourced demand. NMSC's analysis indicates that this outsourcing trajectory, combined with rising biologics pipeline complexity, is compressing sponsors' need for in-house stability program management.

Growth Inhibitors

What Is Restraining Pharmaceutical Stability & Storage Services Market Expansion?

High capital cost of cGMP-compliant chamber and storage infrastructure restrains broader provider participation across the market. Alcami Corporation's Garner, North Carolina facility expansion documents the scale of investment required to support customizable, long-term storage conditions for biopharmaceutical materials. We found that capacity constraints during peak biologics stability testing demand particularly affect smaller sponsors, which face longer lead times securing dedicated chamber space than large pharmaceutical companies with established provider relationships.

What Are the Growth Opportunities?

How Can Cryogenic Capacity Expansion Unlock Value for Advanced Therapy Developers?

Cryogenic and ultra-low temperature storage capacity expansion presents a whitespace opportunity for providers serving developers of gene therapy commercial approvals and cell therapy programs facing constrained infrastructure availability. Providers that commercialize validated, scalable cryogenic networks stand to capture premium pricing among advanced therapy sponsors seeking dedicated capacity ahead of anticipated commercial approvals, particularly across monoclonal antibody categories.

How Can Digital Chain of Custody Systems Benefit Clinical Supply Sponsors?

Rising complexity of global clinical trial depot networks creates an opportunity for providers integrating digital chain of custody records with clinical trial management systems used by sponsors to track investigational product across sites. Early movers that secure interoperable data-sharing agreements can differentiate with sponsors pursuing real-time visibility into comparator storage, label management, and returns handling across multi-country trial networks.

How Can Regulatory and Quality Bundling Benefit Emerging Biotechnology Sponsors?

Rising regulatory complexity across ICH, FDA, EMA, and national frameworks creates an opportunity for providers offering bundled stability protocol design and regulatory documentation services. Early movers that secure integrated testing-to-filing service agreements can differentiate with emerging biotechnology sponsors pursuing capital-efficient regulatory submission pathways alongside dedicated storage capacity.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Stability Testing Services 2025: $0.90 Billion | 2035: $1.63 Billion
Stability Te
Storage Services 2025: $0.45 Billion | 2035: $0.85 Billion
Storage Serv
Analytical Support Services 2025: $0.29 Billion | 2035: $0.57 Billion
Analytical S
Sample Management Services 2025: $0.16 Billion | 2035: $0.36 Billion
Sample Manag
Regulatory and Quality Services 2025: $0.14 Billion | 2035: $0.36 Billion
Regulatory a
Clinical Supply and Depot Services 2025: $0.11 Billion | 2035: $0.28 Billion
Clinical Sup
Stability Testing Services $0.90 Billion $1.63 Billion 6.0%
Storage Services $0.45 Billion $0.85 Billion 6.5%
Analytical Support Services $0.29 Billion $0.57 Billion 7.0%
Sample Management Services $0.16 Billion $0.36 Billion 8.6%
Regulatory and Quality Services $0.14 Billion $0.36 Billion 10.2%
Clinical Supply and Depot Services $0.11 Billion $0.28 Billion 10.1%

Which Offering Segment Dominates the Pharmaceutical Stability & Storage Services Market?

Stability Testing Services led the market with USD 0.90 billion in 2025, reflecting its position as the mandatory regulatory function underpinning every drug development and commercial program. We observed that Regulatory and Quality Services is the fastest-growing offering, expanding at a 10.2% CAGR from 2026 to 2035, as sponsors increasingly outsource stability protocol design and audit support to manage growing regulatory complexity across ICH, FDA, and national frameworks.

2025 (USD Billion)
2035 (USD Billion)
Ambient
Controlled R
Controlled E
Refrigerated
Frozen
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Ambient $10.0 USD Billion $40.0 USD Billion 19.0%
Controlled Room Temperature $17.1 USD Billion $51.1 USD Billion 9.0%
Controlled Elevated Temperature $24.2 USD Billion $62.2 USD Billion 23.0%
Refrigerated $31.3 USD Billion $73.3 USD Billion 21.0%
Frozen $38.4 USD Billion $84.4 USD Billion 10.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Temperature Condition.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Small Molecu
Solid Dosage
Injectable P
Semi-Solid P
Liquid Formu
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Small Molecules $10.0 USD Billion $40.0 USD Billion 8.0%
Solid Dosage Forms $17.1 USD Billion $51.1 USD Billion 26.0%
Injectable Products $24.2 USD Billion $62.2 USD Billion 24.0%
Semi-Solid Products $31.3 USD Billion $73.3 USD Billion 22.0%
Liquid Formulations $38.4 USD Billion $84.4 USD Billion 21.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Molecule Class.

Unlock Full Data

Which Molecule Class Leads Pharmaceutical Stability & Storage Services Market Demand?

Small Molecules remained the leading molecule class within the market, valued at USD 1.13 billion in 2025 on the strength of the established generic and innovative small molecule pipeline requiring routine stability programs. Our findings suggest that Advanced Therapies is the fastest-growing molecule class, registering a 12.6% CAGR from 2026 to 2035, as cell and gene therapy developers increasingly pursue biologics contract development partnerships requiring specialized cryogenic and ultra-low temperature stability and storage capacity to support growing commercial approval volumes.

2025 (USD Billion)
2035 (USD Billion)
Discovery
Preclinical
Phase I
Phase II
Phase III
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Discovery $10.0 USD Billion $40.0 USD Billion 23.0%
Preclinical $17.1 USD Billion $51.1 USD Billion 17.0%
Phase I $24.2 USD Billion $62.2 USD Billion 15.0%
Phase II $31.3 USD Billion $73.3 USD Billion 9.0%
Phase III $38.4 USD Billion $84.4 USD Billion 10.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Development Stage.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Pharmaceutic
Innovative P
Generic Phar
Specialty Ph
Biotechnolog
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Pharmaceutical Companies $10.0 USD Billion $40.0 USD Billion 12.0%
Innovative Pharmaceutical Companies $17.1 USD Billion $51.1 USD Billion 18.0%
Generic Pharmaceutical Companies $24.2 USD Billion $62.2 USD Billion 16.0%
Specialty Pharmaceutical Companies $31.3 USD Billion $73.3 USD Billion 14.0%
Biotechnology Companies $38.4 USD Billion $84.4 USD Billion 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Customer Type.

Unlock Full Data

Which Customer Type Dominates the Pharmaceutical Stability & Storage Services Market?

Pharmaceutical Companies remained the dominant customer type within the market, valued at USD 0.95 billion in 2025 as the largest institutional buyers of stability testing and storage capacity across commercial and development portfolios. Our assessment indicates that Biotechnology Companies is the fastest-growing customer type, expanding at an 8.8% CAGR from 2026 to 2035, as emerging biotechnology developers increasingly outsource stability programs to bio-production contract manufacturing capacity providers to preserve capital while advancing biologics and advanced therapy candidates through clinical development.

2025 (USD Billion)
2035 (USD Billion)
Study-Based
Per Study
Per Protocol
Sample-Based
Per Sample
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Study-Based Revenue $10.0 USD Billion $40.0 USD Billion 23.0%
Per Study $17.1 USD Billion $51.1 USD Billion 13.0%
Per Protocol $24.2 USD Billion $62.2 USD Billion 23.0%
Sample-Based Revenue $31.3 USD Billion $73.3 USD Billion 9.0%
Per Sample $38.4 USD Billion $84.4 USD Billion 26.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Revenue Model.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
ICH Standard
Q1A
Q1B
Q5C
FDA Standard
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
ICH Standards $10.0 USD Billion $40.0 USD Billion 26.0%
Q1A $17.1 USD Billion $51.1 USD Billion 8.0%
Q1B $24.2 USD Billion $62.2 USD Billion 14.0%
Q5C $31.3 USD Billion $73.3 USD Billion 24.0%
FDA Standards $38.4 USD Billion $84.4 USD Billion 11.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Regulatory Framework.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct Enter
Strategic Se
Preferred Ve
Clinical Sup
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Enterprise Sales $10.0 USD Billion $40.0 USD Billion 24.0%
Strategic Service Agreements $17.1 USD Billion $51.1 USD Billion 10.0%
Preferred Vendor Programs $24.2 USD Billion $62.2 USD Billion 8.0%
Clinical Supply Partnerships $31.3 USD Billion $73.3 USD Billion 14.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the Pharmaceutical Stability & Storage Services Market over the 2026-2035 forecast period.

How Can Cryogenic Capacity Expansion Unlock Value for Advanced Therapy Developers?

Cryogenic and ultra-low temperature storage capacity expansion presents a whitespace opportunity for providers serving developers of gene therapy commercial approvals and cell therapy programs facing constrained infrastructure availability. Providers that commercialize validated, scalable cryogenic networks stand to capture premium pricing among advanced therapy sponsors seeking dedicated capacity ahead of anticipated commercial approvals, particularly across monoclonal antibody categories.

How Can Digital Chain of Custody Systems Benefit Clinical Supply Sponsors?

Rising complexity of global clinical trial depot networks creates an opportunity for providers integrating digital chain of custody records with clinical trial management systems used by sponsors to track investigational product across sites. Early movers that secure interoperable data-sharing agreements can differentiate with sponsors pursuing real-time visibility into comparator storage, label management, and returns handling across multi-country trial networks.

How Can Regulatory and Quality Bundling Benefit Emerging Biotechnology Sponsors?

Rising regulatory complexity across ICH, FDA, EMA, and national frameworks creates an opportunity for providers offering bundled stability protocol design and regulatory documentation services. Early movers that secure integrated testing-to-filing service agreements can differentiate with emerging biotechnology sponsors pursuing capital-efficient regulatory submission pathways alongside dedicated storage capacity.

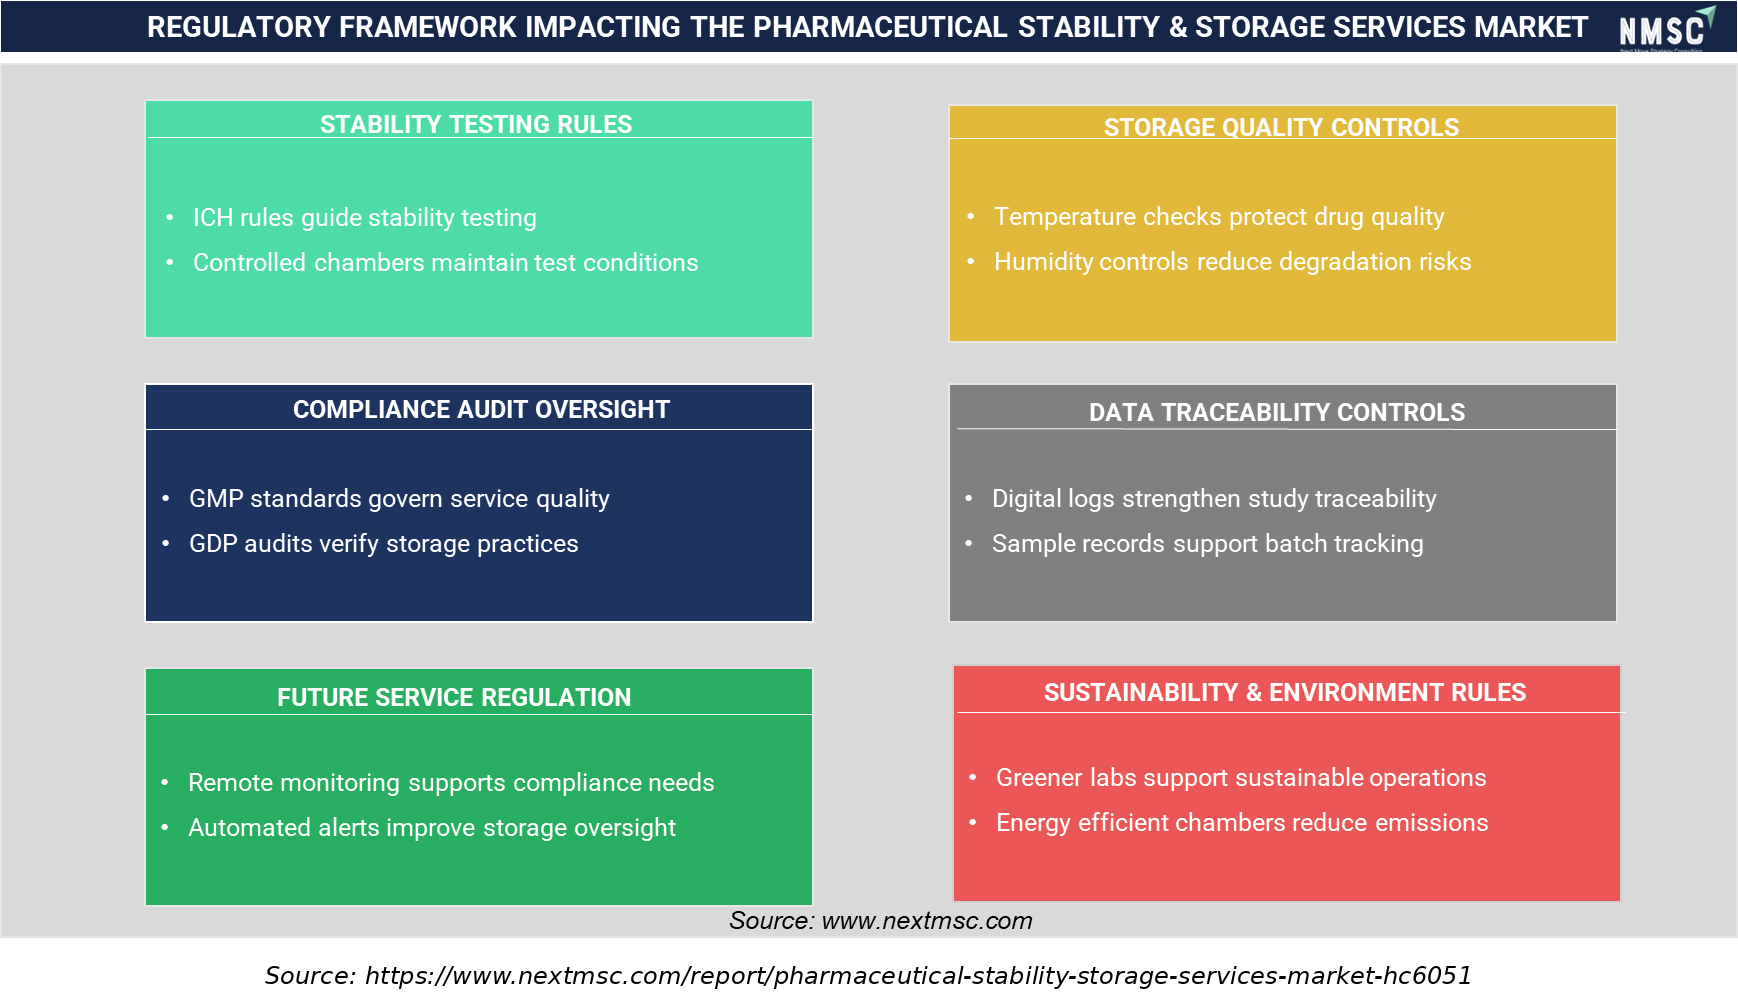
Regulatory Framework Impacting the Pharmaceutical Stability & Storage Services Market

The regulatory framework highlights the key requirements governing pharmaceutical stability testing and storage services, including ICH stability-testing principles, controlled storage conditions, GMP and GDP compliance, data traceability, and evolving service requirements. Temperature and humidity controls, digital records, remote monitoring, and energy-efficient facilities support product quality, regulatory oversight, operational transparency, and sustainable pharmaceutical storage practices.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the Pharmaceutical Stability & Storage Services Market features a moderately consolidated competitive landscape, with diversified testing and inspection groups competing alongside specialized storage and cold chain providers on capacity, certification, and regulatory documentation depth.

Dimension Description
Market Structure Moderately consolidated; the top companies profiled in this report collectively account for a significant share of global Pharmaceutical Stability & Storage Services Market revenue, while specialized regional providers serve niche cryogenic and cold chain demand.
Innovation Focus Cryogenic and ultra-low temperature capacity expansion, real-time environmental monitoring, and digital chain of custody systems dominate current innovation pipelines across leading providers.
M&A Activity Selective consolidation through capability acquisitions, exemplified by DHL Group's March 2025 acquisition of CRYOPDP from Cryoport to strengthen integrated life sciences logistics capability.

How Do Companies Compete in the Pharmaceutical Stability & Storage Services Market?

Companies compete primarily on chamber capacity, regulatory documentation depth, and cGMP certification breadth across the industry. Diversified testing and inspection groups such as Eurofins Scientific SE and SGS SA leverage extensive laboratory networks and healthcare analytical testing capacity to serve multinational sponsors, while specialized storage providers such as Cryoport Inc. and BioLife Solutions Inc. compete on cryogenic infrastructure and cold chain logistics integration for advanced therapy customers.

Which Competitive Archetypes Dominate the Pharmaceutical Stability & Storage Services Market?

Two archetypes dominate the market: diversified testing, inspection, and certification groups offering broad analytical and stability testing portfolios, and specialized storage and cold chain providers focused exclusively on temperature-controlled infrastructure. Thermo Fisher Scientific Inc. and Charles River Laboratories International Inc. exemplify the diversified archetype through integrated laboratory networks, while Cryoport Inc. and Alcami Corporation exemplify the specialized archetype through purpose-built cryogenic and cGMP storage capacity.

How Are Companies Differentiating Through Innovation in Stability and Storage Services?

Innovation and differentiation strategy increasingly center on real-time environmental monitoring and integrated cryogenic logistics validated for regulatory auditability. Cryoport's MVE Biological Solutions condition-monitoring dry vapor shippers and Eurofins' expanded ICH-compliant chamber networks both target reduced excursion risk and faster study turnaround. Our analysis shows that providers unable to demonstrate credible monitoring and documentation capability risk exclusion from sponsor qualification processes as growing biologics pipeline complexity intensifies.

What M&A and Expansion Activity Is Shaping the Pharmaceutical Stability & Storage Services Market?

Mergers, acquisitions, and geographic expansion continue to consolidate stability testing and storage capabilities within the industry. DHL Group's acquisition of CRYOPDP from Cryoport broadened integrated cold chain logistics capacity, while Eurofins BioPharma Product Testing's multi-site North American expansion illustrates how providers pursue geographic expansion to serve rising sponsor demand for dedicated stability and storage capacity.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping stability testing capacity, storage infrastructure, and regulatory service strategy within the global Pharmaceutical Stability & Storage Services Market.

Eurofins Scientific SE SGS SA Intertek Group plc ThermoFisher Scientific Inc. Charles River Laboratories International Inc. WuXi AppTec Co. Ltd. Labcorp Holdings Inc. Catalent Inc. Almac Group Ltd. Cambrex Corporation Alcami Corporation Pace Analytical Services LLC Element Materials Technology Ltd. Frontage Laboratories Inc. Cryoport Inc. Medpace Holdings Inc. NAMSA Q Laboratories Inc. Sharp Services LLC BioLife Solutions Inc.

Latest Developments

We found that recent facility expansions and strategic transactions within the Pharmaceutical Stability & Storage Services Market are concentrated on cryogenic capacity growth and integrated cold chain logistics, reflecting the industry's broader transition toward biologics and advanced therapy support.

Date Event
August 2026 Eurofins expanded its Lentilly, France facility to increase controlled-ambient and refrigerated storage for clinical-trial supplies. Total capacity reached 1,000 m³, including low- and ultra-low-temperature storage. The expansion supports secondary packaging, clinical labeling and global distribution of investigational medicinal products under controlled conditions.
May 2026 Intertek expanded its Royston, UK GMP pharmaceutical stability-storage facility to 625,000 litres, adding a wider range of bespoke storage conditions alongside standard ICH temperature and relative-humidity conditions. The expanded facility supports complex pharmaceutical development programmes, including biologic drug products, ultra-low-temperature storage of cell-based materials, and critical components of next-generation drug-device combination products.

Investment Opportunities

What Capital Inflows Are Targeting the Pharmaceutical Stability & Storage Services Market?

Capital inflows into the market are increasingly directed toward cryogenic storage capacity and integrated cold chain logistics development. Cryoport Inc.'s continued investment in new Global Supply Chain Centers, including facilities in Paris and Santa Ana, California, supports its expanding BioStorage and BioServices revenue base. We observed that investors favor providers demonstrating validated cGMP compliance and monitoring capability, viewing regulatory alignment as a proxy for long-term sponsor contract retention.

How Is Infrastructure Investment Supporting Pharmaceutical Stability & Storage Services Deployment?

Infrastructure investment is expanding stability chamber and cryogenic storage capacity across North America, Europe, and Asia-Pacific to serve rising biologics and advanced therapy demand. Our findings suggest that providers are investing in multi-site regional networks, exemplified by Eurofins' 2025 and 2026 North American facility expansions, supporting sponsors that require dedicated, geographically distributed storage capacity for global clinical and commercial programs.

What ESG Considerations Are Shaping Pharmaceutical Stability & Storage Services Investment Decisions?

Environmental, social, and governance considerations are increasingly relevant to investment decisions across the industry, with energy-efficient chamber operation and temperature-sensitive pharmaceutical packaging waste reduction cited as key criteria. Eurofins' facility sustainability disclosures document company-wide recycling programs and carbon footprint tracking across its BioPharma Product Testing network. We found that investors increasingly favor providers with demonstrated environmental stewardship credentials, treating sustainability performance as a proxy indicator alongside operational reliability in vendor selection.

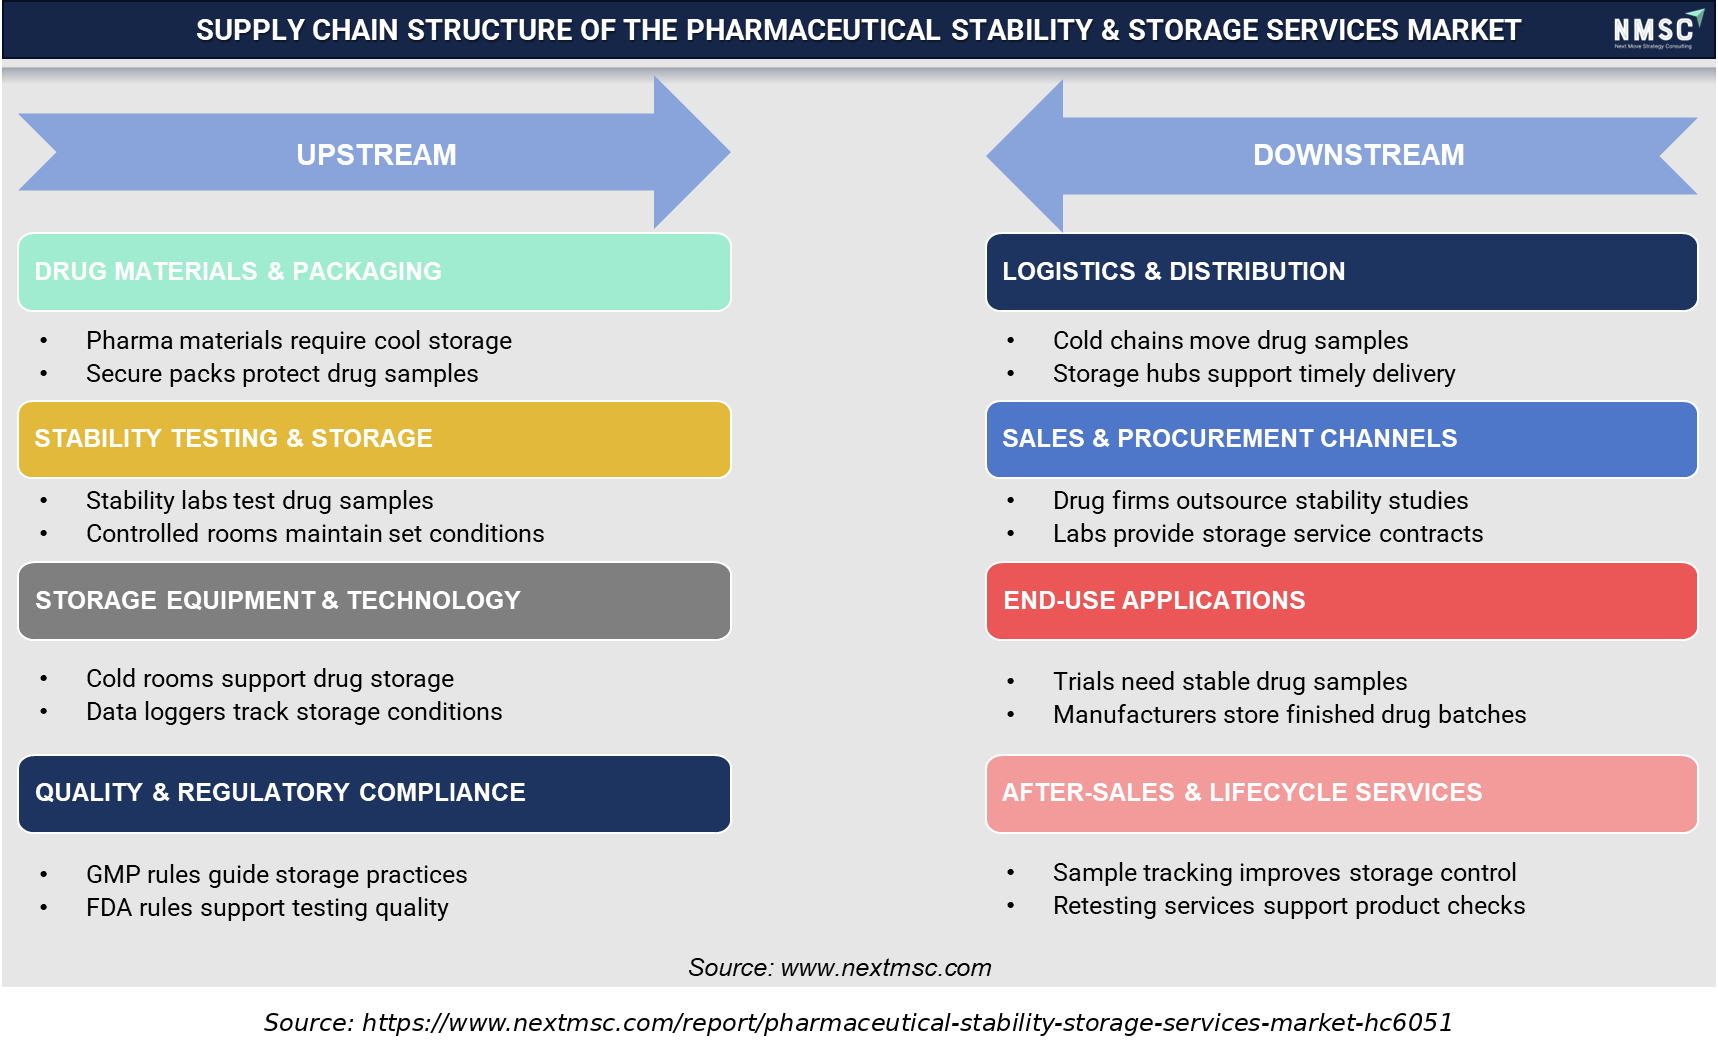
Supply Chain Structure of the Pharmaceutical Stability & Storage Services Market

Supply Chain Structure of the Pharmaceutical Stability & Storage Services Market

The supply chain structure maps the pharmaceutical stability and storage services market from drug materials and packaging through stability testing, storage equipment, and quality compliance. Downstream activities include cold-chain logistics, procurement channels, clinical and manufacturing applications, and lifecycle services. The framework highlights how controlled environments, data monitoring, regulatory adherence, and sample tracking support pharmaceutical product integrity.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support procurement and capacity-planning decisions across the Pharmaceutical Stability & Storage Services industry. Our analysis shows that detailed offering, molecule class, and customer type breakdowns help program managers align specifications with regulatory and storage condition requirements while identifying underserved segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the Pharmaceutical Stability & Storage Services Market supply chain. We observed that the report's regional and segment-level growth differentials help identify which providers are best positioned to capture above-market growth in advanced therapy and Asia-Pacific categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including real-time environmental monitoring, digital chain of custody, and cryogenic condition-monitoring systems, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around excursion risk reduction and audit-ready documentation increasingly required by sponsor qualification processes.

Key Market Segments Evaluated

By Offering

  • Stability Testing Services
  • Storage Services
  • Analytical Support Services
  • Sample Management Services
  • Regulatory and Quality Services
  • Clinical Supply and Depot Services

By Temperature Condition

  • Ambient
  • Controlled Room Temperature
  • Controlled Elevated Temperature
  • Refrigerated
  • Frozen
  • Ultra-Low
  • Cryogenic

By Molecule Class

  • Small Molecules
  • Biologics
  • Advanced Therapies
  • Medical Products

By Development Stage

  • Discovery
  • Preclinical
  • Phase I
  • Phase II
  • Phase III
  • Commercial
  • Post-Market

By Customer Type

  • Pharmaceutical Companies
  • Biotechnology Companies
  • Contract Service Organizations
  • Medical Device Companies
  • Academic and Government Institutions

By Revenue Model

  • Study-Based Revenue
  • Per Study
  • Per Protocol
  • Sample-Based Revenue
  • Per Sample
  • Per Test
  • Capacity-Based Revenue
  • Per Chamber
  • Per Pallet
  • Per Rack Position
  • Per Cubic Meter
  • Contract Revenue
  • Dedicated Capacity Contracts
  • Long-Term Service Agreements

By Regulatory Framework

  • ICH Standards
  • Q1A
  • Q1B
  • Q5C
  • FDA Standards
  • EMA Standards
  • USP Standards
  • WHO Standards
  • Other National Standards
  • PMDA
  • NMPA
  • CDSCO
  • ANVISA
  • MHRA

By Sales Channel

  • Direct Enterprise Sales
  • Strategic Service Agreements
  • Preferred Vendor Programs
  • Clinical Supply Partnerships

Conclusion & Recommendations

The long-term outlook for the market remains positive, with global revenue projected to nearly double from USD 2.05 billion in 2025 to USD 4.05 billion by 2035 at a 7.1% CAGR. We observed that sustained biologics and advanced therapy pipeline expansion, rising outsourcing adoption, and growing regulatory complexity will continue underpinning demand across stability testing, storage, and regulatory service categories through the forecast period.

What Strategic Positioning Should Pharmaceutical Stability & Storage Services Providers Pursue?

Providers should prioritize cryogenic and ultra-low temperature capacity expansion while pursuing integrated regulatory and quality service bundling to secure long-term sponsor contracts. Our assessment indicates that providers investing early in real-time environmental monitoring and digital chain of custody systems will be best positioned to capture premium pricing within the Pharmaceutical Stability & Storage Services Market.

How Attractive Is the Pharmaceutical Stability & Storage Services Market for New Investment?

The Pharmaceutical Stability & Storage Services industry presents an attractive investment case, supported by a USD 1.86 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and advanced therapy categories. We found that investment attractiveness is highest for providers combining cGMP certification credentials with scaled cryogenic capacity, positioning them to serve both established pharmaceutical companies and emerging biotechnology sponsors simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor high capital costs of cGMP-compliant infrastructure, capacity constraints during peak biologics testing demand, and fragmented national regulatory requirements as key risks to the Pharmaceutical Stability & Storage Services Market. Our analysis shows that providers unable to scale dedicated capacity risk losing sponsor contracts to competitors with certified, expanded chamber networks, particularly as biologics and advanced therapy pipelines continue growing across North America and Europe.

What Are the Key Growth Pathways for the Pharmaceutical Stability & Storage Services Market?

Key growth pathways include expanding cryogenic and ultra-low temperature storage portfolios, scaling regulatory and quality service bundling, and deepening penetration into biotechnology and Asia-Pacific customer categories. NMSC's analysis indicates that providers pursuing these pathways while maintaining cost competitiveness in core stability testing categories will be best positioned to capture the Pharmaceutical Stability & Storage Services Market's projected growth through 2035.

FAQs

About the Author

Mihul Sharma

Mihul Sharma

Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Mohit Agarwal

MOHIT AGARWAL

Chief Manager

DryChem India Pvt. Ltd.

Next Move Strategy Consulting is an amazing team of consultants. We required a market study report for our investors on top priority and the team went above and beyond our expectations to deliver the same with ample supporting data within a short time span enabling us to secure the investments and keep our project timeline maintained. Their professionalism, attention to detail, and timely delivery of actionable recommendations have left a lasting impression on our organization.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Diana Trejo

DIANA TREJO

Assistant Manager

Sumitomo Corporation de Mexico, S.A. de C.V.

Recently, we purchased a report on the Mexico Data Center Market from Next Move Strategy Consulting. The service has been excellent, with support that is always timely and thoroughly professional. The information provided is interesting, highly useful, and delivered with clarity. I would highly recommend NextMSC for anyone seeking insightful and dependable analysis.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖