Retail Automation Market Global Industry Analysis and Forecast (2026–2035)

Retail Automation Market size was USD 31.12 Billion in 2025, projected to reach USD 80.39 Billion by 2035, growing at a CAGR of 9.32% from 2026 to 2035. Key drivers include accelerating adoption of autonomous checkout and fulfilment technologies, rising labor cost pressures intensifying demand for store-floor automation, and expanding deployment of AI-powered inventory and shelf intelligence systems, with North America leading the global market.
Download Free Sample PDF
Base Year (2025)
$31.12 Billion
Forecast (2035)
$80.39 Billion
CAGR (2026-2035)
9.3%
Top Country
North America

What Is the Retail Automation Market Size?
The global Retail Automation Market reached USD 31.12 Billion in 2025 and is estimated at USD 36.05 Billion in 2026, forecast to grow to USD 80.39 Billion by 2035 at a CAGR of 9.32% between 2026 and 2035. North America leads with approximately 39% revenue share in 2025, while Hardware is the dominant offering, holding around 60% of total market revenue.
Based on research conducted by NMSC, we found that sustained labor cost inflation across the U.S., Europe, and key Asia-Pacific economies is compressing retail operating margins and driving technology investment ahead of pre-2020 baselines, embedding automation as a recurring capital priority across grocery, general merchandise, and e-commerce fulfilment verticals.

Retail Automation Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast

Values in USD Billion

2025 $31.12 Billion
2025
2026 $36.05 Billion
2026
2027 $39.41 Billion
2027
2028 $43.08 Billion
2028
2029 $47.10 Billion
2029
2030 $51.49 Billion
2030
2031 $56.29 Billion
2031
2032 $61.53 Billion
2032
2033 $67.27 Billion
2033
2034 $73.54 Billion
2034
2035 $80.39 Billion
2035

Key Takeaways

By Offering: Hardware held the largest share, expanding from USD 18.67 Billion in 2025 to USD 43.41 Billion by 2035; Retail Automation Services is the fastest-growing sub-segment at 11.96% CAGR from 2026–2035.

By Technology: Barcode and Optical Scanning held the largest share, expanding from USD 5.60 Billion in 2025 to USD 10.45 Billion by 2035; Computer Vision is the fastest-growing sub-segment at 13.77% CAGR from 2026–2035.

By Deployment: Storefront held the largest share, expanding from USD 14.00 Billion in 2025 to USD 33.76 Billion by 2035; Hybrid Retail Fulfilment Facility is the fastest-growing sub-segment at 16.32% CAGR from 2026–2035.

By End User: Grocery and Supermarket held the largest share, expanding from USD 7.47 Billion in 2025 to USD 16.88 Billion by 2035; Pure E-Commerce is the fastest-growing sub-segment at 16.91% CAGR from 2026–2035.

By Sales Channel: Direct Sales held the largest share, expanding from USD 9.96 Billion in 2025 to USD 24.12 Billion by 2035; OEM and Embedded Sales is the fastest-growing channel at 13.78% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 39% revenue share in 2025, anchored by large-format grocery and general merchandise deployment.

Fastest-Growing Region: Middle East & Africa is expected to register the highest CAGR of 15.72% during 2026–2035, driven by smart retail initiatives and Vision 2030 investment.

Dominant Country: The U.S. led the market with an estimated USD 9.96 Billion in 2025, supported by concentrated grocery and e-commerce fulfilment automation spending.

Fastest-Growing Country: India is the fastest-growing major Asia-Pacific country, projected to expand from USD 1.24 Billion in 2025 at approximately 13.6% CAGR driven by rapid organized retail formation.

The Retail Automation Market presents an absolute investment opportunity of approximately USD 44.34 Billion between 2026 and 2035, representing the difference between the 2035 revenue forecast of USD 80.39 Billion and the 2026 base of USD 36.05 Billion, positioning autonomous fulfilment hardware and AI-powered store intelligence software as the key technology categories for investment consideration for retail technology investors.

According to NMSC analysis, the convergence of real-time shelf intelligence, autonomous mobile robotics, and AI-driven demand forecasting is enabling retailers to automate decision loops that previously required manual labor at every step, a structural shift that is compressing the ROI payback period for automation investment and accelerating capital commitment from both tier-one and mid-market operators in the sector.

Ecosystem Analysis of the Retail Automation Industry

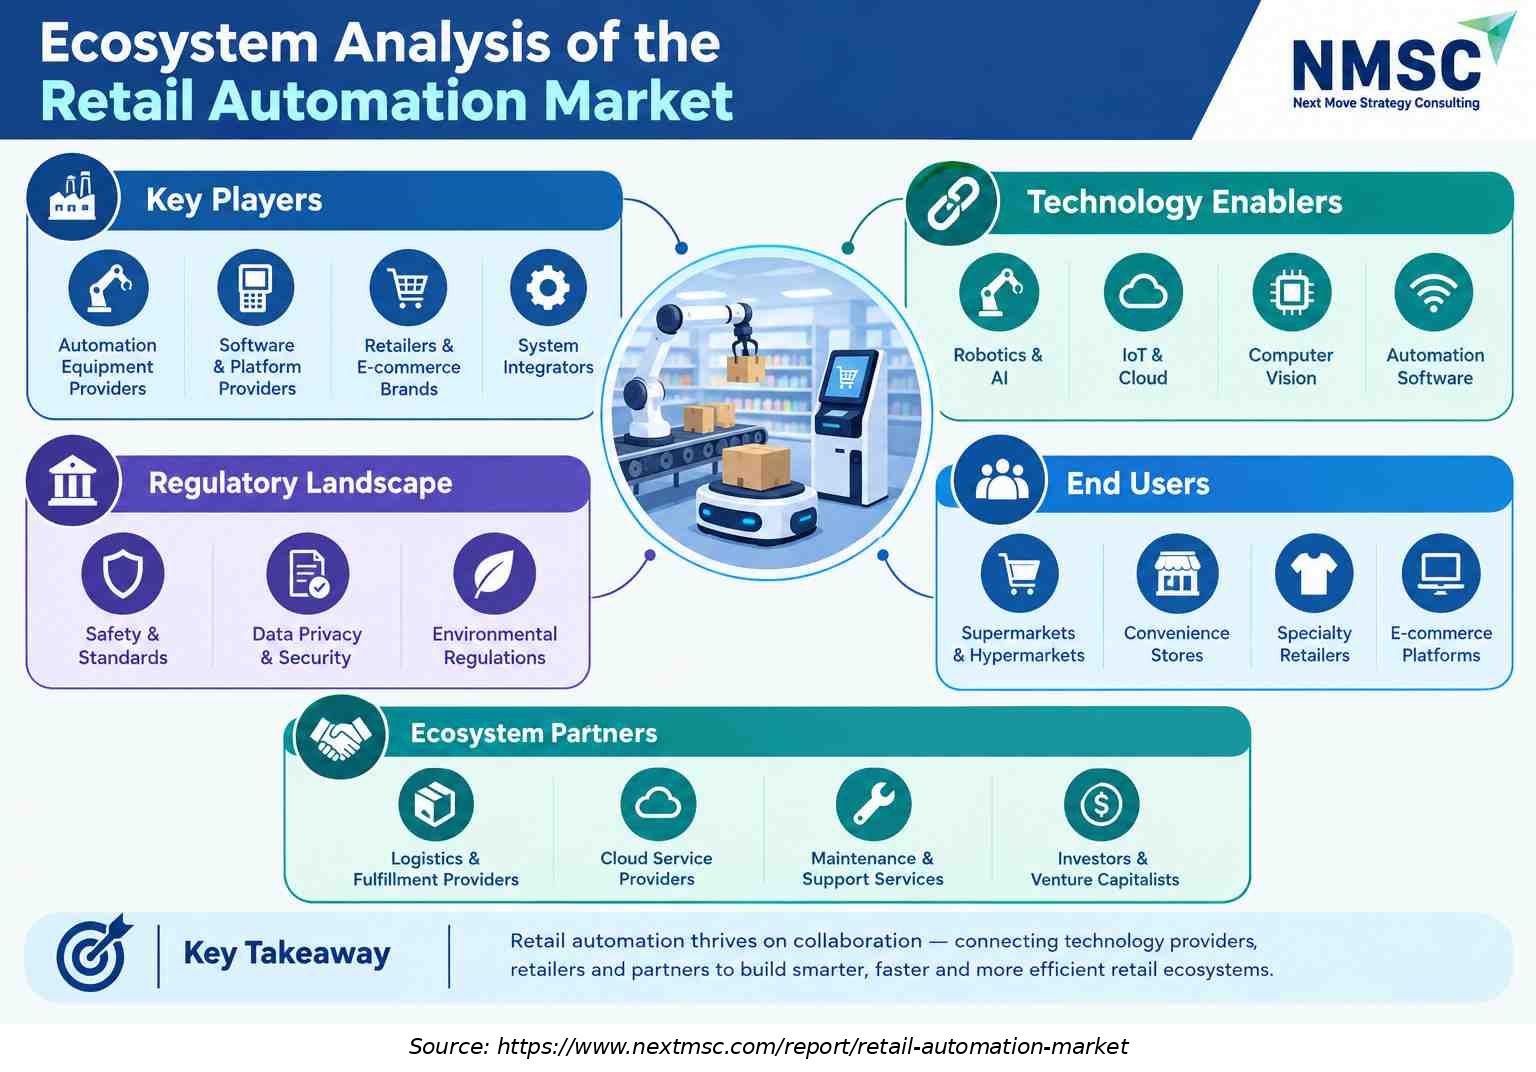
The above infographic provides a detailed ecosystem analysis of the retail automation market, mapping out key players, technology enablers, and regulatory bodies. It highlights how advancements like robotics, AI, and IoT drive efficiency across diverse end users, from supermarkets to e-commerce platforms. Supported by logistics and maintenance partners, the ecosystem navigates safety and data privacy regulations. Ultimately, the key takeaway emphasizes that retail automation thrives on collaboration to build smarter, faster, and more efficient retail environments.

What does the Retail Automation Market Encompass?

The Retail Automation Market spans hardware, software, and services deployed across storefronts, store backrooms, distribution centres, and fulfilment facilities to reduce manual task intensity, improve inventory accuracy, and accelerate transaction throughput. Demand for self-checkout systems, electronic shelf labels, RFID readers, autonomous robots, computer vision cameras, and their associated software platforms and integration services is captured within this definition. The industry has evolved from isolated barcode-scanning hardware into a networked automation layer that spans the entire retail value chain, from vendor-managed replenishment to last-yard customer fulfilment.

The regulatory environment influencing this industry centres on consumer data privacy frameworks, including the EU's General Data Protection Regulation, which shapes how computer vision and customer analytics software may collect and process in-store behavioral data. Labor law changes and minimum wage legislation across North America, Europe, and parts of Asia-Pacific are also shaping the speed of checkout and shelf-replenishment automation investment, while food safety and traceability regulations drive RFID and barcode data capture adoption in grocery and pharmacy verticals.

Market Drivers & Dynamics

Interactive Dataset
Rising labor costs and minimum wage legislation accelerating checkout and shelf automation investment driver +3.1% North America, Europe, Asia-Pacific 2026–2035
E-commerce fulfilment volume growth driving investment in robotic picking and sortation infrastructure driver +2.4% Global 2026–2035
Electronic shelf label and real-time inventory visibility deployment expanding across grocery chains driver +1.8% Europe, Asia-Pacific 2026–2033
AI-powered demand forecasting reducing shrinkage and improving in-stock rates across store formats driver +1.4% North America, Europe 2026–2031
Government smart city and digital retail modernization programs funding store technology adoption driver +0.9% Middle East & Africa, Asia-Pacific 2026–2030
High upfront capital expenditure for robotic and ASRS systems limiting mid-market adoption restraint −1.3% Global 2026–2035
Technical integration complexity between legacy POS infrastructure and new automation layers restraint −0.8% North America, Europe 2026–2032
Consumer privacy concerns constraining full deployment of computer vision analytics in-store restraint −0.6% Europe, North America 2026–2033
Shortage of qualified automation systems integration talent in emerging markets restraint −0.4% MEA, Latin America 2026–2030
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the Retail Automation Market?

Rising labor costs across major retail economies are the primary structural driver of the Retail Automation Market, compelling grocery, hypermarket, and general merchandise operators to accelerate checkout, replenishment, and fulfilment automation investments that reduce per-transaction labor cost. The U.S. Bureau of Labor Statistics reports sustained upward pressure on retail sector wages, while the European Commission's minimum wage directive is elevating labor floor costs across member states. These dual pressures are shortening ROI payback windows for supply chain management automation investments and pulling capital forward from planned multi-year deployment programs.

How Is E-Commerce Fulfilment Growth Driving the Market?

The growth of e-commerce order volumes and consumer expectations for same-day or next-day delivery is driving investment in robotic picking systems, autonomous mobile robots, automated storage and retrieval systems, and sortation infrastructure across both purpose-built fulfilment centres and converted retail distribution facilities. Our assessment indicates that pure e-commerce operators and omnichannel retailers are accelerating micro-fulfilment centre buildouts in urban markets, creating dense demand nodes for compact AMR and sortation deployments that were not part of the retail automation industry scope as recently as 2020.

Growth Inhibitors

What Is Restraining the Retail Automation Market?

The primary restraint is the high upfront capital expenditure required to deploy robotic picking systems, automated storage and retrieval systems, and computer vision networks at meaningful scale, which limits adoption among mid-market and smaller regional retail operators whose balance sheets cannot absorb the multi-million-dollar investment required before ROI materializes. We found that integration complexity with legacy point-of-sale infrastructure, inventory management systems, and workforce scheduling platforms further extends deployment timelines and increases total project cost, compressing the addressable buyer pool beyond what CAGR-level market growth statistics suggest.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Hardware
Checkout Har
Point of Sal
Self-Checkou
Self-Service
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Hardware $10.0 USD Billion $40.0 USD Billion 14.0%
Checkout Hardware $17.1 USD Billion $51.1 USD Billion 8.0%
Point of Sale Terminals $24.2 USD Billion $62.2 USD Billion 14.0%
Self-Checkout Systems $31.3 USD Billion $73.3 USD Billion 20.0%
Self-Service Kiosks $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for Offering.

Unlock Full Data

Which Offering Segment Dominates the Retail Automation Market?

Hardware dominates with USD 18.67 Billion in 2025, reflecting the capital intensity of deploying checkout hardware, RFID infrastructure, autonomous robots, electronic shelf labels, and warehouse automated storage and retrieval system equipment across large retail store networks. Retail Automation Services is the fastest-growing offering at 11.96% CAGR, driven by rising enterprise demand for managed automation infrastructure, remote monitoring, and continuous workflow optimisation services that sustain deployment performance and expand automation scope over time without requiring proportional growth in internal IT headcount.

2025 (USD Billion)
2035 (USD Billion)
Barcode and
RFID
Electronic P
Computer Vis
Robotics and
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Barcode and Optical Scanning $10.0 USD Billion $40.0 USD Billion 25.0%
RFID $17.1 USD Billion $51.1 USD Billion 11.0%
Electronic Paper and Electronic Shelf Labels $24.2 USD Billion $62.2 USD Billion 25.0%
Computer Vision $31.3 USD Billion $73.3 USD Billion 11.0%
Robotics and Autonomous Navigation $38.4 USD Billion $84.4 USD Billion 16.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for Technology.

Unlock Full Data

Which Technology Segment Leads and Which Is Growing Fastest?

Barcode and Optical Scanning is the largest technology segment at USD 5.60 Billion in 2025, reflecting the decades-long installed base of scanning hardware across virtually every retail format globally. Computer Vision is the fastest-growing technology at 13.77% CAGR, expanding from USD 2.49 Billion in 2025 to USD 9.03 Billion by 2035 as shelf monitoring, loss prevention, and customer analytics applications multiply beyond traditional checkout contexts. The convergence of machine learning inference with edge-deployed camera hardware is lowering the per-insight cost of computer vision analytics and accelerating ROI for retail operators evaluating first-time deployments.

2025 (USD Billion)
2035 (USD Billion)
Storefront
Store Backro
Retail Distr
Retail Fulfi
Hybrid Retai
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Storefront $10.0 USD Billion $40.0 USD Billion 27.0%
Store Backroom $17.1 USD Billion $51.1 USD Billion 9.0%
Retail Distribution Centre $24.2 USD Billion $62.2 USD Billion 19.0%
Retail Fulfilment Centre $31.3 USD Billion $73.3 USD Billion 17.0%
Hybrid Retail Fulfilment Facility $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for Deployment.

Unlock Full Data

Which Deployment Segment Dominates and Which Is Fastest-Growing?

Storefront leads all deployment environments at USD 14.00 Billion in 2025, encompassing self-checkout kiosks, electronic shelf labels, RFID readers, computer vision cameras, and payment hardware deployed on the selling floor where customer-facing ROI is most directly measurable. Hybrid Retail Fulfilment Facility is the fastest-growing deployment at 16.32% CAGR, as omnichannel retailers convert portions of retail floor space into micro-fulfilment operations combining sortation systems, AMRs, and picking automation to fulfill online orders at store proximity, compressing delivery windows without adding standalone warehouse footprint.

2025 (USD Billion)
2035 (USD Billion)
Grocery and
Hypermarket
Convenience
Department S
General Merc
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Grocery and Supermarket $10.0 USD Billion $40.0 USD Billion 14.0%
Hypermarket and Warehouse Club $17.1 USD Billion $51.1 USD Billion 24.0%
Convenience and Fuel $24.2 USD Billion $62.2 USD Billion 22.0%
Department Store $31.3 USD Billion $73.3 USD Billion 12.0%
General Merchandise Store $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for End User.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct Sales
Distributor
Systems Inte
OEM and Embe
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Sales $10.0 USD Billion $40.0 USD Billion 24.0%
Distributor Sales $17.1 USD Billion $51.1 USD Billion 22.0%
Systems Integrator Sales $24.2 USD Billion $62.2 USD Billion 20.0%
OEM and Embedded Sales $31.3 USD Billion $73.3 USD Billion 22.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for Sales Channel.

Unlock Full Data

Supply Chain Analysis of the Retail Automation Industry

Supply Chain Analysis of the Retail Automation Industry
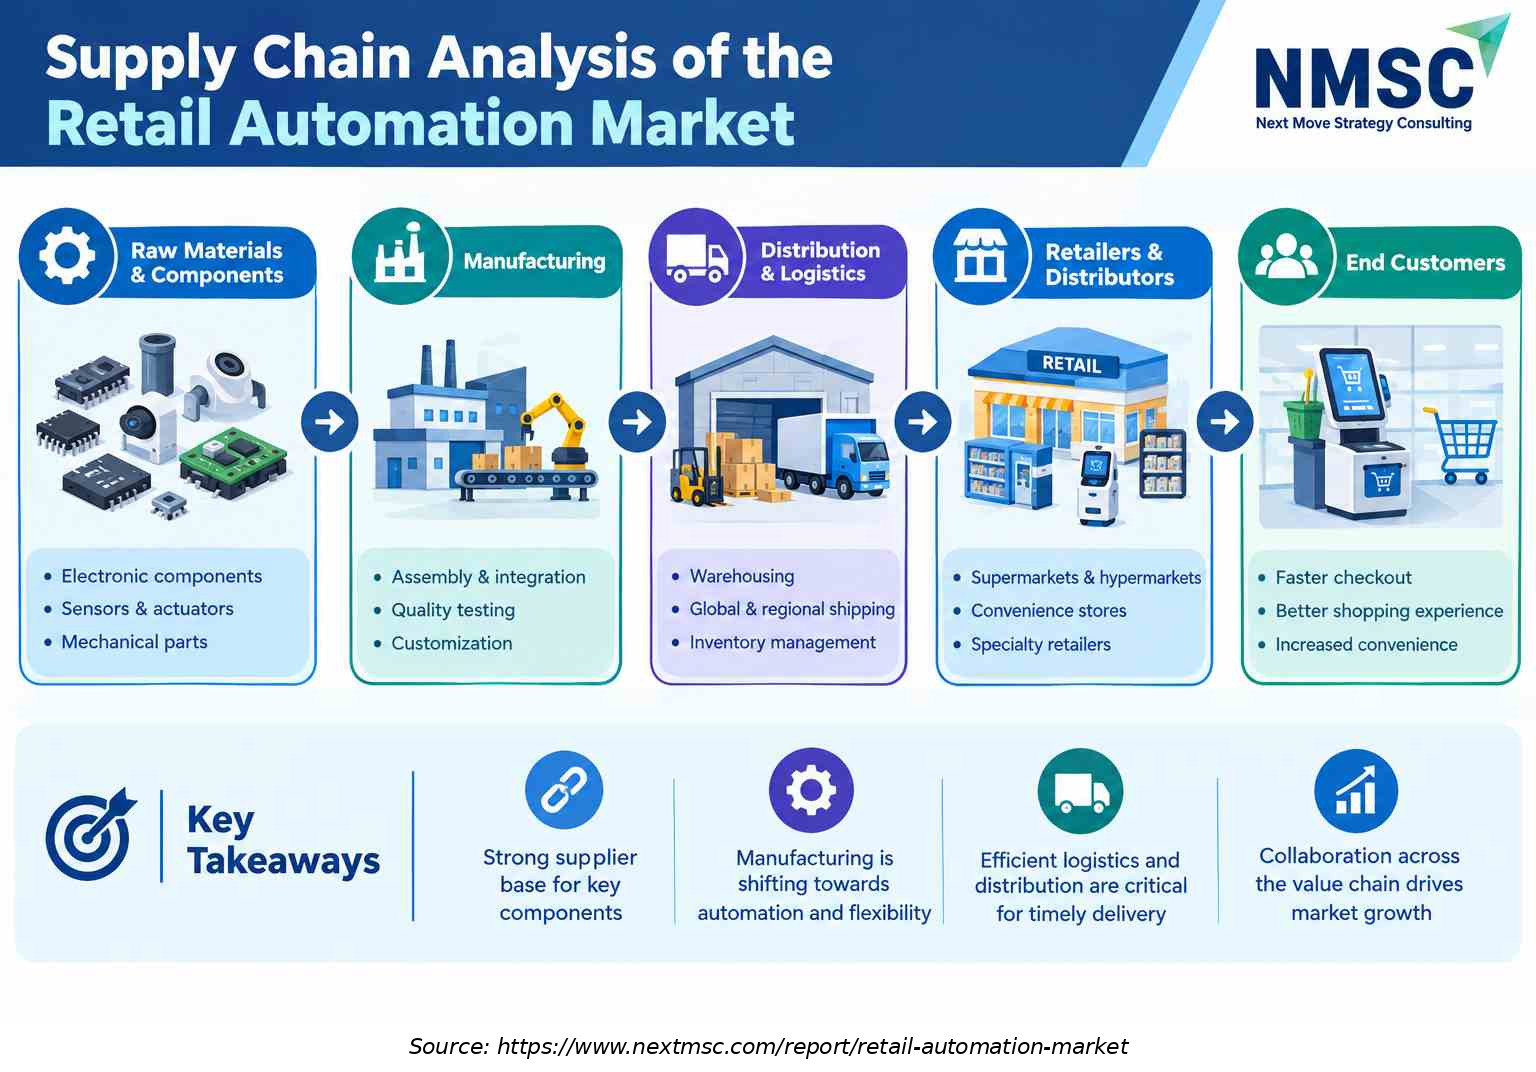
The above infographic provides a detailed supply chain analysis of the retail automation market, outlining a five-step flow from raw materials to end customers. It traces the process from electronic components and manufacturing through distribution to retailers and final consumers. The analysis highlights that manufacturing is shifting toward automation and flexibility to meet demand. Ultimately, it concludes that a strong supplier base, efficient logistics, and collaboration across the value chain are essential for driving market growth and enhancing the customer experience.

Growth Opportunities

Our analysis shows that three structural whitespace opportunities stand out for vendors positioning to capture disproportionate share of the market's USD 44.34 Billion absolute growth window between 2026 and 2035.

Can Mid-Market Retailers Unlock Adoption Through Software-Led Automation Bundles?

Mid-market grocery and general merchandise operators currently underserved by capital-intensive hardware-first automation deployments represent a large latent demand pool addressable through SaaS-based automation software bundles combining warehouse management system capabilities, demand forecasting, and ESL management into a single subscription model. This opportunity benefits the Software offering segment and the Systems Integrator Sales channel, as deployment complexity management shifts to channel partners who can standardize implementation for operators with limited internal IT resources.

Does Pharmacy and Grocery Automation Investment Signal a Durable Vertical Opportunity?

Pharmacy and Health is projecting an 11.13% CAGR through 2035, driven by regulatory requirements for medication dispensing accuracy, rising script volumes, and labor shortages in licensed pharmacy technician roles. Grocery operators deploying RFID for food safety traceability alongside ESL networks for regulatory price labeling compliance are creating multi-year upgrade cycles for hardware and software vendors. Both verticals represent structured budget pools with compliance-driven procurement timelines that provide more predictable demand visibility than general merchandise refresh cycles.

Can Pure E-Commerce Fulfilment Automation Create a Distinct Hardware and Services Market?

Pure E-Commerce is the fastest-growing end-user segment at 16.91% CAGR, as digital-native retailers scaling to meaningful order volumes reach the economic threshold where robotic picking, autonomous storage, and conveyor-based sortation deliver measurable cost advantage over manual fulfilment operations. This opportunity primarily benefits the Robotics and Autonomous Navigation technology segment and the Retail Fulfilment Centre and Hybrid Retail Fulfilment Facility deployment environments, where purpose-built automation investment is most concentrated and where systems integrator sales channels capture the largest deal sizes.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Asia-Pacific
Europe
Latin Americ
Middle East
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Asia-Pacific $17.1 USD Billion $51.1 USD Billion 27.0%
Europe $24.2 USD Billion $62.2 USD Billion 25.0%
Latin America $31.3 USD Billion $73.3 USD Billion 23.0%
Middle East & Africa $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

Our assessment indicates that the competitive landscape spans hardware platform leaders, autonomous robotics specialists, software and analytics providers, and managed services integrators, all competing on technology differentiation, enterprise account depth, and geographic expansion within the Retail Automation Market industry.

Dimension Description
Market Structure Moderately fragmented with distinct competitive clusters spanning checkout hardware, robotic fulfilment systems, ESL networks, and store intelligence software; no single vendor commands cross-category dominance
Innovation Focus Autonomous mobile robotics integration with warehouse execution software, AI-powered computer vision for loss prevention and shelf compliance, and ESL-as-a-platform for shelf communication and analytics
M&A Activity Targeted acquisitions to build software-hardware integration capability; strategic partnerships between AMR vendors and platform software providers to accelerate full-stack retail automation offerings

How Do Companies Compete in the Retail Automation Industry?

Companies compete primarily on integration depth between hardware and software layers, proven ROI documentation at reference retail accounts, and system integration service capability that reduces deployment risk for retail IT decision-makers evaluating multi-million-dollar automation investments. We found that vendors who can demonstrate end-to-end ownership from device hardware through analytics software and managed operations services are capturing larger total contract values than hardware-only or software-only competitors across the Retail Automation Market.

Which Competitive Archetypes Dominate the Market?

Diversified automation platform vendors including NCR Voyix, Zebra Technologies, and Diebold Nixdorf dominate through broad hardware and software portfolio coverage across checkout, identification, and store intelligence categories. Robotic fulfilment specialists including Symbotic, AutoStore, and Dematic compete through proprietary autonomous system architectures with deep system integrator partnerships. ESL and digital shelf specialists including VusionGroup, Hanshow, and Pricer differentiate on ESL network scale, shelf communication intelligence, and robotic process automation integration capabilities that connect shelf data to replenishment and pricing workflows.

What Innovation and Differentiation Strategies Are Companies Pursuing?

We observed that leading companies are converging hardware and software investment toward AI-native automation platforms that generate continuous operational data streams from deployed devices, creating recurring analytics and managed services revenue alongside traditional hardware replacement cycles. Differentiation increasingly centers on the breadth of retail workflow coverage a vendor can automate from a single platform, from demand forecasting through shelf sensing, order generation, picking, and checkout, positioning full-stack capability as the primary barrier to competitive displacement among enterprise retail accounts.

What M&A and Partnership Activity Is Shaping the Retail Automation Market?

Our findings suggest that the competitive landscape is consolidating through targeted acquisitions of software analytics and AI capability by hardware-centric vendors seeking to build recurring revenue models, alongside strategic AMR-to-software partnerships between robotics specialists and warehouse execution software providers. KNAPP's and Vanderlande's integration services investment reflects the systems integrator model's continued importance in converting hardware shipments into multi-year services contracts, particularly for large distribution centre and fulfilment facility deployments where ongoing optimisation services carry strong margin profiles.

Key Market Players

We observed that the following companies represent the validated set of primary participants across hardware, software, and services categories, ranked by estimated market influence and portfolio breadth within the Retail Automation Market.

NCR Voyix Corporation VusionGroup SA Zebra Technologies Corporation Diebold Nixdorf, Incorporated Toshiba Tec Corporation Dematic Corp. KNAPP AG Vanderlande Industries B.V. SSI SCHAEFER GMBH & CO KG Blue Yonder Group, Inc. Manhattan Associates, Inc. Brady Corporation Symbotic Inc. AutoStore Holdings Ltd. Datalogic S.p.A. Geekplus Technology Co., Ltd. Hanshow Technology Co., Ltd. Pricer AB SOLUM CO., LTD. Checkpoint Systems, Inc.

Latest Developments

During our market evaluation, we noticed that 2025–2026 activity reflects an accelerating convergence between robotic hardware platforms and AI-powered software layers, with major vendors prioritizing platform integration breadth over standalone product launches.

Date Event
September 2026 Asda completed deployment of Vusion’s electronic shelf-edge labels across all 517 Express stores, installing approximately 1.2 million labels. The rollout eliminates manual replacement of more than 120,000 paper price tickets weekly, while Vusion shelf-edge cameras are also being trialed for automated availability and out-of-stock detection.
June 2026 Footasylum selected AutoStore and THG Fulfil for an automated fulfillment system incorporating 85 R5 robots, more than 96,000 bin locations, and 24 carousel ports.
June 2026 Dematic partnered with Pattison Food Group to automate its 485,000-square-foot grocery distribution center in British Columbia. The solution includes nearly 62,000 automated storage locations, 16 goods-to-person workstations, and integrated handling and sequencing technologies supporting approximately 11,000 grocery SKUs across nine retail banners.
April 2026 Pricer and JRTech Solutions signed an approximately USD 51 million agreement with Canadian supermarket chain Sobeys covering electronic shelf labels and store infrastructure across an estimated 300–350 stores.
January 2025 Symbotic completed its acquisition of Walmart’s Advanced Systems and Robotics business and signed an agreement to develop and deploy automated systems for Walmart’s Accelerated Pickup and Delivery centers.

Expert Insights

David Barker

President of Honeywell Productivity Solutions and Services | Honeywell

"We are truly in the midst of a new era for the retail sector where evolving AI capabilities will make a positive impact on the shopper's journey, the employee experience and the retailer's supply chain operation. On their journey toward autonomous operations, retailers are looking for AI and automation solutions that provide actionable data and help to upskill their employees."

Analyst Interpretation

We observed that this perspective directly supports the increasing integration of AI, robotics, data intelligence, and automated workflows across retail operations. NMSC’s analysis indicates that the transition toward autonomous retail operations is expanding demand for automated inventory management, smart checkout systems, warehouse automation, computer vision, robotics, and AI-enabled retail analytics. The growing emphasis on actionable real-time data is also shifting retail automation from isolated task-based solutions toward integrated systems that simultaneously improve operational efficiency, employee productivity, inventory visibility, and shopper experiences.

Investment Opportunities

Can Mid-Market Retailers Unlock Adoption Through Software-Led Automation Bundles?

Mid-market grocery and general merchandise operators currently underserved by capital-intensive hardware-first automation deployments represent a large latent demand pool addressable through SaaS-based automation software bundles combining warehouse management system capabilities, demand forecasting, and ESL management into a single subscription model. This opportunity benefits the Software offering segment and the Systems Integrator Sales channel, as deployment complexity management shifts to channel partners who can standardize implementation for operators with limited internal IT resources.

Does Pharmacy and Grocery Automation Investment Signal a Durable Vertical Opportunity?

Pharmacy and Health is projecting an 11.13% CAGR through 2035, driven by regulatory requirements for medication dispensing accuracy, rising script volumes, and labor shortages in licensed pharmacy technician roles. Grocery operators deploying RFID for food safety traceability alongside ESL networks for regulatory price labeling compliance are creating multi-year upgrade cycles for hardware and software vendors. Both verticals represent structured budget pools with compliance-driven procurement timelines that provide more predictable demand visibility than general merchandise refresh cycles.

Can Pure E-Commerce Fulfilment Automation Create a Distinct Hardware and Services Market?

Pure E-Commerce is the fastest-growing end-user segment at 16.91% CAGR, as digital-native retailers scaling to meaningful order volumes reach the economic threshold where robotic picking, autonomous storage, and conveyor-based sortation deliver measurable cost advantage over manual fulfilment operations. This opportunity primarily benefits the Robotics and Autonomous Navigation technology segment and the Retail Fulfilment Centre and Hybrid Retail Fulfilment Facility deployment environments, where purpose-built automation investment is most concentrated and where systems integrator sales channels capture the largest deal sizes.

Where Are Capital Inflows Concentrating in the Retail Automation Market?

Capital inflows are concentrating in autonomous fulfilment robotics, AI-powered store intelligence software, and electronic shelf label network infrastructure, as evidenced by Symbotic's multi-year Walmart deployment commitment, VusionGroup's continued ESL platform investment, and Blue Yonder's AI demand forecasting product roadmap announced through 2025. These investment concentrations reflect venture and corporate capital confidence that automation ROI is now sufficiently documented at enterprise scale to justify accelerated deployment timelines and higher per-site capital allocation.

How Is Infrastructure Investment Shaping Market Capacity?

Infrastructure investment is shifting toward AI inference hardware deployed at the edge within retail stores and fulfilment centres, as real-time computer vision, RFID sensing, and AMR navigation processing requirements exceed the latency tolerance for cloud-round-trip architectures. This shift benefits vendors with proprietary edge compute platforms integrated with their hardware deployments, improving long-term account stickiness. Payment gateway infrastructure investment is also expanding within the Retail Automation Market as frictionless checkout experiences require deeper integration between payment processing layers and self-checkout hardware management platforms.

What ESG Considerations Are Influencing Market Investment?

Environmental, Social, and Governance considerations in the Retail Automation Market center on food waste reduction through AI-driven demand forecasting, energy efficiency improvements from optimised fulfilment routing, and equitable labor transition programs for workers displaced by automation technology. We found that institutional investors are increasingly evaluating retail automation vendors on their ability to document Scope 3 emissions reductions enabled by their technology and to demonstrate community impact programs that address workforce transition responsibilities alongside pure commercial growth metrics.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders?

Retail operators and technology vendors gain segment-level revenue forecasts and CAGR benchmarks across offering, technology, deployment, end-user, and sales channel axes, enabling capital allocation decisions grounded in the consistent 2025–2035 figures used throughout this analysis. Our regional growth differential findings support market-entry and enterprise account strategy decisions for hardware manufacturers, software platform vendors, and managed automation services providers seeking to prioritize geographic and vertical investments within the Retail Automation Market.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts gain a reconciled market-sizing model, competitive landscape assessment, and named-company development tracking that supports valuation and capital-allocation decisions across the retail technology sector. The Growth Catalyst & Risk Assessment Matrix quantifies driver and restraint impact on CAGR, enabling scenario modeling and portfolio positioning across hardware, software, and services revenue streams for retail automation technology companies at different stages of platform maturity.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain visibility into which technology and deployment segments, notably Computer Vision and Hybrid Retail Fulfilment Facility, are growing fastest, informing engineering investment and go-to-market prioritization through 2035. The end-user industry segmentation across grocery, pharmacy, e-commerce, and specialty retail axes provides actionable vertical-specific product roadmap evidence, while the competitive landscape analysis identifies the platform integration depth and managed services capability that enterprise retail buyers are treating as baseline requirements in the market.

Key Market Segments Evaluated

By Offering

  • Hardware 
    • Checkout Hardware
      • Point of Sale Terminals
      • Self-Checkout Systems
      • Self-Service Kiosks
      • Payment Checkout Hardware
      • Checkout Scales
      • Receipt and Cash Handling Hardware
    • Identification and Data Capture Hardware
      • Barcode Scanners
      • RFID Readers
      • RFID Tags and Labels
      • Mobile Computers
      • Label and Barcode Printers
      • Automated Scan Portals
    • Shelf and Pricing Hardware
      • Electronic Shelf Labels
      • Digital Shelf Displays
      • Shelf Sensors
      • Shelf Communication Devices
    • Store Sensing and Security Hardware
      • Computer Vision Cameras
      • Electronic Article Surveillance Hardware
      • Smart Carts
      • Inventory Scanning Robots
      • Customer Service Robots
    • Fulfilment and Material Handling Hardware
      • Automated Storage and Retrieval Systems
      • Autonomous Mobile Robots
      • Automated Guided Vehicles
      • Conveyors
      • Sortation Systems
      • Robotic Picking Systems
      • Robotic Palletising Systems
    • Other Retail Automation Hardware
  • Software 
    • Checkout and Transaction Software
      • Point of Sale Software
      • Self-Checkout Software
      • Mobile Checkout Software
      • Transaction Orchestration Software
    • Inventory and Replenishment Software
      • Store Inventory Management Software
      • Inventory Visibility Software
      • Replenishment Automation Software
      • Store Demand Forecasting and Ordering Software
    • Order and Fulfilment Software
      • Retail Order Management Software
      • Order Orchestration Software
      • Store Fulfilment Software
      • Warehouse Execution Software
    • Shelf and Pricing Software
      • Electronic Shelf Label Management Software
      • Price Management Software
      • Promotion Execution Software
      • Shelf Workflow Software
    • Store Intelligence Software
      • Computer Vision Analytics Software
      • Loss Prevention Analytics Software
      • Shelf Monitoring Software
      • Store Performance Analytics Software
    • Workforce and Workflow Software
      • Task Management Software
      • Guided Work Software
      • Associate Workflow Software
      • Store Process Automation Software
    • Device and Automation Management Software
      • Device Management Software
      • Robot Fleet Management Software
      • Automation Monitoring Software
      • Automation Control Software
      • Automation Orchestration Software
  • Retail Automation Services 
    • Deployment and Integration Services
      • Installation Services
      • Configuration Services
      • Implementation Services
      • Systems Integration Services
    • Maintenance and Support Services
      • Preventive Maintenance Services
      • Repair Services
      • Technical Support Services
      • Software Support Services
    • Managed Automation Services
      • Managed Device Services
      • Managed Software Operations
      • Remote Monitoring Services
      • Managed Automation Infrastructure
    • Optimisation Services
      • Automation Optimisation Services
      • Workflow Optimisation Services
      • Performance Tuning Services
      • Automation Training Services

By Technology

  • Barcode and Optical Scanning
  • RFID
  • Electronic Paper and Electronic Shelf Labels
  • Computer Vision
  • Robotics and Autonomous Navigation
  • IoT and Sensors
  • Payment and Near Field Communication
  • Artificial Intelligence and Machine Learning
  • Other Identifiable Technologies

By Deployment

  • Storefront
  • Store Backroom
  • Retail Distribution Centre
  • Retail Fulfilment Centre
  • Hybrid Retail Fulfilment Facility

By End User

  • Grocery and Supermarket
  • Hypermarket and Warehouse Club
  • Convenience and Fuel
  • Department Store
  • General Merchandise Store
  • Apparel and Footwear
  • Home Improvement
  • Consumer Electronics
  • Pharmacy and Health
  • Pure E-Commerce
  • Other Speciality Retail

By Sales Channel

  • Direct Sales
  • Distributor Sales
  • Systems Integrator Sales
  • OEM and Embedded Sales

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook for the Retail Automation Market is structurally positive, with revenue expanding from USD 36.05 Billion in 2026 to USD 80.39 Billion by 2035 at a 9.32% CAGR, underpinned by durable labor cost pressures, sustained e-commerce fulfilment investment, and expanding AI capability embedded in store hardware and software platforms. We observed that this growth trajectory reflects fundamental retail operating model changes rather than a cyclical technology refresh wave, suggesting that capital commitment will remain elevated even through periods of broader macroeconomic softness.
What Strategic Positioning Recommendations Does NMSC Offer?

Vendors should prioritize building full-stack platform capability spanning sensing hardware, AI analytics, and managed services, as enterprise retail buyers are demonstrating strong preference for ecosystem vendors over point-solution suppliers. Companies lacking software or managed services capability should pursue targeted acquisitions or deep partnership integrations rather than hardware-only growth strategies, given the Retail Automation Market's structural shift toward recurring revenue models that enterprise procurement organizations are increasingly factoring into their vendor selection criteria.

How Attractive Is the Retail Automation Market for Investment?

Investment attractiveness is high across the Retail Automation Market, with the USD 44.34 Billion absolute growth opportunity between 2026 and 2035 providing ample room for both incumbent platform leaders and specialized category vendors to achieve meaningful revenue growth. Middle East & Africa at 15.72% CAGR and Latin America at 13.77% CAGR offer the highest relative growth rates, while North America provides the largest absolute revenue base and the most mature enterprise buyer pool with documented automation ROI benchmarks that de-risk capital deployment decisions.

What Are the Key Market Shifts and Risks in the Market?

Key market shifts include the transition from standalone automation deployments to interconnected automation ecosystems, and from one-time hardware sales to recurring managed services and software subscription models. Primary risks include capital expenditure concentration among large-format grocery and e-commerce operators that creates significant contract concentration risk for tier-one vendors, and technical integration complexity that extends deployment timelines and increases total project cost, particularly in markets where system integration talent is constrained relative to demand growth.

What Are the Primary Growth Pathways for the Market Through 2035?

Primary growth pathways include autonomous fulfilment robotics deployment in pure e-commerce and hybrid omnichannel environments, computer vision-based store intelligence expansion beyond security into operational analytics, and ESL network scaling into additional retail verticals beyond grocery. We found that vendors combining all three pathways, hardware, AI analytics, and services, are best positioned to capture disproportionate share of the USD 44.34 Billion absolute opportunity through 2035, particularly in Asia-Pacific, Latin America, and the Middle East & Africa where first-time adoption cycles are still early relative to the full addressable population of retail operators.
Frequently Asked Questions
1. What is the Retail Automation Market size in 2026?
The Retail Automation Market is estimated at USD 36.05 Billion in 2026.
2. What is the Retail Automation Market revenue forecast for 2035?
The Retail Automation Market is forecast to reach USD 80.39 Billion by 2035.
3. What is the CAGR of the Retail Automation Market from 2026 to 2035?
The Retail Automation Market is projected to grow at a CAGR of 9.32% from 2026 to 2035.
4. Which technology segment dominates the Retail Automation Market?
Barcode and Optical Scanning dominate with approximately 18% of the Retail Automation Market in 2025 at USD 5.60 Billion, reflecting the mature installed base of scanning hardware across virtually all retail formats globally.
5. Which technology segment is growing fastest in the Market?
Computer Vision is the fastest-growing technology segment, expanding at a 13.77% CAGR from 2026 to 2035, driven by loss prevention, shelf monitoring, and customer analytics applications multiplying across large-format retail environments.
6. Which region dominates the Retail Automation Market?
North America dominates with approximately 39% share of the Retail Automation Market in 2025 at USD 12.14 Billion, supported by concentrated grocery, warehouse club, and e-commerce fulfilment automation investment.
7. Which region is growing fastest in the Retail Automation Market?
The Middle East & Africa region is the fastest-growing, expanding at a 15.72% CAGR from 2026 to 2035, driven by smart retail initiatives, Vision 2030 programs, and organized retail expansion across the region.
8. Which country leads the Retail Automation Market?
The U.S. leads the Retail Automation Market with an estimated USD 9.96 Billion in 2025, anchored by large-format retail operators deploying self-checkout, robotic fulfilment, and AI inventory systems at scale.
9. Who are the key players in the Retail Automation Market?
Key players include NCR Voyix Corporation, VusionGroup SA, Zebra Technologies Corporation, Diebold Nixdorf, Incorporated, Toshiba Tec Corporation, and Dematic Corp., among 20 companies profiled in this report.
10. What are the primary growth drivers for the Retail Automation Market?
Rising labor costs accelerating checkout and fulfilment automation investment and e-commerce order volume growth driving robotic infrastructure deployment are the primary growth drivers, contributing an estimated +3.1% and +2.4% impact on CAGR respectively.
11. What is restraining Retail Automation Market growth?
High upfront capital expenditure for robotic and automated storage systems and technical integration complexity with legacy POS infrastructure are the primary restraints, with an estimated combined impact of approximately −2.1% on CAGR.
12. What opportunities exist in the Retail Automation Market?
Mid-market software-led automation bundles, pharmacy and grocery vertical compliance-driven investment, and pure e-commerce fulfilment automation represent the primary addressable opportunities within the USD 44.34 Billion absolute growth window between 2026 and 2035.
13. How is AI impacting the Retail Automation Market?
AI is transforming the sector by embedding demand forecasting, shelf compliance monitoring, loss prevention analytics, and autonomous task management into integrated retail operations platforms, reducing the need for manual intervention across previously labor-intensive workflows and enabling automated decision loops from sensing to execution.
14. What regulatory environment shapes the Retail Automation Market?
Data privacy regulations including the EU's General Data Protection Regulation are shaping how computer vision analytics software is deployed in stores, while labor law changes and minimum wage legislation across North America and Europe are accelerating the ROI case for checkout and shelf automation investment.
15. What is the U.S. Retail Automation Market size?
The U.S. Retail Automation Market was valued at approximately USD 9.96 Billion in 2025 and is projected to reach USD 23.51 Billion by 2035 at a CAGR near 9.0%.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market & Revenue Analysis
  • Historical revenue and installed-base analysis of retail automation solutions by offering, technology, and deployment mode.
  • Identifies high-growth offerings and technologies to prioritize investment and portfolio focus.
Company-Level Solution Revenue Share Analysis
  • Company-level revenue and share benchmarking across hardware, software, and services offerings and automation solution categories.
  • Highlights vendor positioning and white-space segments for competitive strategy and partnerships.
Country-Level Trade Assessment
  • Country-wise import and export analysis of retail automation hardware such as POS terminals, kiosks, scanners, RFID readers, and robotics.
  • Supports sourcing, localization, and distribution decisions across key regional markets.
Retailer Automation Adoption Mapping
  • Adoption mapping of self-checkout, smart shelves, inventory robotics, and automated fulfillment by retail end user and deployment model.
  • Pinpoints retailer formats with the highest automation readiness for targeted customer acquisition.
Deployment Economics and ROI Benchmarking
  • Comparative cost, payback, and labor-productivity benchmarking of cloud versus on-premise automation deployments by retailer type, using public case studies and retailer filings.
  • Strengthens pricing, business-case, and deployment-model strategy for vendor sales teams.
Sales Channel and Go-to-Market Assessment
  • Assessment of direct, system integrator, reseller, and distributor channel roles in retail automation sales by technology and region.
  • Guides channel partner selection and go-to-market design for faster regional expansion.

FAQs

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖