Seeds Market

Seeds Market size was USD 77.50 Billion in 2025, projected to reach USD 143.47 Billion by 2035, growing at a CAGR of 6.11% from 2026 to 2035. Key drivers include rising global food demand, gene-edited and climate-resilient varieties, biological seed treatments, and hybrid seed adoption, with Asia-Pacific leading the market

Download Free Sample PDF
Base Year (2025)
$77.50 Billion
Forecast (2035)
$143.47 Billion
CAGR (2026-2035)
6.1%
Top Country
Asia-Pacific

What Is the Seeds Market Size?

The global seeds market size was valued at USD 77.50 Billion in 2025 and is estimated to grow from USD 84.10 Billion in 2026 to USD 143.47 Billion by 2035, expanding at a CAGR of 6.11% between 2026 and 2035. Asia-Pacific led the seeds market with an approximate 32% revenue share in 2025, while Field Crops remained the dominant crop-type segment with an approximate 58% share of global revenue.

We observed that the seeds market's momentum is best captured through a concise set of indicators before deeper analysis follows.

Seeds Market Revenue Forecast

Values in USD Billion

2025 $77.50 Billion
2025
2026 $82.24 Billion
2026
2027 $87.26 Billion
2027
2028 $92.59 Billion
2028
2029 $98.25 Billion
2029
2030 $104.25 Billion
2030
2031 $110.62 Billion
2031
2032 $117.38 Billion
2032
2033 $124.55 Billion
2033
2034 $132.16 Billion
2034
2035 $143.47 Billion
2035

Key Takeaways

By Crop Type: Field Crops held the largest share, increasing from USD 44.95 billion in 2025 to USD 77.47 billion by 2035; Flower and Ornamental Seeds is the fastest-growing sub-segment at a CAGR of 8.71% from 2026–2035.

By Breeding Method: Hybrid held the largest share, increasing from USD 50.38 billion in 2025 to USD 100.43 billion by 2035; Hybrid is also the fastest-growing sub-segment at a CAGR of 7.15% from 2026–2035.

By Genetic Technology: Conventional Breeding held the largest share, increasing from USD 54.25 billion in 2025 to USD 86.08 billion by 2035; Gene Edited is the fastest-growing sub-segment at a CAGR of 14.15% from 2026–2035.

Dominant Region: Asia-Pacific dominated, increasing from USD 24.80 billion in 2025 to USD 48.78 billion by 2035.

Fastest-Growing Region: Latin America is expected to register the highest CAGR of 9.16% during 2026–2035.

Dominant Country: China was the largest single national contributor within the Asia-Pacific region.

Fastest-Growing Country: Brazil is the fastest-growing country, with its CAGR outpacing the regional Latin America average.

Market Opportunity: The seeds market is projected to generate an incremental revenue opportunity of approximately USD 59.37 Billion between 2026 and 2035, reflecting the absolute dollar gap between the 2035 forecast and the 2026 base value a signal of sustained investment in gene-edited and climate-resilient variety development.

According to NMSC analysis, gene-edited seed varieties are transitioning from pilot commercialization to broader field deployment faster than genetically modified seeds did at a comparable stage, a dynamic not fully captured in aggregate revenue figures but material to future genetic-technology mix.

What Does the Seeds Market Encompass?

The seeds market encompasses commercial seed for field crops, vegetables, forage, turf, and flower and ornamental applications, produced through hybrid and non-hybrid breeding methods and sold across conventional, genetically modified, and gene-edited genetic technology categories. Our assessment indicates that the market's scope spans germplasm development, variety breeding, seed multiplication, treatment, and certification, with revenue realized through direct-to-grower, wholesale, dealer and retail, and government and institutional distribution channels worldwide.

Structurally, the market has evolved from open-pollinated farm-saved seed toward hybrid and biotechnology-enhanced varieties bred for yield, stress tolerance, and pest resistance. We found that regulatory environments administered by national plant variety protection authorities and biosafety regulators continue to shape genetically modified and gene-edited seed commercialization timelines, while technology adoption trends in genomic selection and precision breeding are compressing variety development cycles across nearly every crop category.

Ecosystem Analysis of the Global Seeds Market

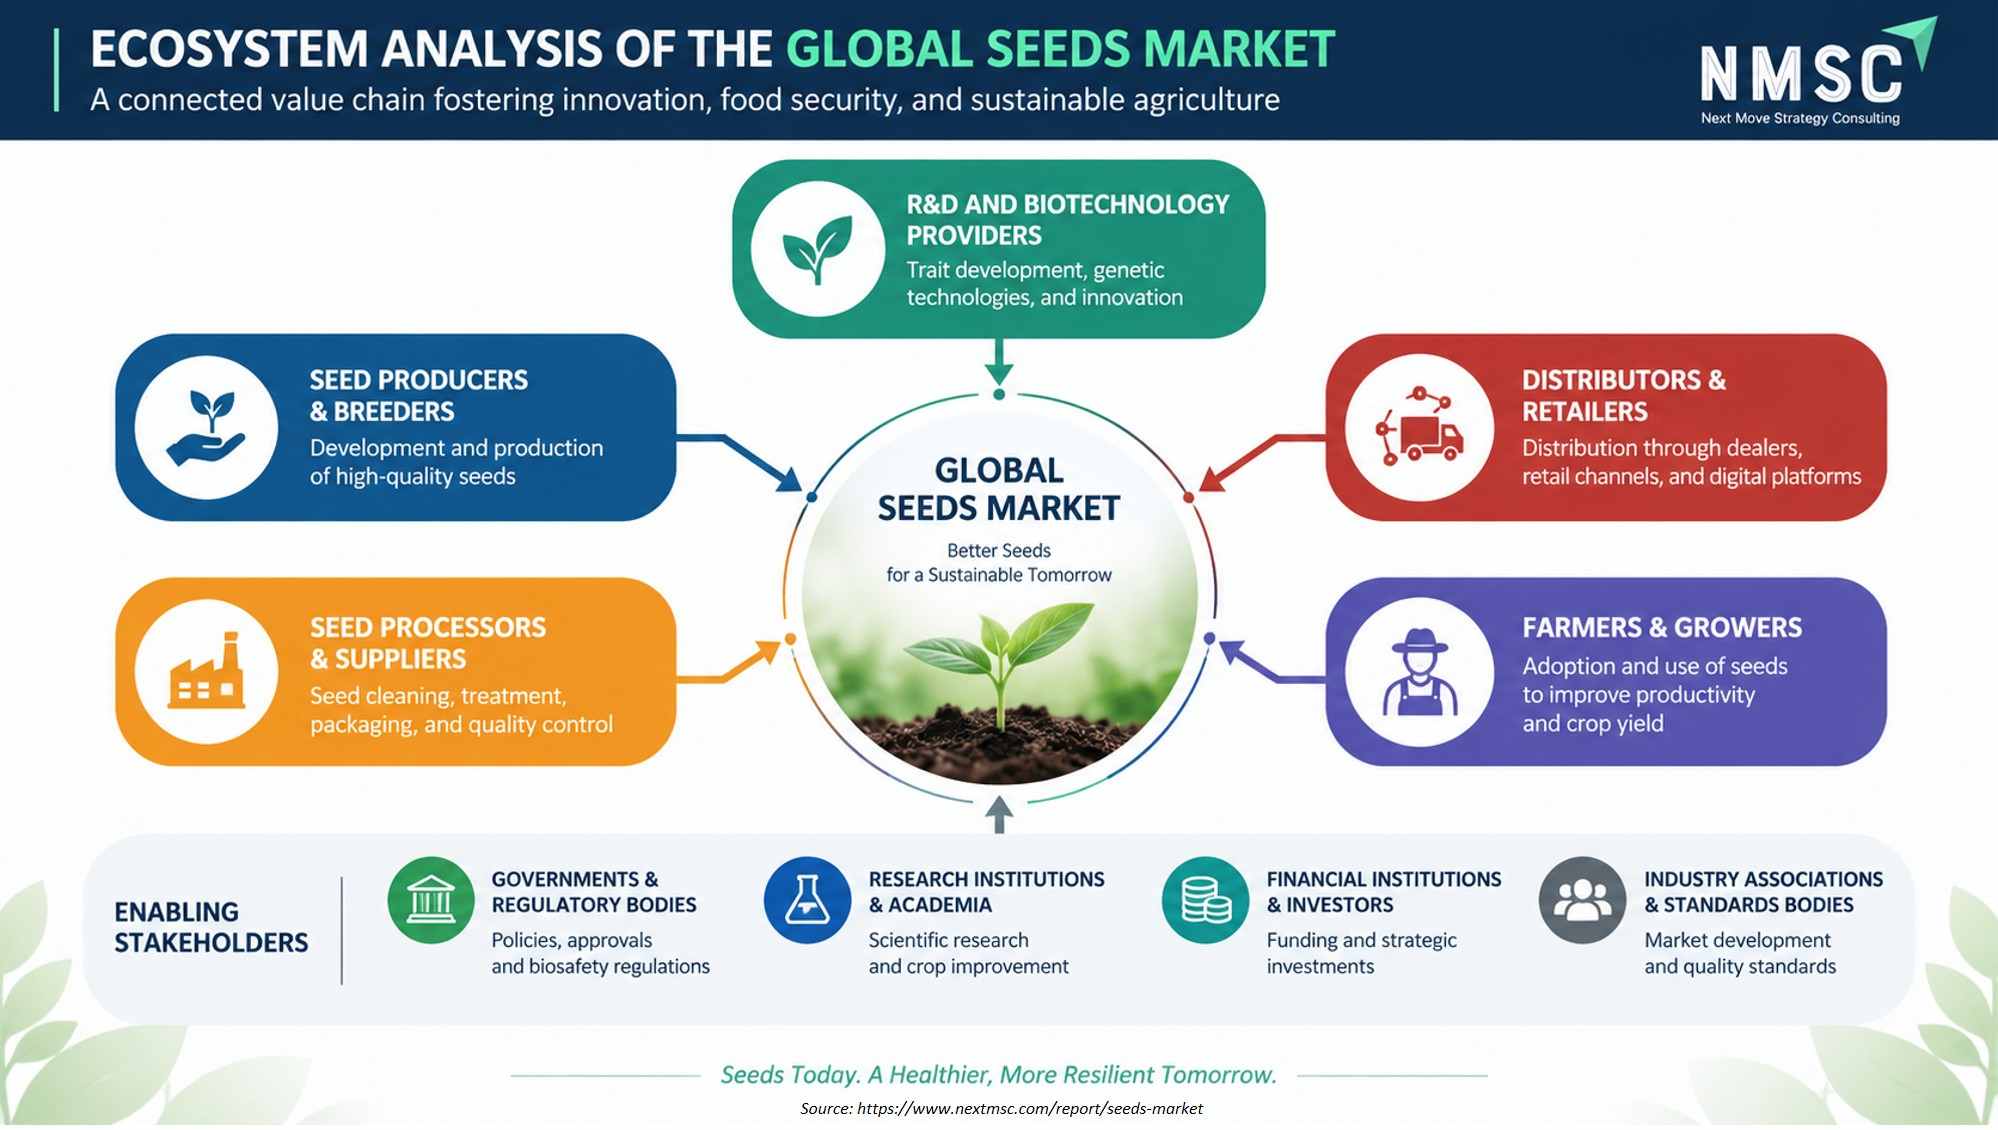
The infographic presents the global seeds market ecosystem as an interconnected value chain. It highlights R&D and biotechnology providers, seed producers and breeders, processors and suppliers, distributors and retailers, and farmers and growers. Supporting stakeholders include governments, regulators, research institutions, academia, investors, and industry associations, emphasizing their roles in innovation, regulation, funding, quality standards, productivity, and sustainable agricultural development.

Market Drivers & Dynamics

Interactive Dataset
Rising global food demand driving yield-focused seed adoption driver +1.6% Global 2026–2035
Expansion of gene-edited and precision-bred variety pipelines driver +1.3% North America, Europe 2027–2035
Growing climate-resilient trait adoption among growers driver +1.0% Asia-Pacific, Latin America, MEA 2026–2035
Increasing vegetable and horticultural seed premiumization driver +0.8% Asia-Pacific, Europe 2026–2033
Expansion of biological seed treatment adoption driver +0.6% North America, Europe 2026–2032
Regulatory uncertainty surrounding gene-edited seed classification restraint −0.7% Europe 2026–2032
Farmer seed-saving practices limiting repeat commercial purchases restraint −0.5% Asia-Pacific, Latin America, MEA 2026–2035
High cost and long timelines of variety development and trials restraint −0.4% Global 2026–2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver for the Seeds Market?

Rising global food demand is the primary growth driver, sustaining consistent grower investment in yield-focused hybrid and biotechnology-enhanced seed varieties. The United Nations Food and Agriculture Organization projects that global agricultural production must continue expanding to meet population-driven food demand through the coming decade, underscoring the scale of the addressable grower base from which seed demand is expanding.

How Is Gene Editing Driving the Market Growth?

Gene editing is driving growth by shortening the development timeline for stress-tolerant and disease-resistant varieties compared with conventional breeding alone. Company analysis indicates that seed developers with established gene-editing platforms are bringing climate-resilient varieties to market faster than competitors reliant on conventional breeding methods. Based on research conducted by NMSC, we found that this shift is most pronounced across North American and European field crop breeding programs.

Growth Inhibitors

What Is Restraining the Seeds Market?

Regulatory uncertainty surrounding gene-edited seed classification is restraining commercialization timelines, particularly across the European Union where distinct regulatory treatment for gene-edited versus conventionally bred varieties remains under active policy development. We observed that this restraint is most pronounced for seed developers seeking harmonized market access across multiple national regulatory frameworks simultaneously.

What Are the Growth Opportunities?

Can Gene-Edited Climate-Resilient Varieties Unlock Emerging-Market Demand?

Gene-edited drought- and heat-tolerant varieties tailored to Sub-Saharan African and South Asian growing conditions can unlock incremental demand among smallholder growers facing volatile climate stress. This mechanism primarily benefits seed developers with established gene-editing platforms and emerging-market distribution partnerships.

Will Digital Direct-to-Grower Platforms Reshape Distribution Economics?

Digital ordering platforms connecting seed developers directly with growers can compress distribution costs and improve variety-performance data feedback loops. Seed companies investing in direct digital distribution infrastructure stand to benefit most from improved margin capture and grower retention relative to traditional dealer-dependent competitors.

Can Biological Seed Treatment Bundling Expand Premium Pricing?

Bundling biological seed treatments with premium genetics offers a mechanism to capture higher per-unit pricing while addressing grower demand for reduced synthetic input use. Seed treatment technology providers and integrated seed developers are best positioned to capture this opportunity as biological adoption accelerates.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Field Crops
Cereals and
Maize
Rice
Wheat
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Field Crops $10.0 USD Billion $40.0 USD Billion 27.0%
Cereals and Grains $17.1 USD Billion $51.1 USD Billion 17.0%
Maize $24.2 USD Billion $62.2 USD Billion 27.0%
Rice $31.3 USD Billion $73.3 USD Billion 9.0%
Wheat $38.4 USD Billion $84.4 USD Billion 22.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Crop Type.

Unlock Full Data

Which Crop Type Dominates the Seeds Market?

Field Crops dominate crop-type segmentation with an estimated USD 44.95 Billion in 2025, rising to USD 77.47 Billion by 2035, reflecting the scale of global cereal, oilseed, and pulse cultivation. Flower and Ornamental Seeds is the fastest-growing segment at a 8.71% CAGR, reflecting rising horticultural premiumization and expanding protected-cultivation ornamental production.

2025 (USD Billion)
2035 (USD Billion)
Hybrid
Non-Hybrid
Open-Pollina
Synthetic
Composite
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Hybrid $10.0 USD Billion $40.0 USD Billion 12.0%
Non-Hybrid $17.1 USD Billion $51.1 USD Billion 14.0%
Open-Pollinated $24.2 USD Billion $62.2 USD Billion 24.0%
Synthetic $31.3 USD Billion $73.3 USD Billion 26.0%
Composite $38.4 USD Billion $84.4 USD Billion 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Breeding Method.

Unlock Full Data

Which Breeding Method Is Gaining the Most Ground?

Hybrid seed dominates breeding-method segmentation with USD 50.38 Billion in 2025 revenue and is also the fastest-growing method at a 7.15% CAGR, reflecting consistent grower preference for hybrid vigor and yield uplift over open-pollinated alternatives across most major field and vegetable crop categories.

2025 (USD Billion)
2035 (USD Billion)
Conventional
Genetically
Gene Edited
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Conventional Breeding $10.0 USD Billion $40.0 USD Billion 21.0%
Genetically Modified $17.1 USD Billion $51.1 USD Billion 11.0%
Gene Edited $24.2 USD Billion $62.2 USD Billion 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Genetic Technology.

Unlock Full Data

Which Genetic Technology Leads and Which Is Growing Fastest?

Conventional Breeding leads genetic-technology segmentation with USD 54.25 Billion in 2025 revenue, reflecting its continued dominance outside major row-crop biotechnology markets . Gene Edited is the fastest-growing category at a 14.15% CAGR, driven by accelerating commercial deployment of precision-bred, stress-tolerant varieties across North America and select Asia-Pacific markets.

2025 (USD Billion)
2035 (USD Billion)
No Commercia
Single Comme
Stacked Comm
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
No Commercial Trait $10.0 USD Billion $40.0 USD Billion 24.0%
Single Commercial Trait $17.1 USD Billion $51.1 USD Billion 10.0%
Stacked Commercial Traits $24.2 USD Billion $62.2 USD Billion 24.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Trait Status.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Treated
Untreated
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Treated $10.0 USD Billion $40.0 USD Billion 20.0%
Untreated $17.1 USD Billion $51.1 USD Billion 26.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Treatment Status.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Open Field
Protected Cu
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Open Field $10.0 USD Billion $40.0 USD Billion 8.0%
Protected Cultivation $17.1 USD Billion $51.1 USD Billion 26.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Cultivation Environment.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct to Gr
Wholesale Di
Dealer and R
Government a
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct to Grower $10.0 USD Billion $40.0 USD Billion 25.0%
Wholesale Distributor $17.1 USD Billion $51.1 USD Billion 19.0%
Dealer and Retail $24.2 USD Billion $62.2 USD Billion 25.0%
Government and Institutional $31.3 USD Billion $73.3 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Distribution Channel.

Unlock Full Data

Growth Opportunities

Growth Opportunities
Beyond current demand drivers, three whitespace opportunities stand out as forward-looking mechanisms for revenue expansion through 2035.

Can Gene-Edited Climate-Resilient Varieties Unlock Emerging-Market Demand?

Gene-edited drought- and heat-tolerant varieties tailored to Sub-Saharan African and South Asian growing conditions can unlock incremental demand among smallholder growers facing volatile climate stress. This mechanism primarily benefits seed developers with established gene-editing platforms and emerging-market distribution partnerships.

Will Digital Direct-to-Grower Platforms Reshape Distribution Economics?

Digital ordering platforms connecting seed developers directly with growers can compress distribution costs and improve variety-performance data feedback loops. Seed companies investing in direct digital distribution infrastructure stand to benefit most from improved margin capture and grower retention relative to traditional dealer-dependent competitors.

Can Biological Seed Treatment Bundling Expand Premium Pricing?

Bundling biological seed treatments with premium genetics offers a mechanism to capture higher per-unit pricing while addressing grower demand for reduced synthetic input use. Seed treatment technology providers and integrated seed developers are best positioned to capture this opportunity as biological adoption accelerates.
Porter’s Five Forces Analysis for the Global Seeds Market
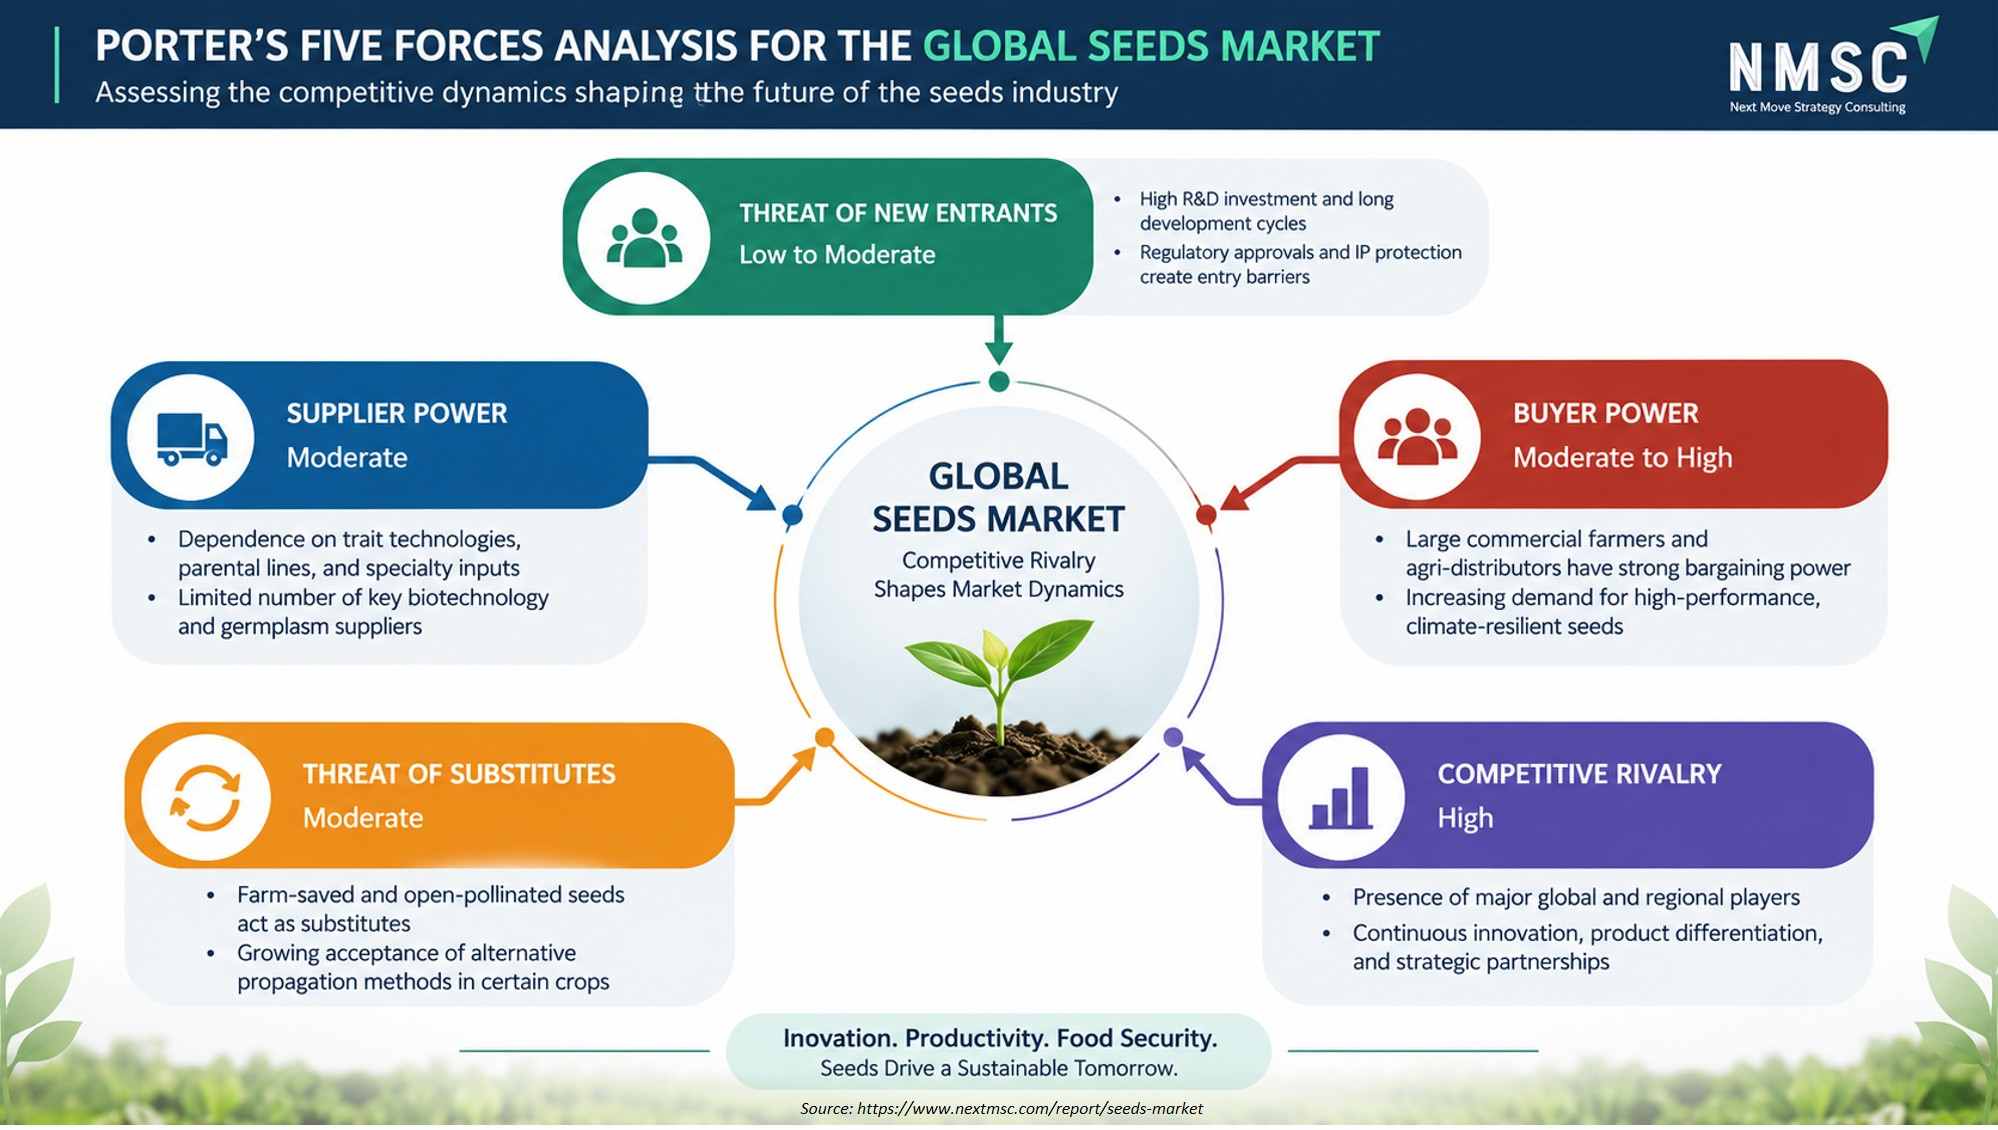
The infographic presents Porter’s Five Forces for the Global Seeds Market, highlighting the competitive pressures shaping the industry. It assesses high competitive rivalry, moderate-to-high buyer power, moderate supplier power, moderate threat of substitutes, and low-to-moderate threat of new entrants. The analysis emphasizes R&D intensity, regulatory barriers, trait technologies, farmer purchasing dynamics, product differentiation, and continuous innovation as key factors influencing market competitiveness.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

Our findings suggest that the competitive landscape spans diversified agricultural biotechnology majors, specialized vegetable and horticultural breeders, and regional field-crop seed developers, each pursuing distinct differentiation strategies. Dimension | Assessment Market Structure | Moderately consolidated; diversified biotechnology majors hold significant field-crop share while specialized breeders dominate vegetable and ornamental categories Innovation Focus | Gene editing, genomic selection, climate-resilient trait development, biological seed treatment integration M&A Activity | Moderate; diversified majors acquire specialized breeding and biotechnology developers to expand trait pipelines Source: www.nextmsc.com

How Do Companies Compete in the Seeds Market?

Companies compete primarily on breeding pipeline depth, trait technology access, and regional distribution network strength. Our analysis shows that developers combining proprietary genetic technology with dense grower-facing distribution sustain larger market share than competitors reliant on licensed trait technology or third-party distribution alone.

Which Competitive Archetypes Dominate the Industry?

Two archetypes dominate: diversified agricultural biotechnology majors spanning field-crop genetics and crop protection, and specialized vegetable and horticultural breeders concentrated in fruiting and leafy vegetable categories. We observed that the differentiation between these archetypes is narrowing as diversified majors expand vegetable seed acquisitions.

What Innovation and Differentiation Strategies Are Companies Pursuing?

Company analysis indicates that leading firms are differentiating through proprietary gene-editing platforms, genomic selection tools, and expanded biological seed treatment portfolios. Investment in climate-resilient trait pipelines continues, alongside expanded breeding station networks in Asia-Pacific and Latin America to serve growing regional demand.

How Active Is M&A in the Seeds Industry?

M&A activity remains moderate as diversified majors acquire specialized vegetable and biotechnology developers to expand trait and germplasm access. Based on research conducted by NMSC, we found that acquisition targets increasingly include gene-editing technology developers, reflecting strategic pivots toward the fastest-growing genetic-technology category.

Key Market Players

Our assessment indicates that the following companies represent the validated set of key players shaping competitive dynamics across field crop, vegetable, forage, and specialty seed categories within the seeds market.

Bayer AG Corteva, Inc. Syngenta AG BASF SE Groupe Limagrain Holding SA KWS SAAT SE & Co. KGaA DLF Seeds A/S Yuan Longping High-Tech Agriculture Co., Ltd. Rijk Zwaan Zaadteelt en Zaadhandel B.V. Sakata Seed Corporation Takii & Co., Ltd. Enza Zaden Beheer B.V. Royal Barenbrug Group B.V. Bejo Zaden B.V. Lidea France SAS RAGT Semences SAS Advanta Enterprises Limited East-West Seed International Limited Kaveri Seed Company Limited Seed Co Limited

Latest Developments

We observed that recent developments across the industry reflect continued investment in gene-editing platforms and climate-resilient variety pipelines.

Date Event
September 2026 Bayer announced the development of genome-edited soybean with improved plant architecture to reduce leaning or falling over, alongside a next-generation herbicide-tolerance trait expected to include tolerance to Icafolin . The company is advancing these seed and crop-protection innovations as part of an integrated R&D strategy, with the genome-edited soybean and associated breeding concepts expected to reach the market early in the next decade.
August 2026 KWS reported a 17% share of Europe’s hybrid oilseed-rape market and first-place positions in Hungary, France and Germany, based on Kynetec data. The result highlights the commercial impact of KWS’s newer genetics and reinforces competitive intensity in European oilseed-rape seed breeding and variety deployment.

Investment Opportunities

Where Is Capital Flowing Within the Seeds Market?

Capital inflows are concentrated in gene-editing platform development and climate-resilient trait licensing deals among diversified agricultural biotechnology majors. We found that venture and strategic capital is also flowing into digital variety-selection and direct-to-grower distribution platforms, signaling growing institutional interest in distribution-layer innovation.

How Significant Is Infrastructure Investment in This Market?

Infrastructure investment is substantial, with seed developers expanding breeding station networks and seed processing and treatment capacity across Asia-Pacific and Latin America. Our assessment indicates that continued investment in genomic selection laboratory infrastructure is becoming a prerequisite for competing in accelerated variety development timelines.

What ESG Considerations Are Relevant to This Market?

ESG considerations center on biodiversity impact of monoculture hybrid seed adoption, smallholder farmer access to improved varieties, and reduced synthetic input use through biological seed treatment adoption. We observed that seed developers increasingly disclose smallholder access program commitments in annual sustainability reporting.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders?

Industry and enterprise leaders gain a structured view of crop-type, breeding-method, and regional revenue distribution, supporting prioritization decisions across breeding pipeline investment and distribution strategy. Our analysis shows that this structured segmentation clarifies where competitive intensity is rising fastest ahead of resource-allocation decisions.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts gain reconciled market-size, CAGR, and regional-growth data supporting valuation and portfolio-allocation decisions. Company analysis indicates that segment-level growth differentials, particularly around gene-edited and genetically modified categories, are material inputs for evaluating seed developer growth durability.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain visibility into genetic-technology and distribution-channel trends shaping breeding and digital platform infrastructure demand. We found that this analysis supports prioritization of engineering investment toward the fastest-growing delivery mechanisms identified across the forecast period.

Key Market Segments Evaluated

By Crop Type

  • Field Crops
  • Vegetable Seeds
  • Forage Seeds
  • Turf Seeds
  • Flower and Ornamental Seeds
  • Other Commercial Seeds

By Breeding Method

  • Hybrid
  • Non-Hybrid

By Genetic Technology

  • Conventional Breeding
  • Genetically Modified
  • Gene Edited

By Trait Status

  • No Commercial Trait
  • Single Commercial Trait
  • Stacked Commercial Traits

By Treatment Status

  • Treated
  • Untreated

By Cultivation Environment

  • Open Field
  • Protected Cultivation

By Distribution Channel

  • Direct to Grower
  • Wholesale Distributor
  • Dealer and Retail
  • Government and Institutional

Conclusion & Recommendations

The long-term outlook remains firmly expansionary, with revenue projected to grow from USD 84.10 Billion in 2026 to USD 143.47 Billion by 2035 at a 6.11% CAGR. Our analysis shows that this trajectory is underpinned by structural demand for climate-resilient and gene-edited varieties rather than cyclical planting-cycle demand alone.

What Strategic Positioning Should Companies Pursue?

Companies should prioritize gene-editing platform investment alongside continued conventional breeding pipeline strength. We found that developers combining proprietary genetic technology with dense grower distribution sustain more resilient revenue than those reliant on a single breeding method or geography.

How Attractive Is the Market for Investment?

Investment attractiveness is high given double-digit growth in gene-edited and Latin American market categories alongside a large, stable base of conventional and hybrid demand in mature markets. Our assessment indicates that capital allocators should weight exposure toward developers with proven gene-editing pipelines over conventional-only competitors.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Key risks include regulatory uncertainty surrounding gene-edited seed classification, farmer seed-saving practices limiting repeat purchases, and the high cost and long timelines of variety development. We observed that regulatory uncertainty poses the most immediate risk to gene-edited variety commercialization timelines across Europe.

What Are the Primary Growth Pathways Through 2035?

Primary growth pathways include gene-edited climate-resilient varieties for emerging markets, digital direct-to-grower distribution platforms, and biological seed treatment bundling for premium pricing. Our findings suggest that companies combining all three pathways will outpace single-lever competitors through the forecast period.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Diana Trejo

DIANA TREJO

Assistant Manager

Sumitomo Corporation de Mexico, S.A. de C.V.

Recently, we purchased a report on the Mexico Data Center Market from Next Move Strategy Consulting. The service has been excellent, with support that is always timely and thoroughly professional. The information provided is interesting, highly useful, and delivered with clarity. I would highly recommend NextMSC for anyone seeking insightful and dependable analysis.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖