SiC GaN Power Semiconductor Market Global Industry Analysis and Forecast (2026–2035)

The global SiC GaN Power Semiconductor Market size was valued at USD 4.85 billion in 2025 and is estimated at USD 5.95 billion in 2026, forecast to reach USD 38.60 billion by 2035, expanding at a 23.1% CAGR from 2026 to 2035. Key drivers include rising EV traction inverter adoption requiring high-efficiency power semiconductors and expanding AI data center power infrastructure, with Asia-Pacific leading the global market.

Download Free Sample PDF
Base Year (2025)
$4.85 Billion
Forecast (2035)
$38.60 Billion
CAGR (2026-2035)
23.1%
Top Region
Asia-Pacific

What Is the SiC GaN Power Semiconductor Market Size?

The global SiC GaN power semiconductor market size was valued at USD 4.85 billion in 2025 and is estimated at USD 5.95 billion in 2026, forecast to reach USD 38.60 billion by 2035, expanding at a 23.1% CAGR between 2026 and 2035. Asia-Pacific leads with approximately 41% share, while discrete power devices dominate all other product types with approximately 58% share.

We observed that growth is broad-based across every segmentation axis, with integrated power devices and data center power applications recording the steepest structural gains through the forecast window.

SiC GaN Power Semiconductor Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast

Values in USD Billion

2025 $4.85 Billion
2025
2026 $5.97 Billion
2026
2027 $7.35 Billion
2027
2028 $9.05 Billion
2028
2029 $11.14 Billion
2029
2030 $13.71 Billion
2030
2031 $16.88 Billion
2031
2032 $20.78 Billion
2032
2033 $25.57 Billion
2033
2034 $31.48 Billion
2034
2035 $38.60 Billion
2035

Key Takeaways

By Product Type: Discrete Power Devices held the largest share of approximately 58% (USD 2.81 billion) in 2025; Integrated Power Devices is the fastest-growing sub-segment at 28.0% CAGR from 2026–2035.

By Material: Silicon Carbide held the largest share of approximately 64% (USD 3.10 billion) in 2025; Gallium Nitride is the fastest-growing sub-segment at 27.0% CAGR from 2026–2035.

By Device Function: Switching held the largest share of approximately 61% (USD 2.96 billion) in 2025; Switching Rectification is the fastest-growing sub-segment at 26.0% CAGR from 2026–2035.

By Voltage Rating: 650–1,200 V held the largest share of approximately 38% (USD 1.84 billion) in 2025; Above 1,700 V is the fastest-growing sub-segment at 27.0% CAGR from 2026–2035.

By Current Rating: 10–50 A held the largest share of approximately 34% (USD 1.65 billion) in 2025; Above 300 A is the fastest-growing sub-segment at 28.0% CAGR from 2026–2035.

By Application: Automotive held the largest share of approximately 34% (USD 1.65 billion) in 2025; Data Center Telecom is the fastest-growing sub-segment at 32.0% CAGR from 2026–2035.

By End User: Automotive held the largest share of approximately 32% (USD 1.55 billion) in 2025; Data Center Telecom is the fastest-growing sub-segment at 31.0% CAGR from 2026–2035.

Dominant Region: Asia-Pacific dominated with approximately 41% revenue share (USD 2.00 billion) in 2025.

Fastest-Growing Region: Latin America is expected to register the highest CAGR of 30.6% during 2026–2035.

Dominant Country: China led with approximately USD 1.15 billion in 2025.

Fastest-Growing Country: Brazil is the fastest-growing country at approximately 31.4% CAGR from 2026–2035.

Market Opportunity: The SiC GaN power semiconductor market is expected to create an absolute dollar opportunity of USD 32.65 billion between 2026 and 2035, presenting significant investment potential across the 800V EV architecture and AI data center power value chain.

According to NMSC analysis, automotive OEMs and data center operators are increasingly co-developing power architectures directly with wide-bandgap device manufacturers rather than sourcing components through generic distribution channels, a shift that favors vertically integrated device manufacturers over pure-play foundries as 800V EV platforms and AI power infrastructure scale through 2035.

What Does the SiC GaN Power Semiconductor Market Encompass?

The SiC GaN power semiconductor market encompasses discrete devices, power modules, and integrated power devices built on silicon carbide and gallium nitride substrates that replace conventional silicon in high-voltage and high-frequency power conversion. Our assessment indicates that the scope spans SiCMOSFET and Schottky diode discrete devices, hybrid and full SiC power modules, and GaN power ICs supplied across automotive, charging infrastructure, industrial, energy, data center telecom, and consumer electronics applications. The category has evolved from niche high-reliability defense and aerospace use into a mainstream automotive and data center power discipline as 800V electric vehicle platforms and AI compute infrastructure scale globally.
Regulatory frameworks such as government incentives for domestic semiconductor manufacturing capacity and vehicle electrification mandates in North America and Europe shape fab investment and design-in cycles for wide-bandgap devices. We observed that technology adoption is shifting toward 300-millimeter GaN wafer manufacturing and higher-voltage SiC platforms that improve production yield and power density. NMSC's analysis indicates that this structural shift, combined with growing AI data center power demand, is redefining procurement criteria across the SiC GaN power semiconductor market.

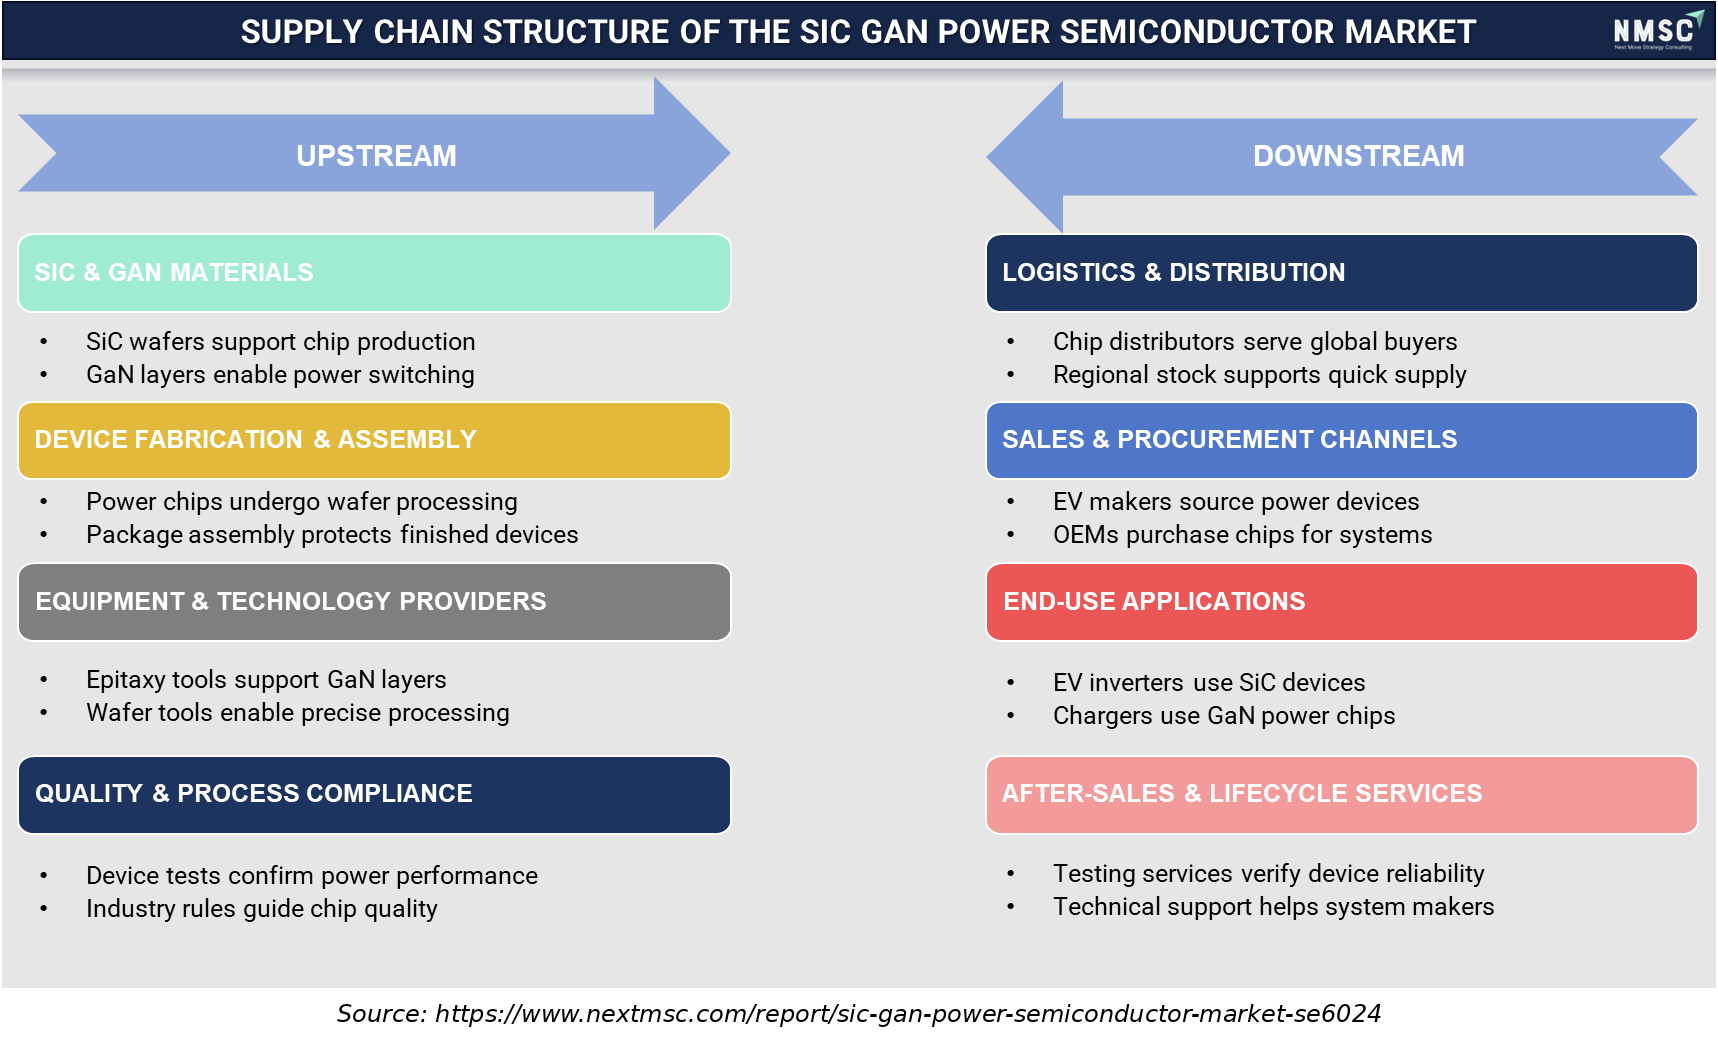
Supply Chain Structure of the SiC GaN Power Semiconductor Market

Supply Chain Structure of the SiC GaN Power Semiconductor Market

The SiC GaN power semiconductor supply chain spans material production, device fabrication, specialized equipment, quality testing, logistics, procurement, and end-use applications. SiC wafers and GaN layers enable advanced power devices, while fabrication and packaging determine performance and reliability. Downstream demand from electric vehicles, charging infrastructure, and other power-intensive systems supports expanding distribution and lifecycle service requirements.

Market Drivers & Dynamics

Interactive Dataset
Rising EV traction inverter adoption requiring high-efficiency power semiconductors driver +2.8% Global 2026–2035
Expanding data center and AI power infrastructure demand driver +2.4% Global 2026–2035
Government incentives for domestic semiconductor manufacturing capacity driver +1.9% North America, Europe 2026–2032
Growing renewable energy inverter and grid infrastructure investment driver +1.6% Global 2026–2035
Falling cost of SiC and GaN wafer production driver +1.3% Global 2026–2031
Rising adoption of GaN fast chargers in consumer electronics driver +1.0% Asia-Pacific 2026–2033
High wafer defect rates and substrate cost versus silicon restraint -1.1% Global 2026–2030
Supply chain concentration in SiC substrate production restraint -0.8% Global 2026–2029
Design complexity and thermal management challenges at high voltage restraint -0.6% Global 2026–2032
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the SiC GaN Power Semiconductor Market?

Rising EV traction inverter adoption requiring high-efficiency power semiconductors is the primary driver of the market. Wolfspeed, Inc.'s January 2025 introduction of its Gen 4 SiC MOSFET platform, spanning 750V to 2,300V voltage classes, reflects sustained automotive-grade demand for higher-efficiency switching devices. We observed that this expansion, reinforced by rising 800V EV battery architecture adoption, continues to anchor baseline demand for SiC and GaN power semiconductors across developed and emerging vehicle markets alike.

How Is AI Data Center Power Demand Driving SiC GaN Power Semiconductor Market Growth?

Expanding AI data center power infrastructure is accelerating demand for high-voltage, high-efficiency power conversion components. Infineon Technologies AG reported that its GaN portfolio included more than 40 product announcements over the preceding year as of November 2025, spanning consumer, mobility, and data center applications. Our assessment indicates that this expansion, combined with scaling 300-millimeter GaN wafer capacity, is compressing adoption timelines for wide-bandgap devices across global data center and telecom infrastructure.

Growth Inhibitors

What Is Restraining SiC GaN Power Semiconductor Market Expansion?

High wafer defect rates and substrate cost relative to conventional silicon restrain broader adoption among cost-sensitive industrial and consumer applications. Supply chain concentration in SiC substrate production continues to constrain capacity expansion industrywide. We found that manufacturers without established wafer supply agreements face particular exposure, as substrate cost premiums reduce near-term margin advantages compared with silicon-based alternatives in price-sensitive product categories.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Discrete Power Devices 2025: $2.81 Billion | 2035: $19.09 Billion
Discrete Pow
Power Modules 2025: $1.26 Billion | 2035: $10.74 Billion
Power Module
Integrated Power Devices 2025: $0.78 Billion | 2035: $8.77 Billion
Integrated P
Discrete Power Devices $2.81 Billion $19.09 Billion 20.9%
Power Modules $1.26 Billion $10.74 Billion 24.0%
Integrated Power Devices $0.78 Billion $8.77 Billion 28.0%

Which Product Type Dominates the SiC GaN Power Semiconductor Market?

Discrete Power Devices led the market with USD 2.81 billion in 2025, supported by their broad qualification across automotive semiconductor and industrial power conversion applications that do not require multi-die integration. We observed that Integrated Power Devices are the fastest-growing product type, expanding at a 28.0% CAGR from 2026 to 2035, as GaN power ICs increasingly combine driver, control, and switching functions on a single die for data center and fast-charging applications.

2025 (USD Billion)
2035 (USD Billion)
Automotive
Charging Inf
Industrial
Energy
Data Center
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Automotive $10.0 USD Billion $40.0 USD Billion 18.0%
Charging Infrastructure $17.1 USD Billion $51.1 USD Billion 16.0%
Industrial $24.2 USD Billion $62.2 USD Billion 22.0%
Energy $31.3 USD Billion $73.3 USD Billion 12.0%
Data Center Telecom $38.4 USD Billion $84.4 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data

Which Application Leads SiC GaN Power Semiconductor Market Demand?

Automotive remained the leading application, valued at USD 1.65 billion in 2025, reflecting sustained OEM investment in traction inverters and on-board chargers for electric vehicle platforms. Our analysis shows that Data Center Telecom is the fastest-growing application, registering a 32.0% CAGR from 2026 to 2035, as AI power systems and server power supplies increasingly adopt GaN and SiC devices to manage rising rack power density.

2025 (USD Billion)
2035 (USD Billion)
Automotive
Industrial
Energy
Data Center
Consumer Ele
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Automotive $10.0 USD Billion $40.0 USD Billion 26.0%
Industrial $17.1 USD Billion $51.1 USD Billion 16.0%
Energy $24.2 USD Billion $62.2 USD Billion 18.0%
Data Center Telecom $31.3 USD Billion $73.3 USD Billion 8.0%
Consumer Electronics $38.4 USD Billion $84.4 USD Billion 23.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data

Which End User Leads SiC GaN Power Semiconductor Market Demand?

Automotive remained the leading end user, valued at USD 1.55 billion in 2025, reflecting passenger and commercial electric vehicle manufacturers' direct investment in wide-bandgap traction and charging components. Our findings suggest that Data Center Telecom is the fastest-growing end user, registering a 31.0% CAGR from 2026 to 2035, as data center operators and network equipment providers increasingly adopt SiC and GaN devices to improve power conversion efficiency amid rising AI compute density.

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the SiC GaN power semiconductor market over the 2026–2035 forecast period.

How Can 48V Data Center Power Architectures Unlock New Revenue?

Emerging 48V and higher-voltage direct current data center power architectures present a whitespace opportunity for GaN and SiC device suppliers serving AI server infrastructure. Suppliers that commercialize integrated GaN power stages for server power supplies stand to capture recurring design-win revenue from data center operators and AI power system integrators seeking higher rack-level power density.

Where Do Solid-State Transformers Create Recurring Grid Infrastructure Revenue?

Solid-state transformers built on high-voltage SiC modules represent an underpenetrated opportunity for power module manufacturers serving grid modernization programs. Vendors that qualify SiC modules for solid-state transformer and grid infrastructure applications can secure long-term contracts with grid operators and utilities pursuing higher-efficiency alternatives to conventional transformer technology.

How Can Domestic Wafer Capacity Expansion Reduce Automotive Supply Risk?

Domestic SiC and GaN wafer fabrication capacity creates an opportunity for device manufacturers seeking to reduce automotive customer exposure to substrate supply concentration. Early movers that expand 300-millimeter GaN and SiC wafer capacity can differentiate with automotive OEMs prioritizing qualified, geographically diversified supply chains over lower-cost single-source alternatives.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
Asia-Pacific
Europe
North Americ
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
Asia-Pacific $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
North America $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the SiC GaN power semiconductor market features a moderately consolidated competitive landscape, with integrated device manufacturers competing alongside fabless GaN designers on wafer capacity scale and automotive design-win depth.

Dimension Description
Market Structure Moderately consolidated; a handful of established integrated device manufacturers profiled in this report collectively serve a majority of large automotive and industrial contracts, while numerous fabless GaN designers and regional suppliers serve consumer and specialized industrial demand.
Innovation Focus 300-millimeter GaN wafer manufacturing, higher-voltage SiC MOSFET platforms, and integrated GaN power ICs dominate current innovation pipelines across leading suppliers.
M&A Activity Selective licensing partnerships and intellectual property disputes, exemplified by Navitas Semiconductor Corporation's strategic SiC technology licensing partnership with Magnachip Semiconductor Corporation.

How Do Companies Compete in the SiC GaN Power Semiconductor Market?

Companies compete primarily on wafer manufacturing scale, automotive qualification depth, and breadth of material portfolio across the industry. Global players such as Infineon Technologies AG and STMicroelectronics N.V. leverage integrated device manufacturing across silicon, SiC, and GaN to serve multinational automotive OEMs, while fabless designers such as Navitas Semiconductor Corporation compete on rapid design-in cycles for consumer and data center power applications.

Which Competitive Archetypes Dominate the SiC GaN Power Semiconductor Industry?

Two archetypes dominate the industry: integrated device manufacturers offering silicon, SiC, and GaN across a unified manufacturing platform, and specialized fabless or pure-play wide-bandgap designers focused on discrete or integrated GaN products. Infineon Technologies AG and Wolfspeed, Inc. exemplify the integrated device manufacturer archetype through large-scale wafer fab investment, while Navitas Semiconductor Corporation and Innoscience Technology Co., Ltd. exemplify the specialized fabless archetype serving niche consumer and data center demand.

How Are Companies Differentiating Through Innovation in SiC GaN Power Semiconductor Design?

Innovation and differentiation strategy increasingly center on wafer-scale manufacturing efficiency and voltage-class breadth. Wolfspeed, Inc.'s Gen 4 SiC MOSFET platform and Infineon Technologies AG's 300-millimeter GaN manufacturing both aim to reduce per-unit cost while expanding addressable voltage classes. Our analysis shows that suppliers unable to demonstrate credible automotive-grade reliability risk exclusion from large OEM vendor shortlists.

What M&A and IP Activity Is Shaping the SiC GaN Power Semiconductor Market?

Licensing partnerships and intellectual property disputes continue to reshape competitive positioning within the industry. Navitas Semiconductor Corporation's July 2026 partnership with Magnachip Semiconductor Corporation to license GeneSiC technology for high-voltage applications illustrates how licensing deals expand market reach, while Wolfspeed, Inc.'s concurrent patent infringement lawsuit against Navitas Semiconductor Corporation underscores rising competitive stakes across overlapping GaN and SiC product lines.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping wafer capacity expansion, product innovation, and automotive qualification depth within the global SiC GaN power semiconductor market.

Infineon Technologies AG STMicroelectronics N.V. ON Semiconductor Corporation Wolfspeed, Inc. ROHM Co., Ltd. Renesas Electronics Corporation Mitsubishi Electric Corporation Fuji Electric Co., Ltd. Toshiba Electronic Devices & Storage Corporation Nexperia B.V. Microchip Technology Incorporated StarPower Semiconductor Ltd. China Resources Microelectronics Limited Silan Microelectronics Co., Ltd. Navitas Semiconductor Corporation Sanan Optoelectronics Co., Ltd. Innoscience Technology Co., Ltd. Alpha and Omega Semiconductor Limited Power Integrations, Inc. Vishay Intertechnology, Inc.

Latest Developments

We found that recent product launches and strategic partnerships within the SiC GaN power semiconductor market are concentrated on higher-voltage platforms and wafer-scale manufacturing expansion, reflecting the industry's broader shift toward automotive and data center power applications.

Date Event
August 2026 Power Integrations demonstrated PowiGaN technology rated up to 2,200V, extending GaN into voltage ranges traditionally served by SiC. The technology targets AI data centers, EVs, photovoltaic systems and HVDC infrastructure, where higher-voltage distribution can improve power density while retaining GaN’s high-frequency switching advantages.
June 2026 Wolfspeed introduced its Gen 5 SiC MOSFET technology for 750V and 1200V applications, reporting up to 27% efficiency improvement versus competitive 1200V solutions. The devices use the company’s automated 200mm manufacturing platform and target automotive and industrial applications requiring higher efficiency, power density and scalable production.
May 2026 STMicroelectronics introduced new 700V PowerGaN devices designed to improve efficiency and power density in AI servers, robotics, industrial equipment and advanced consumer applications. The portfolio targets high-demand power-conversion stages where faster switching and reduced losses can enable smaller, more efficient architectures.

Expert Insights

Johannes Schoiswohl

Johannes Schoiswohl

Head of GaN Business Line | Infineon Technologies

"The relevance of comprehensive power systems will increase, with GaN manifesting its role due to its benefits in efficiency, density and size. Given that cost-parity with silicon is in sight, we will see an increased adoption rate for GaN this year and beyond."

Analyst Interpretation

This statement reflects a broader shift within the industry toward multi-material integrated device manufacturing rather than single-material specialization. NMSC's analysis indicates that Infineon Technologies AG's CoolGaN partnership with Enphase Energy, alongside its parallel SiC and silicon portfolios, illustrates how leading suppliers are hedging technology risk by serving customers across all three material platforms. Our findings suggest that manufacturing breadth and automotive qualification depth are increasingly decisive in OEM vendor selection across the SiC GaN power semiconductor market.

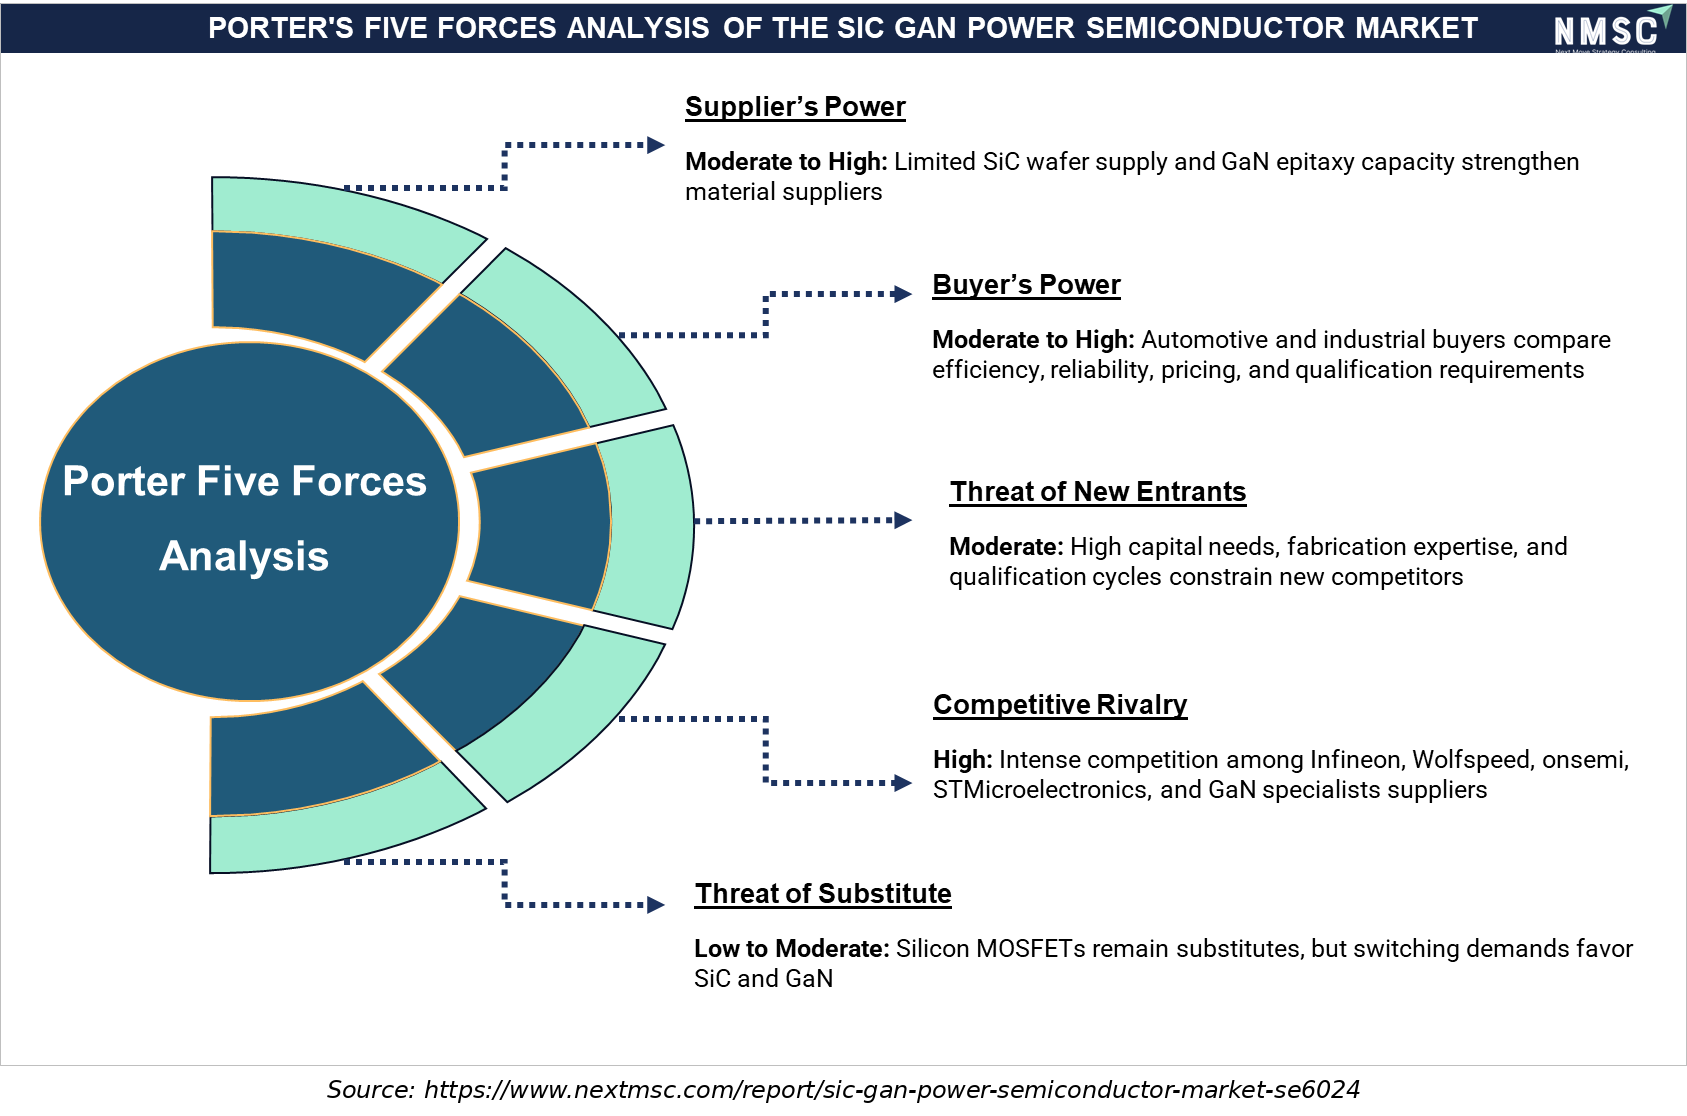
Porter’s Five Forces Analysis of the SiC GaN Power Semiconductor Market

The SiC GaN power semiconductor market exhibits competitive dynamics shaped by technology-intensive manufacturing, specialized materials, established semiconductor capabilities, and growing application demand. Supplier power remains influenced by limited sources of advanced materials and equipment, while buyer power varies across automotive, industrial, and consumer applications. Competitive rivalry is strengthened by ongoing innovation in efficiency, reliability, fabrication, and device performance.

Investment Opportunities

What Capital Inflows Are Targeting the SiC GaN Power Semiconductor Market?

Capital inflows into the SiC GaN power semiconductor market are increasingly directed toward wafer-scale manufacturing expansion and higher-voltage product development. Strategic licensing partnerships continue to reshape competitive access, as seen in Navitas Semiconductor Corporation's July 2026 SiC technology licensing agreement with Magnachip Semiconductor Corporation. We observed that investors favor suppliers demonstrating validated automotive qualification and wafer capacity scale, viewing manufacturing breadth as a durable competitive moat.

How Is Infrastructure Investment Supporting SiC GaN Power Semiconductor Deployment?

Infrastructure investment is expanding domestic wafer fabrication capacity to serve rising automotive and data center demand across North America, Europe, and Asia-Pacific. Our findings suggest that suppliers are investing in 300-millimeter GaN and higher-voltage SiC production lines to reduce per-unit cost and support the volume required for mainstream automotive and data center power applications.

What ESG Considerations Are Shaping SiC GaN Power Semiconductor Investment Decisions?

Environmental, social, and governance considerations are central to investment decisions across the industry, with energy efficiency and decarbonization as key criteria. Infineon Technologies AG has positioned its GaN and SiC portfolio as central to decarbonization and digitalization objectives across its public disclosures. We found that investors increasingly favor suppliers that demonstrate measurable efficiency gains in electric vehicle and renewable energy applications, treating power conversion efficiency as a governance and sustainability indicator.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and technology-partnership decisions across the SiC GaN power semiconductor industry. Our analysis shows that detailed product type, application, and end user breakdowns help procurement teams align specifications with voltage and current requirements while identifying underserved application segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the SiC GaN power semiconductor market supply chain. We observed that the report's regional and segment-level growth differentials help identify which discrete device, power module, and integrated device suppliers are best positioned to capture above-market growth through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including higher-voltage SiC platforms and integrated GaN power ICs, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around wafer-scale manufacturing efficiency and automotive qualification depth increasingly required by OEM and data center procurement processes.

Key Market Segments Evaluated

By Product Type

  • Discrete Power Devices
  • Power Modules
  • Integrated Power Devices

By Application

  • Automotive
  • Charging Infrastructure
  • Industrial
  • Energy
  • Data Center Telecom
  • Consumer Electronics
  • Transportation
  • Aerospace Defense
  • Other Applications

By End User

  • Automotive
  • Industrial
  • Energy
  • Data Center Telecom
  • Consumer Electronics
  • Transportation
  • Aerospace Defense
  • Other End Users

Conclusion & Recommendations

The long-term outlook for the market remains highly positive, with global revenue projected to expand nearly eightfold from USD 4.85 billion in 2025 to USD 38.60 billion by 2035 at a 23.1% CAGR. We observed that sustained 800V EV platform adoption, expanding AI data center power demand, and accelerating GaN wafer-scale manufacturing will continue underpinning demand across discrete, module, and integrated device applications through the forecast period.

What Strategic Positioning Should SiC GaN Power Semiconductor Suppliers Pursue?

Suppliers should prioritize multi-material manufacturing platforms spanning silicon, SiC, and GaN while pursuing higher-voltage product qualification to secure long-term automotive and data center contracts. Our assessment indicates that providers investing early in 300-millimeter GaN wafer capacity and automotive-grade reliability will be best positioned to capture premium pricing within the SiC GaN power semiconductor market.

How Attractive Is the SiC GaN Power Semiconductor Market for New Investment?

The SiC GaN power semiconductor industry presents an attractive investment case, supported by a USD 32.65 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Latin America and data center telecom categories. We found that investment attractiveness is highest for suppliers combining wafer-scale manufacturing depth with automotive qualification, positioning them to serve both cost-sensitive discrete device and premium integrated device segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor high substrate cost, supply chain concentration in SiC production, and intensifying intellectual property disputes as key risks to the SiC GaN power semiconductor market. Our analysis shows that suppliers unable to demonstrate validated automotive-grade reliability and defensible patent positions risk losing procurement shortlists to competitors with larger proprietary manufacturing and intellectual property portfolios, particularly within the increasingly litigation-exposed wide-bandgap device environment.

What Are the Key Growth Pathways for the SiC GaN Power Semiconductor Market?

Key growth pathways include expanding 300-millimeter GaN wafer capacity, scaling higher-voltage SiC module production, and deepening penetration into AI data center and grid infrastructure channels. NMSC's analysis indicates that suppliers pursuing these pathways while maintaining cost competitiveness in standard discrete device categories will be best positioned to capture the SiC GaN power semiconductor market's projected growth through 2035.

FAQs

About the Author

Mihul Sharma

Mihul Sharma

Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Diana Trejo

DIANA TREJO

Assistant Manager

Sumitomo Corporation de Mexico, S.A. de C.V.

Recently, we purchased a report on the Mexico Data Center Market from Next Move Strategy Consulting. The service has been excellent, with support that is always timely and thoroughly professional. The information provided is interesting, highly useful, and delivered with clarity. I would highly recommend NextMSC for anyone seeking insightful and dependable analysis.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖