Ventilators Market Global Industry Analysis and Forecast (2026–2035)

The global Ventilators Market is valued at USD 10.10 Billion in 2026 and is projected to reach USD 19.26 Billion by 2035, growing at a 7.44% CAGR. Chronic respiratory disease and population ageing drive demand, with North America leading at approximately 38% share and Critical Care Ventilators accounting for approximately 36% share.

Download Free Sample PDF
Base Year (2025)
$9.08 Billion
Forecast (2035)
$19.26 Billion
CAGR (2026-2035)
7.4%
Top Region
North America

What Is the Ventilators Market Size?

The global ventilators market size was valued at USD 9.08 billion in 2025 and is estimated at USD 10.10 billion in 2026, forecast to reach USD 19.26 billion by 2035, expanding at a 7.44% CAGR between 2026 and 2035. North America leads with approximately 38% share, while critical care ventilators dominate all other product types with approximately 36% share.

We observed that growth is broad-based across every segmentation axis, with home ventilation, dual capability interfaces, and combined control modes driving the dominant structural shifts through 2035.

Ventilators Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast

Values in USD Billion

2025 $9.08 Billion
2025
2026 $10.10 Billion
2026
2027 $10.85 Billion
2027
2028 $11.66 Billion
2028
2029 $12.53 Billion
2029
2030 $13.46 Billion
2030
2031 $14.46 Billion
2031
2032 $15.54 Billion
2032
2033 $16.69 Billion
2033
2034 $17.93 Billion
2034
2035 $19.26 Billion
2035

Key Takeaways

By Product: Critical Care Ventilators held the largest share of approximately 36% (USD 3.27 billion) in 2025 and are projected to reach USD 5.97 billion in 2035; Home Ventilators are the fastest-growing sub-segment at 9.39% CAGR from 2026–2035.

By Patient Type: Adult Only held the largest share of approximately 62% (USD 5.63 billion) in 2025 and is projected to reach USD 10.98 billion in 2035; Mixed Age is the fastest-growing sub-segment at 9.00% CAGR from 2026–2035.

By Interface: Invasive Only held the largest share of approximately 41% (USD 3.72 billion) in 2025 and is projected to reach USD 6.55 billion in 2035; Dual Capability is the fastest-growing sub-segment at 9.09% CAGR from 2026–2035.

By Mobility: Bedside held the largest share of approximately 49% (USD 4.45 billion) in 2025 and is projected to reach USD 7.90 billion in 2035; Home Portable is the fastest-growing sub-segment at 9.19% CAGR from 2026–2035.

By Ventilation Mode: Volume Control held the largest share of approximately 31% (USD 2.82 billion) in 2025 and is projected to reach USD 5.20 billion in 2035; Combined Control is the fastest-growing sub-segment at 10.12% CAGR from 2026–2035.

By End User: Hospitals and Clinics held the largest share of approximately 56% (USD 5.09 billion) in 2025 and is projected to reach USD 9.05 billion in 2035; Home Care is the fastest-growing sub-segment at 10.14% CAGR from 2026–2035.

By Commercial Channel: Direct OEM held the largest share of approximately 45% (USD 4.09 billion) in 2025 and is projected to reach USD 8.09 billion in 2035; Homecare and DME is the fastest-growing sub-segment at 9.82% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 38% revenue share (USD 3.45 billion) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 9.86% during 2026–2035.

Dominant Country: U.S. led with approximately USD 2.93 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 14.30% CAGR from 2026–2035.

Market Opportunity: The ventilators market is expected to create an absolute dollar opportunity of USD 9.16 billion between 2026 and 2035, presenting significant investment potential across home ventilation, intelligent critical care platforms, and emergency transport systems.

According to Next Move Strategy Consulting analysis, purchasing decisions are shifting from stand alone device specifications toward fleet level value, where interoperability with patient monitoring, remote service access, and clinician workflow tools determine which manufacturers hospitals and home care providers standardize on through 2035.

What Does the Ventilators Market Encompass?

The ventilators market encompasses mechanical devices designed to assist or replace spontaneous respiration. Its scope spans critical care, acute non-invasive, transport, home, high-frequency, and specialty clinical environments. Our assessment indicates that the scope spans adult, pediatric, and neonatal patients served by hospitals, emergency medical services, rehabilitation and long-term care facilities, and households. The category evolved from basic life support equipment into software driven mechanical ventilators that combine lung protective modes, integrated monitoring, and connectivity for fleet management.
Regulatory frameworks shape design and commercialization in the ventilators market. In the United States, continuous ventilators are regulated by the Food and Drug Administration as Class II devices, while the European Union Medical Device Regulation 2017/745 governs conformity assessment in Europe, with transitional periods extended to 2027 and 2028. We observed that technology adoption is moving toward closed loop ventilation, integrated workflow software, and remote control. Next Move Strategy Consulting's analysis indicates that these shifts are redefining procurement criteria across the ventilators industry.

Market Drivers & Dynamics

Interactive Dataset
Rising burden of chronic respiratory disease driver +2.2% Global 2026–2035
Population ageing and shift to home respiratory care driver +1.9% North America, Europe, Asia-Pacific 2026–2035
ICU capacity expansion and fleet replacement driver +1.5% Asia-Pacific, Latin America, Middle East & Africa 2026–2033
Neonatal care investment amid preterm births driver +1.1% Asia-Pacific, Middle East & Africa 2026–2035
Intelligent ventilation and connectivity driver +1.0% North America, Europe 2026–2032
Emergency and prehospital capability build out driver +0.8% Global 2026–2035
Constrained hospital capital budgets restraint −1.4% Global 2026–2035
Regulatory compliance and field corrective actions restraint −0.9% Europe, North America 2026–2030
Clinician staffing and training gaps restraint −0.7% Asia-Pacific, Middle East & Africa 2026–2032
Price competition from regional manufacturers restraint −0.6% Asia-Pacific, Latin America 2026–2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Ventilators Market?

Chronic respiratory disease is the primary driver of the ventilators market. The World Health Organization reports that chronic obstructive pulmonary disease is the third leading cause of death worldwide, causing 3.4 million deaths in 2023 and ranking seventh in lost healthy life years. We observed that this burden sustains demand for acute non-invasive ventilation during exacerbations and for chronic home ventilation after discharge, anchoring volumes across Hospitals and Clinics and Home Care.

How Is Population Ageing Driving Ventilators Market Growth?

Older populations need more intensive care and long term respiratory support, which lifts the ventilators market. The United Nations projects that one in six people worldwide will be aged 65 or over by 2050, up from one in eleven in 2019. Our assessment indicates that this shift raises ICU admissions, extends length of stay, and supports Home Care and Long-Term Care adoption, which together account for about 26% of 2025 revenue.

Growth Inhibitors

What Is Restraining Ventilators Market Expansion?

Constrained capital budgets and compliance burdens restrain expansion of the ventilators market. Hospitals often defer fleet replacement until procurement cycles reopen, and manufacturers must absorb the cost of conformity assessment under the European Union Medical Device Regulation and Food and Drug Administration oversight. We found that field corrective actions raise service costs and prompt buyers to emphasize reliability, which lengthens sales cycles for smaller vendors.

What Are the Growth Opportunities?

Can Connected Home Ventilation Create Recurring Service Revenue?

Home ventilators capture usage, mask leak, and therapy adherence metrics, allowing homecare providers to remotely monitor patient status and unlock recurring telemetry services. Homecare and DME channels rising from USD 1.82 billion in 2025 to USD 4.81 billion in 2035 benefit most, because cloud platforms support proactive visits and consumable resupply. Vendors that combine devices with digital healthcare dashboards earn recurring revenue beyond the initial placement.

Will Neonatal ICU Expansion Open New Demand in High Burden Regions?

The World Health Organization estimates that 13.4 million babies were born preterm in 2020, with around 65% of preterm births occurring in sub-Saharan Africa and southern Asia. Neonatal units there need compact ventilators and consumables. Pediatric and Neonatal Only devices, growing at 8.28% CAGR from 2026 to 2035, benefit as governments expand pediatricmedical devices procurement and training programs.

How Can Fleet Management and Lifecycle Services Be Monetized?

Large hospital networks and national tenders create demand in the ventilators market for standardized fleets with managed maintenance. Dräger cited a major order from Mexico in 2025 that lifted its medical division order intake, showing the scale of such programs. Systems Integrator and Direct OEM channels capture this opportunity through bundled supply, training, and medical equipment maintenance contracts that raise lifetime value and strengthen customer retention.

Regulatory Framework Impacting the Ventilators Market

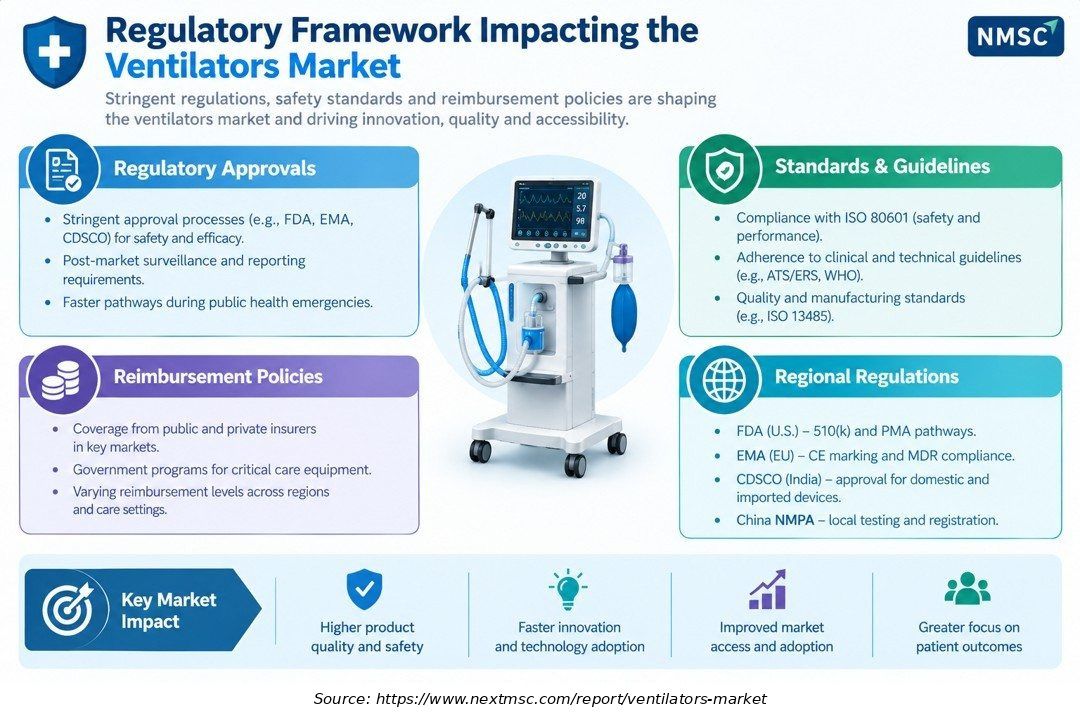
The ventilators market operates within a highly regulated medical-device environment where product safety, clinical performance, quality management, and post-market surveillance are essential. Regulatory frameworks enforced by authorities such as the US FDA, European Union Notified Bodies, and India's CDSCO—alongside ISO standards—dictate device development, commercialization, and reimbursement. These frameworks encourage manufacturers to strengthen compliance, innovation, reliability, and patient safety.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Critical Care Ventilators 2025: $3.27 Billion | 2035: $5.97 Billion
Critical Car
Acute NIV Ventilators 2025: $0.91 Billion | 2035: $1.73 Billion
Acute NIV Ve
Transport Ventilators 2025: $1.09 Billion | 2035: $2.51 Billion
Transport Ve
Home Ventilators 2025: $2.72 Billion | 2035: $6.93 Billion
Home Ventila
High-Frequency Ventilators 2025: $0.55 Billion | 2035: $0.96 Billion
High-Frequen
Specialty Ventilators 2025: $0.54 Billion | 2035: $1.16 Billion
Specialty Ve
Critical Care Ventilators $3.27 Billion $5.97 Billion 5.85%
Acute NIV Ventilators $0.91 Billion $1.73 Billion 6.28%
Transport Ventilators $1.09 Billion $2.51 Billion 8.35%
Home Ventilators $2.72 Billion $6.93 Billion 9.39%
High-Frequency Ventilators $0.55 Billion $0.96 Billion 5.36%
Specialty Ventilators $0.54 Billion $1.16 Billion 7.40%

Which Product Segment Dominates the Ventilators Market?

Critical Care Ventilators, covering General ICU and Neonatal ICU platforms, led the ventilators market with USD 3.27 billion in 2025, supported by high acuity demand and premium pricing. We observed that Home Ventilators are the fastest-growing product, expanding at a 9.39% CAGR from 2026 to 2035, as life support and chronic NIV devices migrate care out of hospitals. Specialty Ventilators, including MRI-compatible units that serve MRI suites, grow at 7.40%.

2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 25.0%
Category B $17.1 USD Billion $51.1 USD Billion 11.0%
Category C $24.2 USD Billion $62.2 USD Billion 25.0%
Category D $31.3 USD Billion $73.3 USD Billion 11.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Patient Type.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 27.0%
Category B $17.1 USD Billion $51.1 USD Billion 9.0%
Category C $24.2 USD Billion $62.2 USD Billion 19.0%
Category D $31.3 USD Billion $73.3 USD Billion 17.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Interface.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 14.0%
Category B $17.1 USD Billion $51.1 USD Billion 24.0%
Category C $24.2 USD Billion $62.2 USD Billion 22.0%
Category D $31.3 USD Billion $73.3 USD Billion 12.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Mobility.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 24.0%
Category B $17.1 USD Billion $51.1 USD Billion 22.0%
Category C $24.2 USD Billion $62.2 USD Billion 20.0%
Category D $31.3 USD Billion $73.3 USD Billion 22.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Ventilation Mode.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 23.0%
Category B $17.1 USD Billion $51.1 USD Billion 9.0%
Category C $24.2 USD Billion $62.2 USD Billion 19.0%
Category D $31.3 USD Billion $73.3 USD Billion 13.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 21.0%
Category B $17.1 USD Billion $51.1 USD Billion 23.0%
Category C $24.2 USD Billion $62.2 USD Billion 25.0%
Category D $31.3 USD Billion $73.3 USD Billion 15.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Commercial Channel.

Unlock Full Data

Growth Opportunities

We observed that three whitespace opportunities offer the clearest route to value creation as ventilation moves toward connected, decentralized care.

Can Connected Home Ventilation Create Recurring Service Revenue?

Home ventilators capture usage, mask leak, and therapy adherence metrics, allowing homecare providers to remotely monitor patient status and unlock recurring telemetry services. Homecare and DME channels rising from USD 1.82 billion in 2025 to USD 4.81 billion in 2035 benefit most, because cloud platforms support proactive visits and consumable resupply. Vendors that combine devices with digital healthcare dashboards earn recurring revenue beyond the initial placement.

Will Neonatal ICU Expansion Open New Demand in High Burden Regions?

The World Health Organization estimates that 13.4 million babies were born preterm in 2020, with around 65% of preterm births occurring in sub-Saharan Africa and southern Asia. Neonatal units there need compact ventilators and consumables. Pediatric and Neonatal Only devices, growing at 8.28% CAGR from 2026 to 2035, benefit as governments expand pediatricmedical devices procurement and training programs.

How Can Fleet Management and Lifecycle Services Be Monetized?

Large hospital networks and national tenders create demand in the ventilators market for standardized fleets with managed maintenance. Dräger cited a major order from Mexico in 2025 that lifted its medical division order intake, showing the scale of such programs. Systems Integrator and Direct OEM channels capture this opportunity through bundled supply, training, and medical equipment maintenance contracts that raise lifetime value and strengthen customer retention.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

Our findings suggest that competition in the industry is defined by clinical performance, software intelligence, service depth, and price positioning across care settings.

Dimension Description
Aspect Key Takeaways
Market Structure Moderately consolidated at the high acuity end, with global groups, regional specialists, and fast growing Asian manufacturers.
Innovation Focus Intelligent ventilation, effort monitoring, weaning support, remote control, and compact emergency and home platforms.
M&A Activity Portfolio pruning, selective acquisitions, and geographic entry are favored over large transformative combinations.

How Do Companies Compete in the Ventilators Market?

Companies in the ventilators market compete on clinical credibility, installed base, and total cost of ownership. We observed that Dräger, Getinge, and Hamilton Medical differentiate through lung protective tools and training, while Mindray and Comen compete on value and breadth. Geographic expansion is active, with Mindray entering the U.S. in March 2026 and Getinge launching Servo-c for targeted markets. Pricing strategies increasingly bundle consumables, software, and service contracts with devices.

Which Company Archetypes Dominate the Ventilators Industry?

Three archetypes dominate the ventilators market. Premium critical care specialists, including Dräger, Getinge, and Hamilton Medical, win on closed loop ventilation and clinical evidence. Diversified medical technology groups such as Philips, GE HealthCare, Mindray, and Nihon Kohden win on monitoring integration and enterprise contracts. Home respiratory leaders such as ResMed, Löwenstein Medical, Breas, and BMC Medical win on adherence data, accessories, and channel reach. Next Move Strategy Consulting's analysis indicates that these differentiation themes explain most share concentration.

What Innovation and Differentiation Strategies Are Shaping the Industry?

Innovation in the ventilators market centers on intelligence and portability. Hamilton Medical released HAMILTON-C6 software version 2.0.x in June 2026 and launched the HAMILTON-EM7 emergency ventilator in August 2026, while Mindray's SV series broadens its critical care offering. During our market evaluation, we noticed that vendors also invest in remote control, centralized alarms, and cybersecurity, since connected fleets must meet healthcare cybersecurity expectations from hospital buyers.

How Active Is M&A Activity in the Industry?

M&A in the ventilators market is selective. ResMed announced in August 2026 an agreement to sell its MatrixCare business. Regional specialists such as Magnamed, SIARE, and Flight Medical remain focal points for partnership and distribution deals. Based on research conducted by Next Move Strategy Consulting, we found that new market entry through direct subsidiaries and distributor networks is more common than large acquisitions among ventilator manufacturers.

Key Market Players

Our assessment indicates that the following twenty companies shape competition through critical care, transport, home, and specialty ventilation portfolios.

Drägerwerk AG & Co. KGaA Getinge AB Hamilton Medical AG Koninklijke Philips N.V. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. GE HealthCare Technologies Inc. ResMed Inc. ZOLL Medical Corporation Nihon Kohden Corporation Löwenstein Medical SE & Co. KG WEINMANN Emergency Medical Technology GmbH + Co. KG Air Liquide Medical Systems S.A. Shenzhen Comen Medical Instruments Co., Ltd. Breas Medical AB Beijing Aeonmed Co., Ltd. SIARE Engineering International Group S.p.A. Magnamed Tecnologia Médica S.A. Flight Medical Innovations Ltd. BMC Medical Co., Ltd. Resvent Medical Technology Co., Ltd.

Latest Developments

We found that 2025–2026 activity is concentrated on intelligent platforms, emergency transport launches, and geographic expansion by global and Asian manufacturers.

Date Event
September 2026 Mindray North America launched the SV70 non-invasive ventilator on September 15, 2026, expanding the company’s SV-Series with a turbine-driven, single-limb platform. The launch specifically addresses hospital demand for non-invasive ventilation equipment amid the withdrawal of Philips V60 systems, supporting fleet replacement and continuity of respiratory-care workflows.
July 2026 Nihon Kohden America announced three new capabilities for the NKV-550 Series on July 15, 2026: non-invasive muscle pressure monitoring, Adaptive Ventilation Mode, and adjustable AdaptiveSync. Together, the features provide continuous visibility into patient breathing effort while automating ventilation adjustments and synchronization, strengthening personalized ICU ventilation and weaning.
June 2026 Dräger announced the Evita V800 software 3.10 advancement on June 22, 2026. The release adds decelerating flow during volume-controlled ventilation, PEEP-FiO2 guidance maps, driving-pressure calculation, and semi-automated static-compliance assessment. These enhancements expand lung-protective ventilation and decision-support capabilities for patients with pulmonary disease, including ARDS.

PESTEL Analysis of the Ventilators Market

PESTEL Analysis of the Ventilators Market
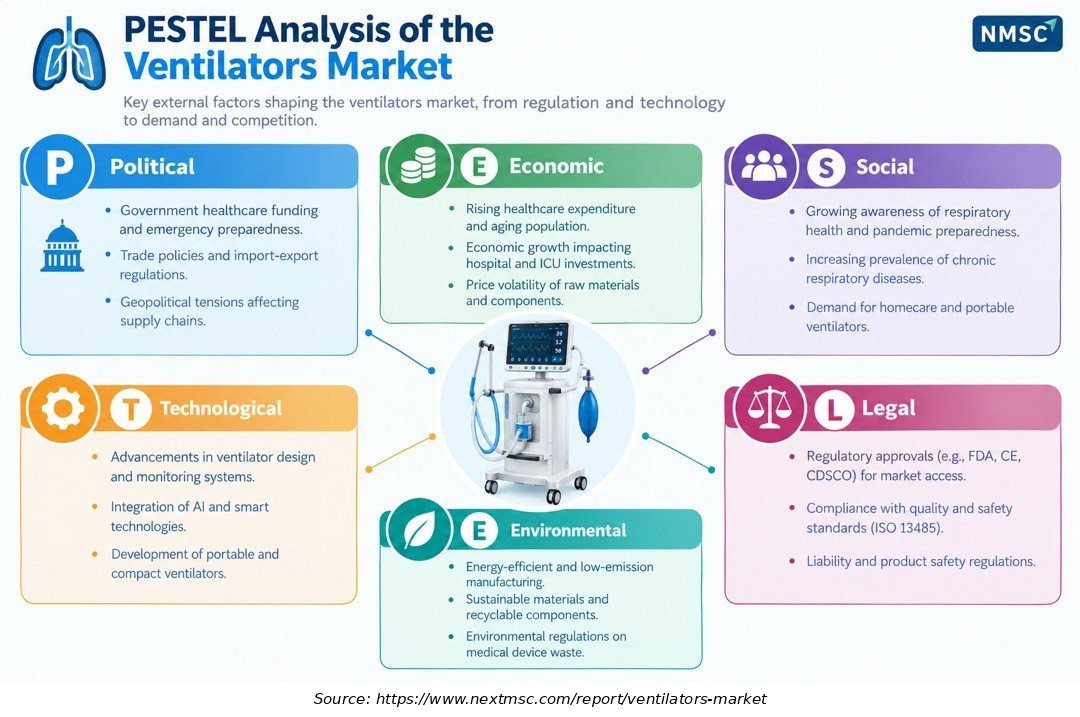
The PESTEL framework highlights the external forces shaping the ventilators market, including healthcare policies, expenditure trends, respiratory disease prevalence, technological innovation, environmental requirements, and regulatory obligations. Increasing healthcare investment, demand for critical-care infrastructure, smart monitoring technologies, and portable solutions create market opportunities, while supply-chain pressures, compliance requirements, material costs, and sustainability considerations influence strategic decisions.

Investment Opportunities

Where Is Capital Flowing in the Ventilators Industry?

Capital in the ventilators market is flowing toward intelligent critical care platforms, home respiratory devices, and market entry infrastructure. Mindray North America entered the U.S. ventilator market in March 2026, and ResMed generated USD 1.6 billion of free cash flow in fiscal 2026, returning more than USD 1 billion to shareholders while investing in digital capabilities. Investors can also target regional specialists and distributors serving fast growing Asia-Pacific and Latin America markets.

Which Infrastructure Investments Will Support Market Expansion?

Infrastructure investment in the ventilators market centers on ICU capacity, neonatal units, medical gas independence, and connected hospital networks. Ventilators that operate independent of wall gas and affordable high acuity platforms suit hospitals with limited infrastructure. The World Health Organization reports that over 90% of extremely preterm babies in low income countries die within days, underscoring the need for neonatal respiratory infrastructure in these regions.

How Do ESG Considerations Influence Investment in the Ventilators Market?

ESG factors increasingly guide capital allocation across the ventilators market. Social impact is significant, since the World Health Organization estimates that 13.4 million babies were born preterm in 2020 and chronic obstructive pulmonary disease caused 3.4 million deaths in 2023. Environmental considerations include energy efficient turbines, longer device lifecycles, and refurbishment programs, while governance relies on post market surveillance and corrective action transparency required by the Food and Drug Administration and European regulators.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Executives gain a segmented forecast from USD 9.08 billion in 2025 to USD 19.26 billion in 2035, with product, patient type, interface, mobility, ventilation mode, end user, and channel detail that supports portfolio choices. The competitive landscape, company benchmarking, and trend analysis help leaders prioritize intelligent ventilation, home platforms, and emerging market entry within the ventilators market.

How Does This Report Benefit Investors and Financial Analysts?

Investors receive an absolute dollar opportunity of USD 9.16 billion between 2026 and 2035, country level CAGRs, and a risk matrix that quantifies drivers and restraints. The analysis identifies where returns concentrate, including Home Ventilators at 9.39% CAGR and Asia-Pacific at 9.86%, and highlights regulatory and budget risks that influence valuation and timing.

How Does This Report Benefit Technology Vendors and Product Teams?

Vendors and product teams gain insight into ventilation modes, interfaces, and mobility formats, including segment level growth for Combined Control at 10.12% CAGR and Dual Capability at 9.09%. The report maps regulatory pathways, connectivity expectations, and channel dynamics that shape design roadmaps, helping teams time launches and align service models with buyer needs.

Key Market Segments Evaluated

By Product

  • Critical Care Ventilators 
    • General ICU
    • Neonatal ICU
  • Acute NIV Ventilators
  • Transport Ventilators 
    • Prehospital
      • Ambulance
      • Air Medical
      • Field and Disaster
    • In-Hospital
  • Home Ventilators 
    • Life-Support
    • Chronic NIV
  • High-Frequency Ventilators 
    • High-Frequency Jet
    • High-Frequency Oscillatory
  • Specialty Ventilators 
    • Hyperbaric
    • MRI-Compatible
    • Other Specialty Environment

By Patient Type

  • Adult Only
  • Pediatric and Neonatal Only
  • Mixed Age

By Interface

  • Invasive Only
  • Non-Invasive Only
  • Dual Capability

By Mobility

  • Bedside
  • Transportable
  • Home Portable

By Ventilation Mode

  • Volume Control
  • Pressure Control
  • Combined Control
  • Other Modes

By End User

  • Hospitals and Clinics
  • Ambulatory Care Centers
  • Emergency Medical Services
  • Rehabilitation Centers
  • Home Care
  • Long-Term Care

By Commercial Channel

  • Direct OEM
  • Distributor and Dealer
  • Homecare and DME
  • Systems Integrator

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico.
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe.
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC.
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA.
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM.

Conclusion & Recommendations

Our assessment indicates that the ventilators market will expand from USD 10.10 billion in 2026 to USD 19.26 billion in 2035 at a 7.44% CAGR, adding USD 9.16 billion in absolute value. Growth is supported by chronic respiratory disease, population ageing, and ICU modernization, and Asia-Pacific, at 9.86% CAGR, is forecast to close much of the gap with North America by 2035.

Strategic Positioning Recommendations

Manufacturers in the ventilators market should prioritize intelligent ventilation, dual capability platforms, and compact home and transport devices, supported by remote service and training. Regional strategies should pair premium positioning in North America and Europe with affordable high acuity ranges in Asia-Pacific, Latin America, and Middle East & Africa. Home Care and Homecare and DME channels, growing at 10.14% and 9.82% CAGR, merit dedicated offerings.

Investment Attractiveness

We found that investment attractiveness is highest in Home Ventilators at 9.39% CAGR, Combined Control at 10.12%, and India at 14.30%. Recurring consumables and service contracts improve earnings quality, while the U.S. and Germany provide scale and stability. Investors should weigh USD 9.16 billion of incremental opportunity against budget, regulatory, and price competition risks.

Market Shifts and Key Risks

Key shifts in the ventilators market include movement from hospital to home, from manual to guided ventilation, and from product sales to lifecycle services. Risks include constrained capital budgets, regulatory transitions under the European Union Medical Device Regulation, field corrective actions, and price competition from regional manufacturers. Our analysis shows that vendors with strong clinical evidence, reliable service, and transparent quality systems will be best placed.

Growth Pathways

Growth pathways in the ventilators market include connected home ventilation, neonatal ICU expansion in high burden regions, prehospital transport platforms, and managed fleet services. Emerging markets in South Asia, Southeast Asia, and the Middle East offer expansion as ICU capacity grows. Based on research conducted by Next Move Strategy Consulting, we found that companies combining intelligent software, affordable hardware tiers, and dependable service will capture the largest share of growth.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Global Trade Flow Assessment
  • Country-wise import and export analysis of ventilators and key components using HS-coded customs data from UN Comtrade and WITS.
  • Identifies supply-dependent countries and export hubs to guide sourcing, distributor selection, and localization decisions.
Company-Level Product Share Analysis
  • Company-level share analysis across ventilator product categories, including invasive, non-invasive, transport, and home-care ventilators.
  • Shows where competitors hold leadership and where portfolio gaps create entry or expansion opportunities.
Historical Unit Shipment and Revenue Analysis
  • Historical ventilator shipment, installed-unit, and revenue analysis by product, end user, and region.
  • Establishes a fact-based baseline of demand cycles, including pandemic-driven spikes, to anchor forecasts and investment timing.
Installed Base and Replacement Demand Forecasting
  • Ventilator installed-base and replacement-cycle forecast by hospital ICU bed capacity and device age across key countries.
  • Quantifies recurring replacement demand versus new capacity demand, supporting service contracts and capital planning.
Patient Type and Interface Adoption Mapping
  • Adoption mapping of ventilators by patient type (adult, pediatric, neonatal) and interface (invasive versus non-invasive) across care settings.
  • Pinpoints high-growth patient and interface segments to prioritize R&D, pediatric variants, and non-invasive product development.
Commercial Channel Pricing and Tender Benchmarking
  • Benchmarking of ventilator pricing and award terms across direct hospital sales, distributors, and government tender and stockpile procurement.
  • Supports channel strategy and pricing decisions by showing price realization and tender win patterns by channel and region.

FAQs

About the Author

Mihul Sharma

Mihul Sharma

Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖