Warehouse ASRS Market Enters a New Era as Honeywell Reshapes Competition | NextMSC
Introduction
The global warehouse automation landscape is undergoing a structural transformation, and automated storage and retrieval systems (ASRS) sit at the center of it. As e-commerce order volumes compound, urban real estate costs escalate, and warehouse labor pools contract, operators across every major geography are replacing manual storage architectures with high-density, software-orchestrated ASRS infrastructure — not as a discretionary upgrade, but as a prerequisite for competitive throughput.
According to Next Move Strategy Consulting's Warehouse Automated Storage and Retrieval System (ASRS) Market report, the global warehouse ASRS market was valued at USD 6.87 billion in 2025 and is projected to reach USD 22.74 billion by 2035, growing at a CAGR of 11.46% from 2026 to 2035. The market is expected to reach USD 8.56 billion by the end of 2026 alone, reflecting the accelerating pace of capital commitment across greenfield and brownfield deployments worldwide. In volume terms, NMSC primary research and analysis projects unit installations to scale from 24.31 thousand units in 2025 to 94.06 thousand units by 2035, at a volume CAGR of 13.04% — a rate that outpaces revenue growth and signals meaningful price compression as modular and as-a-service models broaden market access.
For More Information: Download FREE Sample on Warehouse Automated Storage and Retrieval System Market Report
Competitive Realignment and the Honeywell Intelligrated Divestiture: A Turning Point for the ASRS Industry
The Defining Corporate Event of 2026
The most consequential competitive development in the warehouse ASRS market in 2026 was not a product launch or a greenfield deployment — it was a divestiture. On July 27, 2026, Honeywell Technologies (NASDAQ: HON) completed the all-cash sale of its Warehouse and Workflow Solutions (WWS) business — operating commercially under the Intelligrated and Transnorm brands — to American Industrial Partners (AIP).
Vimal Kapur, Chairman and CEO of Honeywell Technologies, stated in the official press release: "The completion of the WWS divestiture further sharpens Honeywell Technologies as a pure-play automation company. We are poised to lead the industrial sector's transition from automation to autonomy, and this sale enables us to focus more fully on that task, accelerating long-term value creation for our customers and shareowners."
This divestiture followed Honeywell's spin-off of its Aerospace Technologies business as an independent public company (Nasdaq: HONA) on June 29, 2026, and the earlier spin-off of Solstice Advanced Materials (Nasdaq: SOLS) on October 30, 2025. Since 2023, Honeywell has completed approximately USD 11.5 billion in acquisitions while simultaneously shedding non-core assets — a portfolio restructuring that signals a decisive pivot away from warehouse hardware integration toward industrial autonomy software.
The practical consequence for the ASRS market is significant: Intelligrated, one of North America's most established conveyor and sortation integrators, now operates as an independent entity under private equity ownership. This removes a major incumbent from the integrated automation conglomerate tier and creates a window for pure-play ASRS specialists — including Dematic, SSI SCHAEFER Group, and emerging players such as Exotec — to capture enterprise accounts that previously defaulted to Honeywell's bundled portfolio.
Concurrent Innovation: Exotec's Skypod Momentum and the Decathlon Benchmark
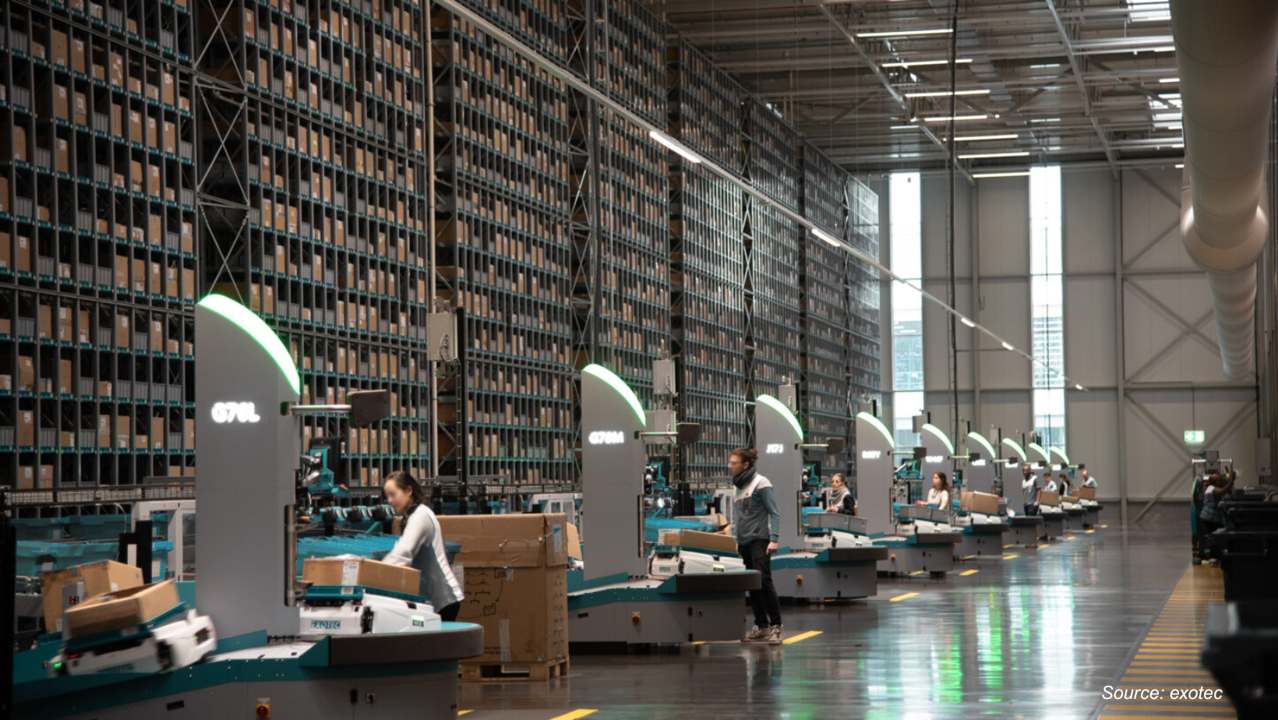
While Honeywell's exit reshaped the competitive supply side, Exotec's recognition as one of Fast Company's World's Most Innovative Companies of 2026 (ranked No. 8 in the Logistics category, announced March 24, 2026) underscored the accelerating shift toward modular, robot-based ASRS architectures.
Exotec's Skyfleet program with Decathlon — a global sportswear brand operating across 72 countries — standardized European fulfillment operations and delivered a 100% increase in order picking throughput. The company's Oxford Industries deployment (Tommy Bahama, Lilly Pulitzer) processes more than 20 million units per year using more than 450 robots supporting both B2B and B2C fulfillment. Across its 200+ global sites, Exotec customers report picking speed improvements of 60%, order capacity increases of up to 50%, and customer order wait time reductions of over 70%.
Most recently, in September 2026, GXO Logistics and Exotec announced a partnership to automate fashion fulfillment for Guess in the Netherlands — extending the Skypod system's footprint into European apparel logistics, a segment historically resistant to full ASRS integration due to SKU variability.
NMSC Strategic Perspective: What These Developments Signal for the Market
NMSC primary research and analysis identifies three structural implications from the Honeywell divestiture and the concurrent rise of modular ASRS specialists:
-
First, the enterprise ASRS procurement landscape is bifurcating. Large-scale, multi-site operators with complex WMS/WCS integration requirements will continue to favor established intralogistics integrators such as Daifuku Co., Ltd., Dematic, and SSI SCHAEFER Group — vendors whose system reliability, global service networks, and software depth justify premium contract values. However, mid-market operators and omnichannel retailers are increasingly evaluating modular, goods-to-person systems from Exotec, AutoStore, and KNAPP AG, where standardized APIs and phased deployment reduce integration risk and upfront capital exposure.
-
Second, the divestiture of Intelligrated to private equity signals that warehouse automation hardware, absent a software-led recurring revenue layer, is increasingly viewed as a low-multiple asset. This reinforces NMSC's assessment that the most defensible competitive positions in the ASRS market belong to vendors who combine physical storage infrastructure with proprietary WCS, WES, and analytics platforms — creating switching costs that extend well beyond the hardware lifecycle.
-
Third, the Exotec-Decathlon and GXO-Guess deployments demonstrate that ASRS adoption is no longer confined to high-volume, low-SKU environments. As robotic picking intelligence improves, the addressable market for goods-to-person ASRS is expanding into apparel, fashion, and general merchandise — segments that collectively represent a substantial share of global e-commerce fulfillment volume.
Section Summary:
The Honeywell Intelligrated divestiture and Exotec's accelerating deployment momentum collectively define the competitive inflection point of 2026 in the warehouse ASRS market.
-
Honeywell's exit from warehouse automation hardware removes a major bundled-portfolio incumbent, opening enterprise accounts to pure-play ASRS specialists.
-
Exotec's Decathlon deployment — delivering a 100% increase in order picking — establishes a new performance benchmark for modular, robot-based ASRS at scale.
-
NMSC analysis identifies software-led recurring revenue as the primary determinant of competitive durability in the ASRS market, with hardware-only positions increasingly vulnerable to margin compression.
-
The addressable market for goods-to-person ASRS is expanding beyond traditional high-volume, low-SKU environments into apparel and fashion logistics.
Industry Impact Analysis
E-Commerce Volume Growth Converts Warehouse Space Constraints into ASRS Demand
The DHL 2026 E-Commerce Trends Report — based on surveys of 29,000 online shoppers and 5,800 e-commerce businesses across 29 countries — found that 70% of shoppers now buy internationally, up 10 percentage points year-on-year from 60% in 2025, with 45% purchasing cross-border more than once per month. This sustained cross-border volume growth translates directly into demand for high-throughput, high-density ASRS within international distribution hubs, where order accuracy and retrieval speed are non-negotiable service-level requirements.
According to Daifuku's January 2026 industry analysis, large centralized distribution centers are consolidating multiple regional nodes into fewer, higher-capacity facilities to improve labor utilization and truck fleet efficiency — a structural shift that concentrates ASRS investment into larger, more complex deployments rather than distributing it across smaller sites. High-capacity AS/RS, shuttle systems, and sortation systems are the primary technologies selected for these environments, chosen specifically for their ability to sustain throughput under demand variability without operational disruption.
Labor Market Structural Pressures Accelerate Automation Timelines
The U.S. Bureau of Labor Statistics Employment Situation report (released October 2, 2026) confirms that the U.S. labor market remains tight, with employers posting 7.6 million job openings in May 2026 — the highest level since 2024. Within the logistics and warehousing sector, this persistent labor scarcity is not a cyclical phenomenon but a structural one: an aging workforce, declining participation rates among prime-age workers in physically demanding roles, and wage inflation in fulfillment operations are collectively compressing operator margins and making the ROI case for ASRS investment increasingly straightforward.
Michael Jerogin, CEO of Dematic APAC, articulated this dynamic in Dematic's 2026 press release: "Labour constraints in logistics are no longer temporary disruptions, they are structural realities. If organisations are still relying on workforce expansion alone to increase output, they are exposed. The question is not whether automation is relevant, but whether you can consistently meet customer expectations without it."
NMSC primary research and analysis confirms that this labor-driven automation imperative is most acute in North America, Western Europe, Japan, and South Korea — markets where warehouse wage inflation and workforce availability constraints are compressing operator margins and accelerating ASRS adoption timelines by one to two years relative to pre-2024 projections.
Daifuku's Shiga Works Expansion: Semiconductor-Linked ASRS Demand Emerges
In April 2026, Daifuku Co., Ltd. completed construction of a new factory building at its Shiga Works hub in Japan, dedicated specifically to transport and storage systems for semiconductor production. The facility increases cleanroom production capacity by 30% to meet surging demand driven by AI chip manufacturing and semiconductor market growth. This development signals an emerging demand vector for ASRS beyond traditional e-commerce and logistics: semiconductor fabs and advanced manufacturing facilities require ultra-precise, contamination-controlled automated storage systems that command significant per-unit value and long-term service contracts.
Balanced Automation Replaces Rapid Adoption as the Industry's Operating Philosophy
Daifuku's 2026 industry analysis identifies a decisive shift in how warehouse operators approach automation investment: "Rather than chasing novelty, companies are looking for balance between scale and flexibility, investment and return, and innovation and operational stability." Four-way shuttle systems are specifically highlighted as a technology that enables significantly higher throughput while maintaining high storage density — and whose modular nature allows capacity to be scaled incrementally by extending storage blocks or adding shuttles, directly addressing the capital sensitivity that has historically constrained mid-market ASRS adoption.
Section Summary:
The industry impact of current market forces is measurable, multi-dimensional, and reinforcing.
-
Cross-border e-commerce volume — with 70% of global shoppers now purchasing internationally per DHL's 2026 survey — is concentrating ASRS demand in high-throughput international distribution hubs.
-
Structural labor scarcity, confirmed by BLS data showing 7.6 million U.S. job openings in May 2026, is compressing operator margins and accelerating ASRS investment timelines.
-
Daifuku's 30% cleanroom capacity expansion at Shiga Works signals semiconductor manufacturing as an emerging, high-value ASRS demand vertical.
-
The industry's operating philosophy has shifted from rapid adoption to balanced automation — favoring modular, scalable systems with demonstrable ROI over large-scale, monolithic deployments.
Pros and Cons of Recent Market Developments
|
Development |
Pros |
Cons |
|
Honeywell's Intelligrated Divestiture to AIP (July 2026) |
Opens enterprise ASRS accounts to pure-play specialists; Honeywell refocuses on higher-margin autonomy software; AIP ownership may accelerate Intelligrated's product investment |
Potential service continuity uncertainty for existing Intelligrated customers during ownership transition; loss of Honeywell's global service network backing |
|
Exotec's Decathlon Skyfleet Deployment (100% picking increase) |
Establishes a replicable, standardized ASRS model for multi-country retail networks; validates modular ASRS in high-SKU environments; reduces integration complexity for future deployments |
Standardized architecture may limit customization for operators with highly specific workflow requirements |
|
Daifuku Shiga Works 30% Cleanroom Capacity Expansion (April 2026) |
Expands ASRS supply capacity for semiconductor and advanced manufacturing verticals; reduces lead times for high-precision systems |
Capacity concentrated in Japan; geopolitical or supply chain disruptions could affect global delivery timelines |
|
ASRS-as-a-Service (RaaS) Model Expansion |
Converts capital expenditure to predictable operational expenditure; enables mid-market operators to access advanced ASRS without large upfront investment; includes maintenance and upgrades |
Vendor lock-in risk over multi-year subscription terms; total cost of ownership may exceed CapEx models for high-utilization facilities |
|
AI-WMS Predictive Slotting Integration |
Reduces retrieval times during demand surges; pre-positions high-velocity SKUs during off-peak hours; minimizes last-minute reshuffling and operational disruption |
Requires high-quality, real-time data infrastructure; integration complexity increases deployment timelines and IT resource requirements |
|
Four-Way Multi-Shuttle Fleet Adoption |
Enables parallel processing across multiple rack levels simultaneously; provides inherent redundancy — individual unit maintenance does not halt operations; scales throughput without proportional footprint expansion |
Higher per-unit hardware cost relative to traditional crane-based systems; requires sophisticated fleet management software for optimal task distribution |
NMSC Warehouse ASRS Market — Segment Share Breakdown (2025)
|
Segment |
Leading Sub-Segment |
Share (2025) |
|
System Type & Core Technology |
Fixed-Path / Rail-Based Systems |
31.88% |
|
Operational Mode |
Fully Automated (No-Human-in-Loop) |
45.26% |
|
Primary System Application |
Order Fulfillment & Piece Picking |
25.27% |
|
Commercial Model |
As-a-Service / Subscription |
39.10% |
|
Payload & Load Carrier |
Mini-Load (30 kg – 500 kg) |
36.45% |
|
End-User Vertical Industry |
Distribution & Logistics |
38.90% |
|
Deployment Scenario |
Greenfield Installation |
32.93% |
Future Outlook & Forecast
The Decade Ahead: From Storage Infrastructure to Demand-Aware Fulfillment Architecture
NMSC primary research and analysis projects the global warehouse ASRS market to reach USD 22.74 billion by 2035, growing at a CAGR of 11.46% from 2026 to 2035. The volume trajectory — from 24.31 thousand units in 2025 to 94.06 thousand units by 2035 at a 13.04% volume CAGR — indicates that unit price compression through modular and as-a-service models will broaden market access faster than revenue growth alone suggests.
Asia-Pacific will be the primary growth engine, with a projected CAGR of 14.05% — the highest of any region. India's warehouse ASRS market, currently representing 9.76% of Asia-Pacific demand, is projected to grow at a CAGR of 21.48%, driven by rapid e-commerce infrastructure development and ongoing warehouse modernization. Indonesia follows at a projected CAGR of 19.31%, reflecting urban logistics expansion and scaling e-commerce distribution networks. These two markets alone represent a combined growth opportunity that will materially reshape the global competitive landscape for ASRS vendors with localized integration capabilities.
In North America, the consolidation of regional distribution nodes into larger, higher-capacity facilities — as identified in Daifuku's 2026 industry analysis — will sustain demand for high-throughput, crane-based and shuttle-based ASRS systems integrated with WMS and WCS platforms. The U.S. accounts for 70.36% of North American ASRS demand, and the combination of persistent labor scarcity and rising warehouse real estate costs will sustain capital commitment to automation through the forecast period.
The As-a-Service commercial model — already the leading model with 39.10% share in 2025 — will continue to expand its share as subscription-based and usage-linked pricing structures reduce the capital barrier for mid-market operators. NMSC analysis identifies this model as the primary mechanism through which the addressable market will expand beyond large enterprises into the mid-market segment, particularly in India, Southeast Asia, and Latin America.
AI-integrated WMS platforms will increasingly define system differentiation. Warehouses leveraging external data signals — social media trends, seasonal demand patterns, weather forecasts — to pre-position high-velocity SKUs during off-peak hours are already demonstrating measurable reductions in retrieval times and operational disruptions during demand surges. As these capabilities mature, ASRS systems will transition from reactive storage infrastructure to proactive, demand-aware fulfillment architectures — a shift that will expand the software revenue layer and strengthen vendor switching costs.
The "dark warehouse" concept — fully autonomous storage environments where oxygen-reduction systems are integrated with ultra-dense vertical racking to eliminate human movement constraints — represents the long-term architectural endpoint for the highest-throughput ASRS deployments. While broad adoption remains a medium-to-long-term development, NMSC analysis indicates that operators designing new greenfield facilities in 2026 are already incorporating dark warehouse principles into their infrastructure specifications.
Section Summary:
The warehouse ASRS market's growth trajectory through 2035 is underpinned by structural demand drivers that are geography-specific, technology-specific, and commercially diverse.
-
NMSC projects the market to reach USD 22.74 billion by 2035 at an 11.46% CAGR, with volume installations reaching 94.06 thousand units at a 13.04% volume CAGR.
-
Asia-Pacific leads at a 14.05% CAGR, with India (21.48%) and Indonesia (19.31%) representing the highest-growth individual markets.
-
The As-a-Service commercial model — already the leading model at 39.10% share — will be the primary mechanism for mid-market ASRS adoption in emerging economies.
-
AI-WMS predictive slotting is transitioning ASRS from reactive storage infrastructure to demand-aware fulfillment architecture, expanding the software revenue layer and strengthening vendor competitive moats.
Next Steps for Stakeholders
For C-Level Executives at Warehouse Operators and 3PLs:
The Honeywell Intelligrated divestiture creates a near-term procurement window. Operators with existing Intelligrated service contracts should conduct a vendor continuity assessment and evaluate whether the transition to AIP ownership affects SLA commitments, software upgrade roadmaps, and integration support. Simultaneously, the competitive landscape now includes a broader set of pure-play ASRS specialists — Exotec, AutoStore, KNAPP AG — whose modular architectures and standardized APIs may offer faster deployment and lower integration risk for brownfield expansion projects.
Prioritize ASRS investments in facilities where labor costs exceed 30% of total operating expenditure, where storage density utilization exceeds 80%, or where same-day and next-day delivery SLAs are creating throughput bottlenecks. These three conditions, in combination, generate the strongest ROI case for ASRS deployment and the shortest payback periods.
For Investors and Private Equity:
NMSC analysis identifies the most defensible investment positions in the ASRS market as vendors combining physical storage infrastructure with proprietary WCS, WES, and analytics platforms. Hardware-only positions face margin compression as modular and as-a-service models commoditize the physical layer. Target companies that demonstrate recurring software revenue as a percentage of total revenue, multi-site deployment track records, and API-driven integration architectures that reduce customer switching costs.
Asia-Pacific — particularly India and Indonesia — represents the highest-growth regional opportunity, with projected CAGRs of 21.48% and 19.31% respectively. Vendors with localized manufacturing, integration partnerships, and cost-optimized product lines for these markets are positioned to capture disproportionate share of the decade's incremental volume growth.
For System Integrators and Technology Partners:
The shift toward hybrid automation architectures — combining fixed ASRS with mobile robotics (AMRs/ACRs) — creates integration complexity that favors system integrators with cross-platform software expertise. Invest in WCS/WES capabilities that enable real-time task orchestration across heterogeneous automation fleets. The ability to integrate ASRS with AI-driven predictive slotting, digital twin platforms, and real-time analytics will be the primary differentiator in competitive bids through 2030.
Conclusion
The warehouse ASRS market in 2026 is defined by three converging forces: a competitive realignment triggered by Honeywell's divestiture of Intelligrated, a technology maturation cycle that is shifting operator preference from rapid adoption to balanced, ROI-driven automation, and a structural demand foundation — labor scarcity, e-commerce volume growth, and urban real estate constraints — that shows no sign of abating. NMSC primary research and analysis projects the market to grow from USD 8.56 billion in 2026 to USD 22.74 billion by 2035 at an 11.46% CAGR, with Asia-Pacific leading at 14.05% and the As-a-Service commercial model expanding market access beyond large enterprises into the mid-market segment globally.
The vendors who will capture disproportionate value over this decade are those who treat ASRS not as a hardware sale but as a platform — combining high-density storage infrastructure with proprietary software orchestration, lifecycle services, and data-driven optimization capabilities that compound in value with each year of deployment. For executives and investors navigating this market, the strategic imperative is clear: the transition from automation to autonomy in warehouse operations has begun, and the window for establishing platform-level competitive positions is narrowing.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment