What’s Driving the Lab-Grown Diamonds Market in 2025?
Introduction
The global lab grown diamonds market is undergoing one of the most consequential structural shifts in the history of the gemstone industry — simultaneously expanding in volume and contracting in per-unit value, while carving out an entirely new industrial frontier. According to Next Move Strategy Consulting's Lab Grown Diamonds Market report, the global lab grown diamonds market is projected to reach USD 34.06 billion by 2030, growing at a CAGR of 8.8% from 2024 to 2030. This trajectory is not driven by a single tailwind but by the convergence of accelerating production efficiency, shifting consumer demographics, government-backed manufacturing incentives, and the emergence of synthetic diamonds as a critical input for semiconductor and quantum computing technologies.
What makes the current moment particularly significant is the market's bifurcation: lab grown diamonds are capturing an ever-larger share of diamond volume globally, yet their monetary value per carat continues to decline sharply relative to natural stones. This dynamic is reshaping competitive strategies across the entire diamond value chain — from mining conglomerates to independent jewelers — and creating distinct investment theses for different segments of the market.
For More Information: Download FREE Sample on Lab Grown Diamonds Market Report
The Lightbox Closure and India's Export Milestone: A Market at an Inflection Point
De Beers Exits the Lab Grown Jewelry Segment — and What It Actually Signals
On May 8, 2025, De Beers Group announced its intention to close Lightbox, its lab grown diamond jewelry brand that had been operational since 2018. The closure was not a retreat from the synthetic diamond space entirely — De Beers' subsidiary Element Six retains its exclusive focus on industrial synthetic diamond applications, including semiconductors and quantum technologies, centralizing CVD production at its Oregon facility.
The strategic rationale was explicit. Al Cook, Chief Executive Officer of De Beers Group, stated: "The persistently declining value of lab-grown diamonds in jewellery underscores the growing differentiation between these factory-made products and natural diamonds. LGD prices in the jewellery sector have fallen 90% at wholesale since Lightbox launched at $800 per carat in 2018. Global competition continues to intensify with more low-cost lab-grown diamond production from China. In the US, supermarkets are driving down lab-grown diamond jewellery prices. Overall, we expect both the cost and price of lab-grown diamonds to fall further in the jewellery sector."
This is a pivotal signal for the market. The Lightbox closure does not indicate that demand for lab grown diamonds is weakening — it indicates that the jewelry segment of the lab grown diamond market is commoditizing at a pace that makes premium-brand positioning structurally unviable. The competitive pressure is coming directly from China's manufacturing scale: according to the Gems and Jewellery Trade Association, China accounted for approximately 40–50% of global lab grown diamond production capacity at 20 million carats, making it the world's largest producer.
For investors and C-suite decision-makers, the Lightbox closure reframes the competitive landscape: the jewelry segment of the lab grown diamond market will increasingly be contested on cost efficiency and distribution scale, not brand equity. The premium value proposition in synthetic diamonds is migrating toward industrial and high-tech applications — a segment where De Beers' Element Six is doubling down.
India's Export Milestone: Volume Leadership Without Value Parity
In March and April 2026, India's lab grown diamond exports surpassed natural diamond exports by volume for the first time on a sustained basis — a development described by industry analyst Edahn Golan as "a major shift, arguably a tectonic one." According to figures from India's Gem & Jewellery Export Promotion Council (GJEPC) cited by Golan, lab grown exports totaled approximately 1.3 million carats in March and 1.4 million carats in April 2026, compared with 1.2 million and 1.3 million carats, respectively, for natural diamonds.
However, the value gap remains stark: despite their volume dominance, lab grown diamonds account for less than 9% of India's wholesale diamond exports in monetary value. This divergence — high volume, low value — is the defining commercial tension of the lab grown diamond market in its current phase.
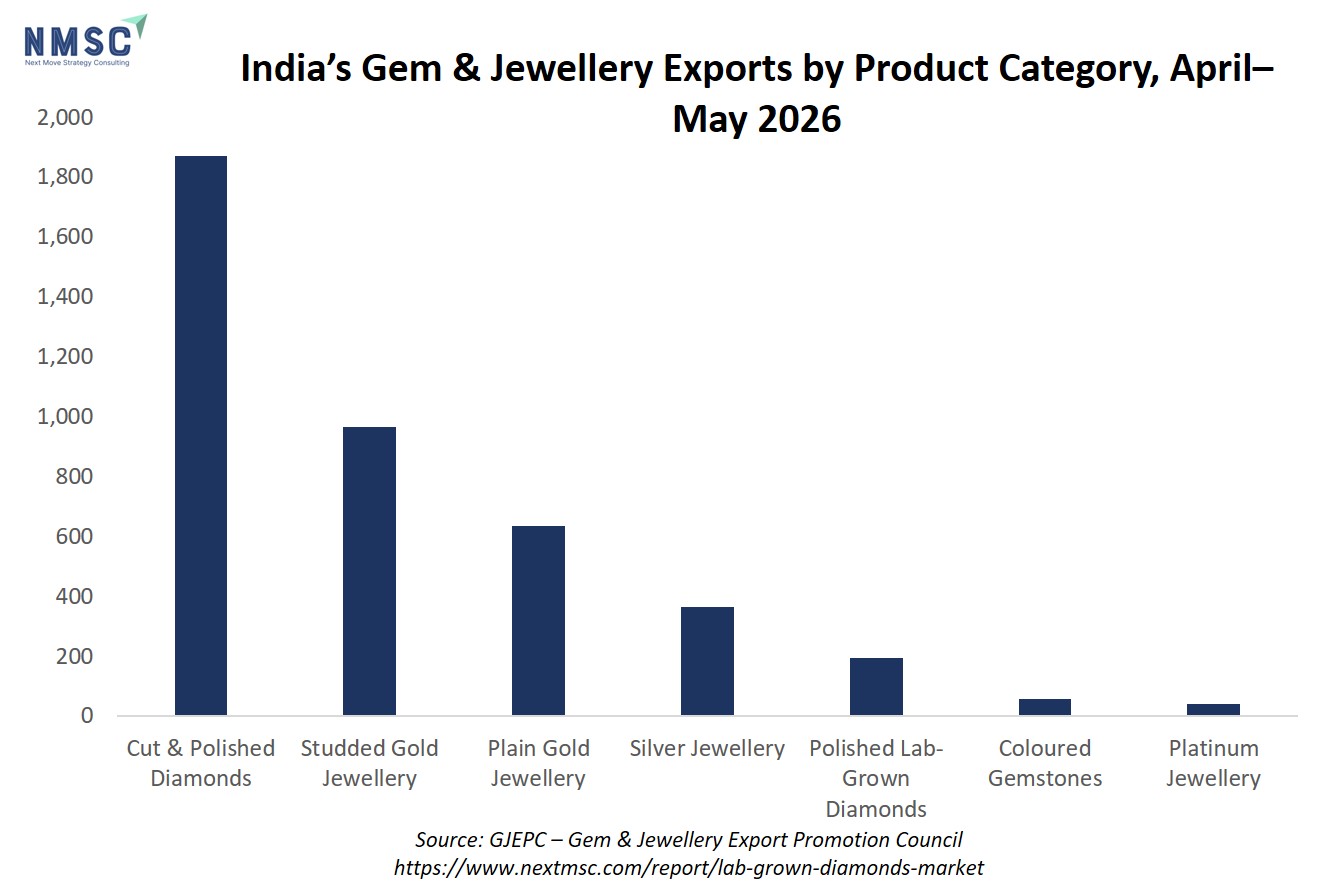
India's ascent as a lab grown diamond export hub is underpinned by deliberate government policy. The Indian government approved ₹242.96 crore over five years to establish a lab grown diamond research center at IIT Madras, aimed at enabling domestic production and reducing import reliance. The Union Budget 2026 continued customs duty support for domestic lab grown diamond manufacturing, further incentivizing local production capacity.
NMSC Strategic Perspective: Reading the Bifurcation Correctly
NextMSC primary research and analysis identifies the current market bifurcation — volume growth without proportional value growth — as the central strategic variable for the forecast period through 2030. The 8.8% CAGR projected by NMSC reflects a market that is expanding in total addressable revenue, driven by three distinct demand pools that are growing at different rates and for different reasons.
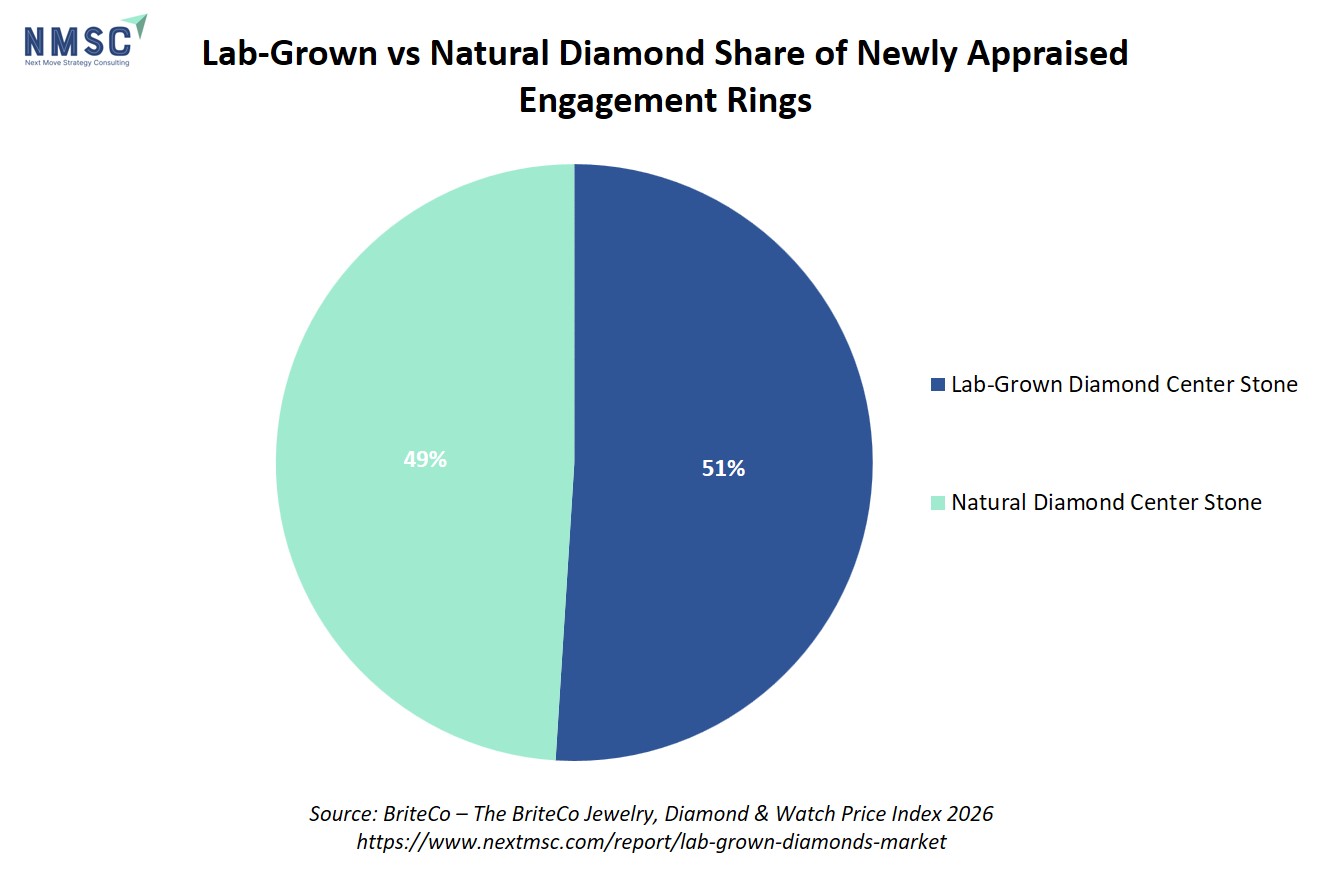
First, the fashion and jewelry segment continues to attract volume-driven growth, particularly among millennial and Gen Z consumers who prioritize carat size and design over provenance. The BriteCo Jewelry, Diamond & Watch Price Index reports that lab grown diamond market share across every diamond jewelry category reached 47% of new appraisals in the first half of 2026. This is a structural shift in consumer behavior, not a cyclical one.
Second, the industrial application segment — encompassing cutting tools, abrasives, thermal management systems, and increasingly, semiconductor substrates and quantum computing components — represents the highest-margin growth vector for synthetic diamond producers. De Beers' decision to concentrate Element Six's CVD production capacity on industrial and high-tech applications is a direct bet on this segment's long-term value creation potential.
Third, the AI-powered grading and certification segment is emerging as a market enabler. AI grading systems trained on large diamond datasets are reducing human subjectivity in evaluating cut, clarity, color, and carat weight — improving quality consistency across lab grown diamond production at scale, which in turn supports consumer confidence and retail pricing stability.
Section Summary:
The lab grown diamonds market is not a monolithic growth story — it is a market in structural bifurcation, with volume leadership decoupling from value leadership. The De Beers Lightbox closure and India's export milestone are two sides of the same coin: commoditization in jewelry is accelerating, while industrial and high-tech applications are emerging as the next value frontier.
Key Takeaways:
-
De Beers closed Lightbox in May 2025 after lab grown diamond wholesale prices fell 90% since 2018, signaling that jewelry-segment brand premiums are no longer commercially sustainable.
-
India's lab grown diamond exports surpassed natural diamonds by volume in March and April 2026 (GJEPC data), but LGDs account for less than 9% of India's wholesale diamond export value.
-
China controls 40–50% of global lab grown diamond production capacity, driving the cost-plus pricing dynamic that is reshaping the entire jewelry segment.
-
The industrial and semiconductor application of synthetic diamonds — where Element Six is concentrating investment — represents the highest-margin growth vector through 2030.
Industry Impact Analysis
Consumer Preference Dynamics: Natural Diamonds Reassert Value, LGDs Capture Volume
De Beers Group's 2026 US Diamond Acquisition Study — based on responses from 18,500 women aged 18–74 — provides the most comprehensive recent data on consumer preference dynamics. The study found that US consumers rank natural diamonds as their top preference for a luxury jewelry item, with 11% of women ranking natural diamond jewelry their most desired luxury gift, ahead of synthetic lab grown diamonds at 8%, other gemstones at 5%, and plain gold jewelry at 4%.
Average prices for natural diamond jewelry rose to USD 4,063 per piece in 2025, up from USD 3,242 in 2023 — a 25% increase driven by consumers purchasing larger carat weights. Meanwhile, the BriteCo Price Index shows lab grown diamond ring average sales prices declining from USD 6,172 in 2022 to USD 4,578 in the first half of 2026.
The De Beers study also identified a notable behavioral constraint: there is a measurable drop-off in lab grown diamond sales once stones reach 3 carats or larger, suggesting that consumers may perceive very large lab grown diamonds as implausible or aesthetically excessive. This behavioral ceiling has direct implications for retailers' ability to upsell to larger sizes, which could compress gross profit margins in the lab grown jewelry segment over the forecast period.
Regulatory Environment: Disclosure Requirements Tighten Globally
The U.S. Federal Trade Commission's disclosure rules require sellers to clearly and conspicuously state that a diamond is "laboratory-grown," "lab-created," or "synthetic" — a requirement that is increasingly enforced as lab grown diamonds reach mainstream retail channels including supermarkets. This regulatory framework is consequential for the market because it structurally prevents lab grown diamonds from being marketed as equivalent to natural diamonds, reinforcing the value differentiation that De Beers and other natural diamond producers are actively promoting.
India's Bureau of Indian Standards introduced IS 19469:2025, new diamond rules effective in 2026, which establish standardized grading and disclosure requirements for lab grown diamonds sold domestically and for export. These standards are expected to improve buyer confidence in Indian-origin lab grown diamonds in international markets, supporting the GJEPC's export growth trajectory.
Pandora's Lab Grown Diamond Strategy: Measured Growth, Not Transformation
Pandora, the world's largest jewelry maker by production volume, has been one of the most prominent mainstream adopters of lab grown diamonds. The company's lab grown diamond segment grew 13% to approximately USD 55 million in 2025 — meaningful growth, but representing just 1% of Pandora's total revenue. This data point is instructive: even for a company that has made lab grown diamonds a strategic priority, the segment remains a small fraction of total business, underscoring that the market's growth is real but its current revenue base is still developing relative to the broader jewelry industry.
Section Summary:
The industry impact of current market dynamics is being felt across consumer behavior, regulatory frameworks, and corporate strategy simultaneously. The net effect is a market that is growing in volume and total revenue, but where value creation is concentrating in specific segments — industrial applications, AI-enabled quality assurance, and government-backed manufacturing ecosystems.
Key Takeaways:
-
Natural diamond jewelry average purchase prices rose 25% between 2023 and 2025 (De Beers Group, 2026), while lab grown diamond ring prices declined from USD 6,172 (2022) to USD 4,578 (H1 2026), per BriteCo.
-
Lab grown diamonds held 15% of independent jewelers' diamond sales by value in 2025, compared with 85% for natural diamonds (De Beers Group, 2026).
-
FTC disclosure rules and India's IS 19469:2025 standard are tightening the regulatory environment, improving market transparency but also reinforcing the value distinction between lab grown and natural diamonds.
-
Pandora's lab grown segment grew 13% in 2025 but remains at 1% of total revenue, illustrating the segment's growth potential alongside its current scale limitations.
India Lab Grown Diamond Export Volume vs. Natural Diamonds — March & April 2026
|
Month |
LGD Export Volume (Million Carats) |
Natural Diamond Export Volume (Million Carats) |
LGD Share of Total Diamond Export Value |
|
March 2026 |
1.3 |
1.2 |
<9% |
|
April 2026 |
1.4 |
1.3 |
<9% |
|
January 2025 (reference) |
~45% of total volume |
~55% of total volume |
<9% |
US Consumer Diamond Preference & Pricing Trends — De Beers Group Diamond Acquisition Study, 2026
|
Metric |
Data Point |
Year / Period |
|
Natural diamond jewelry — most desired luxury gift (% of women ranking it #1) |
11% |
2026 |
|
Lab grown diamond jewelry — most desired luxury gift (% of women ranking it #1) |
8% |
2026 |
|
Average natural diamond jewelry purchase price |
USD 4,063 per piece |
2025 |
|
Average natural diamond jewelry purchase price (prior period) |
USD 3,242 per piece |
2023 |
|
Average total carat weight purchased (natural) |
1.86 carats |
2025 |
|
Average total carat weight purchased (natural, prior period) |
1.65 carats |
2023 |
|
LGD value share of independent jewelers' diamond sales |
15% |
2025 |
|
Natural diamond value share of independent jewelers' diamond sales |
85% |
2025 |
|
Natural diamond sales growth at independent jewelers (Q4 2025) |
+4% YoY |
Q4 2025 |
|
Natural diamond sales growth at independent jewelers (Q1 2026) |
+9% YoY |
Q1 2026 |
|
Gen Z share of natural diamond demand value |
23% |
2026 |
|
Gen Z share of US population |
18% |
2026 |
Future Outlook & Forecast
NMSC Forecast: USD 34.06 Billion by 2030 at 8.8% CAGR
NextMSC primary research and analysis projects the global lab grown diamonds market to reach USD 34.06 billion by 2030, growing at a CAGR of 8.8% from 2024 to 2030. This forecast is grounded in NMSC's bottom-up segment modeling across product type, manufacturing method, application, price range, and distribution channel — incorporating both the jewelry demand trajectory and the emerging industrial application segment.
North America: Sustained Dominance Through R&D and Institutional Verification
North America currently holds the dominant share of the global lab grown diamonds market, supported by advanced CVD and HPHT manufacturing capabilities, a mature retail infrastructure, and the presence of institutional verification bodies. The International Gemological Institute (IGI) and the Diamond Manufacturers and Importers Association (DMIA) launched a same-day diamond verification service in January 2024, streamlining the certification process for both single stones and parcels — a development that directly reduces friction in the lab grown diamond supply chain and supports market confidence.
The De Beers Group's 2026 Diamond Report data showing 9% YoY growth in natural diamond sales at U.S. independent jewelers in Q1 2026 does not diminish the lab grown diamond outlook — it confirms that the overall U.S. diamond market is expanding, with lab grown diamonds capturing the volume-sensitive consumer segment while natural diamonds capture the value-sensitive segment.
Asia-Pacific: The Fastest-Growing Region, Driven by India and China
Asia-Pacific is the fastest-growing regional market for lab grown diamonds, with India and China playing structurally different but complementary roles. China dominates production; India dominates cutting, polishing, and export. The Indian government's sustained policy support — from the IIT Madras research center investment to the Union Budget 2026 customs duty provisions — is building a vertically integrated domestic lab grown diamond industry that is progressively reducing India's dependence on rough diamond imports.
The Industrial Synthetic Diamond Segment: The Long-Term Value Frontier
The most consequential long-term development for the lab grown diamond market is the emergence of synthetic diamond as a critical material for next-generation technologies. De Beers' Element Six is concentrating its CVD production capacity on semiconductor substrates and quantum computing components — applications where synthetic diamond's exceptional thermal conductivity, electrical insulation properties, and hardness make it a material with no viable substitute. Diamond Quanta's 2024 development of the "Unified Diamond Framework" — a technique enabling new elements to be integrated into diamond's crystalline structure without disrupting its integrity — transforms synthetic diamond into a high-performance semiconductor supporting both negative and positive charge carriers. This innovation extends the addressable market for lab grown diamonds well beyond jewelry into the global semiconductor supply chain.
Section Summary:
The lab grown diamonds market's growth trajectory through 2030 is supported by three converging forces: sustained consumer demand for affordable, ethically positioned jewelry; government-backed manufacturing expansion in India and China; and the emergence of synthetic diamond as a high-value industrial material for semiconductors and quantum technologies.
Key Takeaways:
-
NMSC projects the global lab grown diamonds market to reach USD 34.06 billion by 2030 at a CAGR of 8.8%, driven by both jewelry and industrial application demand.
-
North America maintains market leadership through institutional verification infrastructure and advanced manufacturing capabilities.
-
Asia-Pacific is the fastest-growing region, with India's government-backed export ecosystem and China's production scale as the primary growth engines.
-
The industrial synthetic diamond segment — particularly semiconductor substrates and quantum computing components — represents the highest-margin, longest-duration growth opportunity in the market.
Next Steps for Stakeholders
For C-Level Executives in Jewelry Retail:
The 47% lab grown diamond share of new jewelry appraisals in H1 2026 (BriteCo) is not a ceiling — it is a baseline. Retailers that have not yet developed a clear dual-positioning strategy — one that differentiates lab grown diamonds on accessibility and design, and natural diamonds on provenance and rarity — risk losing relevance in both segments simultaneously. The De Beers data showing a drop-off in LGD sales above 3 carats should inform inventory and merchandising decisions: the volume opportunity in lab grown diamonds is concentrated in the sub-3-carat range.
For Investors in Diamond Manufacturing:
The commoditization of lab grown diamond jewelry is structural, not cyclical. Investment theses built on premium pricing in the LGD jewelry segment face sustained margin compression. The more defensible investment positions are in: (1) low-cost, high-volume CVD production with direct-to-retail distribution; (2) industrial synthetic diamond applications, particularly for semiconductor and quantum technology supply chains; and (3) AI-powered grading and certification technology, which is a market-enabling infrastructure play.
For Institutional Investors Evaluating India Exposure:
India's lab grown diamond export ecosystem is at an inflection point. The GJEPC data showing LGD volume surpassing natural diamonds in March and April 2026 reflects a structural shift in India's diamond industry, not a tariff-driven anomaly. The government's sustained policy support — from IIT Madras to Union Budget 2026 customs provisions — provides a durable policy tailwind. However, investors should monitor the value-to-volume ratio closely: LGDs at less than 9% of India's wholesale diamond export value means that revenue growth will require either significant volume scaling or a stabilization of per-carat prices.
For Supply Chain and Procurement Executives:
The FTC's disclosure requirements and India's IS 19469:2025 standard are raising the compliance bar for lab grown diamond sourcing. Procurement teams should audit their supply chain documentation to ensure full traceability and disclosure compliance, particularly as lab grown diamonds enter mainstream retail channels where regulatory scrutiny is intensifying.
Conclusion
The global lab grown diamonds market is not a simple growth story — it is a market in structural transformation, where the rules of competition, value creation, and consumer engagement are being rewritten simultaneously. The De Beers Lightbox closure, India's export volume milestone, the emergence of synthetic diamond in semiconductor applications, and the tightening of disclosure regulations are not isolated events. They are interconnected signals of a market that is maturing rapidly, bifurcating by application, and demanding more sophisticated strategic responses from every participant in the value chain.
NextMSC primary research and analysis projects the market to reach USD 34.06 billion by 2030 at a CAGR of 8.8% — a forecast that reflects both the sustained consumer demand for lab grown diamond jewelry and the expanding industrial application frontier. For executives and investors who understand the distinction between volume growth and value growth in this market, the current inflection point presents well-defined opportunities. For those who do not, the commoditization dynamics that closed Lightbox will continue to compress returns.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment