What’s New in Facial Wipes for 2024–2025?
Introduction
The global facial wipes market is undergoing a structural transformation — one driven not merely by rising consumer demand for on-the-go skincare convenience, but by a convergence of regulatory mandates, ingredient reformulation imperatives, and shifting demographic spending patterns across Asia-Pacific. According to Next Move Strategy Consulting's Facial Wipes Market report, the global facial wipes market is projected to reach USD 4.81 billion by 2030, growing at a CAGR of 7.40% from 2024 to 2030. This trajectory reflects a market that is simultaneously expanding its consumer base — from Gen Z urban commuters to the 30–45 age cohort seeking multifunctional skincare — while being compelled to overhaul its material and chemical composition in response to tightening environmental legislation.
The competitive dynamics within this market are no longer determined solely by fragrance profiles or packaging aesthetics. Manufacturers that fail to align product substrates with the European Union's Single-Use Plastics Directive (SUPD), Extended Producer Responsibility (EPR) frameworks, and the U.S. Federal Trade Commission's Green Guides risk both regulatory exposure and accelerating consumer rejection. At the same time, the Asia-Pacific region — home to the world's largest producers of skincare products — continues to generate the volume growth that sustains the market's upward trajectory. For institutional investors and C-suite decision-makers, the facial wipes market in 2026 presents a bifurcated opportunity: premium, compliant, and organically formulated products are capturing disproportionate margin, while conventional synthetic-substrate wipes face compressing demand in regulated markets.
For More Information: Download FREE Sample on Facial Wipes Market Report
From Convenience to Compliance: The Regulatory Inflection Point Reshaping the Facial Wipes Industry
The EDANA OUTLOOK 2026 Signal: Regulation Is Now a Product Design Variable
In September 2026, the nonwovens and personal care hygiene industry convened at EDANA's OUTLOOK™ 2026 conference — the event's 25th edition — held in Cascais, Portugal, from 22 to 24 September. The conference brought together producers, converters, brands, retailers, and policymakers to address what EDANA described as "a period of significant adjustment as new European regulations reshape the industry." Among the presentations was a session by Elisabeth Swennenhuis, Product Line Manager, Consumer Wipes at Magnera, titled "From Convenience to Compliance: The Transformation of the Wipes Market," which examined how the EU's Single-Use Plastics Directive, EPR schemes, environmental claims legislation, and circular economy policies are directly influencing material selection and product development timelines.
The significance of this conference signal cannot be overstated for facial wipes manufacturers. Swennenhuis's core argument — that regulatory preparedness must now be embedded at the earliest stages of product design rather than treated as a post-development compliance exercise — reflects a structural shift in how the industry's most sophisticated players are allocating R&D resources.
The EU Single-Use Plastics Directive: Wet Wipes Are Explicitly in Scope
The European Commission's Single-Use Plastics Directive (Directive (EU) 2019/904), which entered into force on 2 July 2019 and became applicable on 3 July 2021, explicitly lists wet wipes and sanitary items among the 10 single-use plastic product categories subject to its regulatory framework. The directive requires EU Member States to implement labelling requirements informing consumers about the plastic content of wipes, disposal options to be avoided, and environmental harm from littering — obligations that directly affect how facial wipes are marketed and packaged across the EU's 27 member states.
The Commission's April 2026 report confirmed that ten EU countries are already exceeding SUPD collection targets, signalling that enforcement momentum is accelerating rather than plateauing. Simultaneously, a public consultation and call for evidence on the SUPD's evaluation — held between December 2025 and March 2026 — is informing potential revisions to the directive ahead of its evaluation deadline of 3 July 2027. For facial wipes manufacturers with significant EU revenue exposure, this evaluation window represents both a risk — the possibility of stricter substrate requirements — and an opportunity to shape the regulatory outcome through industry engagement.
The U.S. Dimension: FTC Green Guides and the Greenwashing Liability
In the United States, the Federal Trade Commission's Green Guides govern how companies may make environmental marketing claims, including "biodegradable," "compostable," and "plant-based" assertions that are increasingly central to facial wipes brand positioning. The FTC has previously pursued enforcement actions against companies making unsubstantiated "bamboo" and "organic" claims — including a 2022 action against Kohl's and Walmart that sought the largest-ever civil penalty for bogus bamboo marketing. Facial wipes brands that deploy "biodegradable" or "flushable" claims without rigorous substantiation face analogous enforcement exposure, a risk that is amplifying the cost of non-compliance for brands operating across both the EU and U.S. markets simultaneously.
NMSC Strategic Perspective: The Compliance-Innovation Nexus as a Competitive Moat
NextMSC primary research and analysis identifies the regulatory compliance burden as a market-structuring force that is accelerating consolidation among facial wipes manufacturers. Smaller producers that lack the R&D infrastructure to reformulate substrates — replacing synthetic non-woven fabrics with certified plant-based or biodegradable alternatives — while simultaneously maintaining the softness, tensile strength, and liquid-retention performance that consumers expect, face a narrowing window of competitive viability in regulated markets. Conversely, manufacturers that have already invested in compliant substrate development are positioned to command premium pricing, as the supply of genuinely compliant, high-performance facial wipes remains constrained relative to the demand signal being generated by both regulatory mandates and consumer preference data.
The material science challenge is not trivial: as Magnera's Swennenhuis noted at OUTLOOK™ 2026, no substrate can simultaneously optimize every performance characteristic — improvements in strength may compromise softness, while higher absorbency can affect liquid release properties. This technical constraint means that the compliance-innovation nexus is a genuine competitive moat, not merely a marketing differentiator, for manufacturers that have solved it.
Section Summary:
The regulatory environment governing facial wipes has shifted from a peripheral compliance consideration to a central product development variable. The EU SUPD's explicit inclusion of wet wipes, the acceleration of EPR schemes across Europe, and the FTC's active enforcement of environmental marketing claims are collectively compelling manufacturers to treat substrate selection as a strategic decision with direct implications for market access, brand equity, and litigation exposure.
-
The EU SUPD explicitly targets wet wipes and sanitary items, requiring labelling, EPR compliance, and consumption reduction measures across all 27 EU member states.
-
Ten EU countries exceeded SUPD collection targets as of April 2026, signalling accelerating enforcement momentum ahead of the directive's 2027 evaluation.
-
The FTC's Green Guides create substantiation requirements for biodegradable and plant-based claims that are central to premium facial wipes positioning in the U.S. market.
-
Manufacturers that have solved the compliance-performance trade-off in substrate selection hold a structural competitive advantage that cannot be replicated quickly by undercapitalized competitors.
Industry Impact Analysis
Beiersdorf's NIVEA Rebalancing: A Case Study in Skincare Portfolio Recalibration
Beiersdorf's full-year 2025 results, published on 2 March 2026, provide a granular view of how the global skincare market's deceleration is affecting the competitive landscape in which facial wipes compete. The company reported Group sales of €9.9 billion with organic growth of 2.4% — a marked deceleration from the 6.5% organic growth recorded in 2024. NIVEA, the brand most directly relevant to the mass-market facial wipes segment, delivered organic growth of only 0.9% in 2025, reaching nominal sales of €5.5 billion, as the brand underwent a strategic recalibration to restore portfolio balance across Face Care, Body Care, and Deodorants.
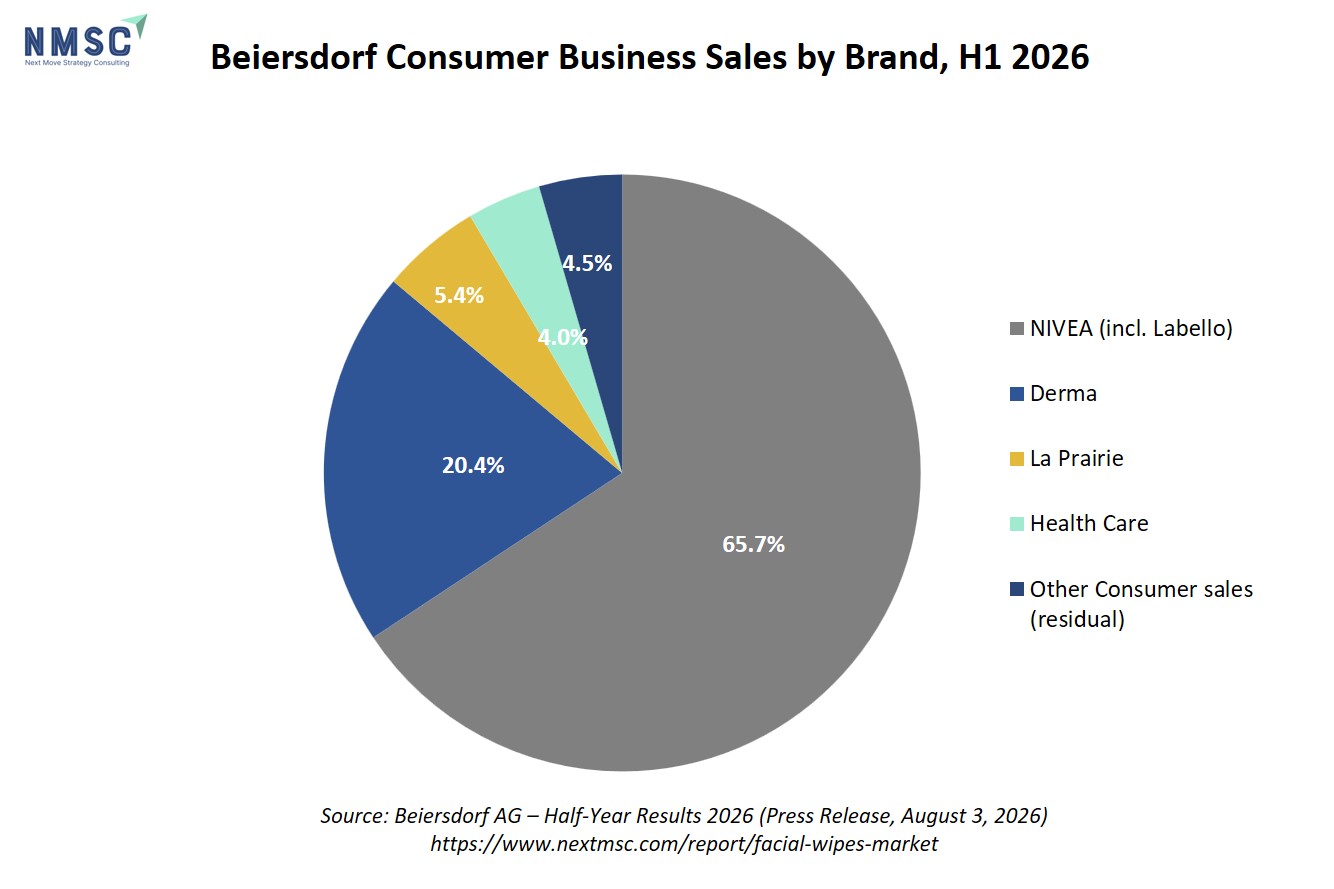
The contrast with Beiersdorf's Derma business — which delivered 11.7% organic growth in 2025, its fifth consecutive year of double-digit expansion — is instructive for the facial wipes market. Derma's outperformance was driven by science-backed, clinically positioned products with active ingredients such as Thiamidol® and Epicelline®. This performance differential signals that facial wipes positioned as dermatologically validated, ingredient-led products — rather than generic cleansing conveniences — are better insulated from the mass-market deceleration that is compressing NIVEA's growth rate. Beiersdorf's Africa/Asia/Australia segment delivered 4.5% organic growth in 2025, reinforcing the Asia-Pacific region's role as the primary volume growth engine for skincare brands with global footprints.
Beiersdorf's sustainability commitments are also directly relevant to the facial wipes competitive landscape. The company has committed to Net Zero by 2045, with a 90% reduction in GHG emissions across its entire value chain versus 2018, validated by the Science-Based Targets initiative. By end of 2024, Beiersdorf had reduced emissions by 25.3% across Scopes 1, 2, and 3, and achieved climate-neutral operations across its European production sites by early 2025. These commitments set a benchmark that competitors in the facial wipes space — including those without Beiersdorf's R&D budget of €365 million in 2025 — will struggle to match without significant capital reallocation.
L'Oréal's 2025 Performance: The Beauty Market's Resilience Benchmark
L'Oréal reported 2025 sales of €44.05 billion, representing 4.0% like-for-like growth, outpacing the global beauty market's approximately 3.5% growth rate in 2025. The Consumer Products Division — the segment most directly competitive with mass-market facial wipes brands — posted 3.5% like-for-like growth. L'Oréal's sustained outperformance of the broader beauty market reflects the competitive advantage of brands that combine ingredient science with distribution scale — a combination that is increasingly defining the premium tier of the facial wipes market.
The M&A Dimension: Strategic Acquirers Are Reshaping the Competitive Map
The beauty sector's M&A activity in 2025–2026 has direct implications for the facial wipes competitive landscape. According to Taylor Sicard's June 2026 analysis of beauty brand acquisition multiples, the beauty sector averaged approximately 3.6x revenue from 2022 to 2025, with breakout brands clearing 5x to 8x. Strategic acquirers — including L'Oréal, P&G, Unilever, and Beiersdorf — are acquiring brands that fill specific portfolio gaps, particularly in the premium skincare and sustainable personal care segments. For facial wipes brands that have successfully positioned themselves at the intersection of skincare efficacy and sustainability compliance, this M&A environment represents a meaningful exit pathway at premium valuations.
Section Summary:
The industry impact of current market dynamics is being felt most acutely at the intersection of sustainability compliance, ingredient science, and regional growth divergence. Mass-market facial wipes brands face margin compression in slowing Western markets, while premium, clinically positioned, and sustainability-compliant products are capturing disproportionate growth in Asia-Pacific and among the 20–45 age demographic globally.
-
Beiersdorf's NIVEA brand grew only 0.9% organically in 2025, while its Derma business (clinically positioned) grew 11.7% — a performance gap that directly maps onto the facial wipes market's premium-versus-mass bifurcation.
-
L'Oréal's 4.0% like-for-like growth in 2025 outpaced the global beauty market's 3.5% growth rate, confirming that scale and ingredient science remain the primary drivers of competitive resilience.
-
Beiersdorf's Africa/Asia/Australia segment grew 4.5% organically in 2025, reinforcing Asia-Pacific as the primary volume growth engine for global skincare brands.
-
The beauty M&A market is rewarding brands at the premium, sustainable, and clinically validated end of the spectrum with acquisition multiples of 5x to 8x revenue, creating a clear strategic incentive for facial wipes manufacturers to invest in compliance and ingredient differentiation.
Key Industry Benchmarks — Selected Facial Wipes Market Players (2025 Financial Data)
|
Company |
Relevant 2025 Metric |
Sustainability Commitment |
|
Beiersdorf (NIVEA) |
Consumer Business: €8.2B (+2.5% organic); NIVEA: €5.5B (+0.9% organic) |
Net Zero by 2045; 90% GHG reduction vs. 2018 (SBTi-validated); climate-neutral European production sites by early 2025 |
|
Beiersdorf (Derma — Eucerin/Aquaphor) |
€1.5B (+11.7% organic); 5th consecutive year of double-digit growth |
80% recycled aluminum for NIVEA cream tin; re-engineered formulas with lighter packaging |
|
L'Oréal |
Group sales: €44.05B (+4.0% like-for-like); Consumer Products: +3.5% |
Committed to sustainable packaging and biodegradable formulations across product lines |
|
Global Beauty Market |
~3.5% growth in 2025 |
Wellness and self-care positioning driving premium segment resilience |
|
Beauty Sector M&A Average Multiple |
~3.6x revenue (2022–2025); breakout brands: 5x–8x |
Sustainability-compliant brands commanding premium acquisition multiples |
Future Outlook & Forecast
The 2030 Horizon: Three Forces That Will Determine Market Leadership
NextMSC primary research and analysis identifies three structural forces that will determine which manufacturers capture the USD 4.81 billion market opportunity by 2030.
Force 1: Substrate Compliance as Market Access
The EU SUPD's evaluation, with a public consultation completed in March 2026 and a directive review deadline of 3 July 2027, is likely to produce tightened requirements for wet wipes substrates. Manufacturers that have already transitioned to certified plant-based, biodegradable, or microplastic-free substrates will face no incremental compliance cost from any tightening, while those still relying on conventional synthetic non-woven fabrics will face both reformulation costs and potential market access restrictions in the EU — the world's most stringent regulatory environment for single-use plastics. The EDANA OUTLOOK™ 2026 conference's central theme — that regulatory preparedness must be embedded in product design from the outset — reflects the industry's recognition that this is not a future risk but a present operational requirement.
Force 2: Asia-Pacific Volume Growth Anchored by South Korea and Japan
Asia-Pacific's dominance of the facial wipes market — confirmed by NextMSC proprietary research as the region holding the largest market share — is structurally supported by the region's role as the world's leading producer and innovator of skincare products. Beiersdorf's Africa/Asia/Australia segment delivered 4.5% organic growth in 2025, with the fourth quarter accelerating to 9.3% organic growth, confirming that the region's demand trajectory remains robust even as Western markets decelerate. The K-beauty innovation pipeline — which has consistently introduced multi-step skincare routines that create demand for specialized cleansing formats including facial wipes — continues to generate product concepts that migrate from South Korea and Japan into global markets within 12–24 months of domestic launch.
Force 3: Ingredient Science as the Premium Pricing Engine
The performance differential between Beiersdorf's mass-market NIVEA brand (0.9% organic growth in 2025) and its clinically positioned Derma business (11.7% organic growth) provides a direct analogue for the facial wipes market's premium-versus-mass bifurcation. Facial wipes formulated with clinically validated active ingredients — including tea tree oil for acne-prone skin, coconut oil for dry skin moisturization, and rose water for sensitive skin — are capturing the 30–45 age demographic that NextMSC proprietary research identifies as a key growth segment. This demographic's willingness to pay a premium for ingredient transparency and clinical efficacy is the mechanism through which the facial wipes market's 7.40% CAGR is being sustained despite the broader mass-market skincare deceleration documented in Beiersdorf's 2025 results.
Section Summary:
The facial wipes market's path to USD 4.81 billion by 2030 is navigable for manufacturers that align their product development, regulatory compliance, and regional expansion strategies with the three structural forces identified above. The market's 7.40% CAGR is not uniformly distributed — it is concentrated in the premium, compliant, and ingredient-led segments of the market, and in the Asia-Pacific region.
-
The EU SUPD's 2027 evaluation is the single most consequential near-term regulatory event for facial wipes manufacturers with EU market exposure; early compliance investment is the lowest-cost path to sustained market access.
-
Asia-Pacific's structural demand drivers — urbanization, K-beauty innovation diffusion, and the region's established skincare manufacturing infrastructure — will sustain the region's market leadership through 2030.
-
Ingredient science (clinically validated actives, natural essential oils, microplastic-free formulations) is the primary mechanism through which premium facial wipes brands are insulating themselves from mass-market margin compression.
-
The beauty sector's M&A environment rewards sustainability-compliant, premium-positioned brands with acquisition multiples of 5x–8x revenue, creating a clear strategic incentive for investment in compliance and differentiation ahead of any potential exit.
Next Steps for Stakeholders
For C-Level Executives at Facial Wipes Manufacturers:
-
Commission a substrate compliance audit immediately. Map every SKU in your portfolio against the EU SUPD's labelling requirements and the FTC Green Guides' substantiation standards. Identify which products require reformulation before the SUPD's 2027 evaluation potentially tightens substrate requirements. The cost of proactive reformulation is materially lower than the cost of reactive market withdrawal.
-
Allocate R&D resources to the compliance-performance trade-off. The technical challenge of maintaining softness, tensile strength, and liquid retention in plant-based substrates is the primary barrier to entry in the premium, compliant segment. Manufacturers that solve this trade-off first will hold a competitive moat that cannot be replicated quickly by undercapitalized competitors.
-
Prioritize Asia-Pacific distribution partnerships. Beiersdorf's Africa/Asia/Australia segment accelerated to 9.3% organic growth in Q4 2025, confirming that the region's demand trajectory is strengthening. Facial wipes manufacturers without established Asia-Pacific distribution infrastructure should evaluate partnership or acquisition pathways to access this growth.
-
Invest in clinical substantiation for ingredient claims. The FTC's enforcement history on environmental and ingredient claims — including the 2022 Kohl's and Walmart bamboo marketing action — demonstrates that unsubstantiated claims create material legal exposure. Clinical substantiation of active ingredient efficacy (tea tree oil, coconut oil, Thiamidol®-adjacent actives) is both a regulatory requirement and a premium pricing enabler.
For Institutional Investors:
-
Screen for substrate compliance as a market access indicator. Facial wipes brands with certified plant-based or biodegradable substrates are better positioned for sustained EU market access than those relying on conventional synthetic non-woven fabrics. This is a binary market access risk, not a gradual margin headwind.
-
Monitor the SUPD evaluation outcome (due July 2027). Any tightening of substrate requirements will create a near-term cost shock for non-compliant manufacturers and a pricing opportunity for compliant ones. Position accordingly ahead of the evaluation conclusion.
-
Evaluate M&A opportunities in the premium, compliant segment. The beauty sector's average acquisition multiple of 3.6x revenue, with breakout brands clearing 5x–8x, reflects the strategic premium that large CPG acquirers (L'Oréal, P&G, Unilever, Beiersdorf) are willing to pay for brands that fill specific portfolio gaps in the sustainable personal care space.
Conclusion
The global facial wipes market's trajectory to USD 4.81 billion by 2030 — at a 7.40% CAGR per NextMSC proprietary research and analysis — is being shaped by forces that extend well beyond consumer convenience preferences. The EU Single-Use Plastics Directive's explicit targeting of wet wipes, the FTC's active enforcement of environmental marketing claims, and the EDANA OUTLOOK™ 2026 industry consensus that regulatory compliance must be embedded in product design from the outset are collectively redefining what it means to be a competitive facial wipes manufacturer in 2026 and beyond.
The performance data from the market's largest players reinforces this conclusion. Beiersdorf's clinically positioned Derma business grew 11.7% organically in 2025 while its mass-market NIVEA brand grew only 0.9% — a divergence that maps directly onto the facial wipes market's premium-versus-mass bifurcation. L'Oréal's sustained outperformance of the global beauty market confirms that ingredient science and distribution scale remain the primary drivers of competitive resilience. And Asia-Pacific's structural demand drivers — anchored by South Korea and Japan's skincare manufacturing leadership — continue to generate the volume growth that sustains the market's upward trajectory.
For manufacturers, investors, and strategic acquirers, the facial wipes market in 2026 rewards precision over scale: precision in substrate selection, ingredient formulation, regulatory compliance, and regional market prioritization. Those who treat compliance as a cost center rather than a competitive investment will find their addressable market shrinking as regulatory requirements tighten. Those who treat it as a moat will find themselves positioned to capture a disproportionate share of a market that NextMSC projects will add nearly USD 1.9 billion in value over the next four years.
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment