Lubricant Additive Volumes Slide at NewMarket as Surcharges Prop Up Sales
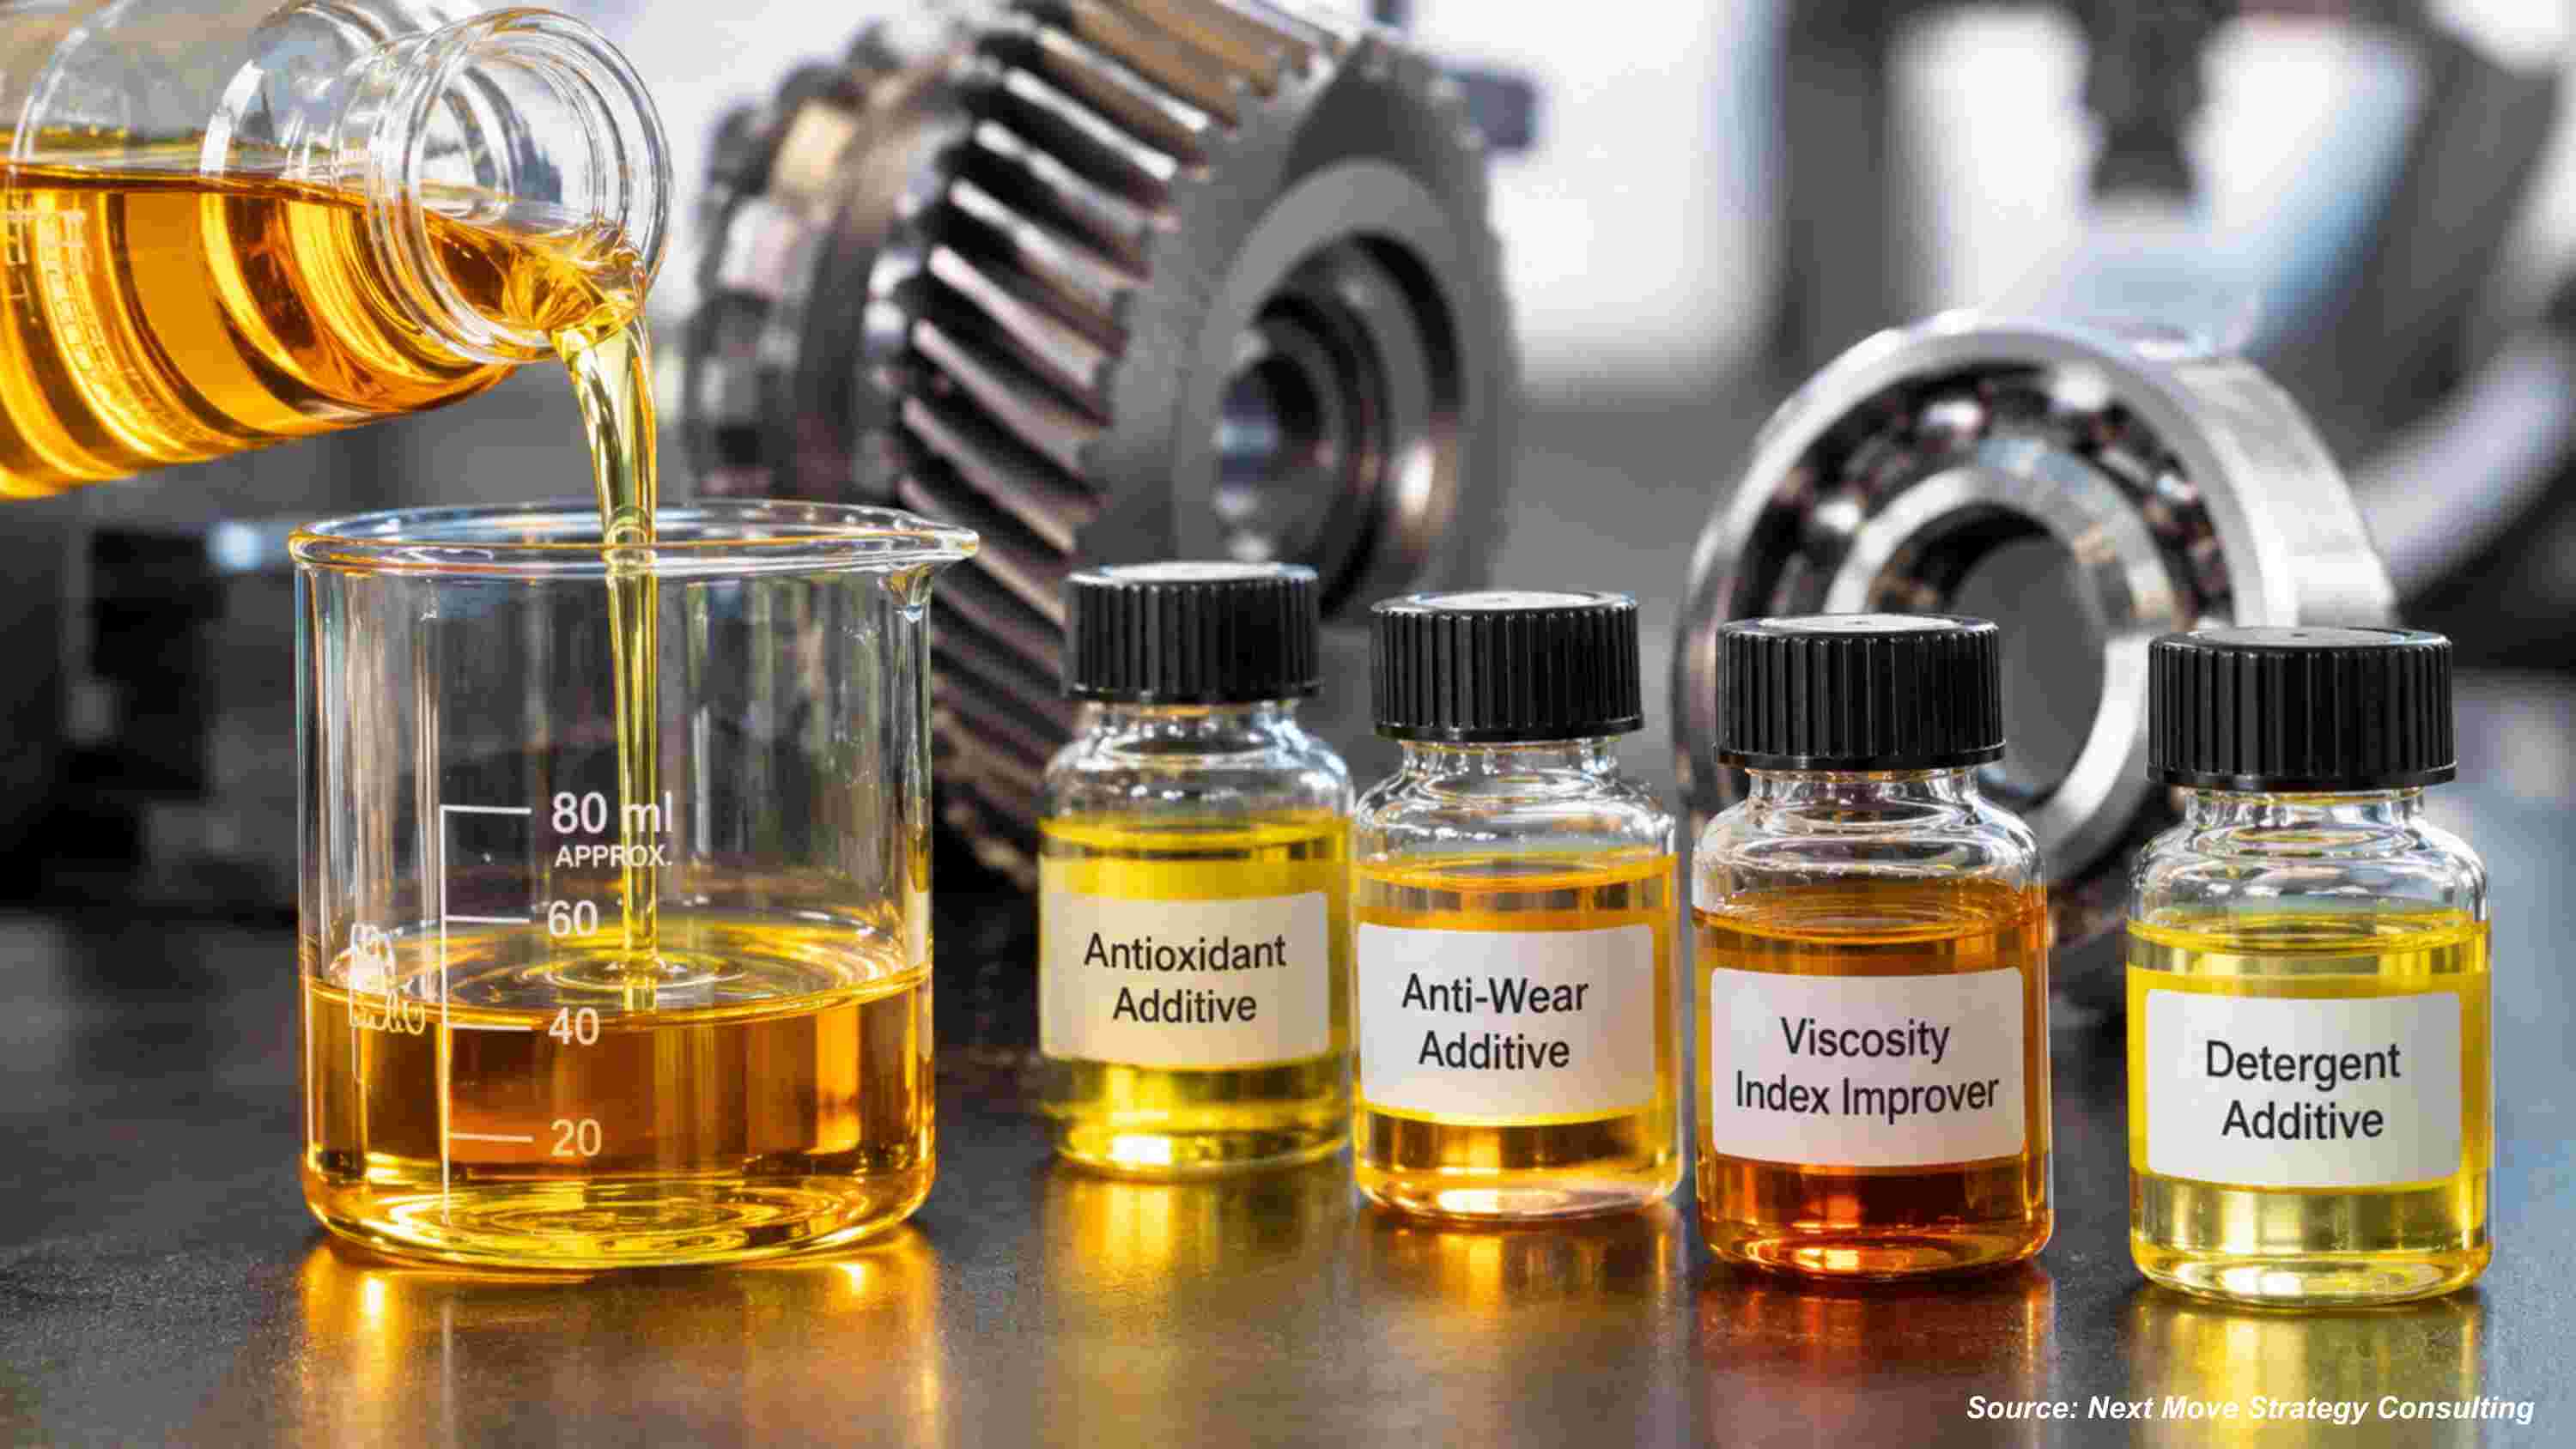
NewMarket's third-quarter results and the race to qualify PC-12 diesel oil chemistry show lubricant additive suppliers defending revenue with price while placing volume bets on 2027 specifications
On October 28, 2026, the NewMarket Corporation earnings release, issued by the parent of Afton Chemical, cited an 8% decline in shipments amid broader market softness in lubricant additives. The company's Form 10-Q puts worldwide petroleum additives shipments down 8% in the third quarter compared with the same period of 2025, with lubricant additives accounting for most of the decline, yet segment net sales edged up to about USD 651 million from USD 649.1 million. According to the 10-Q, higher selling prices, including surcharges introduced in response to supply chain disruptions linked to the conflict in the Middle East, offset the volume loss almost exactly. The filing quantifies how much of the quarter's revenue was carried by price rather than by volume shipped.
According to Next Move Strategy Consulting's Lubricant Additives Market report, the global lubricant additives market was valued at USD 18.85 billion in 2025 and is projected to reach USD 27.85 billion by 2035, growing at a CAGR of 3.97% from 2026 to 2035. NextMSC primary research and analysis places the 2026 value at USD 19.62 billion, a trajectory that depends on suppliers converting tightening engine oil specifications into reformulation demand even while blended lubricant volumes stay flat or soften.
For More Information: Download FREE Sample on Lubricant Additives Market Report
The Financial Logic: Volume Down, Price Up
NewMarket's 10-Q shows that petroleum additives net sales rose 0.3% in the third quarter even though shipments contracted. The company's own reconciliation attributes a USD 52.3 million gain from selling prices and product mix, partly offset by USD 46.9 million of lower lubricant additives shipments, USD 1.8 million of lower fuel additives shipments and a USD 1.8 million unfavorable currency effect. For the first nine months of 2026, shipments declined 6.1%, which NewMarket links partly to its decision to examine and reduce low-margin business in the first half, alongside the third-quarter market softness.
NewMarket Net Sales by Product Line (USD thousand)
|
Product line |
Q3 2026 |
Q3 2025 |
Nine months 2026 |
Nine months 2025 |
|
Lubricant additives |
549,323 |
550,447 |
1,654,516 |
1,666,104 |
|
Fuel additives |
101,627 |
98,638 |
281,825 |
282,410 |
|
Total petroleum additives |
650,950 |
649,085 |
1,936,341 |
1,948,514 |
Components of Change in NewMarket Petroleum Additives Net Sales (USD million)
|
Component |
Third quarter |
Nine months |
|
Net sales, period ended September 30, 2025 |
649.1 |
1,948.5 |
|
Lubricant additives shipments |
(46.9) |
(88.8) |
|
Fuel additives shipments |
(1.8) |
(5.9) |
|
Selling prices, including product mix |
52.3 |
72.2 |
|
Foreign currency impact, net |
(1.8) |
10.3 |
|
Net sales, period ended September 30, 2026 |
650.9 |
1,936.3 |
The price increases carried a cost. NewMarket reported that petroleum additives cost of goods sold rose to 70.3% of net sales in the third quarter from 69.3% a year earlier, and that segment operating profit slipped to USD 130.9 million from USD 131.3 million, a margin of 20.1% against 20.2%. Inventories across the company climbed to USD 576.6 million at September 30, 2026 from USD 502.3 million at the end of 2025, which the 10-Q attributes mainly to higher raw material prices and longer transit times resulting from the conflict in the Middle East. Chairman and Chief Executive Officer Thomas E. Gottwald said in the release that the company's focus on operational efficiency helped sustain strong operating profit margins despite the shipment decline.
“we successfully implemented surcharges to offset higher costs”
—Thomas E. Gottwald, Chairman and Chief Executive Officer, NewMarket Corporation, Third Quarter and First Nine Months 2026 Results (Form 8-K, Exhibit 99.1), October 28, 2026.
The regional pattern matters for anyone reading the headline growth figures for Asia-Pacific. NewMarket's petroleum additives net sales increased 8.3% in Latin America, 1.7% in North America and 1.3% in Europe, the Middle East, Africa and India during the third quarter, but fell 8.1% in Asia Pacific, and lubricant additives shipments were lower in every region. On a consolidated basis, the company's Asia Pacific net sales were USD 120.6 million in the quarter against USD 127.4 million a year earlier, while sales in the United States and in Europe, the Middle East, Africa and India both rose.

The 10-Q reports consolidated net sales of USD 716,502 thousand for the quarter across the four geographic areas shown, a total that includes specialty materials and other businesses as well as petroleum additives.
Key Industry Developments: The PC-12 Reformulation Race
The most concrete demand catalyst for additive suppliers is the American Petroleum Institute's new heavy-duty diesel engine oil specification. On April 13, 2026, API announced the formal approval of Proposed Category 12, known as PC-12, which introduces the API CL-4 and API FB-4 service categories and sets January 1, 2027 as the first licensing date. API stated that the specification targets improved oxidation resistance, enhanced wear protection, expanded elastomer compatibility, better aftertreatment system protection and support for lower viscosity grades aimed at fuel economy, each of which is delivered through additive chemistry rather than base oil alone.
API PC-12 Licensing Milestones
|
Date |
Milestone |
|
April 13, 2026 |
API announces formal approval of PC-12 and the release of API CL-4 and API FB-4 certification marks |
|
June 1, 2026 |
API licensee portal scheduled to open for early entry of CL-4 and FB-4 products |
|
January 1, 2027 |
First licensing date for API CL-4 and API FB-4 |
“PC-12 establishes a strong technical foundation for performance, durability and environmental protection”
—Bill O'Ryan, Director-EOLCS/DEF, American Petroleum Institute, API CL-4 & FB-4 Diesel Oil Specs Released (API press release), April 13, 2026.
Suppliers have moved ahead of the licensing date. Chevron Oronite announced on July 16, 2026 its PC-12 additive technology, built on one platform with two products, OLOA 59382 with an embedded pour point depressant and OLOA 59380 without one, and reported more than 20 licensable industry claims and OEM approvals. Lubrizol followed with its CV1700 Series, which the company said it had begun shipping in North America ahead of the January 2027 first license date and which supports both API CL-4 and API FB-4 across viscosity grades that include 5W-20, 5W-40 and 15W-40. Both companies are positioning ahead of the first license date, which gives lubricant blenders time to finalize formulations and packaging before API licensing opens, according to the product announcements.
Supply Chain Localisation in Asia-Pacific
A second shift is under way in how additives reach Asian customers. Infineum and Kangtai, a subsidiary of Rianlon Corporation, signed a Southern Asia distribution agreement on July 22, 2026, the first operational step under the strategic framework the two groups concluded on January 20, 2026, and Rianlon is building a research, development and manufacturing facility in Johor, Malaysia. On September 18, 2026, LANXESS and Wuxi South Petroleum Additive Co., Ltd. signed a memorandum of understanding at LANXESS headquarters in Cologne to explore cooperation in China and the wider region, with Neelanjan Banerjee, Senior Vice President and Global Head of the Lubricant Additives business unit at LANXESS, pointing to customer demand for local supply, short lead times and dependable availability. In India, LANXESS and Hindustan Petroleum Corporation Limited signed a memorandum of understanding on May 12, 2026 to widen the availability of aviation and industrial lubricant solutions across India and SAARC countries.
Selected 2026 Lubricant Additive Supplier Moves
|
Date |
Company |
Development |
|
May 12, 2026 |
LANXESS and Hindustan Petroleum Corporation Limited |
Memorandum of understanding to expand availability of aviation and industrial lubricant solutions across India and SAARC countries |
|
July 16, 2026 |
Chevron Oronite |
PC-12 additive platform with OLOA 59382 and OLOA 59380 and more than 20 licensable industry claims and OEM approvals |
|
July 22, 2026 |
Infineum and Kangtai |
Southern Asia distribution agreement under the January 20, 2026 strategic framework with Rianlon Corporation |
|
September 2026 |
Lubrizol |
CV1700 Series heavy-duty engine oil additives begin shipping in North America ahead of API CL-4 and FB-4 licensing |
|
September 18, 2026 |
LANXESS and Wuxi South Petroleum Additive Co., Ltd. |
Memorandum of understanding signed in Cologne to explore lubricant additive cooperation in China and Asia-Pacific |
Segment Dynamics: Dispersants Lead, Friction Modifiers Grow Fastest
According to NextMSC primary research and analysis, dispersants are the largest product type, valued at USD 4.34 billion in 2025, roughly 23% of the market, followed by detergents at USD 3.58 billion and viscosity modifiers at USD 3.02 billion. Friction modifiers are the fastest-growing product type at a 6.1% CAGR from 2026 to 2035, rising from USD 0.94 billion to USD 1.67 billion, while viscosity modifiers are projected to expand at a 5.3% CAGR, a pace NextMSC primary research and analysis links to the shift toward lower-viscosity grades such as those API FB-4 supports. Dispersants, which keep combustion by-products suspended in the oil, remain the revenue anchor for heavy-duty and passenger car engine oil packages alike.
By application, NextMSC primary research and analysis finds engine oils held about 46% of the market, or USD 8.67 billion, in 2025, and that bio-based oil is the fastest-growing base oil category at a 10.0% CAGR, although mineral oil-based formulations still account for about 68% of the market at USD 12.82 billion. The gap between those two figures explains why suppliers are validating additive packages across Group II, Group III and renewable base oils simultaneously, as the Lubrizol and Chevron Oronite announcements illustrate.
Regional Outlook
NextMSC primary research and analysis shows Asia-Pacific leading with about 40% of 2025 revenue, or USD 7.54 billion, and the highest regional CAGR at 5.6% through 2035. China was the largest country market at about USD 2.71 billion in 2025, while India is the fastest-growing country at a 10.4% CAGR, from about USD 1.21 billion in 2025 to about USD 3.07 billion by 2035. North America, at USD 4.90 billion and a 2.6% CAGR, and Europe, at USD 4.52 billion and a 2.4% CAGR, are mature markets where growth depends on specification upgrades rather than new vehicle demand.
Growth Drivers and Restraints
Three documented forces are supporting demand. The PC-12 transition gives heavy-duty oil blenders a dated reason to reformulate, with first licensing on January 1, 2027. Supply localisation in Asia, visible in the Infineum-Kangtai and LANXESS-Wuxi South agreements, is widening the number of qualified suppliers reaching price-sensitive regional blenders. And pricing discipline, shown in NewMarket's surcharges, has so far protected supplier revenue when volumes weakened.
The restraints are equally specific. NewMarket reported lower lubricant additives shipments in every region in the third quarter and expects its petroleum additives segment to keep feeling market softness through 2026. Raw material costs and transit times remain exposed to the Middle East conflict, as the company's inventory build shows. NextMSC primary research and analysis also identifies electric vehicle adoption as a structural restraint on conventional engine oil additive volumes in North America, Europe and Asia-Pacific, which is why diversification into industrial, marine and electric vehicle fluid additives is a recurring feature of supplier strategy.
NMSC Strategic Perspective: Price Is Carrying Revenue, Specifications Must Carry Volume
NextMSC primary research and analysis reads the NewMarket quarter as evidence of a two-speed market. Pricing and surcharge mechanisms are sustaining supplier revenue today, but they cannot lift shipments, and a market forecast to grow at 3.97% a year cannot rely on price alone for a decade. The volume engine has to be specification-driven reformulation, and PC-12, with its fixed January 1, 2027 first license date, is the nearest dated test of that thesis.
The regional data adds a caution. NewMarket's Asia Pacific petroleum additives net sales fell 8.1% in the quarter even though NextMSC primary research and analysis expects Asia-Pacific to be the fastest-growing region. NextMSC reads this as a reminder that regional demand growth does not accrue evenly to every supplier: it is being contested by locally manufactured additive components and by distribution tie-ups such as Infineum and Kangtai, and a company-level decline in one quarter is not, on its own, evidence of a change in regional demand. Suppliers that pair global formulation capability with regional manufacturing, as the Infineum, Rianlon and LANXESS agreements attempt to do, are better placed to capture the region's growth.
For stakeholders, NextMSC primary research and analysis points to three priorities: qualify PC-12 chemistry across multiple base oil groups before January 2027, secure regional supply and distribution in Asia-Pacific and India where the fastest country growth sits, and treat friction modifiers, viscosity modifiers and bio-based compatible chemistry as the segments where specification change translates most directly into incremental additive demand. NextMSC primary research and analysis estimates the absolute dollar opportunity between 2026 and 2035 at USD 8.23 billion.
Competitive Landscape
NextMSC primary research and analysis characterizes the lubricant additives industry as moderately consolidated, with integrated additive package developers competing alongside specialty chemistry producers. Chevron Oronite, Lubrizol, Infineum and NewMarket's Afton Chemical sit in the integrated group, each investing in formulation testing infrastructure and OEM approvals, while LANXESS, Rianlon's Kangtai and Wuxi South represent the component and regional-supply layer that the 2026 partnership announcements are connecting to the global package suppliers. The July and September 2026 announcements show the integrated suppliers answering a specification cycle on one side and a regional cost and lead-time challenge on the other.
Bottom Line
NewMarket's third-quarter filing shows the lubricant additives industry in a transition where revenue is being protected by price while volumes soften: petroleum additives shipments fell 8%, yet net sales held at about USD 651 million because selling prices added USD 52.3 million. According to NextMSC primary research and analysis, the market will expand from USD 18.85 billion in 2025 to USD 27.85 billion by 2035 at a 3.97% CAGR, and that path now depends on specification-driven reformulation. API's PC-12 category, with first licensing on January 1, 2027, and the early product launches from Chevron Oronite and Lubrizol, give suppliers a dated catalyst. In Asia-Pacific, the region NextMSC expects to lead growth, supply localisation through Infineum, Kangtai, LANXESS and Wuxi South is reshaping who captures it. Suppliers that qualify new chemistry early and secure regional supply are best positioned as price effects fade.
About Next Move Strategy Consulting
Next Move Strategy Consulting is a premier market research and management consulting firm that has been committed to provide strategically analysed well documented latest research reports to its clients. The research industry is flooded with many firms to choose from, what makes NMSC different from the rest is its top-quality research and the obsession of turning data into knowledge by dissecting every bit of it and providing fact-based research recommendation that is supported by information collected from over 500 million websites, paid databases, industry journals and one on one consultations with industry experts across a diverse range of industry sectors. The high-quality customized research reports with actionable insights and excellent end-to-end customer service help our clients to take critical business decisions that enables them to move beyond time and have competitive edge in the industry.
We have been servicing over 1000 customers globally that includes 90% of the Fortune 500 companies over a decade. Our analysts are constantly tracking various high growth markets and identifying hidden opportunities in each sector or the industry. We provide one of the industry’s best quality syndicate as well as custom research reports across 10 different industry verticals. We are committed to deliver high quality research solutions in accordance to your business needs. Our industry standard delivery solutions that ranges from the pre consultation to after-sales services, provide an excellent client experience and ensure right strategic decision making for businesses.
For more information, please contact:
Next Move Strategy Consulting
5th Floor 867 Boylston St, STE 500,
Boston, MA 02116, U.S.
E-Mail: [email protected]
Direct: +1-217-650-7991
Website: www.nextmsc.com
About the Author
 Priyanshu Das
— Priyanshu Das is SEO Executive at Next Move Strategy Consulting, where he has led on-page and off-page SEO, keyword research, and SEO audits for the firm's B2B market research publications for 2 years. His audit process combines technical crawl analysis, backlink profile review, and competitor keyword gap mapping — using tools including Screaming Frog and Google Search Console — to prioritize fixes by organic search-visibility impact, informed by his own prior in-house and agency SEO experience.
About the Reviewer
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.














Add Comment